
 Airlift Bioreactors Market | 2026-2036
Airlift Bioreactors Market Size, Share, and Industry Trends Forecast 2026-2036
Airlift Bioreactors Market Outlook
Market Context
Buyer concentration among contract manufacturing organizations is recalibrating procurement volumes for airlift bioreactor systems. Lonza leverages its integrated biologics network to secure multi-year vessel supply agreements with gene therapy developers. Sartorius sustains technology leadership through perfusion-ready single-use platforms designed for microbial and mammalian cell lines. Cellexus differentiates via low-shear airlift geometries optimized for sensitive cell cultures in personalized medicine workflows.
Technical Definition and Segment Structure
An airlift bioreactor employs gas-sparged liquid circulation without mechanical agitation, typically operating with aspect ratios of 6:1 to 12:1 and superficial gas velocities between 0.01 and 0.1 meters per second to achieve oxygen transfer coefficients of 100 to 800 per hour in cell culture and protein production applications. Single-use bioreactors capture the dominant share of new installations as pharmaceutical companies prioritize batch flexibility and reduced cross-contamination risk in multi-product facilities. Stainless steel bioreactors retain margin concentration in large-volume therapeutic protein production where fed-batch systems achieve titers exceeding five grams per liter and amortization periods justify capital-intensive infrastructure.
Regulatory Environment and Outlook
FDA process validation guidance and EMA good manufacturing practice Annex 1 revisions enforce closed-system requirements that favor sealed airlift designs over traditional stirred-tank alternatives. ISO 14644 cleanroom classifications and ASME BPE bioprocessing equipment standards govern material selection and surface finish specifications for wetted components. Stakeholders must monitor evolving cell and gene therapy potency assay requirements that will dictate bioreactor scale-down model fidelity and process analytical technology integration priorities.
Market Dynamics
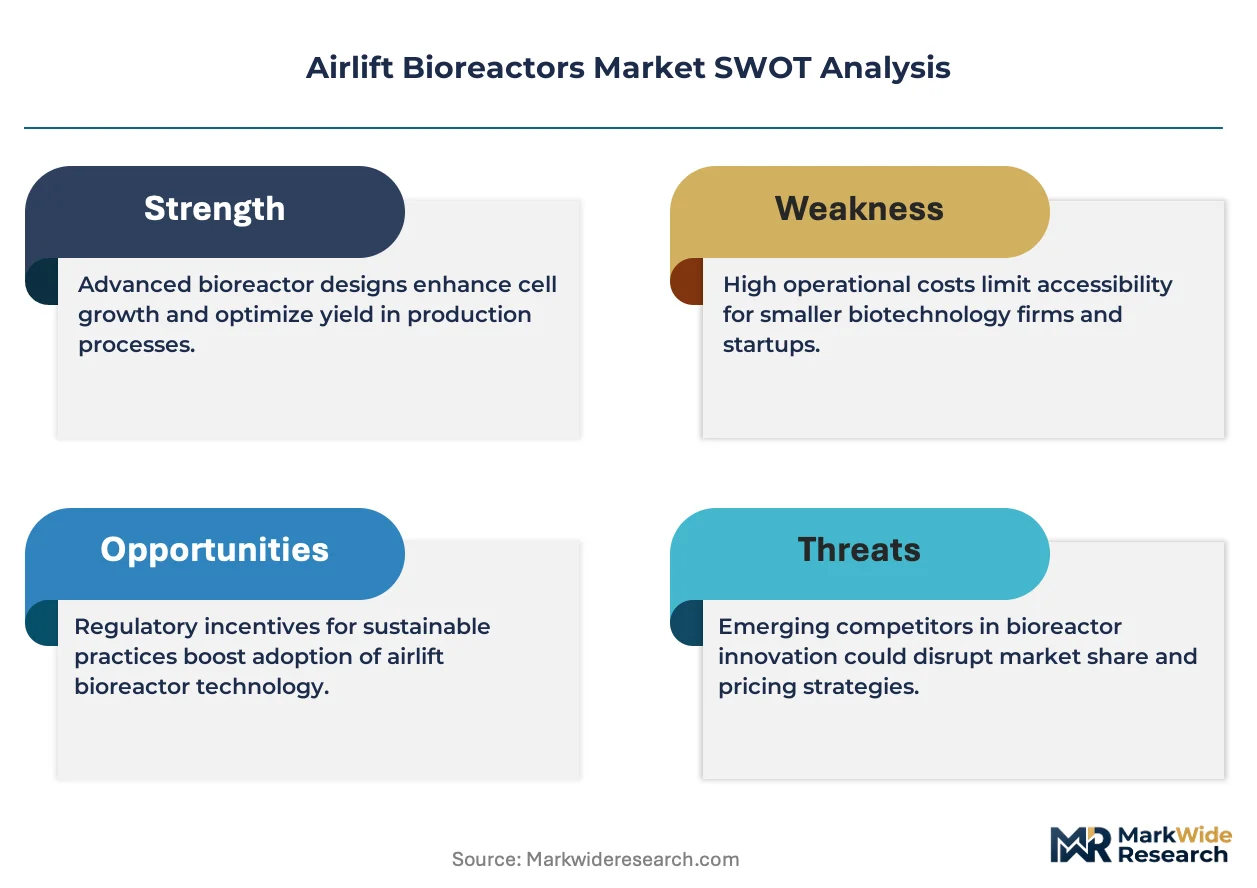
Single-use airlift bioreactor adoption is compressing equipment procurement cycles as contract manufacturing organizations prioritize batch flexibility over capital-intensive stainless steel infrastructure in multi-product viral vector facilities.
Growth Catalysts
- EMA Annex 1 revisions:The updated good manufacturing practice standards mandate closed-system designs that eliminate mechanical seals, directly favoring airlift geometries over traditional stirred-tank alternatives in sterile cell culture applications.
- Gene therapy manufacturing:Viral vector production workflows demand low-shear environments that preserve cell viability, positioning airlift configurations as the preferred vessel architecture for AAV and lentiviral processes.
- German biologics clusters:Concentrated investment in mRNA and cell therapy manufacturing around Munich and Heidelberg is driving localized procurement of perfusion-ready single-use systems.
Market Restraints
- Film resin supply concentration:Specialized multilayer polymer films for single-use bags depend on limited North American and European chemical suppliers, creating input cost volatility and delivery uncertainty.
- Oxygen transfer ceiling:Airlift configurations achieve lower volumetric oxygen transfer coefficients than mechanically agitated alternatives, constraining high-density mammalian cell culture beyond certain titer thresholds.
- Stainless steel amortization:Large-volume therapeutic protein facilities with existing fed-batch infrastructure face sunk-cost disincentives against airlift conversion despite operational flexibility advantages.
Strategic Opportunities
- Personalized medicine workflows:Patient-specific cell therapies require rapid vessel turnaround and minimal cross-contamination risk, creating white space for disposable airlift systems in decentralized manufacturing networks.
- South Korean CDMO expansion:Government-backed biologics manufacturing initiatives around Incheon and Songdo are attracting foreign investment in flexible single-use capacity.
- Process analytical technology integration:Real-time biomass and metabolite sensors embedded in single-use film layers enable closed-loop control without breaching sterile boundaries.
Industry Challenges
- Scale-down model fidelity:Translating bench-scale airlift parameters to production-scale vessels requires computational fluid dynamics validation that stretches internal engineering capabilities at emerging biotech firms.
- Extractables and leachables testing:Single-use film qualification protocols demand extended compatibility studies that delay facility startup timelines and inflate regulatory submission costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Airlift Bioreactors Market |
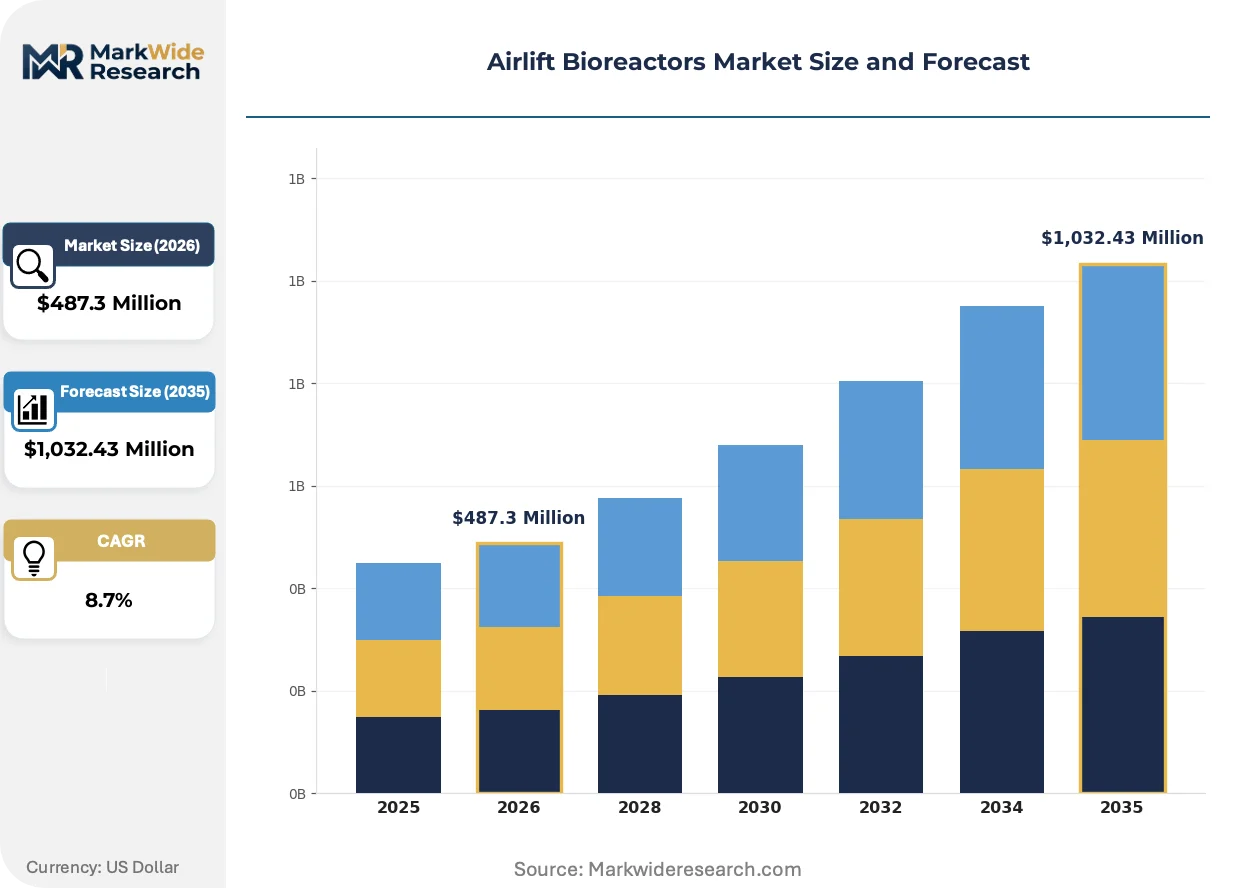
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Use Bioreactors, Stainless Steel Bioreactors, Modular Bioreactors, Continuous Bioreactors End User: Pharmaceutical Companies, Biotechnology Firms, Research Institutions, Contract Manufacturing Organizations Application: Cell Culture, Protein Production, Vaccine Development, Therapeutic Protein Production Technology: Perfusion Technology, Batch Production, Fed-Batch Systems, Scale-Up Techniques |
| Companies Covered | Lonza, Shree Biocare, Kuhner Shaker, Knik Technology, Rotech, Cellexus, Electrolab Biotech, Solida Biotech, Sartorius, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Airlift Bioreactors Market Strategic Shifts
Process intensification methodologies and sensor miniaturization are compressing the gap between stainless steel performance and single-use flexibility, reshaping capital deployment patterns across biologics manufacturing networks.
Perfusion-ready single-use airlift platforms are consolidating process development workflows by enabling continuous operation without mechanical agitation. Gene therapy developers are adopting these systems at accelerated rates for viral vector production. The technology is consolidating vendor relationships as end-users standardize on integrated platform suppliers rather than assembling components from multiple sources.
EMA Annex 1 sterile manufacturing revisions are mandating closed-system architecture for all aseptic processing. This regulatory pressure eliminates stirred-tank alternatives that require mechanical shaft seals. Cell therapy manufacturers in Germany and the Netherlands are retrofitting facilities to comply, accelerating airlift specification in new construction projects.
Buyer concentration among contract manufacturing organizations is compressing equipment procurement into multi-year framework agreements. Direct vendor relationships are displacing traditional distributor channels for standard vessel configurations. This pattern is most visible in the United States, where Lonza and Catalent volume commitments dominate single-use bioreactor allocation schedules.
Airlift Bioreactors Market Segmentation
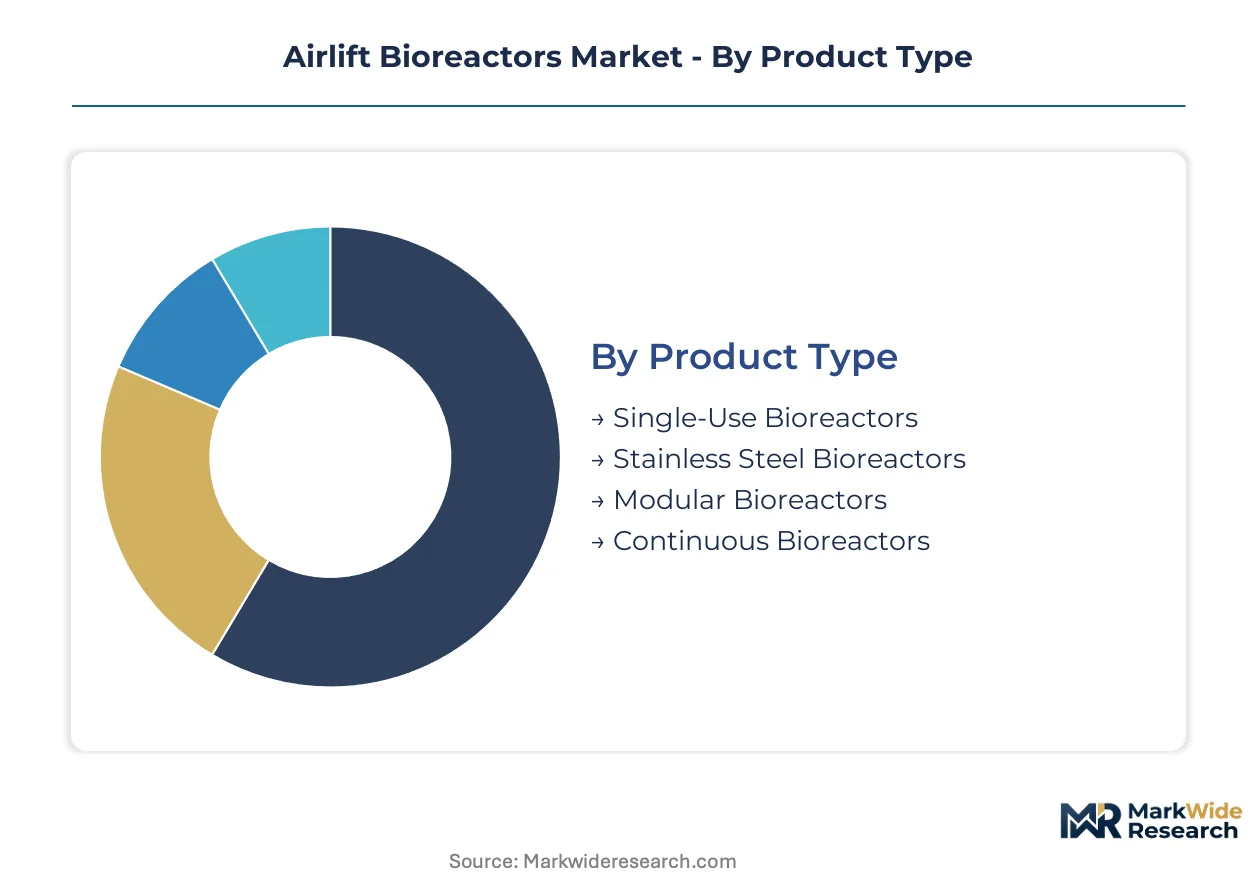
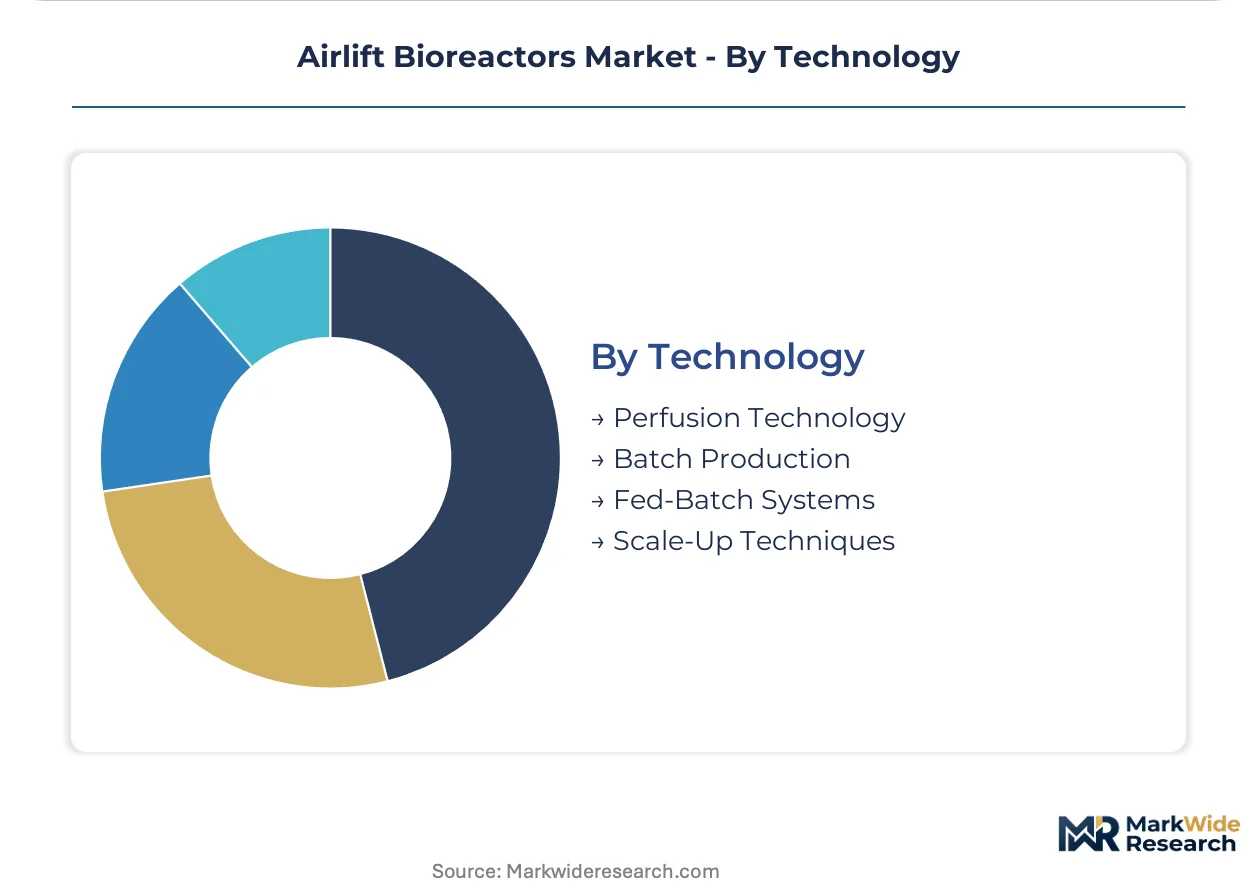
Segmentation in airlift bioreactors reveals distinct procurement patterns across vessel architectures and operational modes. Technology choices determine integration complexity with existing facility infrastructure, while end-user profiles dictate scale requirements and regulatory stringency levels.
Product Type:
Standalone single-use vessels dominate new facility installations where batch flexibility outweighs capital efficiency, while embedded stainless steel systems anchor long-cycle therapeutic protein manufacturing.
- Single-Use Bioreactors:Disposable polymer film vessels eliminate cleaning validation cycles and enable rapid product changeover in multi-product facilities. Contract manufacturing organizations in the United States and Germany are standardizing on these systems for viral vector production where cross-contamination risks mandate sealed, non-penetrating designs.
- Stainless Steel Bioreactors:Permanent vessels with automated clean-in-place systems achieve lowest per-batch operating cost at production scales exceeding 10,000 liters. Large-volume monoclonal antibody facilities in South Korea retain this architecture where fed-batch titers above five grams per liter justify depreciation schedules.
- Modular Bioreactors:Skid-mounted configurations allow incremental capacity expansion without facility reconstruction.
- Continuous Bioreactors:Perfusion-integrated designs enable steady-state operation with residence time control.
Volume placements concentrate in single-use configurations; the faster expansion belongs to modular systems.
End User:
Customer type determines specification rigor, with commercial manufacturers demanding validated scale-down models that research operations often bypass.
- Pharmaceutical Companies:Integrated biologics divisions specify closed-system airlift geometries to comply with EMA Annex 1 sterile manufacturing mandates. Internal engineering teams prioritize perfusion-ready platforms that compress process development timelines for pipeline assets.
- Contract Manufacturing Organizations:CDMO procurement concentrates in multi-year framework agreements that secure vessel allocation priority. Lonza and Catalent volume commitments in North America and Europe are reshaping supplier capacity planning.
- Biotechnology Firms:Emerging developers favor disposable systems to conserve capital for clinical milestone funding.
- Research Institutions:Academic laboratories prioritize bench-scale flexibility over production fidelity.
Procurement volume clusters with contract manufacturing organizations; biotechnology firms are climbing the fastest.
Application:
Process objectives dictate oxygen transfer requirements and shear sensitivity thresholds that segment vessel specification.
- Cell Culture:Mammalian and insect cell propagation demands low-shear environments where airlift sparging preserves membrane integrity. Gene therapy developers in Germany and the Netherlands specify these configurations for patient-specific autologous therapies.
- Protein Production:Microbial expression systems tolerate higher energy dissipation rates, enabling stirred-tank alternatives that airlift designs rarely displace.
- Vaccine Development:Viral antigen production requires biosafety containment that favors sealed airlift architectures.
- Therapeutic Protein Production:Monoclonal antibody manufacturing at scale retains fed-batch stainless steel dominance.
Facility investments concentrate in cell culture; vaccine development shows the steepest expansion trajectory.
Technology:
Operational mode selection determines capital intensity and batch economics across product lifecycle stages.
- Perfusion Technology:Continuous media exchange maintains steady-state cell density with real-time metabolite control. Sartorius integrated platforms are consolidating vendor relationships as end-users abandon component assembly.
- Fed-Batch Systems:Sequential nutrient addition achieves peak titers in conventional stainless steel vessels. Existing large-scale therapeutic protein facilities in South Korea face sunk-cost disincentives against conversion.
- Batch Production:Discrete operation cycles simplify regulatory filing but constrain productivity.
- Scale-Up Techniques:Computational fluid dynamics validation bridges bench parameters to production vessels.
Equipment specifications concentrate in fed-batch modes; perfusion technology is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Contract manufacturing organizations in Germany, the United States, and South Korea are recalibrating procurement volumes for airlift bioreactor systems as biologics manufacturing clusters expand in these markets.
United States
Lonza and Catalent volume commitments dominate single-use bioreactor allocation schedules. FDA process validation guidance enforces closed-system requirements that favor sealed airlift designs. The Greater Boston and San Francisco Bay Area biotech corridors are retrofitting facilities to comply with updated sterility mandates.
Germany
Concentrated investment in mRNA and cell therapy manufacturing around Munich and Heidelberg is driving localized procurement of perfusion-ready single-use systems. EMA good manufacturing practice Annex 1 revisions mandate closed-system architecture for aseptic processing. The Rhine-Main biologics cluster is accelerating airlift specification in new construction projects.
South Korea
Government-backed biologics manufacturing initiatives around Incheon and Songdo are attracting foreign investment in flexible single-use capacity. MFDS pharmaceutical manufacturing standards align with international closed-system requirements. Samsung Biologics and Celltrion expansion programs are reshaping regional vessel demand patterns.
Netherlands
Cell therapy manufacturers in Leiden and Utrecht are retrofitting facilities to comply with EMA Annex 1 sterile manufacturing revisions. The national pharmaceutical regulator enforces strict extractables and leachables testing protocols for single-use film qualification. The Bio Science Park Leiden cluster is consolidating process development workflows around integrated perfusion platforms.
Switzerland
Integrated biologics divisions at major pharmaceutical headquarters specify closed-system airlift geometries for pipeline assets. Swissmedic manufacturing standards emphasize process analytical technology integration for real-time biomass control. The Basel biotech corridor is prioritizing rapid vessel turnaround capabilities for personalized medicine workflows.
Airlift Bioreactors Market Competitive Environment
German and Swiss producers anchor one tier; United States specialists hold contract manufacturing integration positions. The vendor base separates into consolidated platform suppliers and niche geometry developers. Three strategic archetypes dominate: integrated bioprocess solution providers, low-shear design specialists, and perfusion-ready platform vendors. Capacity expansion and multi-year framework agreements represent the dominant competitive moves.
Within the integrated platform tier, Sartorius exemplifies technology leadership through perfusion-ready single-use architectures. Lonza occupies a position as a contract manufacturing organization that secures vessel supply agreements while operating as a demand-side anchor. Cellexus represents the low-shear specialization archetype with geometries optimized for sensitive cell cultures. Among European-based developers, Kuhner Shaker and Solida Biotech sit within the equipment fabrication segment serving research and production scale requirements.
| Leading Market Players |
|---|
| Lonza |
| Shree Biocare |
| Kuhner Shaker |
| Knik Technology |
| Rotech |
| Cellexus |
| Electrolab Biotech |
| Solida Biotech |
| Sartorius |
| Others |
Value Chain & Pricing Dynamics
Captive polymer film production by integrated platform suppliers anchors both supply security and pricing power for single-use airlift systems. Contract manufacturing organizations in Germany and the United States negotiate multi-year framework agreements that lock in vessel allocation priority while compressing per-unit costs through volume commitments.
Pricing Analysis
Volume commitments command margin compression while standalone purchases retain premium positioning. Contract-based long-term offtake dominates procurement between CDMOs and platform suppliers like Sartorius, with pricing differentiation driven by ISO 14644 cleanroom certification tier and after-sales service bundling. Cost compression in standard single-use vessels is intensifying because resin supply volatility feeds through to film layer costs. Emerging biotechnology firms exhibit highest price sensitivity due to capital constraints, whereas integrated pharmaceutical divisions prioritize validated scale-down model fidelity over per-unit expenditure.
Supply Chain Analysis
ASME BPE certification and extractables-leachables qualification protocols gate entry for film resin suppliers and vessel fabricators alike. Specialized multilayer polymer production concentrates in Germany, the United States, and South Korea, with bioprocessing equipment fabrication drawing from North American and European precision manufacturing bases. Single-source vulnerability pervades the specialized fluoropolymer liner segment where qualified alternatives remain limited. Distribution runs through direct vendor relationships that displace traditional distributor channels for standard vessel configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
A vertical-integration race is reshaping competitive positioning as platform suppliers pursue backward control over polymer film resin production to secure input cost stability.
For Market Incumbents: Acquire specialized fluoropolymer film resin production capabilities to neutralize single-source supply risk. Consolidate vendor relationships by offering integrated perfusion-ready platforms that eliminate component assembly complexity. Emerging CDMO framework agreements threaten to lock out non-integrated suppliers from volume allocation schedules. For New Entrants and Emerging Players: Capture decentralized manufacturing networks for patient-specific cell therapies where rapid vessel turnaround requirements favor disposable airlift geometries. The Netherlands and Switzerland present penetrable white space for low-shear design specialists. A go-to-market angle emphasizing EMA Annex 1 pre-compliance accelerates facility qualification timelines. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated bioprocess solution providers seeking to fill technology gaps. Long-term viability hinges on sustained gene therapy pipeline expansion and regulatory validation of closed-system architectures. Watch FDA process validation guidance updates as the inflection signal for accelerated airlift specification mandates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Film Production | Captive resin supply secures margin protection against input cost volatility from North American chemical suppliers. |
| Perfusion-Ready Platform Standardization | Integrated Sartorius architectures compress process development timelines for gene therapy viral vector workflows. |
| EMA Annex 1 Pre-Compliance Certification | Closed-system validation accelerates facility startup for cell therapy manufacturers in Germany and the Netherlands. |
| Multi-Year CDMO Framework Agreements | Lonza and Catalent volume commitments reshape supplier capacity planning across North American biologics corridors. |
| Computational Fluid Dynamics Scale-Down Validation | CFD modeling fidelity bridges bench parameters to production vessels for emerging biotechnology firms. |
Study Parameters
Independent corroboration across primary interviews with bioprocess engineers, regulatory affairs leads at CDMOs, and single-use platform procurement managers underwrites the qualitative findings. Secondary validation draws from FDA 483 inspection observations, EMA good manufacturing practice guidance documents, and ASME BPE standard revision records. Bottom-up vessel shipment analysis triangulates against top-down biologics manufacturing capacity expansion announcements.
Comparable-period anchoring to historical bioreactor installation cycles across the analysis window enables projection calibration. The modeling framework segments by vessel architecture, operational technology, end-user type, and regional regulatory cluster. CAGRs derive from installation run-rate extrapolation adjusted for gene therapy manufacturing capacity buildout intensity and EMA Annex 1 compliance retrofit schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to viral vector platform approval trajectories and polymer resin supply consolidation patterns. A model refresh is warranted upon material change in FDA closed-system guidance enforcement timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Equipment
Global Bioprocess Analyzers Market
Biotechnology Equipment
Global Lab Automation in Protein Engineering Market
Biotechnology Equipment
Portable Bioprocessing Bioreactors Market
Biotechnology Equipment
Cell Lysis Market
Biotechnology Equipment
Fluidized-Bed Bioreactors Market
Biotechnology Equipment
Global Cell Culture Sampling Device Market
Biotechnology Equipment
Global Recombinant Cell Culture Supplements Market
Biotechnology Equipment
Global Single-Use Bioreactor Market
Biotechnology Equipment
Real-Time Bioprocess Raman Analyzer Market
Biotechnology Equipment
Cell and Tissue Culture Supplies Market
Biotechnology Equipment
Upstream Bioprocessing Equipment Market
Biotechnology Equipment
Global DNA/RNA Extraction Kit Market
Biotechnology Equipment
Global Cell Separation Technology Market
Biotechnology Equipment
Global Biological Microscope Objectives Market
Biotechnology Equipment
Global Bioreactor Market
Biotechnology Equipment
Rocking Bioreactors Market