
 Payment Service Provider Market | 2026-2036
Payment Service Provider Market Size, Share, and Industry Trends Forecast 2026-2036
Payment Service Provider Market Outlook
Market Context
Payment bundling is consolidating merchant-facing software with core processing infrastructure, compressing vendor stacks from five layers to two. Stripe leverages API-native architecture to capture developers building embedded finance products. Adyen sustains single-platform economics across online, in-store, and marketplace channels. Square dominates card-present volume among micro-merchants through hardware-software integration.
Technical Definition and Segment Structure
A payment service provider is a financial technology intermediary that authorizes, processes, and settles electronic transactions between buyers and sellers through encrypted data transmission protocols and tokenized credential storage. Its primary commercial purpose is to reduce merchant complexity by abstracting relationships with acquiring banks, card networks, and regulatory compliance layers into a unified service contract. Merchant account services anchor margin pools through recurring SaaS fees and interchange markups, while fraud prevention segments compete on machine-learning model accuracy and chargeback guarantee economics. API integration technology leads developer adoption curves, though contactless payments infrastructure is displacing legacy terminal estates in physical retail at the fastest velocity.
Regulatory Frame and Outlook
The EU's PSD2 strong customer authentication mandates and the Digital Operational Resilience Act reshape product roadmaps for gateway providers serving European merchants. India's RBI payment aggregator licensing, the US OCC fintech charter framework, and the UK's FCA consumer duty rules collectively elevate capital requirements and compliance tooling spend across jurisdictions. Stakeholders must monitor how fragmented national licensing regimes affect cross-border platform economics and partner selection criteria.
Market Dynamics
API-native infrastructure is compressing merchant technology stacks from five vendor layers to two, forcing acquirers to absorb software functionality or cede relationships to platform aggregators. This consolidation pressure is reshaping how payment service providers allocate R&D capital and partnership priorities.
Growth Catalysts
- India's UPI Rails:The National Payments Corporation of India has built real-time settlement infrastructure that reduces merchant onboarding friction from weeks to hours. Payment aggregators licensed under RBI's 2020 framework capture transaction volume through simplified KYC protocols.
- PCI DSS 4.0 Migration:The updated compliance standard mandates stronger encryption and continuous monitoring, creating upgrade cycles for legacy gateway providers serving mid-market retailers. Merchants face audit pressure to replace tokenization systems deployed before 2022.
- Embedded Finance APIs:Software platforms in vertical SaaS categories now embed checkout, lending, and treasury functions through white-label payment infrastructure. This developer demand is automating merchant acquisition for API-first providers.
Market Restraints
- Interchange Cost Compression:Durbin Amendment caps in the US and similar regulatory pressure in Australia squeeze acquirer margins on debit transactions. Payment service providers absorb these constraints through volume commitments or merchant fee adjustments.
- Core Banking Dependency:Settlement finality depends on correspondent banking relationships concentrated in London, New York, and Singapore. Cross-border platforms face counterparty risk when correspondent banks de-risk emerging market corridors.
- Token Standard Fragmentation:Network-specific tokenization schemes from Visa, Mastercard, and domestic schemes like RuPay create technical overhead. Merchants supporting multiple markets must maintain parallel credential vaults.
Strategic Opportunities
- Brazil's Pix Instant Payments:The Central Bank of Brazil's real-time system reached 150 million users within three years of launch. Payment service providers can capture merchant acquiring volume by building Pix-native checkout experiences for e-commerce marketplaces.
- Account-to-Account Convergence:Open banking APIs and real-time rails are converging to displace card networks for recurring bill payments. Utilities and subscription services in the UK and EU pilot direct bank-to-bank settlement.
- Hardware-Software Bundling:Android-based terminal estates enable app marketplaces that transform payment devices into merchant operating systems. This channel innovation captures software revenue from micro-merchants previously served by basic countertop terminals.
Industry Challenges
- Scheme Certification Backlogs:New terminal hardware and software releases require network certification cycles that extend 12-18 months. Product teams face launch delays when certification labs operate at capacity.
- Legacy Core Integration:Tier-1 banks and established acquirers maintain decades-old authorization systems that resist real-time API connectivity. Payment service providers must build abstraction layers that increase operational complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Payment Service Provider Market |
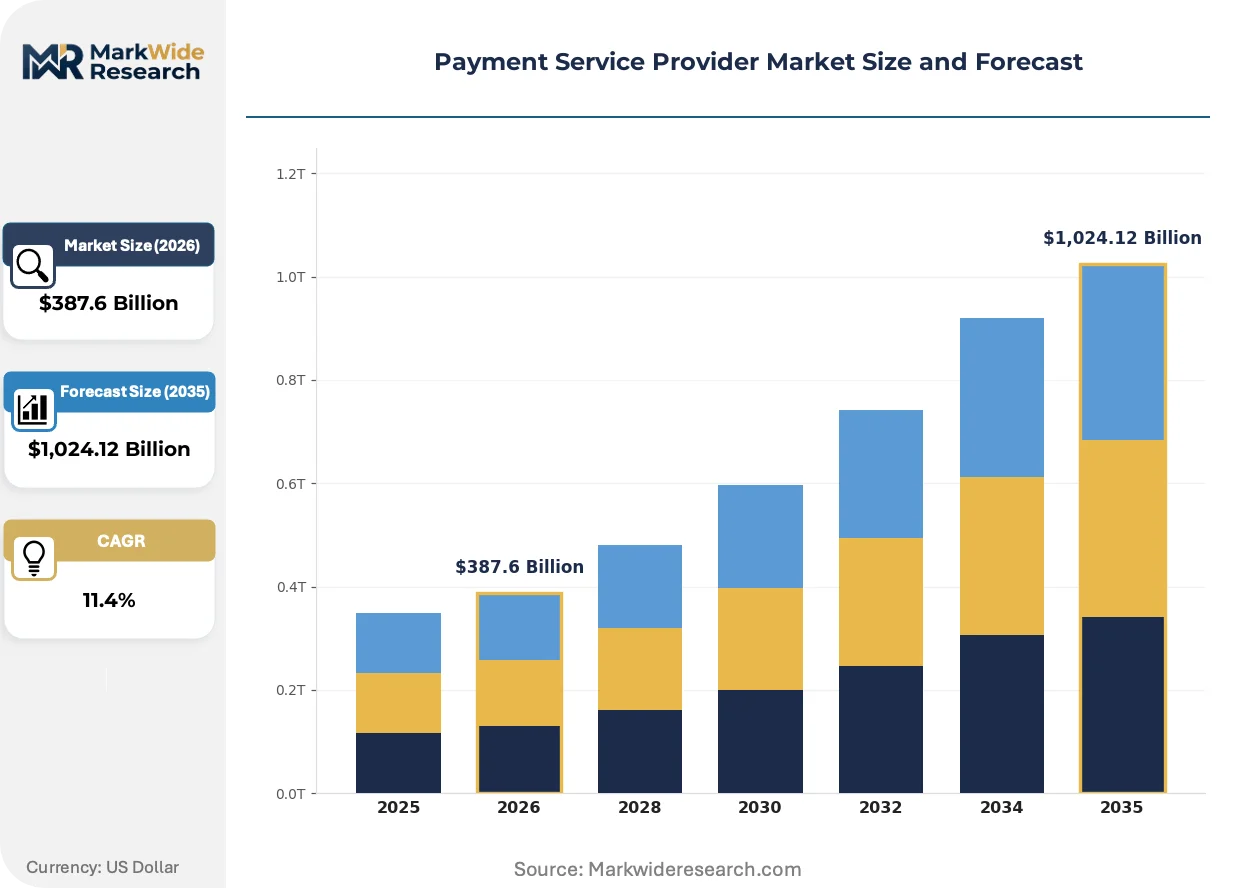
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $1,024.12 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Payment Gateway, Digital Wallet, Merchant Account, Fraud Prevention Technology: API Integration, Mobile Payments, Contactless Payments, Blockchain End User: E-commerce, Retailers, Service Providers, Financial Institutions Transaction Size: Microtransactions, Small Transactions, Medium Transactions, Large Transactions |
| Companies Covered | Worldpay, Elavon, Stripe, Fiserv, Bank of America Gateway, PayPal, Checkout.com, Square, Adyen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Payment Service Provider Market Strategic Shifts
Machine learning is displacing rules-based fraud detection across authorization flows, while regulatory mandates for strong customer authentication reshape checkout experience design. These forces are converging to redefine how payment service providers differentiate technical capabilities.
Real-time transaction monitoring using behavioral biometrics and device fingerprinting is automating fraud decisioning at the network edge. Large e-commerce merchants deploy these models to reduce false declines without increasing chargeback rates. The technology is automating risk management functions previously staffed by manual review teams, compressing operational cost structures for high-volume acquirers.
PSD2 strong customer authentication requirements in the European Union mandate two-factor verification for electronic payments above threshold amounts. Acquirers serving EU merchants must implement 3D Secure 2.0 protocols or face transaction routing penalties. Card-not-present segments in France, Germany, and the Netherlands experience the highest compliance retrofit costs as legacy one-click checkout flows require redesign.
Merchant procurement of payment infrastructure is consolidating toward single-platform contracts that bundle gateway, risk, and acquiring services. Mid-market retailers previously using three to four specialized vendors now prefer unified pricing and reconciliation. This concentration is most visible in the UK, where SaaS-integrated platforms displace standalone gateway relationships among digitally native brands.
Payment Service Provider Market Segmentation
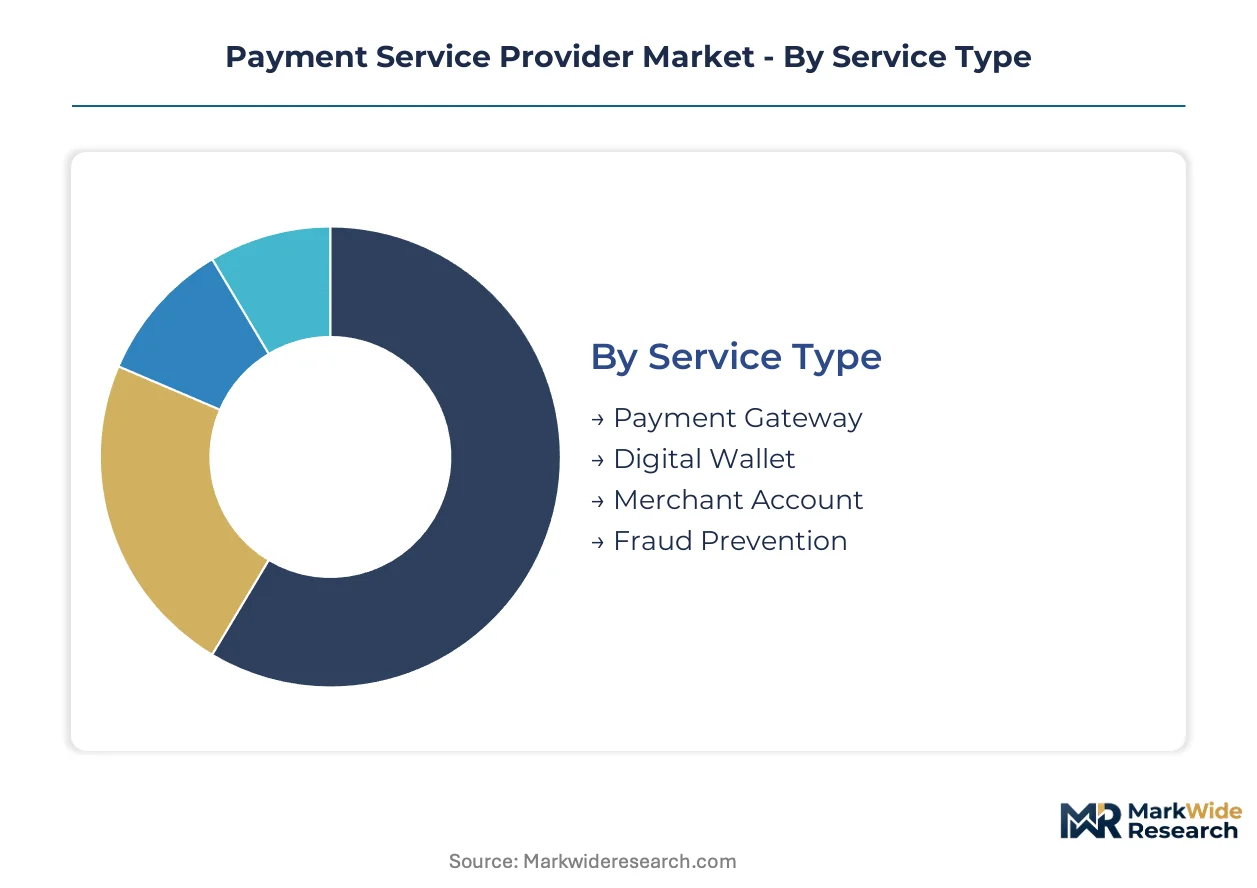
Payment service provider segmentation reveals how infrastructure layers stack differently across merchant maturity levels and technical sophistication. Understanding these divisions clarifies where platform economics compress vendor relationships and where specialized services retain pricing power.
Service Type:
Standalone gateway providers face embedding pressure as merchants consolidate vendor stacks, while integrated service bundles capture larger share of wallet.
- Payment Gateway:API-native platforms encrypt transaction data between merchant checkout and acquiring banks, handling authorization messaging and settlement routing. Demand concentrates among mid-market e-commerce merchants in India seeking RBI-compliant aggregator infrastructure with simplified KYC workflows.
- Digital Wallet:Credential vaults store tokenized payment instruments for one-click checkout across merchant networks. Growth accelerates among small and mid-sized retailers in Brazil building Pix-native checkout experiences for the Central Bank of Brazil's real-time rails.
- Merchant Account:Underlying bank relationships and settlement accounts anchor recurring SaaS fee structures for payment facilitators.
- Fraud Prevention:Machine-learning models automate authorization decisioning and chargeback guarantee economics for high-volume acquirers.
Volume placements concentrate in Payment Gateway; the faster expansion belongs to Digital Wallet.
Technology:
Cost tier separation distinguishes capital-intensive hardware deployments from lightweight software integrations that scale without physical distribution.
- API Integration:RESTful and GraphQL interfaces enable developers to embed checkout, treasury, and lending functions into vertical SaaS platforms. Demand concentrates among software companies in the UK and EU building white-label payment infrastructure for subscription services and utilities piloting account-to-account settlement.
- Contactless Payments:NFC-enabled terminals and tap-to-pay credentials displace legacy magnetic stripe infrastructure in physical retail. Growth accelerates among micro-merchants adopting Android-based terminal estates that support app marketplaces and transform payment devices into merchant operating systems.
- Mobile Payments:SDK-based wallets and in-app purchase rails capture smartphone-native transaction volume.
- Blockchain:Distributed ledger settlement and stablecoin rails address cross-border corridors where correspondent banking relationships face de-risking pressure.
API Integration holds the largest installed base; Contactless Payments is climbing the fastest as terminal replacement cycles accelerate.
End User:
Application context determines whether providers optimize for checkout conversion rates, in-store throughput, or back-office reconciliation automation.
- E-commerce:Online merchants require card-not-present authorization, 3D Secure 2.0 compliance for EU PSD2 mandates, and real-time fraud scoring at the network edge. Demand concentrates among digitally native brands in France, Germany, and the Netherlands retrofitting legacy one-click checkout flows for strong customer authentication requirements.
- Retailers:Brick-and-mortar operators need unified reconciliation across online, in-store, and marketplace channels with hardware-software bundling.
- Service Providers:Platforms and marketplaces demand split-payment logic, escrow functionality, and multi-party settlement orchestration.
- Financial Institutions:Banks and credit unions seek white-label acquiring infrastructure to modernize legacy authorization systems resistant to real-time API connectivity.
E-commerce commands the deepest technology investment; Retailers are gaining share fastest as omnichannel requirements consolidate vendor selection.
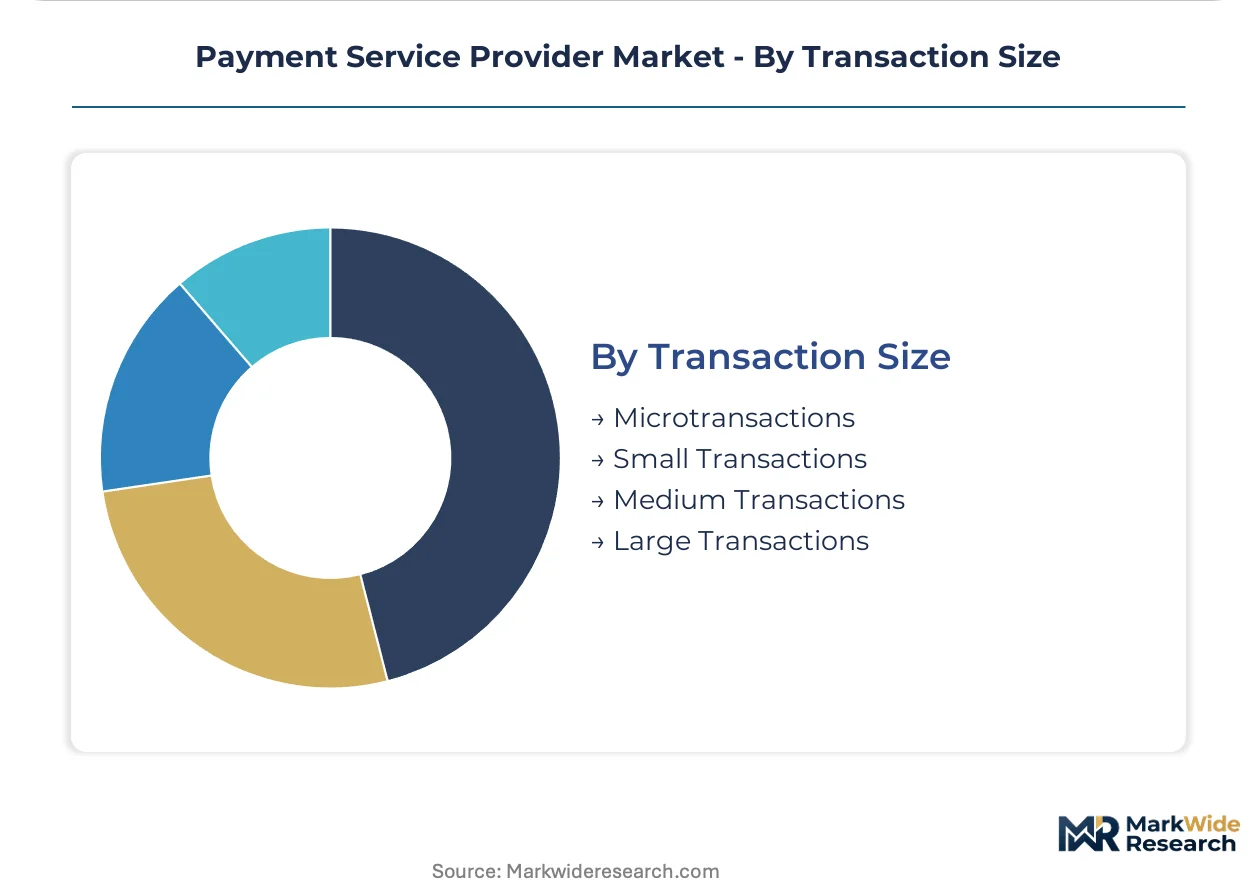
Transaction Size:
Customer type and volume scale shape risk models, interchange economics, and the viability of account-to-account alternatives to card networks.
- Microtransactions:Sub-dollar payments for digital content and transit require specialized routing to avoid minimum fee erosion. Demand concentrates among utility and subscription services in the UK and EU piloting open banking APIs for recurring bill payments that bypass card network interchange.
- Large Transactions:High-value B2B and luxury purchases demand enhanced verification, dynamic currency conversion, and chargeback protection guarantees.
- Small Transactions:Everyday consumer purchases dominate authorization volume and drive tokenization standard adoption.
- Medium Transactions:Mid-ticket retail and professional services balance fraud risk against checkout friction.
Small Transactions process the highest authorization counts; Microtransactions show the steepest expansion trajectory as real-time rails enable viable economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Payment Service Provider Market exhibits a pronounced production-consumption divide. Infrastructure development concentrates in financial technology hubs while merchant adoption accelerates in emerging economies with real-time payment rails. Regulatory fragmentation shapes how providers architect cross-border platform economics.
United States
Durbin Amendment caps on debit interchange compress acquirer margins and force fee structure innovation. The OCC fintech charter framework elevates capital requirements for payment facilitators seeking national operating authority. Silicon Valley and New York clusters anchor API-native platform development for embedded finance distribution.
India
UPI infrastructure reduces merchant onboarding friction from weeks to hours, driving aggregator volume concentration. RBI payment aggregator licensing mandates capital reserves and compliance tooling investments. Mumbai and Bangalore clusters host licensed entities capturing transaction flow through simplified KYC protocols.
United Kingdom
FCA consumer duty rules reshape product governance for gateway providers serving domestic merchants. PSD2 strong customer authentication mandates drive 3D Secure 2.0 retrofit cycles among e-commerce operators. London anchors SaaS-integrated platform development displacing standalone gateway relationships.
Brazil
Pix instant payment rails reached 150 million users within three years, creating merchant acquiring opportunities. Central Bank of Brazil oversight governs payment institution licensing and settlement finality requirements. São Paulo clusters concentrate Pix-native checkout development for e-commerce marketplaces.
Germany
Account-to-account settlement pilots for utilities and subscription services displace card network dependence. BaFin licensing requirements govern payment institution operations and capital adequacy standards. Berlin and Frankfurt clusters develop open banking API infrastructure for recurring bill payment automation.
Payment Service Provider Market Competitive Environment
The competitive structure tilts toward platform aggregators with unified single-stack economics. Market concentration intensifies as merchants consolidate vendor relationships from five layers to two. Three archetypes dominate: API-native developers building embedded finance infrastructure, hardware-software bundlers capturing card-present volume, and full-stack acquirers sustaining omnichannel economics. M&A activity accelerates as legacy processors absorb software functionality, while strategic partnerships proliferate between vertical SaaS platforms and white-label infrastructure providers.
Within the full-stack acquirer tier, Adyen and Stripe exemplify platform economics that compress merchant technology procurement. Worldpay anchors the traditional processor segment with established bank sponsorship relationships. These three entities occupy distinct positioning vectors: unified global acquiring, developer-centric API distribution, and legacy scale infrastructure respectively.
| Leading Market Players |
|---|
| Worldpay |
| Elavon |
| Stripe |
| Fiserv |
| Bank of America Gateway |
| PayPal |
| Checkout.com |
| Square |
| Adyen |
| Others |
Value Chain & Pricing Dynamics
Engineering talent pools in Bangalore and Singapore anchor payment platform development, with labor-cost differentials between these hubs and London or New York widening pricing-tier spreads for API-native infrastructure versus legacy gateway services.
Pricing Analysis
Margin tightening in merchant acquiring reflects Durbin Amendment caps on US debit interchange and similar regulatory pressure in Australia. Three-tier pricing structure across premium API-native platforms, standard bundled services, and economy payment facilitator tiers separates providers by certification depth and settlement speed. Price differentiation hinges on PCI DSS 4.0 compliance grade and volume scale commitments. Micro-merchants exhibit highest price sensitivity; enterprise merchants prioritize uptime guarantees over per-transaction rates.
Supply Chain Analysis
Dual-sourcing requirements for tokenization hardware and settlement banking relationships mandate multi-supplier qualification across India, the United Kingdom, and Singapore. Raw material dependencies include semiconductor chips for terminal manufacturing, encryption modules for PCI-compliant infrastructure, and fiber-optic capacity for real-time data transmission. Supply chain risk centers on single-source vulnerability when correspondent banks de-risk emerging market corridors. Distribution runs through direct API sales to developers and channel partnerships with vertical SaaS platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
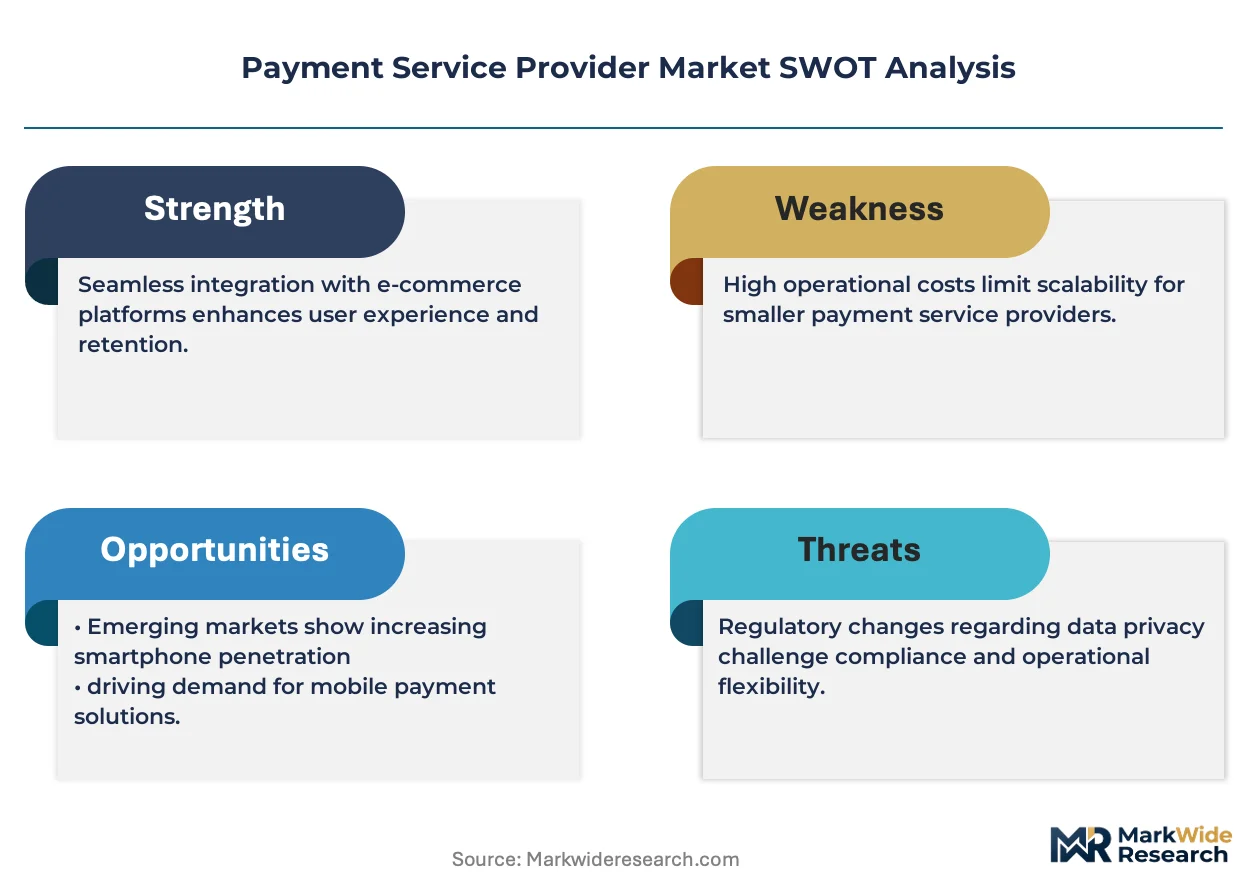
This market reads as a cost-of-compliance story. RBI payment aggregator licensing and PCI DSS 4.0 mandates erect capital-intensive barriers that protect licensed incumbents from unqualified entrants.
For Market Incumbents: Lock in merchant relationships through embedded finance API partnerships with vertical SaaS platforms. Absorb fraud prevention software functionality to defend against pure-play risk analytics entrants. Prioritize certification investment in India's RBI framework to capture UPI rail volume before competitor licensing. For New Entrants and Emerging Players: The price-point gap between premium omnichannel acquirers and economy payment facilitators creates white-space opportunity in Brazil's Pix-native checkout segment and UK account-to-account settlement for utilities. Target mid-market retailers seeking unified reconciliation without enterprise-tier minimums. Lead with developer-centric onboarding velocity against legacy processor certification backlogs. For Investors and Strategic Acquirers: Re-rating potential sits with API-first platforms given embedded finance distribution tailwinds. Long-term viability favors acquirers with single-stack economics spanning online, in-store, and marketplace channels. Monitor scheme certification cycle duration as inflection indicator for product launch velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Embedded Finance Partnership | Vertical SaaS integration automates merchant acquisition for API-native providers. |
| Real-Time Rail Certification | India UPI and Brazil Pix licensing captures volume in fastest-growing settlement corridors. |
| Fraud Prevention Acquisition | Machine-learning risk models differentiate authorization economics against rules-based competitors. |
| Hardware-Software Bundling | Android terminal estates transform payment devices into merchant operating systems. |
| Open Banking API Development | Account-to-account settlement pilots displace card network dependence in UK and EU utilities. |
Study Parameters
Independent corroboration across payment platform executives, merchant acquiring leads, regulatory compliance officers, and vertical SaaS developers underwrites the qualitative findings. Primary fieldwork combined structured interviews with secondary validation against RBI licensing disclosures, SEC filings from listed processors, PCI SSC certification databases, and NPCI transaction volume reports. Bottom-up merchant onboarding data triangulated against top-down acquiring revenue estimates.
Rate-of-change decomposition across the analysis window separates volume growth from pricing and mix effects. Segmentation dimensions modeled include service type, integration technology, end-user application, transaction size tier, and regional regulatory cluster. CAGRs derived from historical authorization volume trajectories, terminal replacement cycle timing, and real-time payment rail adoption curves. Forecast inputs incorporate RBI aggregator license issuance velocity and PSD2 compliance retrofit spend patterns.
Inputs from NPCI, Banco Central do Brasil, and UK Finance were available through the study window; gaps in unlisted processor financial disclosures introduce uncertainty bands around margin estimates. Deviation in correspondent banking de-risking patterns would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Global Payment Processor Market
Payments
Denmark Mobile Payments Market
Payments
China POS Terminals Market
Payments
India Gift Card and Incentive Card Market
Payments
Bus Card Reader Market
Payments
Middle East Gift Card and Incentive Card Market
Payments
Saudi Arabia POS Terminal Market
Payments
Freight Audit and Payment Service Market
Payments
Europe Digital Transaction Management (DTM) Market
Payments
Southeast Asia POS Terminal Market
Payments
Asia-Pacific Payment Gateway Market
Payments
MENA Digital Payments Market
Payments
Australia Payments Market
Payments
Poland Payments Market
Payments
Europe Accounts Payable Automation Market
Payments
Electronic Payment System for Transportation Market