
 Europe Accounts Payable Automation Market | 2026-2036
Europe Accounts Payable Automation Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Accounts Payable Automation Market Analytics
Ireland is rewriting the competitive map for European accounts payable automation through its concentrated cluster of shared service centers and European headquarters for major software vendors. SAP SE leverages its deep ERP integration capabilities to anchor enterprise-grade deployments across the continent. The Sage Group PLC specializes in mid-market cloud migration, while Basware competes on pan-European e-invoicing network density.
Accounts payable automation encompasses software platforms that digitize invoice capture, validate tax and compliance data against regulatory schemas, route approvals through configurable workflows, and execute payment scheduling with full audit trails. These systems reduce manual data entry errors and accelerate cash flow visibility for finance departments. Cloud-based deployment is capturing the fastest expansion as enterprises abandon on-premises maintenance burdens, though ERP Integration remains the stickiest revenue pool because switching costs lock buyers into embedded workflow architectures. Invoice Processing solutions dominate current spending, yet Analytics modules are widening margin profiles as vendors bundle predictive cash forecasting.
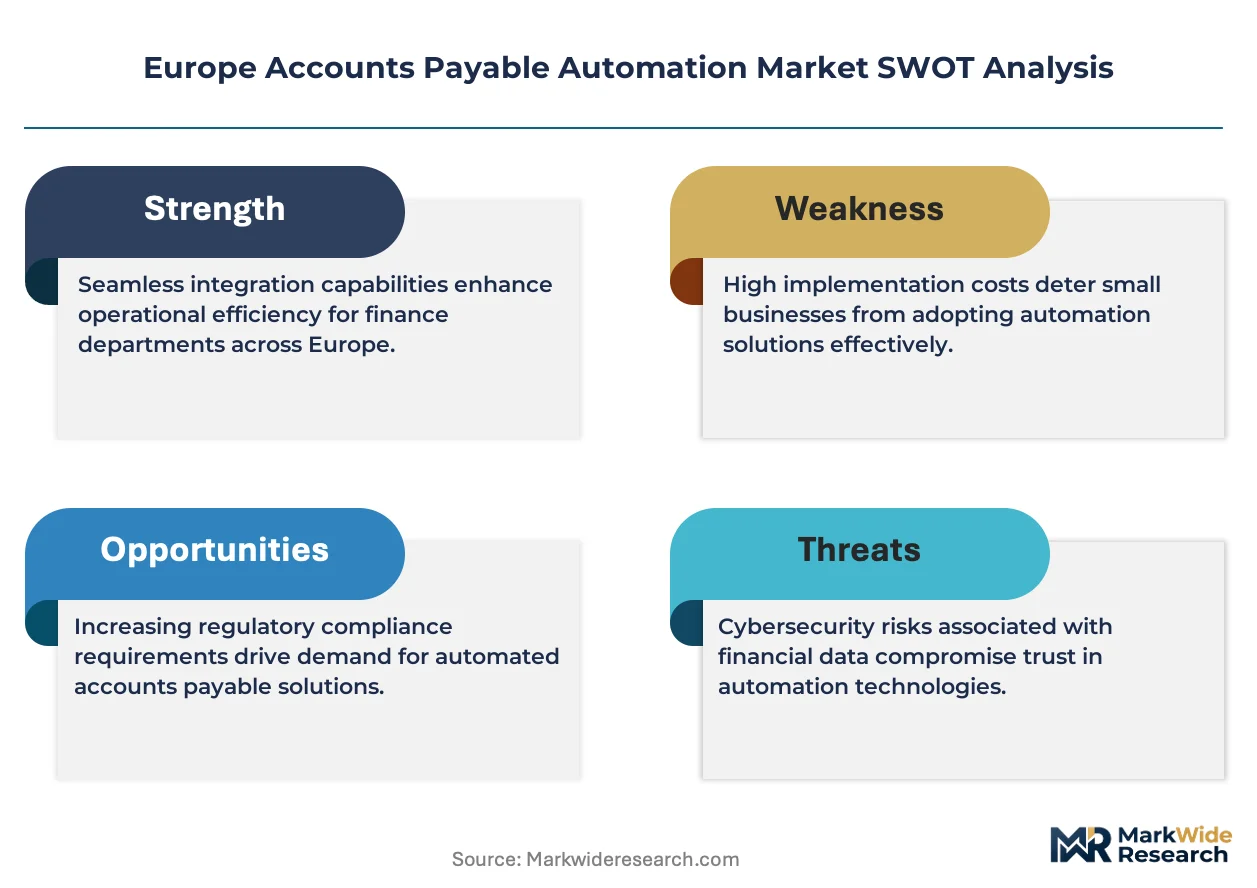
GDPR constrains how vendor platforms process supplier banking details and payment metadata across borders, while the EU AI Act imposes risk-classification requirements on automated approval algorithms. The CSRD disclosure rules are forcing larger enterprises to demand granular carbon and spend tracking from their AP automation providers, reshaping product roadmaps. Stakeholders must weigh whether to build compliance-native platforms or retrofit existing stacks as regulatory layering intensifies.
Market Dynamics
The EU's mandatory e-invoicing rollout and the Digital Operational Resilience Act are compressing replacement cycles for legacy paper-based systems. German manufacturing enterprises are accelerating their migration to automated invoice-to-payment workflows under regulatory pressure.
Growth Catalysts
- EU e-invoicing mandates:Member states are enforcing structured electronic invoice exchange, compelling enterprises to abandon manual processing. This regulatory pressure creates immediate replacement demand across procurement departments.
- Manufacturing digitization:German industrial enterprises are embedding AP automation into ERP modernization programs. These buyers prioritize touchless processing to reduce supplier payment friction.
- Cloud migration:Finance departments are abandoning on-premises maintenance burdens for SaaS deployment models. This shift lowers entry barriers for mid-market adoption.
Market Restraints
- GDPR compliance costs:Cross-border supplier banking data processing requires expensive platform re-architecture. Vendors must maintain localized data residency for payment metadata.
- ERP switching friction:Embedded workflow architectures create high exit costs for enterprise buyers. This concentration locks revenue pools with incumbent vendors.
- Legacy technical debt:Decades-old invoice formats and supplier onboarding databases resist standardization. Integration complexity extends implementation timelines.
Strategic Opportunities
- Eastern European expansion:Polish and Romanian shared service centers are underpenetrated relative to Western adoption rates. These hubs offer scale economies for pan-European deployment.
- CSRD carbon tracking:The Corporate Sustainability Reporting Directive is forcing spend transparency requirements. AP platforms can capture supplier emissions data for disclosure compliance.
- AI-ML convergence:Machine learning anomaly detection combined with automated approval routing addresses fraud prevention gaps. This bundling widens margin profiles beyond basic invoice processing.
Industry Challenges
- EU AI Act risk classification:Automated approval algorithms face new conformity assessment requirements. Vendors must document decision logic for high-risk financial system categorization.
- Tax schema fragmentation:National e-invoicing standards vary across France, Italy, and Germany. Multi-jurisdiction compliance demands continuous platform adaptation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Accounts Payable Automation Market |
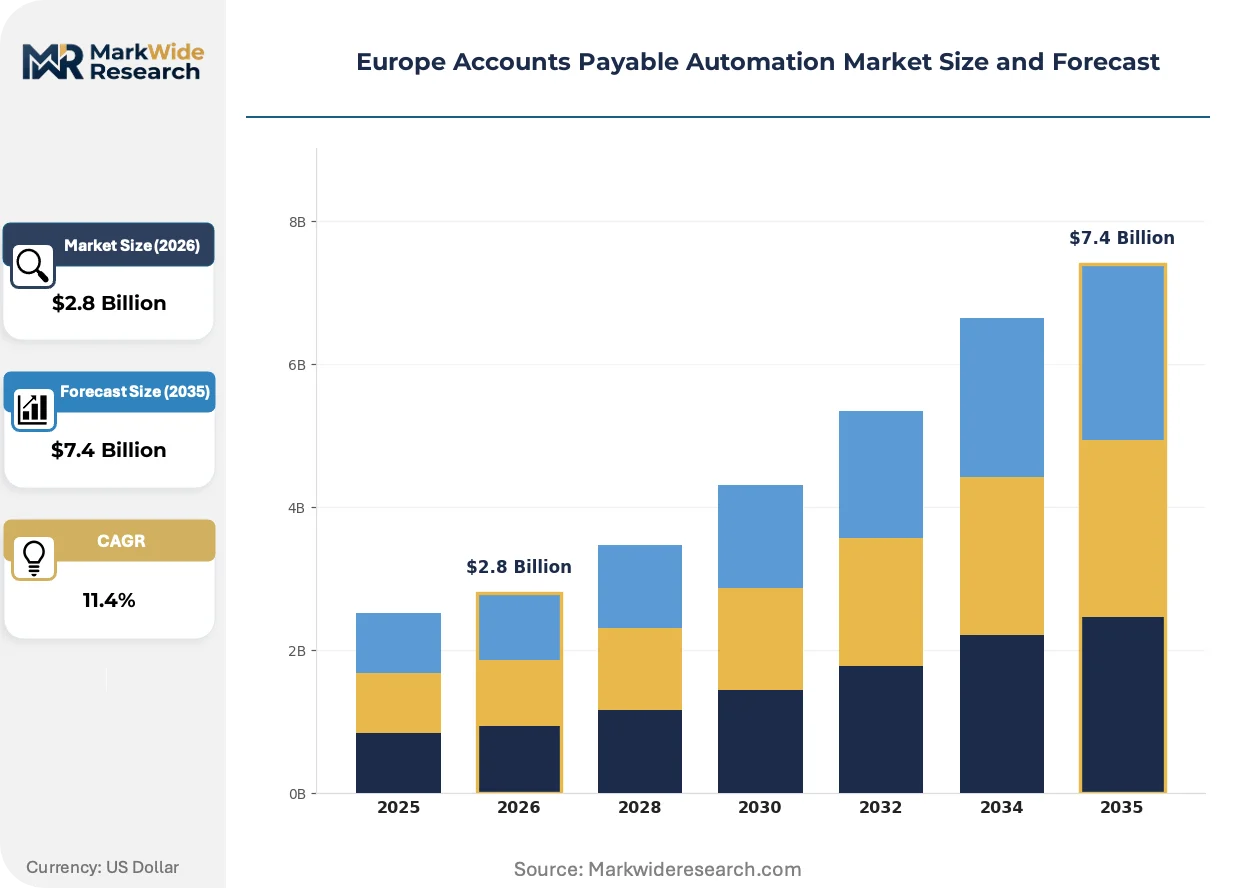
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, SaaS End User: Manufacturing, Retail, Healthcare, BFSI Solution: Invoice Processing, Workflow Automation, Reporting Tools, Analytics Integration Level: ERP Integration, API Connectivity, Data Sync, Custom Integration |
| Companies Covered | SAP SE, The Sage Group PLC, Comarch SA, Bottomline Technologies, Inc., Tipalti, Inc., AvidXchange Holdings, Inc., Zycus, Inc., Basware, Coupa Software, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Accounts Payable Automation Market Evolving Landscape
Intelligent document capture and predictive cash forecasting are displacing rule-based workflow engines. Vendors are bundling analytics modules to escape commodity pricing in basic invoice processing.
Optical character recognition combined with natural language processing is digitizing unstructured supplier invoices across multiple languages and formats. Mid-market enterprises in France and the United Kingdom are adopting these tools fastest. This capability is digitizing the last paper-heavy corner of finance operations and compressing implementation timelines from quarters to weeks.
The EU AI Act imposes risk-classification requirements on automated approval algorithms used in payment authorization. Financial software vendors must now document decision logic and maintain human oversight interfaces for high-risk system categorization. German and French enterprises are demanding pre-certified platforms to avoid regulatory liability.
Subscription-based pricing is displacing perpetual license models as buyers prefer operational expenditure treatment. Mid-market finance departments are rejecting large upfront capital commitments for cloud-native alternatives. This preference shift is most visible in the United Kingdom's SaaS-heavy procurement culture.
Europe Accounts Payable Automation Market Segmentation
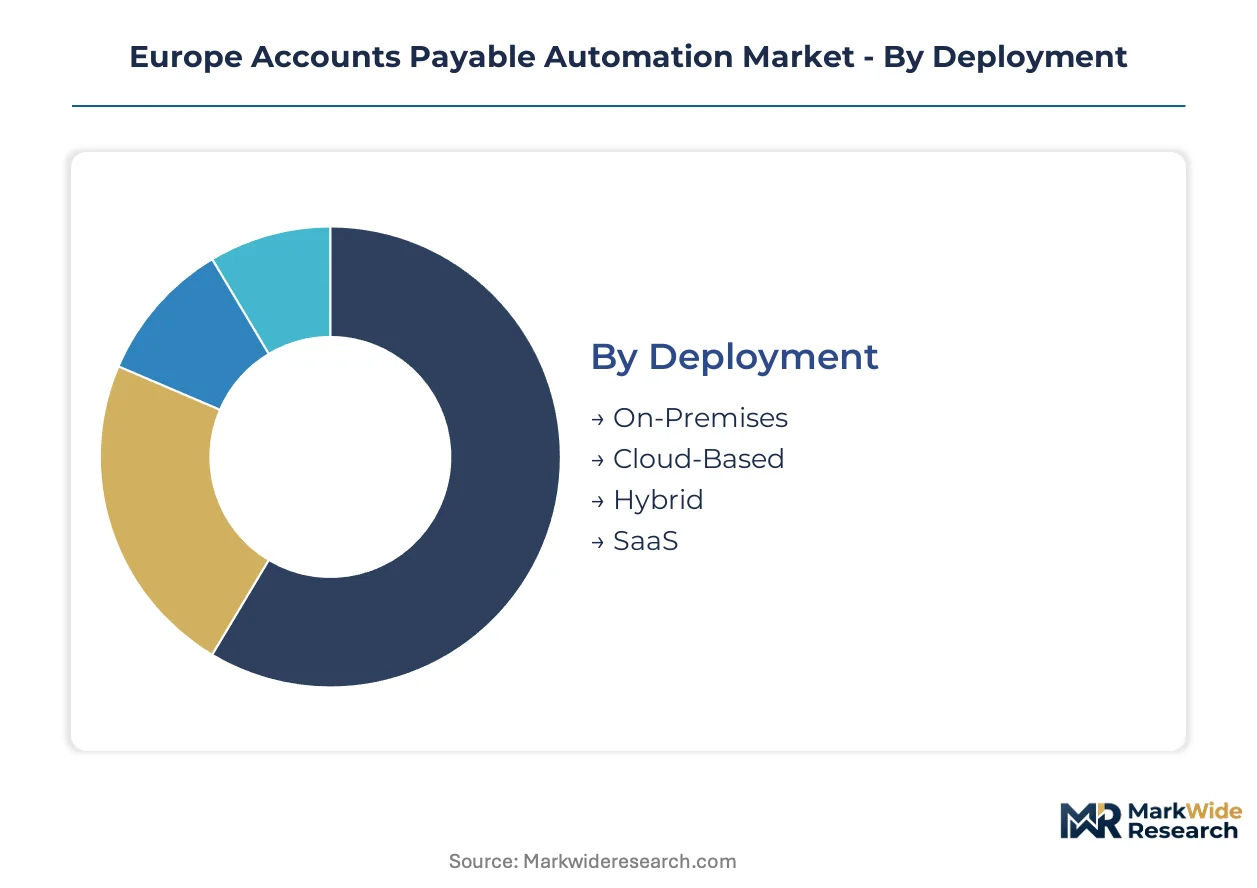
Segmentation in the Europe Accounts Payable Automation Market reveals how deployment choices, end-user verticals, and integration architectures shape vendor positioning. Buyers prioritize different capabilities based on regulatory exposure, existing technology stacks, and supplier network complexity.
Deployment:
Mature enterprise installations anchor on-premises footprints, while cloud-native architectures accelerate fastest among mid-market adopters.
- On-Premises:Legacy installations within German automotive and French aerospace supply chains maintain sovereign data control for GDPR-sensitive supplier banking records. These deployments resist migration due to embedded ERP customization and audit trail continuity requirements.
- Cloud-Based:SaaS platforms hosted in Ireland and Frankfurt data centers serve UK retail and Benelux logistics operators seeking elastic capacity. Finance departments prioritize these models to eliminate hardware refresh cycles and accelerate month-end close processes.
- Hybrid:Split architectures separate invoice capture in-country from analytics processing in regional cloud hubs. Italian and Spanish enterprises favor this pattern to satisfy tax authority data residency rules while accessing machine learning capabilities.
- SaaS:Pure subscription models dominate new procurement in the United Kingdom and Nordic markets. Procurement teams value predictable operational expenditure treatment and rapid feature deployment without IT intervention.
On-Premises handles the majority of throughput; Cloud-Based is the fastest mover on share.
End User:
Cost tier stratification separates high-volume transaction processors from compliance-intensive regulated sectors.
- Manufacturing:German industrial enterprises embed AP automation into SAP-centric ERP modernization programs. Touchless invoice-to-payment workflows reduce supplier friction across tiered automotive supply chains.
- Retail:High-velocity invoice matching against purchase orders and goods receipts dominates demand. UK and French omnichannel operators prioritize real-time cash visibility across multi-currency supplier networks.
- Healthcare:NHS trusts and German hospital networks require audit trails for public procurement compliance. These buyers demand pre-certified platforms meeting EU AI Act risk classification standards.
- BFSI:Banking and insurance carriers in London, Frankfurt, and Zurich impose strict fraud detection and segregation-of-duties requirements. Regulatory scrutiny from BaFin and the FCA drives investment in anomaly detection capabilities.
Manufacturing commands the largest installed base; Retail is expanding most quickly as e-commerce procurement volumes surge.
Solution:
Application depth varies from commodity document digitization to predictive financial intelligence.
- Invoice Processing:Optical character recognition and natural language processing engines digitize unstructured supplier documents across multilingual formats. French and UK mid-market enterprises adopt these tools to compress implementation timelines.
- Workflow Automation:Configurable approval routing with mobile delegation addresses distributed procurement teams. German manufacturers embed these capabilities to enforce delegation matrices across plant-level purchasing.
- Reporting Tools:Standardized dashboards for audit preparation and management review serve compliance-focused buyers. Benelux shared service centers leverage these for consolidated group reporting.
- Analytics:Predictive cash forecasting and supplier spend optimization widen vendor margin profiles. CSRD disclosure requirements are accelerating demand for carbon-intensity tracking within procurement data.
Invoice Processing captures current spending concentration; Analytics is climbing the fastest as buyers bundle intelligence modules.
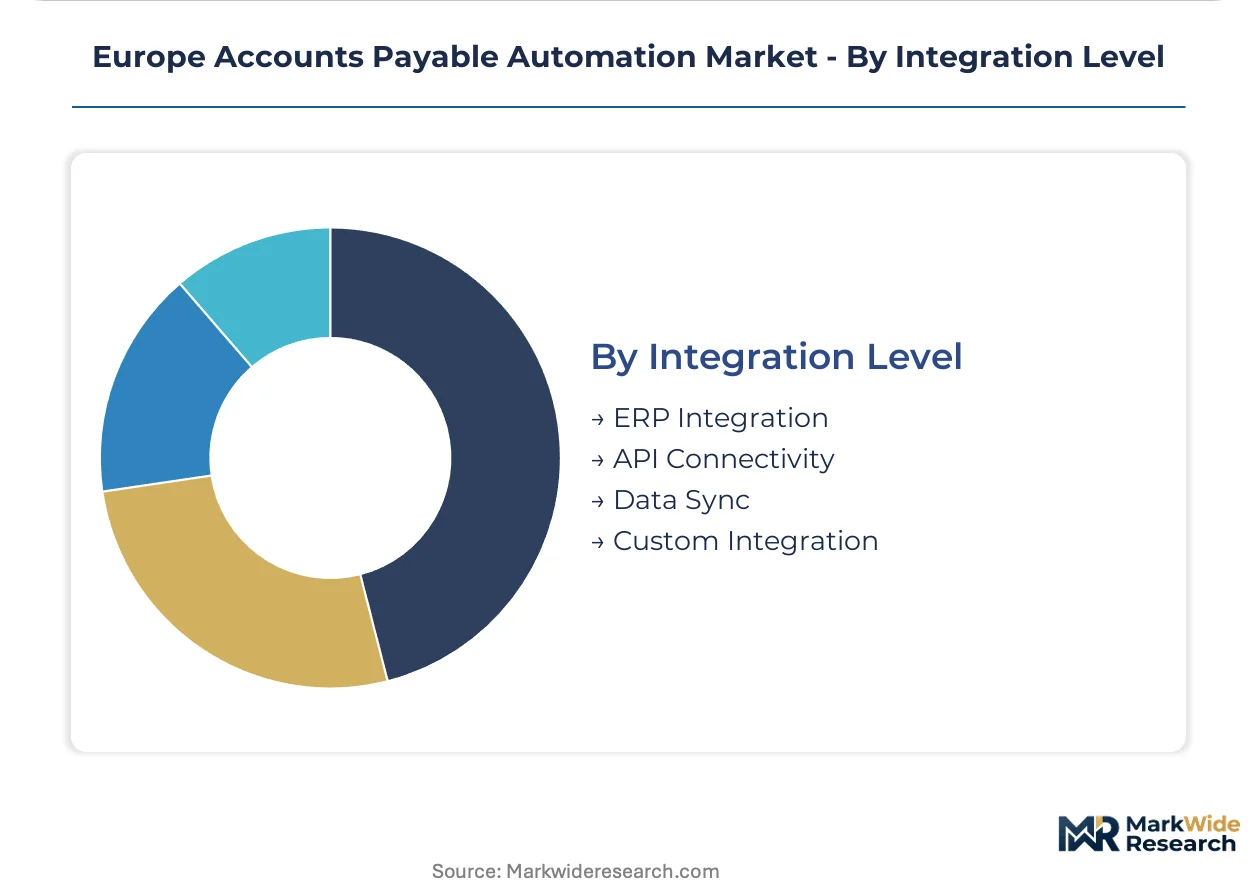
Integration Level:
Supply concentration in embedded ERP architectures creates divergent paths for native versus modular connectivity.
- ERP Integration:Native connectors to SAP, Oracle, and Microsoft Dynamics lock revenue pools through high switching costs. German enterprise buyers rarely displace incumbent embedded workflows.
- API Connectivity:RESTful interfaces enable best-of-breed procurement and treasury system orchestration. UK fintech-heavy finance stacks favor this pattern for rapid vendor substitution.
- Data Sync:Batch and real-time synchronization protocols maintain consistency across distributed ledgers. Polish and Romanian shared service centers deploy these for pan-European hub operations.
- Custom Integration:Bespoke middleware connects legacy mainframe systems and industry-specific procurement platforms. Aerospace and defense supply chains in France and the UK require these specialized bridges.
ERP Integration dominates revenue retention; API Connectivity is gaining share fastest as composable finance architectures proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturing enterprises deploy touchless invoice processing at scale, while UK finance teams favor SaaS procurement for operational flexibility. French buyers prioritize e-invoicing network density. Irish shared service centers concentrate vendor European headquarters.
Germany
Automotive supply chains in Stuttgart and Munich drive enterprise-grade ERP modernization. BaFin scrutiny over payment system resilience accelerates replacement of legacy paper workflows. Industrial clusters in Baden-Württemberg embed AP automation into SAP-centric procurement architectures.
United Kingdom
NHS trusts and London fintech stacks demand pre-certified platforms meeting EU AI Act standards. The FCA's operational resilience expectations push banking and insurance carriers toward anomaly detection capabilities. SaaS procurement culture dominates procurement decisions in Greater London.
France
Aerospace and luxury goods supply chains in Île-de-France require multi-jurisdiction tax schema compliance. ANSM and CNIL oversight shapes data residency requirements for supplier banking details. Lyon and Toulouse manufacturing hubs adopt intelligent document capture for multilingual invoice processing.
Ireland
Dublin's concentrated cluster of shared service centers anchors pan-European deployment scale. GDPR data residency rules favor local cloud infrastructure for payment metadata processing. Software vendor European headquarters clustering creates talent density for platform development.
Poland
Kraków and Warsaw shared service centers offer cost arbitrage for Western European enterprise back-office consolidation. National e-invoicing alignment with EU mandates lags Western adoption rates. These hubs present expansion opportunities for vendors seeking scale economies.
Europe Accounts Payable Automation Market Competitive Landscape
Capability concentration sits with ERP-native vendors; scale advantage sits with cloud-native challengers. The market structures around three tiers: embedded workflow incumbents, best-of-breed specialists, and vertical SaaS entrants. Strategic moves center on API ecosystem expansion and AI-ML feature bundling to escape commodity invoice processing pricing.
Within the ERP-native tier, SAP SE and The Sage Group PLC exemplify divergent scale positions. SAP anchors enterprise-grade deployments through deep system integration, while Sage occupies the mid-market cloud migration vector. Basware represents the network-density archetype, competing on pan-European e-invoicing reach rather than embedded ERP position.
| Leading Market Players |
|---|
| SAP SE |
| The Sage Group PLC |
| Comarch SA |
| Bottomline Technologies, Inc. |
| Tipalti, Inc. |
| AvidXchange Holdings, Inc. |
| Zycus, Inc. |
| Basware |
| Coupa Software |
| Others |
Value Network & Pricing Analysis
Ireland's concentrated cluster of shared service centers and vendor European headquarters anchors margin pools in embedded ERP integration and cloud-native deployment tiers. German automotive and French aerospace supply chains maintain premium pricing for sovereign data control, while UK retail operators drive SaaS commoditization through operational expenditure preferences.
Pricing Analysis
Long-term subscription contracts dominate enterprise procurement, with three-year SaaS agreements capturing the largest revenue pools. Price differentiation rests on ERP integration depth and CSRD-compliant carbon tracking modules. Cost compression in basic invoice processing is intensifying because cloud-native challengers bundle analytics to escape commodity tiers. Mid-market finance departments in the United Kingdom exhibit highest price sensitivity, while German industrial buyers prioritize switching-cost insulation over upfront expenditure.
Supply Chain Analysis
Contract manufacturing concentration in Irish data centers and Frankfurt cloud hubs holds capacity for pan-European deployment. Software development draws from talent clusters in Dublin, London, and Berlin, with localization engineering tethered to Warsaw and Kraków shared service centers. Single-source vulnerability runs through SAP-centric integration architectures that lock buyers into incumbent ecosystems. Distribution runs through direct enterprise sales teams in Stuttgart and Munich, supplemented by channel partners in Benelux logistics corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe's accounts payable automation market sits in early-cycle expansion as EU e-invoicing mandates and DORA compliance deadlines compress replacement timelines for legacy paper workflows. Regulatory layering across GDPR, EU AI Act, and CSRD disclosure rules accelerates platform consolidation decisions.
For Market Incumbents: Insulate embedded ERP revenue pools through deeper SAP and Oracle connector certification, while pre-empting cloud-native substitution by bundling predictive analytics modules. Prioritize CSRD-compliant carbon tracking development to capture sustainability disclosure budgets before vertical SaaS entrants fragment procurement intelligence spend. For New Entrants and Emerging Players: Polish and Romanian shared service centers offer underpenetrated white-space for cost-arbitrage deployment models. Target mid-market manufacturing hubs in Lyon and Toulouse with rapid-implementation intelligent document capture, leveraging API-first architectures to bypass incumbent switching-cost barriers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed best-of-breed specialists possessing dense e-invoicing network coverage but lacking ERP integration depth. Long-term viability hinges on AI-ML feature differentiation and regulatory pre-certification moats. Monitor EU AI Act conformity assessment timelines as inflection indicator for platform consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| CSRD Compliance Module Launch | Captures sustainability disclosure budgets from German automotive and French luxury goods supply chains. |
| API Ecosystem Expansion | Enables orchestration with UK fintech-heavy treasury stacks and Benelux logistics operators. |
| AI-ML Feature Bundling | Widens margin profiles beyond commodity invoice processing through anomaly detection capabilities. |
| Eastern European Hub Establishment | Delivers cost arbitrage for pan-European deployment from Kraków and Warsaw shared service centers. |
| EU AI Act Pre-Certification | Addresses BaFin and FCA scrutiny for NHS trusts and London banking carriers. |
Research Methodology
The analysis maps cloud-native deployment, ERP-integrated on-premises, and hybrid architectures, each validated through CFOs, IT procurement officers, shared service center directors, and platform integration specialists. Primary fieldwork combined with secondary validation from SEC filings, EU regulatory disclosure databases, hyperscaler capex reports, and enterprise software vendor financial statements. Bottom-up sizing of invoice processing volumes and top-down cross-check against ERP modernization expenditure patterns ensured triangulation integrity.
Assumptions held regulatory enforcement timelines and cloud migration velocity constant across the projection horizon, while varying manufacturing digitization intensity and mid-market SaaS penetration rates. Segmentation dimensions modeled include deployment model, organization size, vertical industry, integration complexity, and regional adoption pattern. CAGRs derived from logistic diffusion curves fitted to historical ERP replacement cycles and e-invoicing mandate compliance trajectories. Forecast inputs incorporated EU member state transposition schedules for DORA and national e-invoicing standards.
The forecast holds incumbent behavior within observed patterns; aggressive API ecosystem expansion by cloud-native challengers or accelerated CSRD enforcement would shift outcomes. Quarterly review of EU AI Act conformity assessment publication and member state e-invoicing mandate transposition timelines is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Global Financial Cards and Payments Market
Payments
Voice-Based Payments Market
Payments
Europe Digital Transaction Management (DTM) Market
Payments
Latin America Retail Cash Management Market
Payments
Global Smart Payment Systems Market
Payments
Spain Payments Market
Payments
M Commerce Payment Market
Payments
Mexico Real Time Payments Market
Payments
Italy Payments Market
Payments
Remote Deposit Capture Market
Payments
Belgium POS Terminals Market
Payments
Malta POS Terminal Market
Payments
Saudi Arabia POS Terminal Market
Payments
Payment Analytics Software Market
Payments
Europe Credit Cards Market
Payments
Middle East and Africa Buy Now Pay Later Services Market