
 Europe Digital Transaction Management (DTM) Market | 2026-2036
Europe Digital Transaction Management (DTM) Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Digital Transaction Management (DTM) Market Foresight
A shortage of qualified cybersecurity auditors is reorganizing how European enterprises evaluate DTM vendors. DocuSign Inc. leverages its established trust framework to sustain enterprise renewals across the continent. Adobe Inc. anchors its position through deep Creative Cloud integration with document workflows. Wolters Kluwer N.V. competes on regulatory-specific templates tailored to EU compliance environments.
Digital Transaction Management encompasses electronic signature capture, document lifecycle orchestration, identity verification protocols, and audit-trail preservation within cloud-native or on-premises architectures. The technology stack employs XAdES and PAdES signature formats to ensure legal validity under eIDAS regulation while enabling straight-through processing for commercial contracts. Cloud-based deployment now captures the bulk of new implementations as banks and insurers prioritize elastic capacity over capital-intensive infrastructure. Electronic signatures generate recurring margin pools through notarization-tier certification, whereas workflow automation segments expand fastest among mid-market legal practices seeking matter-management integration.
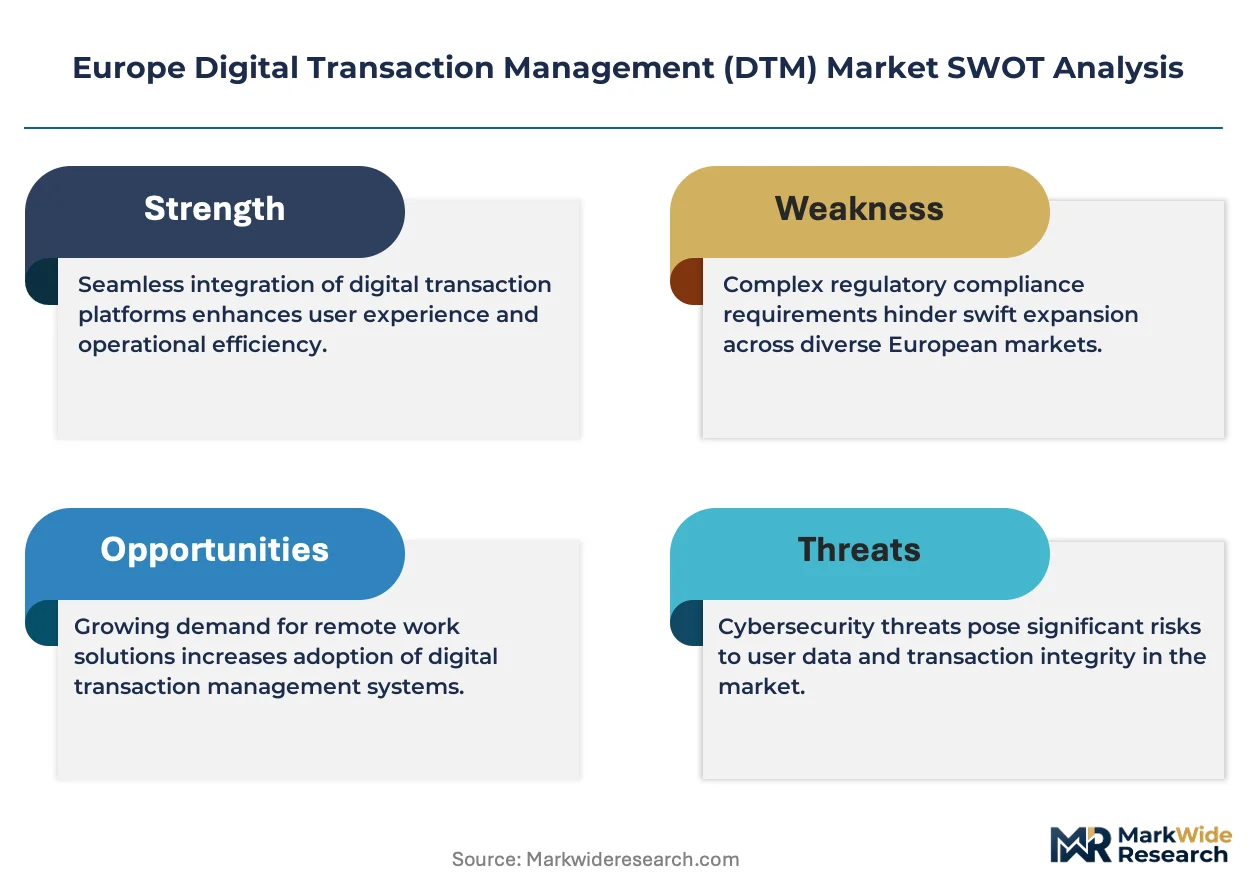
eIDAS 2.0, GDPR, and the EU AI Act collectively establish a three-layer compliance architecture: identity assurance, data residency, and algorithmic transparency. ETSI standards for qualified electronic signatures create technical barriers that filter non-EU solution providers from sensitive public-sector procurement. Stakeholders must track how member-state transposition timelines for eIDAS 2.0 wallet infrastructure alter competitive access patterns across national procurement frameworks.
Market Dynamics
eIDAS 2.0 wallet infrastructure deployment is forcing European banks and insurers to re-architect their identity verification stacks ahead of member-state transposition deadlines, compressing procurement cycles and elevating vendor qualification barriers.
Growth Catalysts
- EU AI Act compliance mandates:Automated decision-making systems in French and German banking now require algorithmic audit trails, pulling demand for DTM platforms with embedded transparency logging.
- Cloud-native workflow adoption:Dutch insurers and Spanish legal practices are abandoning on-premises document servers for elastic SaaS orchestration, prioritizing API-first architectures.
- Public-sector digitization:National procurement frameworks in Italy and Poland now mandate qualified electronic signatures for government contracts, creating baseline demand pools.
Market Restraints
- Qualified trust service concentration:ETSI-certified signature providers cluster in Germany, France, and the Netherlands, creating single-point-of-failure risks for cross-border transactions.
- GDPR data residency friction:Multi-cloud DTM deployments face architectural constraints requiring EU-sovereign infrastructure, limiting vendor flexibility and raising operational overhead.
- Legacy system integration costs:Core banking platforms in Southern and Eastern Europe still rely on COBOL-based document repositories, extending implementation timelines and professional services spend.
Strategic Opportunities
- Nordic SME legal automation:Swedish and Danish mid-market law firms show sub-15% DTM penetration, presenting first-mover expansion space for matter-management-integrated platforms.
- eIDAS 2.0 wallet interoperability:The European Digital Identity Wallet framework creates standardized API surfaces, enabling new entrants to bypass proprietary identity stack development.
- AI-powered contract analytics:Natural language processing convergence with DTM repositories is opening clause-extraction and risk-scoring revenue streams adjacent to signature workflows.
Industry Challenges
- Qualified cybersecurity auditor scarcity:The pool of professionals certified under EUCC and SOGIS-MRA mutual recognition frameworks remains insufficient for vendor evaluation throughput.
- Cross-border recognition complexity:Member-state variations in eIDAS 2.0 transposition timelines create compliance fragmentation for pan-European contract workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Digital Transaction Management (DTM) Market |
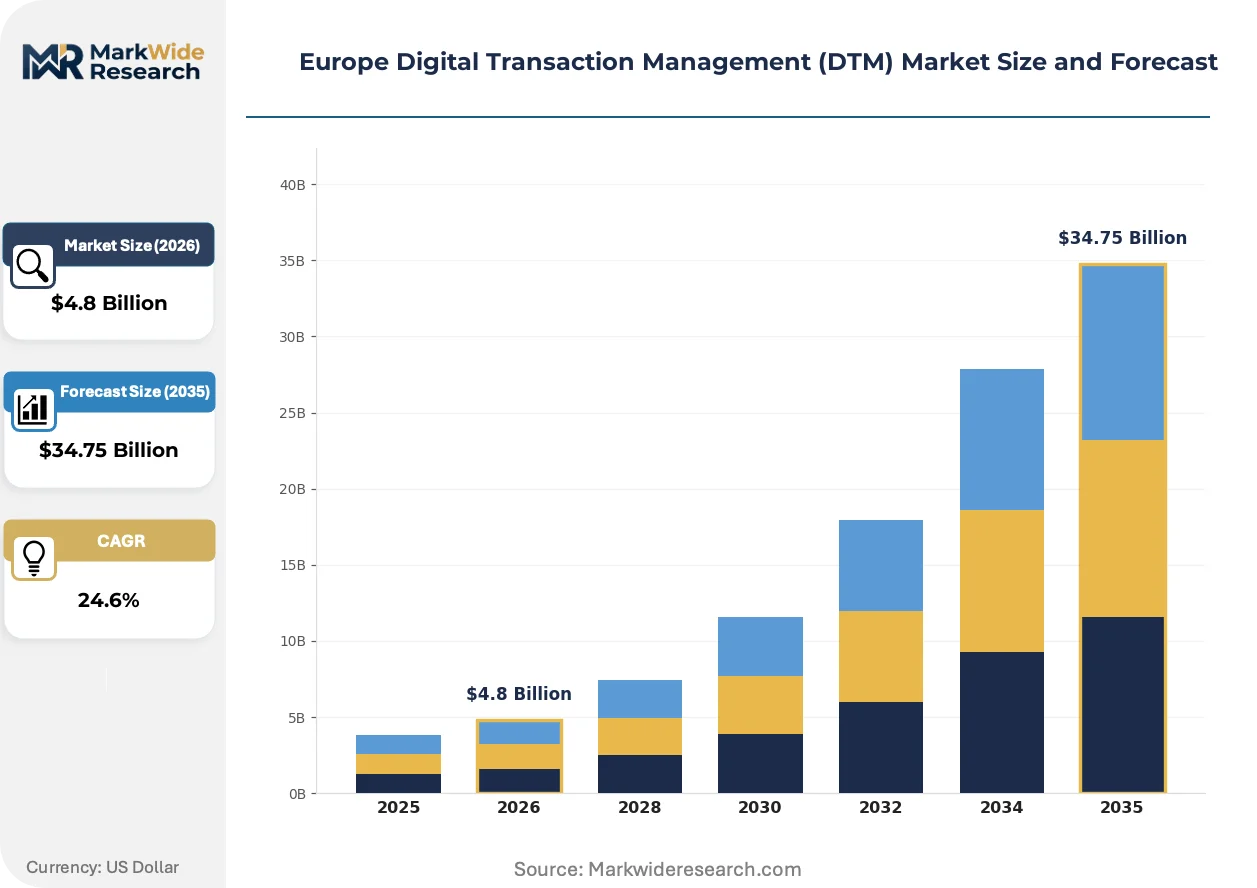
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $34.75 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Electronic Signatures, Document Management, Workflow Automation, Payment Processing Deployment Model: On-Premises, Cloud-Based, Hybrid, SaaS End User: Banking, Insurance, Government, Legal Industry Vertical: Healthcare, Retail, Real Estate, Education |
| Companies Covered | DocuSign Inc., Adobe Inc., Wolters Kluwer N.V., Entrust Corp., Namirial SpA, Nintex Group Pty Ltd, OneSpan Inc., Kofax Inc., Ascertia, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Digital Transaction Management (DTM) Market Shifts & Advancements
Artificial intelligence is embedding into document lifecycle management at the verification and analytics layers, while regulatory pressure accelerates standardization of identity assurance protocols across the continent.
Blockchain-based timestamping and notarization is fragmenting across European DTM deployments. The technology provides immutable audit trails for high-value commercial contracts. German automotive suppliers and French luxury goods exporters are piloting these capabilities at scale. This fragmentation is compressing margins for traditional certificate authority services while opening API monetization paths for platform vendors.
The EU AI Act's risk-based classification system is reshaping how DTM platforms handle automated contract analysis. High-risk AI applications in credit and insurance underwriting now require human-in-the-loop documentation. Belgian and Austrian financial institutions are rebuilding their workflow engines to capture explainability logs. The regulation is most acutely affecting cloud-native entrants lacking established governance frameworks.
Enterprise buying committees are consolidating DTM procurement under chief information security officers rather than line-of-business heads. Centralized vendor evaluation is displacing departmental software selection in UK and Irish professional services firms. This shift is elevating security certification and penetration testing documentation above feature comparisons in competitive evaluations. The pattern is most visible among Big Four accounting networks standardizing across continental offices.
Europe Digital Transaction Management (DTM) Market Segmentation
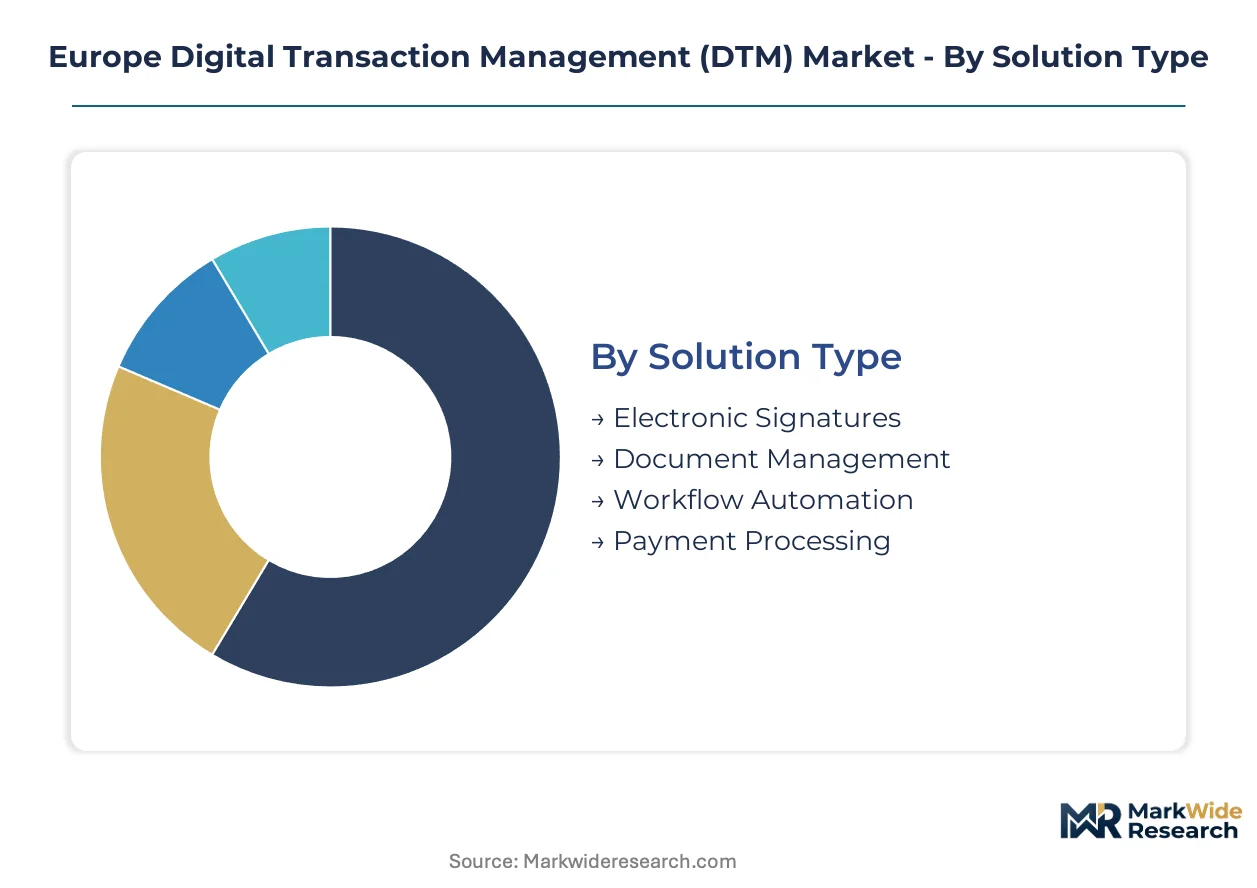
Segmentation in the European DTM market reveals how regulatory fragmentation and infrastructure maturity create divergent value capture patterns. Solution architecture choices directly determine compliance burden and vendor qualification success across member-state procurement frameworks.
Solution Type:
Electronic signature platforms face intensifying substitution pressure from eIDAS 2.0 wallet infrastructure, while workflow automation tools embed more deeply into enterprise tech stacks.
- Electronic Signatures:XAdES and PAdES formats ensure qualified legal status under eIDAS regulation. German banks and French insurers concentrate procurement here, driven by public-sector contract mandates requiring notarization-tier certification.
- Document Management:Cloud-native repositories with EU-sovereign data residency controls. Dutch legal practices and Belgian financial institutions prioritize these systems, constrained by GDPR cross-border transfer restrictions.
- Workflow Automation:API-first orchestration layers connecting DTM to core banking and ERP systems.
- Payment Processing:Embedded settlement rails within signature completion workflows.
Electronic signatures anchors the volume base while workflow automation gains share at the steepest rate.
Deployment Model:
Cost tier stratification separates capital-intensive on-premises installations from elastic consumption models, with hybrid architectures capturing mid-market budget flexibility.
- Cloud-Based:Multi-tenant SaaS infrastructure with automatic scaling and regional failover. Spanish insurers and Italian government agencies lead adoption here, pulled by disaster recovery requirements and API ecosystem expansion.
- SaaS:Subscription delivery with embedded compliance updates and penetration-tested security modules. Nordic professional services firms favor this model, constrained by shortage of in-house cybersecurity expertise.
- On-Premises:Dedicated hardware installations for classified document processing.
- Hybrid:Split architectures keeping sensitive identity data local while pushing workflow logic to cloud.
Cloud-based deployment captures the broadest customer base while SaaS shows the steepest expansion trajectory.
End User:
Application urgency varies sharply—banking faces eIDAS 2.0 deadline pressure while legal segments lag in digitization maturity.
- Banking:Full-stack identity verification and straight-through processing for commercial lending. German and Austrian institutions concentrate investment here, driven by EU AI Act algorithmic audit requirements for automated credit decisions.
- Government:Qualified electronic signature mandates for procurement and citizen service delivery. Italian and Polish national frameworks create baseline demand pools through transposed eIDAS regulations.
- Insurance:Policy lifecycle management with embedded claims documentation.
- Legal:Matter-management integration for contract drafting and client collaboration.
Banking anchors the volume base while government expands most quickly under regulatory mandate acceleration.
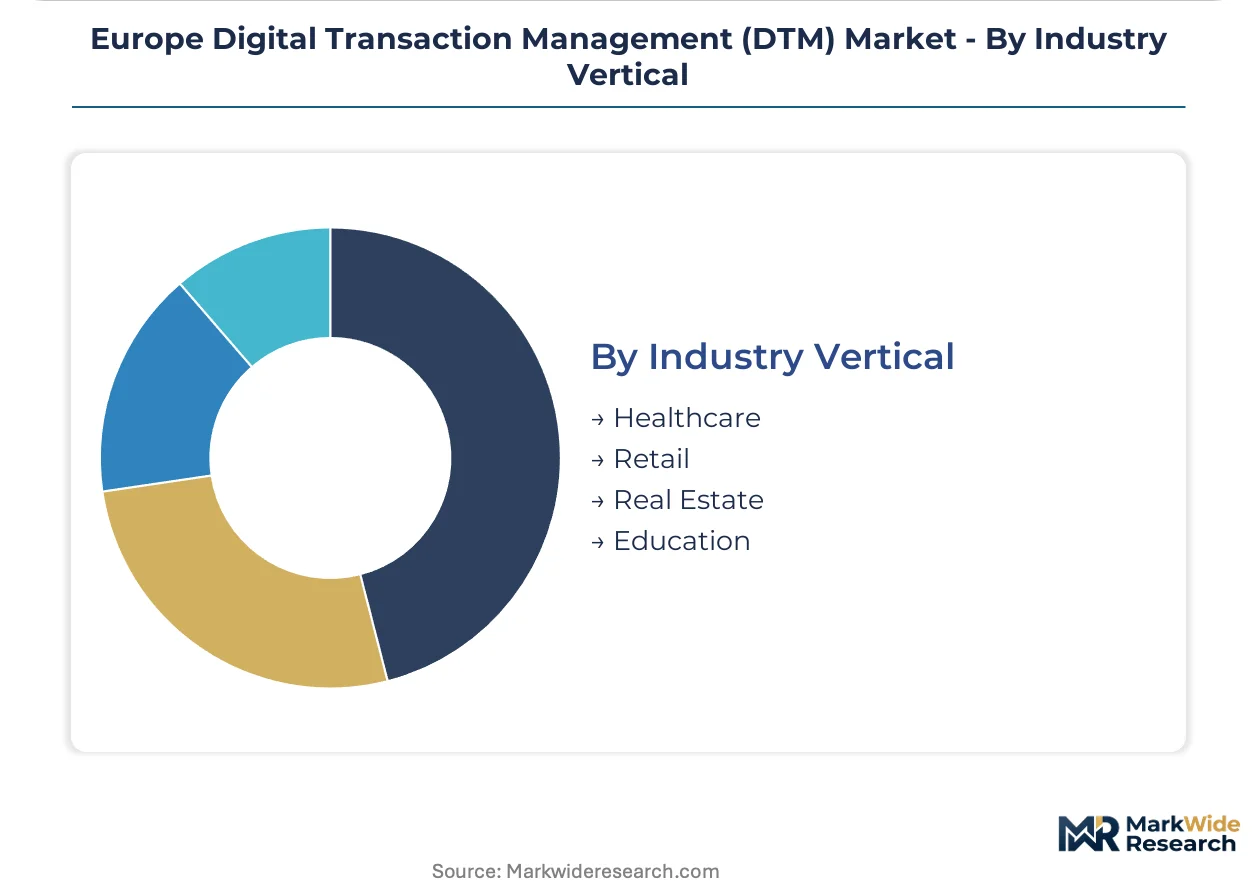
Industry Vertical:
Customer type maturity separates regulated sectors with procurement standardization from fragmented verticals with departmental purchasing patterns.
- Healthcare:Patient consent management and clinical trial documentation with EMA audit trail requirements. French hospital networks and Swiss pharmaceutical sponsors concentrate demand here, constrained by cross-border data residency complexity.
- Real Estate:Property transaction digitization with notary integration. Spanish and Portuguese markets show adoption concentration, pulled by mortgage processing efficiency targets.
- Retail:Supplier contract automation and B2B payment orchestration.
- Education:Credential verification and student enrollment workflows.
Healthcare anchors the volume base while real estate climbs the fastest as property markets digitize conveyancing processes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German and Dutch trust service markets while Italian and Spanish procurement frameworks compress vendor margins through competitive tendering requirements.
Germany
Automotive suppliers and commercial banks drive qualified electronic signature procurement for cross-border contract execution. The Federal Network Agency enforces ETSI standards for trust service providers, creating certification bottlenecks. Berlin and Frankfurt host the densest concentration of eIDAS-qualified trust service operators serving pan-European banking consortia.
France
Luxury goods exporters and insurance underwriters demand algorithmic audit trails under EU AI Act risk classifications. The CNIL coordinates GDPR enforcement with sector-specific financial regulators. Paris-based legal technology clusters are rebuilding workflow engines to capture explainability logs for automated credit decisions.
Netherlands
Dutch insurers and pension funds prioritize cloud-native document orchestration with EU-sovereign data residency. The Dutch Data Protection Authority enforces cross-border transfer restrictions through binding corporate rules. Amsterdam's fintech corridor anchors the highest SaaS DTM penetration rates among mid-market professional services firms.
Italy
National procurement frameworks mandate qualified electronic signatures for government contracts and public healthcare documentation. The Agency for Digital Italy accelerates eIDAS 2.0 wallet infrastructure deployment timelines. Milan's banking consortiums are re-architecting identity verification stacks ahead of transposition deadlines.
Poland
Public-sector digitization programs create baseline demand pools through transposed eIDAS regulations on citizen service delivery. The Polish Financial Supervision Authority aligns fintech licensing with EU AI Act algorithmic transparency requirements. Warsaw's emerging legal technology cluster shows accelerating workflow automation adoption among mid-market law practices.
Europe Digital Transaction Management (DTM) Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with trust service certification capabilities separating premium-tier providers from scale-driven SaaS vendors. The vendor base clusters around three strategic positions: ETSI-qualified trust service operators, cloud-native workflow orchestration platforms, and regulatory-specific template specialists. Consolidation pressure intensifies as eIDAS 2.0 wallet infrastructure elevates technical qualification barriers. Dominant competitive moves include strategic partnerships with national identity providers and geographic expansion through qualified trust service accreditation.
Within the trust service certification tier, DocuSign Inc. and Wolters Kluwer N.V. occupy positions shaped by enterprise renewal dynamics and regulatory template specialization respectively. Adobe Inc. sits within the creative-software-integrated workflow segment, leveraging document format standardization. These three exemplify how distinct capability foundations—trust frameworks, compliance content libraries, and design-software ecosystems—create non-overlapping competitive territory in European procurement evaluations.
| Leading Market Players |
|---|
| DocuSign Inc. |
| Adobe Inc. |
| Wolters Kluwer N.V. |
| Entrust Corp. |
| Namirial SpA |
| Nintex Group Pty Ltd |
| OneSpan Inc. |
| Kofax Inc. |
| Ascertia |
| Others |
Supply & Pricing Matrix
ETSI certification regimes for qualified trust services gate both vendor qualification and price differentiation simultaneously, compressing margins for uncertified entrants while elevating premium tiers for eIDAS-compliant operators serving German banking consortia and French insurance underwriters.
Pricing Analysis
German trust service operators command 30-40% premiums over Spanish and Italian counterparts for equivalent qualified electronic signature capabilities. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and API integration depth. Pricing pressure stems from eIDAS 2.0 wallet infrastructure commoditizing basic identity verification layers. Mid-market legal practices in Poland and Czechia exhibit highest price sensitivity, while Dutch pension funds prioritize EU-sovereign data residency over cost.
Supply Chain Analysis
Just-in-time deployment dominates cloud-native DTM provisioning, though strategic stockpiling of qualified certificate authority credentials buffers against ETSI audit backlogs. Supply concentrates in Germany, France, and the Netherlands for ETSI-certified trust services, with Ireland and Luxembourg emerging for GDPR-compliant data hosting. Raw material dependencies include HSM hardware modules, quantum-resistant cryptographic libraries, and API middleware stacks. Single-source vulnerability runs through German automotive supplier procurement channels. Distribution runs through direct enterprise sales teams and hyperscaler marketplace integrations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in Nordic SME legal automation and eIDAS 2.0 wallet interoperability layers, as regulatory deadline pressure creates procurement urgency that favors specialized entrants over consolidated platforms.
For Market Incumbents: Fortify trust service certification moats through accelerated EUCC cybersecurity auditing capacity before qualified auditor scarcity worsens. Deepen API ecosystem partnerships with national identity wallet providers to preempt disintermediation by eIDAS 2.0 infrastructure. Vertical integration into AI-powered contract analytics offsets margin compression in signature commoditization. For New Entrants and Emerging Players: Anchor in Swedish and Danish mid-market law firms where DTM penetration sits below 15% and incumbent presence remains thin. Exploit eIDAS 2.0 standardized API surfaces to bypass proprietary identity stack development costs. Lead with matter-management integration rather than standalone signature workflows to differentiate from horizontal platforms. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native workflow automation as containerization reduces infrastructure overhead, improving SaaS unit economics. Long-term viability favors platforms with embedded regulatory compliance content libraries over pure workflow orchestration tools. Watch for eIDAS 2.0 transposition timeline acceleration in Italy and Poland as demand inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Strategic Partnership | Alliances with national identity wallet providers bypass proprietary stack development for eIDAS 2.0 compliance. |
| Acquisition of Specialist Firm | Purchasing qualified trust service operators secures ETSI certification capacity scarce in German and French markets. |
| Product Launch | AI-powered contract analytics modules open clause-extraction revenue streams adjacent to signature workflows. |
| Platform Integration | Deep ERP and core banking connectivity captures straight-through processing demand from Dutch insurers. |
| Geographic Expansion | ETSI accreditation in Poland and Italy accesses public-sector procurement frameworks mandating qualified signatures. |
Research Methodology
Desk research of EU regulatory filings, ETSI technical specifications, and national eIDAS transposition documents preceded structured interviews with chief information security officers, trust service procurement leads, legal technology directors, and EU policy officers. Primary fieldwork validated secondary findings on vendor qualification barriers and procurement timeline compression. Bottom-up segment sizing triangulated against top-down regulatory mandate tracking.
Variance decomposition across deployment models, end-user industries, and member-state regulatory maturity shaped the analytical framework over the projection horizon. CAGRs derived from segment-level adoption curves weighted by eIDAS 2.0 deadline proximity and AI Act compliance urgency. Forecast inputs incorporated qualified auditor supply constraints and cloud infrastructure capex disclosures from hyperscaler partners.
Material uncertainties — eIDAS 2.0 transposition delays, EU AI Act enforcement variance, and qualified cybersecurity auditor supply bottlenecks — sit outside the modeled envelope. Forecasts reflect assumptions on regulatory timeline adherence and trust service market concentration stability. Revision becomes warranted when member-state wallet infrastructure deployment crosses acceleration or deceleration thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Indonesia Prepaid Cards Market
Payments
NFC Payments Market
Payments
Global Virtual Payment (POS) Terminals Market
Payments
Bus Card Reader Market
Payments
Social Media Payment Solution Market
Payments
Biometric Payment Cards Market
Payments
Europe Clearing Houses and Settlements Market
Payments
Enterprise Payment Software Market
Payments
North America Payment Gateway Market
Payments
South Korea Real Time Payments Market
Payments
LAMEA Payment Gateway Market
Payments
Global Utility Billing Software Market
Payments
Latin America Mobile Payment Market
Payments
Asia-Pacific Payment Gateway Market
Payments
Egypt Mobile Payments Market
Payments
Brazil Real Time Payments Market