
 Payment Instruments Market | 2026-2036
Payment Instruments Market Size, Share, and Industry Trends Forecast 2026-2036
Payment Instruments Market Intelligence
Retail merchant acceptance is shifting toward contactless and mobile-first checkout experiences. Fiserv leverages its integrated merchant services platform to sustain dominance in North American in-store payment processing. Adyen competes through unified commerce technology that spans online, mobile, and point-of-sale channels across European and Asian markets.
Payment instruments encompass physical and digital mechanisms enabling value transfer between transacting parties, incorporating EMV chip standards, tokenization protocols, and real-time gross settlement architectures to ensure transactional integrity. Their primary commercial purpose centers on reducing friction in consumer and business fund flows while mitigating counterparty risk. E-wallets and contactless instruments capture accelerating transaction volume as NFC terminal penetration deepens across merchant categories. Blockchain-based settlement remains nascent in consumer payments but attracts institutional pilot investment for cross-border remittance corridors.
The European Banking Authority enforces PSD2 strong customer authentication mandates that reshape issuer authentication technology investments. India's Reserve Bank and Brazil's central bank each operate real-time payment rails that dictate infrastructure compliance for domestic market participation. India's NPCI certifies UPI-enabled application providers, creating tiered access pathways for fintech entrants. Stakeholders must monitor divergence between open banking API standardization in Europe and proprietary super-app wallet ecosystems in Asian markets.
Market Dynamics
Real-time payment infrastructure mandates from central banks are compressing settlement windows and forcing incumbent processors to rebuild core architectures around instant gross settlement protocols rather than batch-based legacy systems.
Growth Catalysts
- UPI Ecosystem Expansion:India's NPCI-certified application layer attracts fintech entrants through tiered API access pathways, accelerating wallet penetration into tier-two and tier-three urban centers.
- PSD2 Strong Authentication:The European Banking Authority's SCA mandates drive issuer investment in biometric and tokenized authentication stacks, creating compliance-driven hardware refresh cycles.
- Pix Network Effects:Brazil's central bank-operated real-time rail achieves merchant adoption through zero-cost settlement guarantees, displacing card-based debit volumes at point-of-sale terminals.
Market Restraints
- Interchange Compression:Regulatory caps on merchant discount rates in India and Brazil squeeze acquirer margins and constrain investment in rural terminal deployment.
- Core Banking Fragmentation:Legacy mainframe architectures at tier-one banks in Europe and North America resist API-native integration, delaying open banking compliance timelines.
- Cross-Border Settlement Costs:Correspondent banking networks maintain high friction for remittance corridors, limiting wallet interoperability across national real-time rails.
Strategic Opportunities
- Embedded Finance Convergence:Non-financial platforms in Southeast Asia integrate checkout, lending, and insurance through single-app architectures, capturing transaction data for underwriting.
- Offline QR Standards:India's interoperable Bharat QR specification enables feature-phone transactions, opening rural merchant acceptance without smartphone dependency.
- CBDC Infrastructure Pilots:Central bank digital currency testbeds in China and Nigeria create vendor opportunities for wallet providers and cryptography specialists.
Industry Challenges
- Fraud Detection Talent Scarcity:Real-time settlement eliminates chargeback windows, intensifying demand for machine-learning risk engineers capable of sub-100-millisecond decisioning.
- Certification Backlogs:EMVCo tokenization compliance queues stretch 8-14 months for new entrants, delaying product launches in competitive European markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Payment Instruments Market |
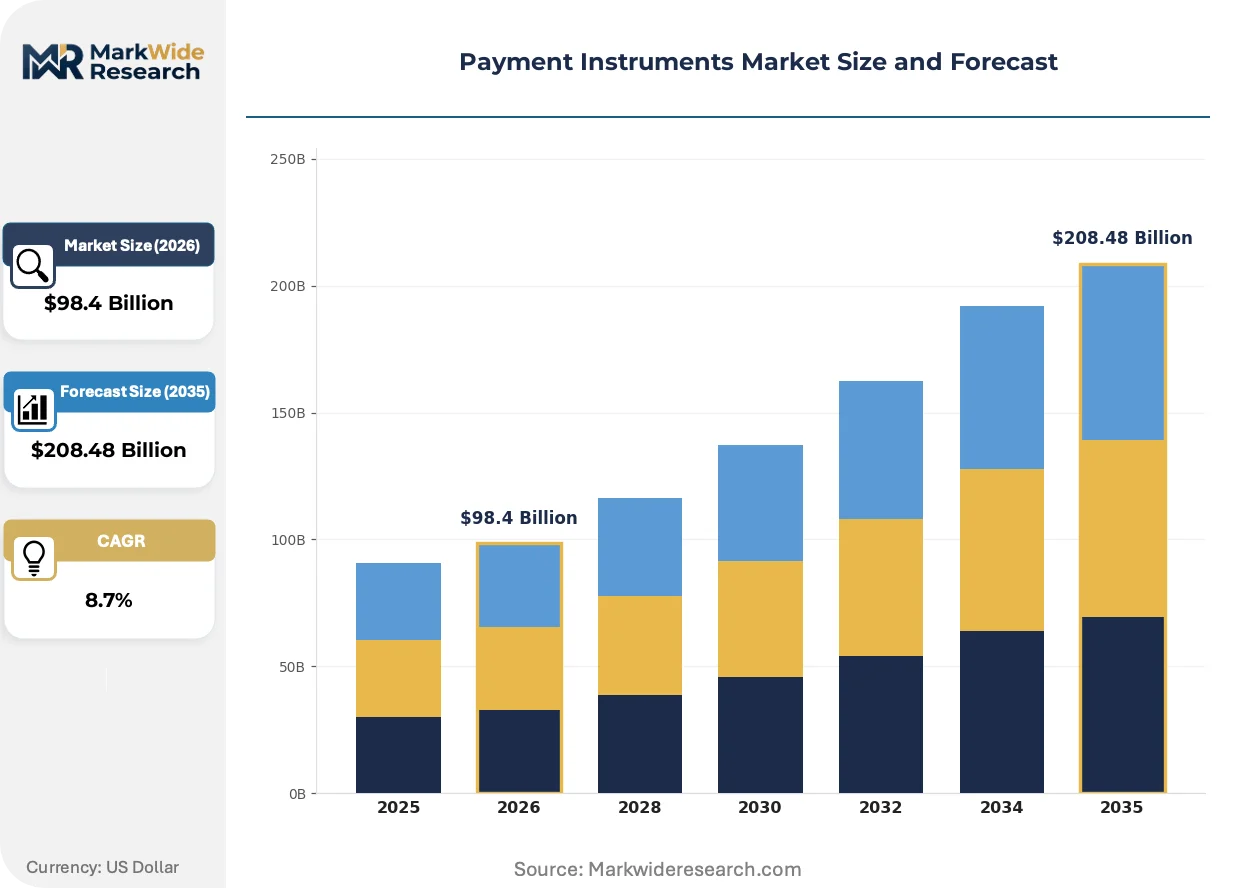
| Market Size in 2026 | $98.4 Billion |
| Market Size in 2035 | $208.48 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Instrument Type: Credit Cards, Debit Cards, E-Wallets, Bank Transfers Technology: Contactless, NFC, QR Code, Blockchain End User: Retailers, E-Commerce, Service Providers, Merchants Transaction Method: Online Payments, In-Store Payments, Mobile Payments, Recurring Payments |
| Companies Covered | Fiserv, FIS, Global Payments, PayPal, Adyen, Stripe, Square, Worldline, Chase Payment Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Payment Instruments Market Strategic Shifts & Innovations
Distributed ledger experimentation is migrating from cryptocurrency speculation to institutional settlement pilots, while authentication modalities shift toward passive behavioral biometrics and regulatory frameworks harden around data localization.
Blockchain-based settlement infrastructure is decentralizing correspondent banking relationships for cross-border remittance corridors. Money transfer operators in Southeast Asia and the Gulf Cooperation Council are piloting stablecoin bridges to bypass SWIFT latency. This architecture compresses settlement from T+2 to near-instant, though regulatory clarity on digital asset custody remains fragmented across jurisdictions.
Europe's Digital Operational Resilience Act imposes strict ICT risk management mandates on payment service providers, requiring incident reporting within 24 hours and annual penetration testing. The regulation forces cloud-dependent fintechs to rearchitect for multi-provider redundancy. Small and mid-sized issuers in Germany and France are consolidating to spread compliance costs across larger balance sheets.
Merchant acquisition is consolidating around software-integrated payment platforms that embed checkout, inventory, and lending into unified dashboards. Restaurant and retail chains in Brazil and Mexico are abandoning standalone terminal contracts for full-stack commerce suites. This preference shift favors technology-forward acquirers with API-native architectures over hardware-centric legacy processors.
Payment Instruments Market Segmentation
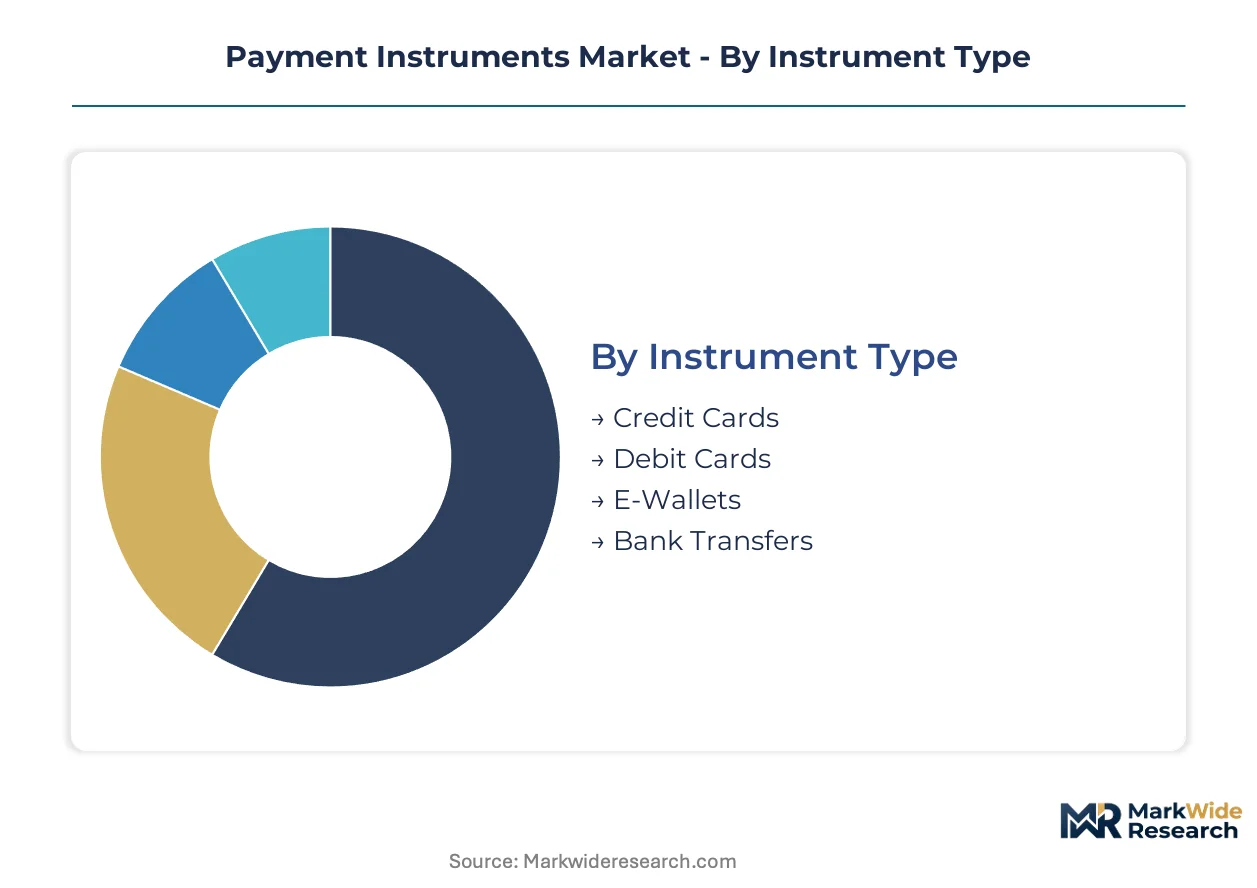
Payment instruments fragment across four intersecting dimensions that determine infrastructure requirements, regulatory exposure, and margin architecture. Technology choices dictate capital deployment intensity, while end-user concentration shapes geographic expansion priorities.
Instrument Type:
Capital intensity varies sharply across instrument categories, with card networks requiring massive issuer processing infrastructure and e-wallets demanding lighter application-layer investment.
- Credit Cards:Revolving credit instruments with embedded interchange fee structures and sophisticated risk-scoring engines. Demand concentrates in Brazil's merchant acquiring market, where Pix displacement is forcing acquirers to defend merchant relationships through subsidized terminal deployment.
- E-Wallets:Stored-value applications operating through tokenized credential vaults and real-time balance settlement. India's tier-two urban centers drive volume expansion as NPCI-certified providers extend UPI interoperability into semi-urban merchant networks.
- Debit Cards:Direct account-linked instruments with lower fraud liability profiles and constrained interchange ceilings. Brazil's central bank mandates are compressing merchant discount rates.
- Bank Transfers:Account-to-account rails leveraging real-time gross settlement protocols with minimal intermediary margins. India's UPI ecosystem and Brazil's Pix network dominate adoption curves.
Credit cards absorb the bulk of installed processing capacity; e-wallets are expanding most quickly.
Technology:
Technology segmentation maps to terminal hardware refresh cycles and merchant upgrade willingness, with contactless infrastructure now baseline in most developed markets.
- Contactless:Proximity-enabled transactions using EMV chip standards with sub-500-millisecond authentication windows. European PSD2 mandates are driving biometric-secured contactless adoption at German and French merchant locations.
- QR Code:Visual scan-based initiation requiring smartphone penetration or printed static codes for feature-phone compatibility. India's Bharat QR specification enables offline merchant acceptance in rural Maharashtra and Uttar Pradesh without smartphone dependency.
- NFC:Near-field communication protocols enabling device-to-terminal data exchange with hardware-encrypted token transmission. Terminal penetration deepens across Southeast Asian retail chains.
- Blockchain:Distributed ledger settlement architectures piloting for cross-border remittance corridors with stablecoin bridges bypassing correspondent banking latency. Gulf Cooperation Council money transfer operators are testing near-instant settlement against T+2 SWIFT benchmarks.
Contactless technology dominates current terminal installed base; QR code adoption is climbing the fastest in emerging market penetration.
End User:
End-user concentration determines pricing power and platform stickiness, with large retail chains commanding volume-based interchange discounts.
- Retailers:Brick-and-mortar merchants with high-frequency, low-ticket transaction profiles requiring integrated inventory-payment reconciliation. Brazil's restaurant and retail chains are consolidating around software-integrated payment platforms.
- E-Commerce:Digital-native merchants with card-not-present fraud exposure and demand for one-click checkout optimization. India's online marketplaces are embedding UPI intent flows to reduce payment abandonment.
- Service Providers:Subscription and utility billing operations with recurring payment authorization requirements and churn-sensitive credential vaulting. European SaaS platforms are adopting SCA-compliant frictionless recurring authentication.
- Merchants:Small and mid-sized businesses with fragmented terminal estates and limited technical integration capabilities. India's tier-three urban centers represent underpenetrated terminal deployment opportunities.
Retailers command the largest share of transaction volume; e-commerce merchants are gaining share fastest.
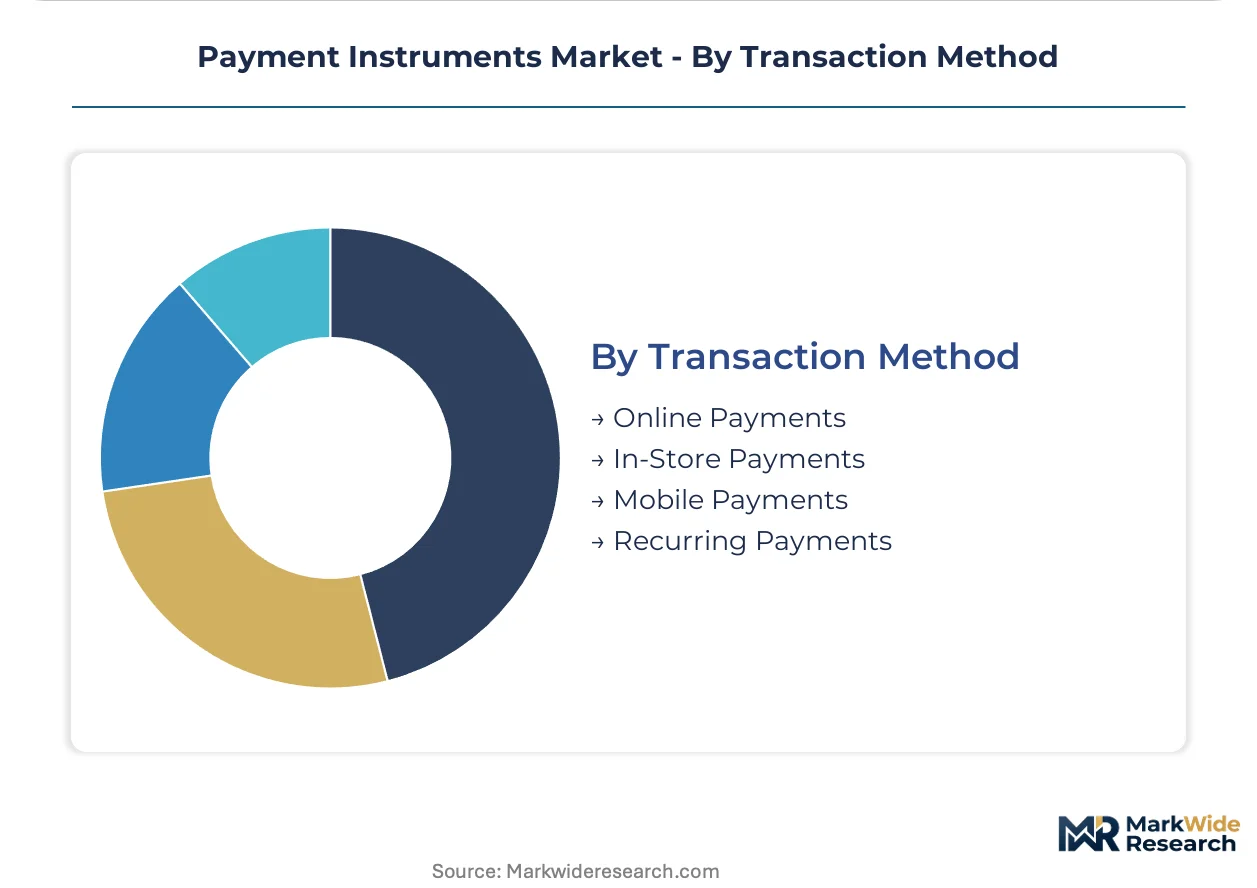
Transaction Method:
Transaction method segmentation aligns with consumer behavior shifts and merchant infrastructure investment priorities, with mobile payment architectures displacing legacy online gateways.
- Mobile Payments:Smartphone-initiated transactions leveraging device-native biometric authentication and tokenized credential storage. India's UPI ecosystem processes the majority of mobile payment volume through NPCI-certified application providers.
- Online Payments:Browser or app-based checkout flows with 3D Secure authentication and redirect-based issuer verification. European merchants are migrating to frictionless checkout flows compliant with PSD2 SCA exemptions.
- In-Store Payments:Physical terminal-present transactions with EMV chip or contactless tap authentication. Brazil's Pix network achieves merchant adoption through zero-cost settlement guarantees at point-of-sale terminals.
- Recurring Payments:Pre-authorized credential-on-file transactions with merchant-initiated billing and variable amount protocols. Subscription economy expansion drives credential vaulting demand.
In-store payments retain the bulk of transaction value; mobile payments are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Special Economic Zones for fintech attract payment infrastructure investment through tax holidays and duty exemptions on hardware imports. These zones concentrate terminal manufacturing and software development clusters that serve domestic and export markets.
India
UPI-enabled wallet penetration and Bharat QR merchant acceptance drive volume growth in tier-two urban centers. The Reserve Bank of India mandates real-time gross settlement compliance for all domestic payment application providers. Mumbai's BKC fintech cluster hosts NPCI-certified technology vendors building interoperable authentication stacks.
Brazil
Pix network merchant adoption and zero-cost settlement guarantees displace card-based debit volumes at retail terminals. The central bank's regulatory framework mandates instant payment rail participation for all deposit-taking institutions. São Paulo's financial district concentrates acquirer technology development and merchant service platform engineering.
Germany
PSD2 strong customer authentication compliance and biometric-secured contactless terminal deployment reshape issuer technology budgets. The Federal Financial Supervisory Authority enforces strict ICT risk management and incident reporting protocols. Frankfurt's banking cluster drives authentication hardware procurement and tokenization infrastructure investment.
United States
Integrated merchant services platforms and software-embedded checkout solutions consolidate acquiring relationships among mid-market retailers. The Federal Reserve's FedNow instant payment infrastructure creates compliance requirements for core banking system upgrades. Atlanta's transaction processing corridor hosts legacy processor data centers and cloud-native fintech engineering operations.
China
Central bank digital currency pilots and super-app wallet ecosystems test programmable payment infrastructure at municipal scale. The People's Bank of China mandates data localization and cryptographic standards for domestic payment providers. Shenzhen's technology corridor concentrates hardware security module manufacturing and blockchain settlement engineering talent.
Payment Instruments Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with integrated platform providers commanding premium positioning in unified commerce while hardware-centric processors defend legacy terminal estates. The vendor base organizes around three archetypes: full-stack technology platforms, specialized merchant acquirers, and infrastructure-as-a-service providers. Consolidation pressure intensifies as software-integrated payment suites displace standalone terminal contracts. Dominant competitive moves include strategic partnerships between fintech application layers and bank-owned rails, plus geographic expansion through local certification acquisition.
Among North American integrated platform providers, Fiserv and Global Payments exemplify the merchant services consolidation archetype, occupying positions that span in-store processing, digital issuance, and core banking technology. European unified commerce specialists include Adyen and Worldline, representing the cross-channel technology platform model with API-native architectures. These named entities anchor competitive dynamics without constraining the full competitive set.
| Leading Market Players |
|---|
| Fiserv |
| FIS |
| Global Payments |
| PayPal |
| Adyen |
| Stripe |
| Square |
| Worldline |
| Chase Payment Solutions |
| Others |
Cost & Logistics Intelligence
Machine-learning risk engineering talent concentration in Bengaluru and São Paulo creates labor-cost differentials that widen pricing-tier spreads between premium authentication stacks and economy-grade terminal deployments.
Pricing Analysis
Lead-time-driven pricing angles dominate procurement negotiations, with premium tiers commanding surcharge multiples for sub-100-millisecond fraud decisioning engines versus standard 8-14 month EMVCo certification queues. Three-tier pricing structure across premium, standard, and economy levels separates biometric-secured contactless terminals from basic NFC readers and feature-phone QR code systems. Cost compression in economy tiers intensifies because India's interchange caps and Brazil's zero-cost Pix mandates squeeze acquirer margins. Small and mid-sized merchants in tier-three urban centers exhibit highest price sensitivity, while large retail chains in São Paulo and Mumbai command volume-based interchange discounts.
Supply Chain Analysis
Dual-sourcing requirements from European and North American acquirers mandate multi-supplier qualification for EMV chip modules and hardware security modules, fragmenting procurement across Taiwan, China, and South Korea manufacturing clusters. Raw material dependencies center on semiconductor-grade silicon wafers, cryptographic processor cores, and NFC antenna substrates. Single-source vulnerability concentrates in Taiwan's foundry capacity for advanced security chips. Distribution runs through certified terminal logistics networks with RBI and Banco Central do Brasil compliance checkpoints before domestic deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over real-time payment rail access and authentication stack ownership determines margin capture.
For Market Incumbents: Lock in merchant relationships through subsidized terminal deployment and exclusive Pix settlement guarantees before fintech entrants achieve NPCI certification. Defend against API-native commerce suites by acquiring software-embedded checkout platforms in Brazil and Mexico. Prioritize backward integration into hardware security module manufacturing to reduce dependency on Taiwan foundry capacity. For New Entrants and Emerging Players: Passive behavioral biometrics authentication offers a technology-first wedge into European PSD2 compliance budgets as tier-one banks delay legacy mainframe upgrades. Target India's tier-two urban centers with Bharat QR-enabled feature-phone solutions where smartphone penetration lags. Pursue NPCI certification pathways for UPI interoperability as the primary go-to-market angle. For Investors and Strategic Acquirers: Re-rating potential sits with cloud-native authentication stack providers given Europe's Digital Operational Resilience Act enforcement timelines. Long-term viability favors vendors with multi-rail certification across UPI, Pix, and FedNow infrastructures. Monitor EMVCo tokenization compliance queue lengths as the inflection indicator for new entrant launch velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unified commerce architectures spanning online, mobile, and point-of-sale channels capture merchant switching costs across European markets. |
| Geographic Expansion | Local certification acquisition in India's Special Economic Zones enables duty-exempt terminal manufacturing for domestic and export demand. |
| Strategic Partnership | Fintech application layer alliances with bank-owned real-time rails secure tiered API access pathways in competitive Asian markets. |
| Acquisition of Specialist Firm | Machine-learning risk engineering teams address sub-100-millisecond fraud decisioning requirements as chargeback windows disappear. |
| Product Launch | Offline QR standards for feature-phone compatibility open rural merchant acceptance without smartphone dependency in Indian states. |
Research Approach
Independent corroboration across payment network executives, central bank regulatory leads, merchant acquiring technology officers, and EMVCo certification managers underwrites the qualitative findings. Primary fieldwork combined structured interviews with secondary validation through RBI circulars, Banco Central do Brasil regulatory filings, European Banking Authority PSD2 implementation reports, and SEC disclosures from listed payment processors. Bottom-up terminal deployment estimates and top-down transaction volume benchmarks triangulate market sizing.
Rate-of-change decomposition across instrument type, technology modality, end-user concentration, and transaction method segments drives the analytical framework over the projection horizon. CAGRs derive from regression analysis against real-time payment rail adoption curves and authentication hardware refresh cycles. Modeled inputs include NPCI-certified application provider counts, Pix merchant terminal penetration rates, and EMVCo tokenization compliance queue durations.
Several conditions sit outside the modeled scope, including unannounced central bank digital currency launch timelines, geopolitical disruption to semiconductor supply chains, and abrupt interchange regulation shifts in major economies. Forecasts reflect documented assumptions about certification backlog resolution and cloud infrastructure redundancy compliance. A model refresh is warranted upon material change in real-time payment rail participation mandates or EMVCo specification updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
3D Secure Payment Authentication Market
Payments
Europe Accounts Payable Automation Market
Payments
Contactless Payment Ring Market
Payments
Japan Retail Cash Management Market
Payments
POS Terminals Market
Payments
United Arab Emirates Mobile Payments Market
Payments
LAMEA Crypto Payment Gateway Market
Payments
Point-Of-Sale [POS] Terminal Market
Payments
Philippines Remittance Market
Payments
Argentina Payments Market
Payments
In-Vehicle Payment System Market
Payments
Japan Payment Gateway Market
Payments
Bulgaria POS Terminals Market
Payments
Japan Prepaid Cards Market
Payments
Argentina Mobile Wallet Market
Payments
Electronic Payment Processing Software Market