
 Saudi Arabia POS Terminal Market | 2026-2036
Saudi Arabia POS Terminal Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia POS Terminal Market Analytics
Buyer concentration in Saudi retail is decoupling from traditional hypermarket chains toward fragmented quick-service restaurant and specialty retail networks. PAX Technology Limited leverages manufacturing scale to supply cost-optimized terminals for mid-tier hospitality deployments. Geidea Solutions anchors domestic demand through payment-acquiring integration and local certification pathways. Toshiba Global Commerce Solutions competes on enterprise-grade fixed POS systems for grocery and department store rollouts.
A point-of-sale terminal is an electronic device combining a processor, secure card reader, touchscreen interface, and connectivity module to authenticate and record payment transactions at commercial locations. The hardware typically integrates PCI-DSS compliant encryption engines and thermal receipt printers to process EMV chip, NFC contactless, or QR code payments in under three seconds. Mobile POS and tablet-based systems are capturing the fastest expansion as Saudi food trucks, pop-up retail, and delivery-first restaurants prioritize low-footprint, cloud-synced hardware over fixed countertop units. Self-service kiosk deployments are maturing in cinema and quick-service environments where labor costs and throughput targets justify capital-intensive installations.
SAMA, the Saudi Central Bank, enforces terminal certification and fintech licensing rules that shape hardware procurement timelines and security architecture requirements. PCI Security Standards Council protocols and the country's national cybersecurity authority guidelines mandate encryption standards that filter non-compliant vendors from public tenders. Stakeholders must monitor how SAMA's open-banking directives and real-time payment infrastructure investments alter terminal software stack requirements and vendor qualification criteria.
Market Dynamics
SAMA's real-time payment infrastructure and open-banking directives are compressing hardware procurement cycles across Saudi retail networks. Terminal vendors must now synchronize firmware updates with central bank API requirements, transforming what was a 5-year replacement cycle into continuous compliance-driven refresh schedules.
Growth Catalysts
- Vision 2030 tourism targets:Hospitality and quick-service restaurant expansion across Riyadh and Jeddah is generating concentrated terminal demand from new venue construction.
- SAMA electronic payment mandates:Regulatory requirements for cashless transaction acceptance are forcing legacy cash register replacement in mid-tier retail.
- Cloud-connected terminal architectures:Remote management capabilities reduce on-site technical support costs for fragmented franchise networks.
Market Restraints
- Semiconductor supply concentration:Payment processor chip fabrication depends on a concentrated East Asian supplier base, creating lead time volatility.
- PCI-DSS certification complexity:Multi-stage security validation timelines extend vendor qualification periods by 8-14 months.
- Mobile wallet substitution:Smartphone-based QR payment acceptance reduces hardware attach rates for basic transaction terminals.
Strategic Opportunities
- Neom and Red Sea Project zones:Greenfield smart city construction permits embedded POS infrastructure deployment without legacy system integration burden.
- SoftPOS technology convergence:NFC-enabled smartphones and tablets are displacing dedicated hardware in delivery-first restaurant operations.
- SAMA fintech licensing framework:New payment service provider categories create captive terminal demand from licensed acquiring startups.
Industry Challenges
- Cybersecurity talent scarcity:Terminal firmware development requires specialized PCI-DSS compliance engineering expertise that remains concentrated among incumbent vendors.
- Legacy ERP integration complexity:Hospitality management software from established providers demands custom API development for cloud-terminal synchronization.
- Multi-certification timeline compression:SAMA, national cybersecurity authority, and PCI Security Standards Council validation sequences must now execute in parallel rather than sequence.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia POS Terminal Market |
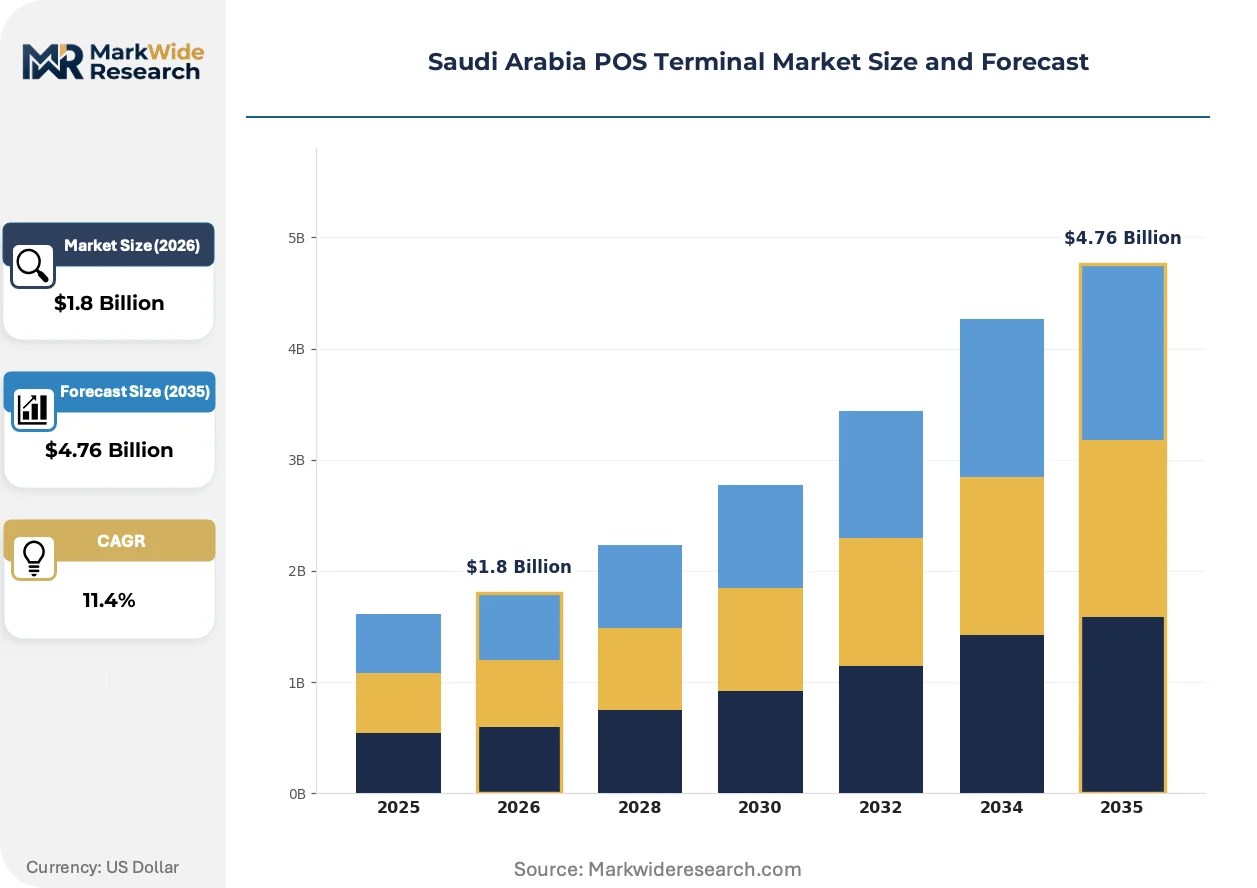
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed POS, Mobile POS, Self-Service Kiosks, Tablet POS Technology: EMV, NFC, Magnetic Stripe, QR Code End User: Retail, Hospitality, Healthcare, Entertainment Deployment: On-Premise, Cloud-Based, Hybrid, Others |
| Companies Covered | Urovo Technology Corporation Limited, Toshiba Global Commerce Solutions, VeriFone Inc., Micros POS Systems (Oracle Corporation), Geidea Solutions, Ingenico (Worldline), Spire Systems Inc., DATECS Ltd., PAX Technology Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia POS Terminal Market Evolving Landscape
Terminal hardware architecture is fragmenting across three simultaneous vectors: payment modality diversification, software-defined feature expansion, and deployment model flexibility. Saudi buyer procurement patterns increasingly prioritize subscription-based terminal-as-a-service arrangements over capital purchase.
Android-based open-platform terminals are converging with third-party application marketplaces, enabling hospitality operators to deploy inventory management, loyalty programs, and kitchen display systems on unified hardware. Mid-tier restaurant chains in Jeddah are adopting these systems fastest, compressing vendor margins on standalone software licenses while expanding addressable hardware volume.
SAMA's open-banking directive and real-time payment infrastructure investment are mandating API-native terminal software stacks. The central bank's technical specifications require local transaction routing capabilities that filter non-compliant hardware from public sector tenders. Enterprise retail deployments in Riyadh are accelerating procurement of domestically certified terminals to preempt compliance deadlines.
Buyer preference is rotating toward usage-based pricing models that bundle hardware, software, and payment processing fees. Quick-service restaurant franchises are displacing outright purchase arrangements with per-transaction fee structures that align terminal costs with revenue. This shift is most visible in Saudi Arabia's western province, where delivery-aggregator partnerships already conditioned operators to variable cost structures.
Saudi Arabia POS Terminal Market Segmentation
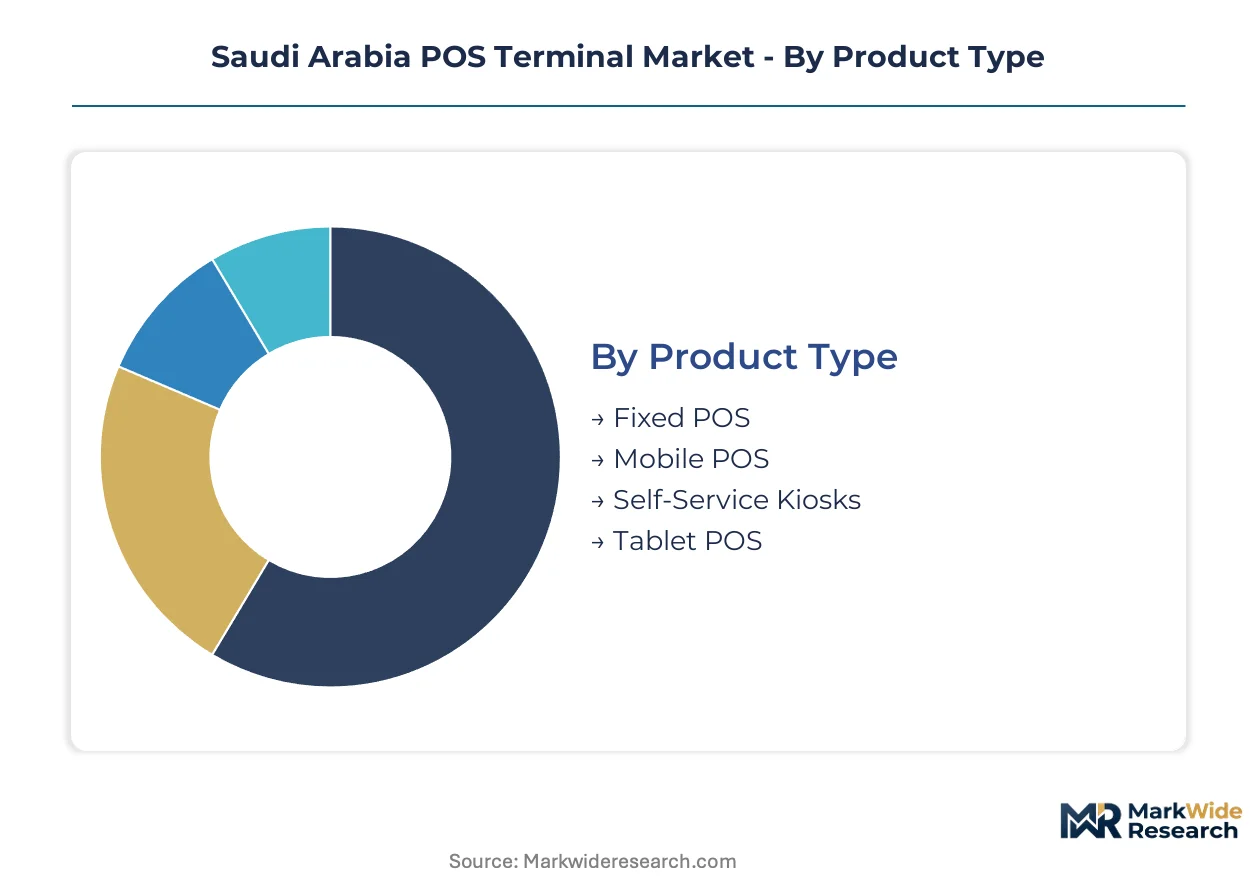
Segmentation in the Saudi Arabia POS Terminal Market reveals how capital allocation, regulatory compliance, and operational scale dictate hardware procurement patterns across retail and hospitality networks. Understanding these divisions clarifies where SAMA mandates concentrate compliance burdens and where cloud architectures reduce total cost of ownership.
Product Type:
Capital intensity varies sharply across hardware form factors, with self-service kiosks demanding the highest upfront investment while mobile POS minimizes fixed asset exposure.
- Fixed POS:Countertop units integrate thermal printers, cash drawers, and PCI-DSS encryption modules in hardened enclosures. Riyadh hypermarkets and Jeddah department stores deploy these for high-throughput checkout lanes where transaction speed and receipt printing remain non-negotiable.
- Mobile POS:Handheld terminals with integrated card readers and 4G/WiFi connectivity enable tableside payment in Riyadh's full-service restaurants and pop-up retail in Jeddah's waterfront districts. Cloud synchronization eliminates dedicated server infrastructure, compressing deployment costs for fragmented franchise operators.
- Self-Service Kiosks:Freestanding units with touchscreen interfaces, integrated payment terminals, and kitchen display system integration command substantial capital outlay for cinema chains and quick-service restaurant rollouts.
- Tablet POS:Consumer-grade tablets paired with encrypted card readers and proprietary mounting systems deliver lowest hardware cost per lane, attracting Saudi food trucks and delivery-first kitchens prioritizing rapid redeployment.
Fixed POS absorbs the bulk of installed capacity across Saudi retail; mobile POS is expanding most quickly as hospitality operators prioritize flexibility over countertop permanence.
Technology:
Payment modality selection determines encryption hardware requirements, certification complexity, and terminal refresh cycles mandated by SAMA and PCI Security Standards Council protocols.
- EMV:Chip card authentication with dynamic data verification requires dedicated secure element processors and contact card slots. SAMA mandates have accelerated EMV terminal penetration across mid-tier Saudi retail previously dependent on magnetic stripe infrastructure.
- NFC:Contactless payment acceptance using 13.56MHz radio frequency interfaces enables tap-to-pay transactions under three seconds. Riyadh's quick-service restaurant chains and Jeddah's cinema complexes deploy NFC-enabled terminals to capture Apple Pay and Mada card volume.
- Magnetic Stripe:Legacy swipe authentication persists in budget hospitality deployments and temporary event infrastructure where terminal replacement cycles lag regulatory mandates.
- QR Code:Camera-based payment acceptance using smartphone-generated codes reduces hardware requirements to software-enabled imaging, displacing dedicated terminals in Saudi delivery-aggregator partnerships and peer-to-peer transfers.
EMV dominates current installed base; NFC is gaining share fastest as contactless transaction limits rise and consumer preference shifts from card insertion to tap.
End User:
Operational environment shapes terminal durability specifications, software integration requirements, and support service intensity across Saudi commercial sectors.
- Retail:Grocery, apparel, and electronics merchants require high-volume transaction processing with inventory management system integration. Riyadh's mall operators and Jeddah's souk modernizations drive fixed POS procurement with multi-lane synchronization.
- Hospitality:Full-service restaurants, quick-service chains, and hotels demand split-check functionality, tip adjustment workflows, and property management system connectivity. Vision 2030 tourism infrastructure expansion concentrates terminal demand in Makkah and Madinah hospitality clusters.
- Healthcare:Clinics and pharmacies require HIPAA-aligned transaction logging and insurance co-payment processing with specialized billing system interfaces.
- Entertainment:Cinema complexes, amusement venues, and event spaces prioritize high-speed ticketing integration with season pass management and concession bundling.
Hospitality captures the steepest expansion trajectory as tourism targets multiply venue construction; retail maintains the largest cumulative deployment base.
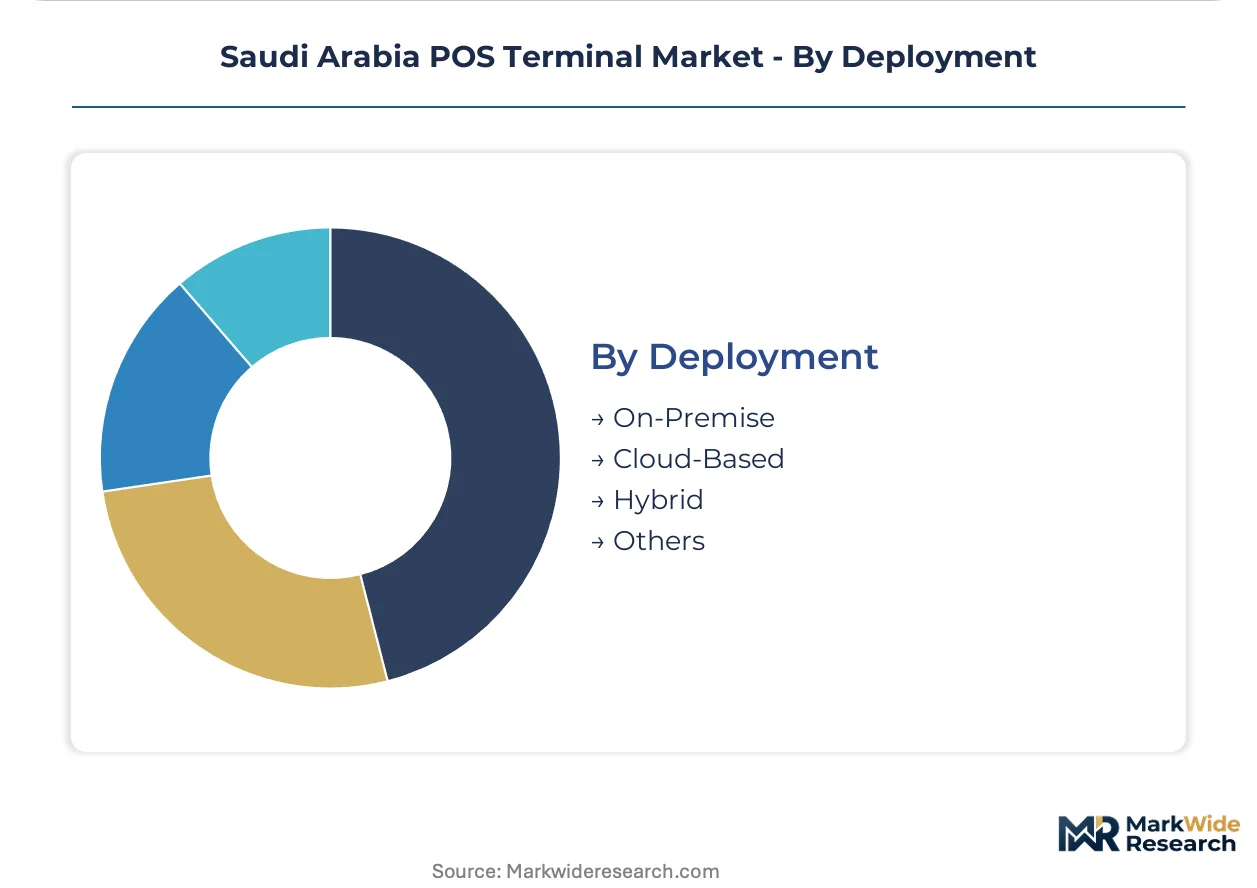
Deployment:
Architecture selection determines data sovereignty compliance, latency sensitivity, and ongoing operational expenditure structure for Saudi terminal operators.
- On-Premise:Local server installations with dedicated transaction processing hardware and private network segmentation. Large Saudi grocery chains retain on-premise deployments for sub-second authorization response times during peak traffic.
- Cloud-Based:Terminal-to-cloud API connectivity with centralized firmware management and real-time transaction routing. SAMA's open-banking directives favor cloud-native architectures for licensed fintech payment service providers.
- Hybrid:Edge transaction processing with cloud reconciliation and backup routing. Hospitality operators in Jeddah's western province deploy hybrid models to balance offline resilience with centralized analytics.
- Others:Emerging edge-computing and blockchain-anchored settlement architectures remain experimental in Saudi pilot programs.
On-premise retains dominant share in legacy retail; cloud-based deployment is climbing the fastest as SAMA API requirements and franchise scalability priorities converge.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Riyadh and Jeddah commercial corridors where retail modernization and hospitality expansion intersect with SAMA electronic payment mandates. Eastern Province industrial zones and emerging NEOM developments are redistributing terminal procurement patterns across new infrastructure corridors.
Riyadh
Riyadh's hypermarket chains and mall operators drive fixed POS terminal procurement for high-throughput checkout environments. SAMA's real-time payment infrastructure requirements are accelerating cloud-native terminal adoption across Saudi Central Bank-licensed fintech operators. King Abdullah Financial District anchors enterprise-grade hardware deployments for banking-integrated retail networks.
Jeddah
Jeddah's quick-service restaurant density and waterfront tourism infrastructure generate concentrated mobile POS demand for tableside and delivery-first operations. Western Province hospitality clusters prioritize Android-based open-platform terminals with third-party application integration. Red Sea Project proximity is conditioning procurement patterns toward subscription-based terminal-as-a-service arrangements.
Eastern Province
Eastern Province petrochemical and industrial city retail networks are replacing legacy cash registers under SAMA cashless transaction mandates. Dammam and Khobar commercial corridors exhibit hybrid deployment preferences balancing on-premise resilience with cloud reconciliation capabilities. Industrial workforce canteens and convenience retail are driving mid-tier terminal volume.
NEOM Northwest
NEOM's greenfield smart city construction permits embedded POS infrastructure without legacy system integration burden. SAMA fintech licensing framework is attracting payment service provider startups requiring domestically certified terminal hardware. Trojena and Sindalah development zones are piloting edge-computing terminal architectures for offline resilience.
Makkah and Madinah
Vision 2030 pilgrimage infrastructure expansion is multiplying hospitality venue construction and associated terminal demand. Religious tourism clusters require PCI-DSS compliant encryption engines for high-volume international card transaction processing. Haramain high-speed rail connectivity is integrating terminal networks across hospitality and retail nodes.
Saudi Arabia POS Terminal Market Competitive Landscape
East Asian producers anchor the manufacturing tier; European and North American specialists hold enterprise software integration positions. The vendor base stratifies across scale-driven hardware fabricators, payment-acquiring integrated domestic operators, and enterprise-grade fixed system providers. Three archetypes dominate: manufacturing-scale suppliers optimizing unit economics, domestic certifiers leveraging SAMA pathway knowledge, and enterprise integrators commanding grocery and department store rollouts. Competitive moves concentrate on strategic partnerships with payment processors and portfolio diversification into subscription-based service models.
Within the manufacturing-scale tier, PAX Technology Limited and Urovo Technology Corporation Limited exemplify cost-optimized production capabilities for mid-tier hospitality deployments. Geidea Solutions occupies a distinctive position as a domestic operator anchoring demand through payment-acquiring integration and local certification pathways. Toshiba Global Commerce Solutions represents the enterprise-grade fixed system archetype competing on hardened enclosures and thermal printer integration for high-throughput retail environments.
| Leading Market Players |
|---|
| Urovo Technology Corporation Limited |
| Toshiba Global Commerce Solutions |
| VeriFone Inc. |
| Micros POS Systems (Oracle Corporation) |
| Geidea Solutions |
| Ingenico (Worldline) |
| Spire Systems Inc. |
| DATECS Ltd. |
| PAX Technology Limited |
| Others |
Value Network & Pricing Analysis
SAMA's PCI-DSS certification mandates gate qualified supply access and premium-tier pricing power for terminal vendors serving Saudi public sector tenders. Compliance-validated hardware commands substantial markups over uncertified alternatives while filtering non-compliant manufacturers from procurement shortlists.
Pricing Analysis
Volume deployments of fixed POS terminals in Riyadh hypermarkets operate on thin margins, while mobile POS and kiosk systems for Jeddah hospitality capture wider spreads through software bundling. Three-tier pricing structure across premium, standard, and economy levels separates enterprise-grade encrypted terminals from mid-tier Android-based units and budget magnetic-stripe hardware. Pricing pressure stems from SoftPOS technology convergence, as NFC-enabled smartphones displace dedicated terminals in delivery-first restaurant operations. Quick-service restaurant franchises exhibit highest price sensitivity, prioritizing per-transaction fee structures over capital purchase; enterprise retail chains in King Abdullah Financial District demonstrate lowest sensitivity, accepting upfront hardware investment for sub-second authorization performance.
Supply Chain Analysis
Reverse-logistics flows for terminal refurbishment and secure component destruction are emerging as cost centers as SAMA mandates accelerate hardware refresh cycles. Secure element processor fabrication concentrates in Taiwan and South Korea, with final assembly anchored in China. Payment terminal production draws from concentrated East Asian semiconductor foundries, thermal printer mechanisms from Japanese precision manufacturers, and hardened enclosure fabrication from regional Gulf metalworking facilities. Single-source vulnerability in EMV chip supply creates lead time volatility for Saudi terminal distributors. Distribution runs through Riyadh-based payment service providers and Jeddah hospitality technology integrators rather than direct vendor-to-merchant relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
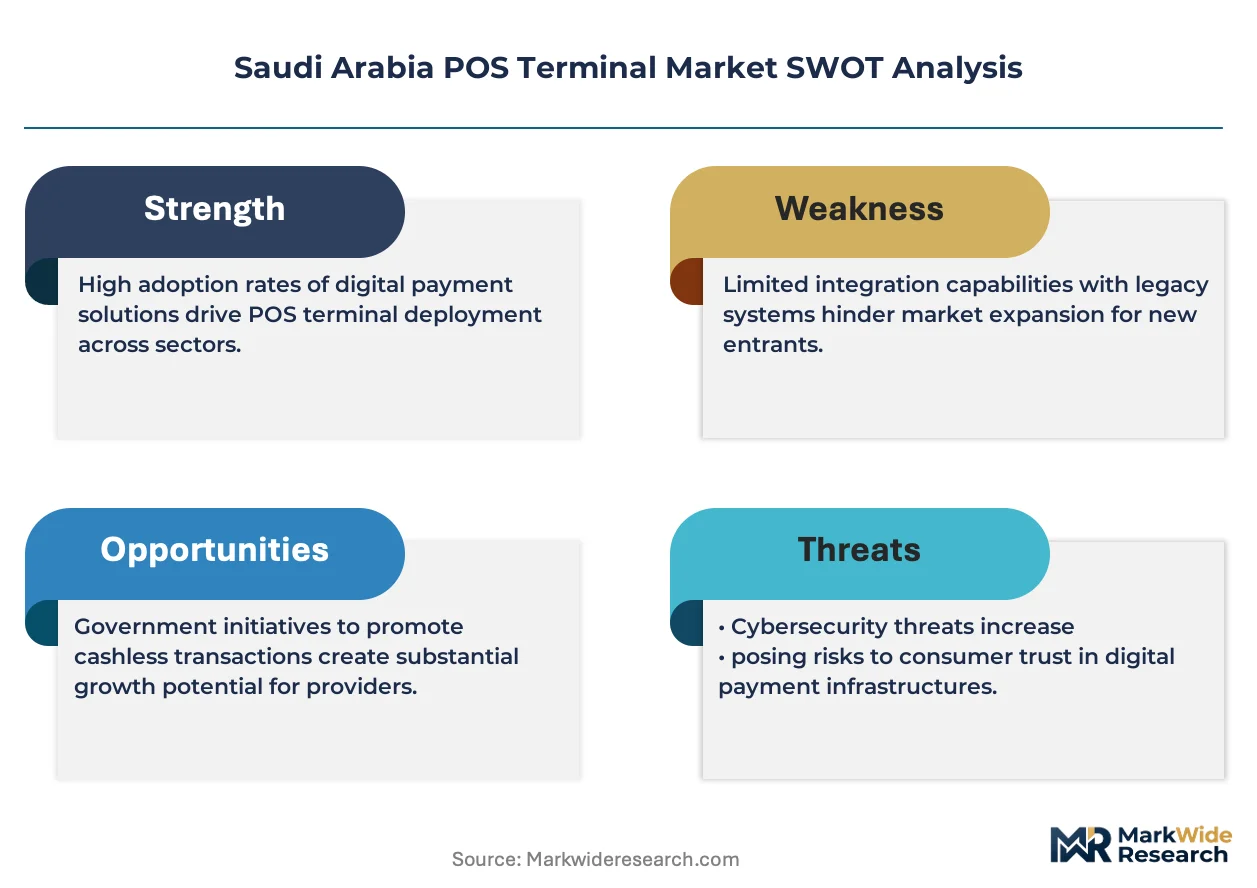
Cloud-native terminal architectures are displacing legacy on-premise systems across Saudi retail networks, compressing replacement cycles and reshaping vendor competitive positioning.
For Market Incumbents: To counter SoftPOS substitution threat, PAX Technology and Geidea Solutions should deepen backward integration into secure element sourcing and expand subscription-based terminal-as-a-service offerings. Certification investment in SAMA's parallel validation pathways for API-native software stacks represents the critical defensive lever against fintech startup disruption. For New Entrants and Emerging Players: Mid-tier hospitality operators in Jeddah's western province present the most penetrable buyer archetype, as delivery-aggregator partnerships have conditioned these operators to variable cost structures. White-space targets include tablet POS for Saudi food trucks and edge-computing terminals for NEOM's offline-resilience pilots. A channel partnership strategy with domestic payment-acquiring platforms accelerates market access faster than direct sales investment. For Investors and Strategic Acquirers: SAMA's first fintech licensing wave for payment service providers is the leading indicator that captive terminal demand from licensed acquiring startups will concentrate hardware procurement decisions among fewer domestic platforms. Long-term viability favors vendors with certification pathway expertise and cloud-native software stacks over pure hardware fabricators. Acquisition targets should display PCI-DSS engineering talent density and established SAMA regulatory relationships. Practitioners should monitor open-banking API specification releases for terminal software compliance triggers.| Strategic Initiative | Industry Significance |
|---|---|
| Terminal-as-a-Service Platform Launch | Aligns hardware costs with transaction volume for Jeddah quick-service franchise operators. |
| SAMA Certification Pathway Investment | Accelerates vendor qualification timelines for Riyadh public sector tenders and bank-integrated retail. |
| SoftPOS Technology Partnership | Captures delivery-first restaurant volume as NFC-enabled smartphones displace dedicated terminals. |
| NEOM Smart City Embedded Infrastructure | Permits greenfield POS deployment without legacy system integration burden in Trojena and Sindalah zones. |
| Android Open-Platform Ecosystem Expansion | Enables third-party hospitality application integration for inventory and loyalty program bundling. |
Research Methodology
Document review covered SAMA regulatory circulars, PCI Security Standards Council protocol documentation, and Saudi Central Bank fintech licensing frameworks, complemented by interviews with terminal hardware procurement managers at Riyadh hypermarket chains, payment-acquiring platform executives at Jeddah-based fintech operators, hospitality technology integrators serving western province quick-service restaurants, and SAMA compliance officers. Secondary validation drew from SEC filings of listed terminal manufacturers, customs import records for payment hardware, and Vision 2030 infrastructure project announcements. Bottom-up terminal deployment estimates triangulated against top-down payment transaction volume projections.
Market sizing outputs segmented across hardware form factor, payment modality technology, end-use sector, and deployment architecture throughout the forecast period. CAGRs derived from regression analysis of historical replacement cycles, regulatory mandate implementation timelines, and tourism infrastructure construction schedules. Industry-specific inputs included SAMA real-time payment infrastructure investment trajectories and NEOM development zone construction phasing.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to semiconductor supply chain disruptions and open-banking API specification changes. Terminal shipment projections reflect assumptions regarding SAMA mandate enforcement consistency and Vision 2030 tourism target achievement. Practitioners should monitor fintech licensing application volumes and Red Sea Project construction milestones for early demand signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Mobile Card Reader Market
Payments
Europe Digital Transaction Management (DTM) Market
Payments
India Real Time Payments Market
Payments
Europe Payment Gateways Market
Payments
Digital Debit Market
Payments
Portugal POS Terminals Market
Payments
Master Recharge API Market
Payments
Spain Payment Gateway Market
Payments
Mobile Payment Security Market
Payments
Recurring Payments Market
Payments
Asia-Pacific Crypto Payment Gateway Market
Payments
Telecom Cloud Billing Market
Payments
B2C Payment Market
Payments
Fuel Cards Market
Payments
Face-Swiping Payment Market
Payments
Asia-Pacific Payment Analytics Software Market