
 Asia-Pacific Payment Gateway Market | 2026-2036
Asia-Pacific Payment Gateway Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Payment Gateway Market Insights
Singapore's fintech sandbox approvals for payment operators is rebalancing regional capacity allocation toward ASEAN hubs. Razorpay leverages its full-stack merchant acquisition engine to dominate India's mid-market segment. Paytm sustains super-app payment density through integrated financial services layering. Stripe competes on developer-centric API architectures that reduce enterprise integration cycles.
A payment gateway is a technology layer that encrypts, routes, and authorizes transaction data between merchants, acquirers, and card networks using TLS 1.3 protocols and tokenization standards to prevent card-not-present fraud. Its primary commercial purpose is to enable secure, real-time fund transfer validation across digital commerce channels. E-wallet transaction volumes are expanding fastest across Southeast Asian markets where bank penetration remains uneven and mobile-first commerce prevails. Cloud-based deployment models capture disproportionate margin pools by eliminating on-premises infrastructure overhead and enabling elastic transaction scaling during peak retail events.
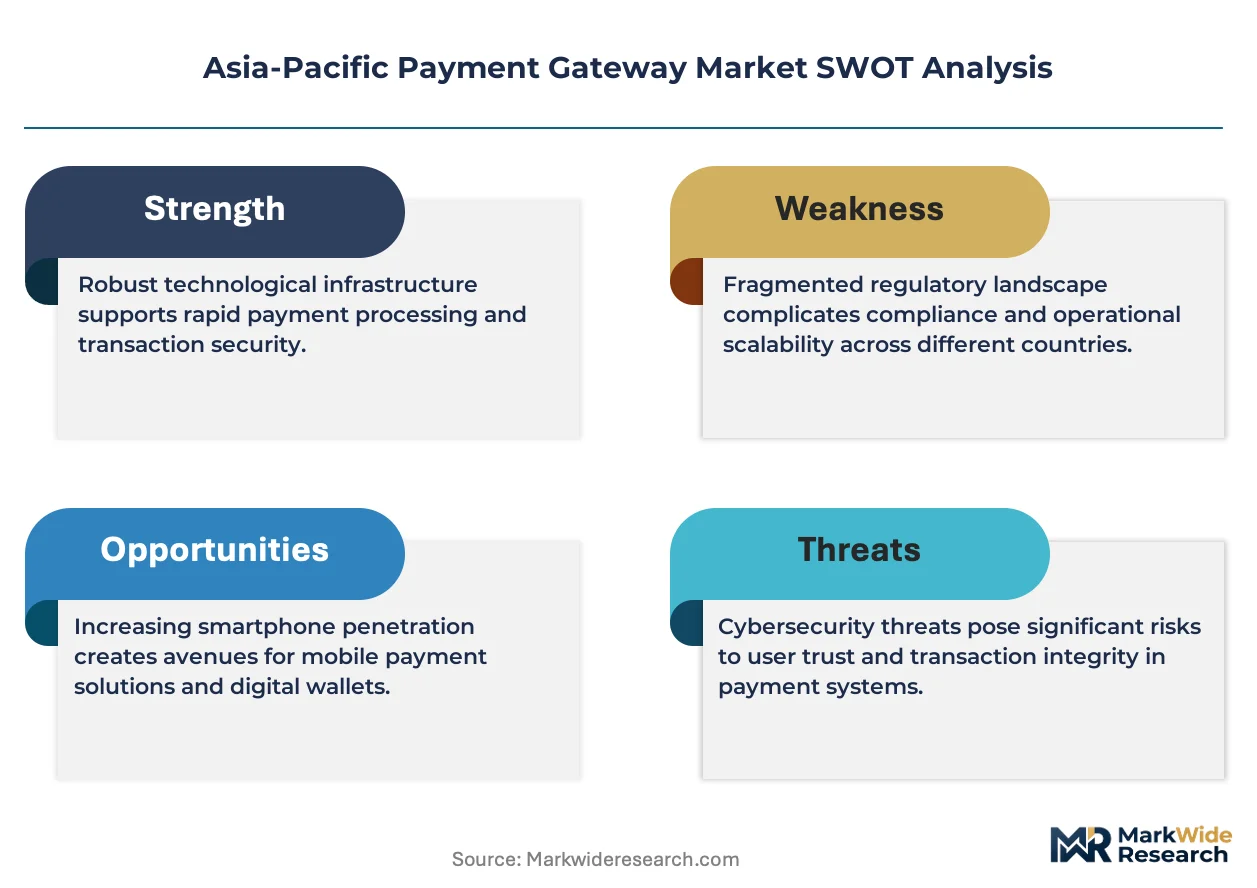
India's RBI mandates two-factor authentication and tokenization for card-not-present transactions, while Australia's ACCC enforces competition safeguards against payment network monopolization. Singapore's MAS licensing framework for major payment institutions shapes cross-border market access requirements across ASEAN corridors. Stakeholders must monitor divergent data localization mandates and real-time settlement interoperability standards as regulatory fragmentation intensifies competitive complexity.
Market Dynamics
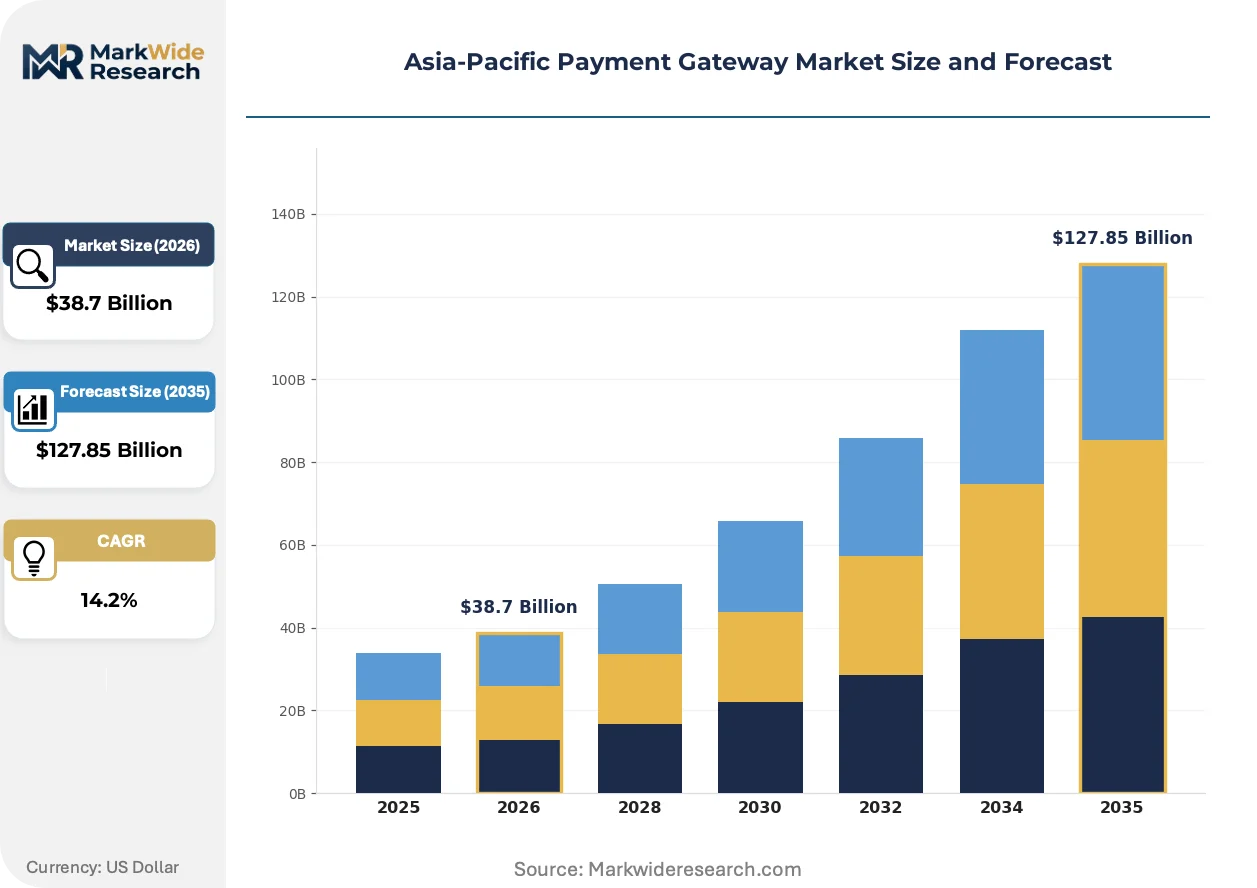
Cloud-native payment orchestration platforms are compressing legacy gateway margins across Southeast Asia, while India's real-time settlement mandates force infrastructure rebuilds at scale. This dual pressure—technology displacement plus regulatory compulsion—defines current competitive restructuring.
Growth Catalysts
- India's UPI protocol expansion:The interoperable real-time payment rail is absorbing merchant transaction volumes previously routed through card networks, forcing gateway providers to integrate native UPI stacks or lose domestic market relevance.
- Cross-border e-commerce corridors:ASEAN digital trade frameworks are reducing settlement friction for Singapore-based merchants selling into Indonesia, Vietnam, and Philippines, expanding addressable transaction volumes for regional gateway operators.
- Tokenization mandates:RBI and MAS requirements for card-not-present transaction security are accelerating merchant migration from basic encryption to advanced token vault architectures, creating upgrade revenue streams.
Market Restraints
- Data localization compliance costs:India's RBI and Vietnam's central bank require transaction data storage within national borders, forcing gateway operators to duplicate infrastructure across jurisdictions rather than centralize on regional cloud clusters.
- Card network concentration:Visa and Mastercard maintain dominant positions in premium cross-border transactions across Australia, Japan, and South Korea, limiting pricing power for independent gateway providers in high-margin segments.
- Real-time rail substitution:Australia's NPP and Thailand's PromptPay are disintermediating traditional card-acquiring flows for domestic transactions, compressing gateway fee capture in mature markets.
Strategic Opportunities
- Indonesia's unbanked merchant base:QRIS standardization across 500+ million mobile wallets creates a unified acceptance layer that gateway providers can leverage to bypass fragmented bank partnerships in the archipelago.
- Embedded finance convergence:The intersection of payment gateways with BNPL origination and merchant cash advance underwriting enables revenue stacking beyond transaction processing fees.
- Singapore's MAS licensing passport:Major Payment Institution licenses granted under Singapore's framework are being recognized across ASEAN bilateral agreements, reducing market entry friction for compliant operators.
Industry Challenges
- API integration talent scarcity:Demand for engineers fluent in ISO 20022 messaging standards and regional real-time rail protocols exceeds supply across Sydney, Bangalore, and Singapore hiring markets.
- Legacy core banking connectivity:Tier-2 and Tier-3 banks across Philippines and Vietnam still operate on batch-based settlement systems, requiring costly middleware development to enable real-time gateway functionality.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Payment Gateway Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $127.85 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payment Method: Credit Card, Debit Card, E-Wallet, Bank Transfer End User: E-Commerce, Retail, Travel, Digital Services Deployment Model: On-Premises, Cloud-Based, Hybrid, SaaS Transaction Type: Recurring Payments, One-Time Payments, Mobile Payments, International Transactions |
| Companies Covered | Razorpay, Paytm, PayPal Holdings, PayU, Amazon Payments, Stripe, Alipay, AsiaPay, Adyen, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Payment Gateway Market Trends and Innovations
Payment infrastructure across Asia-Pacific is converging on modular, API-first architectures that separate transaction routing from value-added services. This technical unbundling is enabling new competitive entry points and compressing traditional bundled pricing models.
Payment orchestration layers are consolidating multiple acquirer relationships and regional payment methods into single integration points. Mid-market merchants across Malaysia and Thailand are adopting these platforms to manage routing logic, failover sequencing, and reconciliation without maintaining direct connections to each underlying provider. The technology is consolidating merchant technology stacks and shifting procurement decisions from bank relationships toward software evaluation criteria.
Singapore's MAS licensing framework for major payment institutions is tightening capital adequacy and operational resilience requirements. Gateway operators must now maintain segregated customer funds, implement 24-hour incident response capabilities, and submit to annual technology risk audits. Australian and Indian regulators are observing these standards for potential adoption, creating compliance convergence pressure across the region.
Merchant procurement of payment infrastructure is fragmenting by transaction type rather than consolidating on single providers. Large e-commerce platforms across India and Southeast Asia are unbundling domestic acceptance, cross-border settlement, and payout disbursement across specialized gateways rather than relying on full-stack relationships. This pattern is most visible in Bangalore and Jakarta, where engineering-led merchant organizations prioritize best-of-breed components over integrated suites.
Asia-Pacific Payment Gateway Market Segmentation
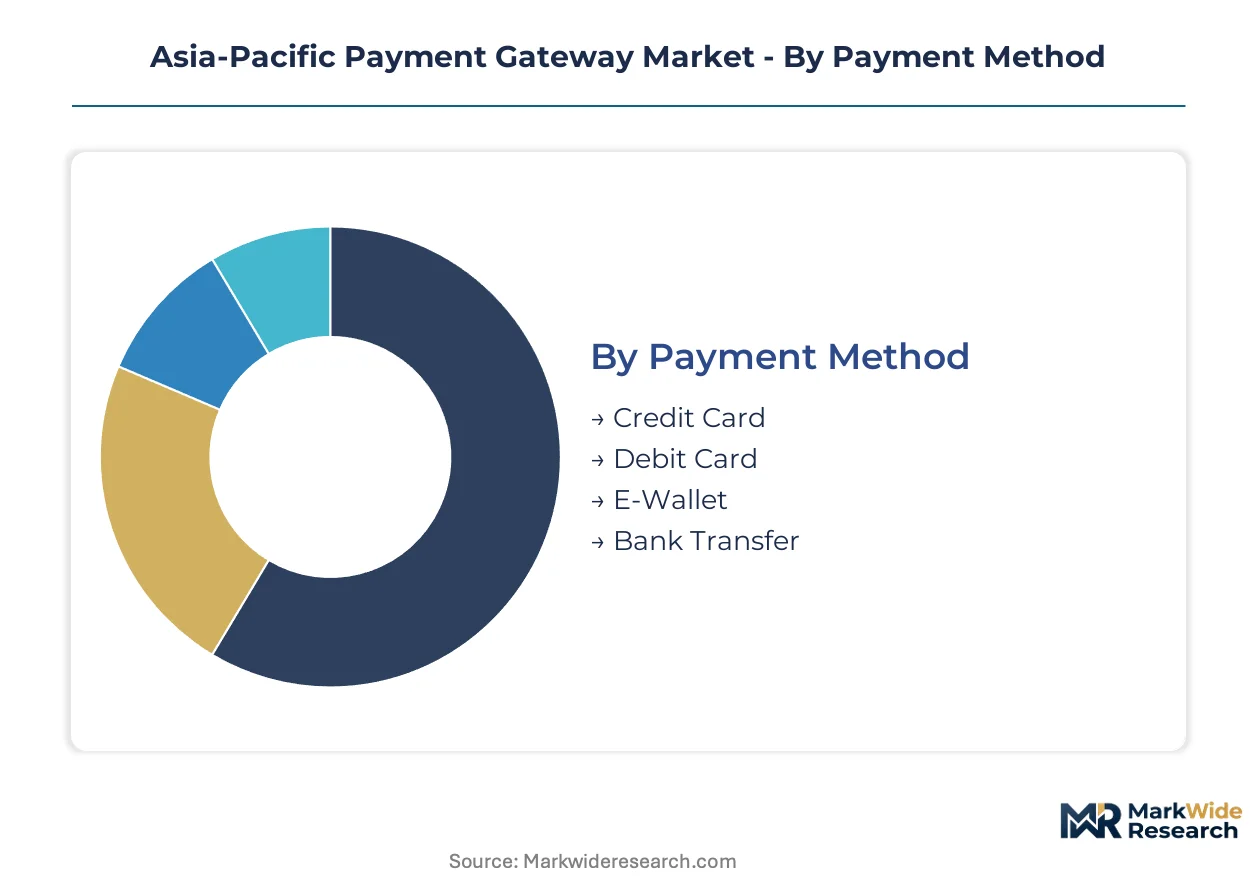
Payment gateway segmentation across Asia-Pacific reveals how transaction routing infrastructure fragments across payment rails, merchant types, and deployment architectures. Each dimension carries distinct regulatory compliance burdens and margin structures that reshape competitive positioning.
Payment Method:
Supply concentration in card networks versus alternative rails determines gateway routing economics and interchange fee exposure across the region.
- Credit Card:Visa and Mastercard rails dominate premium cross-border transactions, particularly in Australia, Japan, and South Korea. Gateways must maintain PCI-DSS Level 1 certification and dynamic 3D Secure orchestration to capture this high-margin volume.
- E-Wallet:QR-code-based mobile wallets across Indonesia, Philippines, and Vietnam are expanding most quickly as bank penetration gaps persist. India's UPI protocol and Southeast Asia's GrabPay, GoPay, and Dana ecosystems force gateway providers to integrate multiple wallet APIs rather than standardizing on card rails.
- Debit Card:Domestic debit schemes in India (RuPay) and China (UnionPay) carry lower interchange but higher transaction volumes for everyday commerce.
- Bank Transfer:Real-time account-to-account rails including Australia's NPP and Thailand's PromptPay are disintermediating card flows for high-value B2B settlements.
Today's leader: Credit Card. Tomorrow's challenger: E-Wallet.
End User:
Merchant sophistication tiers dictate gateway feature requirements and pricing tolerance across the customer base.
- E-Commerce:Online marketplaces require multi-acquirer orchestration, intelligent retry logic, and cross-border settlement capabilities. India's Flipkart and Indonesia's Tokopedia drive demand for sub-second authorization latency and multi-currency pricing engines.
- Digital Services:Subscription platforms and SaaS providers need vault tokenization and dunning management for recurring revenue streams. This segment climbs the fastest as API-first merchants prioritize developer experience over bundled bank relationships.
- Retail:Brick-and-mortar merchants adopting omnichannel strategies demand unified reconciliation across POS and online channels.
- Travel:Airlines and hospitality merchants face elevated chargeback risk and require pre-authorization holds with multi-currency hedging.
E-Commerce commands current procurement budgets. Digital Services is gaining share fastest among engineering-led merchant organizations.
Deployment Model:
Infrastructure ownership patterns separate enterprise control requirements from agility-seeking mid-market adopters.
- Cloud-Based:Elastic scaling eliminates peak-season capacity constraints for India's festival commerce and Southeast Asia's flash sale events. AWS, Azure, and Google Cloud regions in Singapore, Mumbai, and Sydney enable sub-100ms latency for transaction processing.
- SaaS:Pre-configured gateway stacks reduce time-to-live for small merchants lacking dedicated engineering resources across Philippines and Vietnam.
- Hybrid:Sensitive data remains on-premises while routing logic operates in cloud environments to satisfy India's RBI data localization mandates.
- On-Premises:Legacy financial institutions in Australia and Japan maintain captive infrastructure for regulatory audit trails.
Cloud-Based owns the volume trajectory. Hybrid is emerging as the compliance-driven compromise for data-sovereign markets.
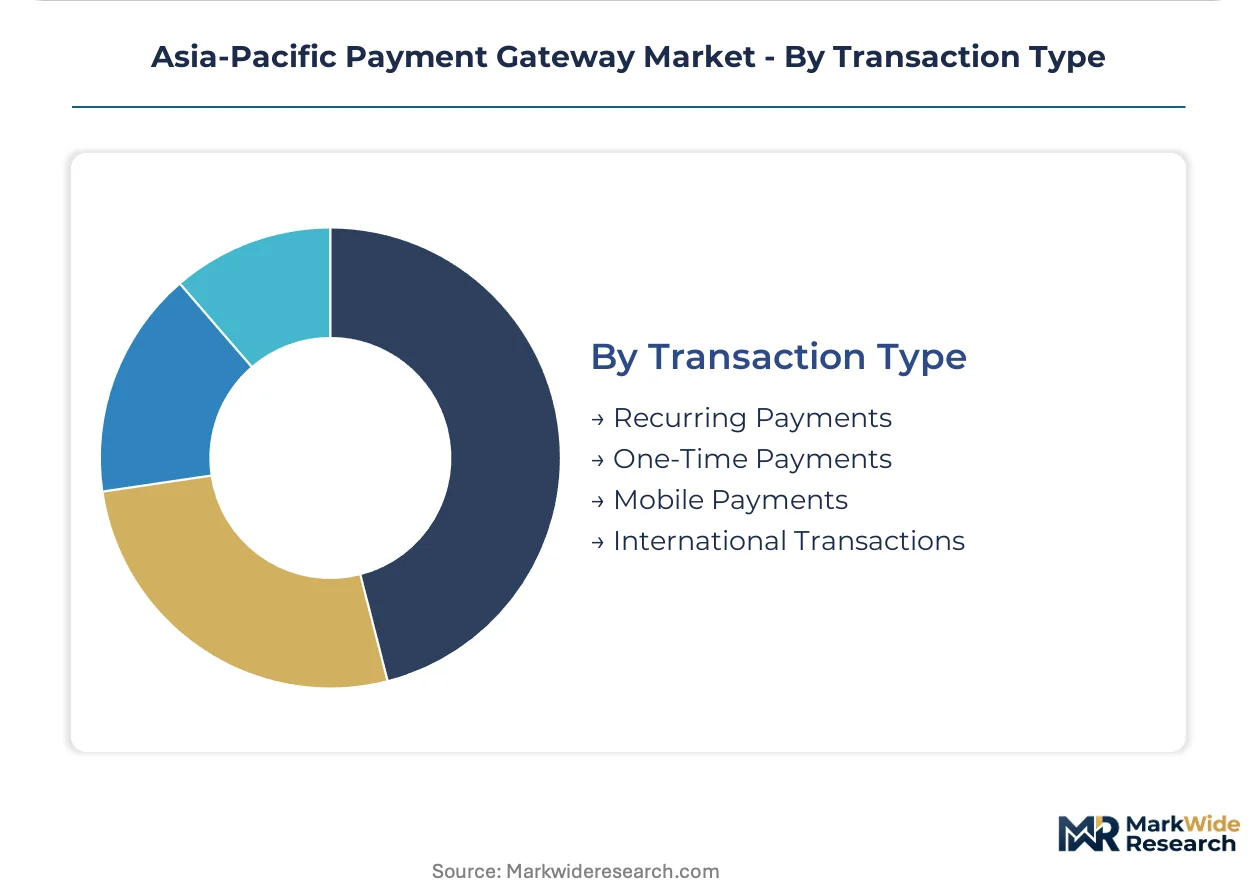
Transaction Type:
Settlement timing and geographic scope create distinct technical and regulatory complexity tiers for gateway operators.
- Mobile Payments:In-app and browser-based wallets require deep OS integration and biometric authentication orchestration. India's merchant base is expanding most quickly here as UPI penetration saturates urban centers and penetrates Tier-2 cities.
- International Transactions:Cross-border corridors demand FX hedging, multi-acquirer redundancy, and sanctions screening across ASEAN-Singapore-India corridors.
- Recurring Payments:Subscription billing requires credential vaulting and intelligent retry sequencing to minimize involuntary churn.
- One-Time Payments:Guest checkout flows prioritize friction reduction over relationship depth for infrequent purchasers.
Mobile Payments captures domestic growth momentum. International Transactions represents the margin expansion frontier for regional gateway operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gateway operators are arbitraging compliance-cost differentials across Asia-Pacific, concentrating infrastructure investment in Singapore's regulatory-passport jurisdictions while maintaining data-localized nodes in India and Vietnam where mandates force duplication.
India
Merchant onboarding volumes and UPI transaction density are expanding fastest in Bangalore, Mumbai, and Delhi-NCR. RBI mandates two-factor authentication and domestic data storage, forcing foreign operators to build India-specific infrastructure rather than route through regional hubs. The National Payments Corporation of India operates the UPI protocol that now dominates domestic settlement.
Singapore
MAS licensing for major payment institutions is attracting regional headquarters from gateway operators seeking ASEAN market access. The fintech sandbox framework accelerates approval timelines for payment operators testing cross-border settlement rails. Marina Bay and One-North clusters host engineering centers serving Indonesia, Philippines, and Vietnam corridors.
Australia
Real-time payment adoption through the NPP is compressing traditional card-acquiring volumes for domestic transactions. ACCC competition safeguards limit network monopolization, preserving entry points for independent gateway providers. Sydney and Melbourne fintech clusters concentrate API-first merchant infrastructure development.
Indonesia
QRIS standardization across 500 million mobile wallets is creating unified acceptance infrastructure that bypasses fragmented banking partnerships. Bank Indonesia regulations govern electronic money issuance and merchant settlement timelines. Jakarta and Surabaya anchor gateway development targeting unbanked merchant segments across the archipelago.
Vietnam
State Bank of Vietnam data localization requirements force transaction storage within national borders, raising infrastructure costs for regional operators. Ho Chi Minh City and Hanoi clusters concentrate e-commerce gateway development serving cross-border trade with China and ASEAN partners. Mobile wallet penetration is expanding fastest among younger demographics in urban centers.
Asia-Pacific Payment Gateway Market Competitive Landscape
Indian operators anchor the high-volume domestic tier; Singapore-based specialists hold cross-border orchestration capabilities. Market structure fragments across three capability tiers: full-stack merchant acquirers, API-first developer platforms, and regional payment method aggregators. Strategic archetypes include UPI-native domestic champions, ASEAN-licensed regional orchestrators, and global developer-platform entrants. Dominant competitive moves center on M&A for merchant portfolio expansion and technology licensing for real-time rail integration.
Within the full-stack acquirer tier, Razorpay and Paytm exemplify domestic champions that have built merchant density through integrated financial services layering. Stripe occupies a position among developer-centric platforms competing on API architecture and enterprise integration velocity. These three anchors represent divergent strategic bets on market entry: regulatory-native depth versus developer-experience differentiation versus super-app payment density.
| Leading Market Players |
|---|
| Razorpay |
| Paytm |
| PayPal Holdings |
| PayU |
| Amazon Payments |
| Stripe |
| Alipay |
| AsiaPay |
| Adyen |
| Others |
Pricing and Supply Chain Analysis
Cloud-native orchestration layer adoption simultaneously compresses legacy gateway infrastructure costs and concentrates merchant acquisition power among API-first platforms. Singapore-based operators arbitrage MAS licensing efficiency against India and Vietnam data localization mandates, reshaping margin pools across deployment architectures.
Pricing Analysis
Gateway-to-acquirer margin splits vary by transaction rail, with card-network interchange floors establishing price baselines that UPI and real-time rails undercut by 40-60 basis points. Price differentiation rests on tokenization vault sophistication and sub-100ms latency guarantees for festival-commerce peaks. Cost compression in mid-market SaaS tiers intensifies as Stripe and Razorpay compete on developer-experience bundling. E-commerce platforms exhibit highest price sensitivity, while travel and hospitality merchants prioritize chargeback protection over per-transaction economics.
Supply Chain Analysis
Merchant onboarding reversals and gateway migration flows concentrate technical debt in legacy batch-based systems across Philippines and Vietnam. Infrastructure supply concentrates in India, Singapore, and Australia, with AWS Mumbai, Azure Singapore, and Google Cloud Sydney regions anchoring elastic capacity. Critical dependencies include TLS 1.3 certificate authority services, ISO 20022 messaging protocol stacks, and RBI-compliant data center certifications. Single-source vulnerability runs through Visa and Mastercard cross-border switching for premium transactions. Distribution runs through direct API sales for enterprise merchants and channel partners for Tier-2 bank integrations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific payment infrastructure has entered a late-cycle quality phase where merchant procurement prioritizes tokenization-grade security and real-time rail interoperability over basic transaction routing. Premium gateway specifications now dominate RFP criteria as regulatory mandates harden compliance thresholds.
For Market Incumbents: Deepen UPI-native stack integration to defend against real-time rail substitution threatening card-acquiring revenue pools. Fortify India-specific data center capacity before RBI localization audits intensify. Acquire ISO 20022 engineering talent in Bangalore and Singapore to maintain orchestration layer leadership against API-first challengers.
For New Entrants and Emerging Players: Embedded-finance API routes offer lowest competitive density for merchant cash advance and BNPL origination attachment. Target Indonesia's QRIS-standardized merchant base where 500 million wallet users lack sophisticated gateway relationships. Pursue MAS licensing passport strategy to unlock ASEAN corridor access without jurisdiction-by-jurisdiction builds.
For Investors and Strategic Acquirers: Valuations sit cheapest among hybrid-deployment specialists with India data localization compliance and Singapore regional orchestration capabilities. Five-to-ten year viability hinges on real-time rail protocol diversification beyond card network dependency. Monitor UPI transaction share thresholds for inflection signals on domestic gateway relevance compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Real-Time Rail Integration | Native UPI and PromptPay connectivity preserves merchant relevance as card volumes shift. |
| Tokenization Vault Certification | RBI and MAS compliance creates upgrade revenue streams from security-mandated migrations. |
| Embedded Finance Convergence | BNPL origination layering captures merchant lending margins beyond transaction fees. |
| MAS Licensing Passport | Singapore regulatory recognition reduces ASEAN market entry friction and compliance duplication. |
| Hybrid Cloud Deployment | Data-sovereign architecture satisfies India's RBI mandates while maintaining elastic scaling. |
Research Methodology
Coverage spans India, Singapore, Australia, Indonesia, and Vietnam, with primary inputs from each market cluster. The study combines structured interviews with payment gateway CTOs, merchant acquisition heads at Tier-1 banks, MAS licensing officers, and RBI compliance leads with secondary validation. Secondary sources include NPCI UPI transaction disclosures, MAS fintech sandbox approval registers, ACCC competition review filings, and AWS regional infrastructure capex reports. Bottom-up merchant onboarding volume estimates triangulate against top-down payment rail transaction data.
Rate-of-change decomposition separates volume expansion from pricing compression effects across the projection horizon. Segmentation dimensions modeled include payment method rail, merchant sophistication tier, deployment architecture, and transaction settlement geography. CAGRs derive from regression analysis against UPI penetration curves and real-time rail adoption benchmarks. Industry-specific forecast inputs incorporate QRIS wallet standardization timelines and ASEAN digital trade framework implementation phases.
The model assumes a particular technology adoption path; alternative pathways for cloud-native orchestration would alter the outlook if legacy gateway migration stalls. Forecasts reflect assumptions about regulatory convergence on MAS capital adequacy standards and RBI data localization enforcement intensity. Practitioners should monitor UPI transaction share trajectories and MAS licensing reciprocity agreements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Brazil Real Time Payments Market
Payments
Greece POS Terminals Market
Payments
Asia-Pacific Payments Market
Payments
South Korea Digital Payments Market
Payments
United Kingdom Payment Market
Payments
Uganda Mobile Money Market
Payments
Global Payment Monitoring Market
Payments
Third Party Payment Market
Payments
South Africa Real Time Payments Market
Payments
Mobile Payment Data Protection Market
Payments
Portugal POS Terminals Market
Payments
Bitcoin Payments Market
Payments
Fuel and Convenience Store POS Market
Payments
Retail Cash Management Market
Payments
Global Accounts Payable Automation Market
Payments
Canada Real Time Payments Market