
 Payment Security Software Market | 2026-2036
Payment Security Software Market Size, Share, and Industry Trends Forecast 2026-2036
Payment Security Software Market Intelligence
Platform licensing is fragmenting between point-solution vendors and integrated-suite providers across the payment security stack. Thales leverages its hardware security module heritage to anchor high-assurance encryption contracts with central banks. Visa Inc. competes through tokenization standards that extend its network effects into merchant environments. Fiserv differentiates by embedding fraud detection into core banking workflows, sustaining renewal rates among regional financial institutions.
Payment security software comprises cryptographic tools, behavioral analytics engines, and access-control frameworks that protect card-not-present transactions, ACH transfers, and real-time payment rails against unauthorized interception or manipulation. These systems employ AES-256 encryption, dynamic token generation, and machine learning models scoring transaction risk in sub-100-millisecond windows to block fraudulent settlement before funds move. Cloud-based deployment leads among mid-market retailers seeking elastic capacity during peak shopping periods, while on-premises installations persist at financial institutions with sovereign data requirements. Tokenization solutions represent the fastest-expanding product type as merchants adopt network-agnostic vaulting to reduce PCI DSS audit scope.
PCI DSS mandates from the PCI Security Standards Council shape product certification requirements across North America, while the EU AI Act imposes algorithmic transparency obligations on machine learning-driven fraud scoring deployed in Europe. The UK's Financial Conduct Authority and the US Federal Reserve collectively tighten operational resilience standards, forcing payment processors to demonstrate sub-minute failover capabilities. Stakeholders must monitor divergence between regional encryption export controls and cloud data localization statutes when architecting cross-border transaction infrastructure.
Market Dynamics
Real-time payment rails are compressing fraud detection windows from minutes to milliseconds, forcing institutions to rebuild security stacks around sub-100-millisecond decision architectures rather than batch-processed risk scoring.
Growth Catalysts
- PCI DSS 4.0 mandates:Merchants in the United States face expanded encryption key rotation requirements that accelerate replacement of static token vaults with dynamic credentialing systems.
- Cloud-native processors:Mid-market retailers deploying elastic authentication capacity during peak transaction windows drive demand for API-first fraud scoring platforms.
- Behavioral biometrics:Keystroke dynamics and device fingerprinting adoption among European neobanks reduces false-positive rates in card-not-present authentication flows.
Market Restraints
- Hardware security module concentration:Production of FIPS 140-3 Level 3 certified modules concentrates among three specialized foundries, creating single-source vulnerability for central bank procurement.
- Quantum decryption threat horizon:Long-dated encryption contracts face technical obsolescence risk as post-quantum cryptographic standards from NIST remain unfinalized.
- Cross-border data localization:India's RBI and China's PBOC impose conflicting sovereign data residency rules that fragment unified fraud detection architectures.
Strategic Opportunities
- Brazilian instant payment rails:PIX transaction volumes exceed legacy card networks, creating first-mover advantage for tokenization vendors localizing vault infrastructure to São Paulo data centers.
- Embedded finance convergence:Non-financial platforms integrating checkout experiences require white-label authentication APIs that bypass traditional processor relationships.
- EU AI Act transparency obligations:Algorithmic explainability mandates for machine learning fraud models create service revenue streams around model documentation and audit preparation.
Industry Challenges
- Post-quantum cryptographic migration:Financial institutions lack internal cryptographers capable of evaluating lattice-based algorithm performance against latency requirements.
- Legacy core banking integration:COBOL-based settlement systems at regional banks resist API connectivity, forcing expensive middleware development for real-time fraud interception.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Payment Security Software Market |
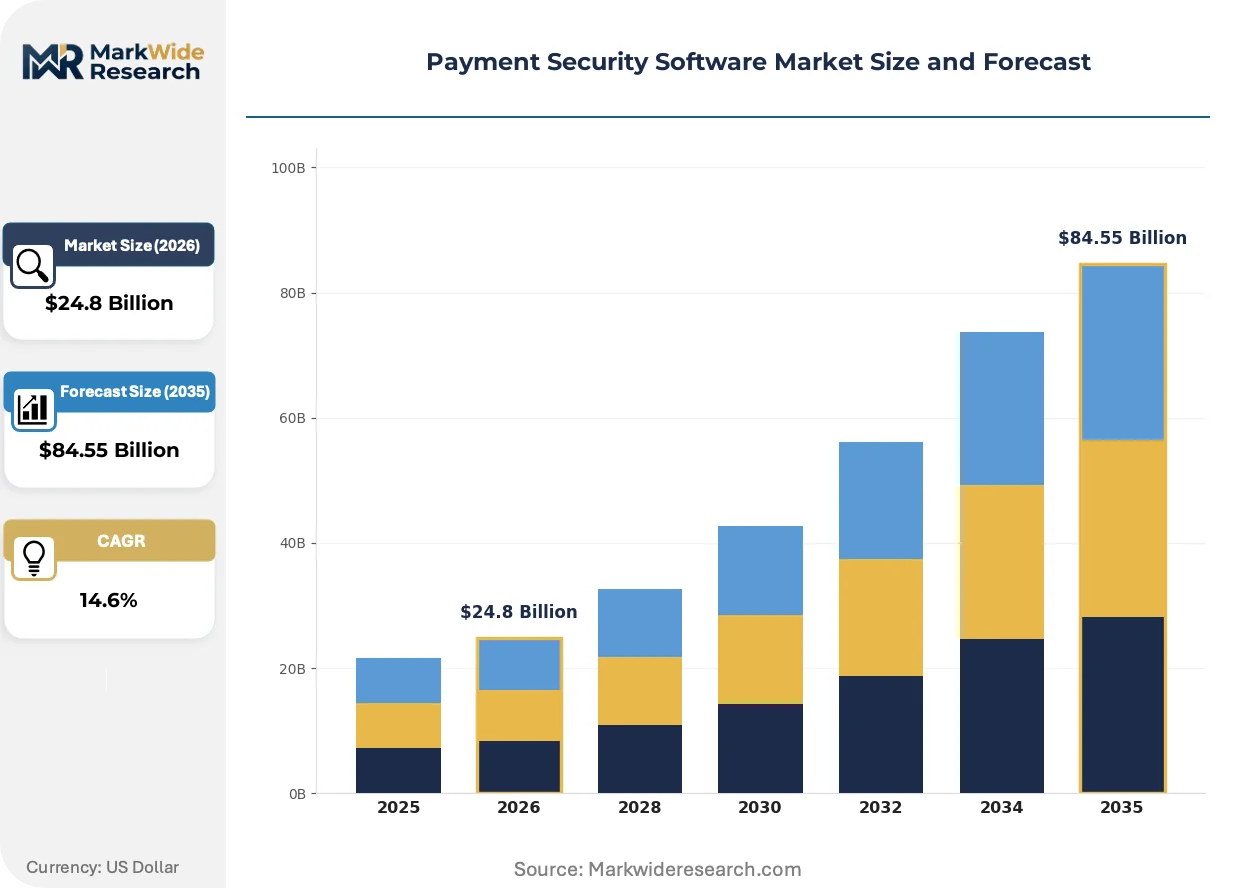
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $84.55 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Encryption Software, Tokenization Solutions, Fraud Detection Tools, Authentication Solutions Deployment: Cloud-Based, On-Premises, Hybrid, Managed Services End User: Retailers, Financial Institutions, E-commerce Platforms, Payment Processors Technology: Blockchain, Machine Learning, AI Analytics, Data Encryption |
| Companies Covered | Thales, PayPal Holdings, Visa Inc., Bluefin Payment Systems, Broadcom Inc., Fiserv, Mastercard Incorporated, ACI Worldwide, Trend Micro, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Payment Security Software Market Strategic Shifts & Innovations
Payment security architectures are pivoting from perimeter defense to continuous authentication, embedding risk scoring directly into transaction initiation rather than verifying identity at session start.
Homomorphic encryption is rendering obsolete traditional token vault architectures that require data decryption for processing. Neobanks in Germany and the Netherlands deploy partially homomorphic schemes for balance verification without exposing plaintext account values. This compression of the trust boundary eliminates the PCI DSS audit surface area previously occupied by cleartext data handling infrastructure.
The EU AI Act imposes algorithmic transparency obligations on machine learning-driven fraud scoring deployed across European payment processors. Model explainability requirements force vendors to abandon black-box neural architectures in favor of interpretable gradient-boosted ensembles. French and Dutch regulators now demand feature-importance documentation for every declined transaction above threshold values.
Merchant procurement of fraud protection is fragmenting from bundled processor contracts toward unbundled best-of-breed point solutions. Mid-market retailers in the United Kingdom and Australia now separately contract device fingerprinting, behavioral biometrics, and transaction monitoring from specialized vendors. This disaggregation compresses switching costs and accelerates replacement cycles as individual components fail to demonstrate ROI against standalone benchmarks.
Payment Security Software Market Segmentation
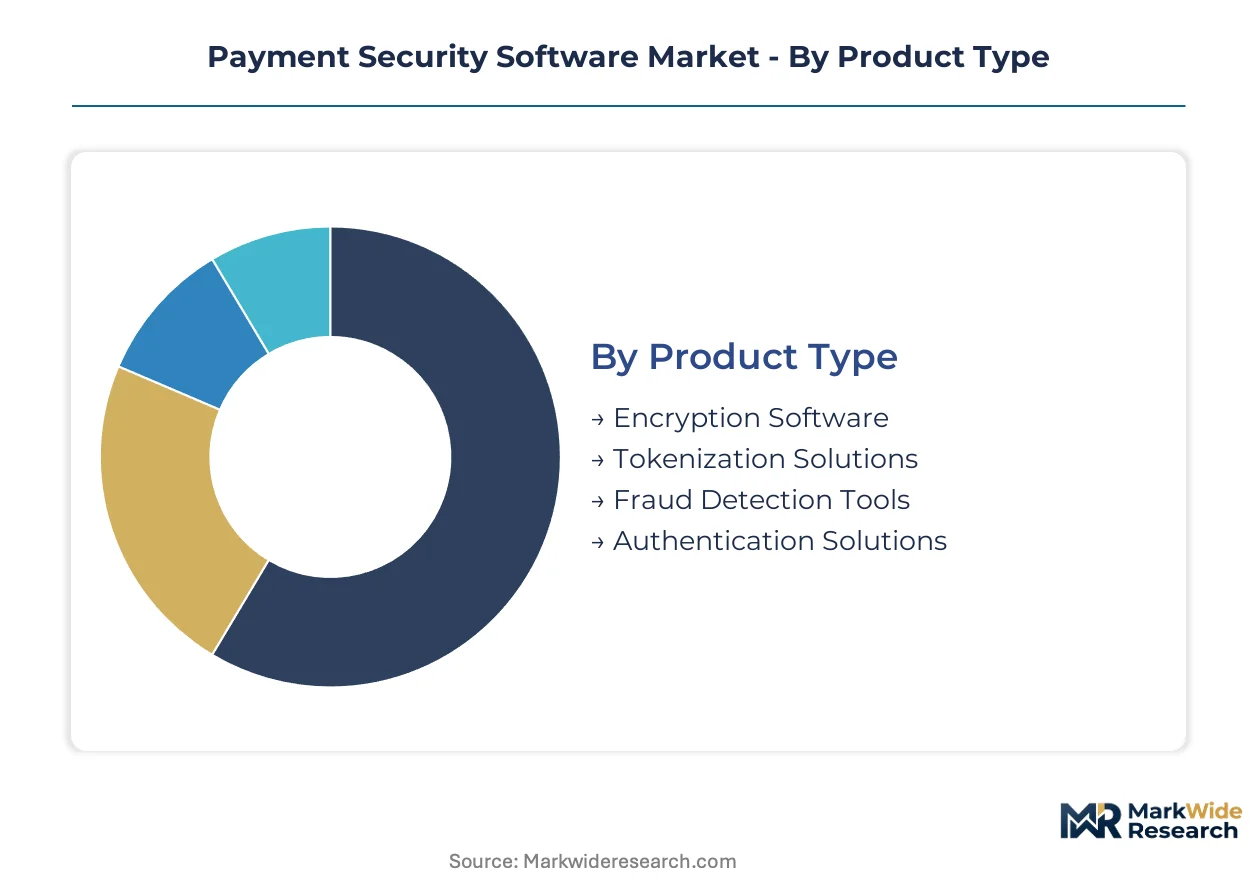
Payment security procurement cycles vary dramatically across segments, with authentication solutions refreshing every 18-24 months while encryption infrastructure persists for 7-10 years. Understanding these replacement rhythms shapes vendor forecasting and R&D prioritization.
Product Type:
Replacement velocity separates the product landscape, with point solutions cycling fastest and infrastructure software anchoring longest tenures.
- Tokenization Solutions:Dynamic credential vaulting systems reduce PCI DSS audit scope by replacing primary account numbers with non-sensitive equivalents. Demand concentrates among mid-market retailers in the United States seeking elastic capacity during peak shopping windows, driven by cloud-native processor mandates for network-agnostic vaulting.
- Fraud Detection Tools:Real-time scoring engines employing machine learning models evaluate transaction risk in sub-100-millisecond windows. European neobanks in Germany and the Netherlands are expanding procurement of behavioral analytics layers to reduce false-positive rates in card-not-present flows, pressured by EU AI Act algorithmic transparency obligations.
- Encryption Software:AES-256 cryptographic stacks and key management systems protect data at rest and in transit.
- Authentication Solutions:Multi-factor and biometric verification frameworks secure transaction initiation.
Tokenization anchors the volume base while fraud detection tools gain share at the steepest rate.
Deployment:
Cost tier stratification drives deployment selection, with capital-constrained mid-market retailers favoring operational expenditure models over upfront infrastructure investment.
- Cloud-Based:API-first platforms deliver elastic authentication capacity without fixed hardware commitments. United States-based payment processors are standardizing on cloud-native architectures to handle surge transaction volumes during retail peak periods.
- Hybrid:Split architectures maintain sensitive cryptographic operations on-premises while pushing analytics to cloud environments. Financial institutions in jurisdictions with conflicting data localization rules are adopting hybrid models to satisfy RBI and PBOC sovereign residency requirements without sacrificing real-time scoring performance.
- On-Premises:Dedicated hardware installations serve institutions with sovereign data requirements.
- Managed Services:Outsourced security operations reduce internal specialist headcount burdens.
Cloud-based deployment captures the dominant procurement share while hybrid configurations climb fastest among regulated institutions.
End User:
Customer type determines solution complexity, with integrated platforms demanding unified stacks and specialized merchants accepting fragmented point solutions.
- E-commerce Platforms:Digital-native checkout experiences require embedded fraud prevention with millisecond latency tolerance. United Kingdom and Australian mid-market retailers are unbundling device fingerprinting, behavioral biometrics, and transaction monitoring from processor contracts to optimize individual component ROI.
- Financial Institutions:Central banks and regional banks procure high-assurance encryption with FIPS 140-3 Level 3 certification. Procurement concentrates among institutions replacing legacy COBOL-based settlement systems with API-connected real-time fraud interception capabilities.
- Retailers:Physical and omnichannel merchants balance checkout friction against fraud loss exposure.
- Payment Processors:Network operators standardize tokenization and authentication protocols across merchant portfolios.
Financial institutions anchor the volume base while e-commerce platforms expand procurement at the steepest trajectory.
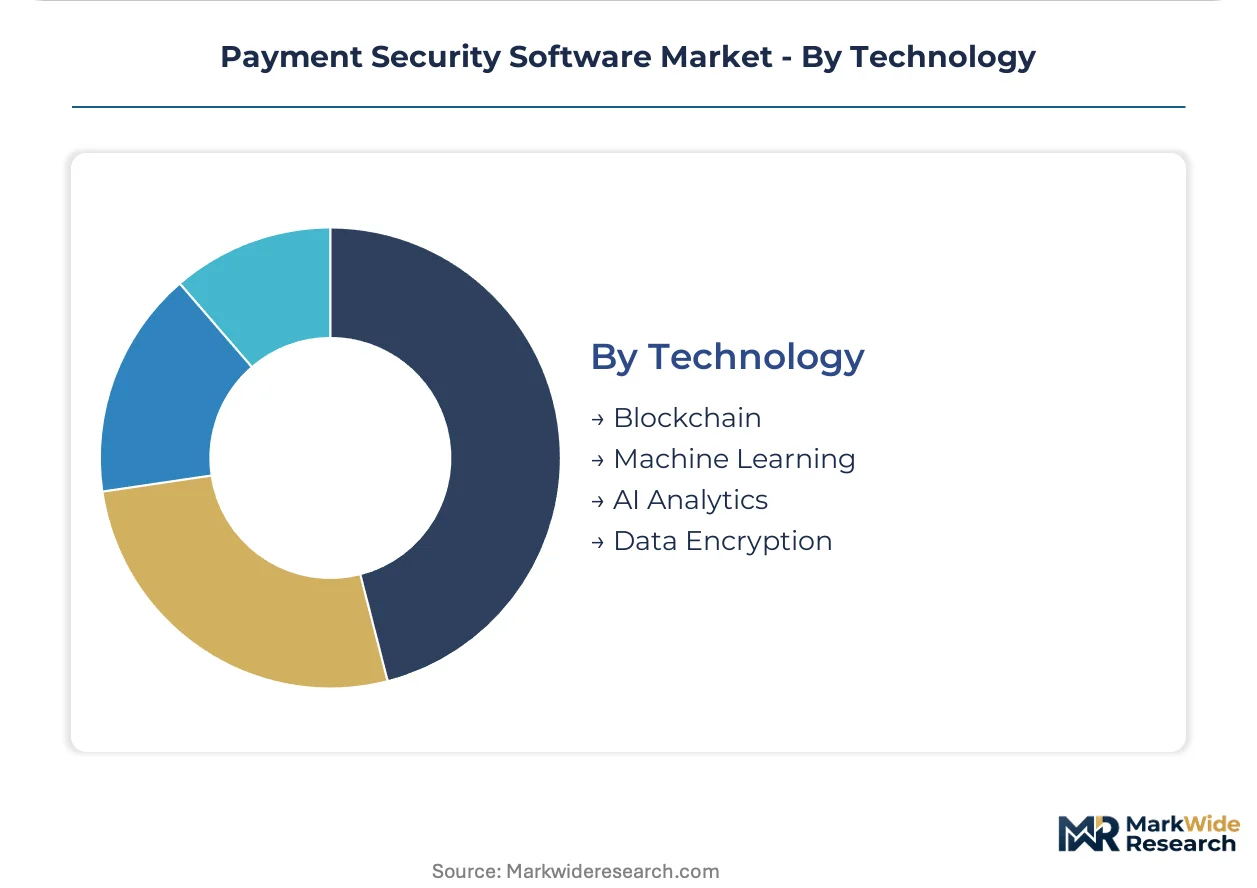
Technology:
Technology maturity stages segment the innovation pipeline, with proven encryption giving way to experimental architectures.
- AI Analytics:Interpretable gradient-boosted ensembles replace black-box neural architectures to satisfy EU AI Act explainability mandates. French and Dutch regulators now require feature-importance documentation for declined transactions above threshold values, forcing model architecture redesigns.
- Machine Learning:Supervised and unsupervised learning models detect anomalous transaction patterns. Behavioral biometric adoption among European neobanks drives keystroke dynamics and device fingerprinting integration into authentication flows.
- Data Encryption:Established AES-256 and emerging post-quantum lattice-based algorithms protect data integrity.
- Blockchain:Distributed ledger verification remains experimental for settlement finality applications.
Data encryption anchors the installed base while AI analytics gains adoption at the steepest rate among regulated European processors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in the United States demonstrate the lowest price elasticity for payment security software, absorbing premium pricing for sub-100-millisecond fraud detection. European procurement exhibits moderate sensitivity, with algorithmic transparency mandates adding compliance cost premiums. Indian and Brazilian markets show highest elasticity, prioritizing cost-efficient cloud-native solutions over on-premises infrastructure.
United States
Cloud-native payment processors and mid-market retailers drive authentication software upgrades with elastic capacity demands. PCI DSS 4.0 mandates from the PCI Security Standards Council accelerate replacement of static token vaults with dynamic credentialing systems. The San Francisco Bay Area and New York Metro clusters concentrate fintech procurement of API-first fraud scoring platforms.
Germany
Neobanks in Berlin and Frankfurt expand behavioral biometrics procurement to reduce false-positive rates in card-not-present flows. The EU AI Act imposes algorithmic transparency obligations on machine learning-driven fraud scoring, forcing model architecture redesigns. The Frankfurt Rhine-Main financial center anchors high-assurance encryption contracts with Bundesbank connectivity requirements.
United Kingdom
Mid-market retailers in London and Manchester unbundle device fingerprinting and transaction monitoring from processor contracts to optimize component ROI. The Financial Conduct Authority tightens operational resilience standards, forcing sub-minute failover demonstrations. The London fintech corridor concentrates procurement of white-label authentication APIs for embedded finance platforms.
Brazil
PIX instant payment rail volumes exceeding legacy card networks create first-mover opportunity for tokenization vendors. The central bank's data localization requirements drive vault infrastructure localization to São Paulo data centers. The São Paulo financial district anchors regional procurement of cloud-native fraud detection with Portuguese-language model training.
India
RBI sovereign data residency rules fragment unified fraud detection architectures for multinational processors. The Mumbai-Pune corridor concentrates domestic fintech procurement of cost-optimized behavioral analytics. Bangalore's technology cluster drives demand for API-first platforms serving mid-market retailers with elastic authentication capacity.
Payment Security Software Market Key Industry Players
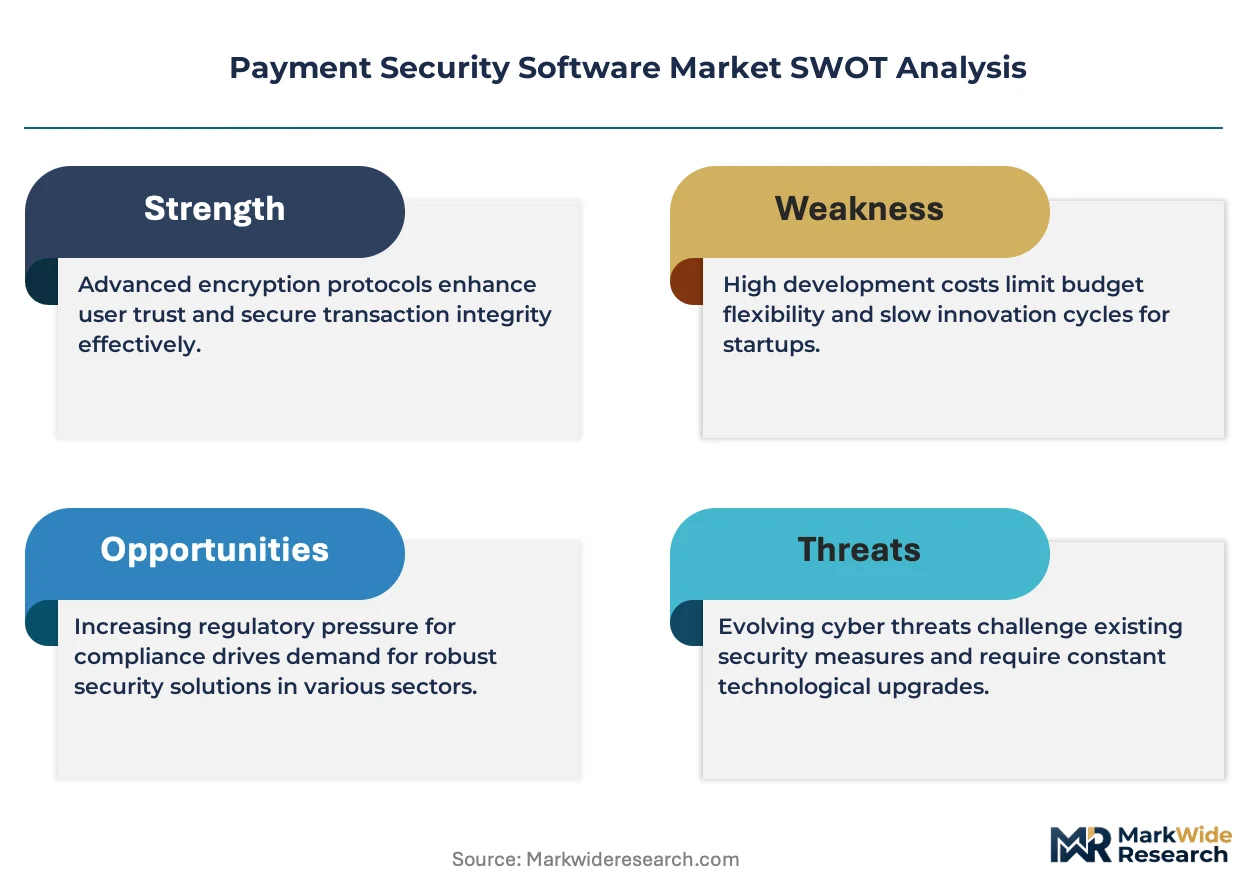
Capability concentration sits with specialized encryption vendors; scale advantage sits with network operators and diversified technology conglomerates. The market structures around three tiers: hardware security module specialists anchoring central bank procurement, payment network operators extending tokenization standards into merchant environments, and diversified technology providers embedding fraud detection into core banking workflows. Dominant competitive moves include strategic partnerships between cloud-native processors and authentication specialists, plus portfolio diversification into adjacent compliance software.
Within the hardware security tier, Thales leverages its module heritage to anchor high-assurance contracts. Visa Inc. and Mastercard Incorporated occupy positions as network operators standardizing tokenization protocols. Fiserv sits within the diversified technology tier, embedding fraud detection into banking workflows. Among these archetypes, Thales exemplifies capability concentration, while Visa Inc. represents scale advantage through network effects.
| Leading Market Players |
|---|
| Thales |
| PayPal Holdings |
| Visa Inc. |
| Bluefin Payment Systems |
| Broadcom Inc. |
| Fiserv |
| Mastercard Incorporated |
| ACI Worldwide |
| Trend Micro |
| Others |
Cost & Logistics Intelligence
Three specialized foundries in Germany, Taiwan, and the United States anchor FIPS 140-3 Level 3 certified hardware security module production, concentrating upstream margin capture with central banks and tier-one payment processors while squeezing mid-market authentication vendors into commodity software tiers.
Pricing Analysis
Recurring service revenue from key rotation management and compliance audit support drives lifetime value beyond initial licensing. Three-tier pricing structure across premium, standard, and economy levels separates central bank HSM contracts from neobank SaaS subscriptions and mid-market retailer API tiers. Price differentiation rests on certification depth and sub-100-millisecond latency guarantees. Cost compression in the standard tier intensifies as cloud-native processors bundle fraud detection into interchange fees. Mid-market retailers in Brazil and India exhibit highest price sensitivity, while United States financial institutions absorb premium positioning for real-time scoring architectures.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for semiconductor-dependent encryption hardware. Manufacturing concentrates in Taiwan for advanced chip fabrication, Germany for precision HSM assembly, and the United States for sovereign-certified final integration. Raw material dependencies include rare earth elements for magnetic shielding, specialized substrates for tamper-resistant enclosures, and cryptographic-grade random number generators. Single-source vulnerability persists at the foundry level for FIPS 140-3 Level 3 certification. Distribution runs through direct enterprise sales for central bank procurement and API marketplaces for cloud-native authentication services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Payment security is undergoing a platform-economics inflection as tokenization standards and open banking APIs dismantle processor-controlled merchant relationships, with network-agnostic vaulting and embedded finance interoperability redefining competitive moats.
For Market Incumbents: Entrench central bank relationships through post-quantum cryptographic readiness programs and sovereign data residency certifications. Deepen vertical integration into cloud infrastructure partnerships to defend against API-first challengers. Prioritize FIPS 140-3 Level 4 pre-certification investment ahead of NIST standard finalization.
For New Entrants and Emerging Players: Mid-market retailers in Southeast Asia and Latin America represent the most penetrable entry point for unbundled behavioral biometrics point solutions. Embedded finance platforms integrating checkout experiences require white-label authentication APIs that bypass traditional processor relationships. Target PIX and UPI instant payment rails with localized Portuguese and Hindi model training.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed fraud detection specialists holding ISO 27001 and PCI DSS 4.0 pre-certification. Long-term viability hinges on algorithmic explainability capabilities satisfying EU AI Act mandates. Watch for NIST post-quantum standard finalization as portfolio revaluation trigger.
| Strategic Initiative | Industry Significance |
|---|---|
| Post-Quantum Cryptographic Migration | NIST lattice-based standard adoption positions vendors for central bank renewal cycles. |
| API-First Platform Integration | Open banking interoperability dismantles processor-controlled merchant authentication relationships. |
| Embedded Finance Partnership | Non-financial platform checkout integration bypasses traditional acquiring bank channels. |
| Algorithmic Explainability Investment | EU AI Act compliance creates audit documentation revenue streams for European processors. |
| Geographic Vault Localization | São Paulo and Mumbai data center deployment satisfies RBI and Banco Central do Brasil residency rules. |
Research Approach
A spread of perspectives from chief information security officers at tier-one banks, payment processor platform engineers, neobank fraud operations leads, and merchant technology procurement managers converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against PCI Security Standards Council certification databases, central bank procurement disclosures, and cloud hyperscaler security service roadmaps. Bottom-up transaction volume modeling and top-down encryption infrastructure spending estimates were triangulated against regulatory filing patterns.
Demand-supply-balance framing anchored the analytical approach across the analysis window. Segmentation dimensions modeled include deployment architecture, end-user category, authentication technology maturity, and regional regulatory cluster. CAGRs were derived from replacement cycle velocity differentials between 18-month authentication refreshes and 10-year encryption infrastructure tenures. Forecast inputs incorporated PIX and UPI instant payment rail transaction trajectories alongside PCI DSS 4.0 mandate compliance timelines.
Macroeconomic conditions sit as an overlay; deviation in central bank interest rate policy affecting fintech venture funding, or abrupt shifts in India-China data localization diplomacy, would shift the trajectory. Forecasts reflect documented assumptions around NIST post-quantum standard finalization schedules and EU AI Act enforcement intensity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Vietnam Mobile Payments Market
Payments
Payment Instruments Market
Payments
Remote Deposit Capture Market
Payments
France Buy Now Pay Later Services Market
Payments
Global Master Card Market
Payments
Digital Transfer Services Market
Payments
Global Smart Payment Systems Market
Payments
Saudi Arabia Cash Management Services Market
Payments
Mobile Point of Sale Devices (Mpos) Market
Payments
Buy Now Pay Later (BNPL) Services Market
Payments
Slovenia Point of Sale (POS) Terminal Market
Payments
Cyprus POS Terminals Market
Payments
United Arab Emirates Mobile Payments Market
Payments
Global Real-Time Payments Market
Payments
South Korea Digital Payments Market
Payments
Nigeria Mobile Money Market