
 Remote Deposit Capture Market | 2026-2036
Remote Deposit Capture Market Size, Share, and Industry Trends Forecast 2026-2036
Remote Deposit Capture Market Intelligence
Buyer concentration is shifting as mid-sized credit unions and regional banks fragment across competing platform providers rather than clustering around legacy core processors. Fiserv leverages its core banking integration to sustain deposit capture workflows within existing infrastructure stacks. Jack Henry anchors community and regional bank segments with vertically aligned processing relationships. Mitek competes on mobile image capture accuracy, extending its computer vision specialization into check fraud detection adjacent services.
Remote deposit capture encompasses digital systems that transmit check images and magnetic ink character recognition data from customer endpoints to clearing networks, replacing physical presentment. Image quality specifications mandate minimum dots-per-inch resolution and strict adherence to ANSI X9 standards for exchange and settlement. Cloud-based deployment leads segment growth as banks shed on-premises maintenance burdens, while hardware device solutions retain entrenched positions among high-volume commercial treasury clients where scanner-based batch processing still dominates. Software solutions capture expanding margin pools through API-embedded distribution into fintech deposit products and neobank onboarding flows.
Check 21 Act provisions enforced by the Federal Reserve Board govern substitute check legality and truncation rights, directly shaping product design requirements for image retention and audit trails. NACHA operating rules and FFIEC authentication guidance layer compliance obligations onto multi-factor authentication and encryption implementations within security feature configurations. Stakeholders must monitor evolving FedNow interoperability standards and real-time payment network convergence to anticipate whether check digitization demand sustains or redirects toward instant payment rail alternatives.
Market Dynamics
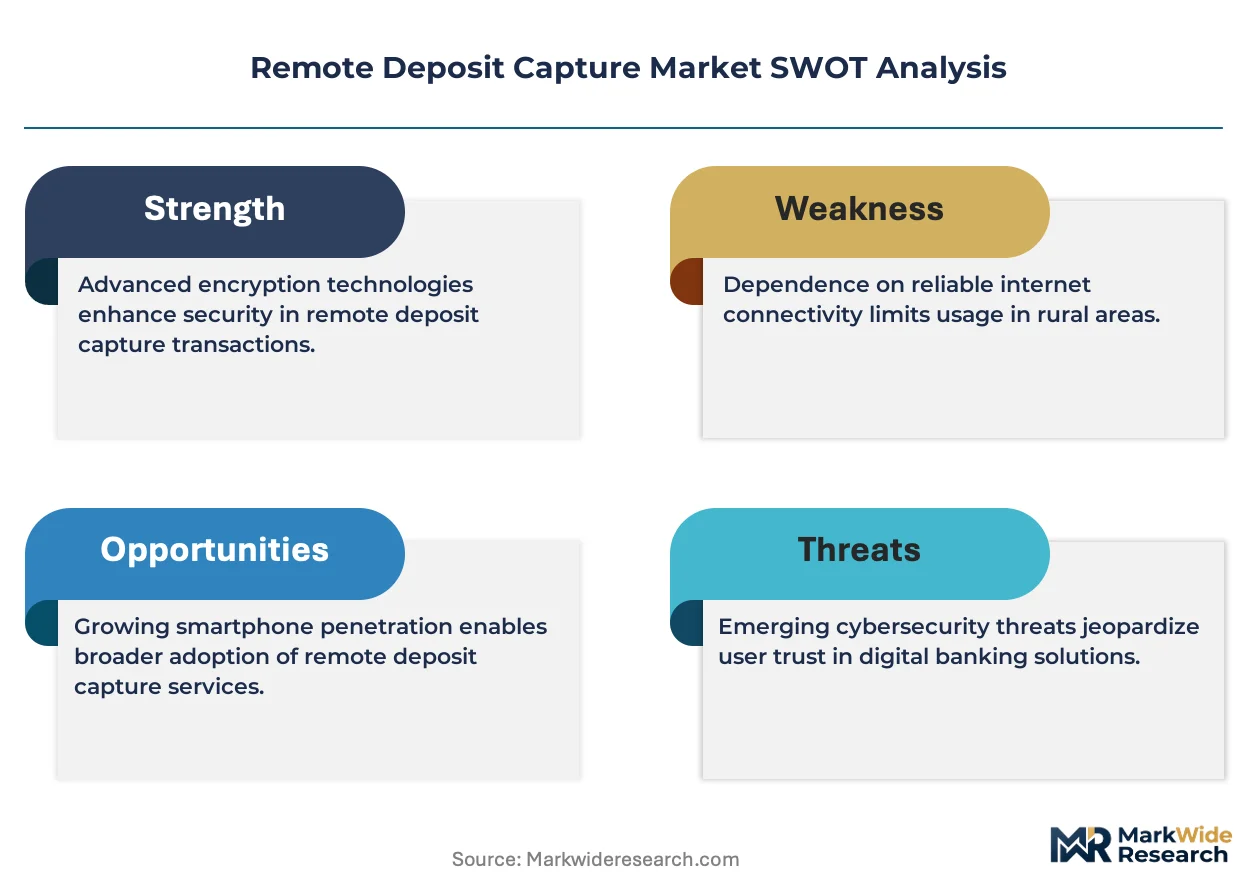
Branch rationalization across United States community banking is compressing physical check presentment infrastructure while accelerating cloud-native deposit platform procurement cycles. This structural force fragments buyer concentration away from legacy core processors toward specialized remote capture vendors.
Growth Catalysts
- Check 21 Act truncation rights:Federal Reserve Board enforcement of substitute check legality enables financial institutions to eliminate physical transport costs while maintaining clearing eligibility.
- Mobile image capture accuracy improvements:Computer vision algorithms now achieve MICR-line recognition rates sufficient for consumer-grade smartphone deployment without dedicated scanner hardware.
- Credit union digital transformation mandates:Member-owned institutions with limited IT staffing prioritize API-embedded deposit solutions requiring minimal on-premises maintenance.
Market Restraints
- High-volume commercial treasury batch processing:Scanner-based hardware retains entrenched positions among corporate clients processing thousands of checks daily, slowing pure software substitution.
- NACHA operating rules compliance friction:Multi-factor authentication and encryption implementation requirements extend vendor certification timelines and inflate security feature development costs.
- FedNow real-time payment convergence:Instant payment rail development threatens sustained check digitization demand as treasurers evaluate alternative settlement mechanisms.
Strategic Opportunities
- Fintech deposit product embedding:Neobank onboarding flows and digital-first banking platforms create API distribution channels bypassing traditional core processor relationships.
- Adjacent check fraud detection services:Image capture infrastructure enables computer vision extension into counterfeit detection and signature verification revenue streams.
- FFIEC authentication guidance alignment:Compliance-forward positioning around federal examination standards differentiates vendors during community bank procurement evaluations.
Industry Challenges
- ANSI X9 standards adherence:Image quality specifications mandate precise dots-per-inch resolution and exchange format compliance, requiring specialized engineering talent scarce outside established vendors.
- Core banking integration complexity:Deposit capture workflows must maintain interoperability with legacy infrastructure stacks while supporting modern API architectures, straining implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Remote Deposit Capture Market |
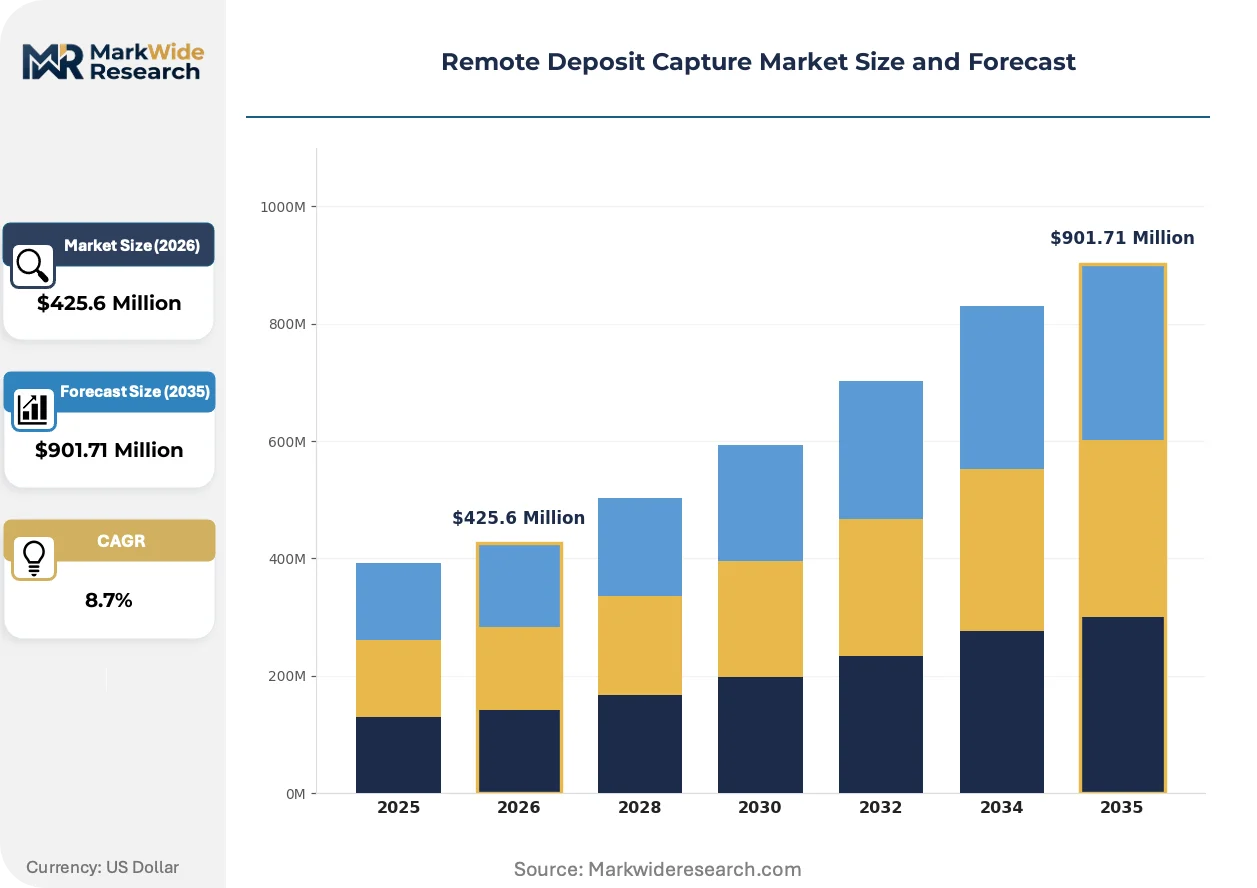
| Market Size in 2026 | $425.6 Million |
| Market Size in 2035 | $901.71 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Mobile App, Online Portal, Hardware Device, Software Solution End User: Retail Banks, Commercial Banks, Credit Unions, Fintech Companies Deployment: Cloud-Based, On-Premises, Hybrid, SaaS Security Feature: Encryption, Multi-Factor Authentication, Biometric Verification, Tokenization |
| Companies Covered | Deluxe, Jack Henry, Fiserv, Silicon Valley Bank, e-Zest, Mitek, VSoft, U.S. Bank, RDM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Remote Deposit Capture Market Strategic Shifts & Innovations
Remote deposit capture architecture is fragmenting from monolithic enterprise deployments toward composable service layers. This decomposition enables selective capability procurement and accelerates feature iteration cycles.
Artificial intelligence-powered image preprocessing is modularizing quality assurance workflows previously embedded in hardware scanners. Mid-sized regional banks now deploy cloud-based correction engines that auto-correct skew, glare, and edge detection failures before transmission. This capability compression eliminates dedicated scanner requirements for moderate-volume commercial clients.
Federal Reserve Board oversight of Check 21 Act implementation is tightening audit trail retention mandates. Financial institutions must now maintain searchable image archives with structured metadata fields for examination retrieval. Community banks with limited compliance staffing increasingly outsource retention infrastructure to specialized deposit capture vendors.
Commercial treasury buyers are unbundling scanner hardware from software licensing agreements. Procurement teams negotiate separate maintenance contracts for physical devices while sourcing capture platforms through subscription models. This bifurcation is most visible among United States middle-market companies with distributed lockbox operations seeking operational expense treatment over capital expenditure classification.
Remote Deposit Capture Market Segmentation
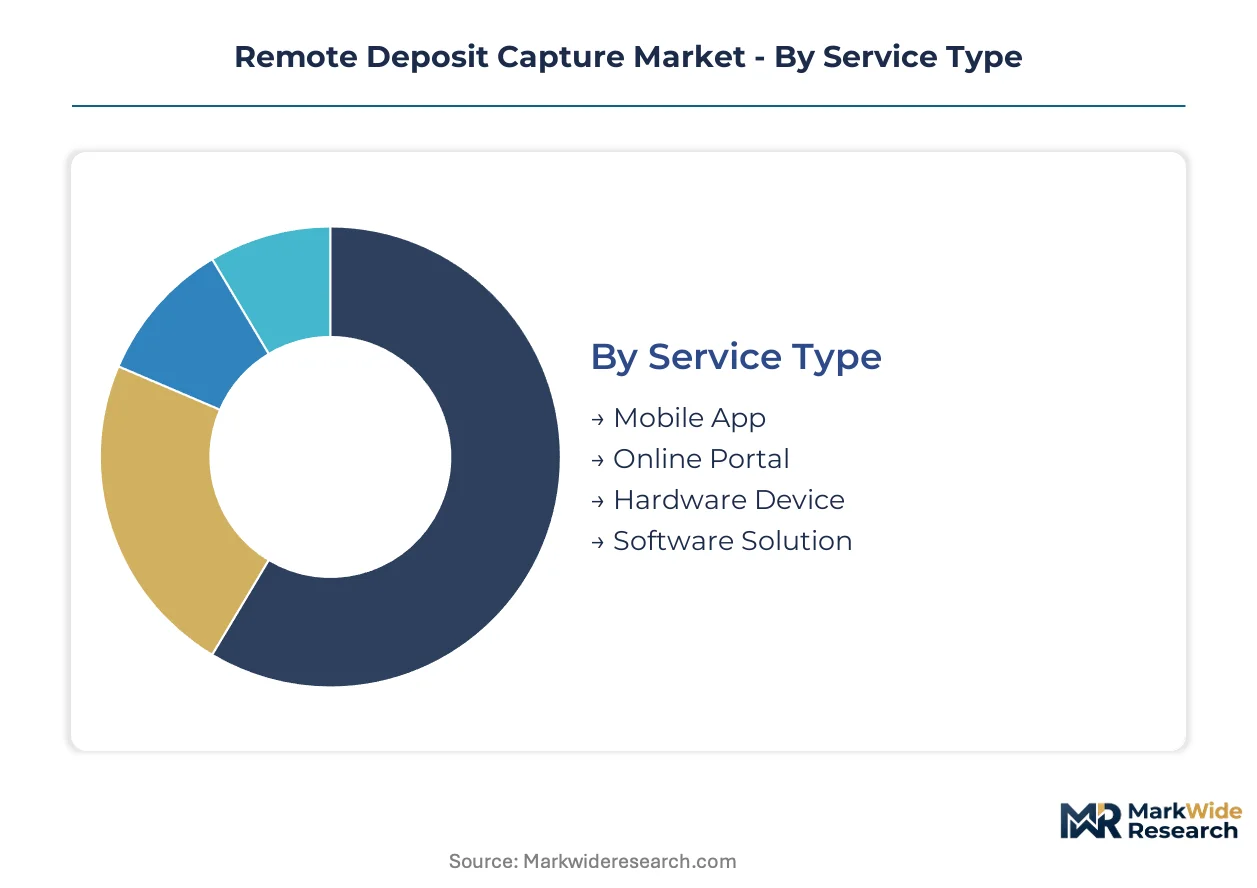
Remote deposit capture segmentation reveals how compliance obligations, infrastructure maturity, and customer scale reshape procurement priorities across financial institutions. Each dimension carries distinct certification burdens that determine vendor selection criteria and implementation timelines.
Service Type:
Check 21 Act substitute check legality mandates ANSI X9 image quality standards across all service categories, though hardware-dependent solutions carry additional FCC equipment certification requirements for scanner devices.
- Software Solution:API-embedded platforms enable direct integration into core banking stacks and fintech onboarding flows without physical infrastructure. Demand concentrates among credit unions and neobanks seeking minimal IT staffing overhead, driven by FFIEC authentication guidance alignment requirements.
- Mobile App:Consumer-grade smartphone deployment leverages computer vision algorithms for MICR-line recognition. United States community banks prioritize this segment for branch rationalization initiatives, constrained by NACHA operating rules compliance friction extending vendor certification timelines.
- Hardware Device:Scanner-based batch processing systems for high-volume commercial treasury operations.
- Online Portal:Browser-accessible deposit interfaces for business clients with moderate transaction volumes.
Leading the category by volume: Software Solution. Growing fastest: Mobile App.
End User:
Procurement authority varies sharply across institutional types, with credit unions and fintechs favoring subscription models while commercial banks negotiate enterprise licensing with retained hardware assets.
- Credit Unions:Member-owned institutions with constrained IT budgets prioritize cloud-native platforms requiring minimal on-premises maintenance. United States regional credit unions drive segment expansion, motivated by digital transformation mandates and limited compliance staffing.
- Commercial Banks:High-volume treasury operations retain scanner-based infrastructure for corporate lockbox services. Demand clusters among middle-market companies with distributed operations, influenced by operational expense versus capital expenditure classification preferences.
- Retail Banks:Branch networks transitioning to digital-first deposit workflows.
- Fintech Companies:Neobank and digital-first platforms embedding capture via API distribution.
Commercial Banks command the largest procurement budgets. Credit Unions are expanding most quickly.
Deployment:
Cloud migration accelerates as institutions shed datacenter maintenance burdens, though hybrid architectures persist where legacy core processor interoperability demands retained on-premises components.
- Cloud-Based:Fully hosted platforms eliminate infrastructure ownership and accelerate feature iteration through vendor-managed updates. United States community banks dominate adoption, propelled by branch rationalization pressures and FedNow interoperability preparation.
- SaaS:Subscription licensing models align vendor incentives with ongoing platform performance. Regional banks fragment procurement across specialized vendors rather than legacy core processors, seeking operational flexibility without long-term capital commitments.
- Hybrid:Split architectures maintaining sensitive data on-premises while leveraging cloud processing.
- On-Premises:Self-managed installations retained by institutions with stringent data residency requirements.
Cloud-Based holds dominant share. SaaS displays the steepest expansion trajectory.
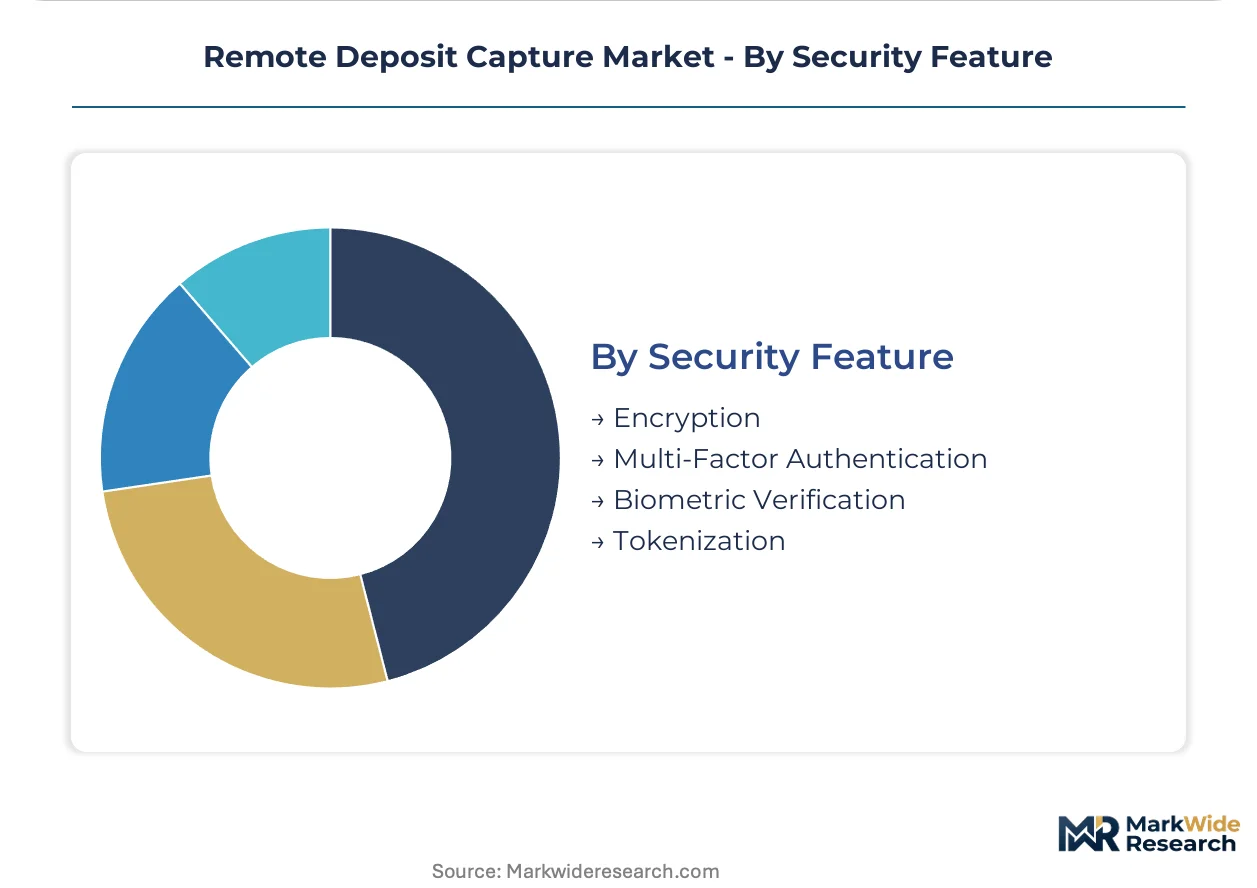
Security Feature:
FFIEC authentication guidance and NACHA operating rules layer multi-factor and encryption mandates onto all deployment modes, with biometric verification emerging as a differentiation vector for consumer-facing applications.
- Multi-Factor Authentication:Federated credential verification combining knowledge, possession, and inherence factors. Financial institutions across the United States implement this as baseline compliance, shaped by federal examination standards and audit trail retention mandates.
- Encryption:Data protection at rest and in transit mandated for all Check 21 Act governed transmissions. Commercial treasury clients with high-value transactions demand specialized key management, extending procurement evaluations beyond standard vendor offerings.
- Biometric Verification:Fingerprint and facial recognition for mobile app authentication.
- Tokenization:Sensitive data substitution reducing breach exposure in cloud environments.
Encryption represents universal deployment. Multi-Factor Authentication is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States financial institutions concentrate procurement authority for remote deposit capture platforms, with legacy check volumes and branch rationalization pressures intersecting most acutely there. Canada and Mexico follow as secondary demand centers shaped by cross-border payment integration and digital banking modernization. European and Asia-Pacific adoption remains comparatively nascent.
United States
Community banks and credit unions drive procurement volume as physical branch networks contract across the Midwest and Southeast. Federal Reserve Board enforcement of Check 21 Act substitute check provisions mandates image retention infrastructure that smaller institutions outsource to specialized vendors. Atlanta and Charlotte banking clusters anchor vendor implementation teams serving regional depository institutions.
Canada
Credit union digitization mandates from provincial regulators accelerate cloud-native platform adoption among member-owned institutions with constrained IT staffing. The country's national payments system operator maintains interoperability standards that shape vendor certification requirements. Toronto's financial services corridor concentrates fintech partnership activity for API-embedded deposit solutions.
Mexico
Neobank licensing expansion by the country's central bank creates distribution channels for mobile-first capture platforms targeting underbanked populations. Regulatory emphasis on financial inclusion prioritizes smartphone-accessible deposit infrastructure over traditional branch expansion. Mexico City fintech clusters anchor implementation partnerships with United States-based platform providers.
United Kingdom
Open banking framework implementation by the Financial Conduct Authority enables API-embedded deposit capture integration into challenger bank onboarding flows. Check imaging infrastructure remains limited compared to North American markets, constraining addressable market scale. London's financial technology district hosts vendor development centers targeting European expansion.
Germany
Savings bank sector consolidation pressures regional institutions to modernize deposit infrastructure through standardized platform procurement. Bundesbank oversight of payment system stability influences vendor selection criteria for core banking interoperability. Frankfurt's banking cluster maintains conservative procurement timelines favoring established vendor relationships over emerging entrants.
Remote Deposit Capture Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue API-embedded distribution and fraud detection adjacencies. Market structure fragments across legacy core processors, specialized capture vendors, and fintech infrastructure providers rather than consolidating around dominant platforms. Three archetypes predominate: vertically integrated banking technology conglomerates, computer vision specialists extending into financial services, and cloud-native deposit infrastructure pure-plays. Competitive dynamics center on strategic partnerships with neobank platforms and geographic expansion into credit union segments.
Within the vertically integrated tier, Fiserv and Jack Henry exemplify archetypes leveraging existing core banking relationships to sustain deposit capture workflow integration. Mitek occupies a specialist position representing computer vision-native entrants competing on mobile image capture accuracy. These three companies anchor the competitive landscape without exhausting its diversity.
| Leading Market Players |
|---|
| Deluxe |
| Jack Henry |
| Fiserv |
| Silicon Valley Bank |
| e-Zest |
| Mitek |
| VSoft |
| U.S. Bank |
| RDM |
| Others |
Cost & Logistics Intelligence
Captive cloud infrastructure ownership by established core banking vendors anchors both supply positioning and pricing power across the remote deposit capture value chain. These vertically integrated technology stacks constrain procurement flexibility for community banks while enabling incumbent providers to bundle deposit capture workflows within broader relationship pricing.
Pricing Analysis
Volume-scale buyers command enterprise licensing discounts while smaller institutions absorb SaaS-tiered premiums. Three-tier pricing structure across premium, standard, and economy levels separates high-volume commercial treasury clients from mid-market regional banks and credit unions with constrained IT budgets. Cost compression in the mobile app segment is intensifying because computer vision algorithm commoditization erodes software differentiation. Credit unions exhibit the highest price sensitivity due to member-owned capital constraints, whereas commercial banks with distributed lockbox operations prioritize operational expense classification over unit cost minimization.
Supply Chain Analysis
API distribution channels handle neobank and fintech platform demand, while direct-to-bank sales teams manage core processor replacement cycles. Hardware component sourcing concentrates in Taiwan for scanner imaging sensors, China for device assembly, and the United States for MICR recognition firmware development. Manufacturing rests on specialized optical character recognition chipsets, cloud hosting infrastructure, and ANSI X9 compliance testing laboratories. Single-source vulnerability in computer vision algorithm licensing creates concentration risk as specialized vendors control mobile capture accuracy IP. Distribution runs through core banking vendor partnerships, independent software vendor marketplaces, and direct fintech infrastructure procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
A vertical-integration race is reshaping competitive positioning as vendors pursue downstream control over neobank distribution channels to secure API-embedded volume growth.
For Market Incumbents: Acquire computer vision algorithm specialists to defend mobile capture accuracy leadership against pure-play entrants. Consolidate certification infrastructure investments to accelerate NACHA operating rules compliance timelines for mid-sized credit union clients. FedNow interoperability preparation represents the critical regulatory shift threatening deposit capture workflow stickiness. For New Entrants and Emerging Players: Neobank platform partnerships offer the most penetrable channel for bypassing legacy core processor relationships. Credit union digital transformation mandates create white-space demand for cloud-native solutions with minimal on-premises maintenance requirements. API-first go-to-market positioning enables rapid embedding into fintech onboarding flows without lengthy bank procurement cycles. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by core banking technology conglomerates seeking mobile capture capabilities. Long-term viability hinges on sustained check digitization demand against real-time payment rail substitution. The signal to watch is FedNow transaction volume acceleration as treasurers evaluate instant settlement alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Architecture | Enables direct embedding into neobank onboarding flows bypassing legacy core relationships. |
| Computer Vision Acquisition | Secures mobile image capture accuracy IP against algorithm commoditization pressures. |
| FedNow Interoperability Investment | Positions vendors for real-time payment network convergence threatening check digitization demand. |
| Credit Union Channel Expansion | Captures member-owned institution procurement fragmented away from legacy processors. |
| Adjacent Fraud Detection Services | Extends image capture infrastructure into signature verification and counterfeit detection revenue. |
Research Approach
SEC filings, NACHA regulatory guidance documents, and Federal Reserve payment system reports formed the secondary backbone for market sizing and competitive positioning assessment. Primary interviews with core banking technology executives, credit union CIOs, fintech platform engineers, and check processing operations directors validated demand assumptions and procurement timeline estimates. Bottom-up triangulation across vendor-reported implementation counts and top-down reconciliation against aggregate clearing volume data anchored value projections.
Historical trendline analysis of remote deposit capture adoption rates informed growth trajectory modeling across the projection horizon. Segmentation dimensions included service type, end-user institution category, deployment architecture, and security feature configuration. CAGRs were derived from fitted growth curves applied to disclosed vendor revenue ranges and inferred from check volume truncation trends. Industry-specific forecast inputs encompassed Check 21 Act enforcement patterns and mobile image quality algorithm advancement rates.
Several conditions sit outside the modeled scope, including potential FedNow real-time payment displacement of check-based settlement and unannounced regulatory revisions to FFIEC authentication guidance. Forecasts reflect assumptions about sustained legacy check volume and branch rationalization continuity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Payment Card Market
Payments
Credit Card Payments Market
Payments
Cryptocurrency Payment Apps Market
Payments
Saudi Arabia POS Terminal Market
Payments
Mobile Payment Security Software Market
Payments
United Arab Emirates Payment Market
Payments
Digital Remittance Service Market
Payments
China Payments Market
Payments
Global Master Card Market
Payments
Portugal POS Terminals Market
Payments
Slovakia POS Terminal Market
Payments
Sweden Mobile Payments Market
Payments
Europe Payment Analytics Software Market
Payments
Slovenia Point of Sale (POS) Terminal Market
Payments
North America POS Terminal Market
Payments
Japan Payment Gateway Market