
 Package Drop Box Market | 2026-2036
Package Drop Box Market Size, Share, and Industry Trends Forecast 2026-2036
Package Drop Box Market Insights
Galvanized steel is consolidating its position as the dominant enclosure material for outdoor cabinet installations, displacing lower-grade aluminum in corrosion-prone climates. Luxer One leverages in-house metal fabrication to control cost curves across its commercial locker portfolio. Parcel Pending anchors its competitive stance through software integration with property management platforms. Yale Lock differentiates via electronic lock expertise ported from residential security into parcel applications.
A package drop box is a secure, weather-resistant receptacle designed for unattended receipt of parcels, typically constructed from 16-gauge steel or reinforced polymer composite with tamper-resistant locking mechanisms and drainage channels. The unit serves commercial mailrooms, multifamily residential lobbies, and curbside residential installations by eliminating failed delivery attempts and reducing package theft incidence. Smart lockers command the dominant revenue position due to electronic access logging and modular scalability for apartment complexes. Wall-mounted units represent the fastest-expanding category as urban density constraints and zero-footprint requirements reshape installation preferences. Traditional drop boxes retain residual demand in rural and cost-sensitive segments where connectivity infrastructure remains limited.
FCC certification governs wireless communication modules embedded in connected locker systems, while ADA compliance mandates accessible reach ranges and tactile interfaces for public-facing installations. Municipal zoning boards in cities such as Austin, Denver, and Seattle are drafting parcel-specific ordinances that dictate placement, dimensions, and aesthetic standards for curbside units. Stakeholders must monitor how fragmented local regulations interact with national product safety standards to determine certification burden and market access timelines.
Market Dynamics
Smart locker integration with building access systems is compressing procurement cycles and forcing hardware vendors to certify against fragmented municipal delivery ordinances across North American cities.
Growth Catalysts
- Multifamily construction pipelines:Apartment developers in the United States are mandating connected parcel infrastructure as standard amenity packages. This specification pull accelerates deployment velocity in new-build residential.
- FCC certification pathways:Streamlined approval processes for wireless communication modules embedded in locker systems reduce time-to-market for connected cabinet manufacturers. Certification consistency lowers regulatory friction for cross-state deployment.
- Refrigerated last-mile infrastructure:Cold-chain e-commerce operators are expanding temperature-controlled drop box networks for grocery and pharmaceutical delivery. This application extension opens adjacent revenue pools beyond ambient parcel handling.
Market Restraints
- Galvanized steel input volatility:Fluctuations in zinc-coated steel pricing squeeze fabrication margins for outdoor cabinet producers. Metal cost exposure concentrates among vendors without backward integration into raw material sourcing.
- Rural connectivity gaps:Limited broadband penetration in non-urban geographies constrains smart locker functionality and locks these segments into traditional mechanical drop box formats. Infrastructure asymmetry fragments addressable market expansion.
- ADA compliance burden:Accessible reach range and tactile interface mandates increase unit engineering complexity and certification cost for public-facing installations. Compliance overhead disproportionately affects low-volume manufacturers.
Strategic Opportunities
- Wall-mounted zero-footprint formats:Urban density constraints in cities like New York and San Francisco are accelerating preference for vertical installation configurations. This product architecture opens retrofit opportunities in legacy building stock with limited lobby space.
- Property management software convergence:API-level integration with tenant platforms creates recurring revenue streams through subscription access models. Software attach rates improve customer lifetime value beyond hardware margins.
- Municipal curbside delivery ordinances:Austin, Denver, and Seattle are drafting parcel-specific placement and aesthetic standards that will mandate standardized cabinet deployment. Early compliance positioning secures preferred vendor status in RFP processes.
Industry Challenges
- Legacy access control integration:Retrofitting smart lockers into existing building security architectures requires custom middleware development and extended commissioning timelines. Project complexity erodes margin on refurbishment contracts.
- Skill scarcity in embedded systems:Shortage of firmware engineers with IoT security expertise constrains product roadmap velocity for connected cabinet vendors. Talent competition with broader smart building sector intensifies compensation pressure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Package Drop Box Market |
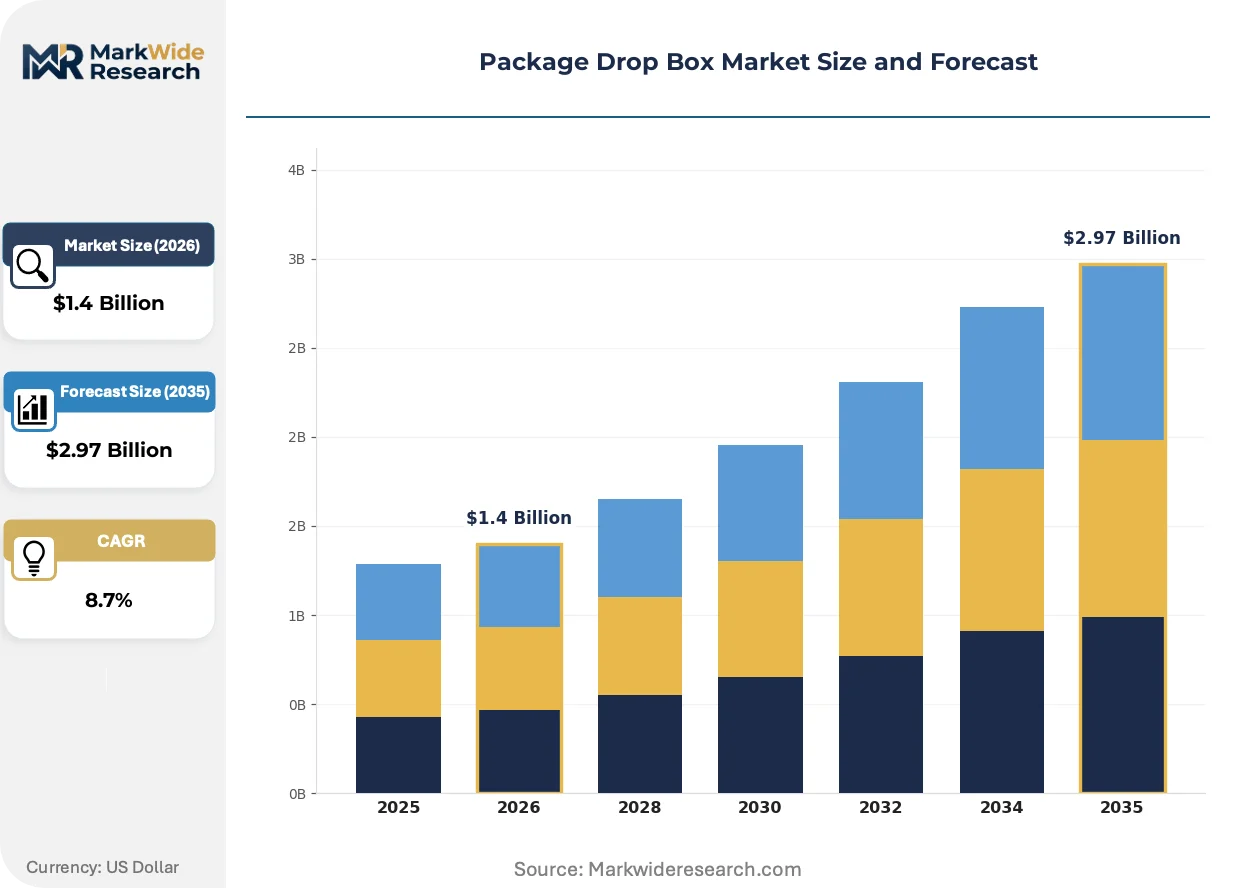
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Lockers, Traditional Drop Boxes, Wall-Mounted Units, Outdoor Cabinets Material: Metal, Plastic, Wood, Composite Installation: On-Site, Off-Site, Residential, Commercial Distribution Channel: Online Retail, Distributors, Direct Sales, Others |
| Companies Covered | Parcel Pending, Package Concierge, Yale Lock, Smart Parcel Box Company, Barska, Eufy, Luxer One, Architectural Mailboxes, iParcelBox, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Package Drop Box Market Trends and Innovations
Electronic access logging and modular scalability are redefining product specifications as buyers prioritize operational visibility over basic theft deterrence.
Biometric authentication modules are converging with parcel locker control systems to eliminate credential sharing and improve chain-of-custody documentation. Multifamily property managers in high-turnover urban markets are piloting fingerprint and facial recognition access at accelerated deployment schedules. This convergence is compressing competitive differentiation around software security architecture rather than mechanical lock durability.
FCC certification requirements for wireless communication modules are tightening electromagnetic interference standards for connected cabinet installations. The regulatory consequence is forcing hardware vendors to redesign antenna configurations and shielding packages. Smart locker manufacturers targeting United States multifamily deployments are absorbing extended pre-market approval timelines and recertification costs for firmware updates.
Buyer procurement patterns are consolidating around integrated building technology platforms rather than standalone parcel hardware. Property management groups are bundling locker access into tenant app ecosystems and unbundling after-sales service from initial capital purchase. This consolidation is most visible in United States institutional real estate portfolios where technology standardization across property clusters overrides site-specific vendor selection.
Package Drop Box Market Segmentation
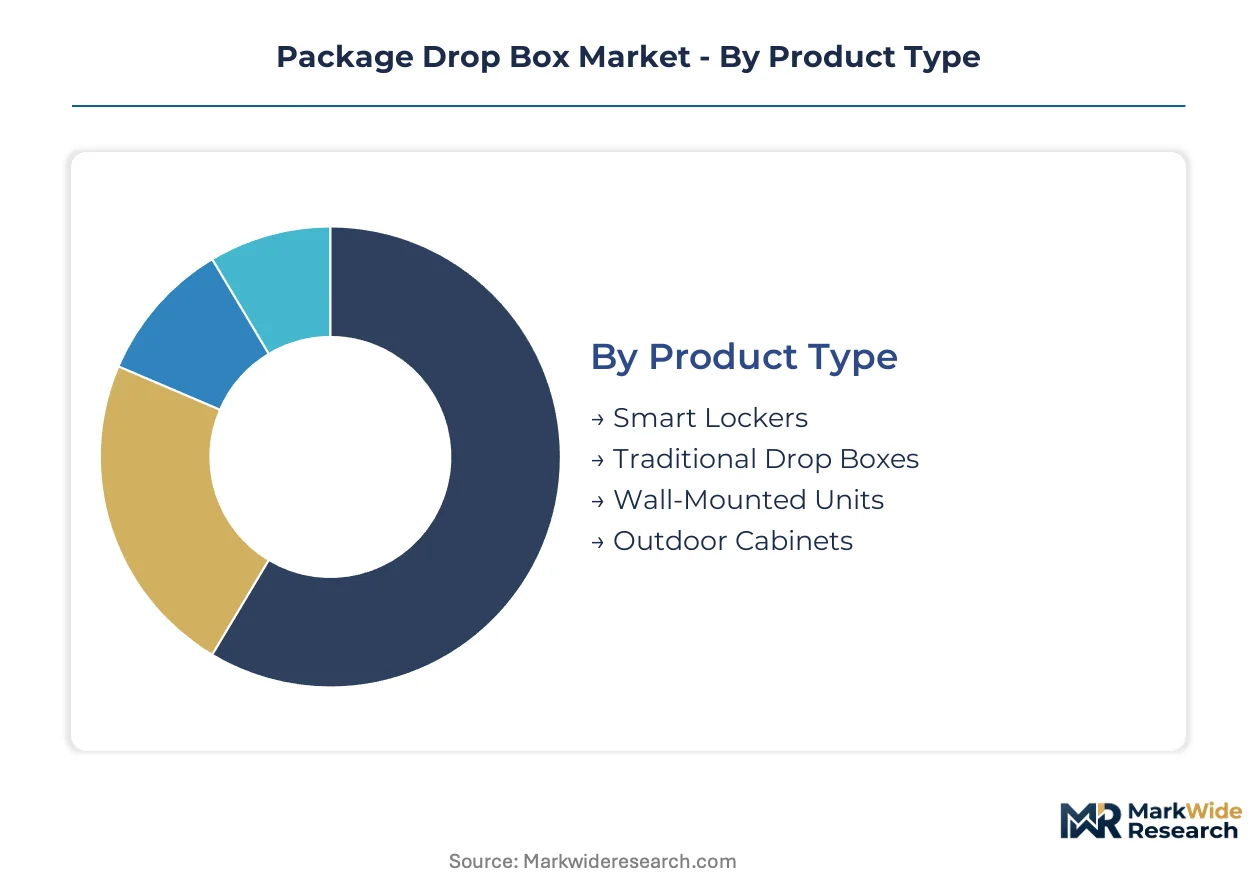
Package drop box segmentation reveals divergent margin profiles across connectivity tiers and installation constraints. Material selection and mounting architecture drive procurement differentiation between new construction and retrofit deployment cycles.
Product Type:
Volume concentrates in connected cabinet formats while premium pricing attaches to modular scalability and electronic access logging capabilities.
- Smart Lockers:Connected systems with electronic access logging, modular compartment configurations, and API integration capabilities. Demand concentrates in United States multifamily residential developments where property management technology budgets mandate connected infrastructure as standard amenity packages.
- Wall-Mounted Units:Vertical installation formats engineered for zero-footprint deployment in space-constrained lobbies and corridors. Deployment is climbing the fastest in urban density clusters like New York and San Francisco where legacy building stock requires retrofit solutions without lobby expansion.
- Traditional Drop Boxes:Mechanical locking receptacles without connectivity modules, constructed from 16-gauge steel or reinforced polymer.
- Outdoor Cabinets:Weather-resistant freestanding enclosures with drainage channels and tamper-resistant anchoring systems.
Today's leader: Smart Lockers. Tomorrow's challenger: Wall-Mounted Units.
Material:
Cost tier stratification separates corrosion-resistant metal specifications from commodity polymer alternatives in outdoor deployment contexts.
- Metal:Galvanized steel and aluminum alloys dominating outdoor cabinet fabrication with zinc-coated corrosion protection. Procurement pulls toward steel in coastal United States markets where salt exposure accelerates enclosure degradation.
- Composite:Reinforced polymer matrices combining structural rigidity with reduced weight for wall-mounted configurations. Specification rates are expanding most quickly in commercial retrofits where installation labor cost sensitivity favors lighter materials.
- Plastic:Injection-molded polymer enclosures for cost-sensitive residential curbside installations.
- Wood:Aesthetic-grade enclosures for high-end residential and hospitality applications requiring architectural integration.
Metal commands current procurement volumes. Composite materials show steepest specification trajectory.
Installation:
Application context dictates procurement channel and commissioning complexity more than hardware specification alone.
- Commercial:Mailroom and lobby deployments requiring ADA-compliant reach ranges and tactile interfaces. Deployment concentrates in United States institutional real estate portfolios where technology standardization mandates connected locker integration with building access systems.
- Residential:Single-family curbside and multifamily lobby installations spanning connected and mechanical formats. Demand fragments across rural connectivity-constrained segments and urban smart locker corridors.
- On-Site:Factory-commissioned systems with embedded firmware and pre-certified wireless modules.
- Off-Site:Modular prefabrication for rapid deployment in temporary or remote locations.
Commercial installations anchor revenue concentration. Residential retrofits present margin expansion opportunity.
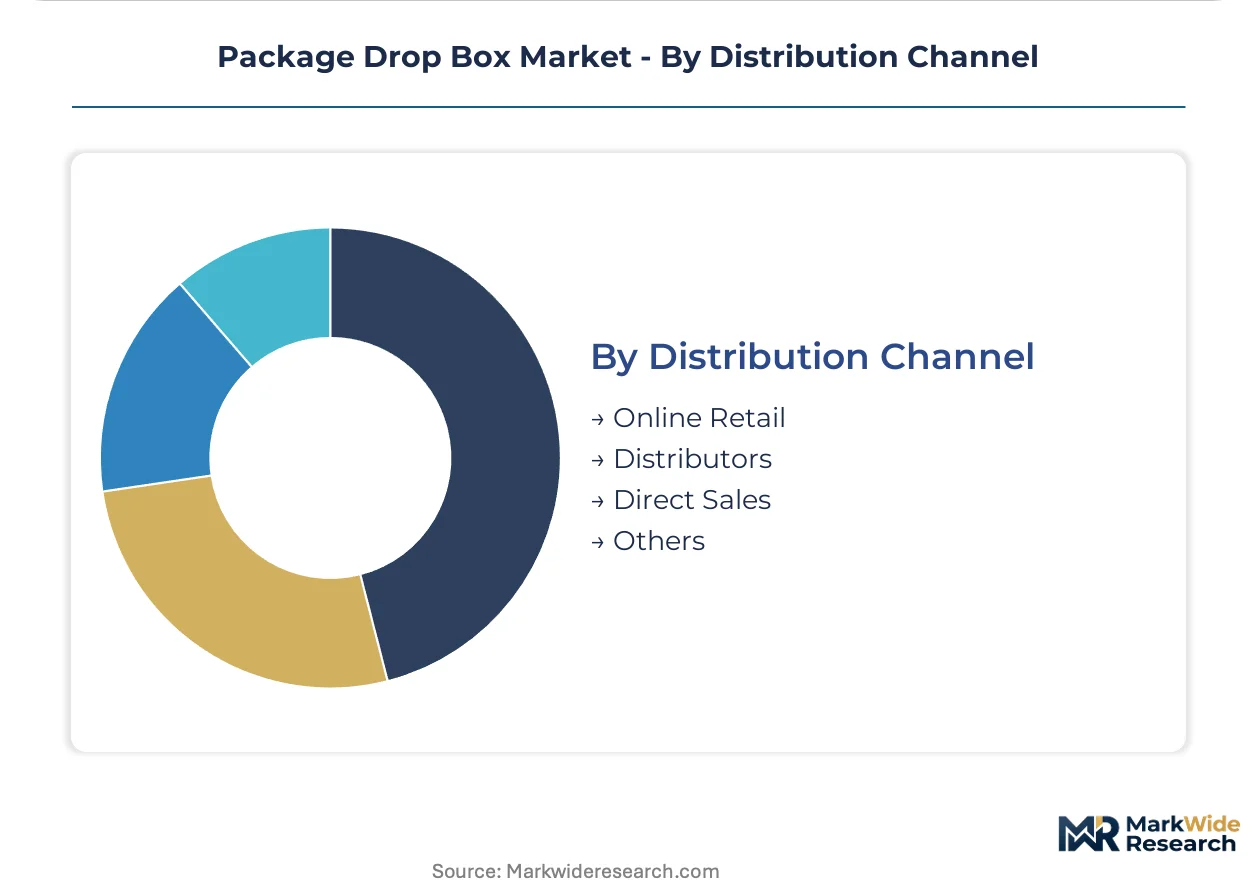
Distribution Channel:
Customer type and order scale determine channel selection between self-service procurement and specification-driven sales engineering.
- Direct Sales:Specification-led engagement with property developers, real estate investment trusts, and institutional facilities managers. Contract values concentrate in United States multifamily construction pipelines where developers mandate connected parcel infrastructure.
- Distributors:Regional inventory and logistics support for contractor and facilities maintenance procurement. Channel share is gaining fastest in commercial retrofit segments requiring rapid replacement and standardized spare parts availability.
- Online Retail:Self-service procurement for residential curbside units and small-scale commercial installations.
- Others:Government procurement portals and cooperative purchasing agreements for municipal curbside deployment programs.
Direct Sales captures premium contract value. Distributors are scaling fastest in aftermarket and retrofit segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States multifamily construction pipelines are mandating connected parcel infrastructure as standard amenity packages, pulling specification demand across urban density corridors. Municipal zoning boards in Austin, Denver, and Seattle are drafting parcel-specific ordinances that dictate placement and aesthetic standards for curbside units.
United States
Apartment developers in New York and San Francisco are accelerating wall-mounted zero-footprint deployments to address legacy building retrofit constraints. FCC certification governs wireless communication modules embedded in connected locker systems, tightening electromagnetic interference standards for cabinet installations. Deployment concentrates in the Pacific Northwest corridor where Seattle's municipal delivery ordinances are reshaping procurement specifications.
Canada
Commercial mailroom operators in Toronto and Vancouver are integrating smart lockers with building access systems to compress procurement cycles. Health Canada guidelines intersect with municipal property standards to regulate public-facing installation accessibility. The Greater Toronto Area anchors connected cabinet demand as institutional real estate portfolios standardize technology across property clusters.
Germany
Industrial fabricators in North Rhine-Westphalia are supplying corrosion-resistant galvanized steel enclosures for outdoor cabinet installations across Central European climates. CE marking requirements govern electronic lock mechanisms and wireless communication modules in connected systems. The Ruhr industrial corridor concentrates metalworking capacity serving cross-border e-commerce logistics infrastructure.
United Kingdom
Property management groups in London are bundling locker access into tenant app ecosystems and unbundling after-sales service from capital purchase. GDPR compliance mandates shape data handling protocols for biometric authentication modules piloted in high-turnover urban markets. The Southeast England corridor drives specification pull as institutional investors mandate connected amenities across residential portfolios.
Japan
Last-mile logistics operators in Tokyo are expanding refrigerated drop box networks for grocery and pharmaceutical delivery applications. METI standards govern IoT security architecture in connected cabinet firmware deployments. The Kanto region concentrates demand as multifamily developers integrate parcel infrastructure with building automation systems.
Package Drop Box Market Competitive Landscape
Global majors compete with regional champions across software integration and metal fabrication capabilities. The vendor base stratifies between vertically integrated fabricators controlling raw material cost curves and software-centric platforms monetizing through API-level property management convergence. Two strategic archetypes dominate: in-house metalworking specialists and cloud-native locker operators. Competitive moves concentrate on backward integration into zinc-coated steel sourcing and municipal ordinance pre-compliance positioning.
Within the integrated fabrication tier, Luxer One and Parcel Pending occupy distinct positioning vectors. Yale Lock sits within the electronic security specialist archetype, leveraging residential lock expertise ported into parcel applications. These three named entities exemplify how competitive differentiation is compressing around software security architecture rather than mechanical durability.
| Leading Market Players |
|---|
| Parcel Pending |
| Package Concierge |
| Yale Lock |
| Smart Parcel Box Company |
| Barska |
| Eufy |
| Luxer One |
| Architectural Mailboxes |
| iParcelBox |
| Others |
Pricing and Supply Chain Analysis
Zinc-coated steel pricing volatility cascades through three distinct hardware tiers, with galvanized sheet metal costs anchoring premium smart locker quotations while composite material alternatives absorb mid-market price compression. Fabrication labor differentials between North American and Asian metalworking centers widen margin spreads for vendors without captive steel sourcing.
Pricing Analysis
Input-cost pass-through from galvanized steel markets shapes tiered pricing architecture across connected cabinet portfolios. Premium-mid-economy pricing differentiation separates FCC-certified smart lockers with API integration from mechanical drop boxes serving rural connectivity gaps. Pricing pressure stems from zinc commodity swings and fabrication margin compression. Commercial multifamily developers show lowest price sensitivity due to amenity bundling, while rural residential curbside buyers concentrate in economy tiers.
Supply Chain Analysis
Direct-to-developer channels handle hyperscale multifamily procurement, while regional distributors serve retrofit replacement demand. Manufacturing concentrates in the United States, China, and Germany, with North American fabricators controlling premium corrosion-resistant enclosure production. Supply chains draw from zinc-coated steel coils, electronic lock mechanisms, and wireless communication modules. Single-source vulnerability concentrates in IoT chipset procurement for connected locker firmware. Distribution runs through property management platform integrations and contractor supply houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FCC certification timelines in the United States lag CE marking efficiency in Germany, creating a regulatory arbitrage window for vendors with dual-approval capabilities. Metal input cost differentials between North American and Asian sourcing corridors further segment viable competitive positioning.
For Market Incumbents: Anticipate municipal ordinance fragmentation by pre-certifying cabinet configurations against Austin, Denver, and Seattle placement standards before RFP publication. Backward integration into galvanized steel sourcing defends fabrication margins against zinc commodity swings. Software security architecture investment counters biometric authentication module suppliers encroaching from residential security markets. For New Entrants and Emerging Players: FCC streamlined approval pathways in the United States open a window for connected locker vendors lacking legacy mechanical lock expertise. Wall-mounted zero-footprint formats in New York and San Francisco legacy buildings present the most penetrable retrofit segment. API-first property management platform integration offers a go-to-market angle bypassing incumbent hardware bundling. For Investors and Strategic Acquirers: Consolidation pressure builds where firmware engineering talent scarcity constrains product roadmap velocity for mid-scale connected cabinet vendors. Long-term viability favors vendors with simultaneous metal fabrication control and software subscription revenue streams. Watch smart locker attach rates in institutional real estate portfolios as the inflection signal separating hardware-commoditized players from platform-integrated survivors.| Strategic Initiative | Industry Significance |
|---|---|
| Municipal Ordinance Pre-Compliance | Early certification against Austin and Seattle standards secures preferred vendor status in municipal RFP processes. |
| Backward Integration into Steel Sourcing | Captive zinc-coated steel supply insulates fabrication margins from commodity volatility in outdoor cabinet production. |
| API-Level Platform Convergence | Property management software integration creates recurring subscription revenue beyond one-time hardware margins. |
| Biometric Authentication Module Development | Fingerprint and facial recognition capabilities differentiate offerings in high-turnover urban multifamily markets. |
| Refrigerated Last-Mile Infrastructure Expansion | Temperature-controlled drop box networks capture adjacent revenue from grocery and pharmaceutical cold-chain operators. |
Research Methodology
Bottom-up multifamily construction modeling reconciled against top-down e-commerce logistics infrastructure tracking forms the analytical core of this study. Primary interviews with property development executives, facilities technology managers, municipal zoning administrators, and smart locker procurement officers combined with secondary validation from FCC certification databases, municipal ordinance filings, and steel commodity exchange data. Triangulation between installer channel feedback and institutional real estate portfolio technology standardization disclosures anchored volume estimates.
Input-output matrices mapped connected cabinet deployment against multifamily construction permits, e-commerce delivery density indices, and municipal delivery ordinance adoption curves across the analysis window. Segmentation dimensions modeled include product connectivity tier, material specification, installation context, and distribution channel structure. CAGRs derived from regression analysis of historical deployment velocity against predictive construction pipeline indicators and refrigerated last-mile infrastructure expansion rates.
Revisions become necessary when municipal ordinance adoption accelerates beyond modeled timelines or galvanized steel input costs diverge from base-case commodity assumptions. Forecasts reflect documented assumptions regarding FCC certification pathway efficiency and property management software convergence velocity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Solutions
FMCG Packaging Market
Packaging Solutions
Interior Packaging Market
Packaging Solutions
Australia Contract Packaging Market
Packaging Solutions
United Kingdom Packaging Market
Packaging Solutions
Temperature Controlled Packaging Solutions Market
Packaging Solutions
Global Noise Control Enclosures Packaging Market
Packaging Solutions
Corrugated Packaging Software Market
Packaging Solutions
Global Lithium Ion Battery Packaging Solutions Market
Packaging Solutions
Advanced Packaging Market
Packaging Solutions
Contract Packaging Market
Packaging Solutions
Global Coding and Marking Solutions Market
Packaging Solutions
North America E-Commerce Packaging Market
Packaging Solutions
North America Secondary Packaging Market
Packaging Solutions
Global E-Commerce Packaging Market
Packaging Solutions
Anti-Counterfeit Clothing Packaging Market
Packaging Solutions
CBD Product Packaging Market