
 Promotional Packaging Market | 2026-2036
Promotional Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Promotional Packaging Market Analytics
Asset-light leasing models for high-volume printing equipment are tilting competitive dynamics toward mid-tier converters that previously faced capital barriers. Mondi Group leverages its integrated paperboard operations to sustain margin control across European promotional campaigns. WestRock anchors North American supply through corrugated display specialization. Smurfit Kappa competes via modular shelf-ready packaging systems that reduce retailer labor costs.
Promotional packaging encompasses engineered containers, wraps, and point-of-sale displays designed to combine product protection with consumer engagement, typically incorporating printable substrates, die-cut structures, and tamper-evident closures for retail environments. Boxes dominate volume across seasonal campaigns and limited-edition product rollouts, while labels capture premium margin pools through NFC and augmented-reality integration. Plastic faces structural pressure from paper alternatives as Food & Beverage buyers enforce recyclability roadmaps.
The EU Packaging and Packaging Waste Regulation and FDA food-contact substance notifications shape material selection and ink chemistry compliance across export-bound production. REACH restrictions on heavy-metal pigments are forcing reformulation of decorative coatings for cosmetics applications. Stakeholders must monitor emerging extended-producer-responsibility fee structures to anticipate cost pass-through requirements.
Market Dynamics
Interactive QR-enabled packaging is virtualizing consumer engagement touchpoints, forcing converters to retool production lines for variable-data printing while brands demand real-time campaign analytics that static substrates cannot deliver.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Mandatory recyclability targets are accelerating paperboard substitution for plastic promotional displays across Food & Beverage supply chains in Germany, France, and the Netherlands.
- NFC-integrated labels:Cosmetics and premium spirits brands are embedding near-field communication chips to unlock augmented-reality experiences and authenticated provenance storytelling.
- Seasonal campaign density:Limited-edition product rollouts in confectionery and alcoholic beverages are compressing design-to-shelf cycles, expanding demand for rapid-changeover die-cutting equipment.
Market Restraints
- Pulp price volatility:Kraft linerboard and coated paperboard input costs swing with Nordic softwood supply disruptions, compressing converter margins on fixed-price annual contracts.
- Specialty ink concentration:Decorative metallic and thermochromic pigment supply concentrates among three German and Japanese chemical suppliers, creating single-source vulnerability for high-end cosmetic packaging.
- REACH heavy-metal restrictions:Cadmium and lead pigment bans are forcing complete reformulation of decorative coatings, extending qualification timelines for export-bound European production.
Strategic Opportunities
- Modular shelf-ready systems:Smurfit Kappa's retail-ready packaging formats that slash in-store labor are penetrating convenience store chains in Poland and Romania where labor costs are rising.
- Extended producer responsibility fee structures:Emerging packaging waste levies in Italy and Spain will reward lightweight, recyclable designs with lower fee tiers, incentivizing material innovation.
- QR-to-DTC channel integration:Connected packaging is enabling brands to bypass retail intermediaries for replenishment and loyalty program enrollment, capturing first-party consumer data.
Industry Challenges
- Variable-data printing talent scarcity:Converters lack operators trained on HP Indigo and Xeikon digital presses capable of short-run personalized campaigns, constraining capacity expansion.
- Multi-substrate bonding certification:FDA food-contact notifications for laminated paper-plastic structures require 18-24 month toxicology reviews, delaying product launches.
- Legacy ERP integration:Web-to-print customer portals for promotional campaign management face friction connecting with decades-old production scheduling systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Promotional Packaging Market |
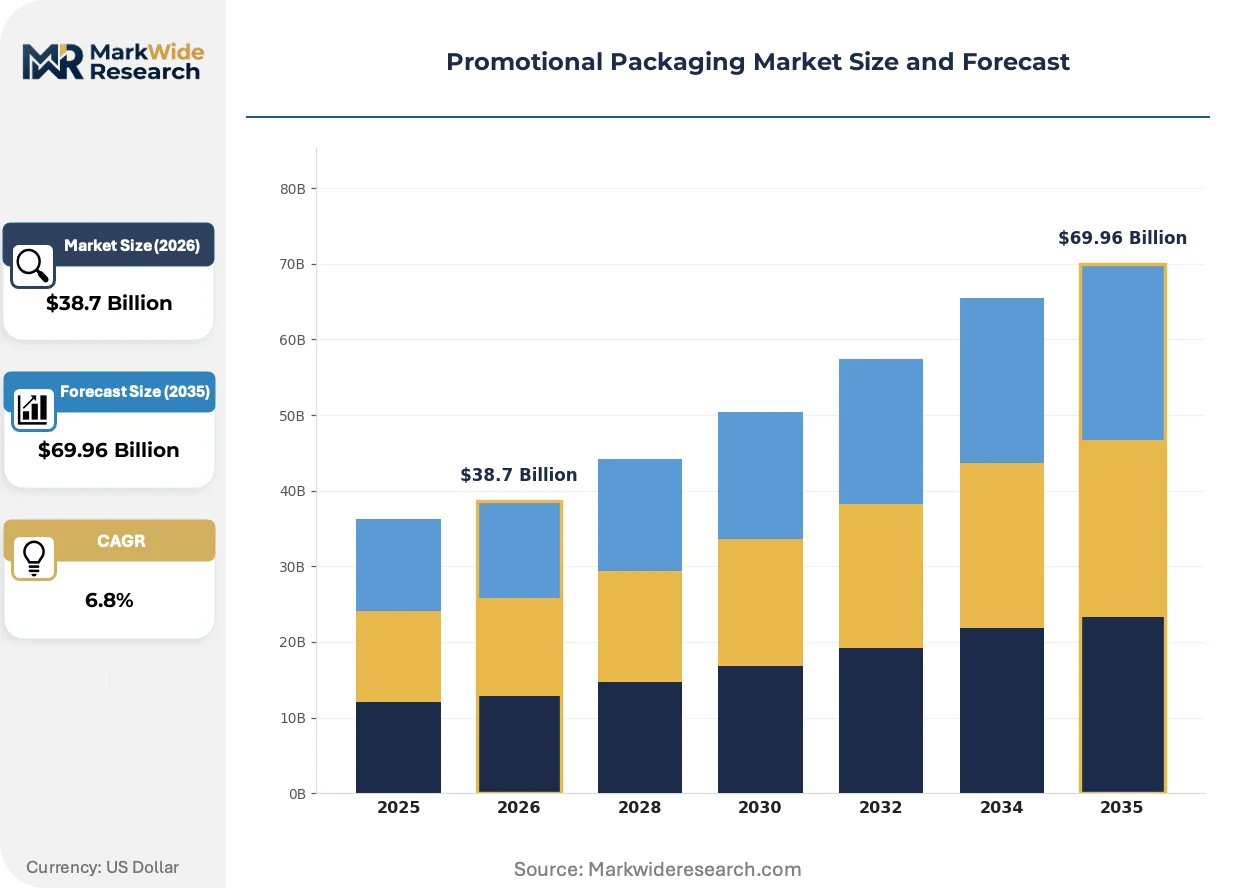
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Boxes, Bags, Labels, Wraps Material: Paper, Plastic, Metal, Glass Functionality: Protection, Display, Branding, Information End User: Food & Beverage, Cosmetics, Electronics, Pharmaceuticals |
| Companies Covered | Amcor Plc, Mondi Group, WestRock, Sealed Air Corporation, International Paper, Smurfit Kappa, DS Smith, Graphic Packaging Holding Company, UFlex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Promotional Packaging Market Evolving Landscape
Augmented-reality packaging experiences are collapsing the distinction between physical shelf presence and digital brand storytelling, requiring converters to master software-layer competencies alongside structural engineering.
Connected packaging is virtualizing consumer touchpoints through scannable triggers embedded in folding cartons and labels. Food & Beverage marketers in Germany and the UK are deploying these capabilities at scale for traceability and gamified loyalty programs. The technology is virtualizing traditional point-of-sale display functions into smartphone-mediated experiences that reduce reliance on bulky physical structures.
REACH restrictions on persistent organic pollutants are tightening compliance windows for decorative coatings used in cosmetics promotional sets. The regulation is forcing pigment suppliers to accelerate bio-based metallic alternatives through ECHA pre-registration protocols. Premium beauty brands exporting to EU member states are responding by consolidating supplier audits and demanding full material disclosure documentation.
Brand procurement teams are consolidating promotional packaging sourcing under outcome-based metrics linking converter payments to retail sell-through performance rather than unit volume. This reconfiguration is displacing traditional price-per-thousand contracting in North American beverage and snack categories. The shift is most visible in Coca-Cola and PepsiCo supply chains where marketing procurement now shares accountability with packaging suppliers for campaign effectiveness.
Promotional Packaging Market Segmentation
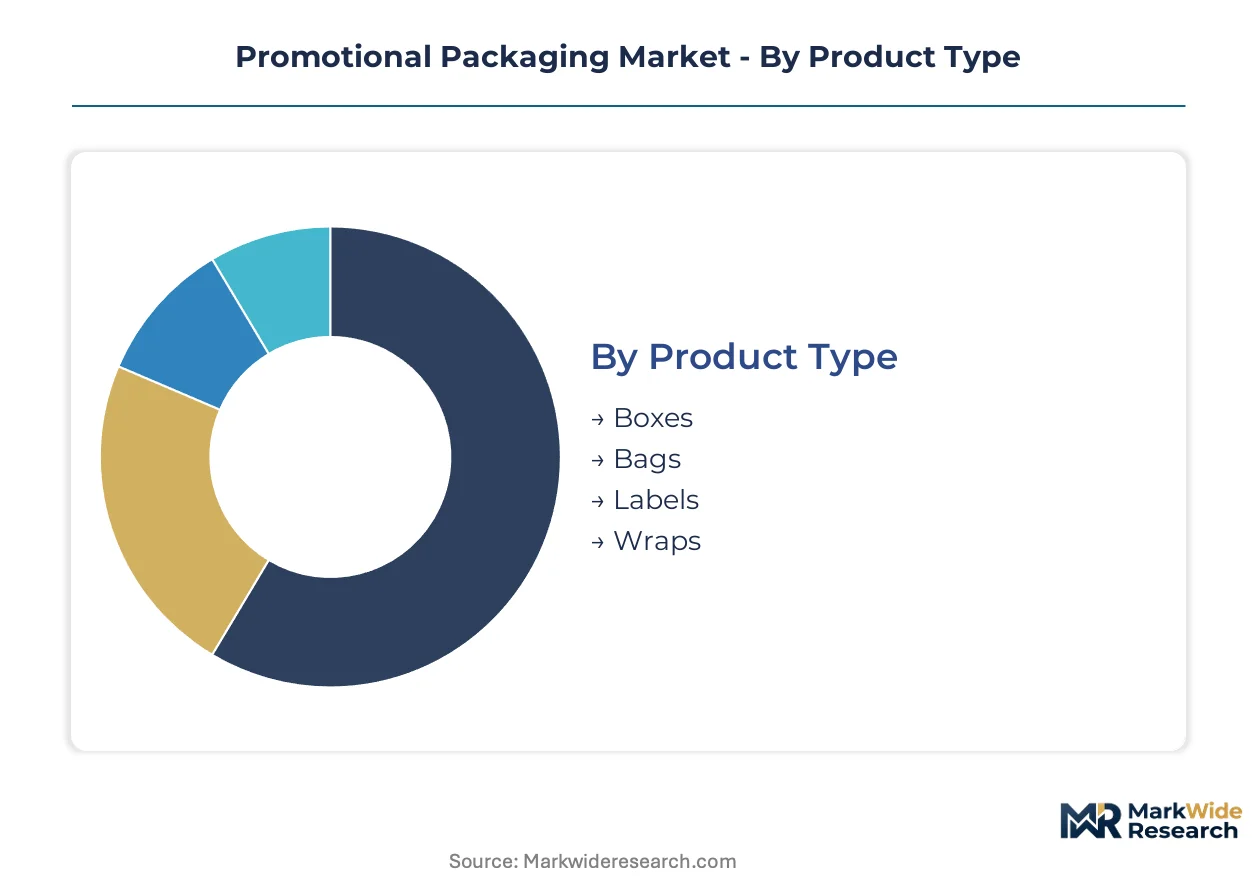
Promotional packaging segmentation reveals how converter capabilities align with brand campaign economics. Material selection and functional requirements determine equipment investment intensity and margin profiles across converter tiers.
Product Type:
After-sales service intensity varies sharply across product categories, with complex die-cut structures demanding sustained technical support while standardized formats minimize ongoing converter engagement.
- Boxes:Corrugated and paperboard folding cartons engineered with die-cut windows, inserts, and shelf-ready perforations dominate seasonal campaign volumes. Demand concentrates in German confectionery and alcoholic beverage rollouts where rapid-changeover production lines compress design-to-shelf cycles.
- Labels:Pressure-sensitive and shrink-sleeve formats incorporating NFC chips and augmented-reality triggers capture premium positioning. Cosmetics and premium spirits brands in France and the UK embed these for authenticated provenance storytelling and gamified loyalty programs.
- Bags:Flexible pouches and stand-up formats with resealable closures serve grab-and-go retail environments.
- Wraps:Printed films and foils for gift sets and promotional bundles emphasize decorative surface graphics.
Boxes hold the largest share; momentum sits with labels as connected packaging expands.
Material:
Cost tier differentiation separates commodity converters from specialty suppliers capable of certifying multi-substrate laminates for food-contact applications.
- Paper:Coated paperboard and kraft linerboard substrates dominate European promotional displays under tightening EU Packaging and Packaging Waste Regulation recyclability mandates. German retailers now require paper-based alternatives for seasonal point-of-sale structures previously executed in plastic.
- Plastic:PET, PP, and bio-based films retain share in moisture-sensitive applications despite structural displacement pressure. Electronics brands in the Netherlands specify thermoformed blisters with recycled content thresholds.
- Metal:Tinplate and aluminum tins serve premium gift sets requiring dimensional rigidity.
- Glass:Decorative bottles and jars for limited-edition cosmetics and spirits releases.
Paper commands volume leadership; plastic faces steepest substitution pressure from regulatory compliance costs.
Functionality:
Application-driven specifications determine whether converters compete on structural engineering, print quality, or software-layer integration competencies.
- Protection:Cushioned inserts, tamper-evident closures, and barrier coatings safeguard product integrity through distribution. Pharmaceutical brands in Germany specify child-resistant and senior-friendly mechanisms for promotional sample packs.
- Display:Shelf-ready and retail-ready formats with pre-creased perforations reduce in-store labor. Convenience chains in Poland and Romania adopt modular systems that slash stocking time.
- Branding:High-impact graphics, metallic embellishments, and tactile coatings differentiate shelf presence.
- Information:QR codes, NFC tags, and variable-data printing enable traceability and direct-to-consumer channel integration.
Display functionality anchors revenue; information capabilities are expanding most quickly as brands virtualize consumer touchpoints.
End User:
Customer type dictates compliance burden and design sophistication, with food-contact and pharmaceutical applications imposing the most stringent qualification requirements.
- Food & Beverage:Folding cartons, corrugated displays, and flexible wraps for confectionery, snacks, and alcoholic beverages generate the highest campaign frequency. German and Dutch brands lead QR-enabled packaging adoption for traceability and replenishment.
- Cosmetics:Rigid boxes, decorative tins, and premium labels with metallic and thermochromic effects face REACH heavy-metal pigment restrictions. ECHA pre-registration protocols are accelerating bio-based metallic alternative development.
- Electronics:Anti-static blisters and printed inserts for device accessories and promotional bundles.
- Pharmaceuticals:Compliance-focused cartons and labels for sample distribution and patient education materials.
Food & Beverage represents the largest addressable base; cosmetics delivers the steepest margin expansion through premium finishing techniques.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented converters in Germany and the Netherlands supply promotional packaging across EU member states, while import-dependent markets in Central and Eastern Europe source premium formats from Western European producers. Trade flows concentrate on paperboard substrates compliant with tightening recyclability mandates.
Germany
Premium retail and sustainability standards converge in German confectionery and alcoholic beverage campaigns. The EU Packaging and Packaging Waste Regulation accelerates paperboard substitution for plastic point-of-sale displays. The Rhine-Main industrial corridor hosts rapid-changeover die-cutting operations serving seasonal rollouts.
United States
Beverage and snack brands deploy outcome-based procurement linking converter payments to retail sell-through performance. FDA food-contact substance notifications govern laminated structures for promotional sample packs. The Southeast manufacturing belt concentrates corrugated display production for mass retail channels.
France
Cosmetics and premium spirits brands embed NFC chips for authenticated provenance storytelling. REACH restrictions on heavy-metal pigments force reformulation of decorative coatings. The Île-de-France region clusters luxury packaging design studios and specialty finishing operations.
United Kingdom
Food and Beverage marketers deploy QR-enabled packaging at scale for traceability and gamified loyalty programs. Extended producer responsibility fee structures incentivize lightweight recyclable designs. The Midlands manufacturing hub supplies folding cartons for rapid-turnaround promotional campaigns.
China
Electronics brands specify thermoformed blisters with recycled content thresholds for promotional bundles. GB standards and SAMR regulations shape material certification for export-bound production. The Yangtze River Delta concentrates flexible packaging converters serving multinational brand supply chains.
Promotional Packaging Market Competitive Landscape
On the supply side, the industry is consolidating around integrated paperboard producers and specialized display converters with distinct equipment profiles. Tier-one players control captive pulp supply and multi-continent converting networks. Tier-two regional specialists compete on rapid-changeover digital printing and short-run personalization. Dominant competitive moves include backward integration into paperboard manufacturing and strategic partnerships with brand marketing agencies for connected packaging deployment.
Within the integrated paperboard tier, Mondi Group and WestRock exemplify supply chain control strategies. Mondi leverages European pulp operations to sustain margin stability across promotional campaign cycles. WestRock anchors North American corrugated display supply through specialized structural engineering capabilities. Smurfit Kappa occupies a position in modular retail-ready systems that reduce in-store labor costs for convenience chains.
| Leading Market Players |
|---|
| Amcor Plc |
| Mondi Group |
| WestRock |
| Sealed Air Corporation |
| International Paper |
| Smurfit Kappa |
| DS Smith |
| Graphic Packaging Holding Company |
| UFlex |
| Others |
Value Network & Pricing Analysis
Nordic softwood pulp concentration in Sweden and Finland anchors margin volatility for European converters, compressing spreads on fixed-price annual contracts when input costs spike. Brand procurement teams exploit this concentration by consolidating volume commitments in exchange for price stability clauses.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that dominate promotional packaging procurement. Three-tier pricing structure across premium, standard, and economy levels separates NFC-integrated labels with augmented-reality capabilities from basic corrugated displays and commodity folding cartons. Cost compression in standard-tier paperboard is intensifying because kraft linerboard input costs swing with Nordic supply disruptions. Mass retail chains exhibit highest price sensitivity, while premium cosmetics brands accept elevated pricing for REACH-compliant decorative coatings with full material disclosure.
Supply Chain Analysis
Tariff exposure between China and the EU dominates supply chain risk calculations for electronics brands sourcing thermoformed blisters. Production gravity centers on Germany, the Netherlands, and Poland for paperboard substrates compliant with EU Packaging and Packaging Waste Regulation recyclability mandates. Raw material dependencies rest on coated paperboard, metallic pigments from German and Japanese chemical suppliers, and NFC chip modules. Single-source vulnerability concentrates in specialty thermochromic pigment supply. Distribution runs through converter-direct relationships with brand procurement teams, bypassing traditional distribution intermediaries for campaign-specific production runs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Promotional packaging operates on a cyclical recovery trajectory as seasonal campaign density rebounds post-pandemic inventory destocking. Limited-edition confectionery and alcoholic beverage rollouts drive this cyclicality through compressed design-to-shelf cycles.
For Market Incumbents: Insulate margin pools by securing captive pulp supply through backward integration into Nordic softwood operations or long-term offtake agreements with Scandinavian producers. Accelerate certification investment for FDA food-contact substance notifications to capture pharmaceutical sample pack contracts before qualification timelines extend further. Variable-data printing talent scarcity represents the most pressing threat to capacity expansion.
For New Entrants and Emerging Players: Modular shelf-ready packaging systems for convenience store chains in Poland and Romania represent the most penetrable entry point, as labor cost inflation drives retailer demand for reduced stocking time. Rapid-changeover digital printing capabilities for short-run personalized campaigns offer a second white-space target where incumbent capacity constraints create service gaps. A go-to-market angle anchored in web-to-print customer portals with legacy ERP integration expertise addresses a critical pain point.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mid-tier converters that installed HP Indigo and Xeikon digital presses during the 2018-2022 capacity expansion wave. These assets offer long-term viability through the projection horizon as connected packaging virtualizes consumer touchpoints and demands software-layer competencies alongside structural engineering. The signal to watch is extended producer responsibility fee structure implementation in Italy and Spain, which will reward lightweight recyclable designs with lower tier assignments.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulp Supply | Nordic softwood captive supply insulates margin stability against kraft linerboard price volatility. |
| NFC-Integrated Label Capacity Expansion | Cosmetics and premium spirits brands in France embed chips for authenticated provenance storytelling. |
| Modular Retail-Ready System Deployment | Convenience chains in Poland and Romania adopt formats that slash in-store labor costs. |
| Variable-Data Printing Talent Acquisition | HP Indigo and Xeikon operator scarcity constrains short-run personalized campaign capacity. |
| REACH-Compliant Coating Reformulation | Cadmium and lead pigment bans force bio-based metallic alternative development through ECHA protocols. |
Research Methodology
Initial hypotheses were tested against primary input from brand procurement managers, converter operations directors, specialty ink chemical suppliers, and retail category buyers and refined through secondary validation. Primary fieldwork combined structured interviews with folding carton and corrugated display producers across the Rhine-Main industrial corridor and Île-de-France region. Secondary sources included EU Packaging and Packaging Waste Regulation implementation documents, ECHA pre-registration protocols for bio-based pigments, FDA food-contact substance notification databases, and customs records for paperboard substrate trade flows. Bottom-up capacity assessments and top-down brand campaign spend estimates were triangulated to anchor volume projections.
Demand-supply-balance framing shaped the analytical framework across the analysis window, with segmentation modeled across product type, material substrate, functional requirement, and end-use industry. Patient-level treatment analogies informed promotional packaging campaign frequency modeling for Food and Beverage versus Cosmetics verticals. CAGRs were derived from segment-level volume build-ups validated against converter capacity expansion announcements and equipment installation records.
Macroeconomic conditions sit as an overlay; deviation in pulp commodity prices, EU regulatory enforcement intensity, or consumer discretionary spending on premium limited-edition products would shift the trajectory. Forecasts reflect assumptions about seasonal campaign density continuity and REACH heavy-metal restriction implementation timelines. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Solutions
Global Shelf Ready Packaging Market
Packaging Solutions
Corrugated Packaging Software Market
Packaging Solutions
Packaging Solutions Market
Packaging Solutions
Temperature Controlled Packaging Solutions Market
Packaging Solutions
Halal Packaging Market
Packaging Solutions
Panel Level Packaging Market
Packaging Solutions
India E-Commerce Packaging Market
Packaging Solutions
Topical Dispenser Market
Packaging Solutions
Contract Packaging and Fulfillment Service Market
Packaging Solutions
Interior Packaging Market
Packaging Solutions
Europe Contract Packaging Market
Packaging Solutions
Vacuum Skin Packaging Market
Packaging Solutions
Void Fill Packaging Systems Market
Packaging Solutions
Saudi Arabia Packaging Market
Packaging Solutions
CBD Product Packaging Market
Packaging Solutions
Secondary Packaging Market