
 Extraction Kits Market | 2026-2036
Extraction Kits Market Size, Share, and Industry Trends Forecast 2026-2036
Extraction Kits Market Analysis
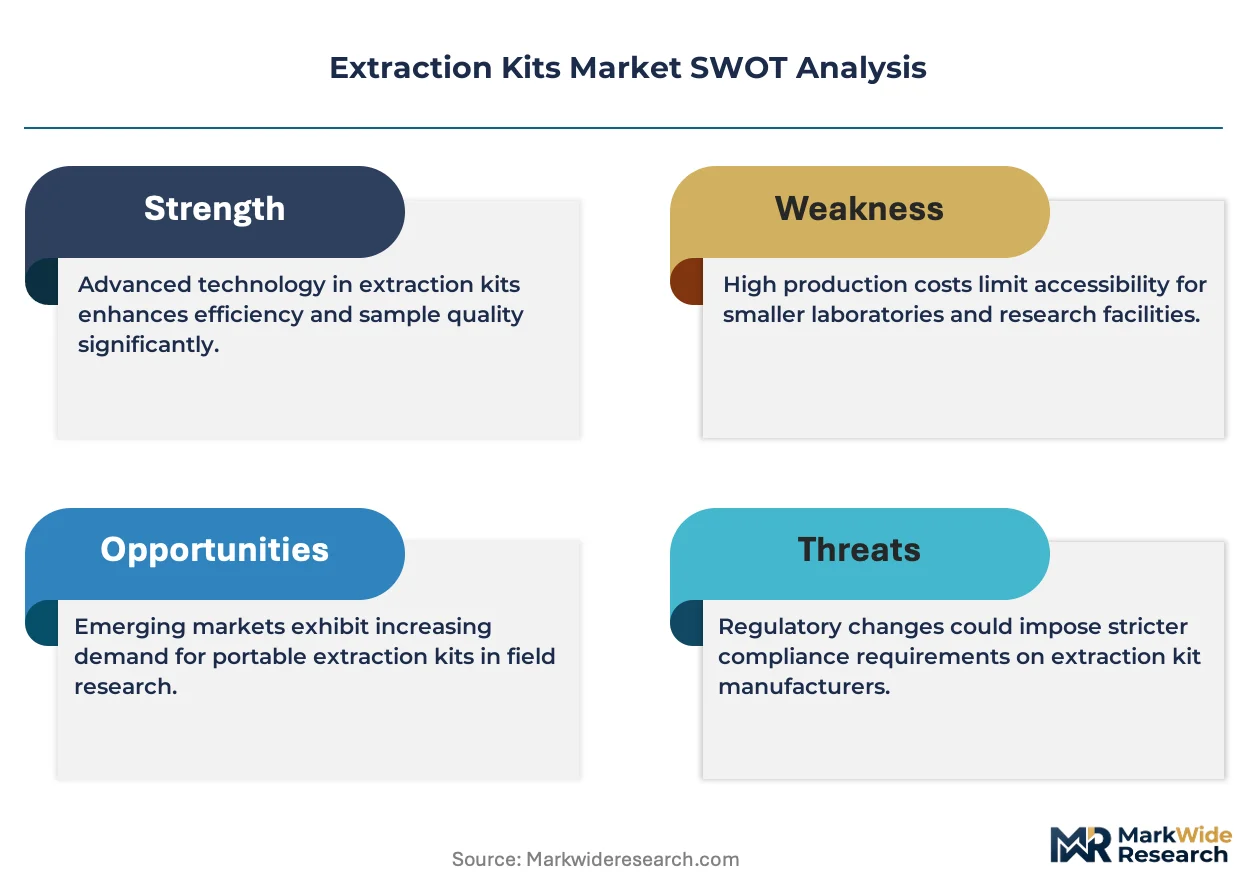
The EU In Vitro Diagnostic Regulation is realigning compliance burdens across sample preparation workflows, forcing kit manufacturers to rebuild technical documentation and performance validation dossiers. Thermo Fisher Scientific leverages its regulatory affairs infrastructure to sustain CE-IVD transitions across European markets. Qiagen anchors its position through dedicated quality management systems that navigate notified body scrutiny. Roche Diagnostics differentiates via integrated instrument-and-consumable platforms that compress validation timelines for clinical laboratories.
Extraction kits are consumable systems—typically silica membrane spin columns, magnetic bead suspensions, or reagent cocktails—engineered to isolate nucleic acids or proteins from biological matrices with defined purity thresholds and yield coefficients. Their primary commercial purpose is to standardize upstream sample preparation for downstream PCR, sequencing, or immunoassay workflows. DNA extraction kits occupy the largest revenue pool given their ubiquity in clinical diagnostics and forensic casework, while RNA extraction kits represent the fastest-expanding category as transcriptomic research and infectious disease surveillance intensify. Pharmaceutical applications command premium pricing due to stringent GMP documentation requirements and lot-to-lot consistency mandates.
The FDA oversees extraction kit performance claims through its IVD regulatory pathway, while the EU AI Act and MDR frameworks increasingly intersect with automated extraction platforms that embed algorithmic sample handling. ISO 13485 certification has become a baseline market access requirement rather than a competitive differentiator. Stakeholders must monitor how harmonization between FDA and EMA guidance on nucleic acid extraction validation evolves, as divergence would fragment product development roadmaps and inflate compliance costs.
Market Dynamics
Hospital laboratory consolidation across the United States is compressing vendor rosters and forcing extraction kit manufacturers to deliver instrument-consumable bundles rather than standalone reagents. This procurement rationalization is reshaping contract structures, technical support obligations, and pricing architectures throughout the clinical diagnostics supply chain.
Growth Catalysts
- EU MDR compliance deadlines:European clinical laboratories face mandatory revalidation of sample preparation workflows, creating replacement demand for certified extraction kits with complete technical documentation.
- Transcriptomic research expansion:Academic medical centers and infectious disease surveillance programs are scaling RNA extraction capacity to support metagenomic sequencing and pathogen detection protocols.
- Silica membrane automation:Magnetic bead chemistry improvements are displacing spin-column workflows in high-throughput settings, reducing hands-on time and technician variability.
Market Restraints
- Purified silica supply concentration:Specialty chemical production for membrane matrices clusters in East Asian manufacturing hubs, exposing kit assemblers to freight cost volatility and customs processing delays.
- IVD regulatory divergence:Misalignment between FDA 510(k) pathways and EU MDR performance documentation requirements forces manufacturers to maintain parallel validation studies, inflating development overhead.
- Lyophilized reagent substitution:Room-temperature stable master mix formats are reducing cold-chain dependency for some PCR workflows, compressing demand for certain nucleic acid extraction adjuncts.
Strategic Opportunities
- Point-of-care molecular diagnostics:CLIA-waived extraction platforms for decentralized testing in urgent care and pharmacy settings remain underdeveloped relative to centralized laboratory automation.
- Pharmaceutical GMP documentation services:Cell and gene therapy manufacturers require extraction kits with extensive lot-to-lot characterization and audit trails, commanding premium positioning.
- AI-enabled sample handling:Convergence of automated liquid handling with machine vision quality control is creating integrated platforms that reduce failed extraction rates and rework costs.
Industry Challenges
- ISO 13485 auditor scarcity:Notified body capacity constraints in Europe are extending certification timelines for new kit introductions, delaying revenue recognition and freezing product development schedules.
- Legacy LIMS integration:Automated extraction instruments must communicate with heterogeneous laboratory information management systems, requiring costly custom middleware development for each hospital network deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Extraction Kits Market |
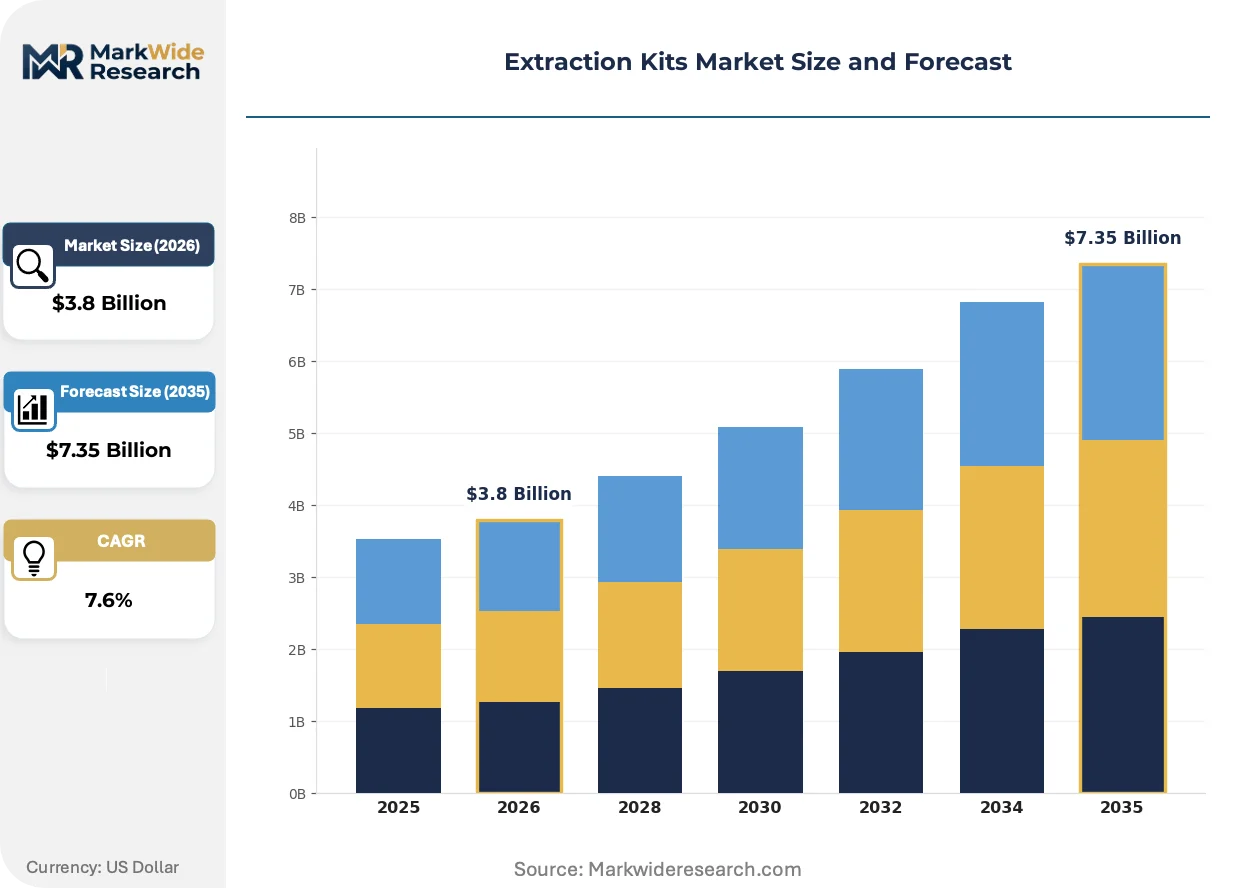
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.35 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DNA Extraction Kits, RNA Extraction Kits, Protein Extraction Kits, Nucleic Acid Extraction Kits Application: Forensic Analysis, Clinical Diagnostics, Research Laboratories, Pharmaceutical Applications End User: Hospitals, Academic Institutions, Biotechnology Companies, Contract Research Organizations Distribution Channel: Online Stores, Distributors, Retail Pharmacies, Direct Sales |
| Companies Covered | Thermo Fisher Scientific, Qiagen, Roche Diagnostics, Promega Corporation, Bio-Rad Laboratories, Agilent Technologies, Merck KGaA, Takara Bio, PerkinElmer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Extraction Kits Market Emerging Trajectories
Automation architectures are converging with regulatory data requirements, compressing the gap between sample preparation execution and compliance documentation. This integration is forcing kit manufacturers to embed traceability features directly into consumable design rather than treating documentation as an aftermarket obligation.
Cartridge-based extraction systems are unifying reagent storage, waste containment, and nucleic acid elution into single-use consumables compatible with walk-away automation. Reference laboratories in the United States are adopting these closed-system formats to reduce cross-contamination risk and satisfy CAP inspection criteria. The structural consequence is unifying instrument and consumable procurement decisions, locking laboratories into vendor ecosystems and raising switching costs for alternative chemistry platforms.
The EU AI Act intersects with automated extraction platforms that embed algorithmic sample handling and failure detection. Manufacturers must now document training data provenance and performance drift monitoring for software components previously treated as mechanical control systems. Clinical diagnostic laboratories in Germany and France are prioritizing CE-IVD platforms with explicit AI Act conformity assessments to preempt notified body scrutiny during MDR audits.
Consolidated procurement by multi-hospital health systems is compressing vendor evaluation cycles and unbundling after-sales service from consumable pricing. IDNs in Texas and California are negotiating multi-year extraction kit contracts with performance guarantees tied to turnaround time metrics rather than unit cost alone. This behavioral shift is visible most acutely in the United States, where laboratory standardization initiatives across Catholic health networks and for-profit systems are aggregating purchasing power previously fragmented across individual hospital laboratories.
Extraction Kits Market Segmentation
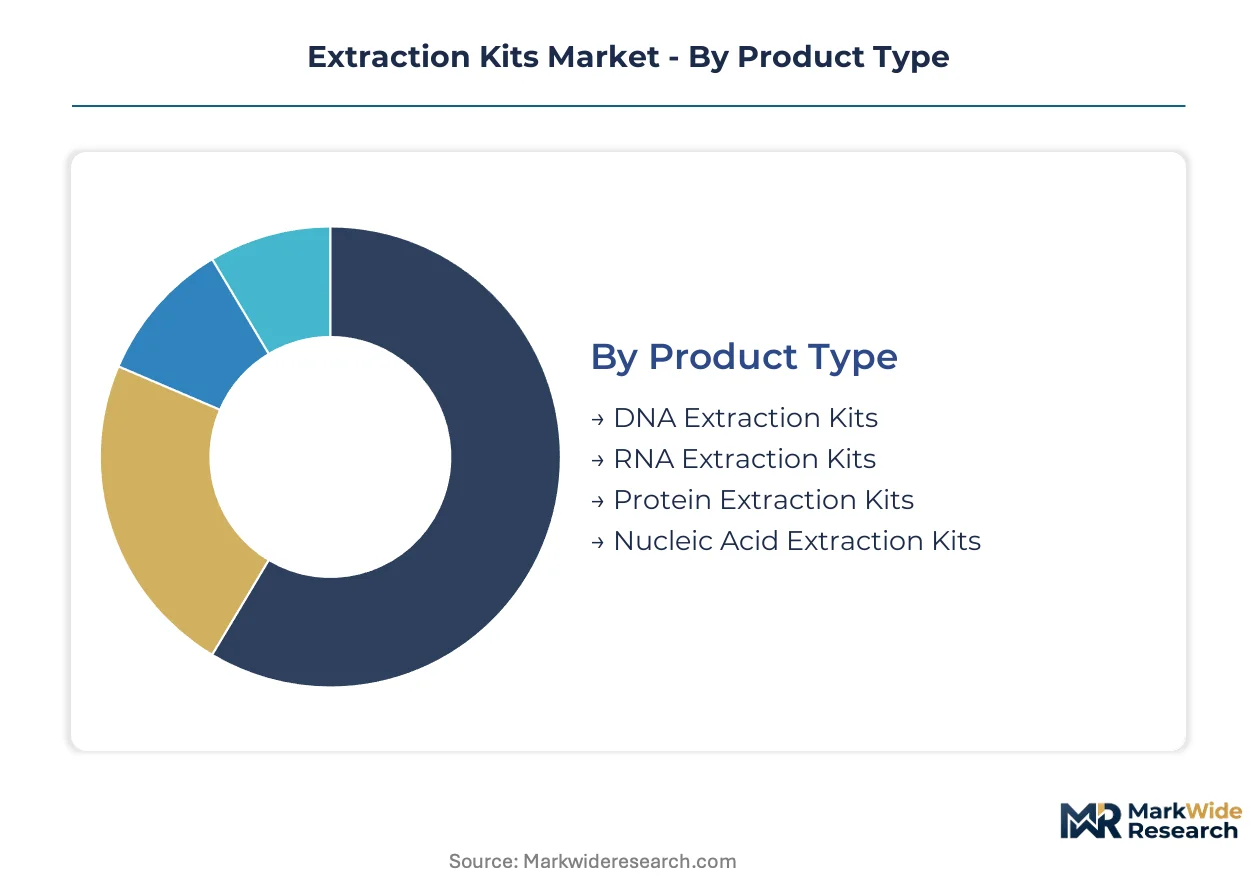
Extraction kit purchasing decisions cascade differently across product architectures, end-use environments, and procurement channels. Segment boundaries blur where clinical laboratories demand instrument-integrated consumables while research settings retain flexibility for standalone reagent selection.
Product Type:
Standalone spin-column formats persist in low-throughput settings while magnetic bead chemistries embed into automated liquid handling platforms.
- DNA Extraction Kits:Silica membrane and magnetic bead formats dominate clinical diagnostics and forensic casework with defined yield coefficients. Hospital laboratories in the United States standardize on these kits for infectious disease PCR workflows, though silica supply concentration in East Asian manufacturing hubs creates procurement risk.
- RNA Extraction Kits:Transcriptomic research and pathogen surveillance programs drive demand for RNase-free reagent systems with stabilized column matrices. Academic medical centers in Germany and France are scaling capacity to support metagenomic sequencing protocols amid EU MDR revalidation requirements.
- Protein Extraction Kits:Cell lysis buffers and detergent-based reagent cocktails serve proteomics and bioprocessing applications with solubility optimization for membrane-bound targets.
- Nucleic Acid Extraction Kits:Universal chemistries accommodating both DNA and RNA isolation from varied biological matrices appeal to reference laboratories seeking workflow consolidation.
Volume placements concentrate in DNA extraction formats; the faster expansion belongs to RNA extraction kits.
Application:
Regulatory stringency stratifies sharply between research-use-only environments and clinical diagnostic settings requiring IVD certification.
- Clinical Diagnostics:CE-IVD and FDA-cleared kits with complete technical documentation serve hospital laboratories facing CAP inspection criteria and EU MDR compliance deadlines. Multi-hospital health systems in Texas and California negotiate multi-year contracts with turnaround time guarantees.
- Pharmaceutical Applications:GMP-compliant kits with extensive lot-to-lot characterization and audit trails command premium positioning from cell and gene therapy manufacturers requiring regulatory submission support.
- Research Laboratories:Academic medical centers prioritize flexibility and cost efficiency over certification, adopting spin-column workflows for exploratory transcriptomic and genomic studies.
- Forensic Analysis:Casework laboratories demand high-purity DNA recovery from degraded samples with chain-of-custody documentation for criminal justice system admissibility.
Contract values peak in pharmaceutical applications; research laboratories generate the highest kit consumption volumes.
End User:
Procurement sophistication varies from centralized IDN purchasing offices to principal-investigator-driven academic ordering.
- Hospitals:Consolidated laboratory networks aggregate purchasing power previously fragmented across individual facilities, compressing vendor rosters toward instrument-consumable bundles.
- Biotechnology Companies:Cell and gene therapy developers require extraction kits with GMP documentation and regulatory submission packages, accepting premium pricing for reduced compliance risk.
- Academic Institutions:Grant-funded research programs balance reagent cost against publication-grade reproducibility, often standardizing on established column chemistries.
- Contract Research Organizations:Multi-site service providers demand kit consistency across global laboratory networks to ensure client data comparability.
Biotechnology companies drive margin expansion; hospitals anchor absolute volume demand.
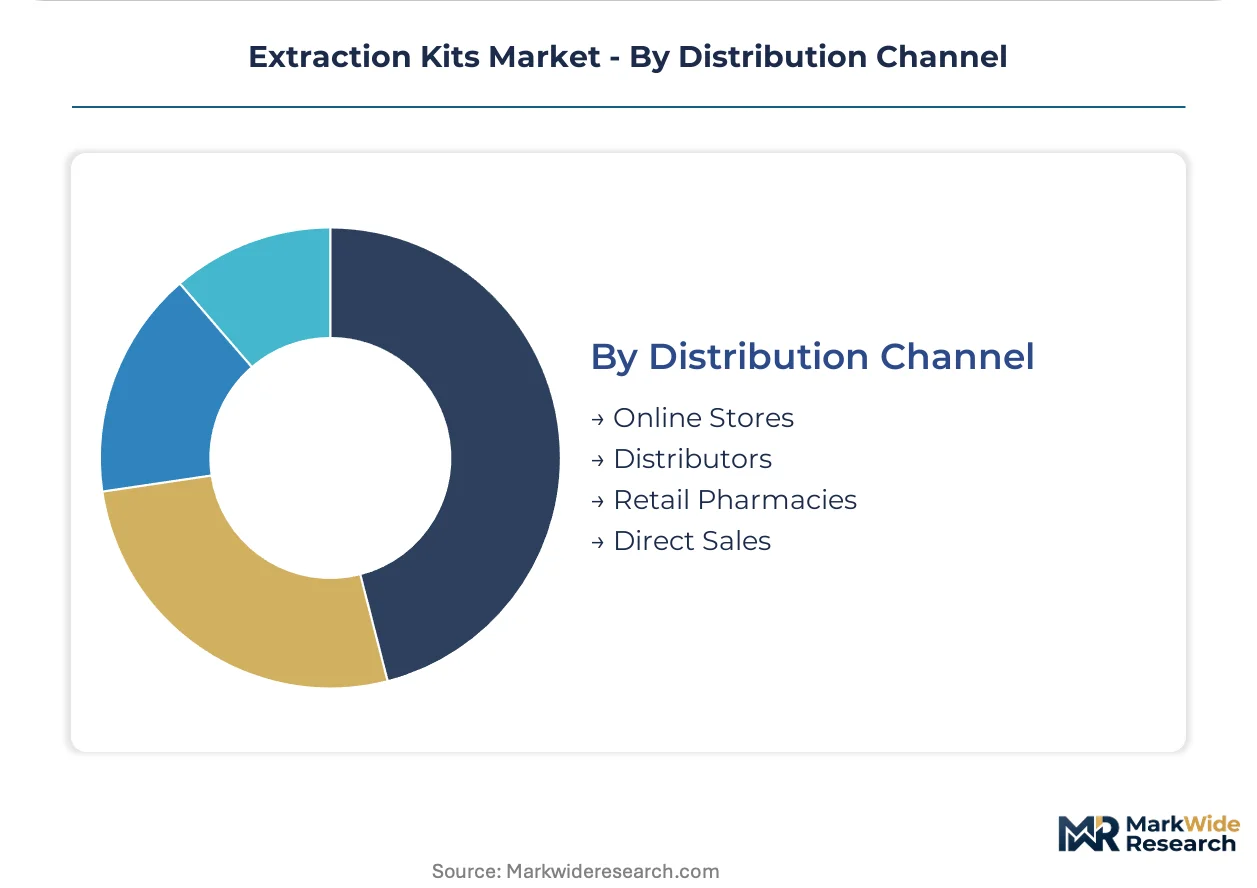
Distribution Channel:
Channel selection reflects order scale, technical support requirements, and integration complexity with existing procurement systems.
- Distributors:Regional life science distributors with field application scientists dominate mid-size hospital and academic accounts requiring workflow optimization support.
- Direct Sales:Manufacturers deploy specialized diagnostic account teams for multi-hospital IDN negotiations and pharmaceutical GMP service contracts with multi-year terms.
- Online Stores:E-commerce platforms capture research laboratory spot purchases and small-volume academic orders with rapid fulfillment expectations.
- Retail Pharmacies:Pharmacy chains with CLIA-waived testing capabilities represent an emerging channel for point-of-care molecular diagnostic consumables.
Distributors capture the broadest account coverage; direct sales secure the largest contract values.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing of silica membranes and magnetic bead chemistries clusters in East Asian chemical hubs, while consumption concentrates in North American and European clinical laboratory networks. This geographic split exposes kit assemblers to freight volatility and customs delays. Procurement rationalization in multi-hospital health systems is reshaping regional demand patterns.
United States
Hospital laboratory consolidation and reference lab expansion drive standardized kit procurement at scale. FDA IVD pathway requirements govern performance claims for clinical diagnostic workflows. Texas and California IDNs negotiate multi-year extraction kit contracts with turnaround time guarantees rather than unit-cost pricing.
Germany
Academic medical centers in Munich and Heidelberg scale RNA extraction capacity for metagenomic sequencing protocols. EU MDR compliance deadlines force revalidation of sample preparation workflows, creating replacement demand for certified kits with complete technical documentation. Berlin-based notified bodies extend certification timelines amid auditor scarcity.
China
Specialty chemical production for membrane matrices concentrates in coastal manufacturing zones serving global kit assemblers. NMPA regulatory frameworks increasingly align with international IVD standards for nucleic acid extraction platforms. Shanghai and Suzhou chemical parks supply purified silica to European and North American consumable manufacturers.
France
Paris and Lyon clinical laboratories prioritize CE-IVD platforms with explicit EU AI Act conformity assessments for automated extraction systems. ANSM scrutiny intersects with MDR audits for algorithmic sample handling components. French infectious disease surveillance programs expand transcriptomic research capacity.
Japan
PMDA oversight of IVD extraction kits maintains stringent performance documentation requirements for clinical diagnostic entry. Tokyo and Osaka pharmaceutical manufacturers demand GMP-compliant kits with extensive lot-to-lot characterization for cell and gene therapy applications. METI industrial policy supports domestic reagent chemistry development.
Extraction Kits Market Vendor Landscape
The competitive structure tilts toward diversified life science conglomerates with regulatory affairs infrastructure. Consolidation pressures squeeze mid-tier standalone reagent suppliers as hospital networks demand instrument-consumable bundles. Three archetypes dominate: full-platform integrators owning extraction-automation-software stacks; regulatory specialists navigating CE-IVD and FDA 510(k) pathways; and chemistry-focused suppliers of membrane and bead matrices. Competitive moves concentrate on M&A for regulatory dossier libraries and strategic partnerships for silica supply security.
Among diversified platform integrators, Thermo Fisher Scientific and Qiagen anchor the premium tier through quality management systems and notified body relationships. Roche Diagnostics occupies a position at the instrument-consumable convergence point. Merck KGaA represents the European regulatory specialist archetype, while Bio-Rad Laboratories and Agilent Technologies exemplify technology-diversified competitors with extraction kit adjacencies. Promega Corporation, Takara Bio, and PerkinElmer sit within the research-to-clinical transition segment, balancing flexibility demands against certification overhead.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Qiagen |
| Roche Diagnostics |
| Promega Corporation |
| Bio-Rad Laboratories |
| Agilent Technologies |
| Merck KGaA |
| Takara Bio |
| PerkinElmer |
| Others |
Supply Flow & Price Mechanics
Purified silica membrane costs cascade from East Asian chemical parks through three distinct pricing tiers before reaching clinical diagnostic laboratories in the United States and Germany. Freight volatility and customs processing delays at major port gateways amplify input cost variability, forcing kit assemblers to absorb margin compression or renegotiate multi-year IDN contracts.
Pricing Analysis
Throughput-based pricing anchors contract structures, with multi-hospital health systems in Texas and California negotiating turnaround time guarantees rather than per-unit rates. Three-tier pricing structure across premium, standard, and economy levels separates GMP-documented pharmaceutical kits from CE-IVD clinical grades and research-use-only formats. Pricing pressure stems from lyophilized reagent substitution reducing cold-chain dependency for certain PCR workflows. Research laboratories exhibit the highest price sensitivity, while cell and gene therapy manufacturers accept premium positioning for reduced compliance risk.
Supply Chain Analysis
Dual-sourcing requirements from major kit assemblers mandate qualified secondary suppliers for purified silica matrices, mitigating single-source vulnerability. Manufacturing concentrates in China, South Korea, and Japan, with Shanghai and Suzhou chemical parks feeding global consumable production. Magnetic bead chemistries and stabilized column matrices depend on specialty polymer synthesis and surface chemistry functionalization. Tariff exposure on East Asian chemical imports creates structural risk for European and North American assemblers. Distribution runs through regional life science distributors with field application scientists for mid-size accounts, while direct sales teams capture multi-hospital IDN negotiations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Purified silica supply concentration in East Asian manufacturing hubs props pricing power for membrane matrix suppliers, constraining downstream kit assembler margins across the analysis window.
For Market Incumbents: Deepen backward integration into specialty chemical production or secure long-term offtake agreements with Shanghai and Suzhou chemical parks to defend against freight volatility. Lock hospital networks into instrument-consumable bundles with embedded technical support obligations, raising switching costs for alternative magnetic bead platforms. Prioritize notified body relationship investment to navigate ISO 13485 auditor scarcity extending European certification timelines. For New Entrants and Emerging Players: Launch via CLIA-waived point-of-care distribution channels in urgent care and pharmacy settings, where decentralized molecular diagnostics remain underdeveloped relative to centralized laboratory automation. Target research-to-clinical transition segments with flexible spin-column formats that academic medical centers can validate in-house before regulatory submission. Emphasize AI-enabled sample handling integration to differentiate from legacy automated platforms. For Investors and Strategic Acquirers: EU MDR compliance deadline extensions are the leading indicator that replacement demand curves for certified extraction kits will steepen, favoring quality management system investments over pure chemistry plays. Position for five-to-ten year holding periods around regulatory dossier libraries and notified body relationships rather than standalone reagent suppliers. Watch for consolidation signals when mid-tier manufacturers face parallel FDA 510(k) and EU MDR validation cost burdens.| Strategic Initiative | Industry Significance |
|---|---|
| CE-IVD Certification Pathway | Notified body relationships in Berlin and Munich compress validation timelines for German clinical laboratory entry. |
| Silica Supply Security Agreement | Long-term offtake contracts with East Asian chemical parks mitigate freight volatility for membrane matrix assemblers. |
| AI-Enabled Sample Handling Integration | Machine vision quality control embedded in automated platforms reduces failed extraction rates for high-throughput reference labs. |
| Hospital System Partnership | Multi-year contracts with Texas and California IDNs aggregate purchasing power previously fragmented across individual facilities. |
| Pharmaceutical GMP Documentation Service | Extensive lot-to-lot characterization and audit trails command premium positioning from cell and gene therapy manufacturers. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across diagnostic laboratory directors, GPO contracts managers, biomedical engineers, and regulatory affairs leads at notified bodies. FDA 510(k) summaries, EMA MDR submission dossiers, and import-export manifests provided volume and pricing benchmarks. Bottom-up kit consumption estimates from hospital procurement databases and reference laboratory capital expenditure disclosures triangulated against top-down market sizing from silica membrane and magnetic bead chemical production data.
Segment-level modeling captured product architecture splits between spin-column and magnetic bead formats, application tiering across clinical diagnostics, pharmaceutical GMP, and research-use-only environments, and end-user procurement sophistication variations from centralized IDN purchasing to principal-investigator-driven academic ordering. Geographic clusters reflected regulatory framework differences between FDA IVD, EU MDR, and NMPA pathways. CAGRs derived from fitted growth curves applied to validated baseline consumption estimates, with cross-checks against automated liquid handling platform installation rates and transcriptomic research funding flows.
The model assumes a particular technology adoption path; alternative pathways for lyophilized reagent substitution or cartridge-based closed-system formats would alter the outlook for traditional spin-column demand curves. Deviation in EU MDR auditor capacity constraints or silica supply chain disruption would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Sperm Count Test Market
Diagnostics
Influenza Diagnostic Tests Market
Diagnostics
Blood Urea Nitrogen Diagnostics Market
Diagnostics
Prostate Cancer Diagnostics Market
Diagnostics
Vibrio Diagnostics Market
Diagnostics
Europe Kidney Cancer Diagnostics Market
Diagnostics
US in Vitro Diagnostics Market
Diagnostics
Global Chromoendoscopy Agents Market
Diagnostics
At-Home Cancer Testing Market
Diagnostics
Hydrogen Breath Test Analyzer Market
Diagnostics
Global Yersinia Diagnostics Market
Diagnostics
United States Melanoma Diagnostics & Therapeutics Market
Diagnostics
Non-Alcoholic Steatohepatitis (NASH) Biomarkers Market
Diagnostics
Point of Care (Poc) Molecular Diagnostics Market
Diagnostics
Alanine Aminotransferase Reagent Market
Diagnostics
Europe in Vitro Diagnostics (IVD) Market