
 Brining Systems Market | 2026-2036
Brining Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Brining Systems Market Analytics
Denmark is rewriting competitive dynamics in brining equipment supply as Danish engineering firms expand stainless-steel fabrication capacity for food-grade systems. GEA Group leverages its Copenhagen-area manufacturing footprint to anchor European demand for hygienic continuous brining lines. Alfa Laval competes through heat-exchanger integration that reduces thermal cycling in batch operations. Evoqua Water Technologies specializes in brine recovery modules that cut wastewater discharge for protein processors.
Brining systems engineer controlled salt saturation, temperature management, and mass transfer to preserve, flavor, or tenderize raw materials across protein, vegetable, and industrial applications. These systems typically operate at brine concentrations between 15% and 26% sodium chloride, with precision injection systems achieving distribution uniformity within 3% deviation to ensure consistent product yield and shelf stability. Continuous systems dominate capital expenditure in high-volume meat processing due to throughput advantages, while batch configurations retain margin pools in artisanal and specialty food manufacturing where recipe flexibility commands premium pricing. Mobile brining units represent the fastest-growing system type as remote fisheries and seasonal protein operations seek to avoid fixed infrastructure commitments.
FDA food safety modernization rules and USDA-FSIS pathogen reduction standards shape equipment design requirements for North American meat brining operations, mandating clean-in-place compatibility and microbial intervention validation. The EU MDR and CE marking frameworks govern contact-surface materials and pressure-vessel integrity for systems deployed across European protein plants. Stakeholders must monitor how brine-recycling regulations evolve in water-stressed jurisdictions, as zero-liquid-discharge mandates could render conventional single-pass systems economically unviable regardless of upfront capital efficiency.
Market Dynamics
EU F-Gas Regulation and REACH compliance are forcing meat processors to retire refrigerant-dependent batch systems and adopt closed-loop brine recovery architectures, compressing equipment replacement cycles across European protein plants.
Growth Catalysts
- Clean-label mandates:Retail chains in Germany and Denmark now require nitrite-free cured meat lines, pulling investment into precision-controlled brining systems that maintain shelf stability without traditional preservatives.
- Water-stressed jurisdictions:Zero-liquid-discharge mandates in Spain and Italy are accelerating adoption of brine recovery modules that recycle 85% of process water in high-volume ham and salami operations.
- Mobile system demand:Seasonal fisheries in Norway and remote poultry operations in Poland are avoiding fixed infrastructure through containerized brining units with plug-and-play utility connections.
Market Restraints
- Stainless steel input volatility:Food-grade 316L stainless price swings constrain fabrication margins for Copenhagen and Hamburg equipment builders, delaying quoted delivery windows by 8-12 weeks during commodity spikes.
- CE marking complexity:Pressure vessel and hygienic design certification under EU MDR extends lead times for custom continuous lines, freezing small-batch artisanal producers out of system upgrades.
- Substitution by dry-curing:Traditional Parma ham and Iberico producers in Italy and Spain retain margin pools in static salt-chamber methods that bypass brining infrastructure entirely.
Strategic Opportunities
- Vegetable protein expansion:Plant-based bacon and deli slice manufacturers in the Netherlands require adapted brining chemistry for soy and pea isolates, opening equipment retrofit demand from existing meat system suppliers.
- EU Green Deal alignment:Carbon border adjustment mechanisms reward low-energy thermal cycling designs, creating competitive differentiation for heat-exchanger-integrated batch systems in Danish engineering clusters.
- Service unbundling:Aftermarket brine chemistry monitoring and predictive maintenance contracts represent recurring revenue streams as processors outsource technical staffing in Germany's tight labor market.
Industry Challenges
- Clean-in-place engineering shortage:Protein plants struggle to hire process engineers capable of validating microbial intervention protocols under USDA-FSIS and EFSA parallel requirements for export-qualified output.
- Legacy system integration:Brownfield meat facilities in Northern Italy face downtime risk when grafting continuous brining lines onto 1970s-era slicing and packaging workflows with mismatched throughput speeds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brining Systems Market |
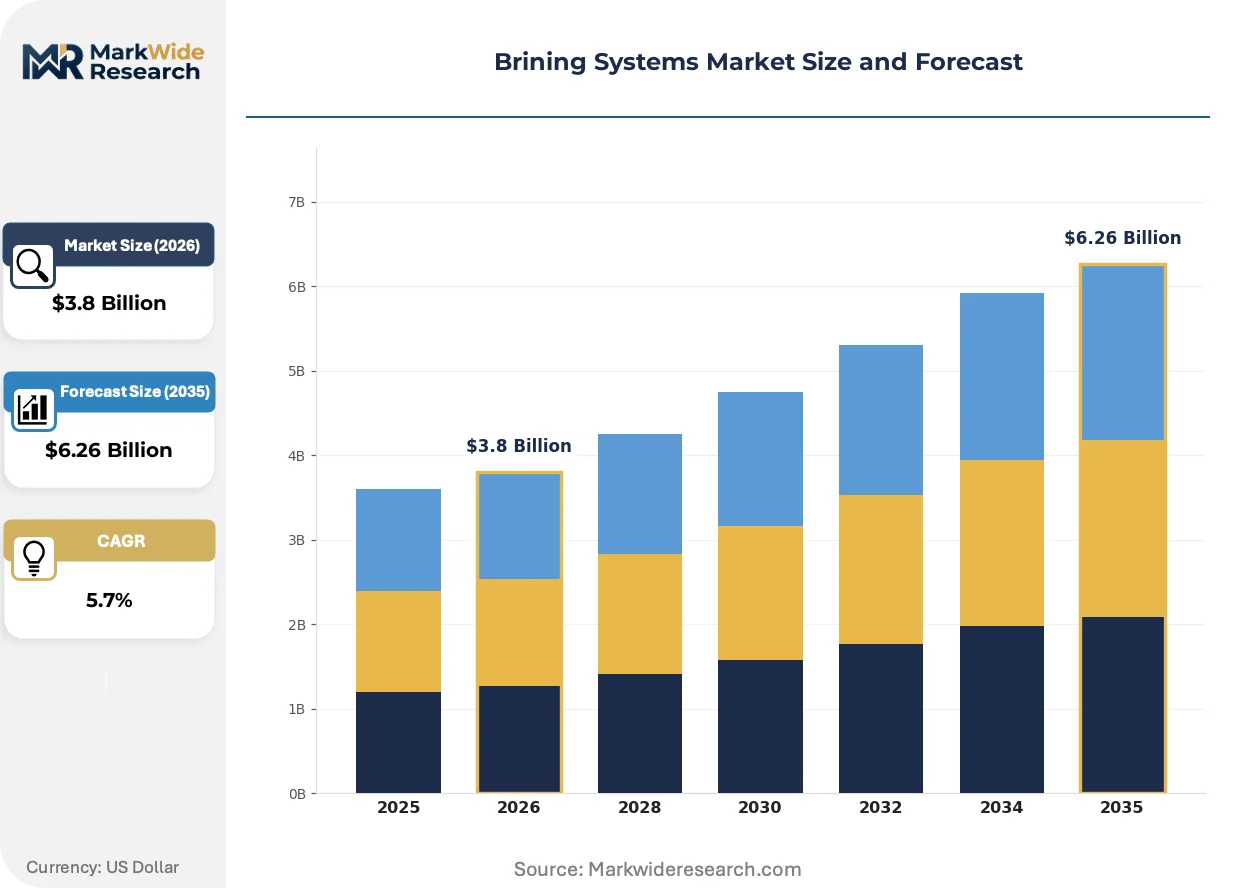
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Food Processing, Chemical Processing, Water Treatment, Oil Extraction System Type: Batch Systems, Continuous Systems, Semi-Continuous Systems, Mobile Brining Units End User: Food Manufacturers, Beverage Producers, Wastewater Treatment Plants, Fisheries Technology: Reverse Osmosis, Electrodialysis, Vacuum Brining, Traditional Salting |
| Companies Covered | van den Heuvel Dairy & Food Equipment, GEA Group, Alfa Laval, Veolia Water Technologies, Evoqua Water Technologies, TETRA Technologies, Halliburton Company, Schlumberger, Baker Hughes Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brining Systems Market Evolving Landscape
Electrochemical brine generation and AI-driven saturation monitoring are compressing operational variance in high-throughput protein processing, while regulatory chemistry restrictions force equipment redesign at the component level.
Pulsed electric field pre-treatment is migrating from experimental installations to standard configuration in Danish pork belly operations, where GEA Group and regional integrators now bundle field chambers with continuous brining lines. Mid-size sausage processors in Lower Saxony adopt the technology to accelerate salt penetration without extending residence time, compressing equipment footprints by 30% in renovated plant halls.
REACH restrictions on chromium-containing alloys are reshaping contact-surface specifications for brining vessels and injection needles across EU member states. Equipment fabricators in Hamburg and Copenhagen now stockpile compliant duplex stainless grades, while Italian ham producers delay system purchases pending clarity on grandfathering clauses for existing installed base.
Buyer consolidation among German retail cooperatives is compressing vendor qualification cycles and unbundling after-sales service from capital equipment contracts. Procurement teams at major sausage and cured meat groups now demand standalone technical support agreements with 4-hour response commitments, displacing traditional bundled warranty structures in Bavaria and Baden-Württemberg processing clusters.
Brining Systems Market Segmentation
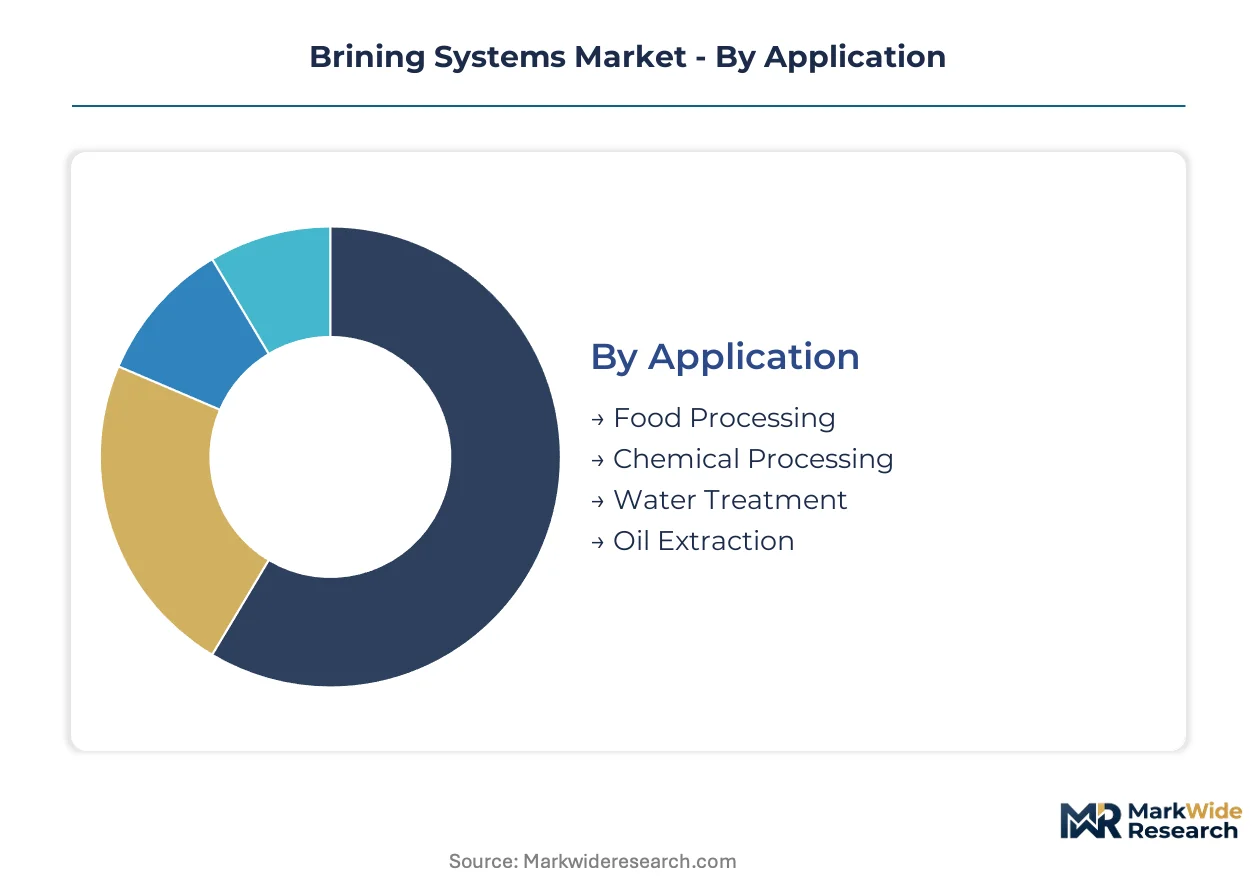
Equipment specification in brining systems diverges sharply across protein chemistry, industrial fluid separation, and regulatory compliance contexts. Segmentation reveals how batch configurations retain margin pools in artisanal food manufacturing while continuous architectures dominate capital deployment in high-volume chemical processing. Technology selection increasingly hinges on water recovery mandates and energy intensity thresholds rather than throughput alone.
Application:
End-use chemistry spans osmotic preservation, ion exchange, and density-driven separation with divergent equipment specifications.
- Food Processing:Precision injection systems achieve salt distribution uniformity within 3% deviation for meat, poultry, and vegetable protein operations. Demand concentrates in Germany's sausage and cured meat clusters, where clean-label mandates force nitrite-free line investments.
- Chemical Processing:Industrial brining facilitates crystallization control and reaction medium preparation across pharmaceutical and specialty chemical synthesis. Water-stressed jurisdictions in Spain and Italy drive zero-liquid-discharge retrofits with 85% brine recovery targets.
- Water Treatment:Desalination reject streams and industrial wastewater require brine concentration before crystallizer or deep-well injection stages.
- Oil Extraction:Density modification through brine injection supports enhanced recovery operations in mature petroleum reservoirs.
The dominant share belongs to Food Processing, while Water Treatment is closing the gap fastest.
System Type:
Capital intensity and operational flexibility trade off across fixed infrastructure and containerized deployments.
- Batch Systems:Recipe-flexible vessels with programmable temperature and saturation profiles serve artisanal ham, cheese, and specialty protein manufacturers. CE marking complexity under EU MDR extends lead times for custom hygienic designs, freezing small-batch producers out of upgrades.
- Continuous Systems:High-throughput lines with integrated injection, tumbling, and conveyor stages dominate pork belly and poultry breast operations. Stainless steel input volatility constrains Hamburg and Copenhagen fabricators, delaying quoted deliveries by 8-12 weeks during commodity spikes.
- Semi-Continuous Systems:Hybrid architectures bridge throughput and flexibility for mid-size processors with seasonal product mix variation.
- Mobile Brining Units:Containerized systems with plug-and-play utility connections serve remote Norwegian fisheries and seasonal Polish poultry operations avoiding fixed infrastructure commitments.
Continuous Systems command the largest installed base, though Mobile Brining Units are expanding most quickly.
End User:
Customer technical capability and outsourcing appetite shape service bundling and aftermarket contract structures.
- Food Manufacturers:Meat, dairy, and prepared food processors specify clean-in-place compatibility and microbial intervention validation under FDA food safety modernization and USDA-FSIS parallel requirements. Procurement teams at German retail cooperatives now unbundle after-sales service from capital contracts.
- Beverage Producers:Fermentation brine management and barrel curing operations in wine and spirits require precise microbiological control.
- Wastewater Treatment Plants:Municipal and industrial facilities concentrate brine streams ahead of crystallization or disposal.
- Fisheries:On-vessel and shore-based operations for whitefish and salmon preservation use compact batch or mobile configurations.
Food Manufacturers retain the deepest equipment penetration, while Beverage Producers are gaining share fastest.
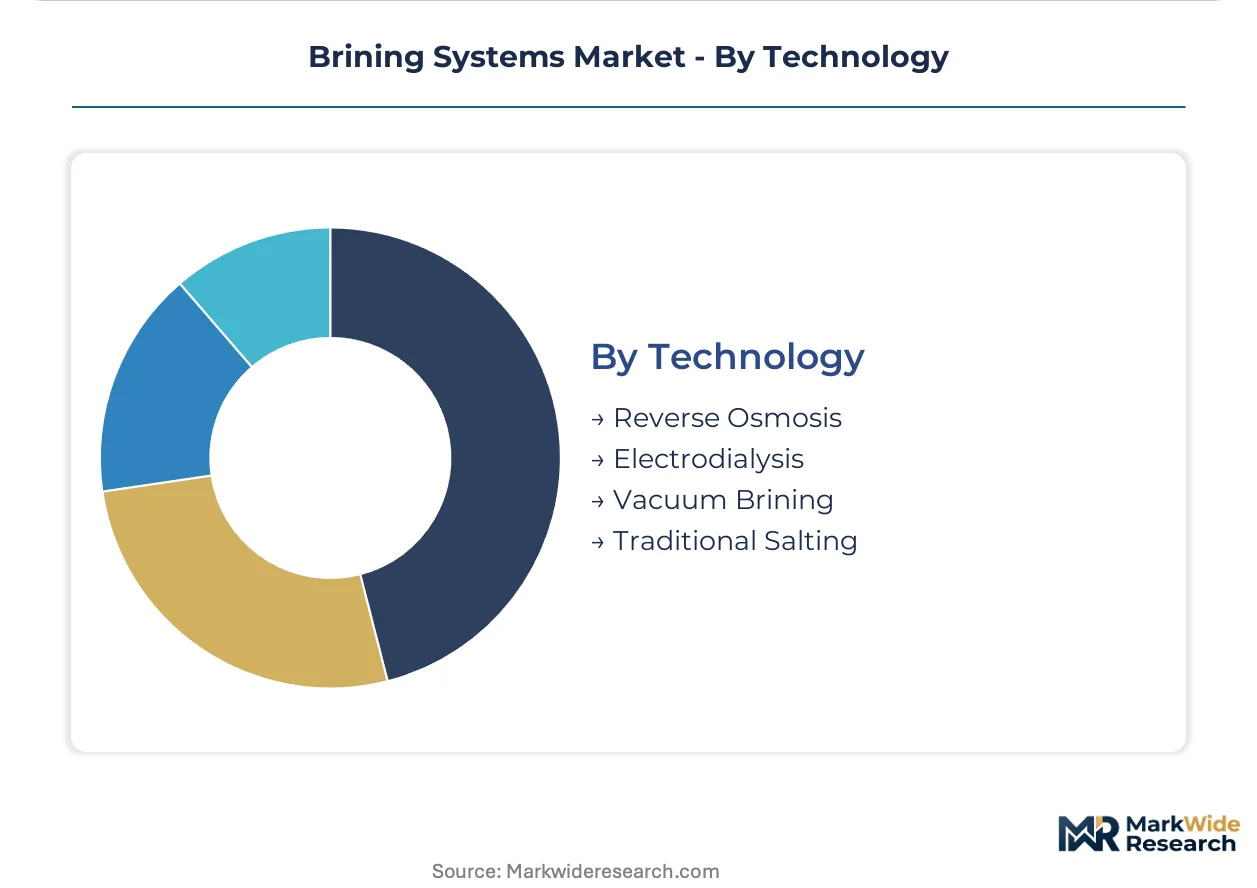
Technology:
Separation physics and energy input mechanisms differentiate capital cost, operating expense, and regulatory compliance profiles.
- Reverse Osmosis:Membrane-based brine concentration achieves high water recovery with pressure-driven salt rejection for desalination and industrial wastewater. REACH restrictions on membrane materials and EU Green Deal carbon border adjustments reward low-energy configurations in Danish engineering clusters.
- Electrodialysis:Electric-field-driven ion transport enables selective salt recovery and acid-base regeneration with lower pressure requirements than membrane alternatives.
- Vacuum Brining:Reduced-pressure saturation accelerates mass transfer in protein applications with temperature-sensitive quality attributes.
- Traditional Salting:Static salt-chamber methods persist in Parma ham and Iberico production, bypassing mechanical brining infrastructure entirely.
Reverse Osmosis holds the dominant technology position, while Electrodialysis is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German meat processors deploy continuous brining lines for high-volume sausage production, while Italian ham makers retain static salt-chamber methods that bypass mechanical infrastructure entirely. Danish engineering clusters specialize in stainless-steel fabrication for hygienic food-grade systems. Spanish and Italian water-stressed regions drive zero-liquid-discharge retrofits with brine recovery mandates.
Germany
Retail cooperatives in Bavaria and Baden-Württemberg demand nitrite-free cured meat lines, pulling investment into precision-controlled brining systems. The EU F-Gas Regulation forces processors in Lower Saxony to retire refrigerant-dependent batch equipment ahead of schedule. Equipment fabricators in Hamburg face 8-12 week delivery delays when food-grade 316L stainless prices spike.
Italy
Parma ham and traditional salami producers in Emilia-Romagna maintain margin pools in static salt-curing methods that require no mechanical brining infrastructure. REACH restrictions on chromium-containing alloys delay system purchases as producers await grandfathering clarity for existing installed base. Northern Italian brownfield facilities face integration downtime when grafting continuous lines onto 1970s-era slicing workflows.
Spain
Iberico ham producers in Extremadura and Andalusia bypass brining systems through traditional dry-curing chambers that command premium pricing in export markets. Zero-liquid-discharge mandates in water-stressed regions accelerate adoption of brine recovery modules targeting 85% process water recycling. Mid-size processors retrofit existing lines to meet EU Green Deal carbon border adjustment thresholds.
Denmark
Copenhagen-area engineering firms expand stainless-steel fabrication capacity to anchor European demand for hygienic continuous brining lines. Danish pork belly operations adopt pulsed electric field pre-treatment bundled with GEA Group continuous systems to compress equipment footprints by 30%. The national cluster specializes in heat-exchanger-integrated designs that reduce thermal cycling energy intensity.
Poland
Seasonal poultry operations in rural regions avoid fixed infrastructure commitments through containerized mobile brining units with plug-and-play utility connections. Remote processors face procurement constraints as CE marking complexity under EU MDR extends lead times for custom hygienic designs. Polish facilities balance throughput expansion against labor market tightness that limits in-house technical staffing for brine chemistry monitoring.
Brining Systems Market Competitive Landscape
Capability concentration sits with specialized engineering firms that control stainless-steel fabrication and hygienic design expertise; scale advantage sits with diversified industrial groups that leverage cross-sector technology platforms. The vendor base organizes around three strategic archetypes: food-grade system specialists, water technology integrators, and diversified process engineering conglomerates. Competitive moves center on geographic expansion into protein processing clusters and portfolio diversification toward brine recovery and water treatment adjacencies.
Within the diversified engineering tier, GEA Group and Alfa Laval represent archetypes of scale-driven platform players that leverage Copenhagen-area manufacturing footprints and heat-exchanger integration expertise respectively. Among water technology specialists, Evoqua Water Technologies exemplifies the service-unbundling strategy that targets recurring revenue from brine chemistry monitoring contracts. The competitive set spans Dutch dairy equipment heritage, Swedish separation technology roots, and American water treatment specialization.
| Leading Market Players |
|---|
| van den Heuvel Dairy & Food Equipment |
| GEA Group |
| Alfa Laval |
| Veolia Water Technologies |
| Evoqua Water Technologies |
| TETRA Technologies |
| Halliburton Company |
| Schlumberger |
| Baker Hughes Company |
| Others |
Value Network & Pricing Analysis
Food-grade 316L stainless steel stockpiles in Hamburg and Copenhagen fabrication clusters directly determine where margin pools accumulate downstream, with equipment builders capturing premium pricing during commodity troughs while processors absorb volatility spikes through extended delivery windows.
Pricing Analysis
Long-term offtake contracts dominate capital equipment procurement for continuous brining lines in German sausage clusters, while spot purchasing prevails among seasonal Polish poultry operators deploying mobile containerized units. Three-tier pricing structure across premium hygienic-design, standard CE-marked, and economy refurbished systems differentiates on certification grade and after-sales bundling. Cost compression in mid-tier batch configurations is intensifying because REACH-compliant duplex stainless grades command material premiums. Small-batch artisanal ham producers in Italy exhibit highest price sensitivity due to CE marking complexity freezing upgrade budgets, whereas German retail cooperatives show lowest sensitivity given clean-label mandate compliance requirements.
Supply Chain Analysis
Export-control regimes on precision injection pump technology limit component flows from Danish engineering clusters to non-EU protein processing markets, constraining capacity expansion for regional integrators. Supply concentration centers on Germany, Denmark, and Italy for hygienic vessel fabrication, with Poland emerging for mobile unit assembly. Component dependencies rest on food-grade stainless grades, high-pressure injection manifolds, and heat-exchanger bundles. Single-source vulnerability runs through specialized electrochemical brine generation cell suppliers in Copenhagen-area manufacturing zones. Distribution runs through direct OEM sales for large continuous lines and regional equipment distributors for batch and mobile configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach opportunities in brining systems markets outpace hardware growth, with predictive maintenance contracts and brine chemistry monitoring subscriptions expanding faster than capital equipment sales as German processors outsource technical staffing.
For Market Incumbents: Insulate installed base relationships through captive aftermarket service contracts that displace independent technical support providers in Bavaria and Baden-Württemberg processing clusters. Deepen backward integration into food-grade stainless fabrication by acquiring Copenhagen-area specialist metalworkers to secure supply continuity against commodity volatility. CE marking complexity under EU MDR presents the primary threat, requiring certification investment to maintain qualification pipelines for custom hygienic designs. For New Entrants and Emerging Players: Establish a beachhead in mobile brining unit deployment for remote Norwegian fisheries and seasonal Polish poultry operations avoiding fixed infrastructure commitments. Target vegetable protein adaptation retrofits in Netherlands plant-based bacon manufacturing as the most penetrable white-space segment. Lead with containerized plug-and-play configurations that bypass lengthy CE marking cycles through standardized hygienic designs. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed Danish engineering specialists that expanded stainless fabrication capacity ahead of EU F-Gas Regulation-driven replacement demand. Long-term viability across the analysis window hinges on water recovery technology integration and service revenue mix expansion. Monitor brine-recycling regulation adoption in Spanish and Italian water-stressed jurisdictions as the inflection signal for zero-liquid-discharge retrofit demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Stainless Fabrication | Copenhagen-area metalworker acquisitions secure supply continuity against 316L price volatility. |
| Service Revenue Unbundling | Standalone predictive maintenance contracts displace traditional bundled warranty structures in Germany. |
| Mobile Unit Platform Expansion | Containerized plug-and-play configurations bypass CE marking delays for Polish seasonal operators. |
| Vegetable Protein System Adaptation | Retrofit chemistry modules capture Netherlands plant-based bacon manufacturing demand. |
| Brine Recovery Technology Licensing | Zero-liquid-discharge module partnerships accelerate Spanish and Italian regulatory compliance. |
Research Methodology
The analysis maps continuous brining lines, batch vessels, mobile units, and brine recovery modules, each validated through equipment procurement directors, plant engineers at protein processing facilities, aftermarket service managers, and stainless steel fabrication specialists. Primary interviews combined with secondary validation from EU MDR filing databases, ECHA REACH substance restriction updates, F-Gas Regulation implementation guidance, and German retail cooperative sustainability procurement disclosures. Bottom-up equipment shipment tracking and top-down protein processing capacity analysis triangulate market sizing across the projection horizon.
Assumption sets held regulatory enforcement timelines and stainless steel commodity bands fixed while varying clean-label mandate adoption rates and water-stress policy intensity across modeled scenarios. Segmentation dimensions span system type, application chemistry, technology mechanism, and end-user technical capability. CAGRs derive from installed base turnover analysis and replacement cycle compression factors. Forecast inputs incorporate EU Green Deal carbon border adjustment thresholds and pulsed electric field pre-treatment adoption curves in Danish pork operations.
Stress conditions across F-Gas phase-out acceleration, REACH alloy restriction expansion, and zero-liquid-discharge mandate geographic spread were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on replacement cycle timing and service revenue attach rates. Material shifts in EU MDR grandfathering clarity for existing installed base or abrupt stainless steel supply disruptions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Distillation Analyzer Market
Food Processing Equipment
Canning Machine Market
Food Processing Equipment
Food Recycler Market
Food Processing Equipment
Tortilla Machine Market
Food Processing Equipment
Automatic Liquid Dispenser Machine Market
Food Processing Equipment
Softgel Encapsulation Machine Market
Food Processing Equipment
Global Industrial Food Blanchers Market
Food Processing Equipment
Frozen Food Processing Machinery Market
Food Processing Equipment
Plastic Processing Equipment Market
Food Processing Equipment
Microbrewery Equipment Market
Food Processing Equipment
Global Meat Mixer Market
Food Processing Equipment
Commercial Wood Fired Pizza Oven Market
Food Processing Equipment
Global Powder Processing Equipment Market
Food Processing Equipment
Spray Dryer Market
Food Processing Equipment
Planetary Mixer Market
Food Processing Equipment
Industrial Planetary Mixers Market