
 Fluidized Bed Dryer Market | 2026-2036
Fluidized Bed Dryer Market Size, Share, and Industry Trends Forecast 2026-2036
Fluidized Bed Dryer Market Analysis
Pharmaceutical-grade cGMP compliance is unwinding legacy equipment replacement cycles across the fluidized bed dryer landscape. Bühler Group leverages integrated process control systems to sustain premium positioning in food and pharma applications. GEA Group anchors European supply through specialized containment solutions for potent compounds. Glatt competes on fluidized bed coater-dryer hybrid architectures that reduce batch transfer losses.
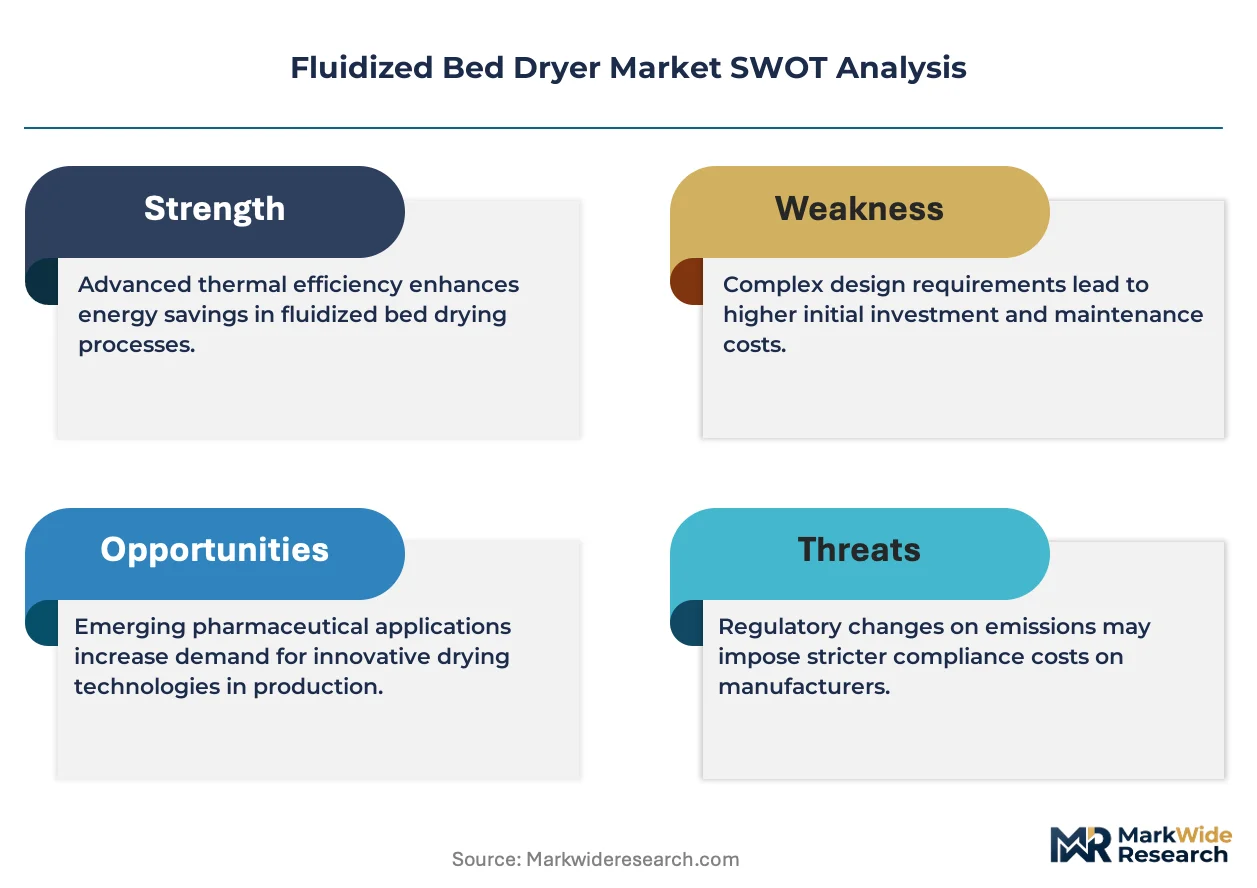
A fluidized bed dryer suspends particulate solids in an upward-flowing gas stream—typically air or nitrogen at 40-200°C—creating a fluid-like bed for rapid, uniform moisture removal. The equipment achieves drying rates of 5-50 kg water evaporated per hour per square meter of distributor plate, serving pharmaceutical granulation, food powder production, and chemical catalyst preparation. Continuous dryer configurations capture the fastest expansion as chemical producers seek throughput gains over batch cycles. Hot air circulation technology retains the largest installed base, though microwave-assisted systems gain traction where thermal degradation of active ingredients poses formulation risks. Pharmaceutical companies represent the highest-margin end-user segment due to validation documentation and containment requirements.
FDA cGMP guidelines and EMA GMP Annex 15 on qualification and validation shape equipment specification and documentation burdens for suppliers targeting regulated markets. REACH chemical safety standards in Europe restrict certain coating solvents, redirecting dryer selection toward closed-loop nitrogen systems with solvent recovery. China's NMPA alignment with ICH Q9 quality risk management principles accelerates domestic equipment upgrades. Stakeholders must monitor evolving containment standards for highly potent active pharmaceutical ingredients as regulatory thresholds tighten without harmonization across FDA, EMA, and NMPA frameworks.
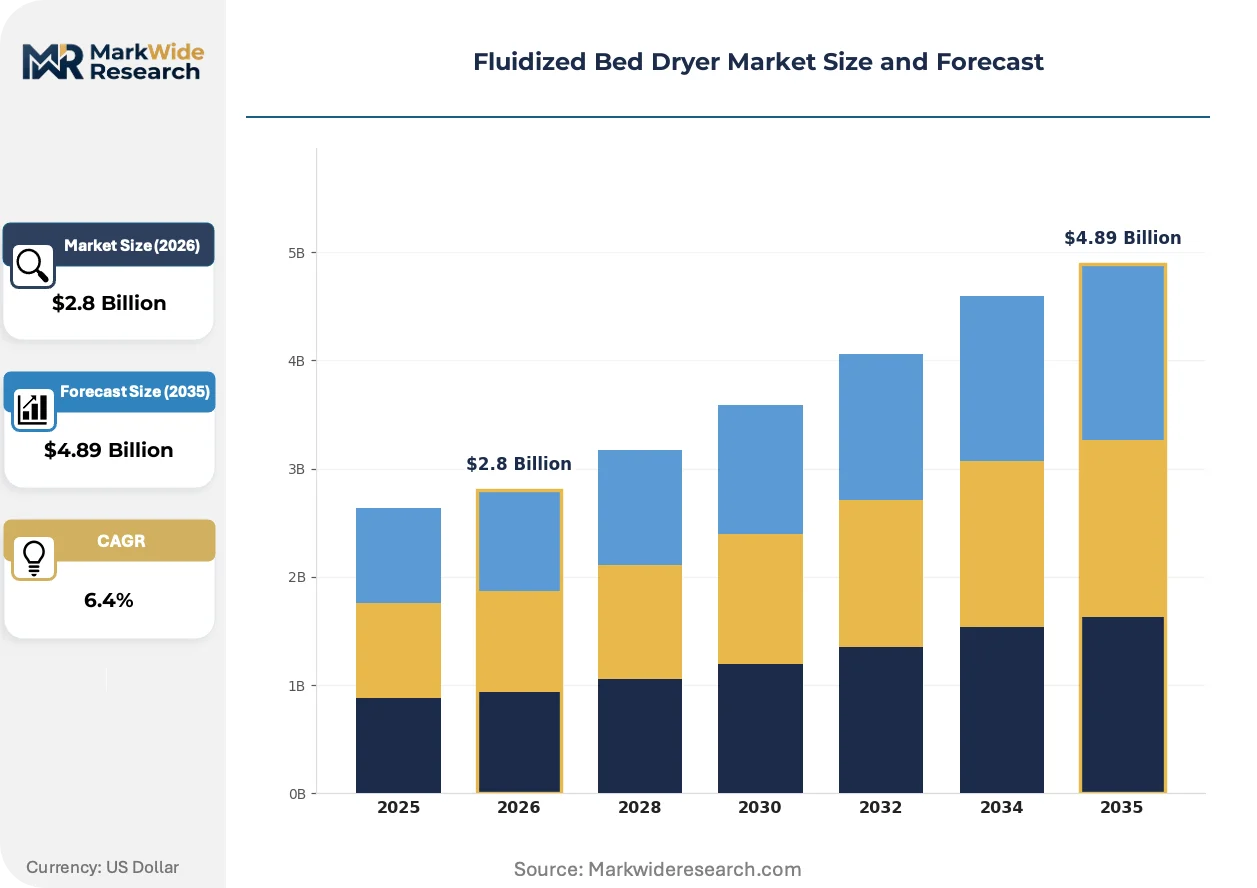
Market Dynamics
Batch-to-continuous processing migration is compressing equipment replacement cycles as pharmaceutical and chemical manufacturers chase throughput gains and energy efficiency. This structural shift favors integrated dryer-coater systems over standalone units.
Growth Catalysts
- EMA GMP Annex 15 validation requirements:European pharmaceutical manufacturers must document equipment qualification, forcing upgrades from legacy dryers lacking automated data capture.
- Food powder processing:Instant coffee and infant formula producers adopt fluidized bed technology for uniform particle coating and moisture control.
- Nitrogen-based closed-loop systems:Solvent recovery mandates under REACH drive replacement of open-air dryers in fine chemical production.
Market Restraints
- Stainless steel price volatility:316L and 304 grade sheet metal constitutes 35-45% of equipment cost, exposing margins to nickel and chromium fluctuations.
- Specialized fabricator concentration:Precision distributor plate manufacturing clusters in southern Germany and northern Italy, creating single-source vulnerability.
- Freeze-drying substitution:Heat-sensitive biologics producers increasingly specify lyophilization for protein stability, limiting dryer addressable market in high-value segments.
Strategic Opportunities
- India's PLI scheme for active pharmaceutical ingredients:Domestic manufacturing incentives attract greenfield investments requiring cGMP-compliant drying equipment.
- Microwave-hybrid drying:Convergence of conventional hot air with microwave energy enables rapid moisture removal without thermal degradation of temperature-sensitive actives.
- Contract manufacturing expansion:CDMOs in Ireland and Singapore build multi-product facilities requiring flexible, containment-capable dryer configurations.
Industry Challenges
- Containment engineering talent scarcity:Designing isolator-integrated systems for potent compounds requires rare cross-disciplinary expertise in pharmaceutical process safety and mechanical engineering.
- Legacy SCADA integration:Brownfield sites struggle to connect modern fluidized bed controllers to aging plant-wide automation architectures without full line shutdowns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fluidized Bed Dryer Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Batch Dryer, Continuous Dryer, Pilot Dryer, Mini Dryer Application: Food Processing, Pharmaceutical Manufacturing, Chemical Production, Powder Coating End User: Food Industry, Pharmaceutical Companies, Chemical Firms, Research Institutions Technology: Hot Air Circulation, Microwave Assistance, Infrared Heating, Vibratory Motion |
| Companies Covered | Bühler Group, Lödige, GEA Group, DIOSNA, Romaco Group, Glatt, SPX FLOW, Jiangsu Jinling Drying Technology, Syntegon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fluidized Bed Dryer Market Emerging Trajectories
Equipment architecture is splitting between standardized platforms for commodity applications and highly customized systems for potent compound containment. This divergence reshapes R&D allocation and service models across the supplier base.
Continuous fluidized bed processing is bifurcating the installed base. Chemical catalyst manufacturers adopt fully automated systems with real-time moisture analytics and self-adjusting airflow. Batch pharmaceutical producers resist full continuous conversion due to validation complexity, creating a persistent technology gap. The market is compressing around two distinct equipment tiers with minimal overlap in specification or pricing.
REACH chemical safety standards are tightening solvent emission thresholds for coating operations. Manufacturers must specify nitrogen-recirculating dryers with integrated condensate recovery or face operational restrictions. German chemical producers lead compliance investment, while southern European facilities lag in retrofit scheduling.
After-sales service unbundling is disrupting traditional equipment procurement. Pharmaceutical buyers now separate dryer acquisition from validation support and maintenance contracts, sourcing documentation and IQ/OQ execution from third-party specialists. This fragmentation is most pronounced in North American facilities with mature quality assurance functions.
Fluidized Bed Dryer Market Segmentation
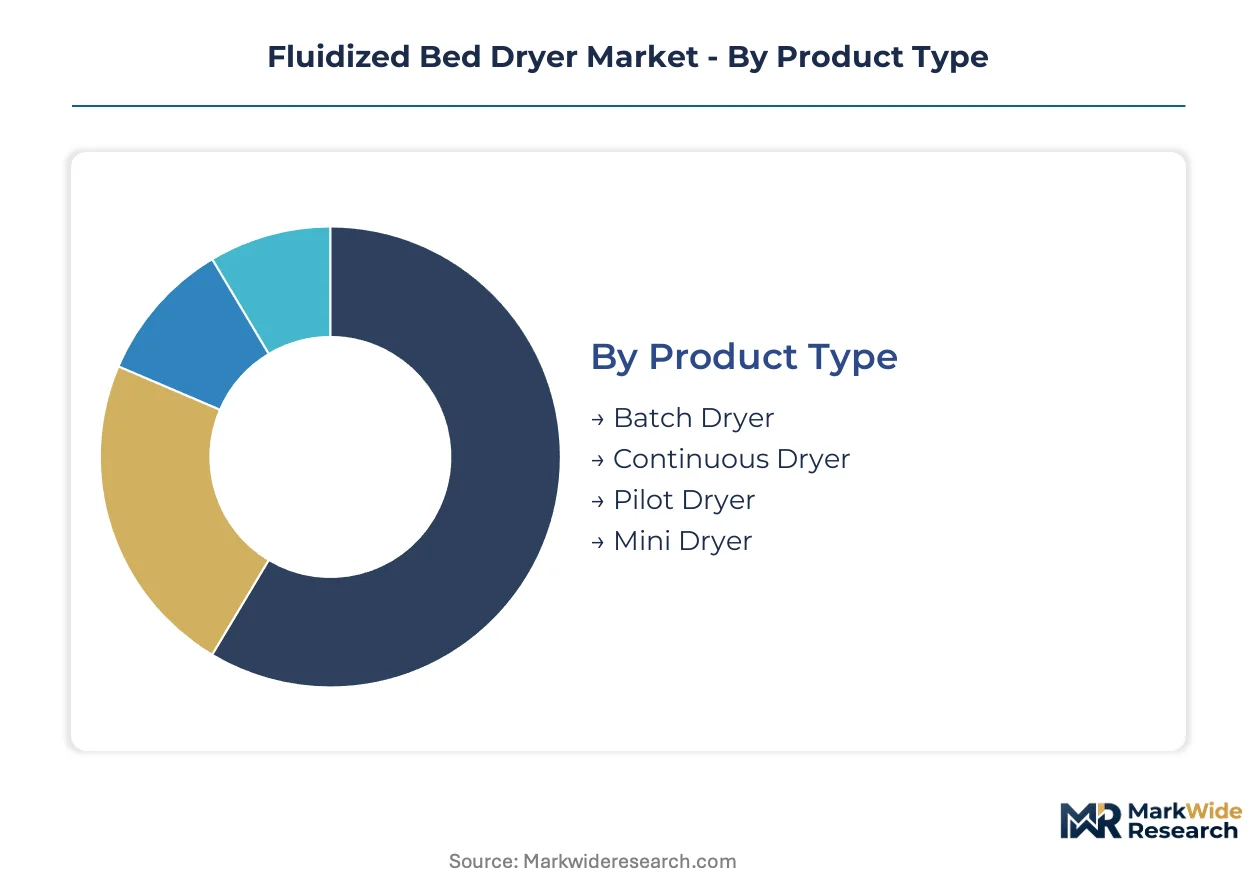
Fluidized bed dryer procurement channels diverge sharply across end-use verticals. Pharmaceutical buyers validate through specialized engineering firms, while food processors source through integrated equipment distributors.
Product Type:
Channel mix varies by scale: batch and pilot units flow through regional distributors with validation support, while continuous systems sell direct with long-term service contracts.
- Batch Dryer:Chamber-based systems process discrete pharmaceutical lots under cGMP documentation protocols. German pharmaceutical machinery clusters around Cologne and Düsseldorf concentrate demand as EMA GMP Annex 15 validation requirements force legacy replacement.
- Continuous Dryer:Conveyorized configurations enable uninterrupted catalyst and food powder production with real-time moisture feedback. Chemical producers in Germany's industrial corridor adopt these for REACH-compliant solvent recovery integration.
- Pilot Dryer:Scaled-down units support formulation development with full-scale process mimicry. Research institutions and CDMOs in Singapore specify these for multi-product flexibility.
- Mini Dryer:Benchtop systems serve laboratory-scale powder characterization. University research centers and startup API developers drive niche demand.
Batch Dryer dominates installed base. Continuous Dryer is where expansion concentrates.
Application:
Margin tiers separate these segments: pharmaceutical and chemical applications command premium pricing for containment engineering, while food processing competes on throughput efficiency.
- Pharmaceutical Manufacturing:Granulation and coating operations require isolator-integrated systems with automated data capture for FDA and EMA compliance. India's PLI scheme for active pharmaceutical ingredients is accelerating greenfield investments in cGMP-compliant equipment.
- Chemical Production:Catalyst drying and fine chemical processing demand nitrogen-recirculating architectures. REACH solvent emission thresholds are redirecting German chemical producers toward closed-loop system upgrades.
- Food Processing:Instant coffee and infant formula production prioritize uniform moisture distribution. Equipment here emphasizes cleanability over containment.
- Powder Coating:Industrial coating applications utilize standard hot air configurations without pharmaceutical-grade documentation burdens.
Pharmaceutical Manufacturing captures the highest margin tier. Chemical Production is climbing the fastest as solvent recovery mandates tighten.
End User:
Customer type dictates procurement sophistication: pharmaceutical companies unbundle validation from equipment purchase, while chemical firms bundle engineering and maintenance.
- Pharmaceutical Companies:Multinational manufacturers and CDMOs specify containment-capable systems with IQ/OQ documentation. Facilities in Ireland and Singapore lead multi-product facility investment.
- Chemical Firms:Fine chemical and catalyst producers prioritize throughput and energy recovery over validation complexity. German producers lead REACH compliance investment.
- Food Industry:Powder processors emphasize hygiene design and rapid product changeover. Infant formula manufacturers represent the most demanding subsegment.
- Research Institutions:Universities and national labs pilot novel drying configurations with minimal production scale requirements.
Pharmaceutical Companies anchor premium revenue. Chemical Firms are where volume expansion is steepest.
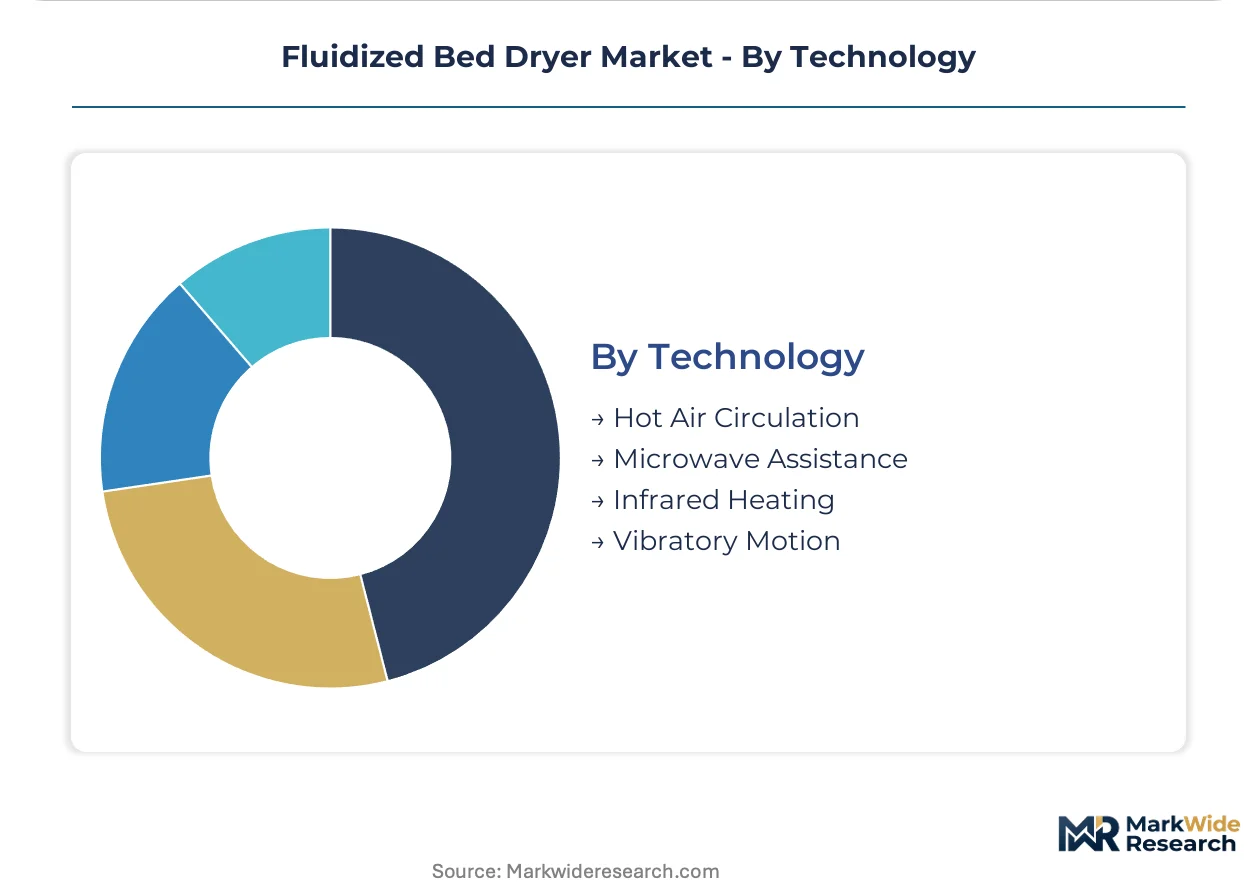
Technology:
Technology selection tracks thermal sensitivity of processed materials, with hybrid systems gaining traction where conventional hot air risks degradation.
- Hot Air Circulation:Convective drying with filtered air or nitrogen at 40-200°C retains the broadest installed base across all applications. Food powder processors and standard chemical operations default to this mature approach.
- Microwave Assistance:Hybrid configurations combine conventional airflow with microwave energy for rapid moisture removal without thermal degradation. Temperature-sensitive biologics and high-value APIs drive adoption where lyophilization costs prove prohibitive.
- Infrared Heating:Radiant energy transfer suits surface-sensitive coating applications with precise zone control.
- Vibratory Motion:Mechanical fluidization assistance handles cohesive or irregular particles that standard airflow cannot suspend uniformly.
Hot Air Circulation holds the largest installed base. Microwave Assistance is gaining share fastest in high-value pharmaceutical segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-heavy equipment fabricators in Germany and Switzerland balance trade surpluses against import-dependent pharmaceutical clusters in India and Singapore. Regional demand splits between REACH-driven European replacement cycles and PLI-scheme greenfield construction in Asia.
Germany
Pharmaceutical machinery clusters around Cologne and Düsseldorf concentrate cGMP-compliant batch dryer demand. EMA GMP Annex 15 validation requirements force legacy equipment retirement across Rhineland facilities. Chemical producers in the industrial corridor adopt continuous configurations with integrated solvent recovery to meet REACH emission thresholds.
United States
CDMO expansion in Massachusetts and North Carolina drives multi-product facility investment with containment-capable specifications. FDA cGMP guidelines shape equipment documentation burdens for suppliers targeting regulated markets. After-sales service unbundling is most pronounced in facilities with mature quality assurance functions.
India
Domestic API manufacturing incentives under the PLI scheme attract greenfield investments requiring validation-ready equipment. CDSCO alignment with ICH Q9 quality risk management principles accelerates equipment upgrades in Maharashtra and Gujarat. Pharmaceutical clusters in Hyderabad and Ahmedabad specify isolator-integrated systems for export-oriented production.
China
NMPA regulatory convergence with international standards reshapes equipment specification in Jiangsu and Zhejiang provinces. Domestic pharmaceutical producers upgrade from legacy hot-air systems to nitrogen-recirculating configurations. Fine chemical manufacturers in Shandong face solvent emission controls under MEE environmental enforcement.
Singapore
Contract manufacturing hub status attracts multi-product facilities requiring flexible dryer configurations. Research institutions and CDMOs specify pilot-scale units for formulation development with full-scale process mimicry. Regional headquarters of multinational pharmaceutical companies concentrate procurement decision-making for Southeast Asian operations.
Fluidized Bed Dryer Market Vendor Landscape
Listed leaders compete with private specialists across documentation and validation capabilities. The vendor base separates into three tiers: integrated process control providers, containment engineering specialists, and regional fabricators serving commodity applications. Strategic moves center on validation support unbundling and microwave-hybrid technology licensing rather than capacity expansion.
Within the integrated systems tier, Bühler Group and GEA Group exemplify archetypes combining process control with regulatory documentation capabilities. Glatt occupies a position representing hybrid coater-dryer architectures that reduce batch transfer losses. Among Chinese fabricators, Jiangsu Jinling Drying Technology sits within the regional specialist archetype serving domestic pharmaceutical and chemical producers with standardized configurations.
| Leading Market Players |
|---|
| Bühler Group |
| Lödige |
| GEA Group |
| DIOSNA |
| Romaco Group |
| Glatt |
| SPX FLOW |
| Jiangsu Jinling Drying Technology |
| Syntegon |
| Others |
Supply Flow & Price Mechanics
FDA cGMP and EMA GMP Annex 15 qualification requirements gate both supplier certification and price stratification across pharmaceutical-grade equipment tiers. Pharmaceutical buyers unbundle validation from hardware procurement, compressing margins on standalone dryer sales while elevating documentation-intensive service premiums. Stainless steel price volatility in 316L and 304 grades feeds directly into equipment cost structures, exposing fabricators to nickel and chromium commodity cycles.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium containment-integrated, standard cGMP-compliant, and economy hot-air configurations. Price differentiation rests on certification depth and isolator engineering complexity, with pharmaceutical CDMOs showing lowest sensitivity and commodity chemical processors most responsive to stainless steel cost passthrough. Cost compression in standard-tier batch units is intensifying as regional Chinese fabricators expand export capacity.
Supply Chain Analysis
Strategic stockpiling of distributor plates and precision-welded components dominates inventory posture among German and Italian fabricators facing extended lead times for 316L sheet metal. Supply concentrates in southern Germany and northern Italy for precision distributor plate manufacturing, with secondary sourcing from Swiss machining specialists. Single-source vulnerability in containment isolator engineering creates structural risk, while distribution runs through direct sales for continuous systems and regional distributors for batch and pilot configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment architecture is converging toward platform economics as integrated process control systems displace standalone dryer-coater combinations. Interoperability between dryer SCADA and plant-wide MES platforms is reshaping competitive moats around data integration rather than mechanical performance alone.
For Market Incumbents: Shield premium positioning through captive containment engineering capabilities as microwave-hybrid systems threaten thermal-efficiency differentiation. Backward integration into precision distributor plate manufacturing reduces exposure to Italian and German fabricator concentration. Investment in IQ/OQ documentation automation counters third-party validation unbundling.
For New Entrants and Emerging Players: Anchor in India's PLI-driven API manufacturing expansion, where greenfield facilities seek validation-ready equipment without incumbent service legacy. Target pilot-scale and mini dryer segments serving research institutions and startup API developers, where procurement cycles shorten and brand loyalty remains unformed. Lead with microwave-assisted technology licensing to bypass mechanical fabrication barriers.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across continuous dryer configurations as modular platform designs reduce custom engineering overhead. Acquisition focus should center on containment engineering specialists with isolator-integrated system portfolios and established FDA/EMA validation track records. Signal to monitor: REACH solvent emission threshold tightening accelerating nitrogen-recirculating system replacement cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Containment Engineering Acquisition | Isolator-integrated capabilities address potent compound handling requirements under tightening EMA guidelines. |
| Microwave-Hybrid Technology Licensing | Thermal-sensitive API processing opens high-margin pharmaceutical segments beyond conventional hot-air reach. |
| India PLI Scheme Facility Buildout | Domestic API manufacturing incentives create sustained equipment demand in Maharashtra and Gujarat clusters. |
| Validation Service Unbundling Response | Automated IQ/OQ documentation counters third-party specialist encroachment in North American markets. |
| Precision Component Backward Integration | Captive distributor plate manufacturing reduces vulnerability to southern German and northern Italian supply concentration. |
Methodological Framework
Desk research of customs trade databases, pharmaceutical machinery association directories, and regulatory filing repositories preceded structured interviews with plant engineers at API manufacturers, procurement leads at CDMOs, aftermarket service heads at equipment distributors, and technical R&D directors at containment engineering specialists. Primary intelligence combined with secondary validation against SEC filings of listed equipment suppliers and EMA GMP inspection databases. Bottom-up equipment shipment analysis triangulated against top-down pharmaceutical capital expenditure surveys.
Variance decomposition across product type, application vertical, technology configuration, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs derived from segmented growth rate modeling with cross-validation against industry association capacity expansion announcements. Forecast inputs incorporated REACH solvent emission compliance timelines and India's PLI scheme disbursement schedules.
Material uncertainties — stainless steel commodity price spikes, REACH threshold revisions, and NMPA enforcement intensity — sit outside the modeled envelope. Forecasts reflect assumptions regarding regulatory harmonization pace and CDMO facility commissioning schedules. Revision becomes warranted when containment standard divergence across FDA, EMA, and NMPA frameworks crosses thresholds affecting equipment specification commonality.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Oven Market
Food Processing Equipment
Nugget Ice Machines Market
Food Processing Equipment
Tea Processing Machine Market
Food Processing Equipment
Countertop Convection Oven Market
Food Processing Equipment
Electric Chicken Scalder Market
Food Processing Equipment
Griddle Market
Food Processing Equipment
Mobile Bottling Line Market
Food Processing Equipment
Commercial Oven for Bakery Market
Food Processing Equipment
Contact and Convective Dryers Market
Food Processing Equipment
Hot Food Processing Equipment Market
Food Processing Equipment
Edible Oil Extracting Machine Market
Food Processing Equipment
Aseptic Processing Equipment Market
Food Processing Equipment
Sword Feeders Market
Food Processing Equipment
Small Continuous Fryer Market
Food Processing Equipment
North America Food and Beverage Filling and Capping Machines Market
Food Processing Equipment
Used Commercial Freezer Market