
 Europe Household Food Waste Composting Machine Market | 2026-2036
Europe Household Food Waste Composting Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Household Food Waste Composting Machine Market Foresight
Germany's manufacturing base for domestic composting equipment is tilting toward automated in-vessel systems. Oklin International Ltd. leverages proprietary microbial acceleration chambers to differentiate its premium residential units. Food Cycle Science Corporation anchors North European distribution through direct-to-builder partnerships. Keter Group SA sustains volume leadership via injection-molded outdoor bin platforms with integrated aeration.
A household food waste composting machine is an electromechanical or passive biological processor designed to decompose organic kitchen refuse through controlled temperature, moisture, and oxygen regimes, typically achieving usable humus within 14 to 90 days depending on method. These devices serve the primary commercial purpose of diverting putrescible waste from municipal collection streams while producing soil amendments for domestic gardens or landscaping. In-vessel systems command the dominant share of replacement value due to sealed construction and accelerated cycle times, while worm composting occupies a narrower premium niche among organic gardening enthusiasts. The mechanical technology segment leads unit shipments across the analysis window, though biological processing configurations capture disproportionate margin pools through consumable additive subscriptions.
The EU Green Deal's waste framework directives, Germany's KrWG circular economy law, and France's AGEC anti-waste legislation collectively mandate separate organic collection or household-level processing, directly expanding addressable demand for certified domestic units. ECHA REACH compliance for plastics and electrical components constrains material sourcing, favoring suppliers with pre-validated component ecosystems. Stakeholders must monitor whether proposed EU-wide harmonized compostability standards will require hardware redesigns or open certification pathways for imported systems.
Market Dynamics
EU Green Deal waste hierarchy mandates and Germany's KrWG circular economy law amendments are compressing organic diversion timelines, forcing municipal fee structures and household procurement patterns toward accelerated on-site processing adoption.
Growth Catalysts
- France's AGEC Anti-Waste Legislation:Mandatory separate organic collection requirements in suburban single-family zones are expanding certified domestic unit demand. Municipal collection fee differentials in Benelux urban corridors accelerate payback calculations for residential buyers.
- Microbial Acceleration Chambers:Proprietary in-vessel biological processors with sealed construction and shortened cycle times command replacement value premiums. Automated temperature and moisture control regimes reduce user intervention requirements.
- German Packaging Law Amendments:Extended producer responsibility frameworks tighten organic waste diversion quotas for food retailers. This creates downstream pressure for household-level processing infrastructure.
Market Restraints
- ECHA REACH Compliance Costs:Pre-validated plastics and electrical component ecosystems constrain material sourcing flexibility. Suppliers without established compliance pathways face extended certification timelines.
- Substitution by Municipal Collection:Free or subsidized curbside organic pickup in dense urban cores reduces the economic case for household capital expenditure. Collection frequency improvements compress the odor-management advantage of on-site systems.
- Input Cost Volatility:Specialized microbial additive formulations and replacement filter media experience price instability. Consumable subscription models expose users to recurring cost uncertainty.
Strategic Opportunities
- Direct-to-Builder Partnerships:New construction integration in North European markets embeds composting infrastructure before occupancy. Developers capture green building certification points while locking in equipment specifications.
- EU Harmonized Compostability Standards:Proposed certification pathways for imported systems may open hardware redesign opportunities. Pre-compliant suppliers gain first-mover positioning in harmonized market access.
- Worm Comping Premium Niche:Organic gardening enthusiast segments demonstrate willingness to pay for biological processing configurations. Disproportionate margin pools from consumable additive subscriptions sustain specialist positioning.
Industry Challenges
- Technical Certification Timelines:Electrical safety and biological efficacy testing for in-vessel systems extends product launch schedules. Multiple national approval requirements fragment go-to-market sequencing.
- Integration Complexity with Legacy Waste Streams:Households with established separation habits require behavioral retraining for new processing interfaces. Contamination rates from non-compostable inputs degrade output quality and user satisfaction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Household Food Waste Composting Machine Market |
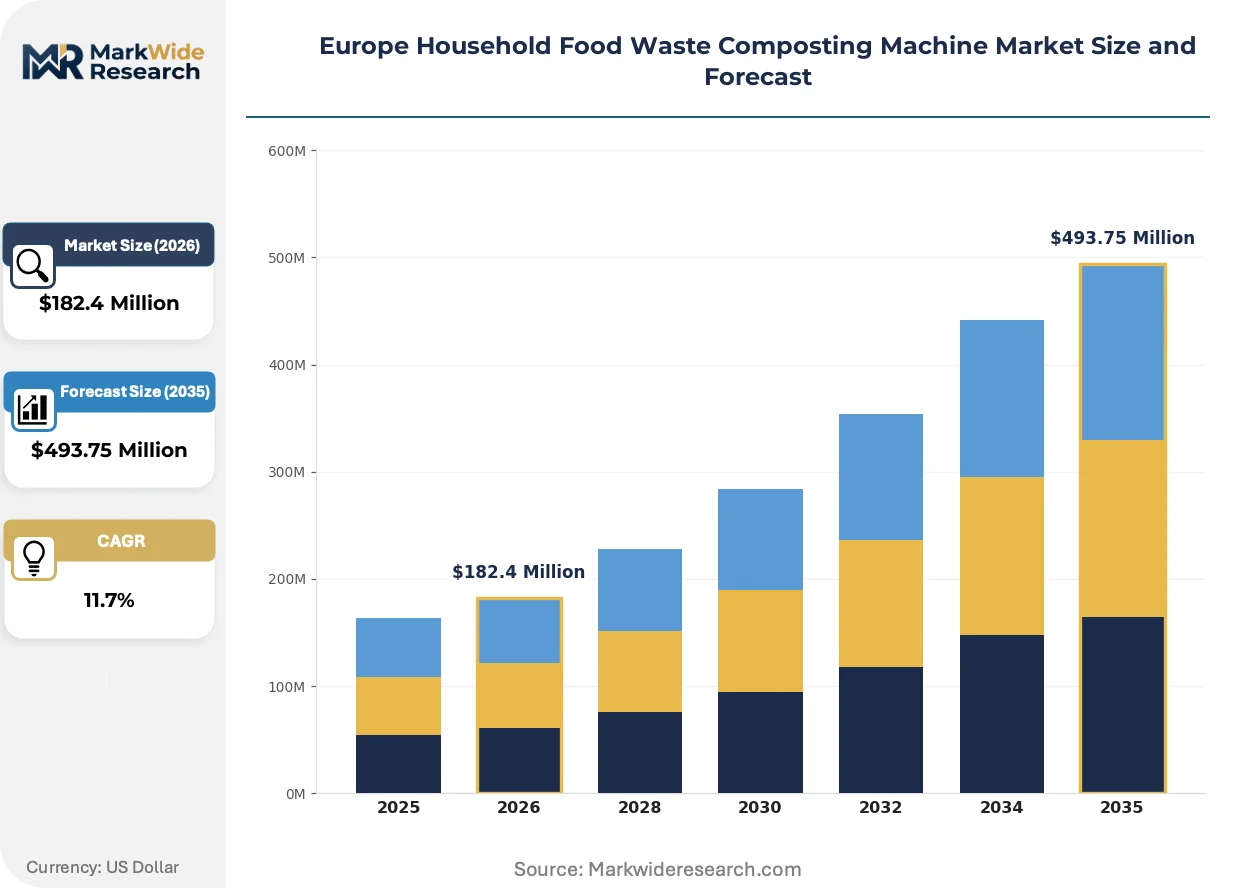
| Market Size in 2026 | $182.4 Million |
| Market Size in 2035 | $493.75 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: In-Vessel, Aerobic, Anaerobic, Worm Composting Technology: Organic Recycling, Mechanical, Thermal, Biological End User: Households, Restaurants, Cafes, Food Outlets Installation: Indoor, Outdoor, Portable, Fixed |
| Companies Covered | Oklin International Ltd., Food Cycle Science Corporation, HotBin Composting, Keter Group SA, Green Mountain Technologies Inc., Tidy Planet Limited, NatureMill Inc., Enviro World Corporation, Ridan Composting Ltd., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Household Food Waste Composting Machine Market Shifts & Advancements
Biological processing architectures and electromechanical control systems are converging to compress decomposition cycles while reducing energy intensity. Equipment design priorities are rotating toward silent operation and odor containment for indoor placement.
Automated in-vessel composting is migrating from outdoor utility placement to kitchen-adjacent installation. Urban apartment dwellers in Paris and Amsterdam corridors demand countertop-scale units with activated carbon filtration. This shift is compressing the addressable market definition from garden-owning households to all organic waste generators.
The EU Green Deal's waste framework directives are tightening separate organic collection mandates across member states. Industrial consequence includes hardware redesign requirements for interoperability with municipal processing standards. French and German markets exhibit the most aggressive compliance timelines, with certification bodies expanding testing capacity.
Builder procurement specifications are displacing retail channel dominance for new household formation. Direct partnerships with residential developers in Belgium and the Netherlands bypass traditional hardware retail markup structures. This channel rotation concentrates volume in project-based contracts with extended payment terms and installation service bundling.
Europe Household Food Waste Composting Machine Market Segmentation
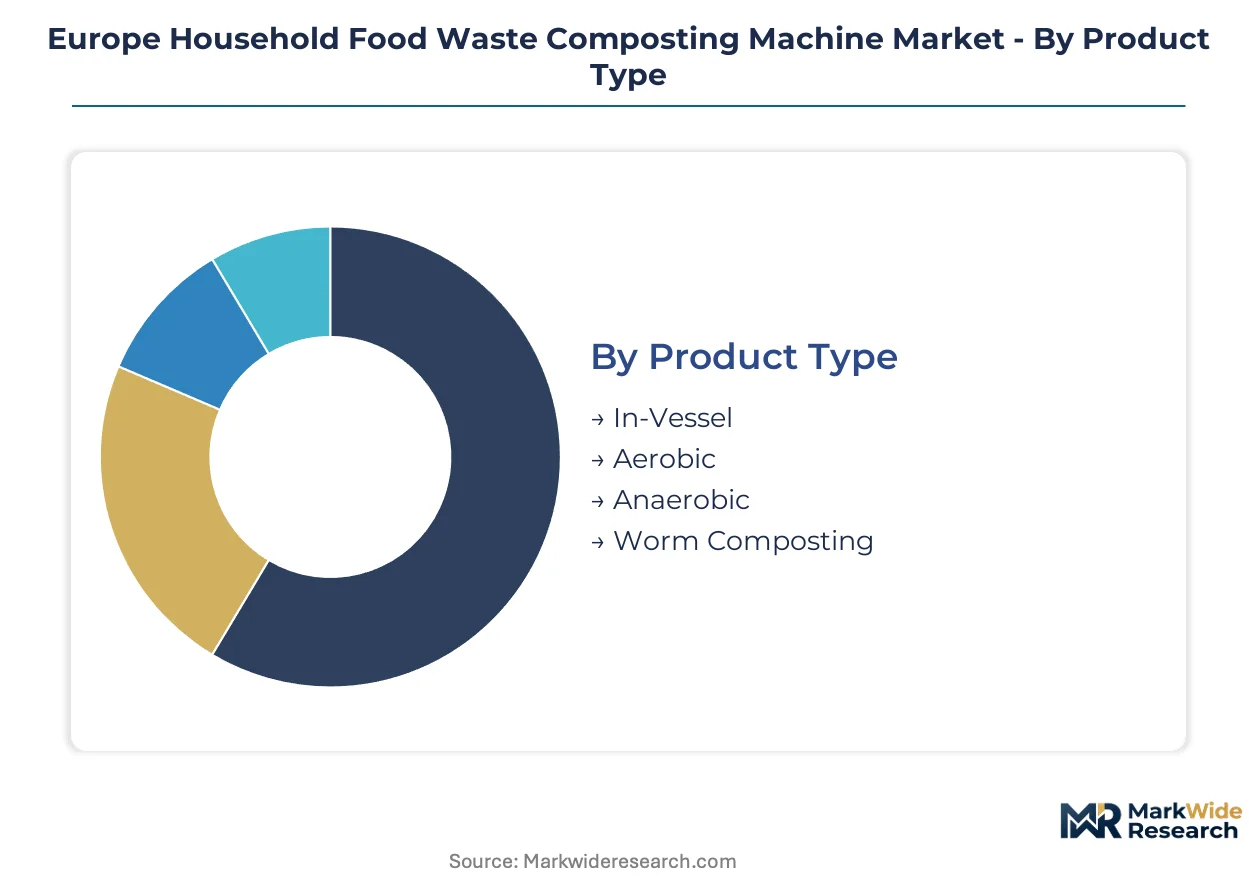
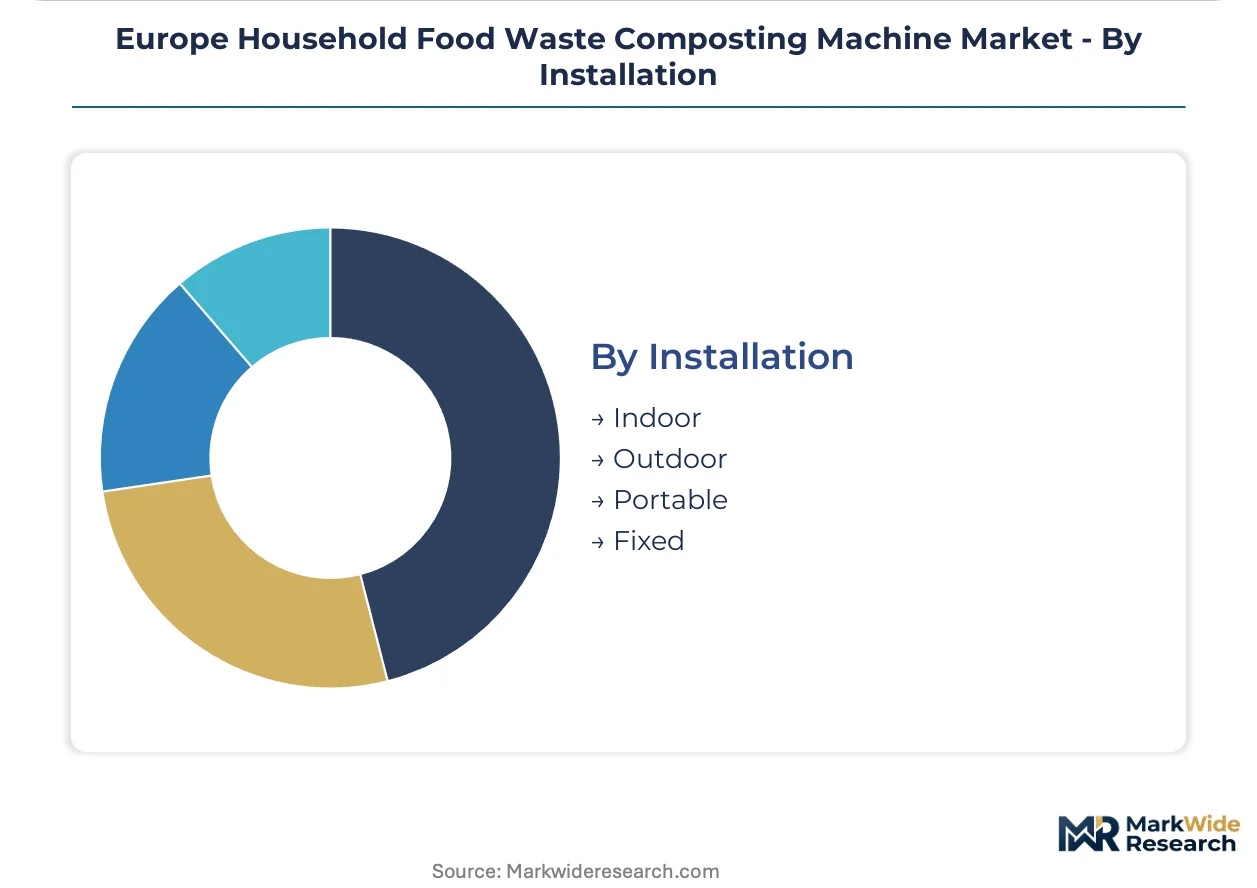
Segmentation reveals how composting machine specifications align with distinct user environments and waste processing requirements. Differentiation across product architecture, processing technology, and placement constraints shapes procurement patterns and margin structures across European markets.
Product Type:
Deployment contexts range from high-throughput suburban gardens to space-constrained urban kitchens, with each architecture carrying distinct maintenance and cycle time profiles.
- In-Vessel:Sealed electromechanical chambers with automated temperature and moisture control dominate suburban single-family installations in France. Benelux municipal fee differentials accelerate payback calculations for these premium units.
- Aerobic:Open or semi-enclosed systems relying on passive oxygen circulation and periodic turning serve cost-sensitive gardeners. German hobbyist segments favor these for established composting routines with lower capital outlay.
- Anaerobic:Oxygen-excluded digesters producing biogas precursors occupy narrow technical enthusiast niches. Netherlands pilot programs test domestic-scale units for grid-injection potential.
- Worm Composting:Vermiculture-based processors command premium positioning among organic gardening specialists. Consumable additive subscriptions sustain disproportionate margin pools for specialist suppliers.
Established volume favors In-Vessel; emerging adoption favors Worm Composting.
Technology:
Processing methodology determines energy intensity, decomposition velocity, and recurring revenue potential through consumable or service attachments.
- Mechanical:Shredding and aeration systems lead unit shipments across the analysis window. Automated blade configurations reduce particle size to accelerate microbial breakdown in Dutch and Belgian installations.
- Biological:Microbial inoculation and enzyme acceleration capture disproportionate margin pools through recurring additive subscriptions. French AGEC compliance timelines expand certified biological system demand.
- Thermal:Heat-assisted desiccation systems dehydrate waste prior to decomposition, compressing cycle times. Energy cost sensitivity limits penetration in markets with high electricity tariffs.
- Organic Recycling:Hybrid approaches combining mechanical pre-processing with biological finishing serve multi-waste-stream households. German KrWG diversion mandates create specification pull for flexible input tolerance.
Mechanical systems anchor current procurement volumes; Biological configurations climb the fastest on recurring revenue expansion.
End User:
User scale and waste composition intensity dictate capacity requirements, odor control specifications, and regulatory compliance obligations.
- Households:Single-family suburban zones in France represent the fast-expanding adopter segment. EU Green Deal waste hierarchy targets tighten organic diversion mandates for residential generators.
- Restaurants:Commercial food service operations face extended producer responsibility pressure under German packaging law amendments. High-volume organic streams justify capital-intensive automated systems.
- Cafes:Smaller food service footprints with limited back-of-house space demand compact countertop units. Paris and Amsterdam urban corridors drive indoor-placement specification requirements.
- Food Outlets:Retail grocery and prepared food retailers manage packaged and unpackaged organic waste streams. Separate collection mandates in Benelux accelerate on-site processing adoption.
Households concentrate absolute unit demand; Restaurants gain share fastest on regulatory compliance pressure.
Installation:
Placement constraints determine form factor, noise suppression, and filtration engineering priorities across housing typologies.
- Outdoor:Garden-adjacent utility placement accommodates larger capacity and passive aeration designs. Suburban French and German single-family zones sustain this traditional configuration.
- Indoor:Kitchen-integrated units with activated carbon filtration and silent operation respond to apartment dweller demand. Paris and Amsterdam corridors lead specification for countertop-scale systems.
- Portable:Relocatable designs with wheeled bases or modular construction serve rental households and seasonal users. Flexibility premiums attract urban transient populations.
- Fixed:Permanent installation with hard utility connections dominates new construction integration. Belgian and Dutch direct-to-builder partnerships embed these specifications before occupancy.
Outdoor placement retains volume leadership; Indoor installation expands most quickly on urban densification trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal waste hierarchy mandates anchor demand concentration across European markets. Germany's KrWG circular economy law and France's AGEC anti-waste legislation compress organic diversion timelines. Municipal collection fee structures in Benelux urban corridors accelerate household payback calculations for on-site processing equipment.
Germany
Single-family suburban zones in Bavaria and Baden-Württemberg drive in-vessel system adoption. The KrWG circular economy law amendments tighten organic waste diversion quotas for food retailers. Stuttgart's manufacturing base tilts toward automated electromechanical chambers with sealed construction.
France
Suburban single-family households represent the fastest-expanding adopter segment for certified domestic units. The AGEC anti-waste legislation mandates separate organic collection requirements in residential zones. The Paris metropolitan corridor demands countertop-scale indoor systems with activated carbon filtration.
Netherlands
Municipal collection fee differentials accelerate payback calculations for residential buyers in Randstad urban corridors. Extended producer responsibility frameworks under EU Green Deal directives tighten compliance timelines. Eindhoven's builder partnerships embed fixed-installation specifications in new construction.
Belgium
Direct-to-developer procurement channels displace traditional hardware retail for household formation. Benelux organic diversion mandates create specification pull for flexible input tolerance systems. Brussels-Antwerp-Ghent corridor concentrates project-based contracts with installation service bundling.
United Kingdom
Hobbyist gardeners in Southeast England favor aerobic systems with passive oxygen circulation. Post-Brexit regulatory divergence creates certification pathway uncertainty for imported equipment. London's apartment dwellers drive demand for silent-operation indoor units with odor containment engineering.
Europe Household Food Waste Composting Machine Market Competitive Landscape
Capability concentration sits with electromechanical specialists; scale advantage sits with injection-molded outdoor bin fabricators. The vendor base spans three tiers: premium in-vessel automation, mid-market passive aeration, and entry-level aerobic bins. Strategic archetypes include microbial acceleration chamber developers, direct-to-builder partnership specialists, and consumable additive subscription operators. Competitive moves center on certification pre-compliance for EU harmonized standards and backward integration into validated plastics supply chains.
Within the microbial acceleration tier, Oklin International Ltd. and Food Cycle Science Corporation exemplify proprietary biological processing configurations. Keter Group SA anchors the volume-driven injection-molded segment. These three entities occupy distinct positioning vectors: electromechanical premium, North European distribution partnership, and outdoor utility platform scale respectively.
| Leading Market Players |
|---|
| Oklin International Ltd. |
| Food Cycle Science Corporation |
| HotBin Composting |
| Keter Group SA |
| Green Mountain Technologies Inc. |
| Tidy Planet Limited |
| NatureMill Inc. |
| Enviro World Corporation |
| Ridan Composting Ltd. |
| Others |
Supply & Pricing Matrix
ECHA REACH compliance bottlenecks for pre-validated plastics and electrical components compress both pricing tier spreads and supplier flexibility, forcing manufacturers toward captive sourcing or premium tier positioning to recover certification cost burdens.
Pricing Analysis
German in-vessel systems command 40-60% premiums over Benelux-sourced aerobic bins due to automated chamber engineering and sealed construction. Three-tier pricing structure across premium automated, standard passive, and economy aerobic levels stratifies by certification grade and after-sales service bundling. Cost compression in the economy tier is intensifying because municipal collection improvements reduce odor-management value capture. Single-family suburban households in France exhibit highest price sensitivity; organic gardening specialists purchasing worm composting systems show lowest sensitivity due to consumable subscription lock-in.
Supply Chain Analysis
Tariff exposure between Chinese injection-molded component suppliers and EU assembly facilities dominates supply chain risk planning for outdoor bin manufacturers. Manufacturing gravity centers on Germany for electromechanical chambers, Netherlands for builder-integrated fixed installations, and Belgium for distribution hub consolidation. Raw material dependencies span REACH-compliant ABS plastics, microbial inoculant formulations, and activated carbon filtration media. Single-source vulnerability concentrates in specialized microbial additive suppliers. Distribution runs through direct-to-builder partnerships in Belgium and Netherlands, bypassing traditional hardware retail markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across urban apartment, suburban single-family, and commercial food service segments creates specialist niches as indoor countertop specifications diverge sharply from outdoor garden utility placement.
For Market Incumbents: Harden certification pre-compliance positions against EU harmonized compostability standards to capture first-mover hardware redesign contracts. Deepen backward integration into validated plastics supply chains to neutralize ECHA REACH timeline risks. Lock direct-to-builder partnerships in Randstad and Brussels-Antwerp-Ghent corridors before channel consolidation accelerates. For New Entrants and Emerging Players: Southeast England hobbyist gardeners represent the most penetrable white-space target given post-Brexit certification pathway uncertainty delaying incumbent entry. Paris and Amsterdam apartment dwellers demand countertop-scale indoor units with silent operation engineering absent from current portfolios. Enter through consumable additive subscription models to capture recurring revenue pools in the worm composting premium niche. For Investors and Strategic Acquirers: The market sits at a regulatory acceleration phase that favors microbial acceleration chamber developers with proprietary IP and established CE marking pathways. Long-term viability over a 5-10 year window rests on EU Green Deal mandate expansion beyond current member state fragmentation. Target acquisition archetype: mid-cap electromechanical specialists with pre-validated component ecosystems. Watch ECHA REACH enforcement intensity as the inflection signal for supply chain restructuring premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Validated Plastics | ECHA REACH compliance timelines compress for suppliers with captive pre-certified polymer sourcing from German compounders. |
| Direct-to-Builder Partnership Expansion | Belgian and Dutch developers embed fixed-installation specifications before occupancy, locking out retail channel competitors. |
| Microbial Additive Subscription Launch | Biological processing configurations capture disproportionate margin pools through recurring revenue lock-in among gardening enthusiasts. |
| Indoor Countertop Product Line Extension | Paris and Amsterdam apartment demand for kitchen-adjacent placement with activated carbon filtration outpaces outdoor utility supply. |
| EU Harmonized Standards Pre-Compliance | Certification pathway readiness positions suppliers for hardware redesign contracts under proposed EU-wide compostability mandates. |
Research Methodology
The analysis maps in-vessel automated, aerobic passive, worm composting, and anaerobic digester sub-sectors, each validated through product managers at electromechanical manufacturers, procurement leads at residential developers, regulatory affairs specialists at certification bodies, and channel partners at hardware distributors. Primary interview findings triangulate against EU Green Deal directive texts, ECHA REACH substance database entries, French AGEC implementation decrees, German KrWG amendment tracking, and Benelux municipal waste fee schedules. Bottom-up unit shipment modeling from named supplier bill-of-materials reconciles with top-down addressable household calculations across suburban and urban typologies.
Assumptions held fixed include current EU member state regulatory fragmentation and ECHA enforcement intensity; varied conditions span municipal collection fee differential persistence and builder partnership channel share capture. The projection framework segments by product architecture, processing technology, end-user scale, and installation placement constraints across the analysis window. CAGRs derive from logistic adoption curve fitting against organic diversion mandate phase-in schedules. Forecast inputs incorporate microbial additive pricing volatility and injection-molded resin cost pass-through elasticity.
The forecast holds incumbent behavior within observed patterns; aggressive certification pre-investment by emerging Asian manufacturers or accelerated EU harmonization would shift volume concentration timelines. Continuous validation against municipal procurement contract awards and builder specification releases is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Pasty Products Filling Machine Market
Food Processing Equipment
Conveyor Ovens and Impinger Ovens Market
Food Processing Equipment
Tea Processing Equipment Market
Food Processing Equipment
Craft Beer Saccharification Equipment Market
Food Processing Equipment
Food Recycling Machines Market
Food Processing Equipment
North America Ginger Processing Market
Food Processing Equipment
Countertop Convection Oven Market
Food Processing Equipment
Food-Grade Mixing Tank Market
Food Processing Equipment
Ice Cream Freezer Market
Food Processing Equipment
Deaeration Machine Market
Food Processing Equipment
Deep Fryer Market
Food Processing Equipment
Coffee Processing Machine Market
Food Processing Equipment
Nut Processing Machine Market
Food Processing Equipment
Food Processing Equipment Market
Food Processing Equipment
Air Cooled Cube Ice Machines Market
Food Processing Equipment
Fish Cutting Machine Market