
 Smart Food Machine Market | 2026-2036
Smart Food Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Food Machine Market Insights
Cloud kitchen proliferation is realigning demand toward compact, networked cooking systems. Bühler AG leverages its milling and processing heritage to dominate industrial-scale smart food equipment. GEA Group AG anchors European commercial kitchen automation through thermal processing specialization. Tetra Laval International S.A. competes across packaging-integrated food lines with dairy and beverage focus.
Smart food machines encompass sensor-equipped, network-connected appliances that automate cooking, processing, and preservation tasks through programmable temperature control, precision timing, and remote monitoring protocols. These systems integrate IoT modules and AI-driven recipe algorithms to reduce human intervention while maintaining consistency across high-volume foodservice operations. The product type dimension shows smart ovens capturing margin pools in premium commercial segments, while multi-cookers expand fastest through household penetration. Technology segmentation reveals AI-powered systems commanding price premiums through predictive maintenance and adaptive cooking profiles, whereas touchscreen interface variants sustain volume leadership in cost-sensitive institutional procurement.
The FDA enforces food contact material safety and sanitation standards that shape equipment design requirements for US commercial deployments. EFSA and CE marking frameworks govern European market access, with REACH compliance adding material disclosure obligations for connected device components. Stakeholders must monitor evolving cybersecurity mandates for IoT-enabled kitchen infrastructure as regulators extend digital product safety rules into foodservice equipment categories.
Market Dynamics
Labor cost compression across US quick-service restaurant chains is accelerating capital deployment toward automated kitchen infrastructure, while FDA Food Safety Modernization Act monitoring mandates force equipment replacement cycles.
Growth Catalysts
- Cloud kitchen proliferation:Ghost restaurant formats in the United States demand compact, networked cooking systems that minimize footprint while maximizing throughput across distributed locations.
- FSMA monitoring mandates:FDA automated monitoring requirements for temperature logging and hazard analysis are compelling commercial foodservice operators to upgrade legacy equipment.
- AI-driven predictive maintenance:Machine learning algorithms embedded in smart ovens reduce downtime through component failure forecasting, attracting premium commercial segment buyers.
Market Restraints
- Stainless steel input volatility:Food-grade 304 and 316 stainless steel price swings compress equipment margins and complicate long-term contract pricing for manufacturers.
- IoT component supply concentration:Sensor module and wireless chipset sourcing concentrates in East Asian manufacturing clusters, exposing lead time risks to North American and European assemblers.
- Interoperability limitations:Absence of unified kitchen equipment communication protocols forces costly custom integration work for multi-vendor deployments.
Strategic Opportunities
- India cloud kitchen expansion:FSSAI compliance requirements and urban delivery density create demand for compact, certification-ready smart cooking systems in Mumbai and Bangalore.
- EU AI Act alignment:European automated kitchen equipment vendors can capture premium positioning by certifying AI-driven recipe algorithms under emerging EU artificial intelligence product liability frameworks.
- Subscription-based equipment access:Equipment-as-a-service models reduce upfront capital barriers for independent restaurant operators while locking in recurring revenue streams for manufacturers.
Industry Challenges
- Mechatronics technician scarcity:Shortage of technicians capable of servicing sensor-integrated thermal processing equipment extends repair timelines and elevates service costs for operators.
- CE marking certification delays:Extended EFSA material safety review timelines for novel food-contact coatings slow European product launches and compress competitive windows.
- Legacy kitchen infrastructure integration:Retrofitting IoT-enabled equipment into existing ventilation and power configurations requires costly site-specific engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Food Machine Market |
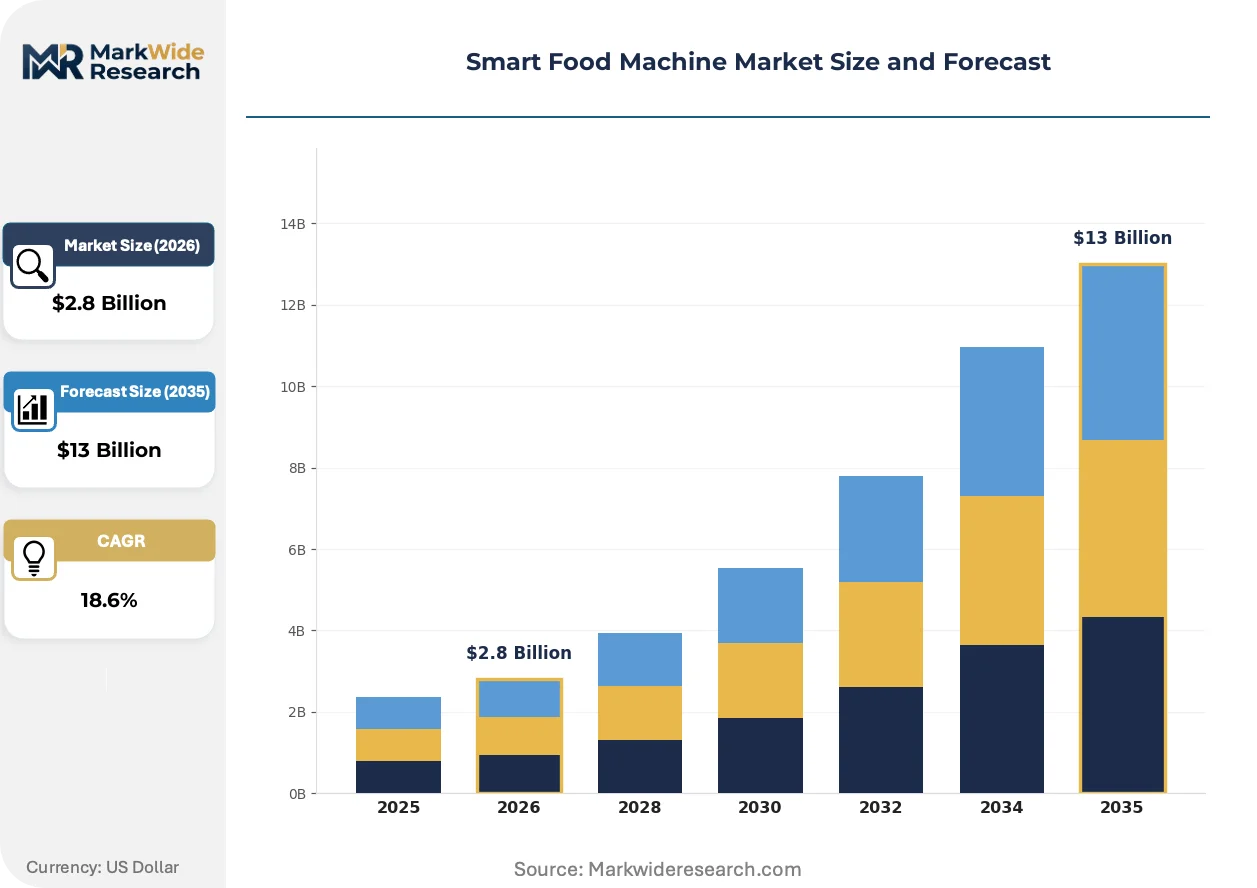
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $13 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic Cookers, Food Processors, Smart Ovens, Multi-Cookers Technology: IoT, AI-Powered, Voice Control, Touchscreen Interface End User: Households, Restaurants, Catering Services, Institutions Application: Meal Preparation, Food Preservation, Cooking Assistance, Recipe Management |
| Companies Covered | Schneider Electric SE, Rockwell Automation Inc., Emerson Electric Company, ABB Limited, GEA Group AG, Tetra Laval International S.A., John Bean Technologies Corporation, Bühler AG, GE Appliances, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Food Machine Market Trends and Innovations
Smart food equipment is evolving from isolated appliances toward orchestrated kitchen systems where data flows drive operational decisions. Three developments are compressing development cycles and redrawing competitive boundaries.
Computer vision systems for real-time food doneness detection are converging with cloud-based recipe libraries to enable autonomous cooking adjustments. Fine-dining and fast-casual chains in the United States are piloting these systems to reduce training dependency and plate inconsistency. This convergence is compressing the performance gap between high-skill kitchen labor and automated equipment.
EU F-Gas Regulation phase-down schedules are forcing refrigerant transitions in smart preservation equipment, accelerating R&D investment in CO2 and hydrocarbon-based thermal systems. European commercial kitchen operators face compliance deadlines that compress replacement cycles for reach-in refrigerators and blast chillers. German and French foodservice distributors are prioritizing equipment portfolios that anticipate 2027 refrigerant availability constraints.
Centralized procurement consortia among US hospital and university foodservice operators are consolidating vendor relationships and demanding outcome-based performance guarantees. Group purchasing organizations now specify uptime thresholds and energy efficiency benchmarks in equipment contracts. This concentration is most visible in California and Texas healthcare systems, where multi-facility standardization mandates favor vendors with national service networks.
Smart Food Machine Market Segmentation
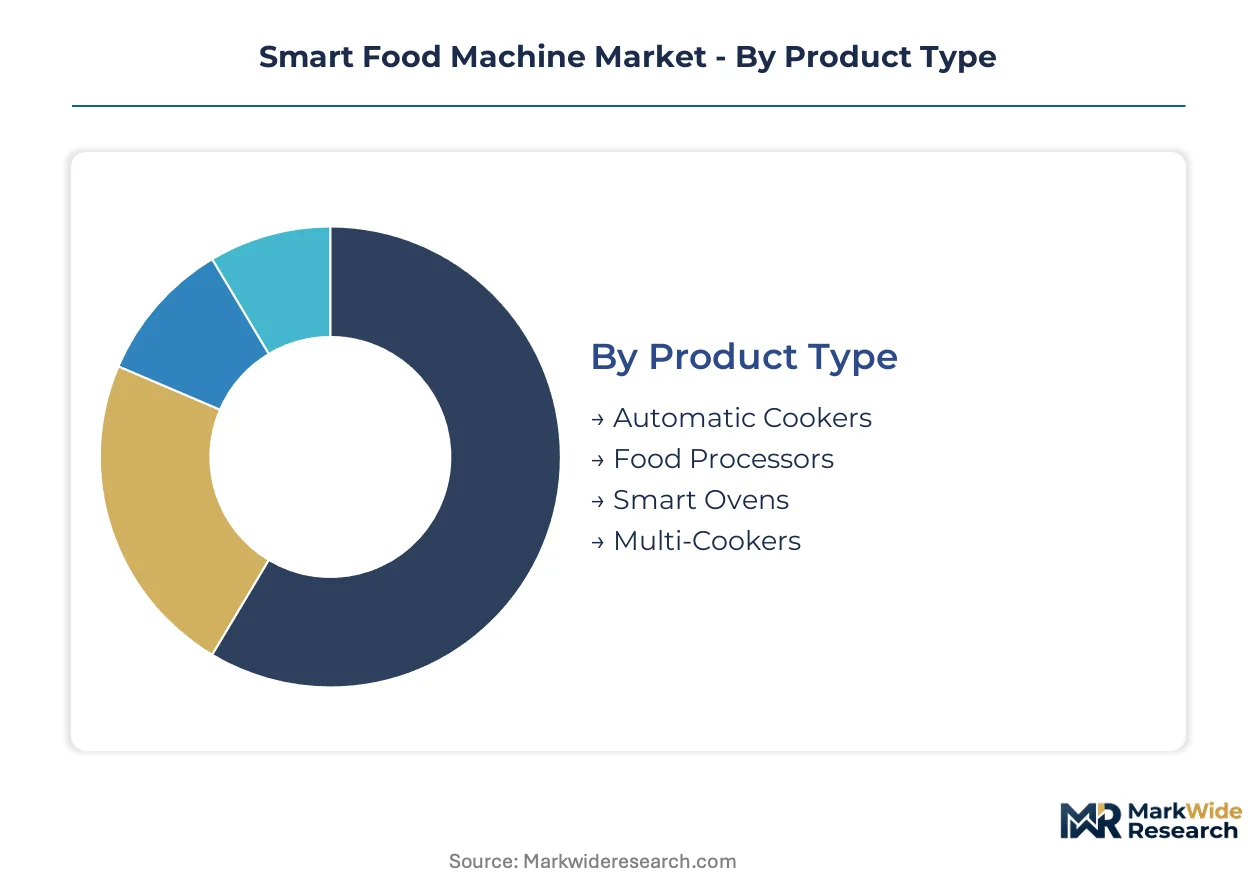
Smart food machine segmentation reveals divergent performance profiles across hardware form factors and intelligence layers. Equipment buyers prioritize different capability bundles depending on operational scale and regulatory exposure, fragmenting vendor go-to-market approaches.
Product Type:
Volume leadership concentrates in compact, multi-function appliances while premium margins flow toward specialized thermal systems with precision controls.
- Smart Ovens:Sensor-integrated thermal chambers with programmable humidity and convection profiles command price premiums in commercial bakery and quick-service deployments. FDA Food Safety Modernization Act temperature logging mandates accelerate replacement cycles across US restaurant chains seeking automated HACCP compliance.
- Multi-Cookers:Pressure-sealed vessels combining sauté, steam, and slow-cook functions in single footprints penetrate fastest through household channels and cloud kitchen formats. Urban delivery density in Mumbai and Bangalore drives compact equipment demand where kitchen square footage commands premium rents.
- Automatic Cookers:Rice and grain-specific appliances with fuzzy logic temperature modulation serve institutional procurement in Asian education and healthcare facilities.
- Food Processors:Motor-driven cutting and mixing systems with interchangeable blade arrays anchor commercial prep line configurations in European catering operations.
Today's leader: Smart Ovens. Tomorrow's challenger: Multi-Cookers.
Technology:
Interface modality and connectivity architecture determine equipment cost tiers and integration complexity for foodservice operators.
- AI-Powered:Machine learning modules enabling predictive maintenance and adaptive recipe calibration attract premium commercial buyers. Component failure forecasting reduces downtime in high-throughput US hospital and university foodservice operations where uptime thresholds are contractually specified.
- Touchscreen Interface:Capacitive glass panels with icon-driven menu navigation sustain volume leadership in cost-sensitive institutional procurement. California and Texas healthcare group purchasing organizations standardize on these variants for multi-facility equipment parity.
- IoT:Wireless sensor networks enabling remote monitoring and cloud-based recipe libraries support distributed ghost kitchen management.
- Voice Control:Speech-activated command interfaces reduce surface contact in hygiene-critical food preparation environments.
Touchscreen variants dominate current procurement volumes. AI-powered systems are climbing the fastest as predictive capabilities mature.
End User:
Operational scale and capital availability shape equipment specification requirements across buyer categories.
- Restaurants:Full-service and quick-service operators deploy networked cooking systems to compress labor costs and standardize output across locations. Labor cost pressure across US quick-service chains accelerates automated kitchen infrastructure deployment.
- Households:Residential buyers prioritize countertop footprint and single-appliance versatility over throughput metrics. Cloud kitchen proliferation in dense urban markets indirectly influences consumer expectations for compact, multi-function equipment.
- Catering Services:Mobile and event-based food operators require portable, rapid-deployment thermal systems with generator-compatible power profiles.
- Institutions:Hospital, university, and correctional foodservice operators centralize procurement through group purchasing organizations demanding outcome-based performance guarantees.
Restaurants anchor commercial revenue. Institutions are expanding most quickly through consolidated procurement mandates.
Application:
Functional use case determines sensor configuration, software stack, and regulatory compliance requirements for equipment deployments.
- Meal Preparation:Automated chopping, mixing, and portioning systems reduce prep labor in high-volume commercial environments. EFSA material safety standards for food-contact coatings shape European equipment design requirements.
- Cooking Assistance:Real-time temperature guidance and automated doneness detection bridge skill gaps in training-constrained kitchens. Computer vision pilots in US fine-dining and fast-casual chains compress performance gaps between high-skill labor and automated equipment.
- Food Preservation:Smart refrigeration and blast chilling systems with automated temperature logging support FDA FSMA hazard analysis requirements. EU F-Gas Regulation phase-down schedules force refrigerant transitions in CO2 and hydrocarbon-based thermal systems.
- Recipe Management:Cloud-based libraries and automated ingredient scaling standardize output across distributed locations and operator skill levels.
Meal Preparation commands current equipment spend. Cooking Assistance is gaining share fastest as computer vision capabilities mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud kitchen clusters in the United States are compressing equipment replacement cycles as ghost restaurant formats demand networked, compact thermal systems. Labor cost pressures and FDA Food Safety Modernization Act mandates are accelerating capital deployment toward automated kitchen infrastructure across major metropolitan markets.
United States
Quick-service restaurant chains in Dallas, Houston, and Atlanta are deploying sensor-integrated cooking systems to offset wage compression. FDA automated temperature logging requirements under FSMA are compelling operators to retire legacy equipment ahead of depreciation schedules. Chicago and Los Angeles cloud kitchen concentrations drive demand for footprint-optimized multi-cookers.
Germany
Commercial kitchen operators in Munich and Hamburg face EU F-Gas Regulation deadlines forcing refrigerant transitions in smart preservation equipment. CE marking and EFSA material safety reviews shape equipment procurement specifications. Baden-Württemberg industrial fabricators are scaling CO2-based thermal system production for 2027 compliance windows.
China
Urban delivery density in Shanghai and Shenzhen is expanding ghost kitchen deployments requiring compact, high-throughput automated cooking lines. National food safety regulators are tightening automated monitoring requirements for commercial foodservice operations. Guangdong Province manufacturing clusters are integrating IoT modules into thermal processing equipment for domestic and export markets.
India
FSSAI compliance mandates and Mumbai-Bangalore cloud kitchen proliferation are creating demand for certification-ready compact cooking systems. Urban real estate costs in Delhi-NCR and Hyderabad are compressing kitchen footprints and favoring multi-function appliances. Maharashtra and Karnataka foodservice operators are standardizing on networked equipment to manage distributed delivery locations.
Japan
Hospital and university foodservice operators in Tokyo and Osaka are consolidating procurement through group purchasing organizations demanding uptime guarantees. METI energy efficiency standards are shaping smart equipment specifications for institutional buyers. Kanto region commercial kitchen renovations are integrating AI-driven predictive maintenance modules to reduce technician dependency.
Smart Food Machine Market Competitive Landscape
Strategic partnerships dominate the current landscape as equipment vendors align with automation technology providers and cloud kitchen operators. The market exhibits tiered concentration with industrial-scale thermal processing specialists, diversified industrial automation conglomerates, and compact appliance specialists occupying distinct competitive positions. Three archetypes define the field: heritage food processing equipment houses, diversified industrial automation platforms, and emerging connected appliance specialists. Geographic expansion into high-growth cloud kitchen markets and technology licensing for AI-driven cooking algorithms represent the dominant competitive vectors.
Within the heritage processing equipment tier, Bühler AG and GEA Group AG exemplify European industrial-scale specialization, while Tetra Laval International S.A. anchors packaging-integrated system architecture. Among diversified automation platforms, Schneider Electric SE and Rockwell Automation Inc. occupy positions bridging industrial control systems with foodservice equipment integration. These groupings illustrate how competitive positioning fragments across thermal processing heritage, automation platform breadth, and packaging integration depth rather than concentrating around any single capability set.
| Leading Market Players |
|---|
| Schneider Electric SE |
| Rockwell Automation Inc. |
| Emerson Electric Company |
| ABB Limited |
| GEA Group AG |
| Tetra Laval International S.A. |
| John Bean Technologies Corporation |
| Bühler AG |
| GE Appliances |
| Others |
Pricing and Supply Chain Analysis
US hospital and university group purchasing organization consolidation is forcing equipment vendors to absorb certification and service bundling costs, compressing margins and accelerating sourcing shifts toward East Asian component suppliers.
Pricing Analysis
Stainless steel input cost pass-through dominates equipment pricing, with food-grade 304 and 316 alloy volatility forcing manufacturers into quarterly price adjustment clauses. Three-tier pricing structure across premium AI-powered, standard touchscreen, and economy non-connected tiers separates buyers by certification requirements and predictive maintenance capability. Pricing pressure stems from cloud kitchen procurement concentration demanding volume discounts for multi-location deployments. Independent restaurant operators exhibit highest price sensitivity, while institutional buyers prioritize uptime guarantees over unit cost.
Supply Chain Analysis
Container freight rate volatility from East Asian manufacturing hubs to North American assembly plants is elevating landed cost uncertainty for sensor modules and wireless chipsets. Component manufacturing concentrates in China, South Korea, and Taiwan, while final equipment assembly localizes in Germany, the United States, and India to satisfy regional certification requirements. Food-grade stainless steel, IoT sensors, and thermal control systems constitute critical input dependencies. Single-source vulnerability in semiconductor-grade sensor fabrication exposes lead time risks. Distribution runs through authorized dealer networks serving commercial foodservice operators and direct procurement consortia for institutional buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Smart Food Machine Market functions as a regulatory compounder where FDA Food Safety Modernization Act automated monitoring mandates are creating forced replacement demand across US commercial foodservice infrastructure.
For Market Incumbents: Lock in cloud kitchen operator relationships through equipment-as-a-service subscription models that reduce upfront capital barriers and capture recurring revenue streams. Defend against emerging connected appliance specialists by deepening backward integration into IoT sensor module sourcing and securing exclusive thermal processing algorithm licensing from European industrial heritage partners. For New Entrants and Emerging Players: AI-driven predictive maintenance algorithms offer the most penetrable wedge for displacing legacy touchscreen-dominant vendors in US hospital and university foodservice procurement. Target India cloud kitchen expansion in Mumbai and Bangalore where FSSAI compliance requirements favor certification-ready compact equipment over established Western brands. Pursue white-label manufacturing partnerships with Guangdong Province fabricators to accelerate cost-competitive product launches. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale automation technology providers possessing FDA-validated temperature logging software and established service networks in California and Texas healthcare systems. Five-to-ten year viability hinges on regulatory compliance durability rather than hardware differentiation alone. Monitor EU AI Act certification timelines for AI-driven recipe algorithms as an inflection signal for premium positioning capture in European commercial kitchen markets.| Strategic Initiative | Industry Significance |
|---|---|
| Equipment-as-a-Service Subscription Launch | Reduces upfront capital barriers for independent restaurant operators while locking in recurring revenue streams. |
| AI Algorithm Certification Under EU AI Act | Captures premium positioning in European commercial kitchen markets ahead of competitor compliance timelines. |
| Backward Integration into Sensor Module Sourcing | Mitigates East Asian supply concentration risk and secures component availability for predictive maintenance systems. |
| Cloud Kitchen Operator Partnership Expansion | Aligns equipment portfolios with Mumbai and Bangalore urban delivery density growth and FSSAI compliance requirements. |
| Predictive Maintenance Software Licensing | Monetizes machine learning capabilities through recurring fees from US hospital and university foodservice operators. |
Research Methodology
Multiple input streams — primary interviews with commercial kitchen operators, equipment procurement managers, and foodservice technology integrators, combined with secondary validation against FDA FSMA guidance documents, EFSA material safety registrations, and SEC equipment manufacturer filings — were reconciled through bottom-up and top-down triangulation.
Historical shipment data cross-referenced against expert panel inputs on cloud kitchen deployment timelines and regulatory compliance windows anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, technology layer, end-user category, and application function, with CAGRs derived from curve-fitting against replacement cycle acceleration patterns and urban delivery density growth trajectories.
The model holds under stable regulatory enforcement intensity and continued labor cost compression in US quick-service restaurant chains; deviation in FDA inspection prioritization or stainless steel price volatility would shift equipment replacement timing. Stakeholders should weight assumptions against their own operating context and regional regulatory exposure.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Global Food and Beverage Coding and Marking Equipment Market
Food Processing Equipment
Cook Processor Market
Food Processing Equipment
Multiple Unit Pellet Systems Market
Food Processing Equipment
Freezers Market
Food Processing Equipment
Insect Protein Processing Equipment Market
Food Processing Equipment
Conveyor Ovens and Impinger Ovens Market
Food Processing Equipment
Electric Chicken Scalder Market
Food Processing Equipment
Pet Food Extrusion Market
Food Processing Equipment
Cookers and Ovens Market
Food Processing Equipment
Used Commercial Freezer Market
Food Processing Equipment
Blast Chillers Market
Food Processing Equipment
Cake Cutting Machines Market
Food Processing Equipment
Softgel Encapsulation Machine Market
Food Processing Equipment
Shrimp Peeling Machine Market
Food Processing Equipment
Walk-In Refrigerator Market
Food Processing Equipment
Global Non Thermal Processing Market