
 Pasta Machine Market | 2026-2036
Pasta Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Pasta Machine Market Analytics
Commercial kitchens is restructuring equipment procurement across the pasta machine industry as fresh pasta menus expand in casual dining and fast-casual chains. Bühler Group leverages its industrial-scale extrusion technology to anchor supply relationships with large foodservice operators. FATA S.p.A. competes through specialized long-cut pasta systems that dominate traditional Italian-format production lines. GEA Group extends its hygiene-engineering expertise into clean-in-place designs that sustain premium positioning among European processors.
A pasta machine is a mechanical device designed to mix, extrude, laminate, cut, or shape dough into pasta forms, operating through roller pairs with gap adjustments from 0.5 mm to 5 mm and extrusion pressures reaching 80–120 bar for industrial units. Electric models command the largest installed base due to throughput advantages in restaurants and commercial kitchens, while manual units retain margin pools among artisan producers and culinary enthusiasts seeking texture control. Stainless steel construction leads material preference because of durability and regulatory compliance, though aluminum occupies cost-sensitive segments where weight and thermal conductivity matter. The accessories and attachments category is growing fastest as modular designs allow operators to expand format ranges without full system replacement.
FDA food-contact surface regulations and EU Framework Regulation (EC) No 1935/2004 govern material safety for pasta machines sold in the United States and European Union respectively, with CE marking required for electrical safety compliance in Europe. ISO 22000 food safety management systems increasingly shape supplier qualification for commercial buyers auditing manufacturing facilities. Stakeholders must monitor evolving energy efficiency standards and water consumption limits in commercial kitchen equipment as sustainability criteria penetrate procurement specifications.
Market Dynamics
Automated extrusion systems are compressing production timelines for commercial kitchens while FDA and EU food-contact regulations force material upgrades across imported equipment portfolios.
Growth Catalysts
- EU Framework Regulation (EC) No 1935/2004:Food-contact compliance mandates are accelerating stainless steel adoption in commercial procurement specifications across European hospitality networks.
- Fresh pasta format expansion:Casual dining chains are installing dedicated pasta production lines to support made-to-order menu architectures and reduce frozen inventory dependencies.
- Emilia-Romagna manufacturing cluster:Concentrated supplier density in northern Italy is shortening lead times for extrusion dies and specialized cutting attachments serving export markets.
Market Restraints
- Specialized steel alloy costs:Surgical-grade stainless steel input prices fluctuate with nickel and chromium commodity markets, compressing margin structures for mid-tier equipment manufacturers.
- Die fabrication concentration:Precision extrusion die production concentrates among a handful of Italian tooling specialists, creating single-source vulnerabilities for format-specific equipment lines.
- Manual unit substitution:Artisan producers and culinary training institutions continue favoring hand-cranked machines for texture control, limiting electric model penetration in premium craft segments.
Strategic Opportunities
- Clean-in-place integration:Hygiene-engineered designs incorporating automated washdown cycles are opening specification windows among European processors facing labor cost pressures.
- Modular attachment ecosystems:Quick-change die and cutter systems allow operators to expand pasta format ranges without full production line replacement, capturing upgrade revenue from installed bases.
- ISO 22000 qualification protocols:Third-party food safety audits are becoming mandatory for supplier approval by large foodservice operators, creating differentiation for certified manufacturers.
Industry Challenges
- Multi-jurisdiction certification timelines:Simultaneous FDA, CE marking, and ISO 22000 approvals extend product launch cycles by eight to fourteen months for new equipment platforms.
- Legacy kitchen integration complexity:Retrofitting automated pasta lines into existing commercial kitchens requires custom electrical and plumbing reconfiguration, inflating total installed cost estimates.
- Skilled maintenance technician scarcity:Specialized knowledge of extrusion pressure calibration and die wear patterns remains concentrated among factory-trained personnel, limiting field service coverage.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pasta Machine Market |
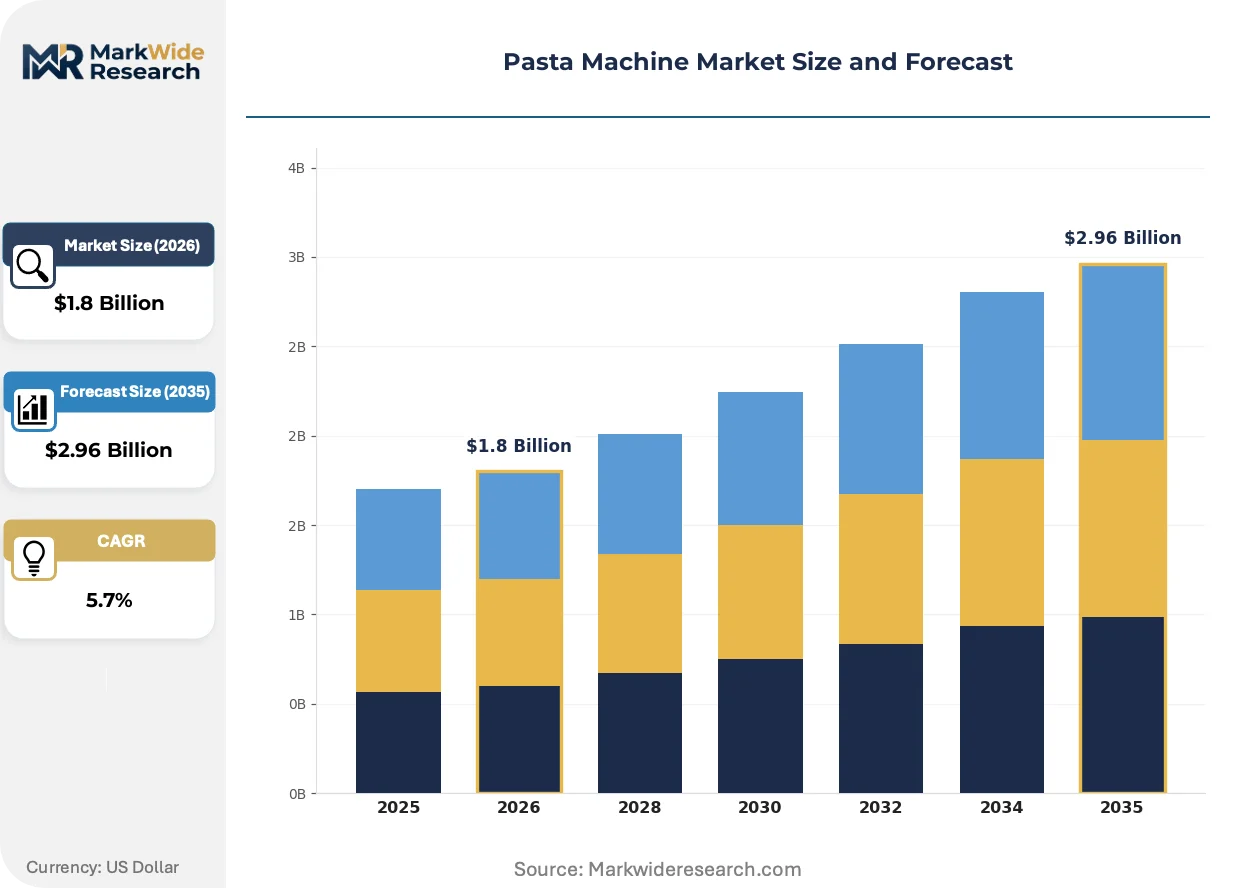
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual, Electric, Accessories, Attachments Material: Stainless Steel, Aluminum, Plastic, Wood End User: Household, Restaurants, Commercial Kitchens, Caterers Distribution Channel: Online Retailers, Supermarkets, Specialty Stores, Others |
| Companies Covered | Bühler Group, FATA S.p.A., GEA Group, Tornaghi S.p.A., CEME, Alfa Laval, Mecmar S.r.l., Lineapasta, Philips, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pasta Machine Market Evolving Landscape
Digital control interfaces and hygiene-engineered architectures are restructuring competitive requirements for commercial pasta equipment, while procurement patterns favor flexible format capabilities over fixed production lines.
Intelligent extrusion control systems are unifying pressure modulation, temperature management, and cutting synchronization into single-operator interfaces. Mid-scale commercial kitchens are adopting these platforms to reduce labor headcount during off-peak production windows. The technology is compressing the performance gap between entry-level and industrial-grade equipment, forcing mid-tier suppliers to differentiate through service rather than specification.
REACH substance restrictions and EU F-Gas Regulation phase-down schedules are eliminating certain lubricant and refrigerant chemistries from food-processing equipment supply chains. Manufacturers must reformulate bearing assemblies and thermal management systems to maintain compliance. Italian and German equipment builders are most exposed given their export dependence on EU-certified component ecosystems.
Foodservice operators are consolidating vendor relationships around full-format suppliers capable of delivering extrusion, lamination, and cutting equipment from single procurement contracts. Distributor networks that previously specialized in discrete machine categories are losing specification influence to direct manufacturer partnerships. This concentration is most visible in North American fast-casual chains expanding fresh pasta menus across multi-state footprints.
Pasta Machine Market Segmentation
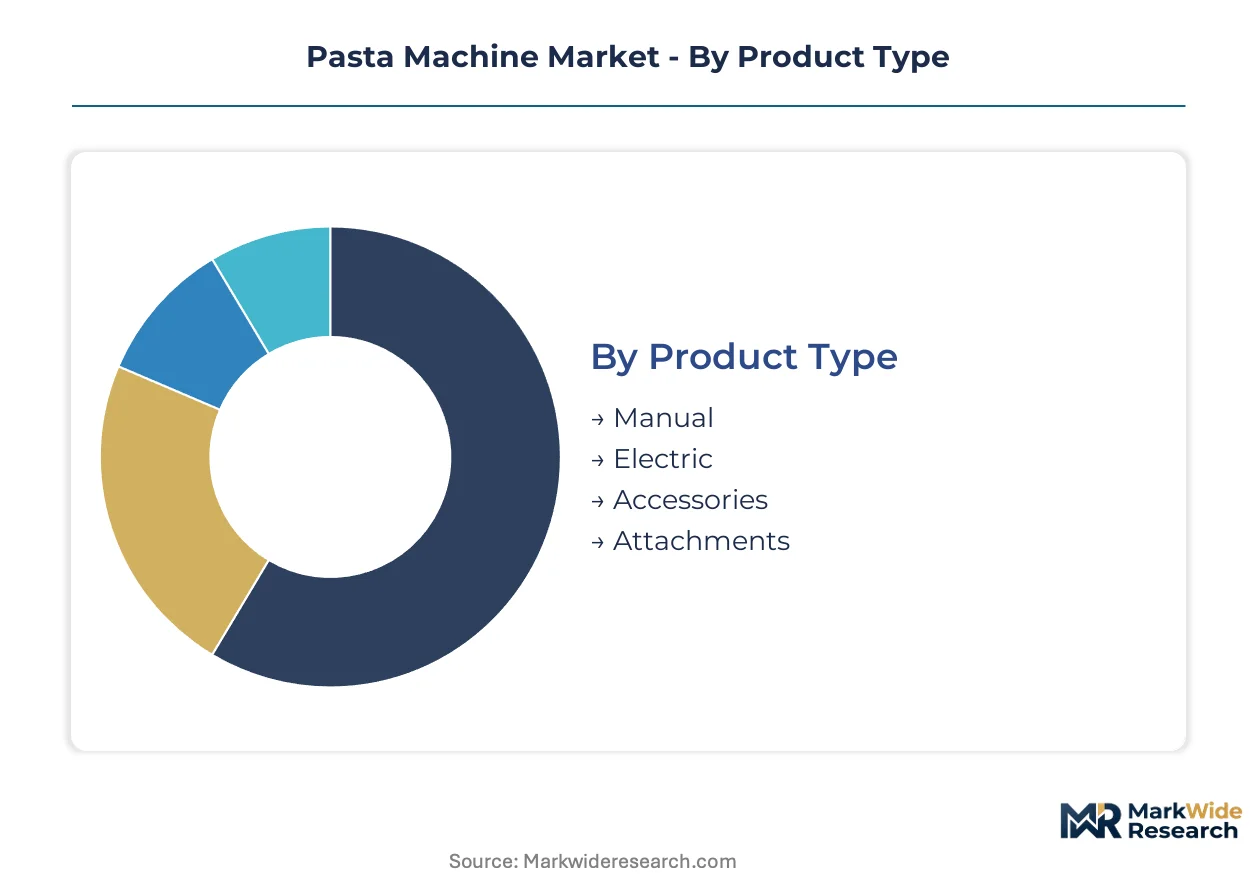
Pasta machine procurement patterns diverge sharply across operator types, with certification requirements and throughput specifications dictating material choices and power configurations. Understanding these segment boundaries clarifies where stainless steel investments, electric conversions, and modular attachments generate returns.
Product Type:
Electric models carry CE marking and FDA food-contact surface obligations that manual units avoid, though all categories face escalating hygiene audit expectations from commercial buyers.
- Manual:Hand-cranked roller systems with gap adjustments from 0.5 mm to 5 mm serve artisan producers and culinary training institutions prioritizing texture control over throughput. Demand concentrates in Italy's Emilia-Romagna craft segment and Japanese culinary academies where traditional technique certification programs mandate hand-operated equipment.
- Electric:Motor-driven extrusion and lamination platforms operating at 80–120 bar pressure dominate restaurant and commercial kitchen procurement in the United States and Germany, where labor cost pressures and volume requirements justify electrification investments despite higher compliance burdens.
- Accessories:Modular ravioli stamps, drying racks, and cutting guides expand format ranges without full system replacement.
- Attachments:Quick-change die and cutter systems compatible with stand mixer power hubs serve household and small restaurant upgrade cycles.
Leading the category by volume: Electric. Growing fastest: Attachments.
Material:
Cost tier structures separate surgical-grade stainless steel from commodity alternatives, with nickel and chromium price volatility compressing margin pools for mid-tier aluminum suppliers.
- Stainless Steel:Surgical-grade 304 and 316 alloys satisfy EU Framework Regulation (EC) No 1935/2004 and FDA 21 CFR requirements for food-contact surfaces, commanding premium positioning across European hospitality networks and North American foodservice chains.
- Aluminum:Lightweight die-cast frames with anodized finishes occupy cost-sensitive segments where thermal conductivity aids rapid dough temperature management, though surface coating durability concerns limit penetration in high-throughput commercial environments.
- Plastic:Polypropylene and ABS housings reduce unit weight and manufacturing cost for entry-level household markets.
- Wood:Traditional beech and maple construction persists in artisan and heritage-format production lines serving specialty retail and demonstration cooking applications.
Stainless steel captures the largest revenue share. Aluminum faces margin pressure from alloy input costs.
End User:
Application intensity determines equipment specification, with commercial kitchens requiring ISO 22000-qualified suppliers while household buyers prioritize countertop footprint and storage convenience.
- Commercial Kitchens:Automated extrusion lines with clean-in-place integration and HACCP-compliant designs anchor procurement in centralized production facilities supplying multi-unit restaurant chains across France, the United Kingdom, and the United States.
- Restaurants:Made-to-order pasta stations in fast-casual and casual dining formats drive demand for compact electric laminators with rapid format changeover capabilities.
- Household:Countertop manual and small electric units serve home cooking enthusiasts with limited space and intermittent use patterns.
- Caterers:Mobile production requirements favor lightweight, breakdown-capable equipment for off-site event service.
Commercial kitchens deploy the highest average equipment value per installation. Restaurants show the steepest expansion trajectory in unit installations.
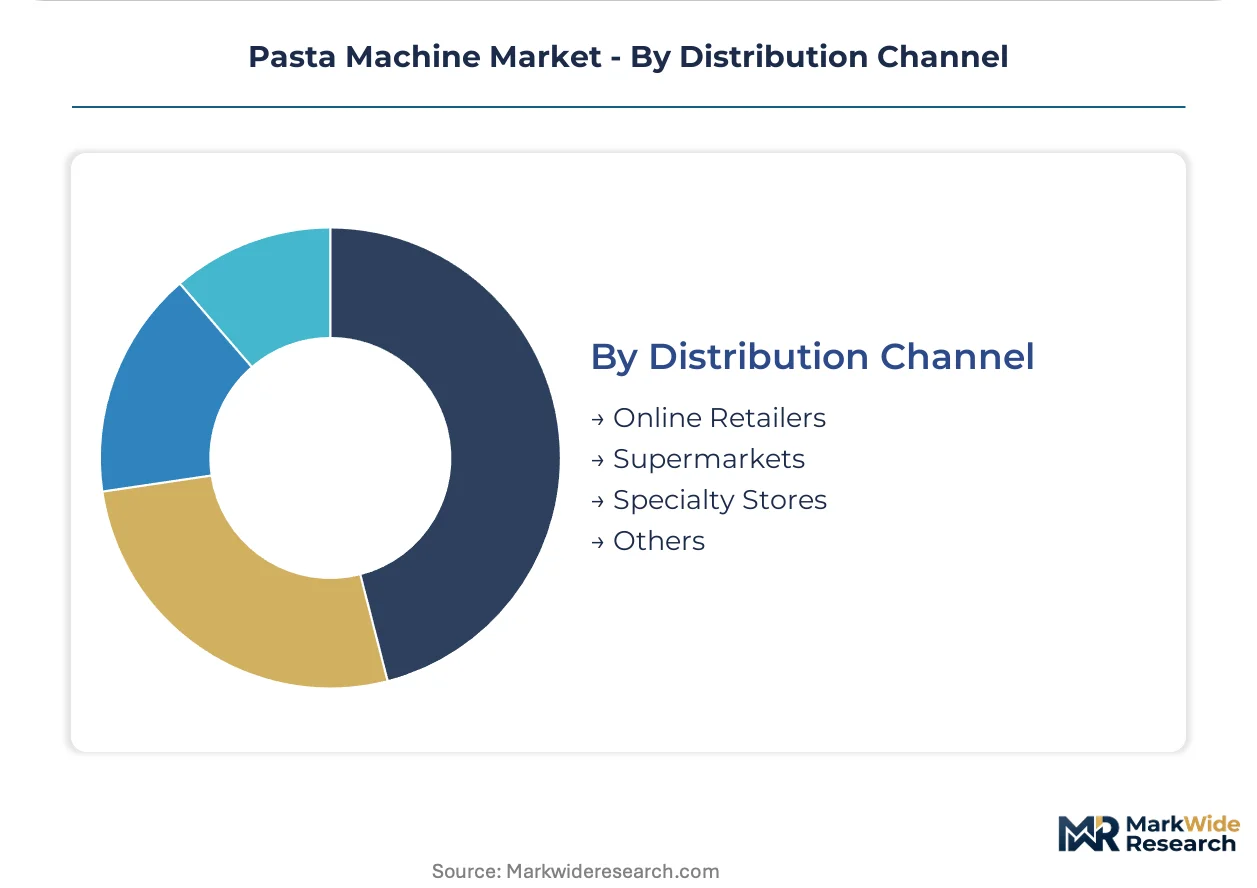
Distribution Channel:
Customer type concentration shapes channel profitability, with direct manufacturer relationships displacing traditional distributor influence among large foodservice operators.
- Specialty Stores:Culinary equipment retailers in Milan, New York, and Tokyo provide hands-on demonstration and die customization services that secure premium pricing from serious amateur and professional buyers.
- Online Retailers:E-commerce platforms capture household and small restaurant segments with standardized SKUs and comparison shopping convenience, though complex commercial specifications still require direct sales engagement.
- Supermarkets:Mass-market retail channels move entry-level manual and small electric units through seasonal promotional cycles.
- Others:Direct procurement contracts and foodservice dealer networks serve institutional and chain accounts with volume pricing and service bundling.
Specialty stores retain margin leadership in premium segments. Online retailers are gaining share fastest in household and small commercial categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italy's Emilia-Romagna region anchors equipment manufacturing through concentrated die fabrication clusters and specialized stainless steel supply chains serving export markets.
United States
Fast-casual chains are installing dedicated pasta production lines to support made-to-order menu architectures. FDA food-contact surface regulations under 21 CFR govern material safety for imported equipment. Chicago and New York City hospitality networks drive specification demand for automated extrusion systems with clean-in-place integration.
Germany
Commercial kitchens prioritize ISO 22000-qualified suppliers for centralized production facilities supplying multi-unit restaurant chains. CE marking requirements under EU electrical safety directives shape procurement standards. Bavaria's industrial equipment manufacturers export hygiene-engineered designs across European hospitality networks.
Italy
Traditional long-cut pasta systems dominate procurement for heritage-format production lines serving specialty retail. EU Framework Regulation (EC) No 1935/2004 mandates food-contact compliance for stainless steel surfaces. Emilia-Romagna's manufacturing cluster concentrates precision extrusion die production and specialized cutting attachment fabrication.
France
Casual dining operators are scaling fresh pasta menus to reduce frozen inventory dependencies. REACH substance restrictions eliminate certain lubricant chemistries from bearing assemblies in food-processing equipment. Lyon and Paris foodservice markets anchor demand for compact electric laminators with rapid format changeover capabilities.
Japan
Culinary training institutions mandate hand-operated equipment for traditional technique certification programs. METI industrial standards influence equipment safety specifications for commercial kitchen imports. Tokyo and Osaka specialty retailers provide hands-on demonstration services securing premium pricing from professional buyers.
Pasta Machine Market Competitive Landscape
Top-tier vendors anchor industrial-scale supply relationships with large foodservice operators, while mid-tier specialists compete through format-specific engineering and regional manufacturing clusters. The vendor base stratifies across Swiss-German industrial conglomerates, Italian precision tooling specialists, and diversified European engineering groups. Three archetypes dominate: hygiene-engineering specialists, extrusion technology integrators, and die fabrication masters. Consolidation pressure is accelerating through direct manufacturer partnerships displacing distributor networks, and modular attachment ecosystems capturing upgrade revenue from installed bases.
Within the precision tooling tier, FATA S.p.A. and Tornaghi S.p.A. represent Italian specialists concentrated in Emilia-Romagna's manufacturing cluster, while Bühler Group anchors the industrial-scale segment. These three exemplify how geographic concentration in northern Italy and Swiss-German engineering corridors shapes competitive positioning across extrusion die fabrication and automated production line integration.
| Leading Market Players |
|---|
| Bühler Group |
| FATA S.p.A. |
| GEA Group |
| Tornaghi S.p.A. |
| CEME |
| Alfa Laval |
| Mecmar S.r.l. |
| Lineapasta |
| Philips |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap specialists in Italy's Emilia-Romagna cluster maintain pricing discipline through captive die-fabrication capabilities and long-standing relationships with stainless steel forges, insulating premium tiers from commodity volatility while forcing price competition onto aluminum-dependent entrants.
Pricing Analysis
Premium positioning for surgical-grade 304 and 316 stainless steel machines commands 40-60% markups over aluminum alternatives, with ISO 22000 certification and FDA food-contact compliance serving as the primary price differentiation drivers. Short lead times from Emilia-Romagna's concentrated supplier base justify additional premiums for European hospitality networks facing menu rollout deadlines. Cost compression in mid-tier electric units is intensifying as nickel and chromium alloy input volatility squeezes margin structures, with North American fast-casual chains exhibiting the highest price sensitivity due to multi-unit procurement scale.
Supply Chain Analysis
Regional distribution centers in Milan, Chicago, and Tokyo anchor hub-and-spoke patterns that position finished equipment within 72-hour delivery windows for major foodservice markets. Manufacturing concentrates in Italy, Germany, and Switzerland, with precision extrusion die fabrication drawing from a handful of Emilia-Romagna tooling specialists. Supply chain risk centers on single-source vulnerability for format-specific dies, as Italian craftsmen retain irreplaceable knowledge of pressure calibration and wear patterns. Distribution runs through direct manufacturer partnerships that are displacing traditional specialty store networks among large chain accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around hygiene-engineered platforms as multi-jurisdiction certification timelines of eight to fourteen months force weaker, undercapitalized players toward exit or acquisition.
For Market Incumbents: Anchor defensive positioning through backward integration into precision die fabrication, securing captive supply of format-specific tooling that emerging competitors cannot replicate. Invest in clean-in-place engineering capabilities to maintain specification windows among European processors facing labor cost pressures. Prioritize ISO 22000 qualification protocols as a mandatory filter for supplier approval by large foodservice operators, creating differentiation that mid-tier challengers cannot match. For New Entrants and Emerging Players: Enter via modular attachment ecosystems targeting the fastest-growing accessories segment, where quick-change die systems allow operators to expand format ranges without full production line replacement. Focus penetration efforts on Japanese culinary training institutions and artisan producers in heritage-format segments where manual units retain margin pools. Pursue direct e-commerce channels for household and small restaurant upgrade cycles, bypassing distributor networks that incumbent manufacturers already dominate. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier electric specialists in Germany and northern Italy facing margin compression from alloy input costs and certification burden expansion. Long-term viability hinges on exposure to fast-casual chain expansion across North America and clean-in-place integration capabilities among European processors. Watch for inflection signals in F-Gas Regulation compliance costs and REACH substance restriction enforcement that will accelerate consolidation among lubricant-dependent bearing assembly suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Die Fabrication | Captive supply of precision extrusion tooling eliminates single-source vulnerabilities and protects margin structure. |
| Clean-in-Place Engineering Investment | Automated washdown cycles open specification windows among European processors facing labor cost pressures. |
| ISO 22000 Qualification Protocols | Third-party food safety audits become mandatory filters for supplier approval by large foodservice operators. |
| Modular Attachment Ecosystem Development | Quick-change systems capture upgrade revenue from installed bases without requiring full production line replacement. |
| Direct Manufacturer Partnership Expansion | Bypassing distributor networks secures volume pricing and service bundling with multi-state fast-casual chains. |
Research Methodology
Multi-period observation of equipment procurement patterns, certification timeline extensions, and alloy input price movements anchored the trend analysis, supplemented by interviews with commercial kitchen equipment procurement directors, pasta machine manufacturing executives, foodservice chain operations managers, and precision die fabrication specialists. Secondary validation drew from FDA 21 CFR filings, EU Framework Regulation compliance databases, SEC equipment manufacturer disclosures, and trade customs data for stainless steel food-processing machinery. Bottom-up segment sizing triangulated against top-down market value estimates.
Input-output matrices modeled relationships between extrusion pressure specifications, material certification tiers, and end-user throughput requirements across the projection horizon. Segmentation dimensions included product type, material grade, end-user application intensity, and distribution channel concentration. CAGRs derived from fitted growth curves applied to baseline installation data, with cross-validation against foodservice expansion patterns and regulatory compliance cost trajectories.
Revisions become necessary when nickel and chromium commodity volatility exceeds historical bands, when F-Gas Regulation phase-down schedules accelerate lubricant reformulation timelines, or when fast-casual chain expansion stalls in target North American markets. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Walk-In Refrigerator Market
Food Processing Equipment
French Fries Cutter Market
Food Processing Equipment
Shrimp Peeling Machine Market
Food Processing Equipment
Global Wine Tanks Market
Food Processing Equipment
Vee Bee Consistometer Market
Food Processing Equipment
Glass Processing Equipment Market
Food Processing Equipment
Hot Food Processing Equipment Market
Food Processing Equipment
Bread Slicer Market
Food Processing Equipment
Tube Ice Machine Market
Food Processing Equipment
Potato Processing Market
Food Processing Equipment
Loss-In-Weight Feeder Market
Food Processing Equipment
Chewing Gum Machine Market
Food Processing Equipment
Clean in Place Market
Food Processing Equipment
Commercial Winery Equipment Market
Food Processing Equipment
Reach-In Freezers Market
Food Processing Equipment
Global Food and Beverage Processing Equipment Market