
 French Fries Cutter Market | 2026-2036
French Fries Cutter Market Size, Share, and Industry Trends Forecast 2026-2036
French Fries Cutter Market Foresight
Stainless steel is decoupling from carbon steel frames in mid-range commercial cutters, lowering lifetime maintenance costs for high-volume operators. Omcan leverages its North American distribution network to dominate replacement blade aftermarket sales. Nemco Food Equipment anchors its position through specialized manual cutters for independent restaurants. Robot Coupe differentiates with precision-motor electric units targeting European hospitality procurement standards.
A french fries cutter is a food preparation device engineered to reduce whole potatoes into uniform strips, typically achieving cross-sections between 7mm and 13mm through interchangeable blade grids or rotary disc assemblies. The equipment serves commercial kitchens and food processing facilities requiring throughput consistency and labor reduction at volumes exceeding fifty kilograms hourly. Electric cutter configurations lead installed base across fast food chains, while hydraulic press technology captures margin pools in industrial food processing plants where continuous operation demands exceed eight hours daily. Blade cutting technology remains mature with limited innovation upside, whereas rotary cutting systems are gaining traction among snack producers seeking reduced starch loss during high-speed processing.
NSF International standards govern food-contact surface specifications across the United States commercial foodservice equipment sector. The European Food Safety Authority framework shapes CE marking requirements for electric cutter motors and hydraulic systems sold into EU member states. Food manufacturers and snack producers must monitor evolving energy efficiency regulations from the Department of Energy and emerging state-level commercial kitchen electrification mandates that could accelerate displacement of hydraulic units in certain North American jurisdictions.
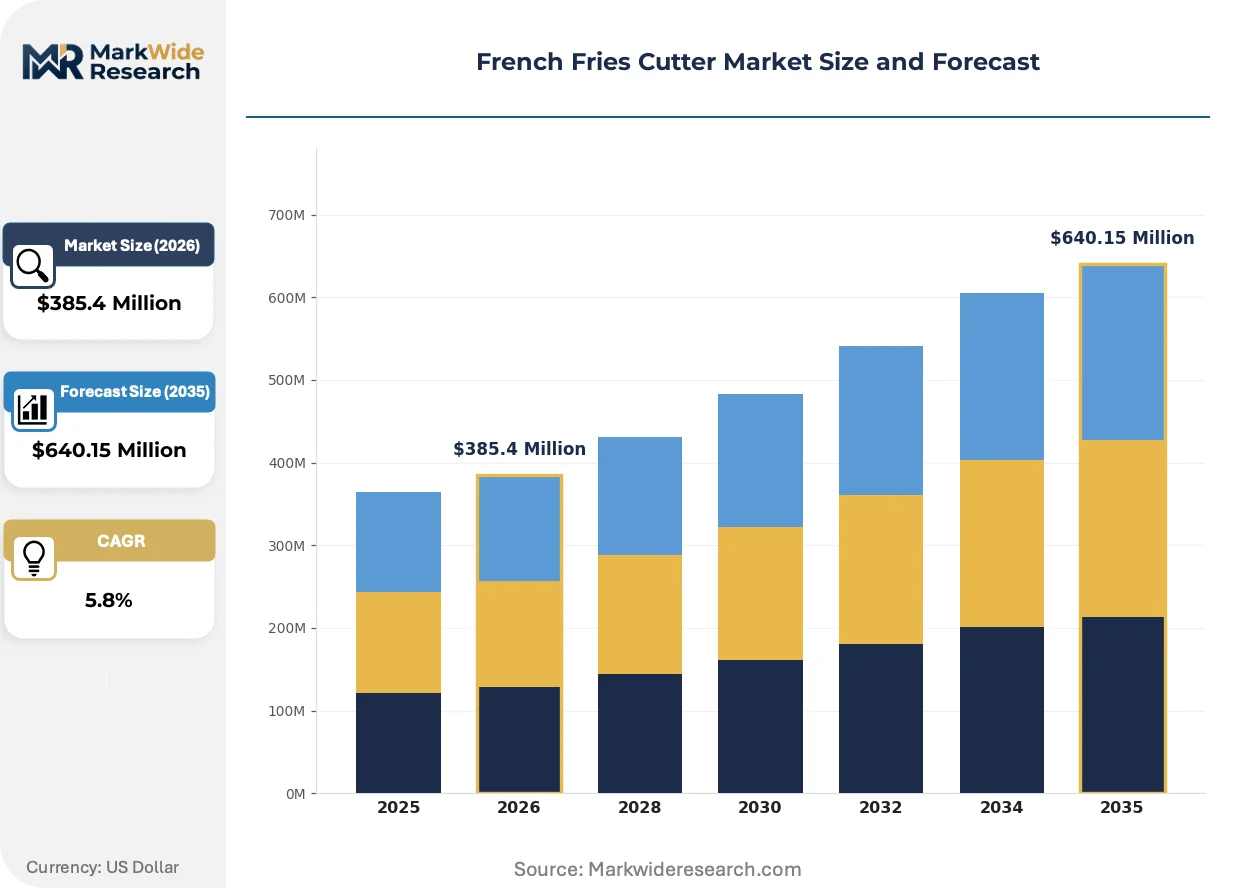
Market Dynamics
NSF International's tightening stainless steel specifications are forcing material recertification across commercial cutter portfolios, while Southeast Asian quick-service restaurant automation drives throughput requirements above fifty kilograms hourly.
Growth Catalysts
- Commercial Kitchen Electrification:US Department of Energy efficiency mandates accelerate displacement of hydraulic units in North American jurisdictions, favoring precision-motor electric configurations.
- Southeast Asia QSR Expansion:Vietnam and Indonesia anchor demand concentration as local potato processing capacity scales to serve automated kitchen line rollouts.
- Rotary Disc Technology:Snack producers adopt high-speed rotary cutting systems to reduce starch loss during continuous operation exceeding eight hours daily.
Market Restraints
- Stainless Steel Input Volatility:Nickel and chromium price swings compress margin pools for blade manufacturers dependent on food-grade 304 and 316 alloys.
- Replacement Blade Supply Concentration:North American distribution networks dominate aftermarket sales, creating dependency risk for operators outside core logistics corridors.
- Hydraulic System Regulatory Friction:Emerging state-level commercial kitchen electrification mandates threaten installed base of hydraulic press technology in industrial food processing plants.
Strategic Opportunities
- Vietnam Processing Infrastructure:Local equipment assembly partnerships capture import tariff advantages as domestic potato volume expands.
- Interchangeable Blade Grid Convergence:Cross-compatible blade systems spanning 7mm to 13mm cross-sections enable single-platform flexibility across menu categories.
- European Hospitality Procurement Standards:CE marking alignment for electric cutter motors opens specification access to EU member state institutional buyers.
Industry Challenges
- NSF Recertification Timeline Compression:Material specification updates require blade grid redesign cycles that conflict with annual procurement budgeting windows.
- Legacy Hydraulic Integration Complexity:Industrial plants face eight-hour continuous operation revalidation when retrofitting electric units into existing production lines.
- Specialized Maintenance Skill Scarcity:Precision-motor diagnostics and rotary disc calibration demand technician training programs that outpace vocational pipeline output.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | French Fries Cutter Market |
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $640.15 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Cutter, Electric Cutter, Hydraulic Cutter, Hydraulic Electric Cutter Technology: Blade Cutting, Hydraulic Press, Die Cutting, Rotary Cutting Application: Restaurants, Fast Food Chains, Catering Services, Food Processing Plants End User: Commercial Kitchens, Hospitality Sector, Food Manufacturers, Snack Producers |
| Companies Covered | Omcan, ALFA International, Nemco Food Equipment, The Vollrath Company, Robot Coupe, Edlund Company, Browne Foodservice, Thunder Group, New Star Foodservice, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
French Fries Cutter Market Shifts & Advancements
Equipment architecture is bifurcating between precision-electric units for hospitality and heavy-duty hydraulic systems for industrial processing, with blade technology maturity limiting differentiation.
Rotary disc assemblies are integrating servo-controlled speed modulation to match potato density variations in real time. High-volume snack producers in Indonesia adopt these systems to minimize starch gelatinization during high-speed cutting. The technology is integrating predictive maintenance algorithms that compress unplanned downtime intervals below four hours annually.
REACH substance restrictions are tightening chromium compound specifications for blade coatings sold into EU member states. Manufacturers must reformulate surface treatments to maintain NSF International compliance while satisfying ECHA registration thresholds. Electric cutter motor suppliers face dual certification burden as CE marking requirements expand to cover embedded control software under EU AI Act risk classifications.
After-sales service unbundling is fragmenting procurement relationships across fast food chains. Operators now source replacement blade grids through specialized distributors rather than original equipment manufacturers, compressing spare parts margin pools. Vietnam-based quick-service restaurants demonstrate this pattern most visibly, where local fabrication shops reverse-engineer blade specifications to undercut certified aftermarket pricing.
French Fries Cutter Market Segmentation
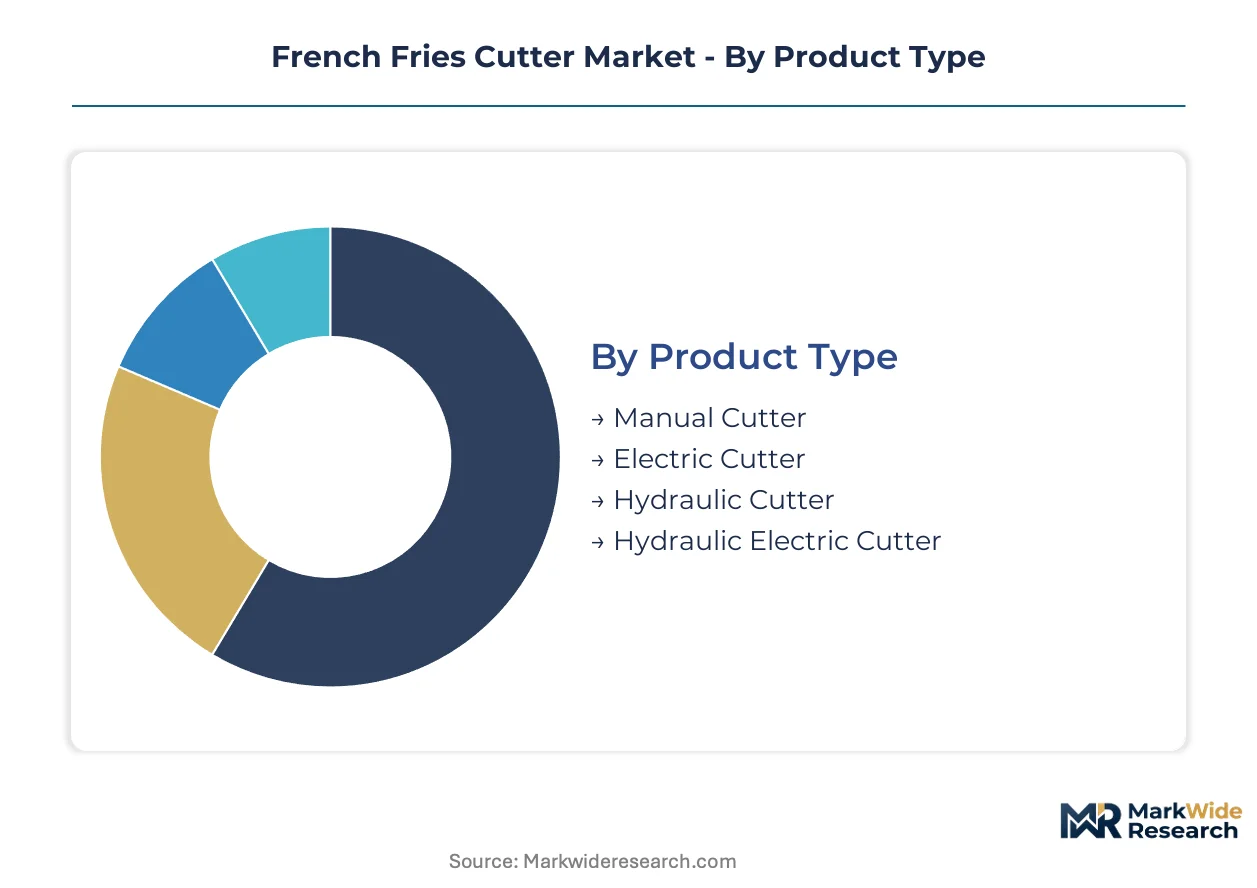
Segmentation in the French Fries Cutter Market reveals how equipment specifications diverge across operational scales and regulatory environments. Procurement patterns cluster around throughput requirements and electrification mandates rather than brand loyalty.
Product Type:
Supply concentration tilts toward electric configurations as foodservice operators phase out hydraulic dependencies.
- Manual Cutter:Lever-actuated blade grids deliver 7mm to 13mm cross-sections without electrical infrastructure. Independent restaurants in Vietnam favor these units where kitchen electrification remains incomplete and technician scarcity limits precision-motor maintenance.
- Electric Cutter:Precision-motor configurations achieve throughput exceeding fifty kilograms hourly with NSF-certified stainless steel blade assemblies. Fast food chains across Indonesia deploy these systems to meet automated kitchen line specifications while satisfying emerging state-level commercial kitchen electrification mandates.
- Hydraulic Cutter:Heavy-duty press technology serves industrial food processing plants requiring continuous operation beyond eight hours daily.
- Hydraulic Electric Cutter:Hybrid architectures bridge legacy hydraulic infrastructure with electric control systems for retrofit installations.
Electric Cutter absorbs the bulk of installed capacity; Manual Cutter is expanding most quickly among cost-constrained independents.
Technology:
Cost tier separation runs deep between mature blade systems and capital-intensive rotary alternatives.
- Blade Cutting:Interchangeable grid assemblies with 304 and 316 stainless steel specifications dominate commercial kitchen installations. NSF International recertification timelines compress margin pools for manufacturers dependent on food-grade alloy supply chains.
- Rotary Cutting:Servo-controlled disc assemblies modulate speed against potato density variations in real time. Snack producers in Indonesia adopt these systems to minimize starch gelatinization during high-speed processing exceeding eight hours daily.
- Hydraulic Press:Continuous-duty ram configurations persist in industrial plants where legacy integration complexity slows electric retrofit adoption.
- Die Cutting:Custom profile extrusion serves specialty fry formats outside standard strip geometries.
Blade Cutting retains the deepest installed base; Rotary Cutting is gaining share fastest among starch-loss-sensitive operators.
Application:
Volume concentration separates high-throughput chain deployments from intermittent catering use.
- Fast Food Chains:Automated kitchen lines demand electric cutter configurations with predictive maintenance algorithms compressing unplanned downtime below four hours annually. Vietnam and Indonesia anchor procurement concentration as local potato processing capacity scales.
- Food Processing Plants:Continuous-operation environments exceeding eight hours daily favor hydraulic press technology or heavy-duty rotary systems with servo-controlled speed modulation.
- Restaurants:Mid-volume operators balance capital constraints against throughput consistency requirements.
- Catering Services:Mobility requirements and intermittent duty cycles favor manual or compact electric configurations.
Fast Food Chains command the largest equipment footprint; Food Processing Plants is climbing the fastest on snack export demand.
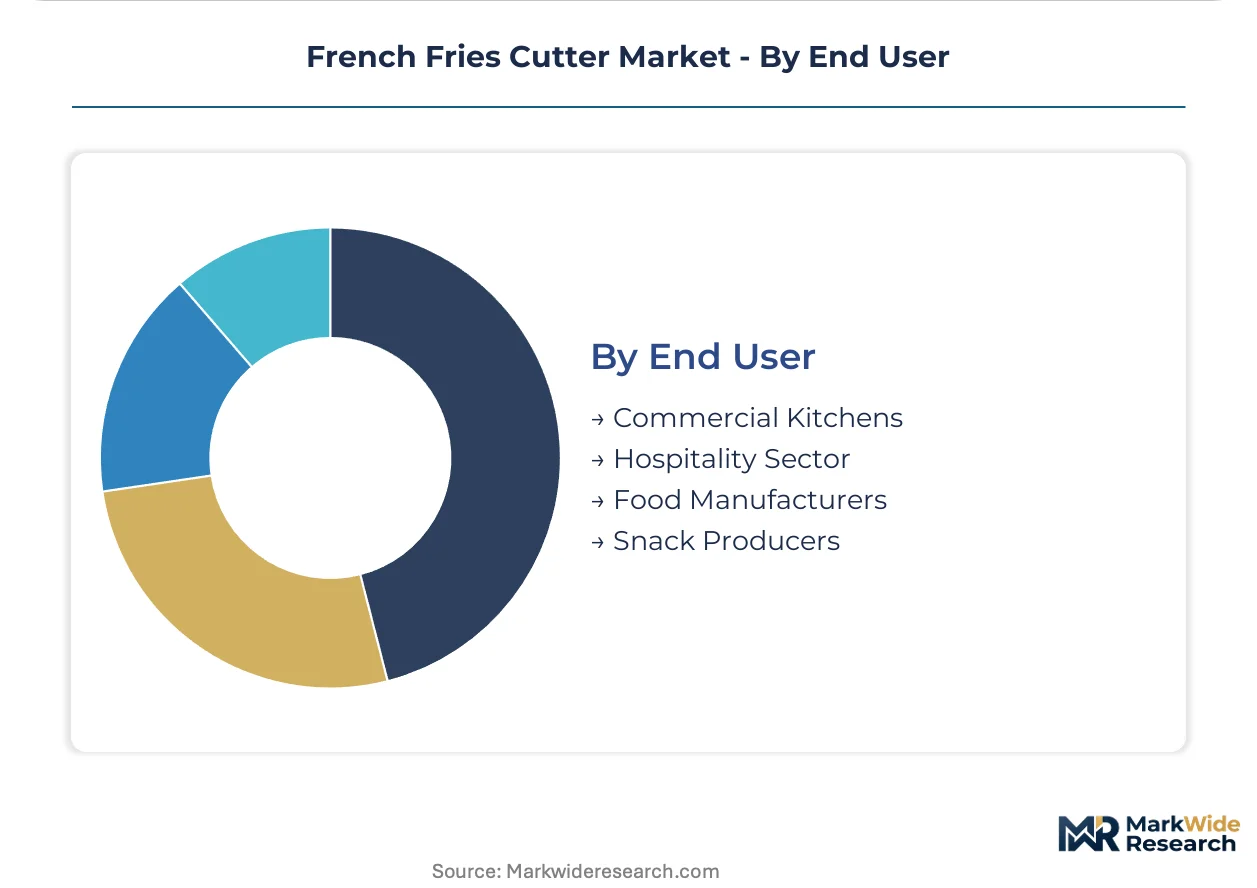
End User:
Customer type fragmentation splits procurement between hospitality procurement standards and industrial throughput mandates.
- Commercial Kitchens:NSF International compliance and CE marking alignment drive specification requirements across quick-service restaurant rollouts. After-sales service unbundling pushes these operators toward specialized distributors for replacement blade grids.
- Snack Producers:Starch loss minimization priorities accelerate rotary cutting adoption with real-time density compensation. REACH substance restrictions force blade coating reformulation to maintain ECHA registration thresholds.
- Food Manufacturers:Integrated processing lines demand hydraulic electric hybrid configurations for legacy compatibility.
- Hospitality Sector:European institutional buyers prioritize CE marking for electric cutter motors under expanded EU AI Act risk classifications.
Commercial Kitchens represents the dominant procurement channel; Snack Producers is expanding most quickly on premium fry export growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vietnam and Indonesia concentrate equipment demand through quick-service restaurant automation rollouts, while stainless steel specification tightening across multiple jurisdictions reshapes supplier compliance burdens.
United States
Fast food chains drive electric cutter procurement above fifty kilograms hourly throughput. NSF International governs food-contact surface specifications for commercial foodservice equipment. California's state-level commercial kitchen electrification mandates accelerate hydraulic unit displacement in high-volume operations.
Germany
European hospitality procurement standards prioritize CE marking alignment for electric cutter motors. ECHA REACH substance restrictions tighten chromium compound specifications for blade coatings. Industrial clusters in Baden-Württemberg host precision-motor diagnostics training programs for technician skill development.
Vietnam
Local potato processing capacity scaling supports automated kitchen line expansion across quick-service restaurants. Import tariff structures favor domestic equipment assembly partnerships over complete unit imports. Ho Chi Minh City anchors fabrication shop concentration where reverse-engineered blade specifications undercut certified aftermarket pricing.
Indonesia
Snack producers adopt servo-controlled rotary disc systems to minimize starch gelatinization during eight-hour continuous operations. The national food safety regulator enforces equipment certification for commercial processing facilities. Jakarta and Surabaya concentrate high-speed processing infrastructure serving export-oriented fry production.
France
EU AI Act risk classifications expand CE marking requirements to cover embedded control software in electric cutter motors. EFSA frameworks shape food-contact equipment standards across institutional procurement. Lyon hospitality equipment clusters specialize in precision-motor configurations targeting European restaurant chains.
French Fries Cutter Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with aftermarket blade distribution concentrating through North American logistics networks while equipment fabrication fragments across Asian assembly partnerships. Three archetypes dominate: precision-motor electric specialists, manual cutter traditionalists, and hydraulic system incumbents serving industrial plants. Competitive moves cluster around strategic partnerships for local assembly rights and portfolio diversification into predictive maintenance software.
Within the branded equipment tier, Omcan anchors North American replacement blade aftermarket positioning, Nemco Food Equipment exemplifies manual cutter specialization for independent restaurants, and Robot Coupe occupies the precision-motor electric segment targeting European hospitality procurement standards.
| Leading Market Players |
|---|
| Omcan |
| ALFA International |
| Nemco Food Equipment |
| The Vollrath Company |
| Robot Coupe |
| Edlund Company |
| Browne Foodservice |
| Thunder Group |
| New Star Foodservice |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap blade manufacturers in Italy and Germany anchor supply discipline through generational ownership structures that resist margin compression during nickel price spikes. Their captive forging operations insulate pricing power from commodity volatility while fast food chains exploit fragmented distributor networks to extract service bundling concessions.
Pricing Analysis
High-volume electric cutter procurement concentrates margin capture in precision-motor configurations while manual cutter segments absorb cost compression from reverse-engineered blade competition. Three-tier pricing structure across NSF-certified premium, CE-marked standard, and uncertified economy levels separates procurement channels for fast food chains, independent restaurants, and catering operators. Pricing pressure stems from Vietnamese fabrication shops undercutting certified aftermarket grids by forty to sixty percent. Independent restaurants in Southeast Asia exhibit highest price sensitivity; European hospitality procurement shows lowest elasticity due to CE marking mandates.
Supply Chain Analysis
Skilled stainless steel forging technician scarcity in Baden-Württemberg and Veneto limits blade grid output expansion despite order backlogs from Indonesian snack producers. Manufacturing concentrates in Germany, Italy, and Vietnam with raw material dependencies on Indonesian nickel, South African chromium, and Chinese rare earth elements for servo motors. Single-source vulnerability in 316 stainless steel cold-rolled sheet from Finnish mills exposes margin pools to logistics chokepoint risk. Distribution runs through specialized foodservice equipment distributors rather than direct OEM channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
NSF recertification timelines and REACH substance restrictions are forcing undercapitalized blade specialists into distressed asset sales. Consolidation favors precision-motor electric portfolios with embedded predictive maintenance software.
For Market Incumbents: Deploy backward integration into 304 and 316 stainless steel cold-rolling capacity to neutralize Finnish mill single-source vulnerability. Capture Vietnamese assembly partnerships before import tariff structures harden against complete unit imports. Electric cutter specialists face substitution threat from servo-controlled rotary disc systems in starch-loss-sensitive snack processing segments. For New Entrants and Emerging Players: Direct-to-caterer digital channels bypass distributor margin stacking for compact electric configurations in intermittent-duty applications. Target Vietnamese independent restaurants where kitchen electrification gaps persist and technician scarcity limits precision-motor maintenance penetration. White-space exists in predictive maintenance software licensing to fast food chains seeking sub-four-hour annual downtime guarantees. For Investors and Strategic Acquirers: Distressed-cycle entries favor manual cutter specialists with Vietnamese fabrication relationships and uncertified blade reverse-engineering capabilities. Long-term viability hinges on CE marking alignment for EU hospitality procurement access. Watch for Indonesian national food safety regulator enforcement waves as inflection indicator for certified equipment demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Stainless Steel Forging | Captive 304 and 316 alloy supply neutralizes nickel price volatility from Indonesian mining disruptions. |
| Vietnamese Assembly Partnership Formation | Domestic equipment assembly captures import tariff advantages as local potato processing volume expands. |
| Predictive Maintenance Software Licensing | Algorithm-driven downtime compression below four hours annually commands premium pricing from fast food chains. |
| CE Marking Alignment Investment | EU AI Act risk classifications for embedded motor software open institutional procurement access across member states. |
| Rotary Disc Technology Portfolio Entry | Servo-controlled speed modulation addresses starch gelatinization concerns in Indonesian snack export facilities. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for demand modeling across commercial kitchen and food processing plant segments. Primary interviews with fast food chain procurement directors, aftermarket service managers, and stainless steel blade forging technicians combined with NSF International certification databases, ECHA REACH substance registries, and Vietnamese customs import records. Bottom-up equipment shipment analysis and top-down potato processing capacity expansion data triangulated market sizing.
Granularity-level modeling disaggregated electric, manual, hydraulic, and hybrid cutter configurations across fast food chain, food processing plant, restaurant, and catering service applications. CAGRs derived from throughput requirement trajectories, electrification mandate adoption curves, and rotary technology penetration rates in starch-loss-sensitive operations. Segmentation incorporated blade cutting, rotary cutting, hydraulic press, and die cutting technology tiers alongside NSF and CE certification status.
The model holds under stable nickel and chromium alloy pricing; deviation in Indonesian mining export restrictions or EU AI Act enforcement intensity would shift equipment procurement timelines. Forecasts reflect assumptions about Southeast Asian quick-service restaurant automation rollout velocity and REACH substance restriction implementation pace. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Spray Dried Food Market
Food Processing Equipment
Electric Chicken Scalder Market
Food Processing Equipment
Walk-In Coolers and Freezers Market
Food Processing Equipment
Freeze-Drying Equipment Market
Food Processing Equipment
Food Irradiation Equipment Market
Food Processing Equipment
Fish Deboning Machine Market
Food Processing Equipment
Corn Puff Making Machine Market
Food Processing Equipment
Freezers Market
Food Processing Equipment
Dual-Ovenable Cook Trays Market
Food Processing Equipment
Pulp Washing Equipment Market
Food Processing Equipment
Small Continuous Fryer Market
Food Processing Equipment
Global Non Thermal Processing Market
Food Processing Equipment
Exhaust Hood Filters and Cleaning Kits Market
Food Processing Equipment
Potato Processing Market
Food Processing Equipment
Portable Clean-In-Place Market
Food Processing Equipment
Canning Equipment Market