
 Hot Food Processing Equipment Market | 2026-2036
Hot Food Processing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Hot Food Processing Equipment Market Intelligence
Price differentiation between premium, high-automation systems and basic, commodity-grade units is pivoting on energy efficiency, IoT connectivity, and data logging capabilities. GEA Group AG specializes in large-scale, integrated processing lines for industrial food producers. JBT Corporation leverages its expertise in thermal processing technologies for specialized sterilization applications. Marel hf. competes by offering advanced software-driven systems for complex protein processing operations.
Hot food processing equipment encompasses devices designed for the thermal treatment of food, operating at temperatures typically exceeding 100°C to achieve cooking, baking, or pasteurization. These systems are engineered to ensure uniform heat transfer and precise temperature control, which are critical for food safety. The market's product types include mature categories like ovens and griddles, while advanced electric and induction technologies are gaining share over gas models. Among end users, restaurants and large-scale catering services constitute the largest demand centers.
Equipment design is heavily influenced by food safety standards, including FDA regulations in the United States and the CE marking framework in Europe. Standards from organizations like NSF International further dictate material and sanitation requirements, impacting global market access for manufacturers. The critical decision for purchasers involves balancing higher upfront capital investment for compliant, energy-efficient machinery against long-term operational savings.
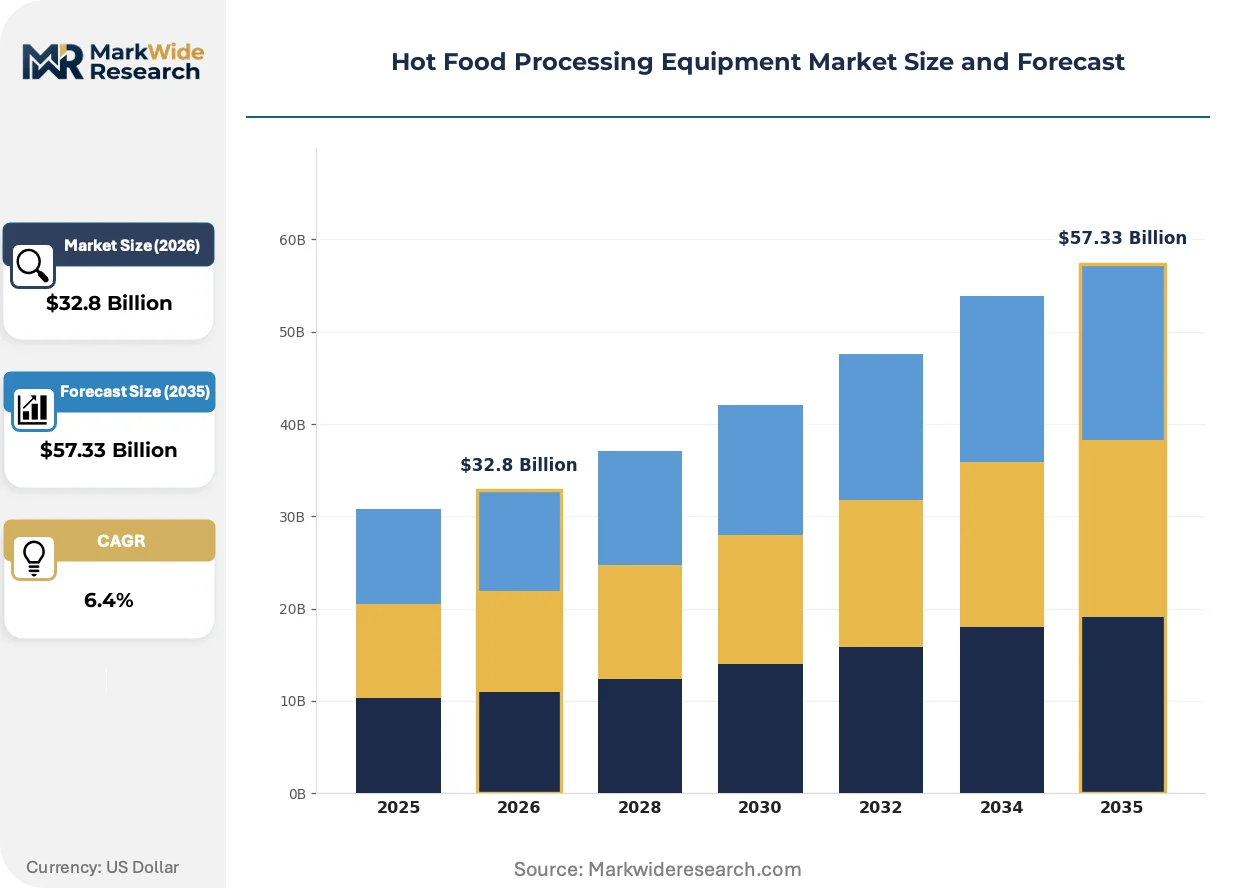
Market Dynamics
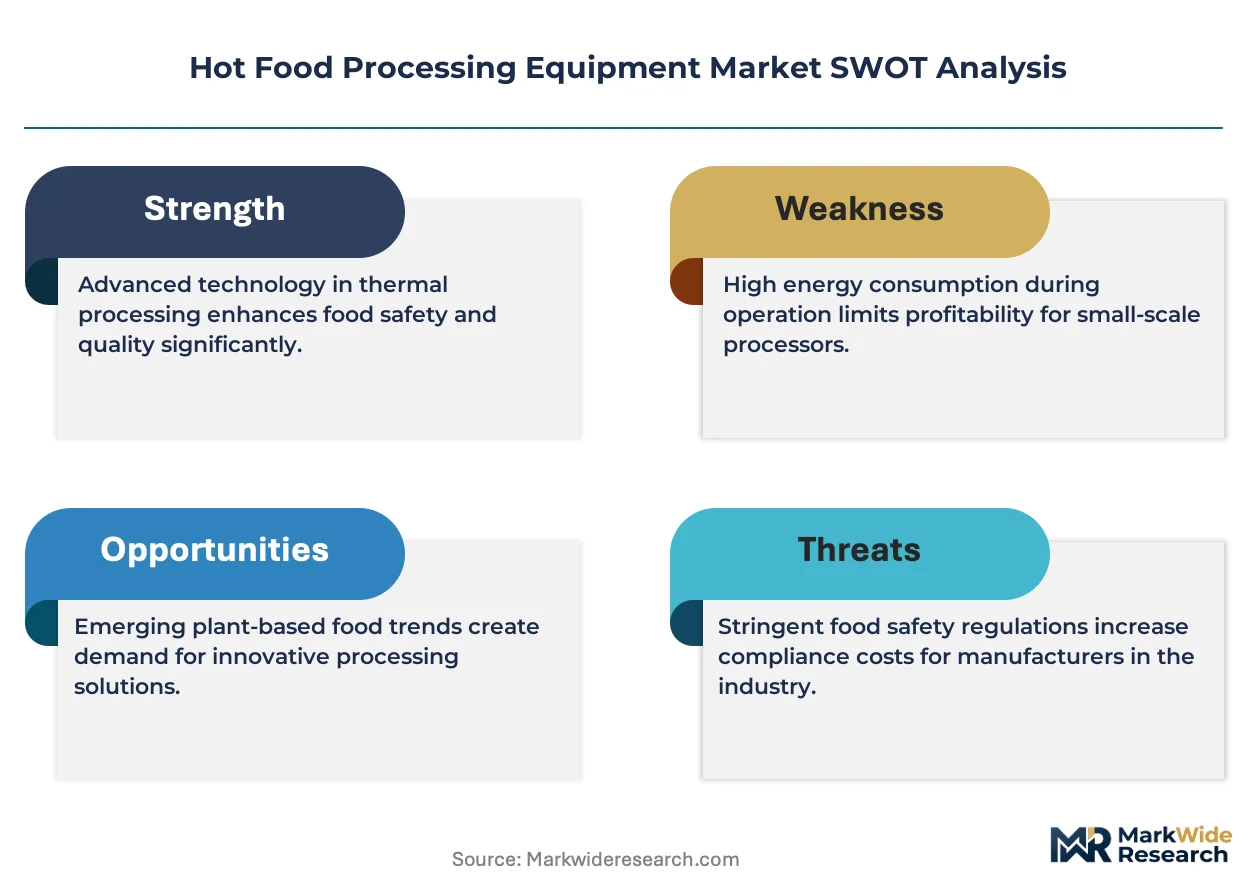
The central dynamic shaping the market is the tension between the high capital expenditure required for equipment compliant with stringent food safety regulations and the long-term operational savings derived from enhanced energy efficiency and automation.
Growth Catalysts
- QSR Expansion in Asia:The rapid proliferation of quick-service restaurant chains, particularly in India, creates sustained demand for standardized, high-volume cooking equipment like commercial griddles and ovens to ensure product consistency across locations.
- Food Safety Mandates:Increasingly strict food contact material regulations from bodies like the European Food Safety Authority (EFSA) compel food processors to upgrade older equipment to compliant systems, driving replacement cycles.
- Energy Efficiency Imperatives:The rising operational cost of energy is accelerating the transition from traditional gas-powered units to advanced electric and induction heating technologies that offer more precise temperature control and lower consumption.
Market Restraints
- High Capital Investment:The significant upfront cost for automated, IoT-enabled, and certified processing lines presents a substantial barrier for small and medium-sized enterprises, limiting their ability to adopt the latest technologies.
- Input Material Price Volatility:Fluctuations in the price of high-grade stainless steel and other food-safe alloys, critical for manufacturing compliant equipment, directly impact production costs and introduce pricing instability for manufacturers.
- Legacy System Integration:The technical complexity and cost of integrating new, digitally controlled equipment with existing analog production lines in established food processing facilities can deter or delay investment in modernization.
Strategic Opportunities
- Plant-Based Food Processing:The development of specialized thermal processing equipment tailored for the unique textures and properties of plant-based proteins represents a significant growth vector for manufacturers.
- Predictive Maintenance Services:Offering subscription-based services that leverage IoT sensor data for predictive maintenance and process optimization provides a new, recurring revenue stream beyond initial equipment sales.
- Circular Economy Designs:Designing equipment for easier disassembly, refurbishment, and material recovery can create a competitive advantage as end-users face increasing pressure to meet corporate sustainability goals under frameworks like the EU Green Deal.
Industry Challenges
- Skilled Operator Scarcity:A widening skills gap exists for technicians and operators who can manage and maintain complex, software-driven processing lines, challenging the adoption of fully automated systems.
- Certification and Compliance Delays:Navigating the lengthy and expensive certification processes for standards like NSF International or CE marking can delay market entry for new products and innovations.
- Cybersecurity Vulnerabilities:The increasing connectivity of processing equipment introduces new cybersecurity risks, requiring manufacturers to invest in securing data logging and remote control functions against potential breaches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hot Food Processing Equipment Market |
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $57.33 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fryers, Griddles, Ovens, Steamers Technology: Electric, Gas, Induction, Solar End User: Restaurants, Catering Services, Food Trucks, Bakeries Application: Cooking, Baking, Heating, Roasting |
| Companies Covered | JBT Corporation, Tetra Laval International S.A., GEA Group AG, TNA Australia Pty Limited, Alfa Laval AB, Bühler AG, SPX Flow, Marel hf., The Middleby Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hot Food Processing Equipment Market Strategic Shifts & Innovations
Digitalization and sustainability are fundamentally altering equipment design, shifting the competitive focus from simple thermal performance to total lifecycle cost, including energy use and data-driven operational intelligence. These forces are creating a clear divide between basic hardware and integrated systems.
Integrated sensor technology is becoming a standard feature in premium equipment. These sensors collect real-time data on temperature, processing times, and energy consumption. Adoption is accelerating among industrial-scale food producers and multi-site restaurant chains seeking to enforce operational consistency. The integration of hardware with advanced analytics is unifying previously siloed functions like process control, quality assurance, and energy management into a single operational interface.
The EU's Ecodesign for Sustainable Products Regulation is establishing new benchmarks for energy efficiency and material circularity in industrial machinery. This regulatory pressure compels manufacturers to innovate beyond core performance, focusing on lifecycle impacts. Ovens, fryers, and pasteurization systems are most affected, with new models featuring enhanced insulation, heat recovery systems, and designs that facilitate repair and recycling.
A notable behavioral shift is visible in how large operators evaluate new equipment, with a growing emphasis on systems that provide comprehensive data for traceability and efficiency analysis. This change is diminishing the appeal of non-connected, standalone units, especially within the high-volume catering and industrial processing segments. This preference for data-rich equipment is most evident in North America and Europe, where stringent food safety documentation and operational optimization are key procurement drivers.
Hot Food Processing Equipment Market Segmentation
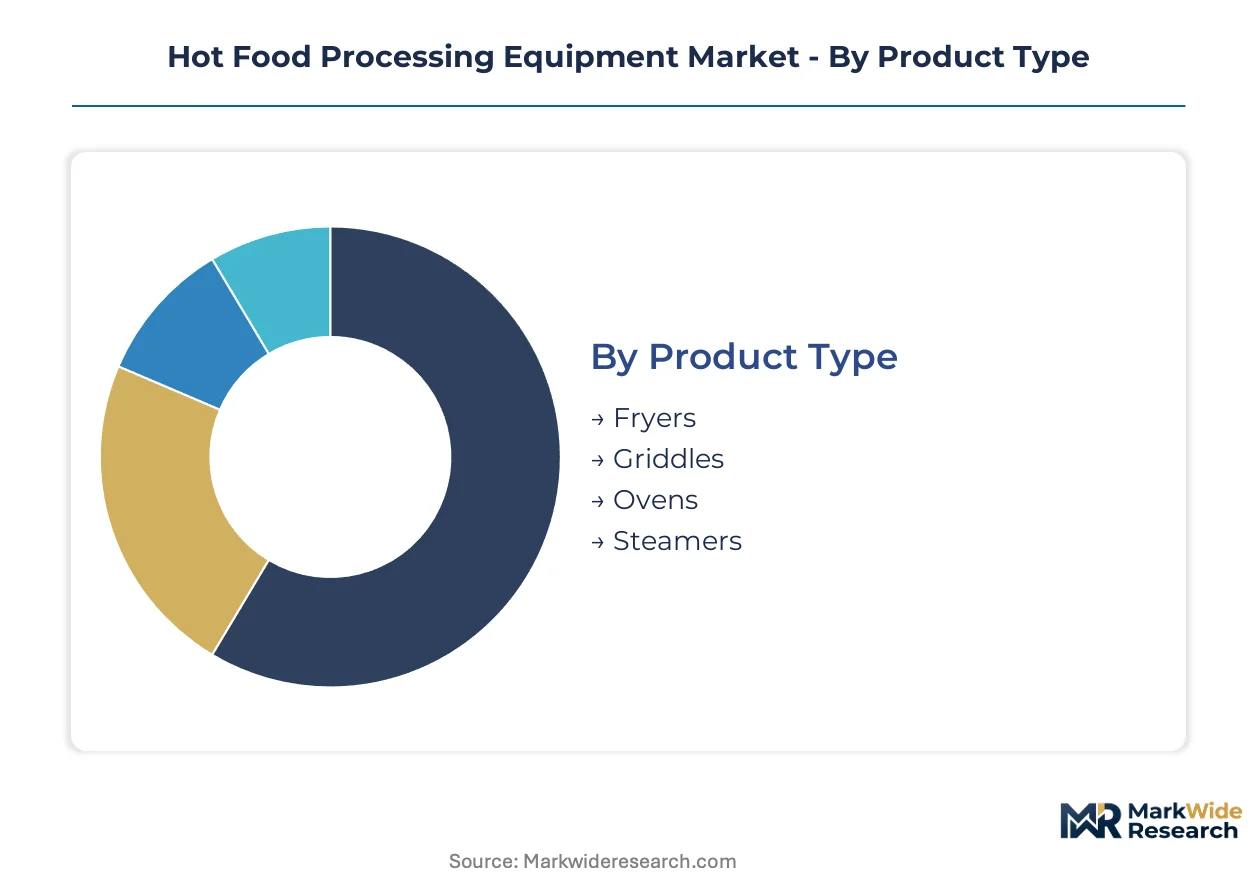
The Hot Food Processing Equipment Market is fundamentally shaped by diverse product functionalities and end-user requirements. Understanding these distinct segments illuminates varying demand patterns and technological priorities across the industry. This granular analysis reveals where innovation efforts are concentrated and identifies specific areas of commercial opportunity.
Product Type:
Product type segmentation focuses on the core functional design and operational characteristics of the equipment. Each category addresses specific thermal processing needs within commercial kitchens and industrial settings.
- Ovens:These enclosed chambers use dry heat for baking, roasting, and heating, ensuring uniform temperature distribution for consistent food quality. Demand is strong in multi-site restaurant chains in India, supporting standardized menu items across a proliferating quick-service network.
- Griddles:Flat, heated cooking surfaces provide direct contact heat for searing, frying, and grilling, critical for high-volume breakfast and lunch service. Major catering services in Europe utilize these for efficient, rapid preparation of large quantities of food, driven by stringent hygiene standards.
- Fryers:Equipment designed for cooking food in hot oil, offering rapid cooking times for various items.
- Steamers:Units that cook food using steam, preserving nutrients and moisture for healthier preparations.
Ovens leads on scale; Griddles leads on momentum.
Technology:
The market's technology segments are differentiated by their primary energy source and heating mechanism, influencing operational efficiency and environmental impact.
- Electric:These systems convert electricity directly into heat, offering precise temperature control and reduced emissions, often incorporating advanced digital interfaces. Industrial food producers in Germany adopt electric systems to meet strict EU Green Deal targets and minimize operational energy costs.
- Induction:Utilizing electromagnetic fields to heat cookware directly, induction technology provides rapid, energy-efficient heating with minimal heat loss and enhanced safety features. Quick-service restaurants in the United States integrate induction cooktops for faster service and improved energy consumption.
- Gas:Equipment powered by natural gas or propane, widely used for its high heat output and quick response times.
- Solar:Systems that harness solar energy for heating, primarily used in off-grid or specialized applications.
Electric technologies are expanding most quickly, driven by efficiency mandates.
End User:
End-user segmentation highlights the distinct operational scales and specific equipment requirements of different commercial food service environments.
- Restaurants:Commercial eateries, ranging from fine dining to casual establishments, require versatile equipment for diverse menus and varying capacities. QSR expansion in India drives demand for standardized, high-volume cooking equipment to ensure product consistency across numerous locations.
- Catering Services:These operations provide food for events and institutions, demanding robust, high-capacity equipment capable of preparing large batches and maintaining food quality during transport. Large-scale catering services in the United Kingdom prioritize equipment compliant with strict food safety documentation.
- Food Trucks:Mobile food vendors needing compact, efficient, and durable equipment to operate in confined spaces.
- Bakeries:Establishments specializing in baked goods, requiring precise temperature control for ovens and proofers.
Restaurants show the steepest expansion trajectory, propelled by global QSR growth.
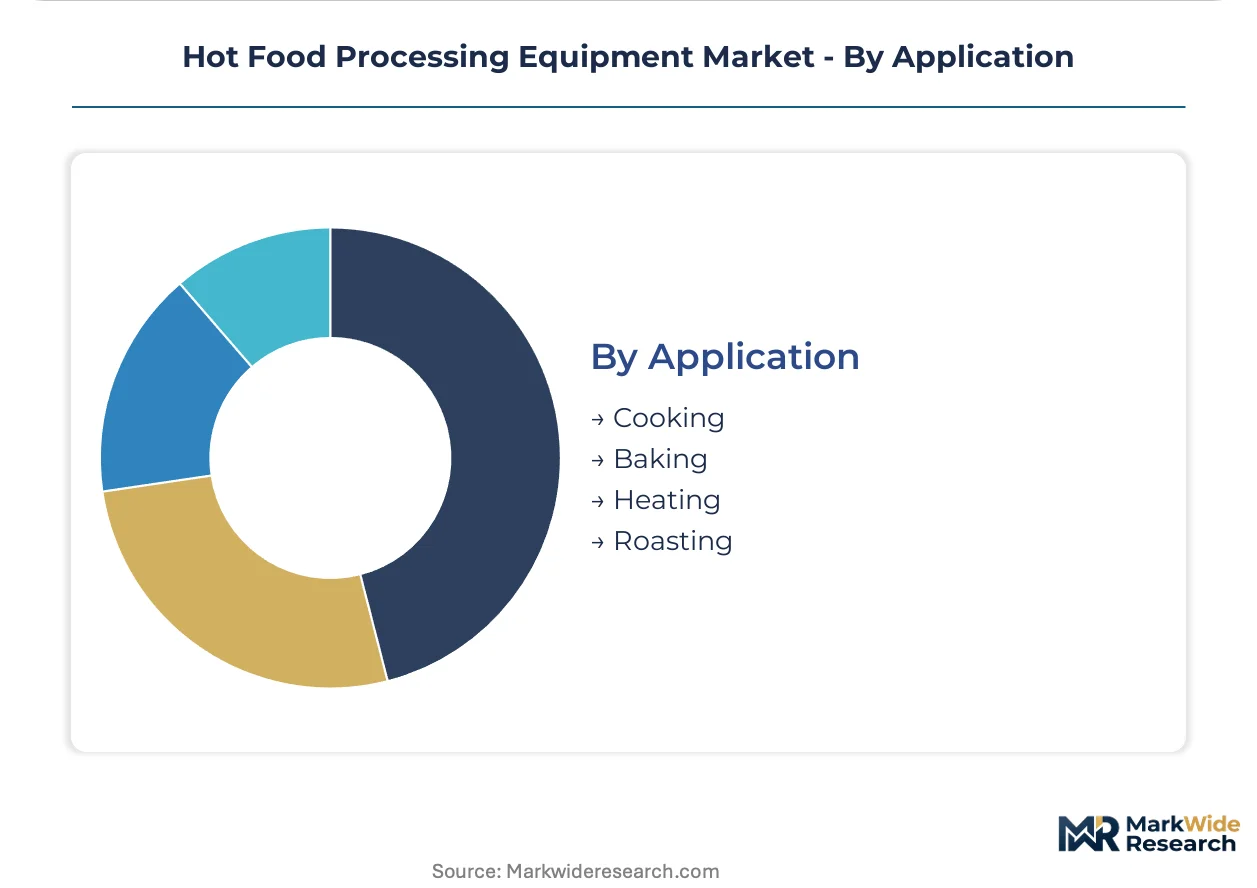
Application:
This segmentation defines the primary culinary processes performed by the equipment, reflecting specialized functional designs for specific thermal transformations.
- Cooking:Encompasses a broad range of thermal processes to prepare food for consumption, including boiling, frying, and grilling. This application dominates demand across all end-user segments, particularly within the quick-service restaurant industry for rapid item preparation.
- Baking:Involves cooking food with dry heat, typically in an oven, to produce items like bread, pastries, and casseroles, requiring precise temperature and time control. Commercial bakeries in France are investing in advanced baking equipment to meet evolving consumer preferences for artisanal products.
- Heating:The process of re-therming or maintaining food at a desired temperature, common in buffet lines and food holding units.
- Roasting:A dry-heat cooking method that uses hot air to cook food, often meats and vegetables, producing a browned exterior.
Cooking applications are gaining share fastest due to their universal necessity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
While quick-service restaurant expansion in India fuels demand for high-volume cooking equipment, stringent food safety mandates in Germany drive upgrades to advanced electric systems. These contrasting drivers highlight the diverse regional influences on the hot food processing equipment market.
India
Rapid proliferation of quick-service restaurant chains creates sustained demand for standardized, high-volume cooking equipment. The Food Safety and Standards Authority of India (FSSAI) compels processors to maintain high hygiene standards for prepared foods. The Delhi-NCR region sees significant investment in new equipment to support the expanding footprint of national and international restaurant brands.
Germany
Industrial food producers adopt electric systems to meet strict EU Green Deal targets and minimize operational energy costs. The EU's Ecodesign for Sustainable Products Regulation establishes new benchmarks for energy efficiency in industrial machinery. Bavaria, a hub for advanced manufacturing, concentrates companies developing innovative, energy-efficient thermal processing solutions.
United States
Quick-service restaurants integrate induction cooktops for faster service and improved energy consumption. FDA regulations in the United States heavily influence equipment design, particularly for food contact materials. California's dynamic food tech ecosystem fosters demand for connected equipment that provides comprehensive data for traceability and efficiency analysis.
United Kingdom
Large-scale catering services prioritize equipment compliant with stringent food safety documentation and high capacity. The CE marking framework and local food hygiene standards mandate specific material and sanitation requirements for imported and domestically produced machinery. London, with its extensive event catering industry, shows consistent demand for robust, high-throughput cooking units.
France
Commercial bakeries invest in advanced baking equipment to meet evolving consumer preferences for artisanal products. European Food Safety Authority (EFSA) guidelines on thermal processing dictate precise temperature control and uniform heat transfer. The Brittany region, known for its culinary traditions, is seeing specialized equipment manufacturers develop solutions for high-precision baking applications.
Hot Food Processing Equipment Market Key Industry Players
Top-tier vendors anchor the integrated processing lines segment, while mid-sized specialists focus on niche applications and technology-driven solutions. The market exhibits a tiered structure, with a clear distinction between providers of highly automated systems and suppliers of more basic, commodity-grade units. Strategic archetypes include large-scale integrators, thermal processing specialists, and software-driven system providers. Dominant competitive moves include mergers and acquisitions for technology acquisition and geographic expansion into emerging markets.
On the premium-tier vector, GEA Group AG exemplifies large-scale, integrated processing line solutions for industrial food producers. JBT Corporation occupies a position in specialized sterilization applications, leveraging thermal processing technologies. Marel hf. sits within the advanced software-driven systems segment for complex protein processing operations, emphasizing data-driven operational intelligence.
| Leading Market Players |
|---|
| JBT Corporation |
| Tetra Laval International S.A. |
| GEA Group AG |
| TNA Australia Pty Limited |
| Alfa Laval AB |
| Bühler AG |
| SPX Flow |
| Marel hf. |
| The Middleby Corporation |
| Others |
Cost & Logistics Intelligence
Fluctuations in high-grade stainless steel prices, a critical input, directly influence the cost of compliant equipment across all pricing tiers, from basic griddles to premium integrated lines downstream.
Pricing Analysis
Capacity additions in Germany for advanced electric systems are reshaping price floors for energy-efficient equipment. The dominant pricing model is a tiered premium-mid-economy differentiation, separating highly automated, IoT-enabled systems from standard and basic units. Certification level, such as NSF International compliance, and after-sales service bundles are key differentiation drivers. Pricing softness emerges in the commodity-grade segment due to increased competition from Asian manufacturers. Quick-service restaurants are highly price-sensitive for basic units, while large industrial food producers prioritize value over upfront cost.
Supply Chain Analysis
Reverse-logistics efforts for equipment refurbishment and material recovery are gaining traction, driven by circular economy designs. Geographic supply concentration for components like specialized sensors and control systems resides in Germany and the United States. Raw material dependencies include high-grade stainless steel and food-safe alloys. Input material price volatility represents a significant structural risk. Downstream distribution typically runs through specialized equipment dealers for restaurants and direct sales channels for large industrial food producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hot food processing equipment market presents a clear margin-expansion story, driven by the shift towards premium, data-logging systems that command higher value and recurring service revenues.
For Market Incumbents:Anticipate continued consolidation through strategic acquisitions of software-driven automation specialists to counter the threat of niche technology entrants. Invest heavily in certification processes for new product lines, particularly for EU Green Deal compliance, to leverage the lever of regulatory-driven replacement cycles. Deepen vertical integration into advanced component manufacturing to mitigate input material price volatility.
For New Entrants and Emerging Players:Enter via specialized thermal processing solutions tailored for plant-based food production, targeting the underpenetrated market for alternative proteins. Focus on developing compact, energy-efficient induction technologies for the quick-service restaurant segment in emerging Asian markets. A go-to-market angle should emphasize IoT connectivity and predictive maintenance services to differentiate from commodity offerings.
For Investors and Strategic Acquirers:Roll-up economics work for private equity firms targeting regional equipment manufacturers because of the fragmented nature of the SME market and the high value placed on local service networks. The long-term viability favors platforms offering comprehensive data-driven solutions and circular economy designs over the next decade. Acquisition targets should be specialists in advanced electric or induction technologies with established certification credentials. Monitor the increasing stringency of food safety mandates from bodies like EFSA as an inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Technology Acquisition | Acquiring specialized software firms enhances IoT integration and data analytics capabilities for industrial food producers. |
| Geographic Expansion | Expanding into India's quick-service restaurant market captures sustained demand for high-volume cooking equipment. |
| Circular Design Integration | Implementing circular economy principles in equipment design meets EU Green Deal targets and appeals to sustainability-focused catering services. |
| Predictive Maintenance Launch | Offering subscription-based predictive maintenance services creates new recurring revenue streams for large operators in North America. |
| Certification Investment | Investing in NSF International and CE marking certifications ensures global market access and compliance for premium equipment. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary insights with robust secondary validation. Primary data involved discussions with plant engineers, procurement managers, R&D directors, and food safety officers. Secondary sources included regulatory filings from FDA and EFSA, industry association reports, and company annual statements, triangulating market size. This approach ensured a comprehensive, bottom-up and top-down market assessment.
Market projection utilized a segment-weighting approach, modeling equipment demand across product type, technology, end-user, and application dimensions. The analytical framework integrated historical performance data with future growth catalysts over the projection horizon. Compound annual growth rates were derived through a regression analysis of demand drivers. Key forecast inputs included quick-service restaurant expansion rates and regulatory upgrade cycles.
The model holds under current regulatory stability and input material cost trends; deviation in global trade policies or energy price volatility would shift the market trajectory. Forecasts reflect assumptions regarding technological adoption. Practitioners should monitor new food safety legislation and raw material supply chain disruptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Crossflow Wine Filters Market
Food Processing Equipment
Hand Blender Market
Food Processing Equipment
Ice Flaking Machine Market
Food Processing Equipment
US Cold Storage Market
Food Processing Equipment
Electric Kebab Machine Market
Food Processing Equipment
Global Food and Beverage Processing Equipment Market
Food Processing Equipment
Tea Processing Equipment Market
Food Processing Equipment
Freshwater Flake Ice Machine Market
Food Processing Equipment
Food Processing Blades Market
Food Processing Equipment
Cereal Rolling Machine Market
Food Processing Equipment
Industrial Food Slicers Market
Food Processing Equipment
Sous Vide Cooking Appliances Market
Food Processing Equipment
Global Commercial Food Dehydrators Market
Food Processing Equipment
Pizza Preparation Refrigerator Market
Food Processing Equipment
Asia-Pacific Commercial Sous Vide Machine Market
Food Processing Equipment
Shrimp Peeling Machine Market