
 Reach-In Freezers Market | 2026-2036
Reach-In Freezers Market Size, Share, and Industry Trends Forecast 2026-2036
Reach-In Freezers Market Analytics
Equipment leasing and managed-service agreements is tilting competitive dynamics toward vendors with balance-sheet capacity to carry receivables. True Manufacturing leverages its domestic manufacturing footprint to sustain short-lead-time commitments to foodservice distributors. Hoshizaki Corporation anchors its position through specialized ice-making and refrigeration integration that reduces kitchen equipment redundancy. Carrier Commercial Refrigeration competes on energy-certified product lines that align with utility rebate programs across North American markets.
A reach-in freezer is a self-contained commercial refrigeration unit with vertical cabinet construction, typically featuring one to three solid or glass doors, operating at temperatures between minus 10 and 0 degrees Fahrenheit through vapor-compression cycles using hydrocarbon or HFO refrigerants. These units preserve frozen inventory in foodservice kitchens, retail backrooms, and convenience store floor plans where walk-in space is unavailable or impractical. Glass-door freezers command premium placement in front-of-house retail environments where product visibility drives impulse purchases, while solid-door variants dominate back-of-house foodservice applications where thermal efficiency and durability outweigh display requirements. Stainless steel construction leads the material segmentation due to corrosion resistance and sanitation compliance, though aluminum gains share in cost-sensitive installations.
The US Department of Energy sets minimum efficiency standards for commercial refrigeration equipment, while the Environmental Protection Agency governs refrigerant transitions under its SNAP program, phasing down high-GWP hydrofluorocarbons. The EPA's evolving rules are compelling manufacturers to redesign compressor architectures and insulation systems ahead of compliance deadlines. Stakeholders must monitor refrigerant chemistry transitions and efficiency tier migrations to avoid stranded inventory and secure specification wins with national foodservice chains.
Market Dynamics
The US Department of Energy's amended commercial refrigeration standards are compressing product development cycles and forcing compressor architecture redesigns ahead of compliance deadlines, while foodservice kitchen footprint reduction accelerates demand for compact vertical storage solutions.
Growth Catalysts
- Energy Efficiency Mandates:The US Department of Energy's commercial refrigeration standards are compelling equipment upgrades across quick-service restaurant chains, creating specification-driven replacement demand.
- Kitchen Space Compression:Foodservice operators are downsizing back-of-house footprints, prioritizing vertical reach-in units over horizontal walk-in construction where real estate costs constrain expansion.
- Refrigerant Chemistry Transition:The EPA's SNAP program phasing down high-GWP hydrofluorocarbons is accelerating R&D investment in hydrocarbon and HFO-based compressor systems.
Market Restraints
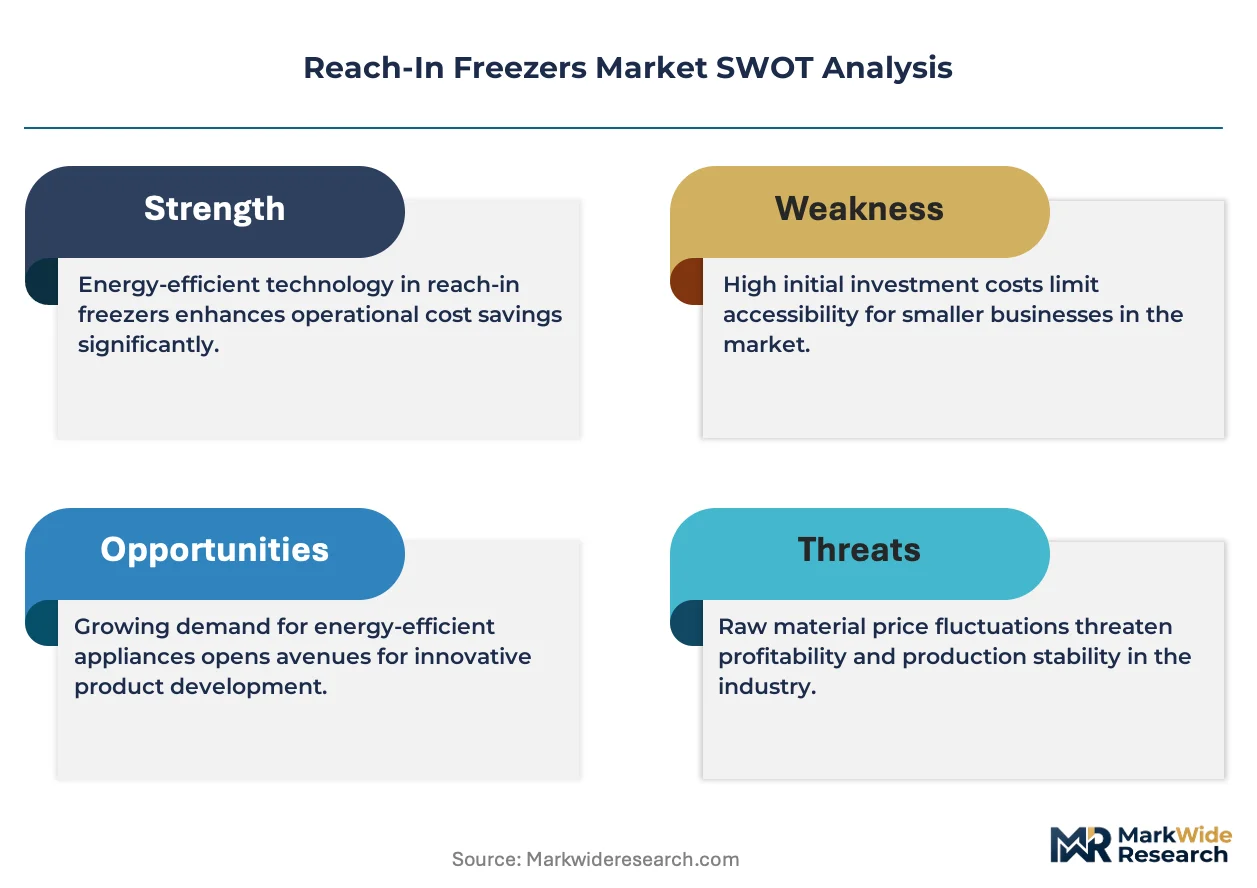
- Steel and Aluminum Input Volatility:Stainless steel construction costs fluctuate with commodity pricing, pressuring margins for manufacturers serving cost-sensitive institutional buyers.
- Compressor Supply Concentration:Specialized hermetic compressor production concentrates among a limited supplier base, creating vulnerability for mid-tier freezer assemblers.
- Regulatory Friction:Divergent state-level energy rebate program requirements complicate national product line standardization for multi-regional foodservice chains.
Strategic Opportunities
- Managed-Service Contract Expansion:Equipment-as-a-service models with predictive maintenance integration are penetrating regional foodservice distributor portfolios.
- Glass-Door Retail Penetration:Convenience store chains are expanding frozen food visibility through front-of-house display freezer deployment.
- Utility Rebate Alignment:Tiered efficiency certification programs in California and New York are creating specification advantages for ENERGY STAR-qualified product lines.
Industry Challenges
- Refrigerant Transition Timeline Compression:The EPA's evolving SNAP rules require simultaneous redesign of insulation systems and compressor architectures within compressed product development windows.
- Integration Complexity with Legacy Kitchen Systems:Retrofit installations in older foodservice locations face electrical infrastructure and spatial compatibility constraints.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reach-In Freezers Market |
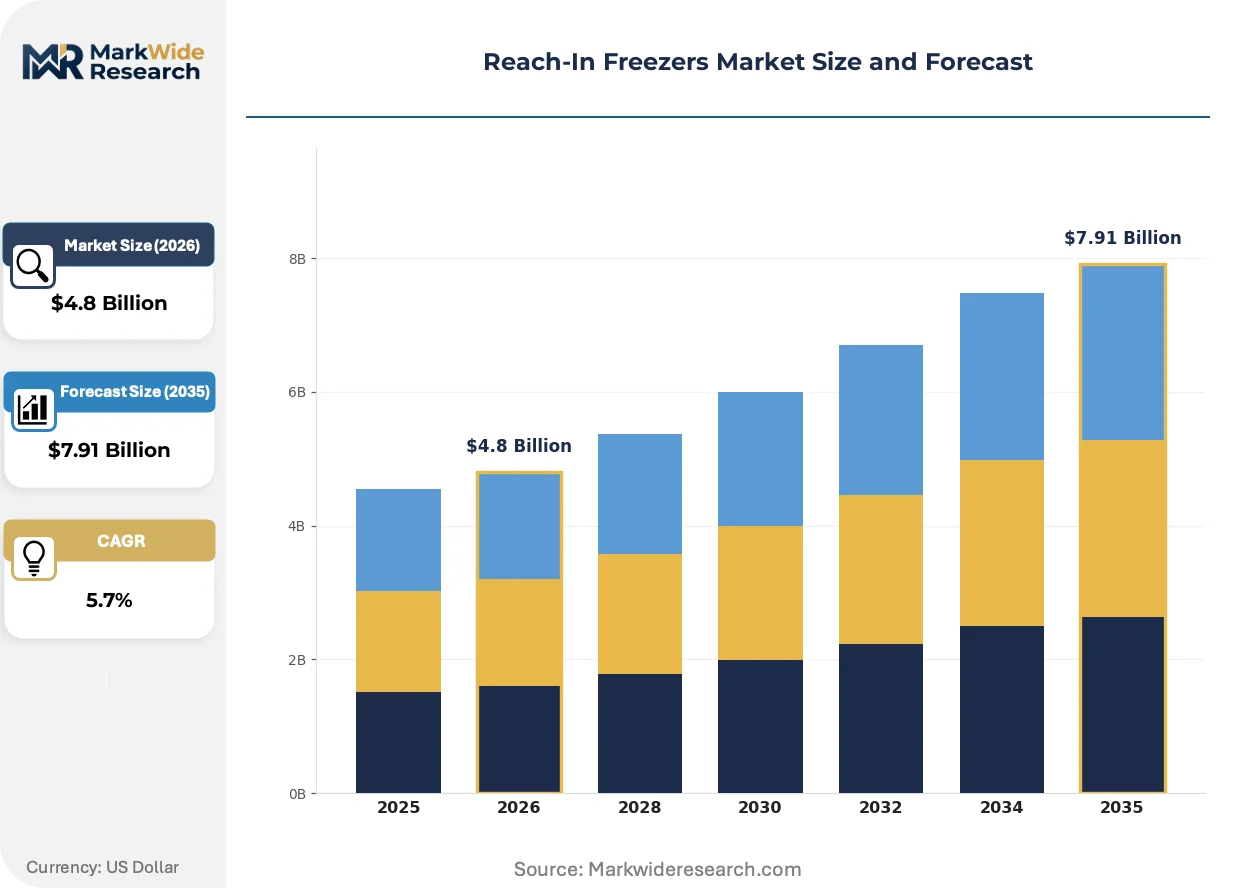
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glass-Door Freezers, Solid-Door Freezers, Countertop Freezers, Undercounter Freezers End User: Foodservice, Retail, Convenience Stores, Supermarkets Size: Small, Medium, Large, Extra Large Material: Stainless Steel, Aluminum, Plastic, Composite |
| Companies Covered | True Manufacturing, Hoshizaki Corporation, Beverage-Air, Continental Refrigerator, Avantco Refrigeration, Carrier Commercial Refrigeration, Dover Corporation, Haier Group Corporation, Daikin Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reach-In Freezers Market Evolving Landscape
Remote temperature monitoring and predictive maintenance capabilities are digitizing equipment performance management, while refrigerant chemistry transitions and procurement model evolution reshape competitive positioning across foodservice and retail channels.
IoT-enabled compressor diagnostics and cloud-connected temperature logging are digitizing fleet management for multi-unit restaurant operators. National quick-service chains are deploying these systems across retrofit programs to reduce spoilage liability and streamline health inspection documentation. The technology is digitizing service contract structures, shifting vendor relationships from break-fix models toward uptime-guarantee arrangements with penalty clauses.
The EPA's SNAP program is accelerating hydrofluorocarbon phase-down schedules for commercial refrigeration equipment categories. Manufacturers are redesigning system architectures to accommodate lower-GWP refrigerants with modified thermodynamic properties. Foodservice specification teams are prioritizing refrigerant-ready platforms that accommodate future chemistry transitions without full equipment replacement.
Foodservice operators are consolidating vendor relationships through single-source equipment and service agreements. Regional distributor networks are absorbing installation and maintenance functions previously fragmented across independent service contractors. This consolidation is most pronounced in the southeastern United States, where private-equity-backed restaurant groups are standardizing equipment specifications across portfolio locations to simplify procurement and reduce spare parts inventory complexity.
Reach-In Freezers Market Segmentation
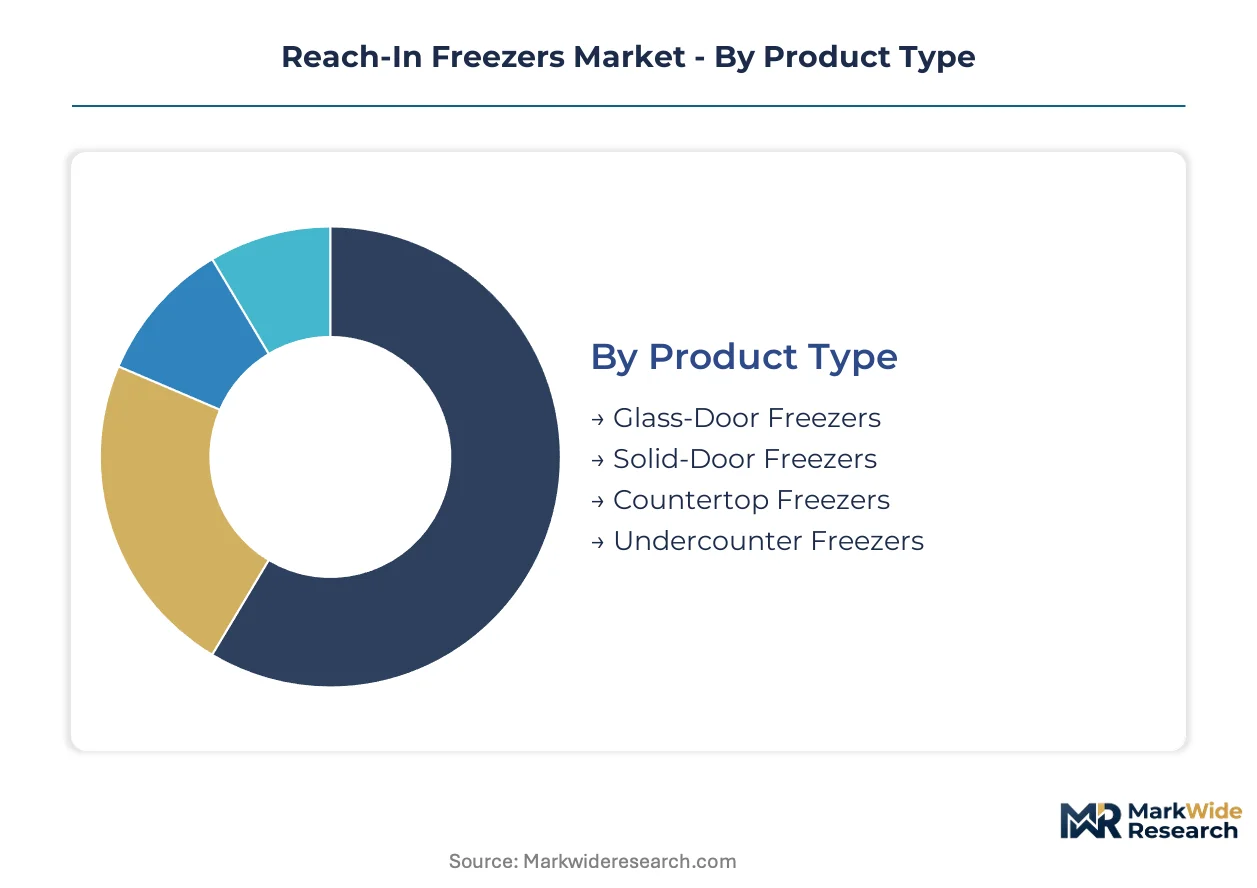
Reach-in freezer purchasing decisions cascade through multiple technical and commercial filters. Specification teams weigh thermal performance against spatial constraints, while procurement officers balance first-cost against lifecycle service exposure. Segmentation clarity enables vendors to align R&D investment with identifiable demand pockets.
Product Type:
Service intensity varies sharply across door configurations, with glass-door units demanding more frequent gasket replacement and lighting maintenance than solid-door alternatives.
- Glass-Door Freezers:Vertical cabinets with transparent panels enable product visibility without thermal compromise. Convenience store chains in the United States deploy these units front-of-house to capture impulse frozen food purchases.
- Solid-Door Freezers:Insulated metal panels maximize thermal efficiency and withstand back-of-house abuse. Quick-service restaurant kitchens favor these units where durability and energy performance outweigh display requirements.
- Countertop Freezers:Compact vertical units occupying under 10 cubic feet serve coffee shops and small-format foodservice with severe space constraints.
- Undercounter Freezers:Horizontal drawer configurations integrate beneath prep surfaces in tight kitchen footprints, common in urban restaurant retrofits.
By volume, solid-door freezers lead. By growth pace, glass-door variants are expanding most quickly.
End User:
Contract structure sophistication separates foodservice from retail procurement, with restaurant groups favoring bundled equipment-service agreements while retail buyers emphasize capital efficiency.
- Foodservice:Full-service restaurants, quick-service chains, and institutional kitchens require NSF-certified units with rapid recovery times. Chains with 50-plus locations standardize specifications to simplify spare parts logistics.
- Retail:Grocers and specialty food stores prioritize display aesthetics and energy rebate eligibility. California and New York utility programs drive specification toward tiered efficiency certifications.
- Convenience Stores:24-hour operations demand reliable compressor systems with remote monitoring compatibility. Chains are consolidating vendor relationships to reduce service response variance.
- Supermarkets:Large-format operators integrate reach-in units as supplemental storage alongside walk-in systems, typically specifying extra-large capacities for backroom overflow.
Foodservice generates the largest absolute volume. Convenience stores are gaining share fastest as frozen food offerings expand.
Size:
Shipping logistics and installation access create discontinuities in size selection, with urban foodservice operators often constrained by doorway dimensions and freight elevator capacity.
- Small:Under 15 cubic feet, these units serve kiosk operations and food trucks where electrical load limits and mobility requirements dominate.
- Medium:The 15-30 cubic foot range balances capacity against footprint, capturing the majority of independent restaurant demand.
- Large:30-50 cubic foot cabinets address high-volume quick-service backrooms and supermarket supplemental storage.
- Extra Large:Exceeding 50 cubic feet, these units approach walk-in capacity thresholds and require reinforced flooring and dedicated electrical circuits.
Medium sizes dominate unit shipments. Small formats are climbing the fastest as kitchen footprints compress.
Material:
Corrosion resistance and cleanability standards drive material selection, with coastal foodservice operators facing salt-air degradation that accelerates replacement cycles.
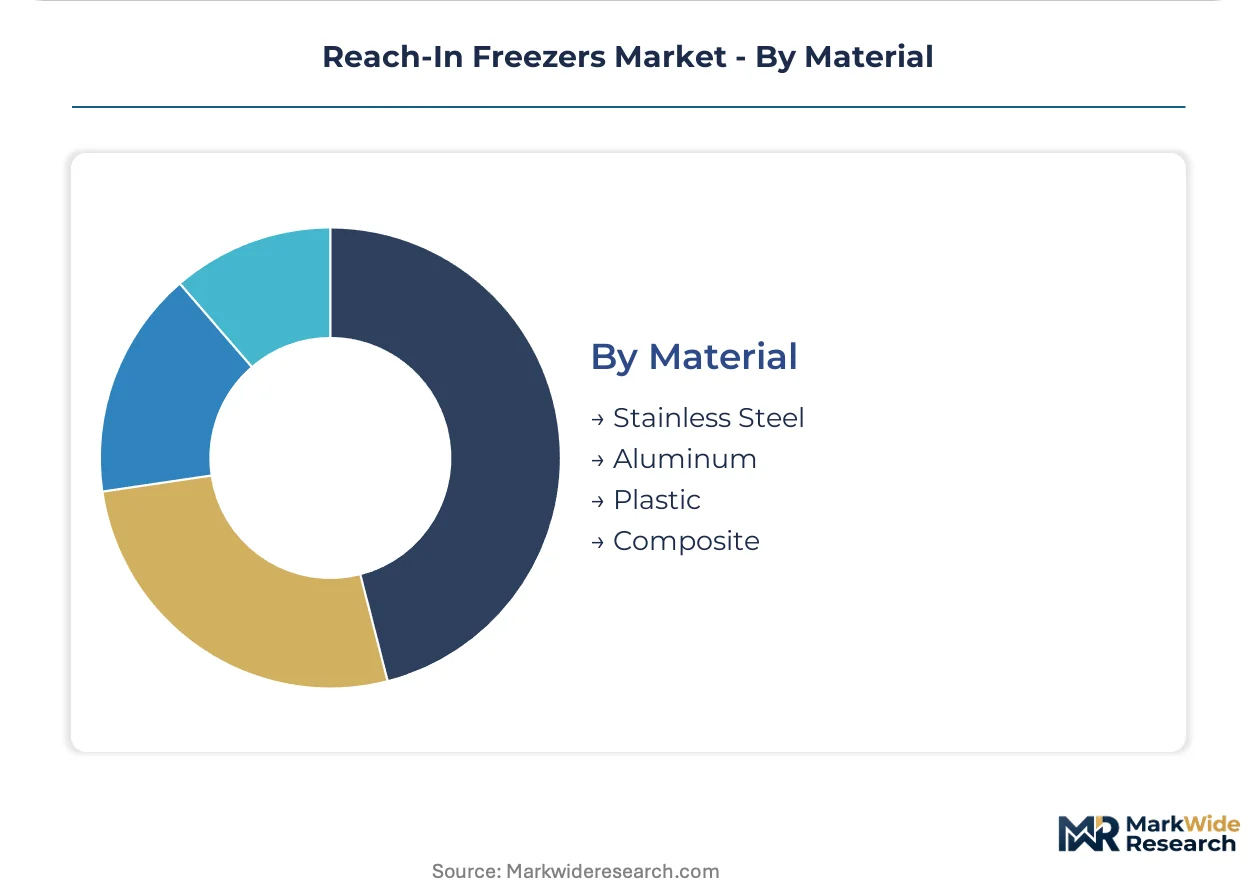
- Stainless Steel:304-grade construction resists corrosion and satisfies NSF sanitation requirements. Premium quick-service chains specify this material exclusively despite 15-20% cost premiums over alternatives.
- Aluminum:Lighter weight reduces shipping costs and simplifies installation in retrofit locations. Cost-sensitive institutional buyers in public school systems favor this material.
- Plastic:Polymer exteriors suit low-abuse environments like office breakrooms and hotel breakfast areas where aesthetic requirements are modest.
- Composite:Hybrid constructions combine metal structural elements with insulated polymer panels, emerging in European-specified units seeking weight reduction without thermal compromise.
Stainless steel commands the volume lead. Aluminum is expanding most quickly in cost-constrained segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in reach-in freezer equipment tilt toward net-importing foodservice markets with dense quick-service restaurant penetration, while manufacturing concentrates in industrial bases with established compressor supply chains and steel fabrication capacity.
United States
Quick-service restaurant chains drive specification-heavy replacement demand as retrofit programs accelerate kitchen footprint compression. The US Department of Energy's amended commercial refrigeration standards mandate efficiency tier upgrades ahead of compliance deadlines. Equipment demand clusters in Texas and California, where regional foodservice distributor networks service high-volume chain deployments.
China
Domestic foodservice expansion and cold-chain infrastructure investment propel medium-format unit demand across tier-two cities. The country's national standards administration enforces energy efficiency labeling for commercial refrigeration equipment under evolving GB standards. Manufacturing concentrates in Shandong and Guangdong provinces, where compressor component ecosystems support cost-competitive export production.
Germany
Precision-engineered equipment demand from bakery chains and institutional foodservice sustains premium-tier procurement. The EU F-Gas Regulation drives refrigerant chemistry transitions across commercial refrigeration categories. Industrial activity centers on Baden-Württemberg, where specialized metal fabrication and refrigeration component suppliers cluster around Stuttgart.
Japan
Convenience store operators with 24-hour frozen food visibility requirements specify compact glass-door units with remote monitoring compatibility. METI energy conservation standards enforce efficiency benchmarks for commercial refrigeration equipment. Tokyo-Osaka corridor demand concentrates in dense urban foodservice locations with severe spatial constraints.
India
Quick-service restaurant penetration in metropolitan areas and organized retail expansion create first-time equipment demand across mid-size cities. BIS certification requirements govern commercial refrigeration equipment safety and performance standards. Procurement activity intensifies in Maharashtra and Karnataka, where foodservice chain regional headquarters coordinate standardized equipment specifications.
Reach-In Freezers Market Competitive Landscape
On the supply side, the industry is bifurcated between integrated refrigeration specialists with captive component production and assembly-focused fabricators reliant on outsourced compressor systems. Tier-one positions concentrate among manufacturers with domestic manufacturing footprints capable of short-lead-time fulfillment. Strategic archetypes include vertically integrated cold-chain equipment conglomerates, specialist commercial kitchen refrigeration houses, and diversified appliance manufacturers leveraging scale economics. Competitive moves center on refrigerant-ready platform development and managed-service contract structures with predictive maintenance integration.
Among North American fabricators, True Manufacturing and Beverage-Air occupy positions within the specialist commercial kitchen refrigeration tier, exemplifying domestic manufacturing footprints that support distributor short-lead-time requirements. Hoshizaki Corporation anchors the integrated equipment-and-ice-systems archetype, representing Japanese-origin manufacturers with refrigeration technology diversification. These three companies illustrate distinct strategic positioning vectors: domestic fabrication specialization, integrated system design, and multinational equipment diversification.
| Leading Market Players |
|---|
| True Manufacturing |
| Hoshizaki Corporation |
| Beverage-Air |
| Continental Refrigerator |
| Avantco Refrigeration |
| Carrier Commercial Refrigeration |
| Dover Corporation |
| Haier Group Corporation |
| Daikin Industries |
| Others |
Value Network & Pricing Analysis
Compressor foundry undercapacity in East Asia is compressing component availability timelines and forcing freezer assemblers toward premium pricing for expedited delivery slots. This utilization squeeze simultaneously elevates input costs for mid-tier fabricators and reinforces pricing power among vertically integrated manufacturers with captive compressor production.
Pricing Analysis
Foodservice chain procurement teams anchor pricing structures around three-tier certification differentiation across NSF-sanitized stainless steel, standard aluminum, and economy polymer constructions. Price differentiation stems from thermal efficiency tier alignment with utility rebate programs and after-sales service bundling intensity. Cost compression in aluminum-tier units is intensifying because commodity volatility and tariff exposure on Chinese-sourced sheet metal are compressing assembler margins. Institutional buyers in public school systems exhibit highest price sensitivity, while premium quick-service chains prioritize specification compliance over first-cost minimization.
Supply Chain Analysis
Specialized hermetic compressor manufacturing concentrates among facilities in China, Thailand, and Mexico, with Shandong and Guangdong provinces hosting the densest component ecosystems. Raw material flows draw from stainless steel mills in the United States and India, aluminum smelters in Canada, and hydrocarbon refrigerant suppliers in the Middle East. Single-source vulnerability in hermetic compressor architectures creates systemic risk for assembly-focused fabricators lacking backward integration. Distribution runs through regional foodservice equipment distributors that consolidate installation and aftermarket service functions previously fragmented across independent contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Short-lead-time fulfillment capability has become the scarce asset in this market, with only domestic manufacturing footprints capable of meeting quick-service chain retrofit schedules. This capability gap separates specification winners from margin-challenged assemblers.
For Market Incumbents: Harden defensible positioning through captive compressor supply arrangements and ENERGY STAR certification pre-alignment with California and New York utility rebate windows. Threat exposure from refrigerant chemistry transitions under EPA SNAP rules demands simultaneous insulation and architecture redesigns; vertical integration into hydrocarbon-compatible compressor sourcing is the critical lever for avoiding stranded inventory. For New Entrants and Emerging Players: India's metropolitan quick-service expansion represents the most penetrable white-space corridor, with Maharashtra and Karnataka regional headquarters standardizing equipment specifications across portfolio locations. Glass-door convenience store deployments in tier-two Chinese cities offer secondary entry traction. Go-to-market execution should emphasize managed-service contract structures with predictive maintenance integration to displace fragmented independent service networks. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among equipment-as-a-service providers with integrated temperature monitoring platforms and uptime-guarantee arrangements. Long-term viability over the projection horizon favors manufacturers with refrigerant-ready platform architectures accommodating future chemistry transitions without full equipment replacement. The signal to watch is EPA SNAP rule acceleration timelines, which would compress product development windows and strand non-compliant inventory.| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant-Ready Platform Development | EPA SNAP compliance deadlines force simultaneous compressor and insulation redesigns ahead of phase-down schedules. |
| Managed-Service Contract Expansion | Predictive maintenance integration digitizes fleet management for multi-unit restaurant operators and reduces spoilage liability. |
| Domestic Manufacturing Footprint Expansion | Short-lead-time commitments to foodservice distributors secure specification wins with national quick-service chains. |
| Utility Rebate Program Alignment | ENERGY STAR certification unlocks tiered efficiency incentives in California and New York procurement specifications. |
| Glass-Door Retail Penetration | Convenience store chains deploy front-of-house display freezers to capture impulse frozen food purchases. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with foodservice chain specification directors, regional equipment distributor principals, compressor component procurement leads, and commercial kitchen design consultants. Secondary validation drew from US Department of Energy efficiency standard filings, EPA SNAP program rulemakings, utility rebate program databases, and trade flow records from customs administrations. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions.
Calibration against historical replacement cycles and regulatory compliance deadlines anchored growth trajectory assumptions across the analysis window. Segmentation dimensions modeled include door configuration, end-use vertical, size tier, material construction, and regional regulatory cluster. CAGRs derived from fitted growth curves incorporating foodservice footprint compression rates, chain expansion pipelines, and refrigerant transition timelines. Forecast inputs included quick-service restaurant retrofit program announcements and convenience store frozen food visibility investments.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by integrated refrigeration conglomerates or accelerated EPA rulemaking would shift outcomes beyond modeled ranges. Quarterly review of compressor component lead times, utility rebate program tier adjustments, and SNAP program rulemaking velocity is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Sous Vide Cooking Appliances Market
Food Processing Equipment
Cookers and Ovens Market
Food Processing Equipment
Hydrostatic Steam Blancher Market
Food Processing Equipment
Optical Sorter Market
Food Processing Equipment
Craft Beer Saccharification Equipment Market
Food Processing Equipment
Batter Mixer Machines Market
Food Processing Equipment
Freeze Thaw Chambers Market
Food Processing Equipment
Conveyor Ovens and Impinger Ovens Market
Food Processing Equipment
Global Conveyor Oven Market
Food Processing Equipment
Brewing Chiller Market
Food Processing Equipment
Non-Thermal Food Processing Market
Food Processing Equipment
Homogenizers Market
Food Processing Equipment
Commercial Mixer Market
Food Processing Equipment
Deep Fryer Market
Food Processing Equipment
North America Commercial Sous Vide Machine Market
Food Processing Equipment
Mixing Vessels Market