
 Commercial Winery Equipment Market | 2026-2036
Commercial Winery Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Winery Equipment Market Outlook
Market Context
The commercial winery equipment landscape is restructuring around a sharp divergence between premium craft-scale systems and high-volume commodity lines. Krones AG dominates automated bottling corridors with integrated inspection and filling architectures that sustain throughput advantages across major wine regions. GEA Group leverages thermal processing specialization to anchor margins in flash-pasteurization and stabilization units. Bucher Industries competes through pneumatic pressing technology leadership that differentiates its footprint in premium red-wine extraction.
Technical Definition and Segment Structure
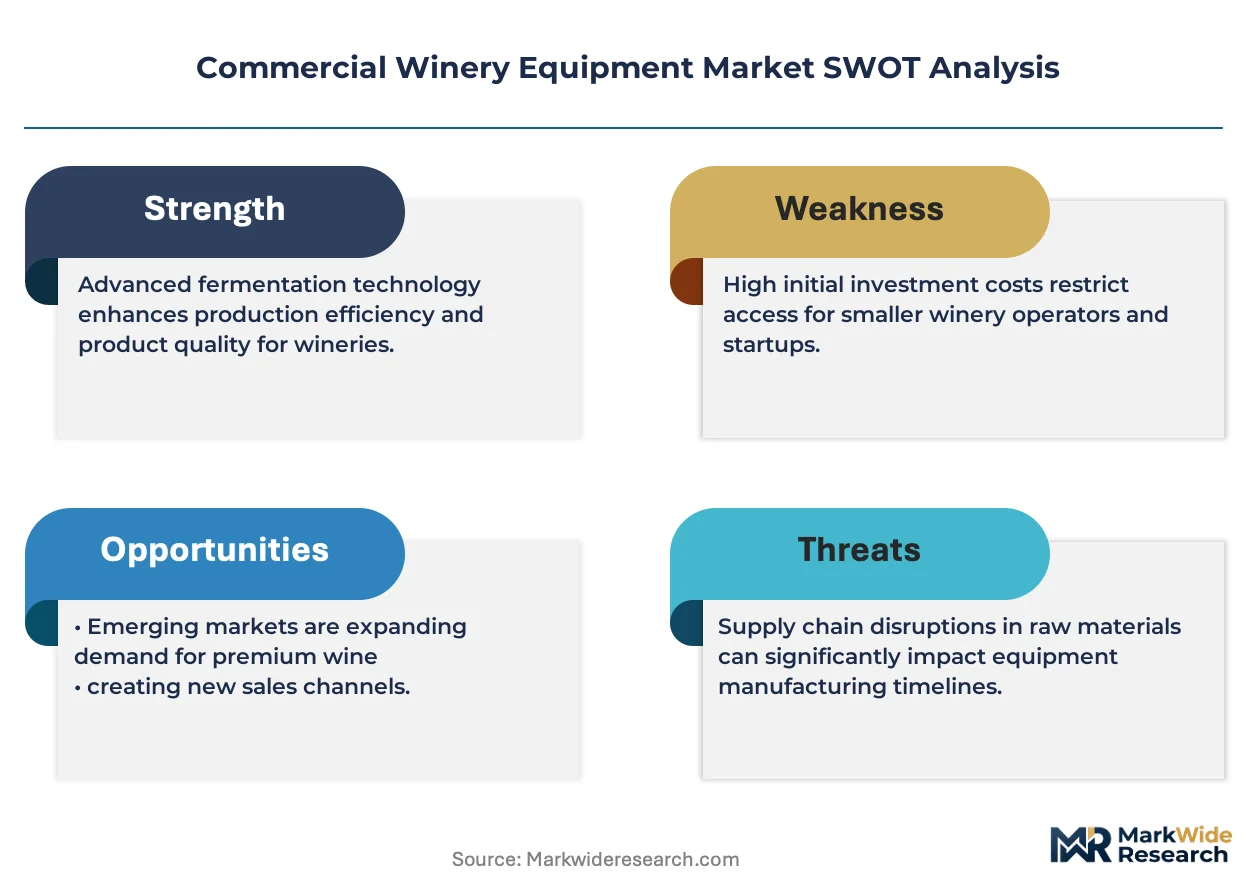
Commercial winery equipment encompasses the engineered machinery, vessels, and process-control systems used to transform harvested grapes into finished wine through controlled fermentation, clarification, stabilization, and packaging operations. Stainless steel fermentation tanks with glycol-jacketed temperature control represent the core capital investment for most production facilities, typically rated from 1,000 to 50,000 liters and designed for CIP (clean-in-place) sanitation cycles. Fermentation tanks command the largest installed base but face margin compression from commoditized Asian fabrication, while automated systems across crushing, pressing, and bottling lines capture the fastest replacement demand as labor costs escalate. Bottling equipment concentrates value in aseptic filling and corking subsystems where throughput reliability directly shapes winery operating economics.
Regulatory Frame and Outlook
FDA food-contact substance regulations govern stainless steel grades and elastomer seals in US-bound equipment, while EU machinery directives and CE marking mandate specific guarding and interlock standards for automated press and bottling lines sold across Europe. Australia's Food Standards Code and Wine Australia labeling requirements further shape equipment specifications for export-compliant production. Stakeholders must monitor evolving energy-efficiency thresholds in California and EU jurisdictions, as these will increasingly disqualify legacy thermal processing and refrigeration architectures from new installations.
Market Dynamics
Automated bottling architectures are compressing replacement cycles across premium wine regions as labor arbitrage erodes and FDA food-contact material standards tighten for stainless steel grades and elastomer seals.
Growth Catalysts
- REACH substance restrictions:European wineries accelerate tank replacement to eliminate legacy sealing compounds now restricted under ECHA candidate list updates, pulling forward capital expenditure timelines.
- Flash-pasteurization systems:Thermal processing upgrades anchor margin expansion for facilities targeting export compliance with Australia's Food Standards Code and Wine Australia labeling requirements.
- Napa Valley cluster:Boutique producers in California's premium corridor consolidate purchasing power for integrated crush-press-bottle lines, creating concentrated demand pools for automated architectures.
Market Restraints
- Commoditized Asian fabrication:Stainless steel fermentation tanks face margin compression from standardized 1,000-50,000 liter vessels produced at scale in Chinese and South Korean fabrication centers.
- Specialized alloy supply:Food-grade 316L stainless availability concentrates in German and Japanese mill networks, exposing equipment manufacturers to input cost volatility and extended lead times.
- CE marking complexity:EU machinery directive compliance for automated press and bottling lines requires third-party guarding validation that extends delivery schedules by 8-14 weeks.
Strategic Opportunities
- Barossa Valley expansion:Australian premium red-wine extraction capacity remains underpenetrated for pneumatic pressing technology, offering whitespace for specialized system deployment.
- EU Green Deal alignment:Energy-efficiency thresholds in thermal processing and refrigeration architectures will disqualify legacy equipment, mandating replacement demand across Italian and French production bases.
- Service unbundling:Predictive maintenance contracts for glycol-jacketed temperature control systems represent emerging recurring revenue streams separate from capital equipment sales.
Industry Challenges
- CIP sanitation engineering:Clean-in-place cycle optimization for mixed fermentation and clarification vessels requires specialized process design talent scarce in regional equipment dealer networks.
- Legacy system integration:Automated bottling line retrofits must interface with existing corking and labeling subsystems, creating commissioning complexity and downtime risk during cutover.
- ISO 22000 certification timelines:Food safety management system validation for export-bound equipment stretches 6-9 months, delaying revenue recognition on completed builds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Winery Equipment Market |
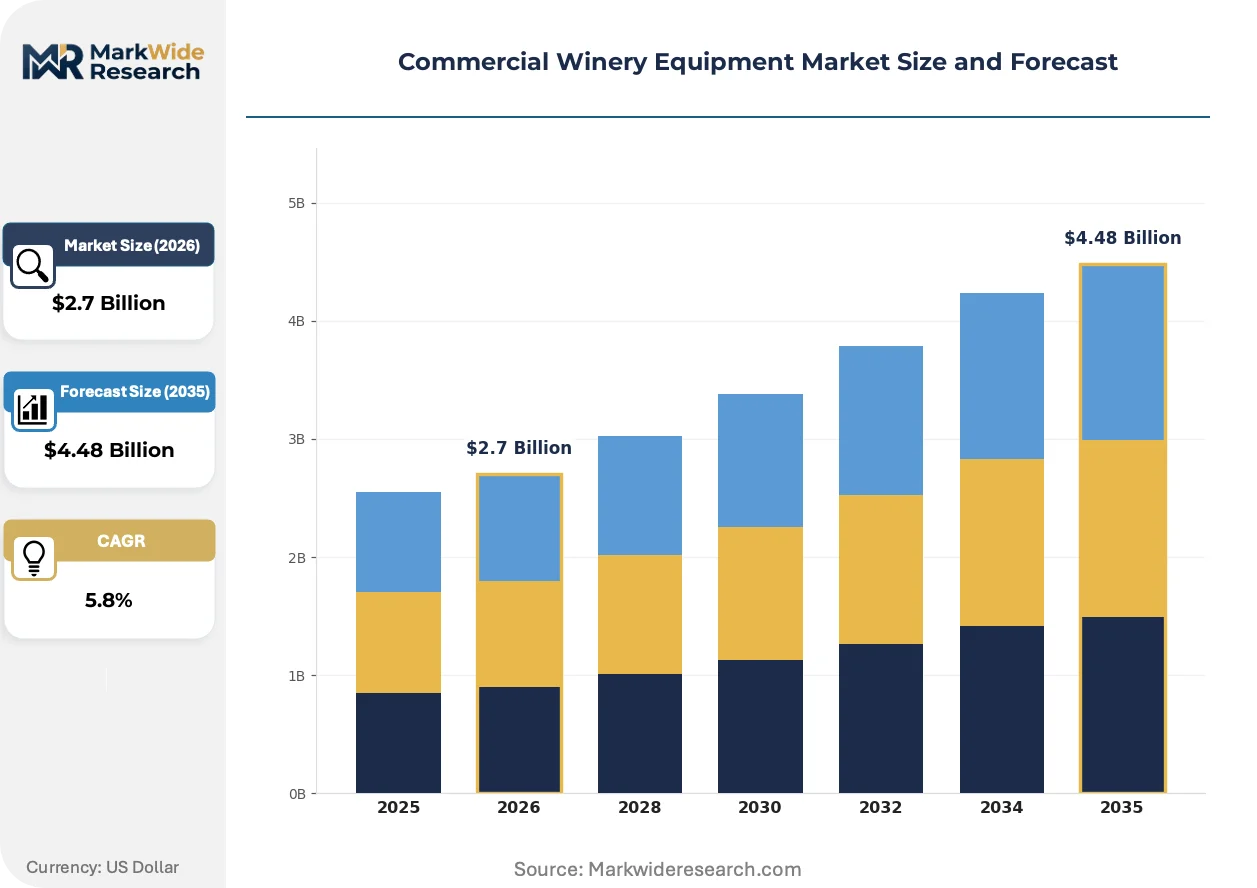
| Market Size in 2026 | $2.7 Billion |
| Market Size in 2035 | $4.48 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fermentation Tanks, Bottling Equipment, Presses, Crushers Technology: Automated Systems, Manual Systems, Pneumatic Pressing, Thermal Processing End User: Wineries, Vineyards, Beverage Producers, Research Institutions Application: Wine Production, Quality Control, Packaging, Storage |
| Companies Covered | Criveller Group, Gai S.p.A., Krones AG, Bucher Industries, Della Toffola, GEA Group, G.W. Kent, Paul Mueller Company, Zambelli Enotech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Winery Equipment Market Strategic Shifts
Digital process control architectures are reshaping winery capital planning as precision fermentation and energy-recovery systems displace manual intervention and thermal waste. Equipment specifications now prioritize data interoperability and modular upgrade paths over monolithic line replacements.
IoT-enabled tank monitoring systems is integrating pressure, temperature, and brix sensors into unified control planes that feed predictive algorithms. Mid-scale producers in France's Bordeaux region deploy these architectures fastest, compressing fermentation cycle variance and reducing spoilage rates. The technology is integrating distributed sensor networks with centralized SCADA platforms, enabling remote intervention that collapses staffing requirements per hectoliter.
F-Gas Regulation phase-down mandates are forcing refrigeration system redesigns across EU-bound equipment. Wineries in Germany and Spain face accelerated replacement timelines for legacy cooling architectures using restricted refrigerants. Thermal processing specialists respond with CO2-based heat pump systems that satisfy efficiency thresholds while maintaining glycol-jacketed temperature precision.
Equipment-as-service contracting is displacing traditional capital purchase models among California's emerging wine producers. Third-party ownership of crush, press, and bottling assets spreads across Sonoma County and Central Coast clusters, transferring obsolescence risk to OEM balance sheets. This arrangement concentrates most visibly in facilities under 50,000-case annual output, where capital constraints intersect with volatility in grape pricing.
Commercial Winery Equipment Market Segmentation
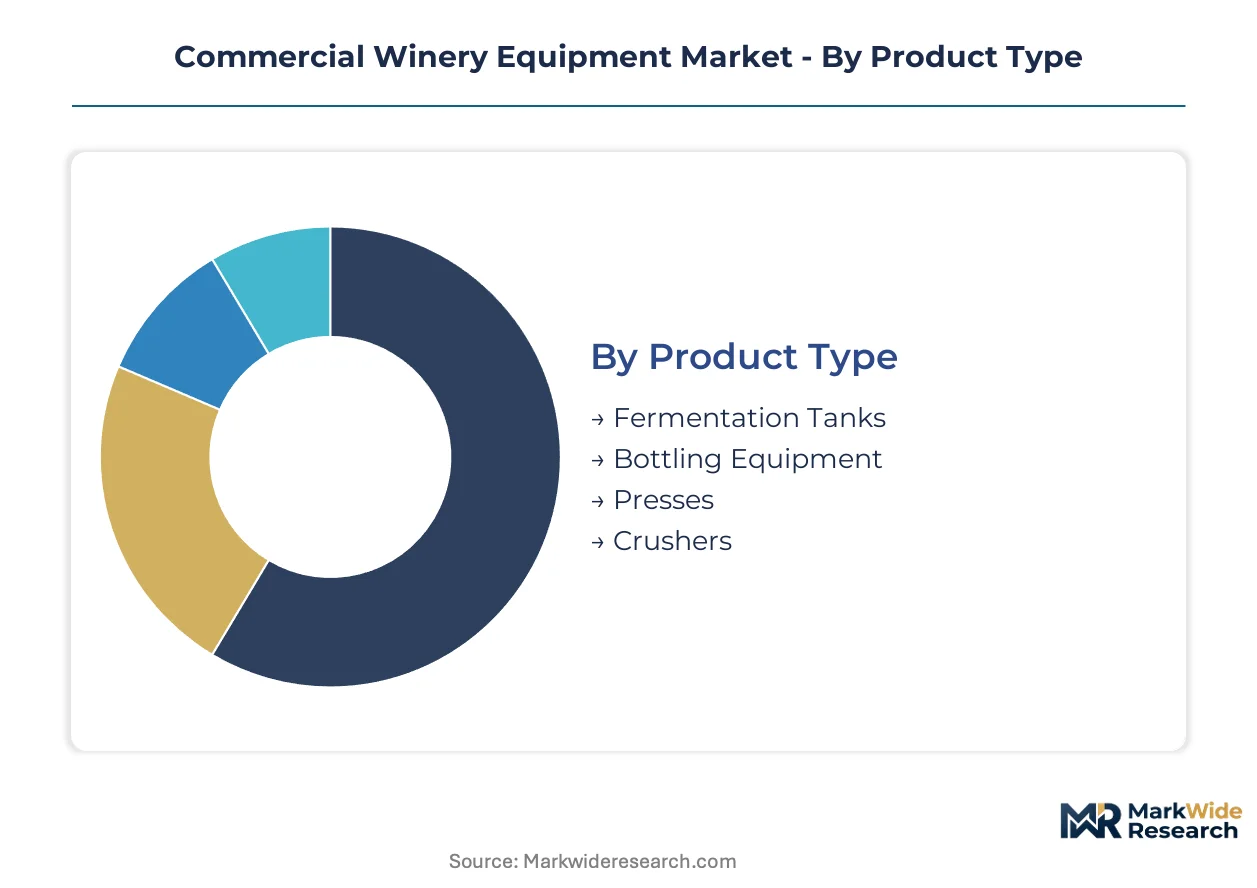
Winery equipment segmentation reveals how capital deployment splits between integrated production lines and standalone unit purchases. Equipment buyers prioritize compatibility with existing infrastructure over isolated performance specifications.
Product Type:
Standalone vessels dominate initial capital outlays, while embedded bottling architectures reshape replacement economics across premium wine corridors.
- Fermentation Tanks:Stainless steel vessels with glycol-jacketed temperature control rated 1,000-50,000 liters constitute the foundational capital commitment for most facilities. Napa Valley boutique producers are upgrading to CIP-optimized designs as FDA food-contact material standards tighten for 316L grades and elastomer seals.
- Bottling Equipment:Integrated filling, corking, and inspection architectures capture the fastest replacement demand as labor arbitrage erodes in France, Italy, and Australia's Barossa Valley. Aseptic filling subsystems concentrate value where throughput reliability directly shapes operating economics.
- Presses:Pneumatic pressing technology anchors premium red-wine extraction capacity in underpenetrated Australian corridors.
- Crushers:Destemmer-crusher units serve as entry-point automation for facilities transitioning from manual harvest processing.
Fermentation tanks lead volumes today; bottling equipment is gaining share fastest.
Technology:
Cost tiers separate precision-controlled architectures from mechanical alternatives, with thermal and pneumatic systems commanding premium positioning.
- Automated Systems:SCADA-integrated crush-press-bottle lines with IoT-enabled monitoring compress staffing requirements per hectoliter. Bordeaux mid-scale producers deploy these architectures fastest, collapsing fermentation cycle variance through distributed sensor networks feeding predictive algorithms.
- Thermal Processing:Flash-pasteurization and stabilization units anchor margin expansion for facilities targeting export compliance with Australia's Food Standards Code. CO2-based heat pump redesigns respond to EU F-Gas Regulation phase-down mandates affecting German and Spanish wineries.
- Pneumatic Pressing:Specialized extraction technology differentiates footprint in premium red-wine production.
- Manual Systems:Mechanical alternatives persist in craft-scale facilities where capital constraints intersect with volatility in grape pricing.
Manual systems retain installed-base dominance; automated architectures are climbing the fastest.
End User:
Volume scale dictates procurement patterns, with emerging producers favoring service-based arrangements over balance-sheet ownership.
- Wineries:Production facilities from boutique to industrial scale drive equipment specifications, with California's Sonoma County and Central Coast clusters consolidating purchasing power for integrated lines.
- Vineyards:Estate-based operations with captive grape supply invest earlier in crush and fermentation capacity.
- Beverage Producers:Diversified alcohol manufacturers cross-utilize bottling infrastructure across product categories.
- Research Institutions:Enology programs and experimental facilities sustain demand for pilot-scale fermentation systems with precision monitoring capabilities.
Wineries command current revenue concentration; research institutions are expanding most quickly.
Application:
Customer type stratification separates production-focused buyers from compliance and logistics-oriented purchasers.
- Wine Production:Core fermentation, pressing, and clarification operations absorb the majority of capital deployment across French, Italian, and Australian production bases.
- Packaging:Aseptic filling and export-compliant labeling systems concentrate investment where Wine Australia and EU machinery directive requirements intersect.
- Quality Control:In-line inspection and laboratory analysis equipment supports FDA and EFSA compliance validation.
- Storage:Temperature-controlled warehousing and tank farm infrastructure completes the value chain for export-bound production.
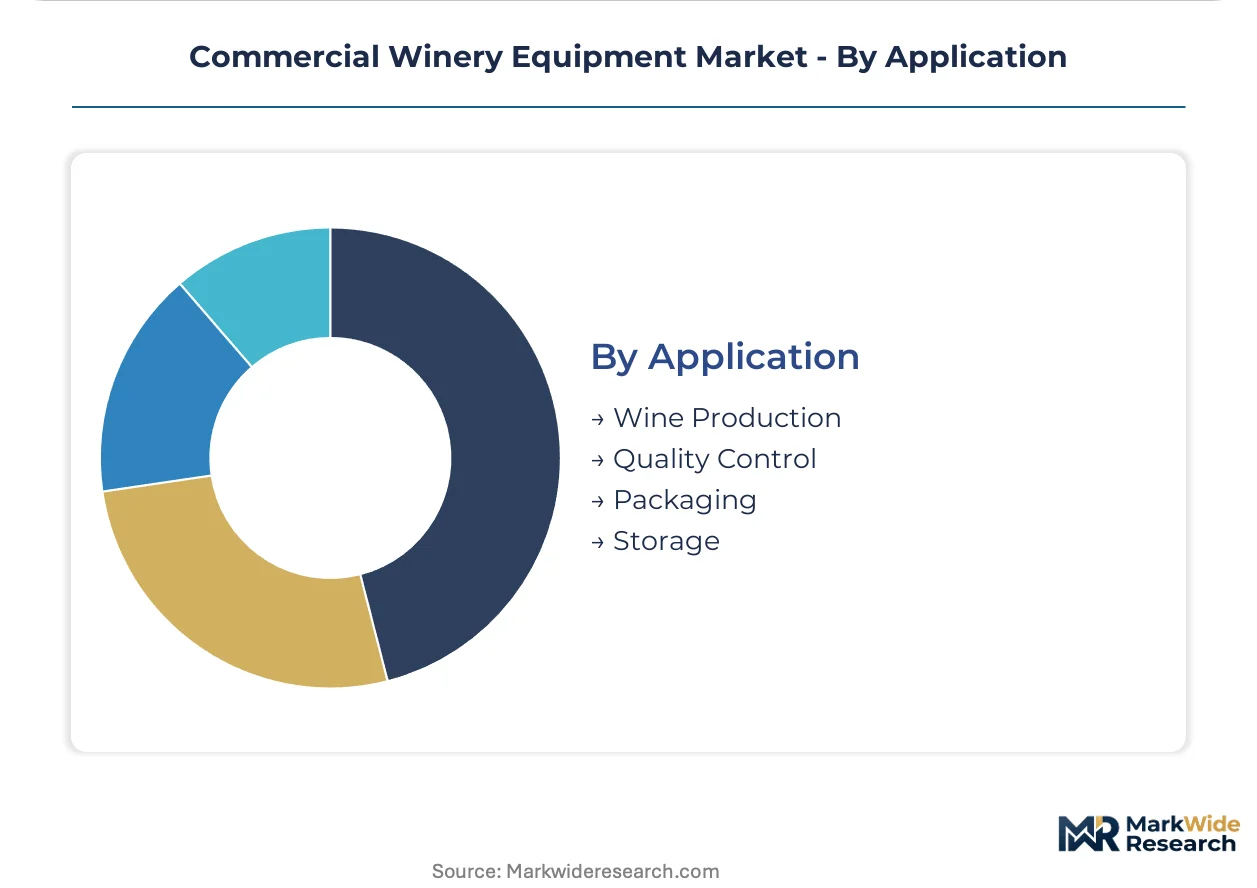
Wine production anchors current investment; packaging is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Winemaking talent concentrates in France's Champagne and Burgundy regions, where generational cellar masters anchor equipment specification expertise. California's Napa Valley employs the densest concentration of enology-trained technicians outside Europe. Australia's Barossa Valley draws specialized fermentation engineers from Adelaide's research universities.
United States
FDA food-contact material standards for stainless steel grades and elastomer seals are compressing replacement cycles across California's premium corridors. Boutique producers in Napa Valley and Sonoma County consolidate purchasing power for integrated crush-press-bottle architectures. Central Coast clusters around Paso Robles are deploying automated bottling lines fastest as labor costs escalate.
France
REACH substance restrictions on legacy sealing compounds are accelerating tank replacement timelines in Bordeaux and Champagne. EU machinery directive compliance for automated press lines extends delivery schedules through third-party guarding validation. Mid-scale producers in Bordeaux deploy IoT-enabled fermentation monitoring faster than any other European cluster.
Italy
EU Green Deal energy-efficiency thresholds are disqualifying legacy thermal processing architectures across Piedmont and Tuscany. CE marking complexity for automated bottling equipment creates 8-14 week delivery extensions. Producers in Emilia-Romagna anchor the strongest demand for pneumatic pressing technology in premium red-wine extraction.
Australia
Wine Australia labeling requirements and Food Standards Code compliance are anchoring investment in flash-pasteurization and export-compliant packaging systems. Barossa Valley remains underpenetrated for specialized pressing capacity relative to its premium red-wine output. South Australian producers face accelerated refrigeration system redesigns under F-Gas Regulation phase-down mandates.
Germany
F-Gas Regulation phase-down is forcing CO2-based heat pump adoption across thermal processing and refrigeration architectures in Rheinhessen and Pfalz. Food-grade 316L stainless supply concentrates in German and Japanese mill networks, exposing equipment manufacturers to input cost volatility. Bavarian fabrication centers supply precision-engineered fermentation controls to wineries across Central Europe.
Commercial Winery Equipment Market Competitive Environment
Top-tier vendors anchor integrated system architectures, while mid-scale specialists compete on pneumatic pressing and thermal processing differentiation. The vendor base stratifies across three tiers: full-line automation providers, component specialists in fermentation or bottling subsystems, and regional fabrication shops serving craft-scale facilities. Two strategic archetypes dominate competitive positioning: precision-engineered European fabricators and scale-driven Asian tank producers. M&A activity concentrates on automation technology tuck-ins, while capacity expansion focuses on glycol-jacketed vessel fabrication in response to CIP-optimized demand.
Among the named players, Krones AG and GEA Group exemplify the integrated-systems archetype, anchoring positions in automated bottling and thermal processing respectively. Bucher Industries occupies a specialist position in pneumatic pressing technology. Criveller Group, Gai S.p.A., and Della Toffola represent the Italian fabrication tradition concentrated in premium equipment segments. Paul Mueller Company and G.W. Kent anchor North American supply chains for stainless vessel and accessory distribution. Zambelli Enotech sits within the craft-scale specialist tier serving emerging producers.
| Leading Market Players |
|---|
| Criveller Group |
| Gai S.p.A. |
| Krones AG |
| Bucher Industries |
| Della Toffola |
| GEA Group |
| G.W. Kent |
| Paul Mueller Company |
| Zambelli Enotech |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between FDA-compliant 316L stainless systems and commodity Asian-fabricated vessels splits pricing power and supply chain sourcing simultaneously. Premium-tier buyers absorb 40-60% cost premiums for CE-marked, CIP-optimized architectures while budget-constrained facilities default to standardized tanks from Chinese and South Korean mills, compressing margins across the mid-market.
Pricing Analysis
Bundled equipment-as-service contracts are displacing per-unit transactional sales among California's sub-50,000-case producers, unbundling capital risk from operating expenditure. Pricing stratifies across premium certified, standard compliant, and economy non-certified tiers, with ISO 22000 validation and FDA food-contact material compliance commanding measurable premiums. Cost compression in economy fermentation tanks intensifies because standardized Asian fabrication floods spot markets with interchangeable 1,000-50,000 liter vessels. Boutique wineries in Napa Valley exhibit lowest price sensitivity, prioritizing throughput reliability and regulatory defensibility over capital outlay minimization.
Supply Chain Analysis
Ocean freight cost volatility from German, Italian, and Chinese fabrication centers to California and Australian wine corridors shapes landed cost structures and inventory positioning strategies. Food-grade 316L stainless concentrate in German and Japanese mill networks, while precision control systems and pneumatic pressing assemblies source predominantly from Italian engineering clusters. Single-source vulnerability in specialized alloy supply exposes equipment fabricators to input cost spikes and extended lead times. Distribution runs through regional dealer networks with captive service capabilities, anchoring aftermarket revenue streams and customer lock-in.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates in automated bottling architectures and thermal processing upgrades, driven by labor cost escalation and F-Gas Regulation-mandated refrigeration redesigns across EU production bases.
For Market Incumbents: Lock in service contract revenue streams through predictive maintenance offerings for glycol-jacketed temperature control systems, insulating against commoditization pressure from Asian tank fabricators. Deepen backward integration into food-grade 316L stainless supply relationships with German and Japanese mill networks, reducing exposure to alloy price volatility and extended lead times that currently compress delivery reliability. For New Entrants and Emerging Players: Capture whitespace in Australian Barossa Valley pneumatic pressing capacity, where premium red-wine extraction demand outstrips specialized equipment deployment. Target emerging California Central Coast producers with equipment-as-service contracting models that transfer obsolescence risk from capital-constrained buyers to OEM balance sheets, accelerating market penetration against traditional purchase structures. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-scale automation specialists possess IoT-enabled monitoring architectures but lack thermal processing or bottling integration capabilities. Long-term viability favors vendors with recurring service revenue exposure and EU Green Deal-aligned product portfolios. Watch F-Gas Regulation enforcement intensity as the critical inflection signal for refrigeration system replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Equipment-as-Service Contracting | Transfers capital risk from California boutique producers to OEM balance sheets, accelerating penetration. |
| Backward Integration into Alloy Supply | Secures food-grade 316L stainless from German and Japanese mills, reducing input cost volatility exposure. |
| CO2-Based Heat Pump Redesign | Aligns thermal processing architectures with EU F-Gas Regulation phase-down mandates affecting German wineries. |
| Predictive Maintenance Service Unbundling | Generates recurring revenue from glycol-jacketed temperature control systems separate from capital sales. |
| CE Marking Pre-Validation Investment | Compresses 8-14 week delivery extensions for automated bottling lines sold across European jurisdictions. |
Study Parameters
Bottom-up winery capacity modeling reconciled against top-down equipment shipment tracking forms the analytical core of this study. Primary interviews with cellar masters, equipment procurement directors, OEM sales engineers, and aftermarket service heads informed demand-side validation. Secondary sources include customs and trade flow data for stainless steel vessel imports, FDA food-contact substance filings, EU machinery directive registration databases, and Wine Australia export compliance records. Triangulation between facility-level capital expenditure surveys and manufacturer order book analysis ensures dimensional consistency.
Historical trendline analysis of replacement cycle compression and technology substitution patterns anchors projection modeling across the forecast horizon. Segmentation dimensions include equipment type, automation tier, end-user scale, and regional regulatory cluster, with energy-efficiency threshold evolution and labor cost trajectories serving as key forecast inputs. CAGRs derive from fitted growth curves calibrated against observed capital deployment timing and regulatory mandate acceleration effects.
Alloy supply disruption, REACH substance restriction expansion, and F-Gas Regulation enforcement timing are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions about replacement cycle elasticity and service contract adoption rates. Stakeholders should weight assumptions against their own operating context and regional regulatory exposure profiles.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Cookie Dropper Machine Market
Food Processing Equipment
Fish Processing Equipment Market
Food Processing Equipment
Wine Bottling Machine Market
Food Processing Equipment
Beverage Processing Equipment Market
Food Processing Equipment
Ultrasonic Homogenizer Machines Market
Food Processing Equipment
Deep Fryer Market
Food Processing Equipment
Commercial Panini Machine Market
Food Processing Equipment
Industrial Food Milling Machine Market
Food Processing Equipment
Bottling Machinery Market
Food Processing Equipment
Pan Feeder Market
Food Processing Equipment
Commercial Oven for Bakery Market
Food Processing Equipment
Convection Ovens Market
Food Processing Equipment
High Speed Oven Market
Food Processing Equipment
Food Ultrasound Market
Food Processing Equipment
Blast Chillers Market
Food Processing Equipment
Yogurt Makers Market