
 Marine Fire Extinguishing System Market | 2026-2036
Marine Fire Extinguishing System Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Fire Extinguishing System Market Foresight
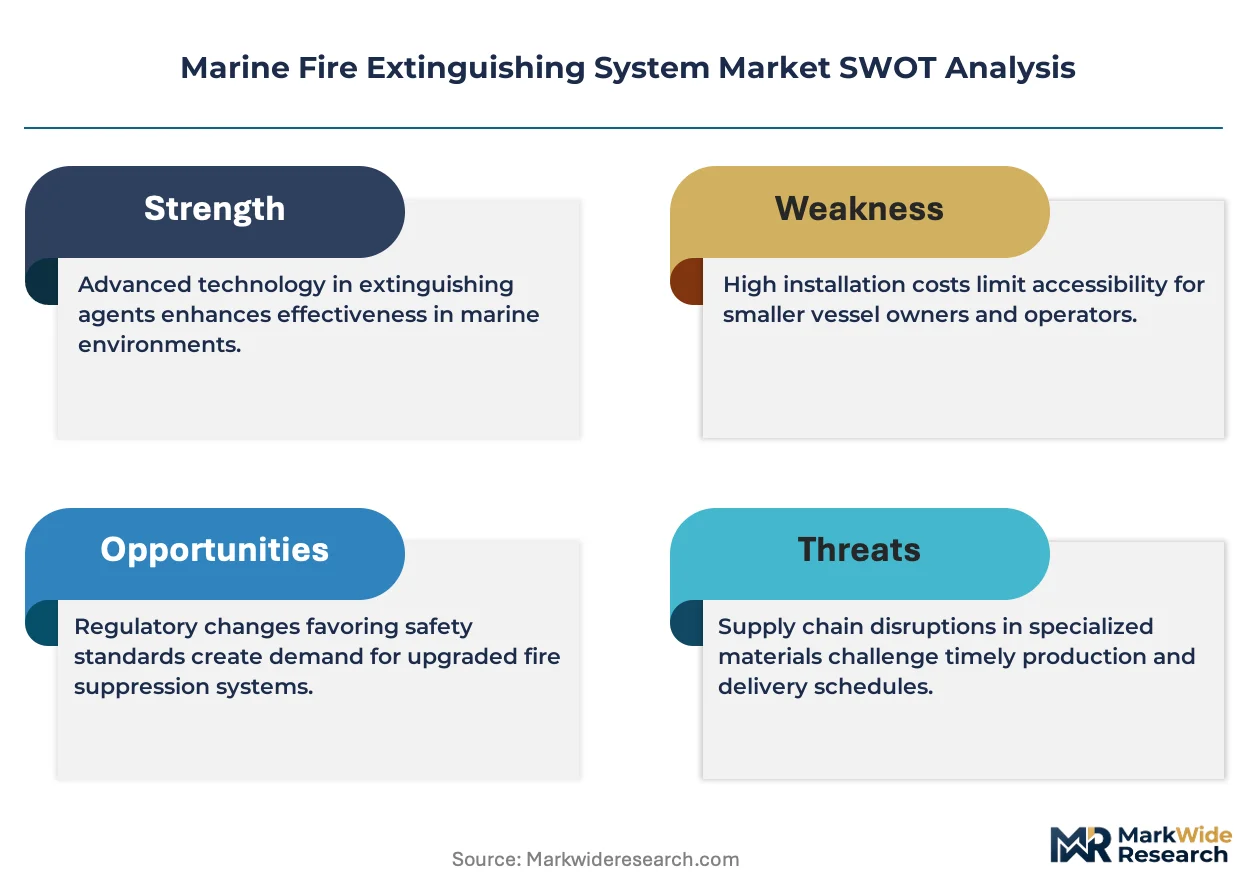
IMO SOLAS certification cycles for marine fire suppression systems is unwinding competitive access, favoring suppliers with sustained type-approval track records. Wärtsilä leverages its integrated automation portfolio to bundle fire safety with propulsion control systems. Minimax GmbH & Co. KG anchors its position through deep specialization in high-pressure water mist for engine rooms and machinery spaces. Consilium Safety Group AB competes on sensor-driven hybrid architectures that bridge manual and automatic activation protocols.
Marine fire extinguishing systems comprise engineered assemblies of suppressant agents, distribution networks, detection sensors, and discharge nozzles designed to contain and suppress combustion in confined maritime environments, typically operating at pressures between 80 and 200 bar for water mist applications and requiring corrosion-resistant alloys for saltwater exposure. These systems protect life, cargo, and vessel integrity across commercial shipping, naval operations, and offshore energy infrastructure. Water mist technology leads product type configurations due to minimal collateral damage and reduced weight penalties, while integrated technology platforms capture the fastest expansion as shipbuilders specify centralized safety management systems. Commercial vessels and offshore platforms represent the deepest application margin pools, driven by regulatory mandates for redundant protection zones and remote monitoring capabilities.
FDA marine equipment export protocols, EPA restrictions on halon replacement chemistries, and IMO SOLAS Chapter II-2 collectively shape product formulation, testing regimes, and market access conditions for system suppliers. The EU MDR and CE marking requirements further constrain component sourcing for vessels operating under European flag registries. Stakeholders must monitor the divergence between national maritime authority interpretations of integrated system standards, as inconsistent enforcement creates compliance fragmentation that favors regionally entrenched certification holders.
Market Dynamics
IMO SOLAS Chapter II-2 retrofit mandates are compressing replacement cycles for legacy halon systems, forcing vessel operators to accelerate capital deployment toward water mist and inert gas architectures before certification deadlines lapse.
Growth Catalysts
- LNG Carrier Newbuilds:South Korean shipyards are specifying integrated fire protection packages for cryogenic cargo containment systems, creating sustained demand for high-pressure water mist networks.
- EPA Significant New Alternatives Policy:Regulatory pressure to phase out halon 1301 is compelling US-flagged commercial fleets toward HFC-227ea and FK-5-1-12 replacement chemistries.
- Naval Fleet Modernization:NATO defense procurement programs are funding next-generation suppression systems with enhanced blast-resistant nozzle configurations for combatant vessels.
Market Restraints
- Specialized Alloy Costs:Corrosion-resistant titanium and super-duplex stainless steel for saltwater-exposed distribution networks face price volatility tied to nickel and molybdenum commodity markets.
- Certification Bottlenecks:IMO MED module B+D approval timelines extend 18-24 months, freezing competitive entry for unapproved system architectures.
- Technical Substitution Limits:Water mist performance degrades in machinery spaces with high airflow ventilation, restricting application scope despite environmental advantages.
Strategic Opportunities
- Autonomous Vessel Architectures:Unmanned engine rooms on remotely operated cargo ships demand fully automatic detection-to-discharge protocols without human intervention loops.
- EU Green Deal Alignment:The F-Gas Regulation phase-down creates preferential market access for fluorine-free suppression technologies in European-flagged fleets.
- Digital Twin Integration:Convergence of fire suppression hardware with vessel safety management software enables predictive maintenance and remote diagnostic revenue streams.
Industry Challenges
- Marine Systems Engineering Talent:Shortage of specialists fluent in both high-pressure hydraulics and maritime classification society rules compresses R&D throughput at mid-tier suppliers.
- Legacy Vessel Integration:Retrofitting pre-2000 cargo ships requires structural modifications to accommodate modern suppressant storage volumes and piping routing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Fire Extinguishing System Market |
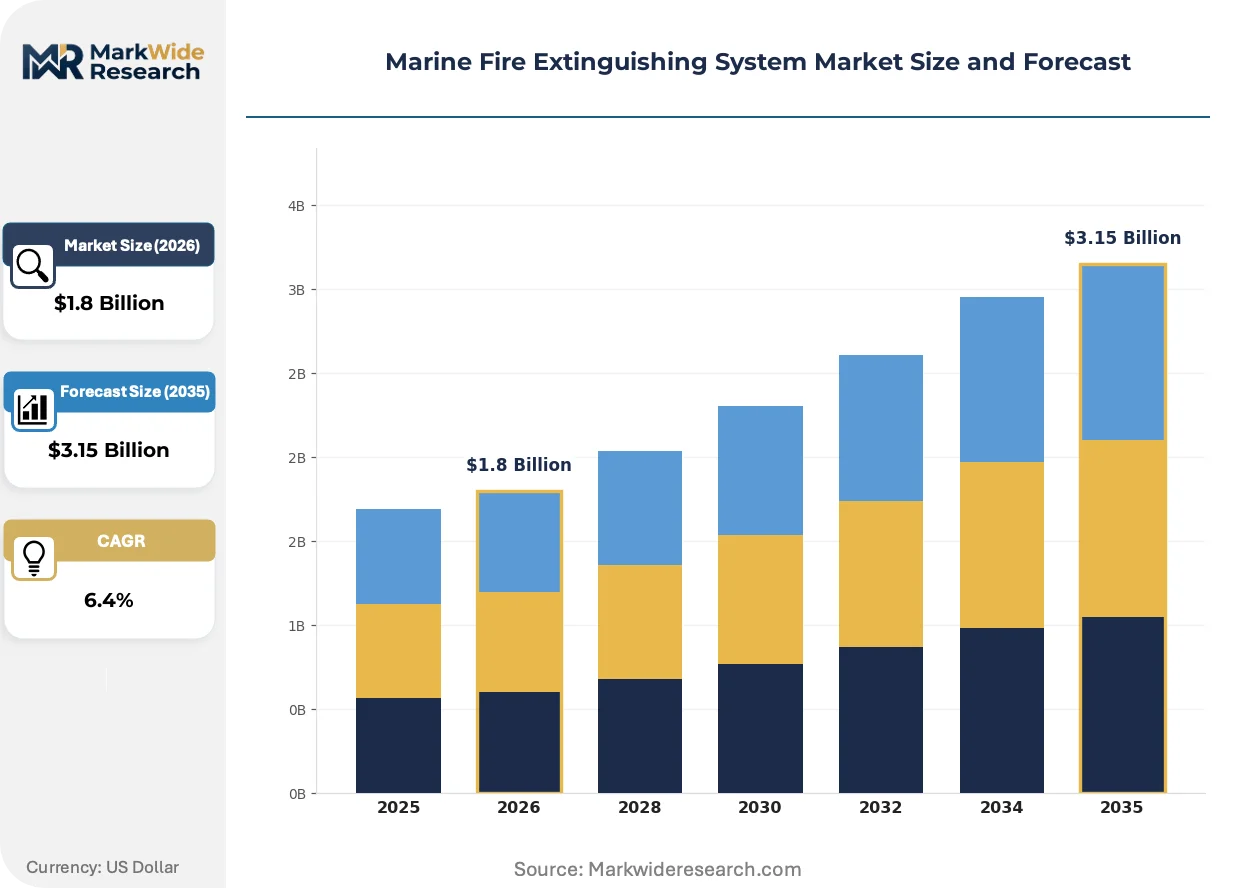
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water Mist, Foam, CO2, Powder Application: Commercial Vessels, Cargo Ships, Offshore Platforms, Yachts Technology: Manual, Automatic, Hybrid, Integrated End User: Shipping Companies, Shipbuilders, Maritime Authorities, Owners |
| Companies Covered | Johnson Controls, Kidde-Fenwal Inc., Fireboy-Xintex, Danfoss A/S, Minimax GmbH & Co. KG, Wärtsilä, Consilium Safety Group AB, National Fire Fighting Manufacturing FZCO, Rotarex Firetec S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Fire Extinguishing System Market Shifts & Advancements
Fire suppression technology is fragmenting along performance-versus-sustainability axes, with regulatory chemistry bans and digital integration demands pulling development in divergent directions simultaneously.
Water mist nozzle engineering is bifurcating between ultra-fine droplet systems for accommodation spaces and coarse-droplet configurations for machinery protection. Cruise line operators are adopting the former to minimize water damage to interiors, while bulk carrier owners prioritize the latter for engine room reliability. This divergence is compressing standardization efforts and forcing suppliers to maintain dual product development tracks.
The EU F-Gas Regulation is accelerating fluorinated gas phase-out timelines for marine applications. System manufacturers must reformulate suppressant chemistries or risk exclusion from European-flagged vessel procurement. Offshore platform operators in the North Sea basin are responding fastest, specifying FK-5-1-12 alternatives ahead of commercial shipping fleets.
Buyer preference is gravitating toward lifecycle service contracts bundling hardware, inspection, and recertification. Shipowners are displacing transactional equipment purchases with decade-long performance agreements. This shift is most pronounced among German and Greek container fleet operators seeking to outsource regulatory compliance burden.
Marine Fire Extinguishing System Market Segmentation
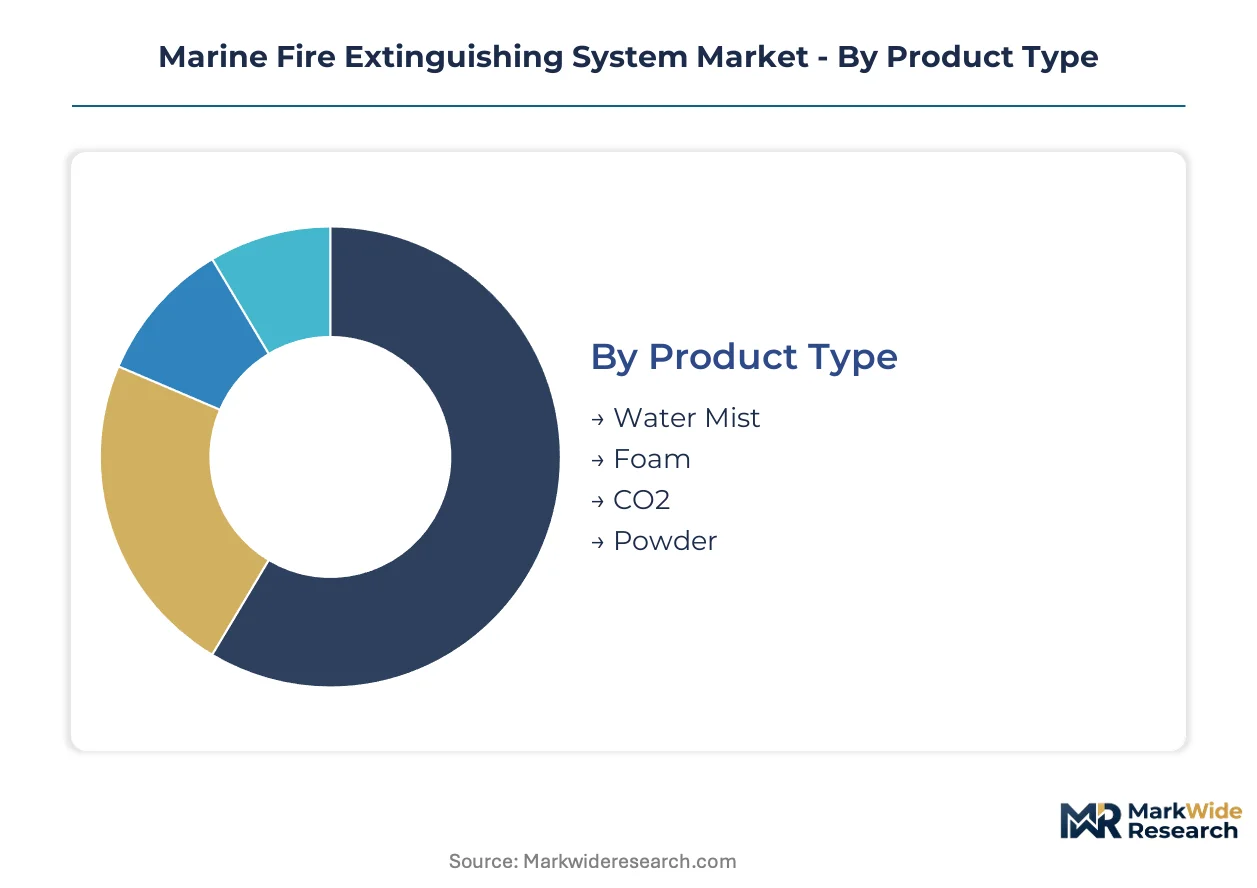
Segmentation in marine fire extinguishing systems reveals where regulatory chemistry bans and digital integration demands create divergent competitive pressure. Suppliers must align product architectures with vessel-specific hazard profiles and flag-state certification requirements.
Product Type:
Water mist faces intensifying substitution pressure from fluorine-free chemistries as EU F-Gas Regulation tightens, while legacy CO2 and powder systems confront IMO SOLAS Chapter II-2 phase-out deadlines.
- Water Mist:High-pressure distribution networks operating at 80-200 bar generate ultra-fine droplets that suppress combustion through oxygen displacement and surface cooling. South Korean LNG carrier newbuilds specify these systems for cryogenic cargo containment zones, driven by minimal collateral damage requirements and weight reduction mandates.
- Foam:Protein and synthetic concentrate formulations create vapor-sealing blankets over liquid fuel fires, with AFFF variants now restricted under EPA Significant New Alternatives Policy for PFAS content. Offshore platform operators in the North Sea basin are accelerating fluorine-free foam procurement ahead of regulatory deadlines.
- CO2:Total flooding systems using stored carbon dioxide remain prevalent in machinery spaces, though confined space toxicity limits crew evacuation timing.
- Powder:Dry chemical suppressants using mono-ammonium phosphate or sodium bicarbonate serve localized Class B and C hazards, with limited maritime adoption due to cleanup burden and corrosion risk.
Water Mist retains volume leadership; Integrated technology platforms hold the steepest expansion curve.
Application:
Cost tier stratification separates capital-intensive newbuild specifications from constrained retrofit budgets across vessel categories.
- Commercial Vessels:Container ships, tankers, and passenger ferries require redundant protection zones with remote monitoring capabilities. German and Greek fleet operators are shifting from transactional purchases toward decade-long lifecycle service contracts bundling hardware, inspection, and recertification.
- Cargo Ships:Bulk carriers and general cargo vessels face acute retrofit pressure as pre-2000 hulls require structural modifications to accommodate modern suppressant storage volumes and piping routing.
- Offshore Platforms:Fixed and floating production installations in the North Sea specify FK-5-1-12 alternatives fastest, responding to EU F-Gas Regulation phase-down timelines.
- Yachts:Superyacht and luxury vessel segments prioritize aesthetic integration and accommodation space protection over machinery reliability.
Commercial Vessels anchor revenue concentration; Offshore Platforms are climbing the fastest.
Technology:
Customer type divergence separates shipbuilders seeking centralized safety management from owners prioritizing manual override reliability.
- Manual:Human-activated discharge protocols using pull stations and remote manual release panels remain specified for crewed machinery spaces where operator judgment is valued.
- Automatic:Detection-to-discharge sequences without human intervention loops serve unmanned engine rooms on remotely operated cargo ships. NATO naval procurement programs fund blast-resistant nozzle configurations for combatant vessels.
- Hybrid:Dual-mode architectures bridging manual and automatic activation protocols dominate current installations, allowing operator override of sensor-triggered sequences.
- Integrated:Centralized safety management systems converging fire suppression hardware with vessel automation platforms capture specification preference among South Korean shipyards.
Hybrid systems retain installation dominance; Integrated platforms gain share fastest.
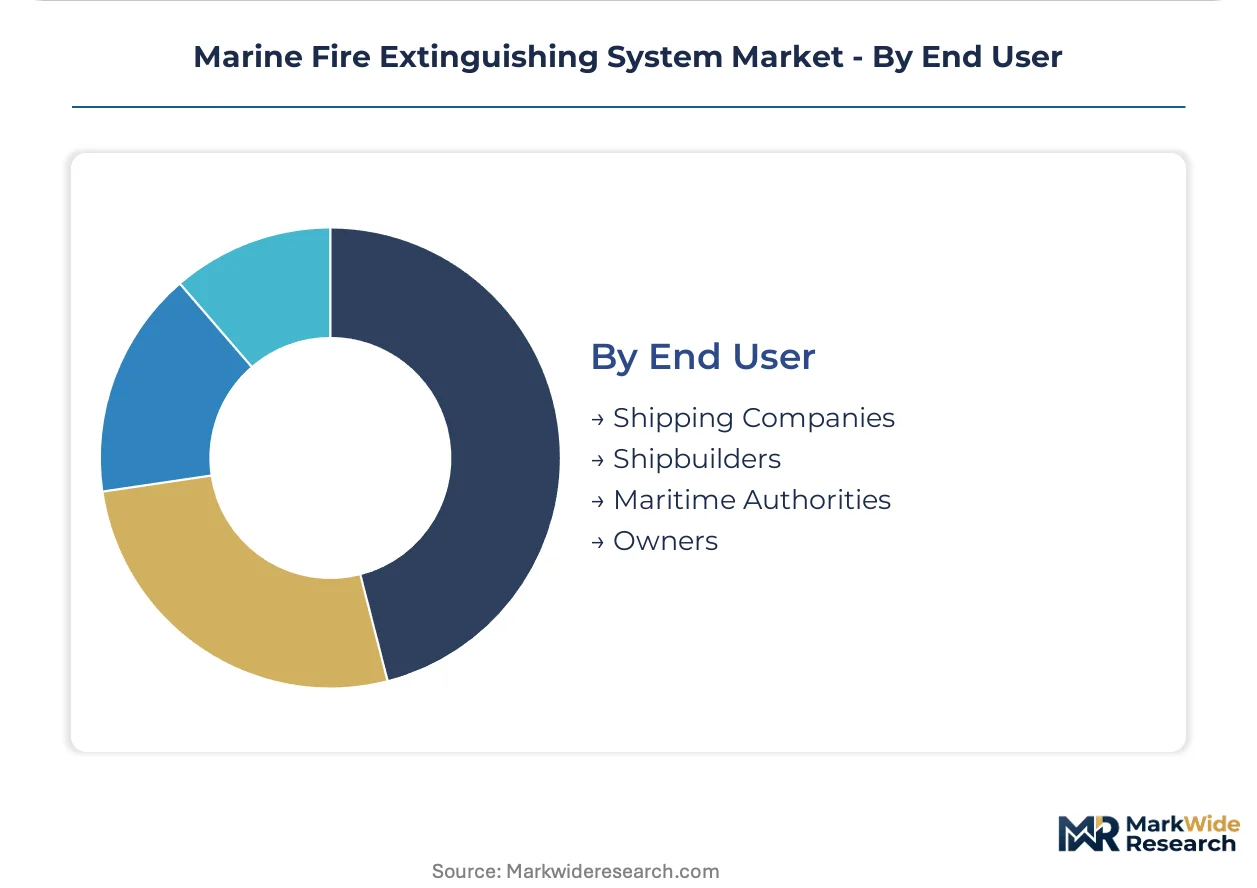
End User:
Procurement authority fragmentation creates divergent specification priorities across the vessel ownership chain.
- Shipping Companies:Fleet operators managing multiple flag registries face compliance fragmentation as national maritime authorities interpret integrated system standards inconsistently.
- Shipbuilders:Hyundai Heavy Industries and Samsung Heavy Industries in South Korea specify bundled fire protection with propulsion control systems, favoring suppliers with sustained IMO MED module B+D type-approval track records.
- Maritime Authorities:Classification societies and flag-state regulators enforce SOLAS Chapter II-2 retrofit mandates, compressing replacement cycles for legacy halon systems.
- Owners:Private and institutional vessel owners balance insurance premium reductions against upfront capital deployment for suppression system upgrades.
Shipbuilders control newbuild specification; Maritime Authorities are accelerating retrofit velocity fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea's shipbuilding subsidies and the EU F-Gas Regulation are redirecting procurement flows toward fluorine-free suppression technologies. Classification societies in Germany and Japan are tightening type-approval timelines. Norwegian offshore operators are accelerating digital twin integration for platform safety systems.
South Korea
Hyundai Heavy Industries and Samsung Heavy Industries dominate LNG carrier newbuild specifications, bundling integrated fire protection with propulsion control systems. The Korea Register of Shipping enforces accelerated MED module B+D approval pathways for domestic suppliers. Busan-Ulsan shipyard clusters concentrate procurement authority for high-pressure water mist networks in cryogenic cargo containment zones.
Germany
German container fleet operators are displacing transactional equipment purchases with decade-long lifecycle service contracts covering hardware, inspection, and recertification. The Federal Maritime and Hydrographic Agency interprets SOLAS Chapter II-2 retrofit mandates with stricter enforcement timelines than Mediterranean flag registries. Hamburg and Bremen harbor authorities coordinate classification society inspections that compress compliance windows for legacy halon system replacements.
United States
US-flagged commercial fleets face EPA Significant New Alternatives Policy pressure to phase out halon 1301 toward HFC-227ea and FK-5-1-12 replacement chemistries. The Coast Guard enforces inconsistent integrated system standards interpretations compared to European maritime authorities. Gulf Coast ship repair clusters in Houston and New Orleans handle structural modifications for pre-2000 cargo hulls retrofitting modern suppressant storage volumes.
Norway
North Sea offshore platform operators specify FK-5-1-12 alternatives fastest, responding to EU F-Gas Regulation phase-down timelines ahead of commercial shipping fleets. The Norwegian Maritime Authority mandates redundant protection zones with remote monitoring capabilities for floating production installations. Stavanger and Bergen engineering consultancies specialize in predictive maintenance software convergence with fire suppression hardware.
Japan
Japanese shipyards are specifying centralized safety management systems that converge fire suppression hardware with vessel automation platforms. METI guidelines promote fluorine-free suppression technology adoption in anticipation of EU regulatory alignment. Nagoya and Kobe industrial corridors concentrate sensor-driven hybrid architecture development bridging manual and automatic activation protocols.
Marine Fire Extinguishing System Market Competitive Landscape
Player mix skews toward diversified industrial conglomerates with maritime automation portfolios alongside specialized fire safety engineers. Market structure tilts consolidated at the specification-setting tier where sustained IMO type-approval track records create certification moats, yet fragments across regional installation and service providers. Two strategic archetypes dominate: integrated platform bundlers leveraging propulsion control cross-selling, and deep specialists anchoring position through high-pressure water mist engineering. Competitive moves concentrate on M&A to fill chemistry portfolio gaps and strategic partnerships for digital twin integration capabilities.
Among diversified Nordic industrial groups, Wärtsilä and Consilium Safety Group AB exemplify platform-bundling archetypes that leverage automation cross-selling into fire safety procurement decisions. Minimax GmbH & Co. KG anchors the deep-specialist tier with German GmbH structure and concentrated expertise in machinery space protection. Johnson Controls represents the diversified conglomerate pattern with building technologies heritage extending into marine applications through acquisition-driven portfolio assembly.
| Leading Market Players |
|---|
| Johnson Controls |
| Kidde-Fenwal Inc. |
| Fireboy-Xintex |
| Danfoss A/S |
| Minimax GmbH & Co. KG |
| Wärtsilä |
| Consilium Safety Group AB |
| National Fire Fighting Manufacturing FZCO |
| Rotarex Firetec S.A. |
| Others |
Supply & Pricing Matrix
Eighteen-to-twenty-four-month IMO MED module B+D approval timelines concentrate supply-side leverage among incumbent certification holders, compressing competitive entry while sustaining premium pricing for type-approved system architectures. This lead-time rigidity shapes procurement patterns across South Korean shipyards and European retrofit fleets alike.
Pricing Analysis
Certification level (IMO MED/CE/FDA-grade) creates the primary spread between premium integrated platforms and economy manual systems. Three-tier pricing structure across premium, standard, and economy levels reflects bundling depth with propulsion automation and lifecycle service contracts. Cost compression in standard-tier water mist components is intensifying because South Korean shipbuilders are consolidating procurement volumes around bundled suppliers. Container fleet operators in Germany and Greece exhibit highest price sensitivity, while NATO naval procurement programs show lowest sensitivity due to blast-resistance specifications.
Supply Chain Analysis
Strategic stockpiling of corrosion-resistant titanium and super-duplex stainless steel dominates inventory strategy, buffering nickel and molybdenum commodity volatility that would otherwise disrupt high-pressure distribution network production. Manufacturing concentrates in Germany, South Korea, and Japan, drawing from specialty alloy foundries in Finland and specialty pump engineering in Denmark. Single-source vulnerability persists in ultra-high-pressure nozzle machining equipment. Distribution runs through shipyard-integrated procurement channels and maritime equipment distributors serving Gulf Coast repair clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are reshaping competitive positioning as fire suppression hardware converges with vessel safety management software, creating interoperability moats that favor suppliers with sustained type-approval track records and digital twin integration capabilities.
For Market Incumbents: Secure IMO MED module B+D certification moats through accelerated investment in fluorine-free chemistry portfolios ahead of EU F-Gas Regulation phase-down deadlines. Deepen backward integration into corrosion-resistant alloy sourcing to buffer commodity volatility threatening margin stability in water mist distribution networks. For New Entrants and Emerging Players: Lifecycle service contract gaps in pre-2000 cargo vessel retrofits present white-space entry points where incumbent bundlers under-serve structural modification requirements. Target Gulf Coast and Mediterranean repair clusters with project-based engineering capabilities for legacy hull suppressant storage integration, leveraging direct shipowner relationships outside shipyard procurement channels. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across integrated technology platform development, favoring acquisition of sensor-driven hybrid architecture specialists over pure-play hardware manufacturers. Monitor FK-5-1-12 chemistry approval velocity at EPA as inflection indicator for fluorinated gas substitution economics.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Integration | Convergence with vessel safety management software enables predictive maintenance revenue streams at Norwegian offshore platforms. |
| Fluorine-Free Chemistry Reformulation | EU F-Gas Regulation compliance secures procurement access for European-flagged LNG carrier newbuilds. |
| Lifecycle Service Contract Expansion | German and Greek container operators are outsourcing regulatory compliance burden through decade-long performance agreements. |
| IMO MED Certification Acceleration | Compressed approval timelines at Korea Register of Shipping favor domestic suppliers in Busan-Ulsan clusters. |
| Blast-Resistant Nozzle Development | NATO naval procurement programs fund next-generation configurations for combatant vessel machinery protection. |
Research Methodology
A standing panel of shipyard procurement directors, classification society surveyors, maritime safety engineers, and fleet technical managers provided ongoing calibration across primary fieldwork and secondary validation. Bottom-up demand modeling triangulated against customs data for corrosion-resistant alloy imports, IMO SOLAS amendment filings, and SEC disclosures from diversified industrial conglomerates with marine automation portfolios. Top-down market sizing cross-referenced shipbuilding order databases with fire suppression system specification rates by vessel category.
Consistency checks validated volume and value outputs against Lloyd's Register vessel statistics, Korean Register newbuild certification records, and offshore platform safety system procurement databases across the North Sea basin. Segmentation dimensions modeled include suppressant agent chemistry, activation technology architecture, vessel application category, and flag-state regulatory cluster. CAGRs were derived from regression analysis of historical replacement cycles and projected retrofit mandate compliance curves, incorporating IMO SOLAS Chapter II-2 deadline phasing and EPA Significant New Alternatives Policy implementation timelines.
Forecasts assume regulatory continuity in IMO SOLAS, EU F-Gas Regulation, and EPA SNAP frameworks; material policy shifts would require re-modeling. Revision becomes warranted when fluorine-free chemistry approval timelines at classification societies cross thresholds that compress competitive entry windows.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fire Safety & Protection
Cellulosic Fire Protection Market
Fire Safety & Protection
China Thermal Protector Market
Fire Safety & Protection
Fire Safety Systems Market
Fire Safety & Protection
Global Fire Barrier Sealant Market
Fire Safety & Protection
Automatic Fire Ball Extinguisher Market
Fire Safety & Protection
North America Fire Extinguisher Market
Fire Safety & Protection
Fire Extinguisher Market
Fire Safety & Protection
Fire and Rescue Helmets Market
Fire Safety & Protection
Wireless Fire Detection Systems Market
Fire Safety & Protection
Flame Detector System Market
Fire Safety & Protection
Australia Emergency Lighting Market
Fire Safety & Protection
Fire Department Software Market
Fire Safety & Protection
Global Fixed Firefighting Misting System Market
Fire Safety & Protection
Fire Door Market
Fire Safety & Protection
Civil Combustible Gas Alarm Market
Fire Safety & Protection
Smoke and Carbon Monoxide Alarm Market