
 Passive Electronic Components in Aerospace & Defense Market | 2026-2036
Passive Electronic Components in Aerospace & Defense Market Size, Share, and Industry Trends Forecast 2026-2036
Passive Electronic Components in Aerospace & Defense Market Insights
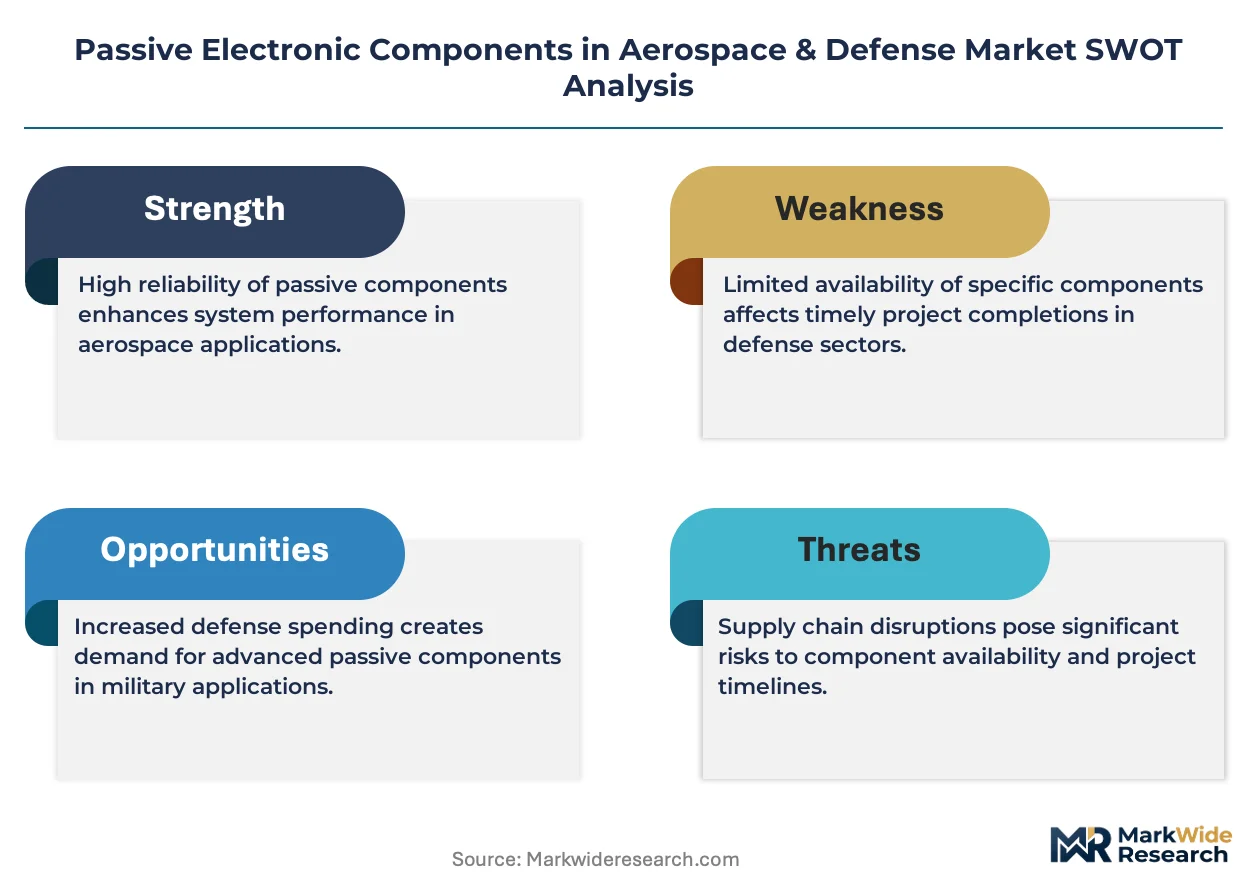
MIL-PRF qualification tier is bifurcating the competitive landscape into qualified and non-qualified supplier pools. Vishay Intertechnology leverages its broad military-grade resistor and capacitor portfolio to sustain long-term defense contracts. TDK Corporation anchors its position through advanced ferrite and ceramic material expertise for high-reliability inductors. KYOCERA AVX Components specializes in tantalum and ceramic capacitors that meet stringent aerospace derating requirements.
Passive electronic components in aerospace and defense encompass non-active circuit elements—capacitors, resistors, inductors, and filters—typically manufactured with specialized dielectrics, precious metal terminations, and fired ceramic or thin-film processes to withstand extreme temperature cycling, vibration, and radiation exposure. These components regulate signal integrity, power conditioning, and electromagnetic interference suppression across mission-critical avionics and weapons platforms. Capacitors command the largest value share due to energy storage demands in radar pulse circuits and flight control systems, while surface-mount form factors are displacing through-hole architectures in new avionics designs to reduce weight and assembly footprint. Filters represent the fastest-growing segment as spectral congestion and electronic warfare threats intensify EMI shielding requirements across communications and radar applications.
FAA airworthiness certification, U.S. DoD MIL-STD-883 test methods, and EU REACH chemical substance restrictions collectively shape material selection, qualification timelines, and market access for component suppliers. The U.S. Defense Federal Acquisition Regulation Supplement imposes domestic sourcing preferences that constrain non-U.S. qualified suppliers from certain Pentagon procurement channels. Stakeholders must monitor evolving export control classifications under the Wassenaar Arrangement and accelerating U.S. Congressional pressure for defense supply chain reshoring.
Market Dynamics
MIL-PRF qualification requirements are bifurcating supplier pools into qualified and non-qualified tiers, while Pentagon domestic sourcing preferences reshape procurement patterns for passive electronic components in defense applications.
Growth Catalysts
- Electronic Warfare Expansion:Spectral congestion and jamming threats drive procurement of advanced EMI filters for radar and communications systems across NATO member states.
- REACH Substance Restrictions:Europe's chemical compliance mandates accelerate development of lead-free terminations and alternative dielectric formulations for aerospace capacitors.
- Hypersonic Platform Development:Extreme thermal cycling requirements in next-generation weapons systems create demand for specialized ceramic and thin-film resistor technologies.
Market Restraints
- Precious Metal Volatility:Palladium and silver price swings in termination materials compress margins for tantalum capacitor manufacturers.
- Qualified Supplier Concentration:U.S. domestic sourcing preferences under DFARS constrain non-U.S. MIL-PRF certified producers from Pentagon procurement channels.
- Radiation Hardening Limitations:Total ionizing dose tolerance thresholds in standard ceramic dielectrics restrict deployment in geostationary satellite applications.
Strategic Opportunities
- India Defense Indigenization:India's PLI scheme for electronics manufacturing creates entry points for component suppliers meeting BIS and DGFT localization requirements.
- Additive Manufacturing Convergence:Integration of printed electronics with traditional fired ceramic processes enables conformal antenna and embedded passive circuits.
- Digital Thread Integration:Model-based systems engineering mandates from the U.S. DoD open service contracts for component traceability and digital twin data packages.
Industry Challenges
- MIL-STD-883 Test Capacity:Burn-in and qualification timeline bottlenecks at certified test facilities extend new product introduction cycles.
- Obsolescence Management Complexity:Counterfeit mitigation and last-time-buy coordination for legacy through-hole architectures strain supply chain resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Passive Electronic Components in Aerospace & Defense Market |
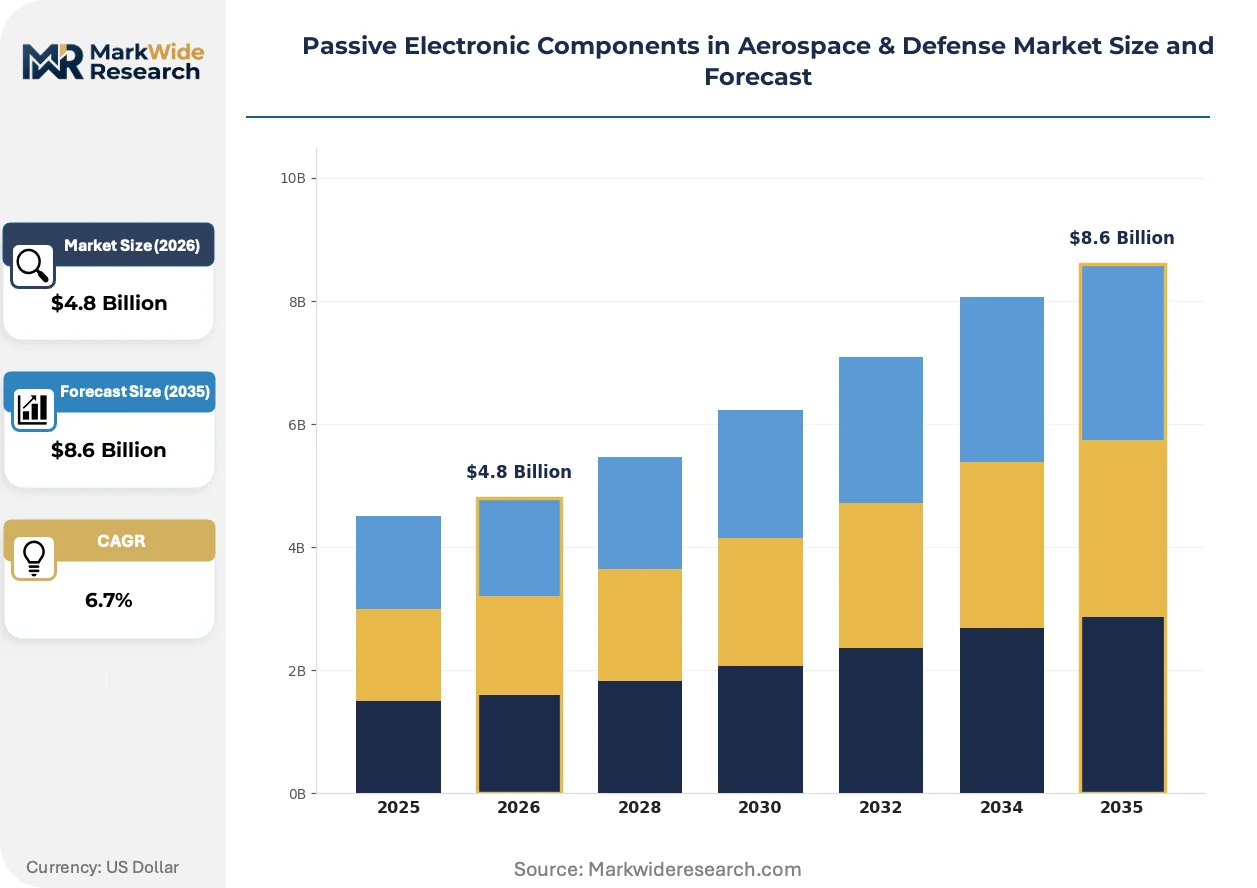
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component Type: Capacitors, Resistors, Inductors, Filters Application: Avionics, Communications, Radar Systems, Weapons Systems End User: Military, Commercial Aviation, Defense Contractors, Government Agencies Form Factor: Surface-Mount, Through-Hole, Chip, Hybrid |
| Companies Covered | Vishay Intertechnology Inc., TDK Corporation, KYOCERA AVX Components Corp., KEMET Corporation, TE Connectivity Ltd., Murata Manufacturing Co., Ltd., Panasonic Holdings Corporation, Bourns, Inc., WIMA GmbH & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Passive Electronic Components in Aerospace & Defense Market Trends and Innovations
Surface-mount form factors are displacing through-hole architectures across avionics designs, while additive manufacturing and digital qualification workflows reshape how passive components are specified, tested, and integrated into defense platforms.
Multilayer ceramic capacitors with X7R and C0G dielectric formulations are miniaturizing into 0201 and 01005 case sizes for space-constrained flight control modules. Prime contractors at Lockheed Martin and Northrop Grumman are specifying these footprints for new fighter avionics builds. This dimensional compression is miniaturizing power conditioning subsystems while maintaining MIL-PRF voltage derating margins.
Europe's REACH substance restrictions and RoHS recast directives are forcing reformulation of barium titanate dielectrics and termination metallizations across the supply base. Component manufacturers must requalify alternative chemistries under ECHA substance authorization timelines. High-reliability tantalum capacitor producers face the steepest compliance burden, with aerospace-grade product lines requiring multi-year requalification cycles.
Defense procurement offices are consolidating vendor lists around qualified suppliers offering integrated component-plus-data packages. Long-term performance-based agreements are replacing transactional spot purchases for mission-critical platforms. This consolidation is most visible in U.S. Navy shipboard electronics programs, where prime contractors now mandate digital thread compatibility from passive component vendors.
Passive Electronic Components in Aerospace & Defense Market Segmentation
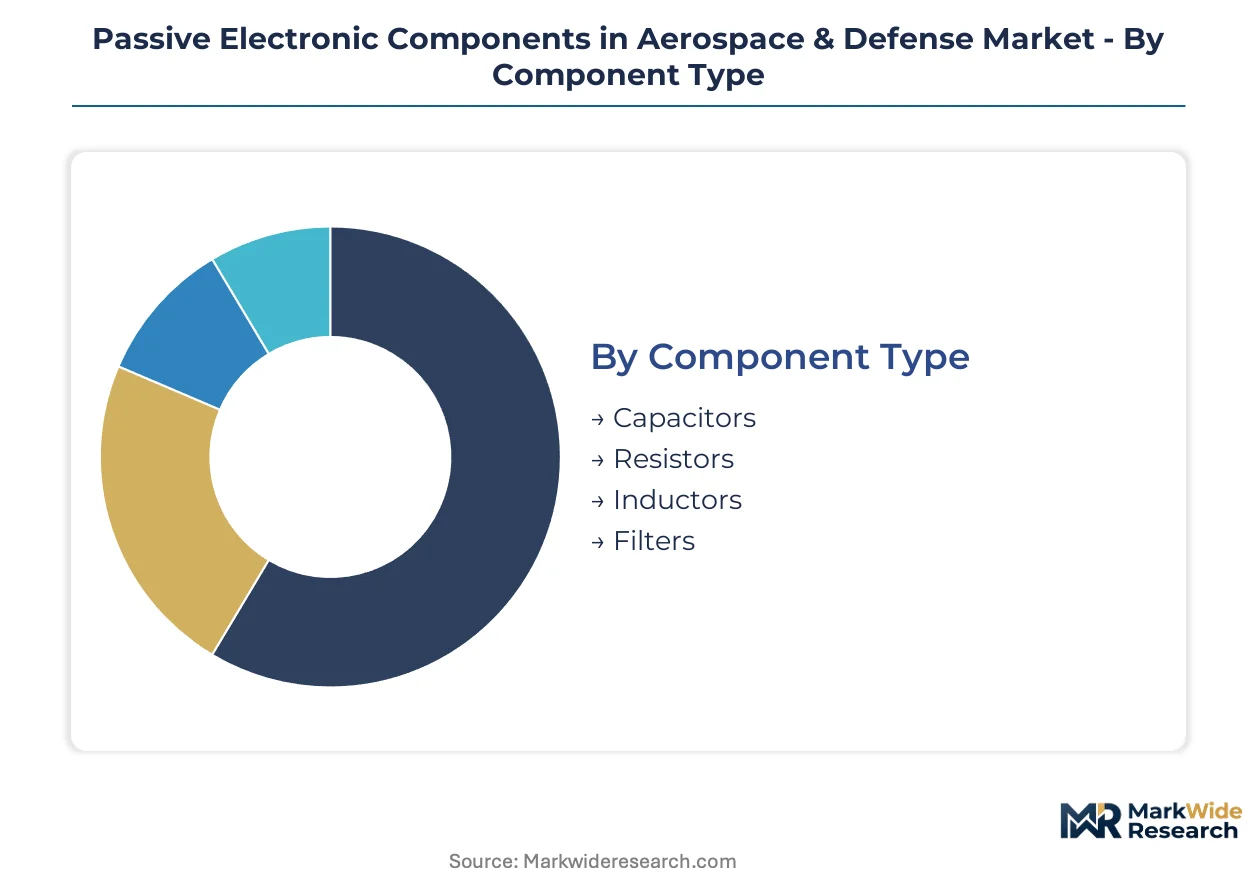
Segmentation in aerospace and defense passive components reveals how qualification tiers, platform requirements, and manufacturing processes create distinct procurement channels. Each dimension carries specific regulatory and technical constraints that shape supplier positioning.
Component Type:
MIL-PRF qualification tiers bifurcate each component category into defense-grade and commercial-off-the-shelf supply pools, with precious metal terminations and ceramic dielectrics facing distinct REACH substance authorization timelines.
- Capacitors:Tantalum and ceramic formulations dominate mission-critical energy storage for radar pulse circuits and flight control systems. Military procurement concentrates in the United States, driven by Pentagon modernization programs and DFARS domestic sourcing mandates that constrain non-U.S. qualified suppliers.
- Filters:EMI suppression components address spectral congestion and electronic warfare threats across NATO communications architectures. Demand is accelerating fastest in radar applications, where prime contractors at Lockheed Martin and Northrop Grumman specify integrated filter assemblies for next-generation platforms.
- Resistors:Thin-film and thick-film technologies withstand extreme temperature cycling in hypersonic weapons systems.
- Inductors:Ferrite-core and air-core designs manage power conditioning in satellite bus electronics.
Capacitors handle the majority of throughput; filters are climbing the fastest on share.
Application:
Platform certification requirements create divergent qualification burdens, with manned aircraft systems facing FAA airworthiness protocols and weapons platforms governed by MIL-STD-883 test methods.
- Avionics:Flight control modules and navigation systems demand miniaturized surface-mount passives in 0201 and 01005 case sizes. U.S. prime contractors specify these footprints for new fighter builds, compressing power conditioning subsystems while maintaining voltage derating margins under MIL-PRF-123 and MIL-PRF-55681.
- Radar Systems:Pulsed power applications drive procurement of high-voltage ceramic capacitors and specialized filter networks. European defense ministries are expanding EMI shielding procurement as spectral congestion intensifies across NATO electronic warfare architectures.
- Communications:Secure radio and data link systems require broadband filters and precision resistors for signal integrity.
- Weapons Systems:Missile guidance and fire control electronics prioritize radiation-hardened components with extended temperature ranges.
Avionics commands the largest procurement volume; radar systems are expanding most quickly as electronic warfare investment accelerates.
End User:
Customer type determines contract structure, with military end users favoring long-term performance-based agreements and commercial aviation operators emphasizing total cost of ownership metrics.
- Military:Pentagon procurement offices consolidate vendor lists around qualified suppliers offering integrated component-plus-data packages. U.S. Navy shipboard electronics programs now mandate digital thread compatibility from passive component vendors, replacing transactional spot purchases with multi-year agreements.
- Defense Contractors:Lockheed Martin, Northrop Grumman, and Raytheon specify MIL-PRF qualified passives for platform integration, acting as intermediaries between component suppliers and government end users.
- Commercial Aviation:Boeing and Airbus suppliers face dual FAA-EASA certification requirements for airworthiness compliance.
- Government Agencies:NASA and national laboratories procure radiation-hardened components for space and research applications.
Military end users dominate procurement volume; defense contractors are gaining influence as prime integrators consolidate supply chains.
Form Factor:
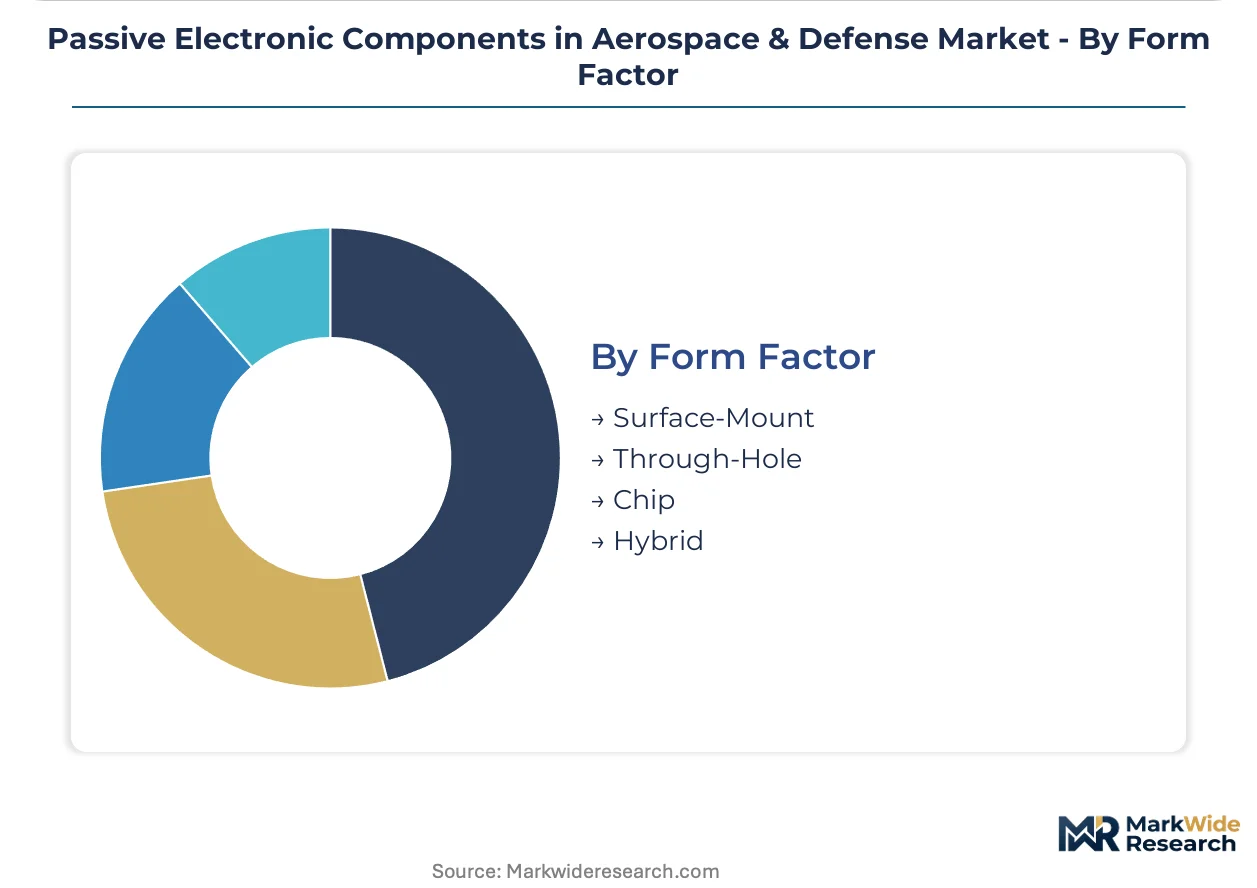
Manufacturing process compatibility and assembly automation requirements differentiate form factor selection, with surface-mount architectures displacing legacy through-hole designs in new platform builds.
- Surface-Mount:Chip-scale passives enable automated assembly and weight reduction in space-constrained avionics modules. Prime contractors specify these exclusively for new fighter and unmanned platform designs, driven by manufacturing throughput and reliability improvements over manual insertion processes.
- Through-Hole:Radial and axial leaded components persist in legacy military platforms with established qualification baselines.
- Chip:Bare die passives integrate into multichip modules for satellite payload electronics.
- Hybrid:Mixed-technology assemblies combine surface-mount and embedded passive structures for conformal antenna applications.
Surface-mount formats carry the majority of new design activity; hybrid configurations are advancing fastest as additive manufacturing converges with traditional ceramic processes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in passive electronic components for aerospace and defense tilt heavily toward surplus nations with established MIL-PRF qualification infrastructure. The United States runs the largest structural deficit in non-qualified components while maintaining stringent domestic sourcing mandates for defense-grade supply.
United States
Pentagon modernization programs and F-35 production lines drive procurement of ruggedized capacitors and EMI filters. The Defense Federal Acquisition Regulation Supplement imposes domestic sourcing preferences that constrain foreign suppliers from military procurement channels. Defense contractors in Texas and Arizona concentrate final assembly of avionics systems requiring qualified passive components.
Germany
Rheinmetall and Airbus Defence procurement sustains demand for high-reliability resistors and ceramic capacitors in fighter and transport platforms. REACH substance restrictions through ECHA force reformulation of barium titanate dielectrics and precious metal terminations. Industrial clusters in Bavaria and Baden-Württemberg host specialized test facilities for MIL-STD-883 qualification cycles.
Japan
Domestic satellite programs and maritime patrol aircraft sustain procurement of radiation-hardened inductors and precision resistors. METI industrial policy promotes supply chain reshoring for critical electronic components. Manufacturing concentration in the Nagoya and Osaka regions supplies ceramic dielectric materials to global aerospace tier ones.
United Kingdom
BAE Systems Tempest program and naval electronics refresh drive demand for miniaturized surface-mount passives. UK Export Control Organization alignment with Wassenaar Arrangement classifications shapes component trade flows. Southwest England and Scottish aerospace clusters specialize in satellite payload integration requiring space-qualified passive networks.
Israel
Domestic missile defense and unmanned aerial vehicle programs consume specialized thin-film resistors and high-temperature capacitors. Ministry of Defense procurement regulations mandate local content thresholds for sensitive platforms. Tel Aviv and Haifa technology corridors concentrate design houses that specify custom passive solutions for electronic warfare systems.
Passive Electronic Components in Aerospace & Defense Market Competitive Landscape
Listed leaders compete with private specialists across qualification tier and geographic coverage. The supplier base concentrates around MIL-PRF certified manufacturers capable of sustaining multi-year defense contracts. Three archetypes dominate: broad-portfolio conglomerates with military-grade divisions, specialized ceramic and tantalum capacitor houses, and precision resistor manufacturers with thin-film expertise. Consolidation through acquisition of qualified test facilities and strategic partnerships for digital thread compatibility represent the primary competitive vectors reshaping vendor relationships.
Within the broad-portfolio tier, Vishay Intertechnology Inc., TDK Corporation, and KYOCERA AVX Components Corp. occupy positions anchored by extensive military-grade product ranges. These entities exemplify suppliers capable of offering integrated component-plus-data packages that meet evolving Pentagon digital thread mandates. Their geographic distribution across North America, Japan, and multinational manufacturing footprints reflects the regulatory fragmentation governing defense procurement access.
| Leading Market Players |
|---|
| Vishay Intertechnology Inc. |
| TDK Corporation |
| KYOCERA AVX Components Corp. |
| KEMET Corporation |
| TE Connectivity Ltd. |
| Murata Manufacturing Co., Ltd. |
| Panasonic Holdings Corporation |
| Bourns, Inc. |
| WIMA GmbH & Co. KG |
| Others |
Pricing and Supply Chain Analysis
MIL-PRF qualification requirements gate both supplier participation and price differentiation simultaneously, bifurcating the market into qualified premium tiers and non-qualified commercial alternatives while Pentagon domestic sourcing mandates constrain cross-border price arbitrage opportunities.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with MIL-PRF certification status and precious metal termination content driving price differentiation. Cost compression in tantalum capacitor lines is intensifying because palladium price volatility squeezes termination material margins. Defense prime contractors exhibit lowest price sensitivity due to mission-critical reliability requirements, while commercial aviation suppliers face acute pressure from total cost of ownership metrics.
Supply Chain Analysis
Extended lead times for MIL-STD-883 burn-in capacity at certified test facilities now stretch new product introduction cycles, constraining upstream throughput. Manufacturing concentrates in the United States, Japan, and Germany, with ceramic dielectric formulations drawing from specialized Bavarian and Nagoya industrial clusters. Single-source vulnerability pervades qualified test facility access. Distribution runs through authorized distributors with traceability documentation for counterfeit mitigation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital thread mandates from the U.S. Department of Defense signal a platform-economics inflection, rewarding component suppliers that embed interoperability protocols and performance data packages into their offerings.
For Market Incumbents: Fortify qualification infrastructure through captive test facility investments or strategic partnerships with certified burn-in providers, countering emerging entrants that lack MIL-PRF pedigree. Deepen backward integration into ceramic dielectric materials to buffer REACH-driven reformulation costs and secure supply continuity for aerospace-grade product lines. For New Entrants and Emerging Players: Digital thread compatibility services represent an under-served layer where incumbents under-invest, creating white-space for specialized data-package vendors to penetrate U.S. Navy shipboard electronics programs. Target India's defense indigenization corridor through BIS certification pathways, leveraging PLI scheme incentives to establish localized production without Pentagon procurement channel constraints. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across additive manufacturing convergence plays, as printed electronics integration demands specialized equipment and qualification workflows. Acquisition candidates with dual-use aerospace-defense certifications and established digital twin data capabilities offer strongest long-term viability. Monitor U.S. Congressional reshoring legislation as the critical inflection signal for domestic sourcing preference expansion.| Strategic Initiative | Industry Significance |
|---|---|
| MIL-PRF Qualification Investment | Opens Pentagon procurement channels constrained by DFARS domestic sourcing mandates. |
| Digital Thread Integration | Meets U.S. Navy mandates for component traceability and model-based systems engineering compatibility. |
| Additive Manufacturing Convergence | Enables conformal antenna and embedded passive circuits for next-generation avionics platforms. |
| REACH Compliance Reformulation | Secures ECHA authorization timelines for barium titanate dielectrics in European aerospace supply chains. |
| India Localization Partnership | Accesses PLI scheme incentives while circumventing U.S. domestic sourcing restrictions on non-qualified suppliers. |
Research Methodology
Operator-level perspectives from component procurement managers at defense primes, MIL-PRF qualification engineers, ceramic materials R&D directors, and aerospace supply chain planners anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through SEC 10-K filings, U.S. DoD contract award databases, ECHA substance authorization registries, and customs trade flow records. Bottom-up segment sizing triangulated against top-down defense budget allocation analysis.
Sensitivity analysis tested forecast robustness across qualification timeline scenarios, precious metal price volatility bands, and reshoring policy intensity variations. Segmentation modeling spanned component type, platform application, end-user contract structure, and form factor adoption curves, with CAGRs derived from defense procurement cycle analysis and platform replacement schedules. Hypersonic weapons thermal cycling requirements and satellite radiation-hardening thresholds provided industry-specific demand elasticity inputs.
Underlying assumptions cover sustained Pentagon modernization funding, stable REACH substance authorization timelines, and intact Wassenaar Arrangement export classifications, with deviation risk concentrated in Congressional defense appropriation volatility and ECHA accelerated restriction schedules. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Passive And Interconnecting Electronic Components
Miniature Ball Bearing Market
Passive And Interconnecting Electronic Components
Global Fixed Resistor Market
Passive And Interconnecting Electronic Components
Inductors, Cores and Beads Market
Passive And Interconnecting Electronic Components
Interconnects and Passive Components Market
Passive And Interconnecting Electronic Components
Discrete Diodes Market
Passive And Interconnecting Electronic Components
Wirewound Resistor Market
Passive And Interconnecting Electronic Components
Passive Infrared Sensor Market
Passive And Interconnecting Electronic Components
Wirewound Variable Resistors Market
Passive And Interconnecting Electronic Components
Global Passive Electronic Components Market
Passive And Interconnecting Electronic Components
Passive Tunable Integrated Circuits Market
Passive And Interconnecting Electronic Components
Anti-Sulfur Chip Resistors Market
Passive And Interconnecting Electronic Components
Electrical Wiring Interconnection System (EWIS) Market
Passive And Interconnecting Electronic Components
Copper Clad Laminate for Consumer Electronics Market
Passive And Interconnecting Electronic Components
Integrated Passive Devices (Ipds) Market
Passive And Interconnecting Electronic Components
Passive and Interconnecting Electronic Components Market
Passive And Interconnecting Electronic Components
Molded Interconnect Devices (MID) Market