
 Disposable Curd Cups Market | 2026-2036
Disposable Curd Cups Market Size, Share, and Industry Trends Forecast 2026-2036
Disposable Curd Cups Market Outlook
Food service distribution is reconfiguring around portion-controlled dairy packaging as institutional buyers consolidate procurement. Huhtamaki leverages its molded fiber expertise to anchor supply relationships with quick-service restaurants across India. Berry Global sustains multi-material production flexibility that competes effectively across price-sensitive emerging markets. Amcor dominates barrier-coated paper formats that extend shelf stability for ambient distribution channels.
Disposable curd cups are single-use containers engineered from polypropylene, polystyrene, or coated paperboard with moisture-barrier properties, thermoformed or injection-molded to hold 100ml to 500ml of fermented dairy product for retail and food service sale. The 200ml format leads volume due to its alignment with household consumption norms in South Asia, while biodegradable materials represent the fastest-expanding material category as EPR rules harden. Custom-branded cups command premium positioning among organized dairy cooperatives, whereas foam-based alternatives face structural decline amid material bans.
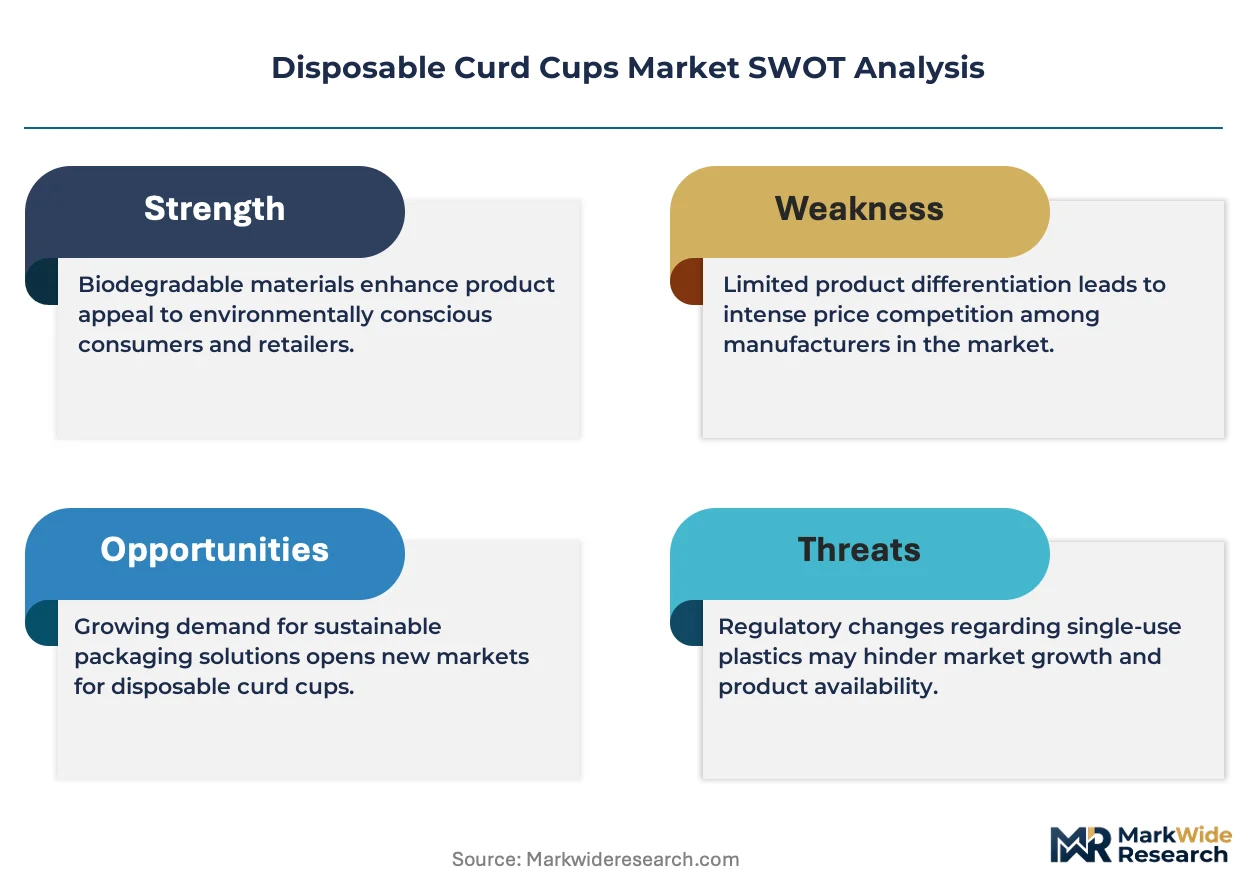
India's BIS mandates dimensional and migration standards for food-contact plastics, while state-level plastic waste management rules in Tamil Nadu and Karnataka enforce EPR compliance that shapes converter material choices. The EU's Packaging and Packaging Waste Regulation and REACH chemical restrictions constrain export-bound producers using conventional polymers. Stakeholders must monitor evolving material certification requirements and decide between backward integration into biopolymer sourcing or partnerships with certified substrate suppliers.
Market Dynamics
India's BIS packaging standards and EPR mandates for plastic waste management are forcing dairy processors and converters to reengineer material specifications across single-serve curd packaging formats.
Growth Catalysts
- EPR Compliance Deadlines:Tamil Nadu and Karnataka state rules enforce producer responsibility obligations that accelerate adoption of certified biodegradable substrates among organized dairy cooperatives.
- Quick-Service Restaurant Expansion:Institutional buyers in India's food service channel consolidate procurement around portion-controlled 200ml formats for chilled curd distribution.
- Barrier-Coated Paper Innovation:Migration-resistant coating technologies enable paperboard alternatives to meet FSSAI shelf-stability requirements for ambient distribution.
Market Restraints
- Biopolymer Feedstock Volatility:PLA and bagasse pricing fluctuates with sugarcane harvest cycles in Maharashtra and Uttar Pradesh, squeezing converter margins.
- Molded Fiber Equipment Concentration:Thermoforming machinery for fiber-based cups concentrates with European and Chinese suppliers, creating import-dependency risk for Indian converters.
- REACH-Compliant Chemistry Gap:Export-bound producers lack domestic access to EU-certified barrier coatings, forcing reliance on German and Dutch chemical suppliers.
Strategic Opportunities
- Kerala's Underserved Retail Corridor:Lower organized dairy penetration relative to Tamil Nadu creates whitespace for branded single-serve curd packaging in Kochi and Thiruvananthapuram.
- Biodegradable Material Mandates:India's Plastic Waste Management Rules amendments signal regulatory tailwind for compostable cup formats in institutional catering.
- E-Commerce Cold Chain Integration:Quick-commerce platforms like Blinkit and Zepto build dedicated chilled dairy infrastructure that favors shelf-ready 100ml portion packs.
Industry Challenges
- Migration Testing Bottlenecks:BIS certification timelines for novel barrier coatings extend 14-18 months, delaying product launches for converters.
- Legacy Polypropylene Inventory Stranding:Dairy processors face write-down risk on conventional cup stockpiles as state-level material bans advance implementation schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Disposable Curd Cups Market |
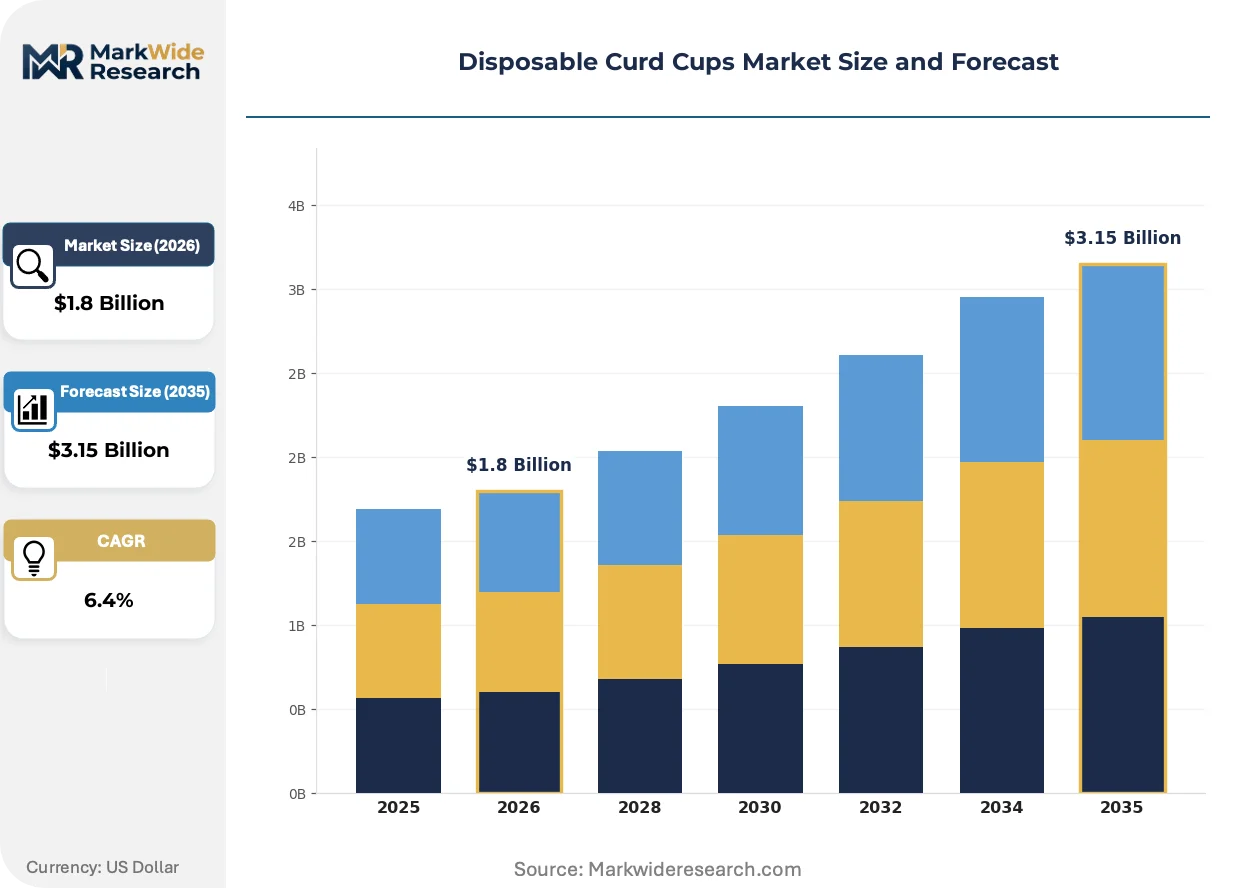
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Cups, Eco-friendly Cups, Multi-compartment Cups, Custom-branded Cups Material: Plastic, Paper, Biodegradable Materials, Foam Size: 100ml, 200ml, 300ml, 500ml Distribution Channel: Online Retail, Supermarkets, Food Service Outlets, Convenience Stores |
| Companies Covered | Amcor, Berry Global, Huhtamaki, Sonoco, Sealed Air, Printpack, Pactiv Evergreen, Dart Container Corporation, Winpak, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Disposable Curd Cups Market Strategic Shifts
Material science breakthroughs and regulatory compression are reconfiguring converter capabilities across India's disposable curd cup supply base, with shelf-life extension and end-of-life compliance emerging as dual performance thresholds.
Barrier-coated molded fiber technology is collapsing the performance gap between conventional plastics and paperboard alternatives for fermented dairy applications. Quick-service restaurant chains in Bengaluru and Chennai pilot 200ml fiber cups with oxygen transmission rates below 5 cc/m²/day. This substrate transition is collapsing converter investment timelines from five-year equipment cycles to 18-month retrofit windows.
India's FSSAI packaging migration limits and BIS dimensional standards are tightening simultaneously, creating compound compliance burdens for multi-format producers. The rules mandate specific neck-finish tolerances and total migration thresholds that exclude uncertified imported substrates. Small-scale converters in Tamil Nadu's Coimbatore cluster face disproportionate adaptation costs, accelerating consolidation toward integrated dairy-packaging operations.
Buyer consolidation among quick-commerce platforms is compressing supplier qualification cycles from annual reviews to quarterly performance audits. Dairy processors now demand real-time inventory visibility and dynamic lot-traceability that legacy ERP systems cannot support. This operational intensity concentrates procurement relationships with converters possessing integrated MES platforms, visible most acutely in Karnataka's Bangalore-Tumkur dairy processing corridor.
Disposable Curd Cups Market Segmentation
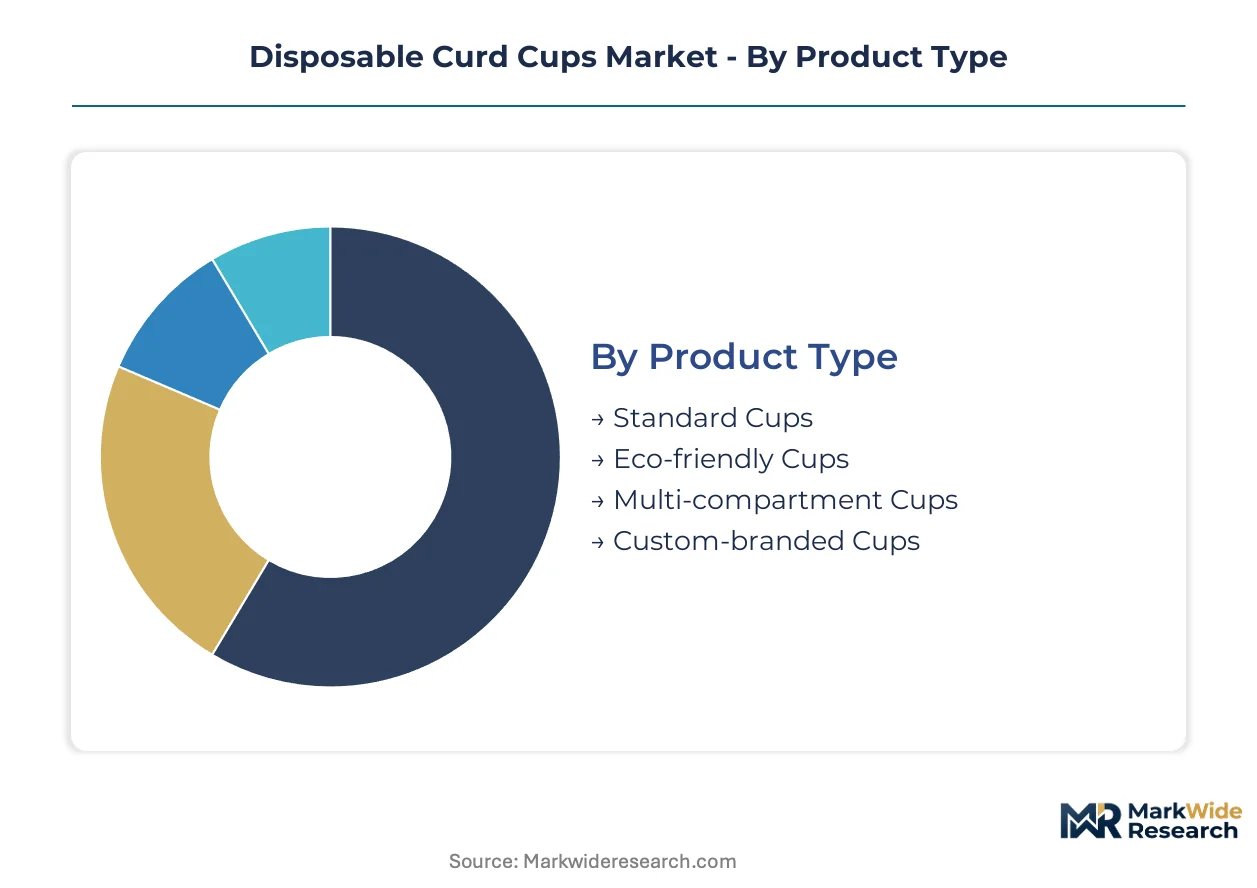
Segmentation in the disposable curd cups market reveals how dairy processors align packaging specifications with distribution channel requirements and regulatory compliance timelines. Material choices and format sizes directly determine shelf-stability performance and end-of-life disposal pathways across India's organized dairy retail corridor.
Product Type:
Standard cups turn inventory fastest through mass-market retail, while custom-branded formats cycle slower through cooperative procurement channels with longer qualification timelines.
- Standard Cups:Polypropylene or polystyrene containers with uniform wall thickness and standardized neck finishes for high-speed filling lines. Demand concentrates in Tamil Nadu's organized dairy cooperatives where BIS dimensional compliance is mandatory for interstate distribution.
- Eco-friendly Cups:Molded fiber or bagasse-based substrates with moisture-resistant coatings engineered for compostability. Expansion concentrates among quick-service restaurants in Bengaluru and Chennai where EPR mandates are enforced earliest.
- Multi-compartment Cups:Partitioned designs separating curd from toppings or condiments for institutional catering applications in Kerala's hospitality sector.
- Custom-branded Cups:Cooperative-specific lithography and proprietary color schemes for differentiated shelf presence in Karnataka's dairy retail networks.
Standard cups dominate installed base. Eco-friendly cups are where expansion concentrates.
Material:
Cost tiers separate legacy polymers from emerging substrates, with biopolymer feedstock volatility creating margin pressure at the premium end.
- Plastic:Injection-molded polypropylene with barrier additives achieving oxygen transmission rates below 10 cc/m²/day. Tamil Nadu's Coimbatore converter cluster maintains largest production capacity for this substrate category.
- Biodegradable Materials:PLA and bagasse formulations certified under India's Plastic Waste Management Rules for compostable end-of-life. Maharashtra and Uttar Pradesh sugarcane harvest cycles directly influence feedstock pricing and converter margins.
- Paper:Barrier-coated paperboard with polyethylene or bio-based lamination for ambient distribution channels requiring FSSAI migration compliance.
- Foam:Expanded polystyrene formats facing structural decline amid state-level material bans in Tamil Nadu and Karnataka.
Plastic retains volume leadership. Biodegradable materials are climbing the fastest.
Size:
Application use cases stratify clearly by consumption occasion, with institutional procurement favoring mid-range formats and quick-commerce platforms driving smallest sizes.
- 200ml:The household consumption standard across South India, thermoformed for optimal material efficiency and stack density in refrigerated retail display. Karnataka's Bangalore-Tumkur dairy corridor processes highest volumes of this format.
- 100ml:Single-serve portion packs engineered for quick-commerce cold chain integration by platforms like Blinkit and Zepto. Kochi and Thiruvananthapuram show fastest uptake as organized dairy penetration deepens.
- 300ml:Family-size formats for multi-day household consumption in Kerala's less frequent purchase patterns.
- 500ml:Bulk institutional formats for food service outlets and catering operations with same-day consumption cycles.
200ml dominates installed base. 100ml is where expansion concentrates.
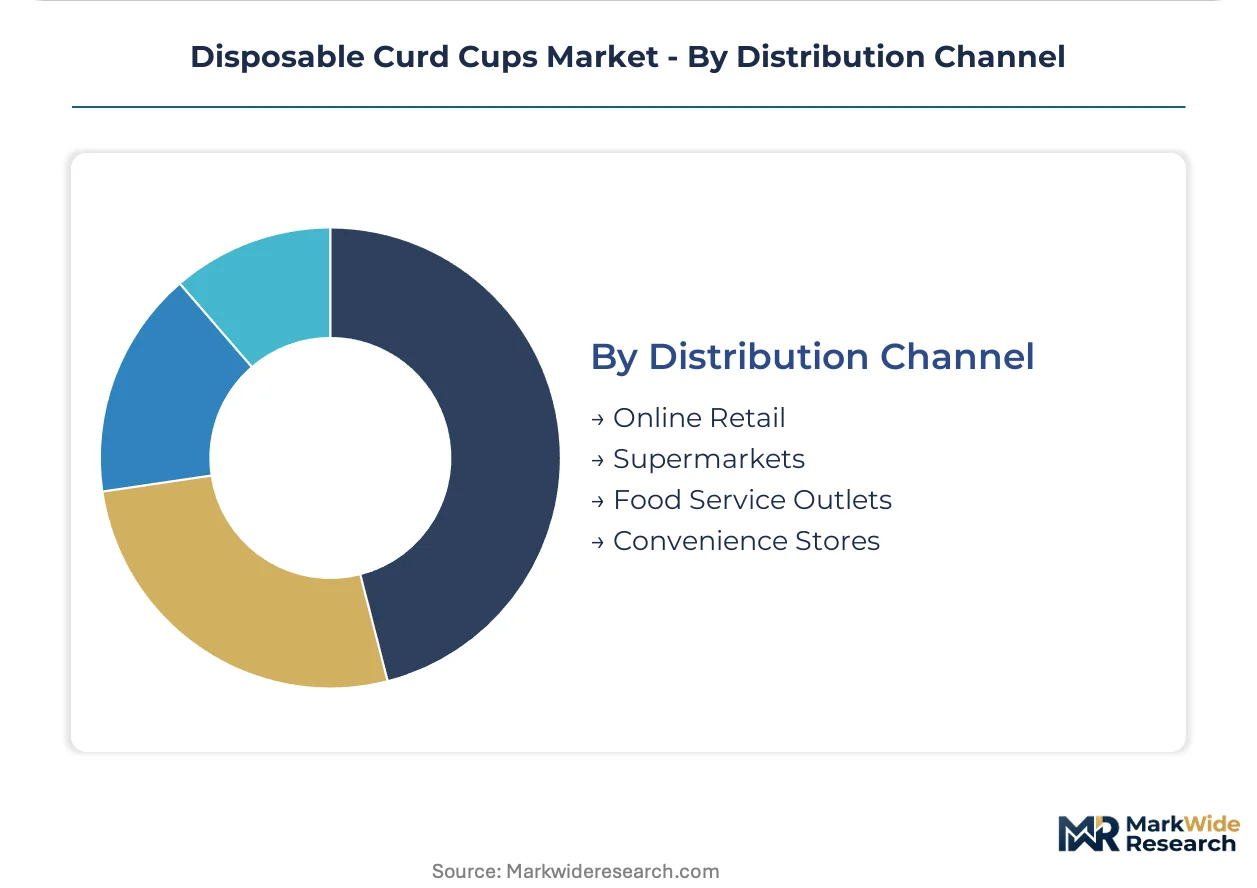
Distribution Channel:
Customer type determines packaging performance requirements, with food service demanding portion control and online retail requiring shelf-ready presentation.
- Food Service Outlets:Quick-service restaurants and institutional caterers specifying 200ml formats with tamper-evident seals and stackability for chilled holding equipment. Huhtamaki's molded fiber supply relationships anchor this channel.
- Online Retail:Quick-commerce platforms requiring real-time inventory visibility and dynamic lot-traceability that favors converters with integrated MES platforms.
- Supermarkets:Organized retail chains in Tamil Nadu and Karnataka with standardized planogram requirements and promotional display specifications.
- Convenience Stores:Small-format neighborhood retailers with limited refrigeration capacity favoring ambient-stable barrier-coated paper formats.
Food service outlets dominate installed base. Online retail is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FSSAI migration limits and BIS dimensional standards anchor regulatory pressure across India's organized dairy retail corridor. State-level EPR enforcement creates compliance fragmentation that shapes converter investment decisions. Tamil Nadu, Karnataka, and Kerala concentrate demand for single-serve curd packaging formats.
Tamil Nadu
Coimbatore's converter cluster processes the highest polypropylene cup volumes for interstate dairy distribution. BIS mandates specific neck-finish tolerances that exclude uncertified imported substrates from interstate commerce. Small-scale thermoforming operations face disproportionate adaptation costs, accelerating consolidation toward integrated dairy-packaging facilities.
Karnataka
The Bangalore-Tumkur dairy corridor drives 200ml format demand through high-speed filling lines serving organized cooperatives. State-level plastic waste management rules enforce EPR compliance deadlines earlier than neighboring states. Quick-service restaurant chains in Bengaluru pilot molded fiber cups with oxygen transmission rates below industry thresholds.
Kerala
Lower organized dairy penetration relative to Tamil Nadu creates whitespace for branded single-serve packaging in Kochi and Thiruvananthapuram. Institutional catering applications favor multi-compartment cup designs separating curd from condiments. Biodegradable material mandates signal regulatory tailwind for compostable formats in hospitality procurement.
Maharashtra
Sugarcane harvest cycles in Maharashtra and Uttar Pradesh directly influence PLA and bagasse feedstock pricing for converter margins. Mumbai's food service distribution networks consolidate procurement around portion-controlled formats for chilled dairy. The state's plastic waste management framework extends EPR obligations to institutional buyers in quick-commerce channels.
Andhra Pradesh
Emerging dairy processing capacity in Visakhapatnam and Vijayawada builds cold chain infrastructure favoring shelf-ready 100ml portion packs. Quick-commerce platform expansion into tier-two cities drives demand for real-time inventory visibility systems. Converter qualification cycles compress from annual reviews to quarterly performance audits as buyer consolidation accelerates.
Disposable Curd Cups Market Competitive Environment
Integrated packaging conglomerates and specialized dairy-format converters split the market between scale-driven substrate supply and application-specific engineering. The vendor base concentrates around multi-material production flexibility and barrier-coated paper expertise. Three archetypes dominate: global substrate suppliers with Indian distribution networks, regional thermoforming specialists with BIS certification capabilities, and quick-service restaurant anchor suppliers with molded fiber scale. Competitive moves center on backward integration into biopolymer sourcing and retrofit partnerships with European thermoforming equipment suppliers.
Among global substrate suppliers, Amcor anchors barrier-coated paper formats that extend shelf stability for ambient distribution channels. Berry Global exemplifies multi-material production flexibility competing across price-sensitive emerging markets. Huhtamaki occupies a position leveraging molded fiber expertise to anchor supply relationships with quick-service restaurants across India. These three represent the strategic archetypes shaping procurement consolidation among organized dairy cooperatives and institutional food service buyers.
| Leading Market Players |
|---|
| Amcor |
| Berry Global |
| Huhtamaki |
| Sonoco |
| Sealed Air |
| Printpack |
| Pactiv Evergreen |
| Dart Container Corporation |
| Winpak |
| Others |
Value Chain & Pricing Dynamics
Maharashtra and Uttar Pradesh sugarcane harvest cycles anchor biopolymer feedstock pricing, concentrating margin pools with converters who secured long-term bagasse supply contracts before harvest volatility intensified. Tamil Nadu's polypropylene converter cluster competes on scale, while Kerala's underserved retail corridor allows premium positioning for certified compostable formats.
Pricing Analysis
Tamil Nadu commands the narrowest price spreads for standard polypropylene cups, while Kerala supports 15-20% premiums for custom-branded formats. Three-tier pricing structure across premium, standard, and economy levels separates BIS-certified barrier-coated paper from uncertified imports from basic polypropylene. Cost compression in biodegradable tiers is intensifying because sugarcane harvest variability squeezes PLA converter margins. Quick-service restaurants show least price sensitivity due to EPR compliance mandates, while unorganized dairy cooperatives in Andhra Pradesh resist any material cost pass-through.
Supply Chain Analysis
Tariff exposure between India and EU chemical suppliers dominates supply chain risk for export-bound producers seeking REACH-compliant barrier coatings. Thermoforming equipment concentrates with German and Chinese machinery suppliers, while raw material sourcing draws from Maharashtra sugarcane, Tamil Nadu petrochemical feedstock, and imported bio-based polymers. Single-source vulnerability sits with European coating chemistry providers who control migration-resistant formulations. Distribution runs through organized dairy cooperatives in Karnataka and Tamil Nadu, with quick-commerce platforms building direct converter relationships in Bengaluru and Hyderabad.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Material certification services and BIS compliance consulting attach recurring revenue streams expanding faster than cup manufacturing itself, as converters face 14-18 month migration testing timelines.
For Market Incumbents: Pre-empt consolidation in Tamil Nadu's Coimbatore cluster by acquiring small-scale thermoforming operations before BIS dimensional mandates force exit. Anchor supply relationships with quick-service restaurant chains through molded fiber capacity expansion in Karnataka. Threat substitution from bagasse-based alternatives demands backward integration into Maharashtra sugarcane processing. For New Entrants and Emerging Players: Kerala's Kochi-Thiruvananthapuram corridor represents the most penetrable entry point, with organized dairy penetration trailing Tamil Nadu by 30-40 percentage points. 100ml portion packs for quick-commerce cold chains offer second white-space target, as Blinkit and Zepto build dedicated chilled dairy infrastructure. Go-to-market through platform-native supplier qualification programs bypasses traditional cooperative procurement barriers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European thermoforming equipment suppliers who overexpanded into India's fiber-cup retrofit wave. Long-term viability hinges on converters who locked biopolymer feedstock contracts before sugarcane price volatility. Watch BIS certification backlog clearance as inflection signal for product launch velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Biopolymer Sourcing | Maharashtra sugarcane processors who captive-supply bagasse isolate margin from harvest volatility. |
| BIS Certification Fast-Track Investment | Converters who compress 14-month migration timelines to 8 months capture QSR procurement consolidation. |
| Molded Fiber Equipment Partnership | European machinery suppliers with local service presence in Bengaluru anchor fiber-cup retrofit cycles. |
| Quick-Commerce Platform Integration | Blinkit and Zepto supplier qualification programs demand real-time MES visibility from converters. |
| EPR Compliance Service Bundling | Converters who package certified compostable cups with waste-management consulting attach recurring revenue. |
Study Parameters
Operator-level perspectives from dairy procurement managers, thermoforming plant engineers, BIS certification consultants, and quick-commerce supply chain directors anchored the qualitative base. Secondary validation drew from FSSAI packaging migration guidelines, BIS dimensional standards filings, state-level plastic waste management rule notifications, and organized dairy cooperative annual reports. Bottom-up volume modeling across material, size, and channel segments triangulated against top-down spending estimates from food service distribution networks.
Scenario-bracketing framed projections across regulatory acceleration and feedstock volatility assumptions over the analysis window. Segmentation dimensions modeled included material substrate tier, cup format size, distribution channel type, and state-level EPR enforcement intensity. CAGRs derived from fitted growth curves applied to base-year volume estimates, with cross-checks against dairy processing capacity expansion in Karnataka and Tamil Nadu and quick-commerce cold chain infrastructure buildout.
Practitioners should monitor BIS certification timeline compression, sugarcane harvest yield variance, and quick-commerce platform supplier consolidation for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Dairy Dessert and Yogurt Market
Dairy Products
Sweetened Condensed Milk Market
Dairy Products
Condensed Milk Market
Dairy Products
Spicy Dairy Products Market
Dairy Products
Mascarpone Cheese Market
Dairy Products
Indonesia Whey Protein Market
Dairy Products
Greek Yogurt Market
Dairy Products
Spoonable Yogurt Market
Dairy Products
GCC Fresh Milk Market
Dairy Products
Global Lipolyzed Butter Fat Market
Dairy Products
Africa Yogurt Market
Dairy Products
South America Dairy Protein Market
Dairy Products
North America Yogurt Market
Dairy Products
Yogurt Drink Market
Dairy Products
Ready-To-Use Cheese Market
Dairy Products
Condensed Whey Market