
 Wet Cat Food Market | 2026-2036
Wet Cat Food Market Size, Share, and Industry Trends Forecast 2026-2036
Wet Cat Food Market Outlook
AAFCO nutrient profiles is rebalancing the cost-of-entry calculus for new entrants by mandating laboratory-verified formulation compliance before products reach retail shelves. Mars Petcare leverages captive manufacturing infrastructure across multiple continents to sustain cost discipline at scale. Nestlé Purina PetCare anchors North American distribution through veterinary clinic partnerships and mass retail channel control. Blue Buffalo differentiates via grain-free positioning and ingredient transparency narratives that command shelf price premiums.
Wet cat food comprises moisture-rich formulations typically containing 75-85% water content, manufactured through retort sterilization or aseptic filling processes to achieve commercial sterility without synthetic preservatives. Canned formats occupy the dominant volume share due to established supply chains and consumer familiarity, while pouches represent the fastest-growing format driven by portion convenience and reduced packaging waste profiles. Grain-free formulations command margin premiums, though high-protein and balanced nutrition segments are expanding as veterinary nutrition science influences purchasing behavior. Online distribution channels are capturing incremental share from supermarkets and pet stores as subscription models and direct-to-consumer platforms reduce intermediary costs.
FDA Center for Veterinary Medicine oversight and AAFCO model regulations govern ingredient safety and nutritional adequacy claims across the United States, while the EU's Feed Hygiene Regulation and FEDIAF nutritional guidelines establish parallel compliance frameworks in Europe. China's Ministry of Agriculture and Rural Affairs (MARA) and national feed safety standards impose additional testing requirements for imported products. Stakeholders must monitor evolving regulatory convergence around sustainability disclosures and packaging recyclability mandates that will reshape sourcing decisions and capital allocation priorities.
Market Dynamics
AAFCO laboratory-verified formulation mandates are compressing the cost-of-entry calculus for wet cat food entrants, forcing pre-market nutritional adequacy testing that favors scaled incumbents with captive laboratory infrastructure.
Growth Catalysts
- Veterinary endorsement channels:Clinic-based prescription diets in the United States and Germany are driving premium wet formulation uptake as pet owners prioritize clinical validation over mass-market positioning.
- Retort pouch technology:Aseptic filling advances are enabling single-serve convenience formats that reduce food waste and command shelf price premiums in urban China.
- Grain-free protein positioning:AAFCO-compliant high-protein label claims are capturing margin expansion as pet owners substitute carbohydrate-heavy dry kibble with moisture-rich alternatives.
Market Restraints
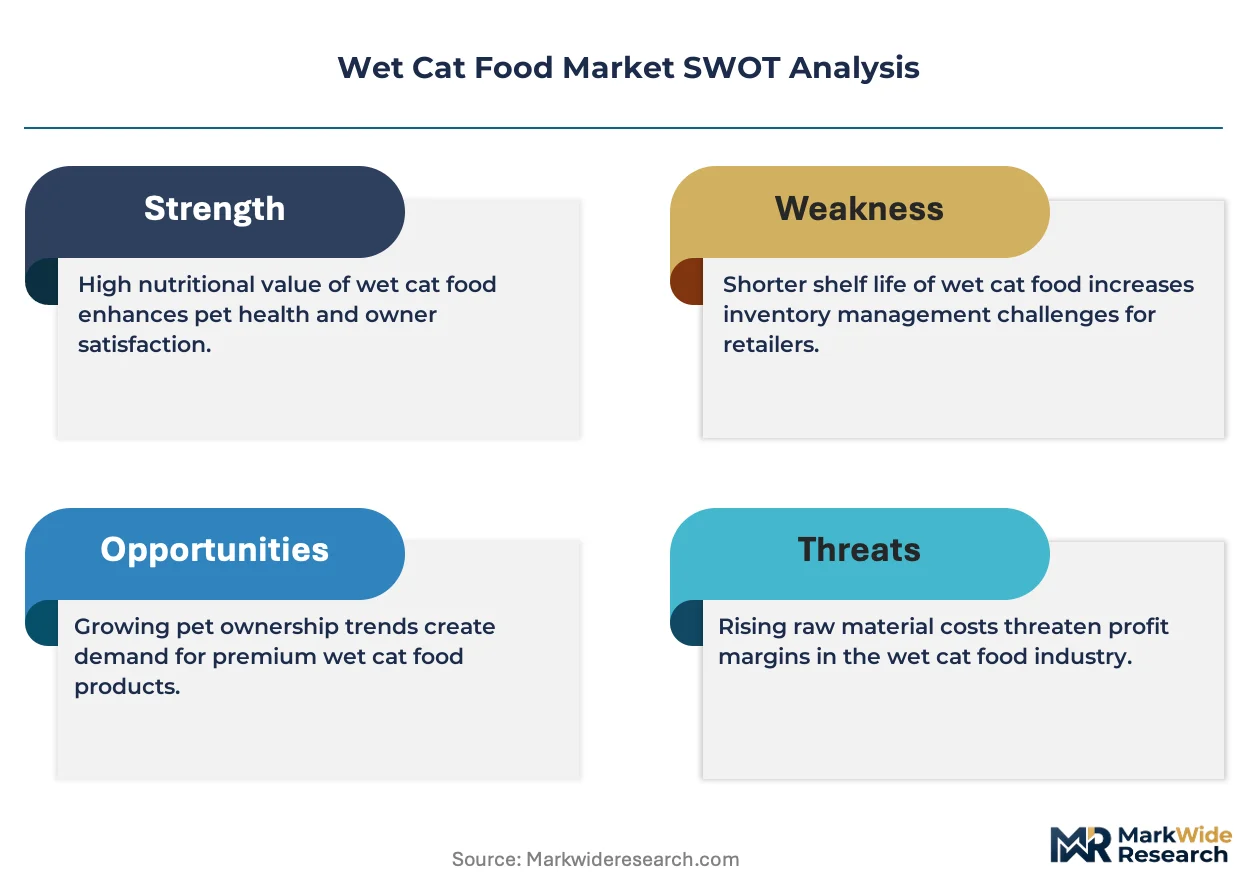
- Animal protein input volatility:Chicken and fish meal prices fluctuate with agricultural commodity cycles, compressing gross margins for mid-tier manufacturers lacking long-term supply contracts.
- Supply concentration in retort canning:North American and European sterilization infrastructure is controlled by a limited set of contract manufacturers, creating queue bottlenecks during demand surges.
- Preservative-free shelf stability limits:Eliminating synthetic additives reduces ambient shelf life to 18-24 months versus 36+ for conventional formulations, constraining inventory flexibility.
Strategic Opportunities
- Subscription direct-to-consumer platforms:Automated replenishment models in the United States are bypassing supermarket slotting fees and capturing recurring revenue streams with higher lifetime value metrics.
- Insect protein regulatory approval:EFSA novel food authorization processes in Europe are creating first-mover advantage for brands achieving compliance ahead of mass-market competitors.
- Veterinary telehealth integration:Remote consultation platforms are expanding prescription diet access beyond physical clinic footprints, particularly in underserved rural United States markets.
Industry Challenges
- Formulation chemist talent scarcity:Laboratory-verified AAFCO compliance requires specialized expertise in pet nutrition science that outstrips current graduate program output.
- Packaging recyclability compliance timelines:EU Single-Use Plastics Directive implementation deadlines are forcing rapid material transitions without guaranteed alternative supply chain readiness.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wet Cat Food Market |
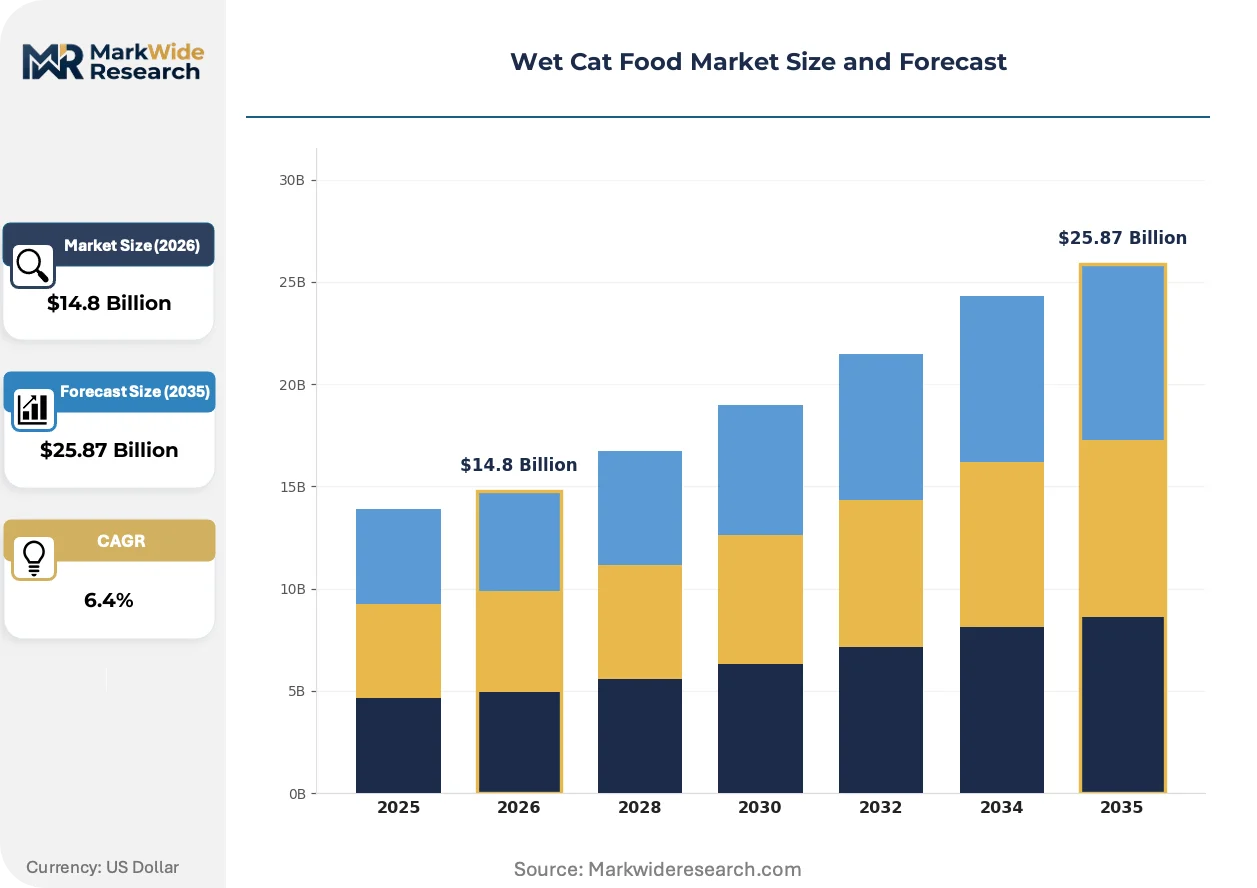
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $25.87 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Canned, Pouches, Tubs, Treats Ingredient Type: Meat, Fish, Poultry, Grains Formulation: Grain-Free, High-Protein, Organic, Balanced Nutrition Distribution Channel: Online, Supermarkets, Pet Stores, Wholesalers |
| Companies Covered | Nestlé Purina PetCare, Mars Petcare, Colgate-Palmolive, Hill's Pet Nutrition, General Mills, The J.M. Smucker Company, Blue Buffalo, Diamond Pet Foods, WellPet LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wet Cat Food Market Strategic Shifts
Moisture-rich formulation science and packaging material transitions are compressing traditional manufacturing economics while enabling new distribution pathways that bypass conventional retail intermediaries.
Aseptic cold-fill processing is decentralizing wet cat food production geography by enabling smaller-scale manufacturing without retort sterilization infrastructure. Regional co-manufacturers in secondary United States markets are adopting this technology to serve subscription brands with localized fulfillment. The technology is decentralizing supply chain concentration away from centralized canning facilities toward distributed production nodes.
EU packaging recyclability mandates under the Single-Use Plastics Directive are forcing material transitions from multi-layer laminates to mono-material pouches. German and French manufacturers are accelerating aluminum and paper-based format trials to maintain market access. Wet food pouches in Europe are most affected, with brands reformulating filling viscosity to accommodate new barrier properties.
Urban pet owners are consolidating purchase decisions around veterinary-validated nutrition claims rather than ingredient marketing narratives. E-commerce platforms in China and the United States are displacing supermarket pet aisles as the primary discovery channel for premium wet formulations. This behavioral pivot is most visible in tier-one Chinese cities where veterinary clinic partnerships drive online prescription fulfillment.
Wet Cat Food Market Segmentation
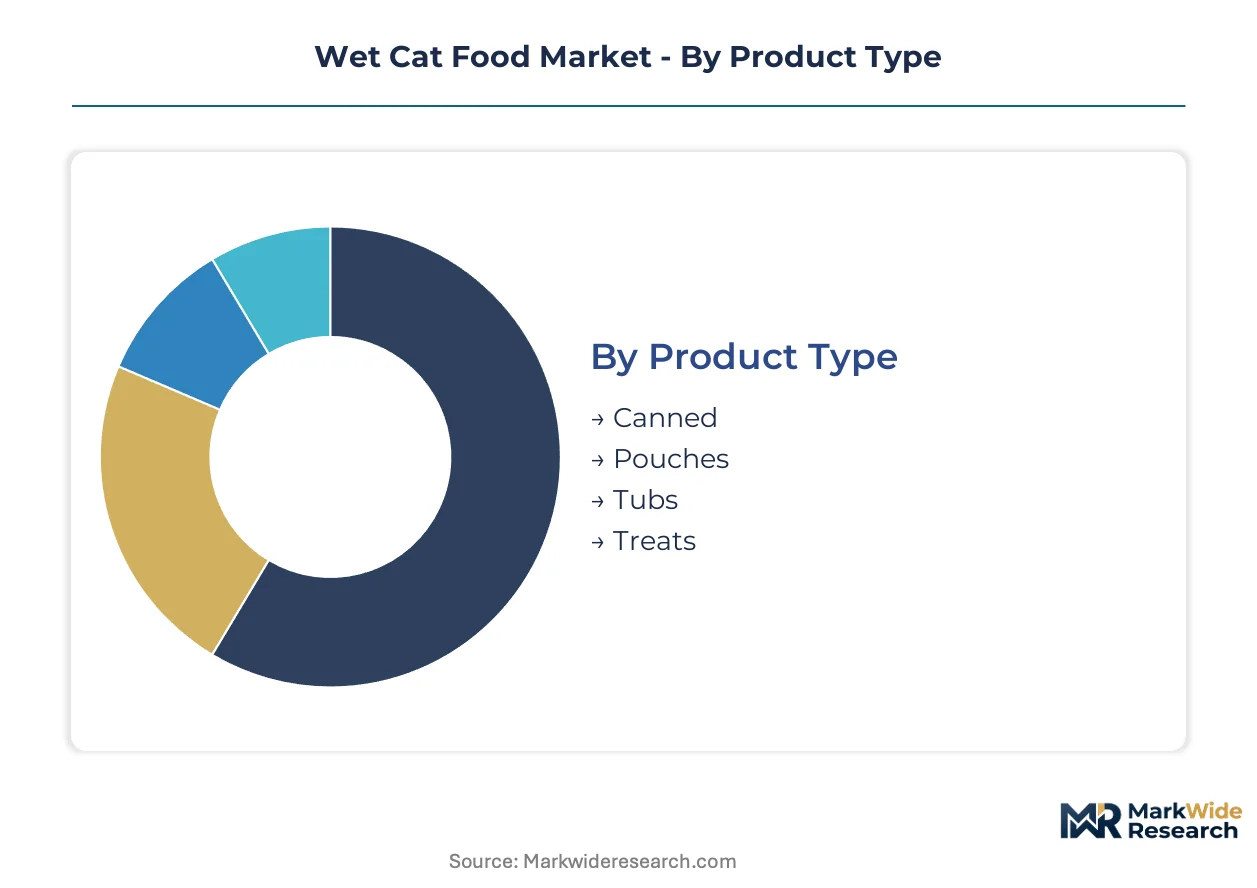
Wet cat food segmentation reveals how capital deployment, regulatory compliance, and channel economics fragment competitive opportunity across four structural dimensions. Manufacturers must align production infrastructure with specific segment requirements rather than pursuing undifferentiated scale.
Product Type:
Retort sterilization equipment and aseptic filling lines represent the primary capital intensity differentiator across formats, with canned production requiring substantially higher upfront investment than flexible alternatives.
- Canned:Metal can formats utilize high-pressure retort sterilization chambers and seam-sealing infrastructure to achieve commercial sterility without preservatives. Demand concentrates in the United States and Germany where established supply chains and veterinary clinic endorsement sustain volume leadership despite higher per-unit packaging costs.
- Pouches:Multi-layer laminate formats employ aseptic cold-fill processing that reduces energy input and enables single-serve convenience positioning. Urban China absorbs the fastest expansion as portion-controlled formats align with smaller household sizes and reduced food waste priorities.
- Tubs:Rigid plastic containers target premium positioning through resealable convenience and enhanced shelf visibility. North American mass retail channels favor this format for multi-cat households seeking value-oriented bulk purchasing.
- Treats:Small-format complementary feeding products occupy impulse purchase occasions with minimal nutritional adequacy requirements. Pet store channels in the United States and United Kingdom drive placement through cross-merchandising strategies.
Canned formats absorb the bulk of installed sterilization capacity; pouches are expanding most quickly as aseptic technology decentralizes production geography.
Ingredient Type:
Raw material procurement patterns and cold-chain requirements determine working capital intensity across protein sourcing strategies, with fresh meat imposing stricter inventory turnover constraints than rendered meals.
- Meat:Beef and pork formulations command veterinary endorsement in prescription diet channels where novel protein protocols address food sensitivity diagnostics. Germany and France sustain concentrated demand through clinic-based distribution partnerships.
- Fish:Tuna and salmon variants dominate Asian markets with established consumer preference for marine protein sources. Supply volatility in Thai and Peruvian fishery outputs compresses margin stability for mid-tier manufacturers lacking long-term purchase agreements.
- Poultry:Chicken-based formulations offer the most stable cost structure through vertically integrated agricultural supply chains. Mass-market positioning in the United States leverages this predictability for promotional pricing cadences.
- Grains:Carbohydrate-inclusive recipes retain cost-sensitive volume in developing markets where price elasticity exceeds nutritional premium willingness. China's tier-three cities sustain this positioning despite grain-free trend penetration in coastal urban centers.
Poultry absorbs the bulk of procurement volume; fish is climbing the fastest as marine protein positioning captures premium shelf placement.
Formulation:
Laboratory verification requirements and certification costs create tiered barriers to entry, with organic and prescription-grade formulations demanding substantially higher compliance investment than standard nutritional adequacy claims.
- Grain-Free:Formulations substitute legumes and tubers for traditional cereal binders to address carbohydrate sensitivity concerns. United States urban markets sustain price premiums through ingredient transparency marketing and AAFCO-compliant protein density claims.
- High-Protein:Elevated amino acid profiles target obligate carnivore metabolic requirements with veterinary nutrition science validation. Clinic channels in Germany and the United States drive prescription-tier placement and recurring subscription conversion.
- Organic:USDA or EU organic certification mandates restrict ingredient sourcing to verified supply chains with complete traceability documentation. Premium positioning captures margin expansion in French and British markets where certification awareness exceeds North American penetration.
- Balanced Nutrition:Standard AAFCO or FEDIAF-compliant formulations optimize cost-positioning for mass-market volume. Supermarket channels in the United States and China depend on this tier for promotional pricing and household penetration metrics.
Balanced nutrition absorbs the bulk of production volume; high-protein is gaining share fastest as veterinary endorsement channels expand beyond physical clinic footprints.
Distribution Channel:
Customer acquisition economics and inventory carrying costs diverge sharply across channels, with direct-to-consumer platforms requiring technology investment that competes with slotting fee obligations in brick-and-mortar retail.
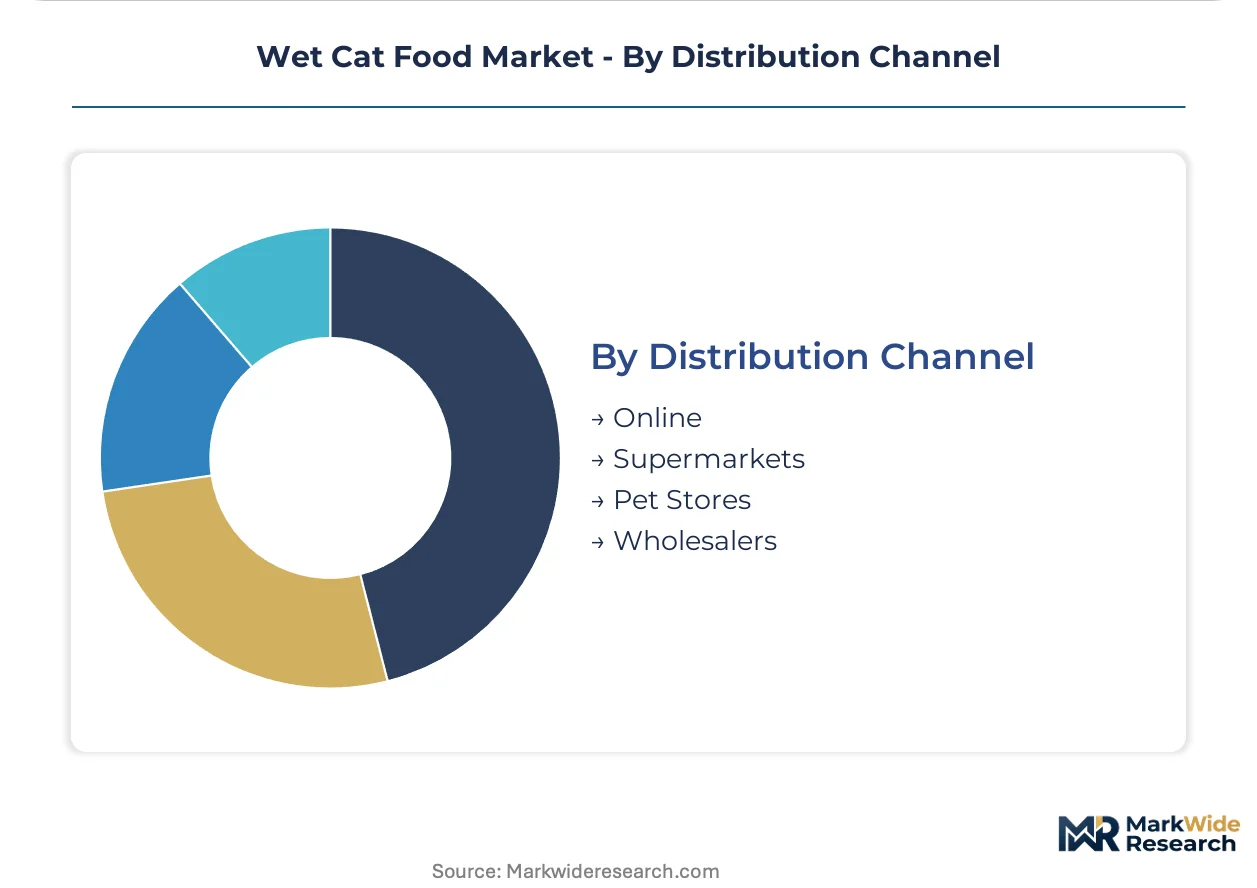
- Online:Subscription models and marketplace platforms bypass intermediary margins while capturing recurring revenue streams with superior lifetime value metrics. China's tier-one cities and United States metropolitan areas sustain the steepest expansion trajectory as veterinary telehealth integration enables prescription fulfillment.
- Supermarkets:Mass retail placement depends on slotting fee negotiations and promotional calendar alignment with category management priorities. Germany's consolidated retail landscape concentrates negotiating power among a limited buyer base.
- Pet Stores:Specialized channels offer educated staff consultation and premium format visibility that supports margin-intensive positioning. United Kingdom and United States independent retailers sustain this role despite e-commerce displacement pressure.
- Wholesalers:Bulk distribution to veterinary clinics, shelters, and multi-unit operators captures institutional volume with reduced marketing overhead. Rural United States markets depend on this channel where direct-to-consumer logistics remain underdeveloped.
Supermarkets absorb the bulk of shipment volume; online is expanding most quickly as subscription automation reduces customer acquisition costs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wet cat food consumption clusters in affluent urban centers where veterinary endorsement and e-commerce penetration intersect. Regulatory frameworks diverge sharply across major markets, shaping formulation costs and channel economics.
United States
Veterinary clinic partnerships and subscription direct-to-consumer platforms drive premium wet formulation uptake. FDA Center for Veterinary Medicine oversight mandates pre-market nutritional adequacy verification through AAFCO laboratory protocols. The Dallas-Fort Worth metroplex hosts concentrated contract manufacturing infrastructure serving national distribution networks.
China
Tier-one cities absorb rapid pouch format expansion as single-serve convenience aligns with smaller household sizes. Ministry of Agriculture and Rural Affairs feed safety standards impose additional testing requirements for imported products. Shanghai's veterinary telehealth platforms are expanding prescription diet access beyond physical clinic footprints.
Germany
Clinic-based prescription diets sustain premium positioning through clinical validation over mass-market alternatives. EU Feed Hygiene Regulation and FEDIAF nutritional guidelines establish parallel compliance frameworks to US standards. Bavaria's manufacturing clusters are accelerating aluminum and paper-based packaging trials to meet Single-Use Plastics Directive deadlines.
United Kingdom
Independent pet retailers sustain margin-intensive positioning despite e-commerce displacement pressure. FEDIAF guidelines govern nutritional adequacy claims alongside national feed safety enforcement. Greater London's subscription fulfillment centers are capturing recurring revenue streams with superior lifetime value metrics.
Japan
Marine protein preference drives tuna and salmon variant demand through established consumer taste profiles. METI standards and national feed safety regulations impose ingredient traceability requirements. Tokyo-Osaka corridor retail channels favor premium resealable tub formats for multi-cat household convenience.
Wet Cat Food Market Competitive Environment
United States producers anchor one tier; European specialists hold formulation science positioning. The vendor base separates into consolidated multinational portfolios and regional co-manufacturing networks. Three archetypes dominate: scaled incumbents with captive laboratory infrastructure, ingredient-transparent challengers commanding shelf price premiums, and contract manufacturers serving private-label and subscription brands. Competitive moves concentrate on veterinary channel partnerships and aseptic filling technology licensing.
Within the scaled multinational tier, Nestlé Purina PetCare and Mars Petcare represent archetypal positions through North American distribution control and captive manufacturing infrastructure across multiple continents. Blue Buffalo exemplifies the ingredient-transparent challenger model through grain-free positioning narratives that command margin premiums in urban United States markets.
| Leading Market Players |
|---|
| Nestlé Purina PetCare |
| Mars Petcare |
| Colgate-Palmolive |
| Hill's Pet Nutrition |
| General Mills |
| The J.M. Smucker Company |
| Blue Buffalo |
| Diamond Pet Foods |
| WellPet LLC |
| Others |
Value Chain & Pricing Dynamics
Captive manufacturing infrastructure across multiple continents anchors both supply security and pricing power for scaled wet cat food producers, enabling cost discipline that contract-dependent competitors cannot replicate. This integration pattern concentrates margin capture among incumbents with in-house retort sterilization capacity while forcing mid-tier brands toward premium positioning to offset third-party manufacturing premiums.
Pricing Analysis
Volume-mass positioning absorbs procurement scale efficiencies in poultry-based formulations, while grain-free and prescription-grade segments command shelf price premiums through AAFCO laboratory verification and veterinary endorsement. Price differentiation rests on certification tier and channel control, with clinic-based prescription diets capturing the least price-sensitive buyers and supermarket bulk formats serving the most elastic demand. Pricing pressure intensifies in mid-tier segments as private-label alternatives compress branded positioning room.
Supply Chain Analysis
Dual-sourcing requirements for animal protein inputs mandate multi-supplier qualification across Thailand, Peru, and domestic United States poultry operations to mitigate fishery output volatility and agricultural commodity cycles. Raw material dependencies center on chicken meal, tuna harvests, and multi-layer laminate packaging substrates. Single-source vulnerability in North American retort canning infrastructure creates queue bottlenecks during demand surges. Distribution runs through veterinary clinic networks, subscription fulfillment platforms, and mass retail channels with divergent slotting fee structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into captive laboratory infrastructure and sterilization capacity has become the defining competitive race, with upstream control over AAFCO compliance verification and downstream channel partnerships determining margin sustainability.
For Market Incumbents: Extend veterinary clinic partnership networks to lock prescription diet access before telehealth platforms democratize distribution. Deepen backward integration into protein rendering operations to buffer agricultural commodity volatility. Threat substitution from aseptic cold-fill technology demands preemptive licensing or acquisition of regional co-manufacturers. For New Entrants and Emerging Players: Aseptic pouch technology offers a manufacturing wedge for subscription-first brands seeking to bypass retort infrastructure constraints. White-space targets concentrate in underserved rural United States markets where veterinary telehealth integration enables prescription fulfillment without physical clinic density. Direct-to-consumer positioning with automated replenishment captures recurring revenue streams. For Investors and Strategic Acquirers: Exit pathways concentrate in regional co-manufacturers with aseptic filling capabilities and established veterinary channel relationships. Long-term viability favors assets with laboratory-verified formulation infrastructure and subscription platform technology. Watch FDA enforcement patterns on AAFCO claim substantiation as the inflection signal for regulatory compliance cost escalation.| Strategic Initiative | Industry Significance |
|---|---|
| Veterinary Channel Partnership Expansion | Clinic-based prescription access locks recurring revenue with higher lifetime value metrics than mass retail. |
| Aseptic Cold-Fill Technology Licensing | Regional co-manufacturers adopt decentralized production to serve subscription brands with localized fulfillment. |
| Backward Integration into Protein Supply | Captive rendering operations buffer chicken and fish meal price volatility compressing mid-tier margins. |
| Subscription Platform Development | Automated replenishment models bypass supermarket slotting fees and capture superior customer lifetime value. |
| Sustainable Packaging Transition | Aluminum and paper-based format trials maintain EU market access under Single-Use Plastics Directive deadlines. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with veterinary nutritionists, pet food formulation chemists, retail category buyers, and contract manufacturing executives. FDA Center for Veterinary Medicine guidance documents, AAFCO model regulations, and EU FEDIAF nutritional guidelines provided regulatory framework validation. Bottom-up production capacity assessments triangulated against top-down consumption estimates across distribution channels.
Data-stream reconciliation integrated shipment volumes, import-export flows, and channel inventory turns across product format, protein source, formulation grade, and distribution pathway dimensions. CAGRs were derived from segmented growth trajectory modeling incorporating urban pet ownership rates, e-commerce penetration curves, and veterinary endorsement channel expansion. Forecast inputs included retort sterilization capacity utilization, aseptic filling technology adoption rates, and packaging material transition timelines.
Several conditions sit outside the modeled scope, including abrupt regulatory enforcement shifts, novel protein ingredient approvals, and macroeconomic disruptions to agricultural commodity markets. Forecasts reflect documented assumptions about veterinary channel partnership stability and subscription platform retention rates. Deviation in FDA AAFCO claim substantiation stringency or EU packaging recyclability mandate acceleration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Food and Infant Formula
Follow on Formula Milk Market
Baby Food and Infant Formula
Parenteral Formula Market
Baby Food and Infant Formula
Baby Food and Infant Formula Market
Baby Food and Infant Formula
Canned Pet Food Market
Baby Food and Infant Formula
Baby Formula Market
Baby Food and Infant Formula
Global Oligosaccharides in Infant Nutrition Market
Baby Food and Infant Formula
Organic Baby Food Market
Baby Food and Infant Formula
Baby Cereal-Based Complementary Food Market
Baby Food and Infant Formula
Infant Nutritional Premix Market
Baby Food and Infant Formula
South America Baby Food Market
Baby Food and Infant Formula
Baby Food Products Market
Baby Food and Infant Formula
South America Organic Baby Food Market
Baby Food and Infant Formula
Asia Pacific Organic Baby Food Market
Baby Food and Infant Formula
Anti-Spit Up Formula Market
Baby Food and Infant Formula
Canada Baby Food Market
Baby Food and Infant Formula
West Africa Baby Food Market