
 Time Series Databases Software Market | 2026-2036
Time Series Databases Software Market Size, Share, and Industry Trends Forecast 2026-2036
Time Series Databases Software Market Outlook
The gap between operational technology and information technology data layers is narrowing as edge computing architectures merge real-time ingestion with cloud analytics. InfluxDB leverages its open-source roots to anchor developer communities across industrial monitoring use cases. TimescaleDB specializes in SQL-compatible time-series extensions that compete directly with traditional relational migrations. kdb+ dominates high-frequency trading deployments where sub-millisecond query latency controls platform selection.
Time series databases software stores, retrieves, and processes data points indexed by timestamps, typically employing columnar storage engines with compression ratios exceeding 90% for sequential numeric values. The technology serves industrial and commercial purposes including predictive maintenance, algorithmic trading, and IoT telemetry pipelines where temporal ordering determines analytical validity. Cloud-based deployment captures the fastest expansion as enterprises exit capital-intensive on-premise infrastructure, while managed service offerings aggregate margin pools through operational outsourcing. Monitoring systems applications lead adoption volume, though financial analytics segments sustain premium pricing due to stringent latency requirements. SQL-based time-series hybrids are displacing pure NoSQL architectures where existing analyst skill pools reduce migration friction.
FDA 21 CFR Part 11 validation requirements shape pharmaceutical manufacturing telemetry standards, while EU GDPR and the EU AI Act impose data provenance and retention constraints on automated decision systems. The Federal Energy Regulatory Commission's Critical Infrastructure Protection standards in the United States mandate encrypted time-stamped logging for grid operators. ISO 27001 certification has become a baseline procurement filter across European energy and telecommunications buyers. Stakeholders must evaluate sovereign cloud requirements against latency budgets when architecting cross-border data pipelines.
Market Dynamics
Edge-to-cloud data pipelines are compressing the traditional latency gap between industrial telemetry ingestion and enterprise analytics, forcing vendors to unify previously separate operational and information technology stacks under single query engines.
Growth Catalysts
- EU AI Act data provenance mandates:Automated decision systems in European manufacturing must maintain immutable timestamped audit trails, accelerating replacement of legacy logging infrastructure with certified time-series platforms.
- Industrial IoT sensor density:Predictive maintenance deployments in automotive and precision engineering clusters generate sub-second resolution data streams that exceed relational database throughput limits.
- Columnar compression advances:Storage engines achieving above 90% compression ratios for sequential numeric telemetry reduce total cost of ownership for multi-year retention requirements in energy grid monitoring.
Market Restraints
- Specialized query language fragmentation:InfluxQL, PromQL, and proprietary SQL extensions force enterprises to maintain parallel skill pools, inflating workforce transition costs during platform migrations.
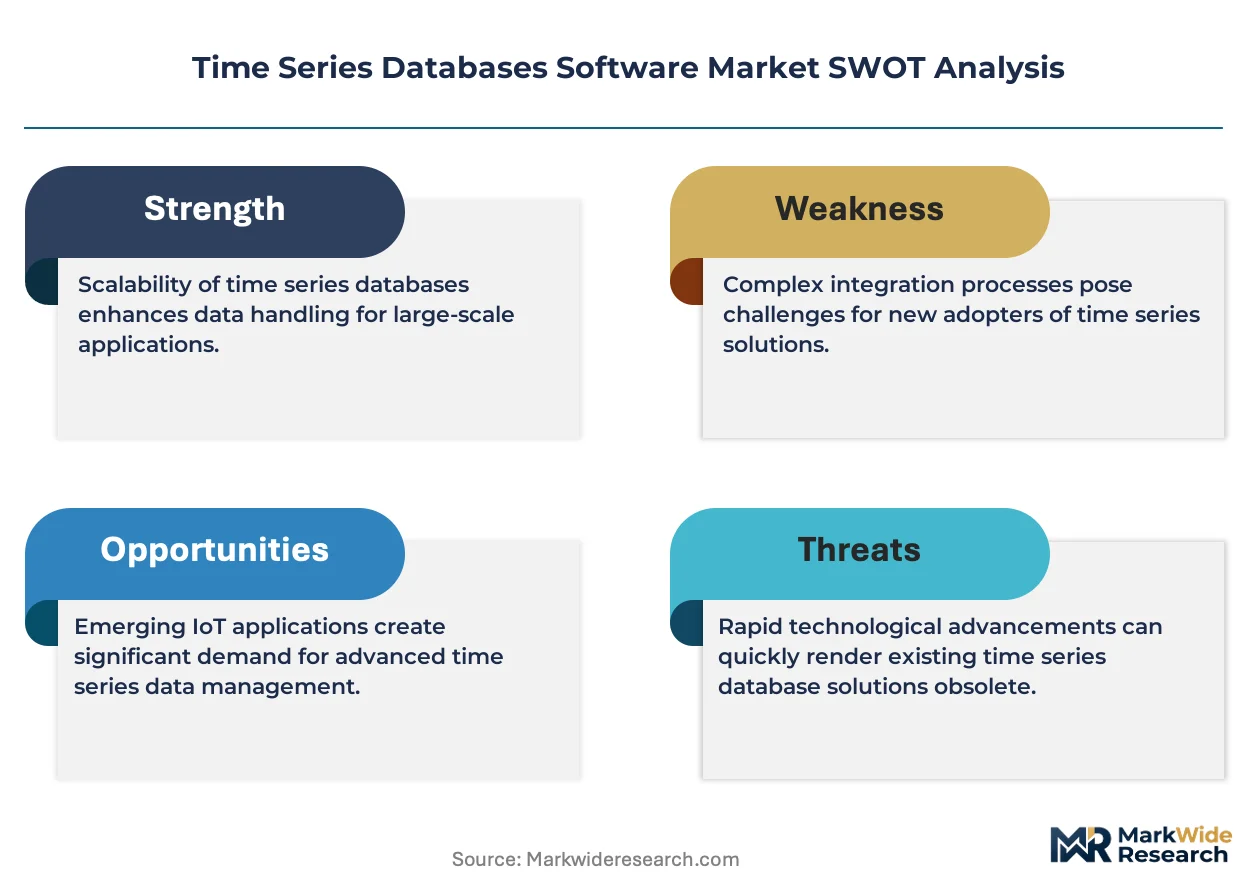
- Memory-intensive indexing overhead:High-cardinality tag sets in IoT deployments consume disproportionate RAM relative to raw data volume, constraining deployment on resource-constrained edge hardware.
- Cloud egress cost volatility:Cross-availability-zone replication of time-ordered datasets amplifies unpredictable bandwidth charges for multi-region industrial operators.
Strategic Opportunities
- Pharmaceutical FDA 21 CFR Part 11 validation:Electronic batch record systems require tamper-evident timestamped data stores, creating certified deployment opportunities in drug manufacturing telemetry.
- SQL-compatible time-series hybrids:PostgreSQL extensions capturing temporal workloads from existing business intelligence teams reduce migration friction against pure NoSQL alternatives.
- FERC Critical Infrastructure Protection standards:United States grid operators must implement encrypted time-stamped logging, mandating database replacements across regional transmission organizations.
Industry Challenges
- Time-series data science skill scarcity:Hybrid competencies spanning statistics, distributed systems, and domain-specific signal processing remain concentrated among quantitative finance and energy sector practitioners.
- ISO 27001 certification timelines:European energy and telecommunications procurement filters require 12-18 month audit cycles that delay vendor qualification for sovereign cloud deployments.
- Legacy historian integration complexity:Decades of proprietary tag naming conventions and custom aggregation logic in OSIsoft PI and Wonderware systems resist automated migration tooling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Time Series Databases Software Market |
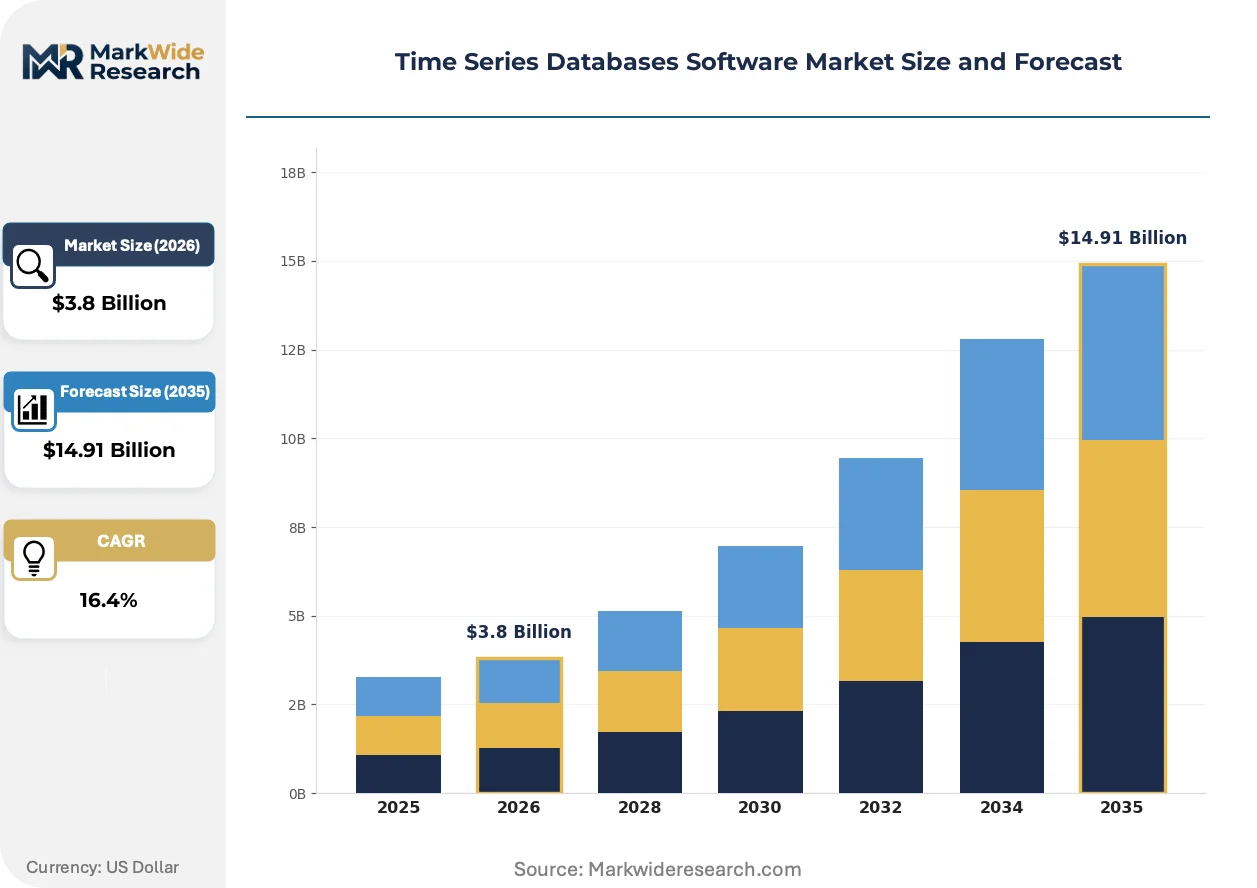
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $14.91 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Managed Service End User: Manufacturing, Telecommunications, Energy, Retail Application: Monitoring Systems, Financial Analytics, IoT Data Management, Log Management Technology: NoSQL, SQL, In-Memory, Time-Series |
| Companies Covered | CrateDB, VictoriaMetrics, InfluxDB, RaimaDB, kdb+, TimescaleDB, QuestDB, eXtremeDB, ClickHouse, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Time Series Databases Software Market Strategic Shifts
Query engine architectures are converging toward unified batch and stream processing, eliminating the historical separation between operational dashboards and retrospective analytics that forced enterprises to maintain dual infrastructure stacks.
Columnar storage formats optimized for sequential timestamped data are collapsing the performance gap between specialized time-series databases and general-purpose data warehouses. Financial services firms running algorithmic trading strategies adopt these engines to consolidate tick data analysis with regulatory reporting pipelines, compressing previously separate infrastructure investments into single platforms.
The EU AI Act's automated decision system requirements are mandating immutable data provenance chains across European manufacturing. Pharmaceutical producers in Germany and France must timestamp every inference input and model output, forcing database vendors to embed cryptographic verification directly within storage layers rather than bolt-on audit modules.
Consumption-based pricing for managed time-series services is displacing capacity-provisioned contracts in industrial IoT deployments. German automotive OEMs now negotiate per-million-metric pricing for predictive maintenance pipelines, transferring infrastructure risk to cloud providers while retaining operational control over edge ingestion points. This shift concentrates negotiating leverage among buyers with above-terabyte daily ingestion volumes.
Time Series Databases Software Market Segmentation
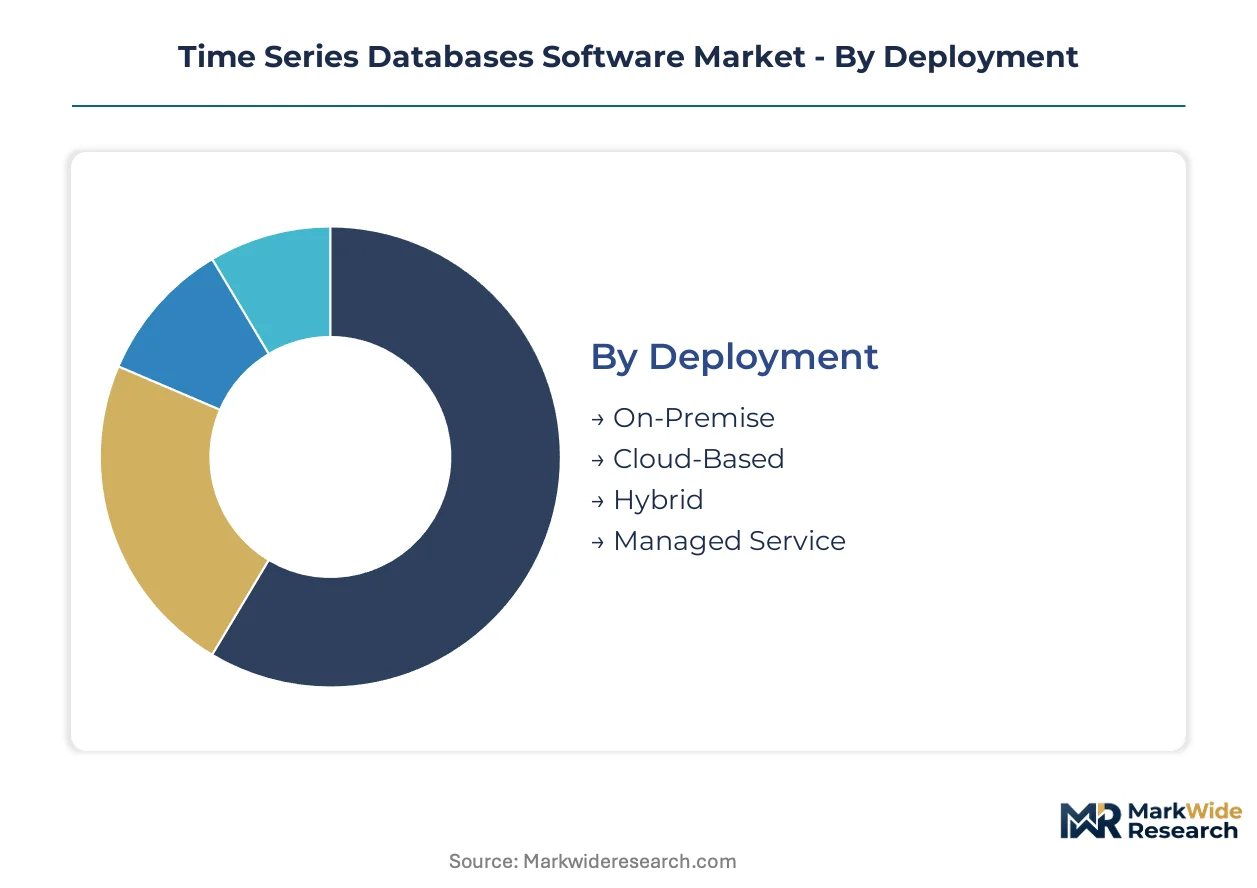
Deployment topology determines latency budgets and compliance postures across industrial IoT and financial services deployments. End-user verticals impose divergent throughput requirements and regulatory validation standards. Application workloads separate operational dashboards from algorithmic trading engines with distinct query patterns.
Deployment:
Cost tier structures separate capital-intensive ownership from operational expenditure models with variable scaling elasticity.
- Cloud-Based:Multi-tenant architectures with consumption-based metering eliminate upfront infrastructure commitments. German automotive OEMs negotiate per-million-metric pricing for predictive maintenance pipelines, transferring infrastructure risk to hyperscale providers while retaining edge ingestion control.
- Managed Service:Operational outsourcing aggregates margin pools through SLAs covering backup, patching, and availability guarantees. ISO 27001 certification timelines of 12-18 months delay vendor qualification for European energy and telecommunications procurement filters.
- On-Premise:Sovereign data residency mandates under GDPR and the EU AI Act sustain demand in defense and pharmaceutical manufacturing.
- Hybrid:Edge-to-cloud pipelines unify operational technology ingestion with enterprise analytics, compressing previously separate infrastructure stacks.
Cloud-Based holds installed capacity. Managed Service is rotating up the share rankings.
End User:
Customer type concentration reflects sector-specific latency thresholds and regulatory validation requirements.
- Manufacturing:Predictive maintenance deployments in automotive and precision engineering clusters generate sub-second resolution data streams exceeding relational database throughput limits. FDA 21 CFR Part 11 validation requirements shape pharmaceutical manufacturing telemetry standards for electronic batch record systems.
- Energy:FERC Critical Infrastructure Protection standards mandate encrypted time-stamped logging for United States grid operators, forcing database replacements across regional transmission organizations. Columnar compression above 90% reduces total cost of ownership for multi-year retention requirements.
- Telecommunications:Network performance monitoring requires sub-second latency for root-cause analysis across distributed infrastructure.
- Retail:Supply chain visibility and demand forecasting pipelines ingest high-cardinality sensor data with seasonal volume spikes.
Manufacturing anchors volume concentration. Energy is climbing the fastest among industrial verticals.
Application:
Functional workload characteristics separate stream-processing operational dashboards from batch retrospective analytics.
- Monitoring Systems:Real-time operational dashboards for infrastructure health and performance metrics lead adoption volume across industrial deployments. Unified batch and stream processing architectures eliminate historical separation between operational and retrospective analytics.
- Financial Analytics:Algorithmic trading strategies sustain premium pricing due to sub-millisecond query latency requirements. Tick data analysis consolidates with regulatory reporting pipelines, compressing previously separate infrastructure investments.
- IoT Data Management:High-cardinality tag sets in sensor deployments consume disproportionate RAM relative to raw data volume, constraining edge hardware configurations.
- Log Management:Immutable timestamped audit trails satisfy EU AI Act automated decision system provenance mandates across European manufacturing.
Monitoring Systems dominates transaction volume. Financial Analytics commands the steepest expansion trajectory in value terms.
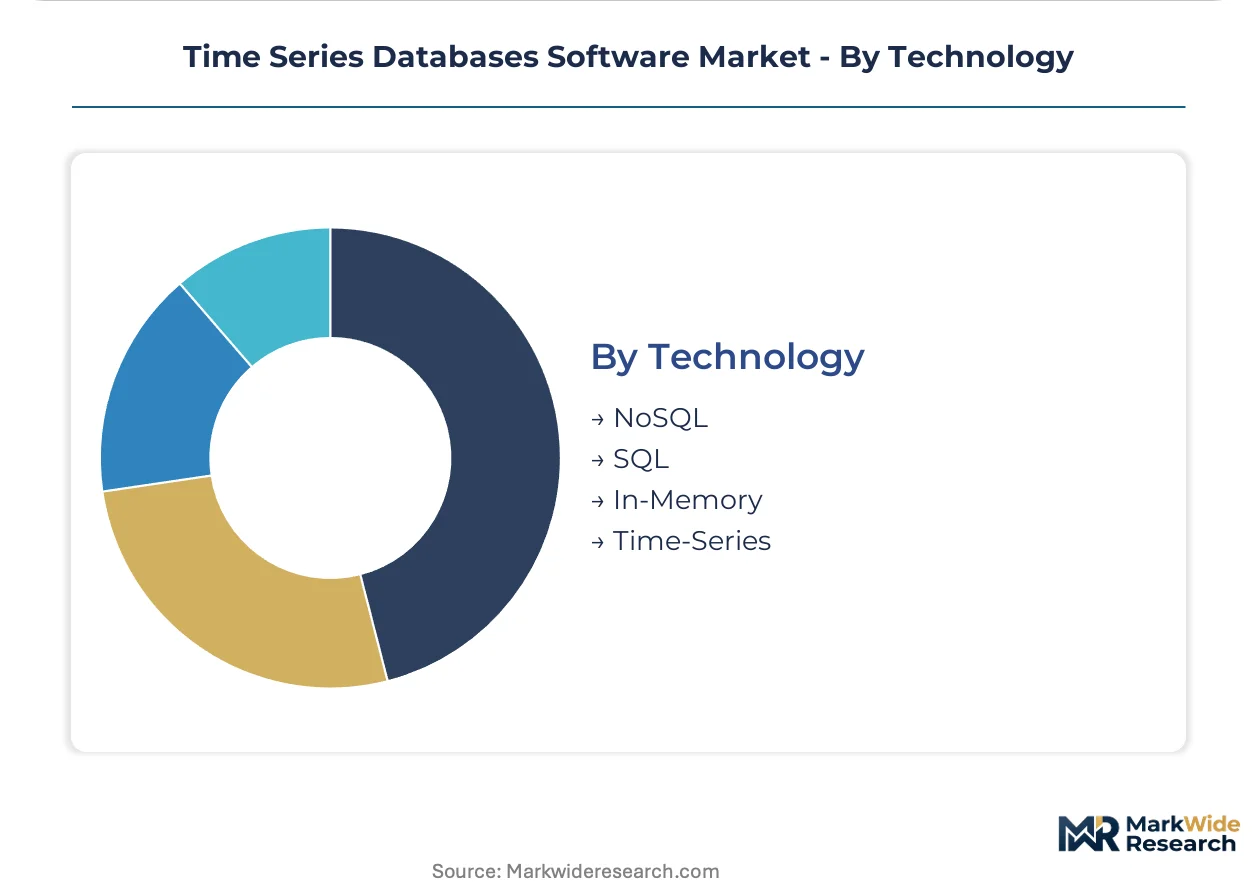
Technology:
Storage engine architecture determines compression ratios, query language compatibility, and migration friction from legacy systems.
- SQL:PostgreSQL extensions capturing temporal workloads reduce migration friction against pure NoSQL alternatives where existing analyst skill pools constrain platform transitions. SQL-compatible time-series hybrids displace pure NoSQL architectures in business intelligence environments.
- NoSQL:Schema flexibility accommodates unpredictable IoT sensor schemas with variable tag cardinality, though specialized query language fragmentation inflates workforce transition costs.
- In-Memory:Sub-millisecond query latency controls platform selection in high-frequency trading deployments where tick-to-trade windows determine profitability.
- Time-Series:Purpose-built columnar storage engines optimized for sequential timestamped data achieve compression ratios exceeding 90% for numeric telemetry.
SQL retains incumbent integration advantages. Time-Series is gaining share fastest as native optimization overtakes general-purpose adaptations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive OEMs and precision engineering clusters command the highest per-deployment telemetry volumes, while United States energy grid operators and financial exchanges sustain premium pricing tiers for sub-millisecond latency architectures.
United States
FERC mandates encrypted time-stamped logging for regional transmission organizations, forcing database replacements across grid infrastructure. The SEC's audit trail requirements for algorithmic trading reinforce demand for immutable data provenance in Chicago and New York financial exchanges. Texas energy operators deploy columnar compression engines to manage multi-year retention for critical infrastructure protection compliance.
Germany
Automotive OEMs in Stuttgart and Munich generate sub-second resolution predictive maintenance streams exceeding relational throughput limits. The EU AI Act's automated decision system mandates require cryptographic verification embedded directly within storage layers for pharmaceutical producers in Ludwigshafen. Baden-Württemberg precision engineering clusters negotiate per-million-metric pricing with hyperscale providers.
China
MIIT industrial internet initiatives accelerate smart manufacturing telemetry deployments across Yangtze River Delta electronics corridors. National data localization requirements under cybersecurity law sustain sovereign cloud demand for defense and pharmaceutical manufacturing in Beijing-Tianjin-Hebei. Shenzhen IoT sensor networks drive high-cardinality tag set architectures for supply chain visibility.
United Kingdom
London financial services firms consolidate tick data analysis with regulatory reporting pipelines under FCA market abuse surveillance mandates. The UK National Grid implements encrypted logging for critical infrastructure resilience standards. Edinburgh fintech clusters adopt SQL-compatible time-series hybrids to reduce migration friction from existing analyst skill pools.
Japan
METI smart factory standards drive predictive maintenance adoption in Nagoya automotive manufacturing corridors. Pharmaceutical producers in Osaka-Tokyo corridors implement FDA-aligned 21 CFR Part 11 validation for electronic batch record systems. Yokohama telecommunications operators require sub-second latency for network performance monitoring across distributed infrastructure.
Time Series Databases Software Market Competitive Environment
Channel-controlling players compete with product-specialist players across deployment topologies, creating a tiered structure where open-source roots anchor developer communities against proprietary high-frequency trading engines. The vendor base separates into three archetypes: SQL-compatible extension providers, purpose-built columnar storage specialists, and in-memory latency-optimized engines. Consolidation pressure intensifies as managed service offerings aggregate operational outsourcing contracts. Strategic moves center on geographic certification timelines and sovereign cloud qualification.
Within the open-source-anchored tier, InfluxDB and TimescaleDB exemplify divergent architectural bets on developer community expansion versus SQL compatibility migration friction reduction. kdb+ occupies a position at the latency-optimized extreme where sub-millisecond query performance controls platform selection. These three anchors illustrate how competitive positioning stratifies across operational technology integration depth, financial services premium pricing capture, and cloud-native consumption model adoption.
| Leading Market Players |
|---|
| CrateDB |
| VictoriaMetrics |
| InfluxDB |
| RaimaDB |
| kdb+ |
| TimescaleDB |
| QuestDB |
| eXtremeDB |
| ClickHouse |
| Others |
Value Chain & Pricing Dynamics
Hyperscale cloud capacity underutilization in Western Europe is forcing managed service providers to absorb infrastructure risk through consumption-based contracts, compressing margins while transferring pricing volatility to buyers with above-terabyte daily ingestion volumes.
Pricing Analysis
Cost-plus contracts indexed to compute instance pricing dominate enterprise procurement, with German automotive OEMs negotiating per-million-metric arrangements that bundle edge ingestion rights with cloud analytics tiers. Price differentiation rests on ISO 27001 certification status and query latency SLAs, with uncertified deployments facing steeper discounts. Pricing pressure stems from open-source alternatives commoditizing core ingestion engines. Small precision engineering clusters exhibit highest price sensitivity; high-frequency trading operations show least sensitivity due to sub-millisecond requirements.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for hardware-dependent edge deployments. Core development talent concentrates in the United States, Germany, and Ireland. Raw material dependencies span silicon wafers for edge processors, rare earth elements for sensor manufacturing, and specialized memory modules for in-memory databases. Distribution runs through hyperscale cloud marketplaces and direct enterprise sales teams with certified implementation partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a switching-cost fortress, where data gravity and query language entrenchment create defensive moats that compound with each additional sensor deployment and dashboard integration.
For Market Incumbents: Build regulatory certification moats by accelerating FDA 21 CFR Part 11 and EU AI Act validation timelines ahead of competitor audit cycles. Deepen vertical integration into edge hardware partnerships to control ingestion point economics. Counter threat from SQL-compatible PostgreSQL extensions by embedding cryptographic provenance directly within storage layers rather than bolt-on modules. For New Entrants and Emerging Players: Japanese pharmaceutical manufacturing corridors show geographic underpenetration by Western time-series vendors despite METI smart factory standardization. Target Osaka-Tokyo electronic batch record system replacements with FDA-aligned validation offerings. Pursue channel partnerships with regional system integrators possessing existing pharmaceutical relationships rather than direct enterprise sales builds. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among managed service providers with sovereign cloud qualifications, as GDPR and EU AI Act mandates sustain multi-year contract tenures. Long-term viability favors vendors with hybrid deployment architectures spanning edge ingestion and cloud analytics. Monitor ISO 27001 certification completion rates as inflection indicator for European energy and telecommunications procurement eligibility.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies edge ingestion with cloud analytics under single query engines for German automotive OEMs. |
| Strategic Partnership | Accelerates FDA 21 CFR Part 11 validation through pharmaceutical system integrator alliances. |
| Geographic Expansion | Captures Japanese METI smart factory standardization contracts in Nagoya manufacturing corridors. |
| Acquisition of Specialist Firm | Absorbs cryptographic provenance technology for EU AI Act automated decision system mandates. |
| Product Launch | Introduces SQL-compatible time-series hybrids to reduce migration friction from existing analyst pools. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with platform engineers at industrial IoT deployments, CTOs at financial services firms, regulatory affairs leads at pharmaceutical manufacturers, and procurement officers at European energy utilities. Secondary validation drew from SEC filings of publicly traded database vendors, hyperscaler capex disclosures, FERC infrastructure protection filings, and EMA regulatory guidance documents. Bottom-up deployment sizing and top-down market aggregation were triangulated to reconcile volume estimates.
Calibration against historical adoption curves and regulatory implementation timelines anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include deployment topology, end-user vertical, application workload, and storage engine architecture. CAGRs were derived from slope analysis of technology substitution patterns and compliance-driven replacement cycles. Industry-specific forecast inputs encompassed EU AI Act audit trail mandate rollout schedules and FERC Critical Infrastructure Protection enforcement intensity.
Macroeconomic conditions sit as an overlay; deviation in cloud infrastructure investment cycles or cross-border data transfer policy would shift the trajectory. Forecasts reflect underlying assumptions about regulatory enforcement consistency and open-source community maintenance continuity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Landscape Software Market
Software & Services
Collaborative Applications Market
Software & Services
Software Defined Broadcasting Market
Software & Services
Global Electronic Design Automation Tools (EDA) Market
Software & Services
Preventive Maintenance Software Market
Software & Services
Chromatography Data System (CDS) Software Market
Software & Services
Animation Design Software Market
Software & Services
Tech Support Services Market
Software & Services
Sports Production Software Market
Software & Services
School Timetable Software Market
Software & Services
Enterprise Resource Planning Market
Software & Services
Feedback Management Software Market
Software & Services
Asia-Pacific Saas-Based SCM Market
Software & Services
Exercise and Weight Loss Apps Market
Software & Services
Software Licensing Market
Software & Services
Software Publishers Market