
 Indonesia IT Services Market | 2026-2036
Indonesia IT Services Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia IT Services Market Insights
ISO 27001 certification is reorganizing competitive eligibility among Indonesia IT services vendors, pushing mid-tier firms toward security investments or partnership models. Telkomsigma leverages its nationwide data center footprint to dominate government and telecom contracts. IBM Indonesia sustains premium positioning through hybrid cloud advisory and mainframe modernization capabilities. Microsoft Indonesia anchors the productivity and platform layer, competing on Azure ecosystem penetration across enterprise accounts.
Indonesia IT services encompass the design, deployment, integration, and ongoing management of computing infrastructure, enterprise software, and network systems, typically governed by service level agreements specifying uptime thresholds between 99.5% and 99.99% and mean time to resolution under four hours for critical systems. These services enable organizations to outsource technology operations, reduce capital expenditure on hardware, and access specialized expertise in cybersecurity architecture or cloud migration. Managed services currently occupies the largest revenue pool as Indonesian enterprises seek to offload infrastructure monitoring and endpoint management. Cloud services represents the fastest-expanding segment, driven by Ministry of Communication and Informatics directives accelerating public sector digitalization. IT security commands premium pricing amid rising ransomware incidents targeting financial institutions and state-owned enterprises.
BIS-equivalent technical standards, Indonesia's Personal Data Protection Law, and Ministry of Communication and Informatics cybersecurity certifications collectively shape vendor qualification criteria and contract eligibility for public sector procurement. Compliance costs are filtering smaller providers from direct bidding on national infrastructure projects, consolidating opportunity around certified tier-one operators. Stakeholders must monitor enforcement intensity around data localization requirements and cross-border transfer restrictions as these rules determine architecture choices and partnership structures for multinational platform providers serving Indonesian enterprises.
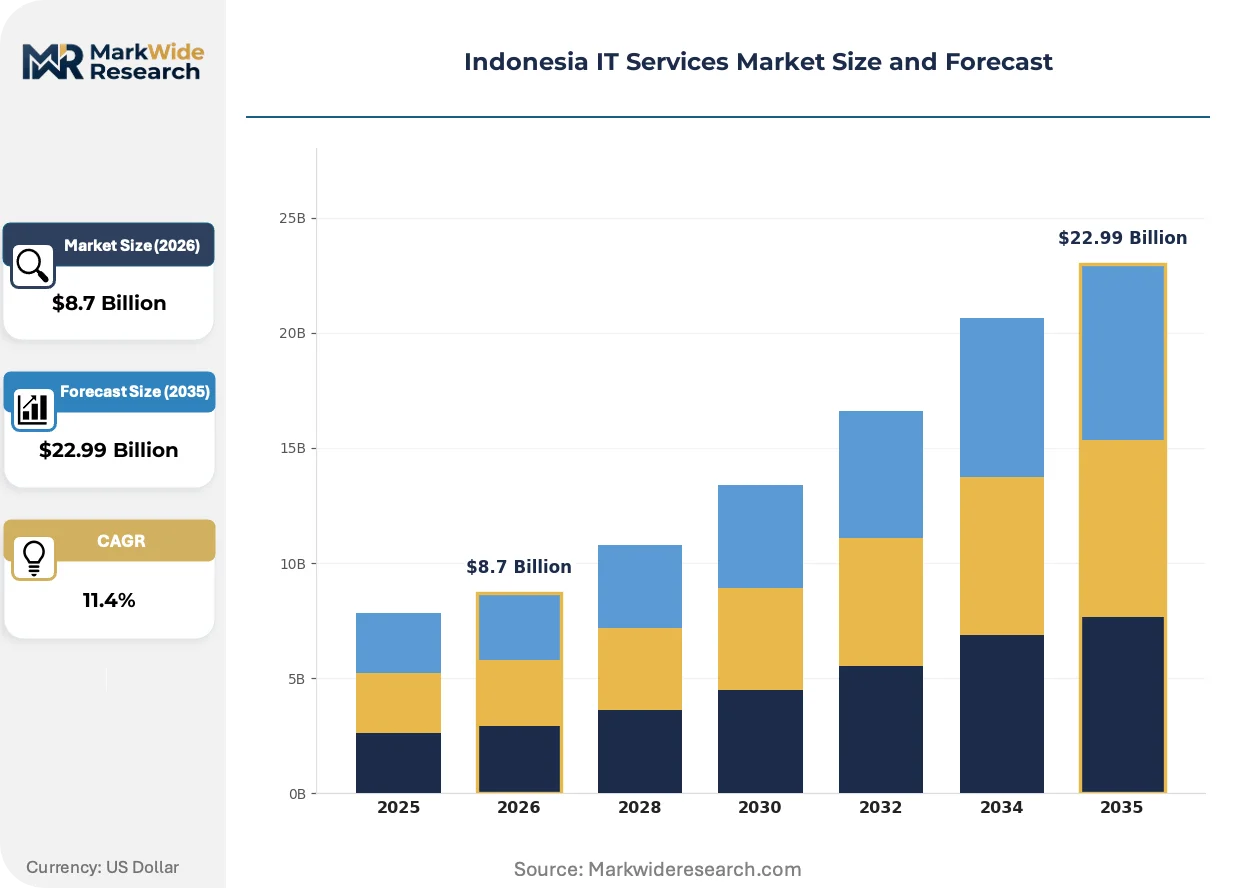
Market Dynamics
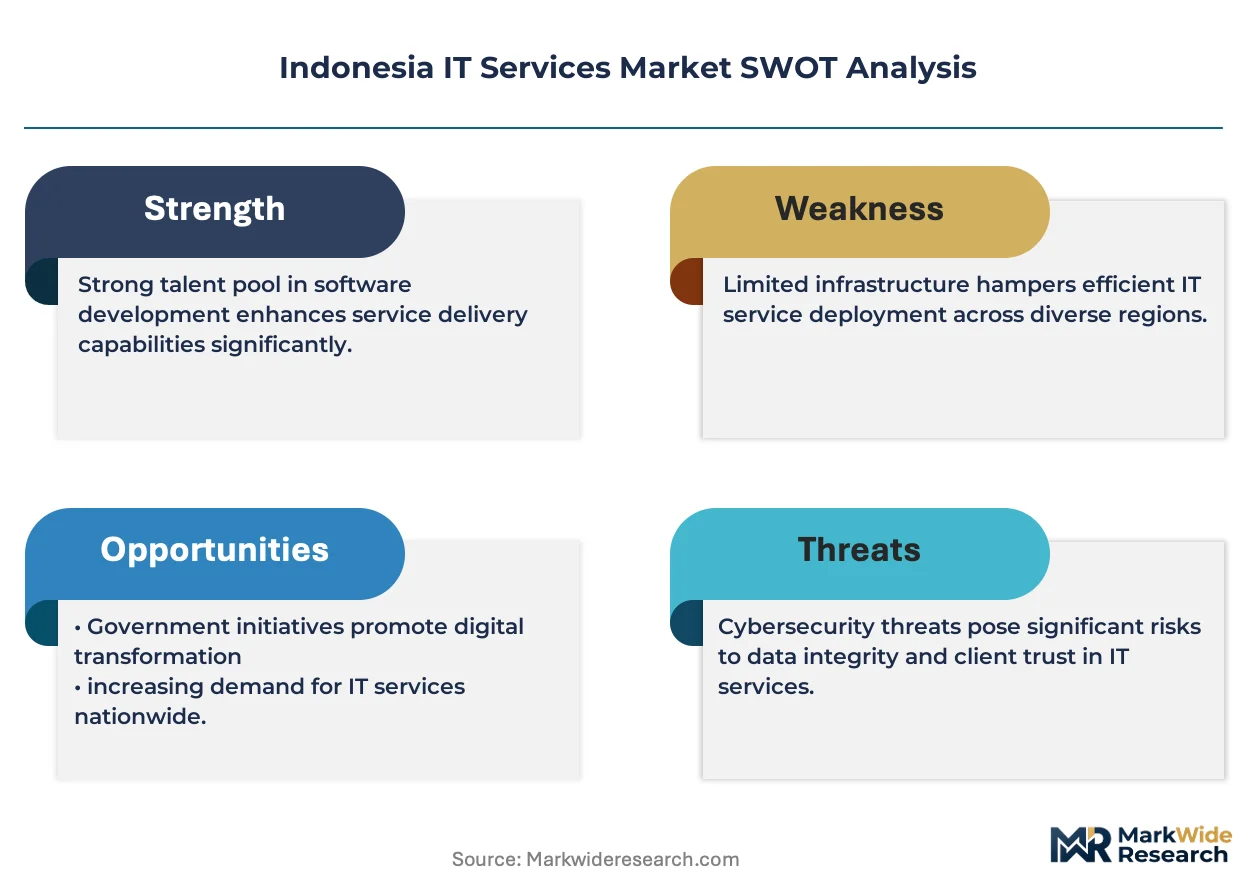
ISO 27001 certification requirements are compressing vendor eligibility for Indonesian government and financial sector contracts, forcing mid-tier providers into security investments or partnership models with certified tier-one operators.
Growth Catalysts
- Personal Data Protection Law enforcement:Compliance mandates from Indonesia's data protection authority are accelerating enterprise spending on managed security services and audit-ready infrastructure architectures.
- Banking digital infrastructure expansion:Indonesian financial institutions are scaling core banking modernization and payment gateway deployments to capture underbanked populations across Sumatra and Sulawesi.
- Hyperconverged infrastructure adoption:Enterprise data centers in Jakarta and Surabaya are consolidating compute-storage-network stacks to reduce rack space requirements and power consumption.
Market Restraints
- Certified talent scarcity:Indonesia produces insufficient cloud architects and cybersecurity specialists relative to enterprise demand, inflating salary costs for implementation partners.
- Data localization hardware requirements:Ministry of Communication and Informatics directives mandate domestic server placement, constraining architecture flexibility for multinational cloud providers.
- Cross-border transfer restrictions:Personal Data Protection Law provisions on international data flows complicate hybrid cloud designs for Indonesian subsidiaries of global enterprises.
Strategic Opportunities
- Eastern Indonesia penetration:Makassar and Denpasar metropolitan areas show rising demand for cloud connectivity and disaster recovery services with limited incumbent competition.
- State-owned enterprise digitization:Ministry of State-Owned Enterprises mandates are opening long-term managed services contracts across energy, transportation, and telecommunications sectors.
- Edge-to-cloud convergence:Manufacturing facilities in Batam and Cikarang are deploying 5G-enabled edge computing nodes integrated with centralized Azure and AWS environments.
Industry Challenges
- Multi-cloud integration complexity:Indonesian enterprises struggle to unify monitoring, cost governance, and security policies across heterogeneous Azure, Google Cloud, and on-premise VMware environments.
- ISO 27001 certification timelines:Mid-tier service providers face 12-18 month audit cycles that delay eligibility for national infrastructure tenders and BUMN procurement windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia IT Services Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cloud Services, Consulting, IT Security, Managed Services Customer Type: SMEs, Large Enterprises, Government, Startups Technology: Artificial Intelligence, Cloud Computing, IoT, Blockchain End User: Retail, Healthcare, Manufacturing, Education |
| Companies Covered | PT Telekomunikasi Indonesia Tbk (Telkomsigma), PT Multipolar Technology Tbk, PT Mitra Integrasi Informatika (MII), PT Metrodata Electronics Tbk, Accenture Indonesia, IBM Indonesia, Microsoft Indonesia, Tata Consultancy Services Indonesia, PT Lintasarta, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia IT Services Market Trends and Innovations
Containerization and Kubernetes orchestration are displacing traditional virtualization stacks across Indonesian enterprise data centers, compressing deployment cycles and enabling finer-grained resource allocation for variable workloads.
Microservices architecture is miniaturizing application deployment units for Indonesian e-commerce and fintech platforms. PT Tokopedia and Bank Mandiri technology teams are decomposing monolithic systems into containerized services. This shift is miniaturizing the minimum viable product cycle from quarters to weeks, forcing traditional system integrators to retool delivery methodologies or lose digital-native accounts.
Indonesia's Personal Data Protection Law implementing regulations are mandating breach notification timelines and data protection officer appointments for organizations above revenue thresholds. Financial services and healthcare providers face the steepest compliance curves. Large domestic banks are responding by establishing captive cybersecurity operations centers rather than relying solely on outsourced monitoring.
Consumption-based pricing models are displacing fixed-fee managed services contracts in Indonesian enterprise procurement. Infrastructure monitoring and endpoint management offerings now compete on per-device or per-terabyte metrics. This shift is most visible among Jakarta-headquartered conglomerates with seasonal revenue patterns that resist multi-year capacity commitments.
Indonesia IT Services Market Segmentation
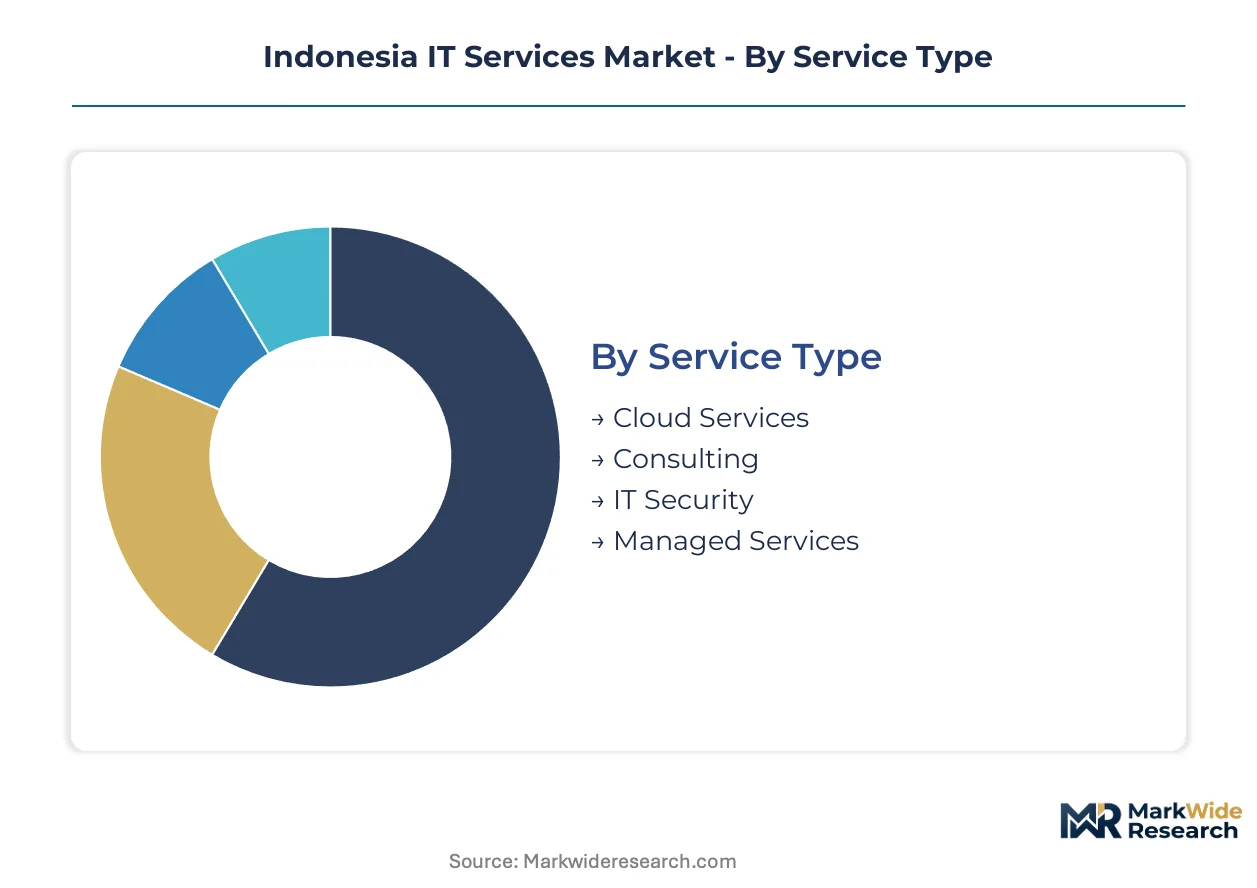
Indonesia IT Services Market segmentation reflects divergent compliance burdens across customer tiers and technology platforms. Ministry of Communication and Informatics certification requirements fragment vendor eligibility differently by service delivery model, customer scale, and infrastructure location.
Service Type:
ISO 27001 certification thresholds from Indonesia's Personal Data Protection Law reshape contract eligibility unevenly across delivery models.
- Managed Services:Infrastructure monitoring, endpoint management, and network operations delivered under multi-year service level agreements with uptime commitments between 99.5% and 99.99%. Banking and financial services institutions in Jakarta metropolitan corridor concentrate procurement here, driven by core banking modernization mandates and payment gateway scaling requirements. Established volume favors Managed Services; emerging adoption favors Cloud Services.
- Cloud Services:Public, private, and hybrid infrastructure provisioning with consumption-based billing models displacing capital-intensive data center builds. Demand clusters in Jakarta and Surabaya metropolitan corridors where Ministry of Communication and Informatics directives accelerate public sector digitalization and data localization compliance.
- IT Security:Managed detection and response, security operations center services, and compliance audit preparation for Personal Data Protection Law adherence. Financial institutions and state-owned enterprises drive premium pricing amid ransomware targeting.
- Consulting:Cloud migration advisory, enterprise architecture design, and cybersecurity strategy formulation for digital transformation programs. Project-based engagements dominate with shorter sales cycles than managed services contracts.
Procurement patterns favor long-term operational commitments in Managed Services; experimental architecture exploration favors Consulting engagements.
Customer Type:
Contract value thresholds and certification requirements stratify vendor engagement models across organizational scale.
- Large Enterprises:Jakarta-headquartered conglomerates and multinational subsidiaries with complex multi-cloud environments requiring unified governance across Azure, AWS, and on-premise VMware stacks. Seasonal revenue patterns accelerate shift toward consumption-based pricing over fixed-fee structures.
- Government:National infrastructure projects and BUMN procurement windows with mandatory ISO 27001 certification and domestic data center placement requirements. Ministry of State-Owned Enterprises digitization mandates open long-term managed services contracts across energy, transportation, and telecommunications sectors.
- SMEs:Mid-market organizations in Surabaya and Bandung seeking standardized cloud productivity suites and outsourced endpoint security without dedicated internal IT functions. Price sensitivity drives preference for bundled service tiers.
- Startups:Digital-native fintech and e-commerce ventures deploying microservices architectures on containerized platforms. PT Tokopedia and similar entities decompose monolithic systems into Kubernetes-orchestrated services with compressed deployment cycles.
Revenue concentration anchors in Large Enterprises; steepest expansion trajectory emerges in Government verticals.
Technology:
Architecture modernization cycles and skills scarcity reshape competitive positioning across technology platforms.
- Cloud Computing:Hyperconverged infrastructure consolidation and hybrid environment management dominating enterprise data center transformation in Jakarta and Surabaya. Containerization and Kubernetes orchestration displace traditional virtualization stacks.
- Artificial Intelligence:Machine learning operations, predictive analytics, and natural language processing applications for customer service automation and fraud detection in banking. Implementation constrained by certified data scientist scarcity.
- IoT:5G-enabled edge computing nodes in Batam and Cikarang manufacturing facilities integrated with centralized cloud environments. Edge-to-cloud convergence drives industrial automation and predictive maintenance deployments.
- Blockchain:Distributed ledger implementations for supply chain traceability and digital identity verification in trade finance. Regulatory uncertainty around cryptocurrency applications limits enterprise adoption scope.
Deployment maturity favors Cloud Computing; capability investment intensity favors Artificial Intelligence.
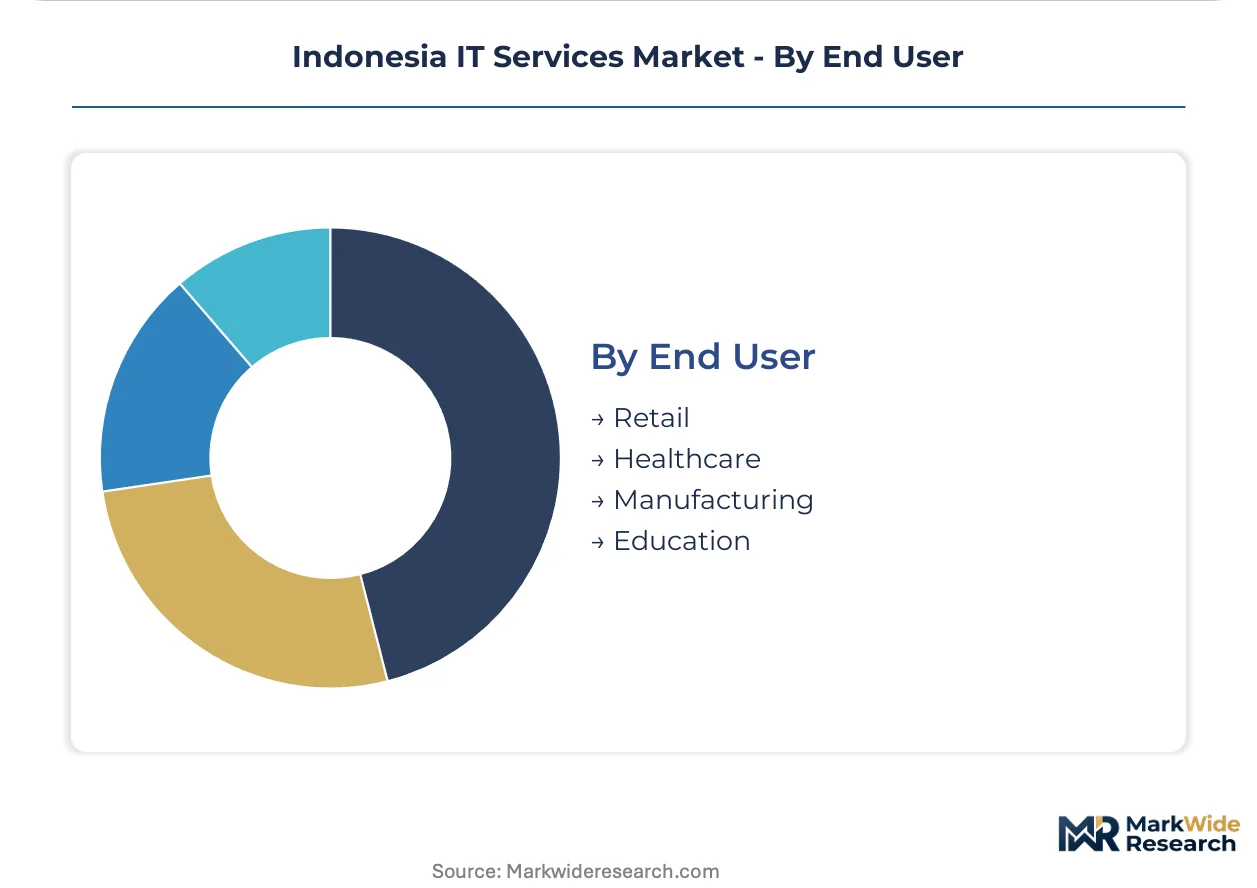
End User:
Sector-specific compliance curves and digital maturity stratify solution requirements and sales cycle duration.
- Banking and Financial Services:Core banking modernization, payment gateway scaling, and captive cybersecurity operations center establishment responding to Personal Data Protection Law breach notification mandates. Sumatra and Sulawesi expansion targets underbanked populations.
- Manufacturing:Industrial IoT deployment and edge computing integration for Batam and Cikarang production facilities. 5G infrastructure enables real-time quality monitoring and automated supply chain coordination.
- Healthcare:Electronic medical record systems and telemedicine platforms with stringent data protection requirements. Steepest compliance curves drive managed security services procurement.
- Retail:E-commerce platform scaling and omnichannel customer data integration for Jakarta-headquartered conglomerates. Microservices architecture adoption accelerates feature deployment velocity.
Security spending intensity concentrates in Banking and Financial Services; infrastructure greenfield opportunity concentrates in Manufacturing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesia's Personal Data Protection Law enforcement is redistributing IT services demand across the archipelago, with Ministry of Communication and Informatics directives accelerating public sector digitalization in secondary metropolitan corridors beyond Jakarta.
Java
Jakarta metropolitan corridor concentrates cloud services demand from banking institutions modernizing core systems. Ministry of State-Owned Enterprises digitization mandates open long-term managed services contracts across energy and telecommunications sectors. Surabaya anchors East Java's enterprise data center consolidation, with hyperconverged infrastructure deployments reducing power consumption for manufacturing conglomerates.
Sumatra
Medan and Palembang financial institutions are scaling payment gateway infrastructure to capture underbanked populations. Bank Indonesia's digital banking licensing framework drives compliance spending on audit-ready security architectures. Batam manufacturing facilities deploy 5G-enabled edge computing nodes integrated with centralized cloud environments for real-time quality monitoring.
Sulawesi
Makassar metropolitan area shows rising demand for cloud connectivity and disaster recovery services with limited incumbent competition. Regional government digitalization programs require ISO 27001-certified vendors for procurement eligibility. Nickel processing and agribusiness operations in Morowali and South Sulawesi drive industrial IoT adoption for supply chain coordination.
Bali and Nusa Tenggara
Denpasar's tourism and creative economy sectors accelerate e-commerce platform scaling and omnichannel customer data integration. Microservices architecture adoption compresses feature deployment cycles for digital-native hospitality ventures. Lombok and Labuan Bajo emerging as secondary data center locations serving disaster recovery requirements for Jakarta-headquartered enterprises.
Kalimantan
Balikpapan and Samarinda energy sector operations drive demand for predictive maintenance platforms and industrial automation systems. East Kalimantan provincial government cloud migration mandates create procurement opportunities for certified service providers. Mining logistics and palm oil processing facilities require edge-to-cloud convergence for automated supply chain management.
Indonesia IT Services Market Competitive Landscape
Listed leaders compete with private specialists across certification eligibility and data center footprint dimensions. Telkomsigma leverages its nationwide infrastructure presence to dominate government and telecom contracts, while multinational platform providers anchor the premium advisory tier. Three archetypes define competitive positioning: state-affiliated operators with domestic data center assets, global systems integrators with hybrid cloud capabilities, and mid-tier specialists pursuing partnership models. Consolidation pressures favor M&A activity among uncertified mid-tier providers and strategic alliances between local operators and multinational cloud platforms.
Within the state-affiliated infrastructure tier, PT Telekomunikasi Indonesia Tbk (Telkomsigma) exemplifies nationwide coverage advantages, while PT Multipolar Technology Tbk occupies a position among diversified technology holding structures. IBM Indonesia and Microsoft Indonesia anchor the multinational advisory and platform layer, representing premium positioning through hybrid cloud ecosystems and enterprise productivity penetration. These three entities illustrate the bifurcation between domestic infrastructure control and global technology platform access.
| Leading Market Players |
|---|
| PT Telekomunikasi Indonesia Tbk (Telkomsigma) |
| PT Multipolar Technology Tbk |
| PT Mitra Integrasi Informatika (MII) |
| PT Metrodata Electronics Tbk |
| Accenture Indonesia |
| IBM Indonesia |
| Microsoft Indonesia |
| Tata Consultancy Services Indonesia |
| PT Lintasarta |
| Others |
Pricing and Supply Chain Analysis
Containerization displacing traditional virtualization stacks simultaneously compresses deployment timelines and redistributes vendor pricing power toward certified Kubernetes specialists, while Ministry of Communication and Informatics data localization mandates reshape infrastructure procurement geography toward domestic data center operators.
Pricing Analysis
Certification level creates the primary spread between ISO 27001-certified tier-one operators and uncertified mid-tier competitors. Consumption-based billing models displace fixed-fee structures across managed services contracts, with Jakarta-headquartered conglomerates driving per-device and per-terabyte metrics. Pricing pressure stems from certified talent scarcity inflating implementation partner salary costs. SMEs exhibit highest price sensitivity, while government and BUMN procurement windows show lowest elasticity due to compliance mandates.
Supply Chain Analysis
Hardware procurement lead times for domestic server placement extend vendor qualification cycles under Ministry of Communication and Informatics directives. Supply concentrates in China, Taiwan, and South Korea for semiconductor components and networking equipment. Raw material dependencies span server-grade silicon, storage arrays, and fiber-optic infrastructure. Single-source vulnerability runs through specialized cybersecurity hardware vendors. Distribution runs through certified systems integrators with direct government procurement access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ISO 27001 certification fragmentation creates defendable niche positions for specialists, as Personal Data Protection Law enforcement stratifies contract eligibility and compresses mid-tier vendor participation windows.
For Market Incumbents: Consolidate certification advantages through captive cybersecurity operations center investments and exclusive BUMN procurement channel control. Acquire uncertified mid-tier providers before 12-18 month audit cycles close national infrastructure tender windows. Threat substitution emerges from global hyperscalers establishing domestic data center footprints.
For New Entrants and Emerging Players: Anchor in Makassar and Denpasar metropolitan corridors where cloud connectivity demand outpaces incumbent coverage. Target disaster recovery and edge-to-cloud convergence for manufacturing facilities in Batam and Cikarang. Go-to-market angle emphasizes rapid ISO 27001 certification completion through partnership with established audit firms.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors certified infrastructure operators with government contract pipelines. Long-term viability hinges on data localization compliance depth rather than pure technology capability. Acquisition target archetype: mid-tier providers with 60-80% certification completion and existing BUMN relationships. Signal to watch is enforcement intensity around cross-border transfer restrictions.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 27001 Certification Acceleration | Compresses vendor eligibility timelines for Ministry of State-Owned Enterprises procurement windows. |
| Domestic Data Center Expansion | Aligns infrastructure footprint with Ministry of Communication and Informatics localization mandates. |
| Captive SOC Establishment | Addresses Personal Data Protection Law breach notification requirements for financial institutions. |
| Edge-to-Cloud Integration Partnership | Captures 5G-enabled manufacturing automation demand in Batam and Cikarang industrial zones. |
| Microservices Delivery Retooling | Responds to PT Tokopedia-style compressed deployment cycles forcing methodology transformation. |
Research Methodology
Operator-level perspectives from CTOs, IT procurement officers, platform engineers, and integration specialists anchored the qualitative base. Primary interview data combined with secondary validation from SEC filings, hyperscaler capex disclosures, and Ministry of Communication and Informatics regulatory circulars. Bottom-up service provider revenue triangulation against top-down enterprise IT spending estimates established market sizing boundaries.
Sensitivity analysis tested forecast robustness across certification enforcement intensity scenarios and public sector digitalization acceleration assumptions. Segmentation dimensions modeled include service delivery model, customer scale tier, technology platform, and infrastructure location. CAGRs derived from weighted average of historical trajectory and policy-driven step-change assumptions. Cloud adoption curves and cybersecurity spending elasticity served as industry-specific forecast inputs across the projection horizon.
Decision-makers should treat outputs as directional under sustained Personal Data Protection Law enforcement and stable Ministry of State-Owned Enterprises digitization mandates; material regulatory deviation or hyperscaler market entry would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Federal Government Software Market
Software & Services
Collaborative Authoring Tools Market
Software & Services
Mainframe Software Market
Software & Services
HR Tech Market
Software & Services
Staffing Agency Software Market
Software & Services
Global Continuous Testing Market
Software & Services
Automotive Operating Systems Market
Software & Services
Europe Human Resource (HR) Technology Market
Software & Services
Global Electronic Data Capture Software Market
Software & Services
Global Online Survey Software Market
Software & Services
Global Data Extraction Software Market
Software & Services
Chatbot Builder Software Market
Software & Services
Supplier Quality Management Applications Market
Software & Services
Construction Simulation Software Market
Software & Services
Global Driving School Software Market
Software & Services
Audit Management Software Market