
 Global Landscape Software Market | 2026-2036
Global Landscape Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Landscape Software Market Foresight
Cloud-native architecture is rewriting how landscape software delivers value, shifting computation from local workstations to distributed GPU clusters that render photorealistic terrain models in seconds. Autodesk leverages its construction technology ecosystem to extend design workflows into adjacent civil engineering markets. Trimble anchors its position through precision GNSS hardware integration that tightens field-to-office data loops. Vectorworks competes by sustaining deep parametric modeling capabilities that appeal to technically sophisticated landscape architects.
Landscape software comprises digital tools for terrain modeling, planting specification, hardscape layout, and irrigation hydraulics, typically operating through CAD-compatible geometry engines with plant databases containing growth parameters, hardiness zones, and maintenance schedules. The primary commercial purpose centers on reducing design iteration cycles while ensuring constructability and long-term ecological performance. Design software occupies the largest revenue pool as legacy AutoCAD users migrate to specialized vertical applications, while cloud-based deployment represents the fastest-expanding segment as municipal IT departments abandon on-premise server maintenance. Maintenance software trails in adoption but carries above-average margins due to recurring subscription attach rates from commercial landscaping fleets.
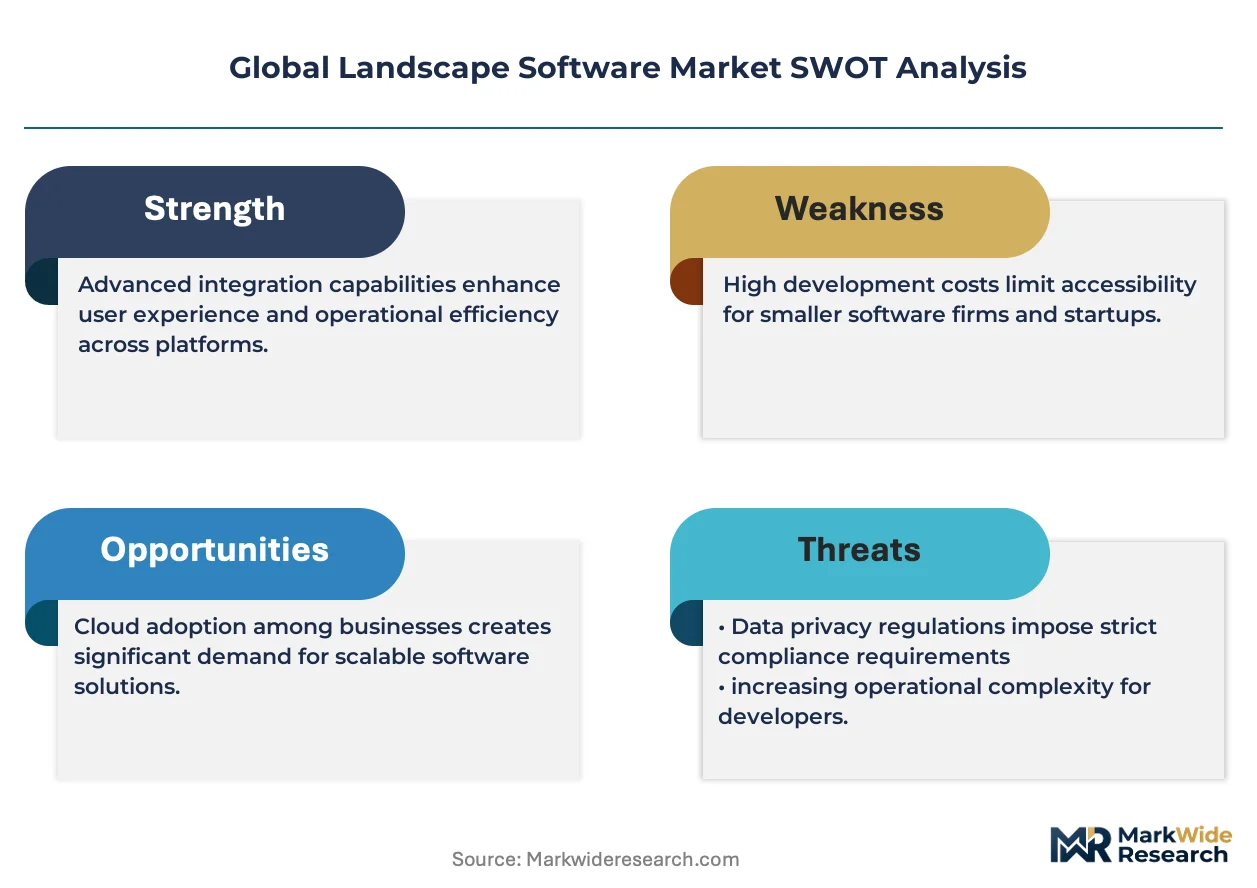
FDA guidelines on software as a medical device do not directly govern this sector, though EPA stormwater regulations in the United States shape hydrological modeling requirements that irrigation software must satisfy. The EU Green Deal's restoration targets and REACH chemical compliance for treated lumber specifications create dual compliance layers for European vendors. EMA plays no direct role, yet WHO urban health guidelines indirectly influence green space planning standards that software tools encode. Stakeholders must monitor whether emerging building performance standards in major economies will mandate digital twin integration, forcing landscape platforms to interoperate with broader BIM ecosystems or risk displacement by generalized construction software suites.
Market Dynamics
Cloud-native rendering architectures are collapsing the traditional workstation-to-server hierarchy in landscape software, redistributing computational loads across distributed GPU clusters and forcing vendors to rebuild licensing models around concurrent cloud seats rather than perpetual desktop installations.
Growth Catalysts
- EU Green Deal biodiversity mandates:European restoration targets require digital compliance tracking for urban green infrastructure, pulling municipal authorities toward integrated design platforms.
- Precision GNSS hardware convergence:Field-to-office data loops tighten as survey-grade positioning integrates directly with terrain modeling workflows, accelerating adoption among commercial landscaping fleets.
- Federal water efficiency standards:EPA irrigation regulations in drought-prone US states mandate hydraulic modeling upgrades, creating replacement demand for legacy systems.
Market Restraints
- Cloud infrastructure cost volatility:GPU cluster pricing fluctuations squeeze vendor margins on rendering-intensive subscription tiers, particularly affecting photorealistic terrain visualization features.
- Parametric modeling skill scarcity:Deep technical proficiency in computational landscape architecture concentrates in Western Europe and select US coastal metros, limiting deployment velocity elsewhere.
- Interoperability friction with BIM ecosystems:ISO 19650 compliance gaps force costly custom API development for landscape platforms seeking construction workflow integration.
Strategic Opportunities
- Australia municipal cloud procurement:State-level green infrastructure programs in Victoria and New South Wales are abandoning on-premise servers, creating first-mover advantages for cloud-native vendors.
- Digital twin convergence with IoT sensors:Real-time soil moisture and canopy health monitoring is collapsing maintenance software into design platforms, opening recurring revenue streams.
- REACH chemical compliance modules:Treated lumber specification tracking creates attachable subscription features for European vendors serving commercial hardscape contractors.
Industry Challenges
- Computational landscape architect talent pipeline:Universities produce insufficient graduates fluent in both ecological science and parametric modeling, forcing vendors to internalize training costs.
- Legacy AutoCAD workflow entrenchment:Migration friction from decades-old DWG-based processes slows specialized vertical adoption among established design practices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Landscape Software Market |
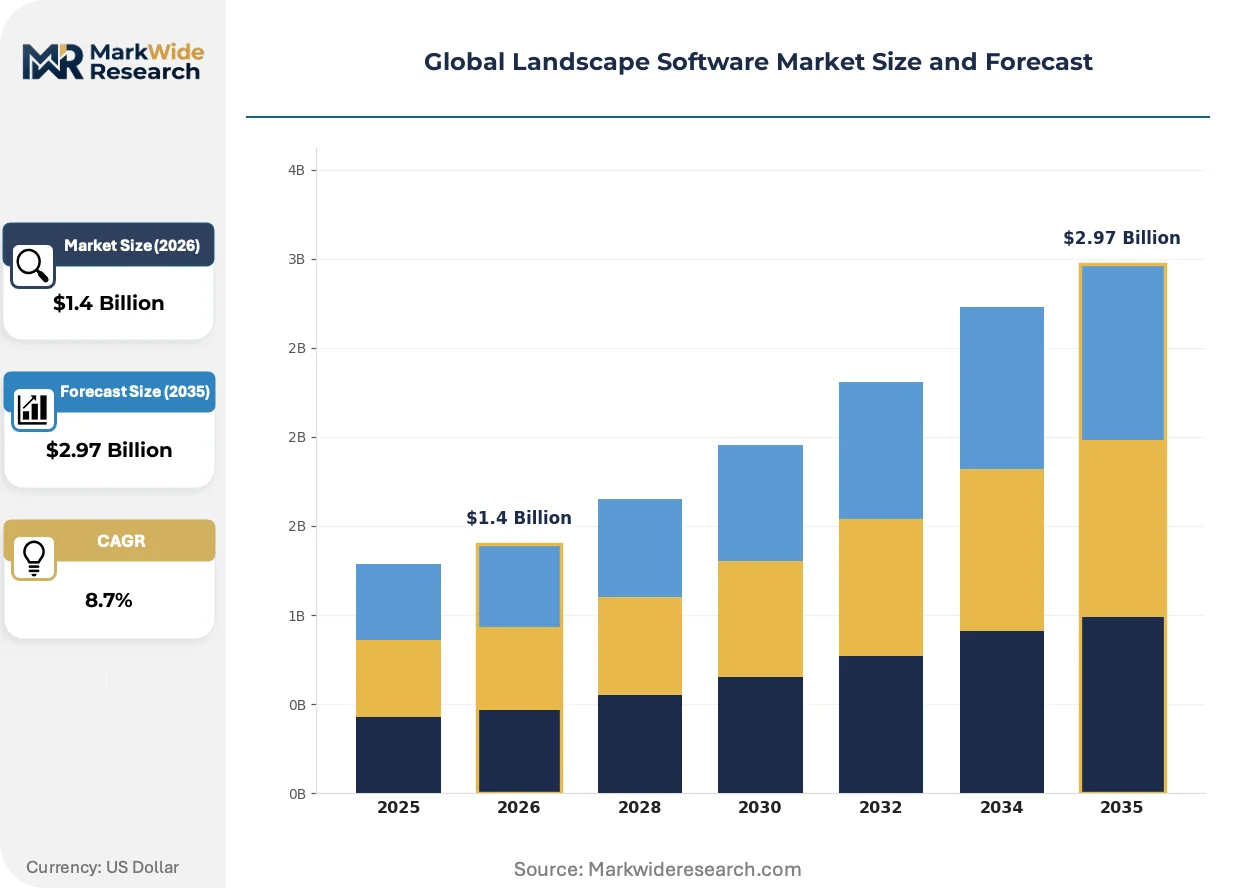
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Design Software, Visualization Software, Maintenance Software, Irrigation Software, Project Management Software Deployment: Cloud-Based, On-Premise, Hybrid, SaaS, Web-Based Application: Urban Planning, Sports Complex Design, Residential Gardening, Commercial Landscaping, Environmental Restoration End User: Landscape Architects, Garden Designers, Municipal Authorities, Property Developers, Environmental Consultants |
| Companies Covered | Autodesk, Land F/X, RealGreen Systems, Include Software, Vectorworks, DynaSCAPE Software, Trimble, ProLandscape, Westrom Software, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Landscape Software Market Shifts & Advancements
Generative design algorithms and real-time environmental simulation are merging into unified platforms, compressing the traditional sequence of concept modeling, ecological validation, and construction documentation into iterative loops that execute in hours rather than weeks.
Neural radiance fields (NeRF) for terrain capture are collapsing the photogrammetry-to-model pipeline from multi-day manual processing to near-instant mesh generation. Municipal planning departments in Germany and Australia now deploy drone-captured NeRF inputs for existing conditions modeling. The structural consequence is collapsing specialized survey vendor relationships as design firms internalize rapid site documentation.
REACH chemical compliance for treated lumber specifications is forcing hardscape layout modules to embed automated material substitution alerts. European vendors must maintain real-time databases of restricted substance thresholds across member state variations. Commercial landscaping fleets in France and Germany face operational disruption without integrated compliance tracking, accelerating platform consolidation.
Subscription unbundling is fragmenting the traditional design-to-maintenance software stack. Australian municipal procurement now separates initial design licenses from ongoing irrigation optimization modules, enabling competitive displacement at contract renewal points. German landscape architecture practices increasingly lease terrain modeling capabilities seasonally rather than maintaining perpetual seats, compressing vendor revenue recognition cycles.
Global Landscape Software Market Segmentation
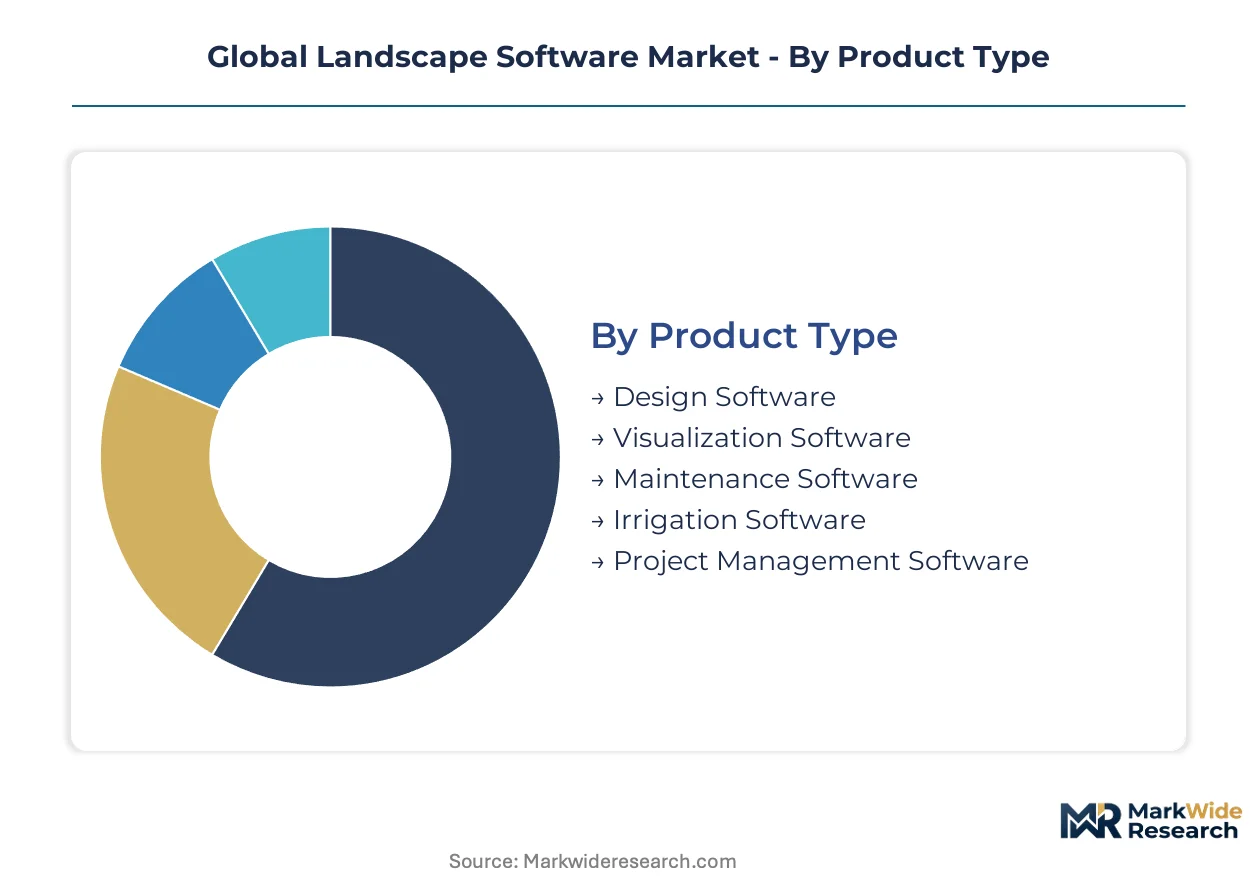
Landscape software vendors engineer pricing tiers around post-deployment service intensity. Design platforms demand intensive onboarding and template customization. Maintenance modules generate recurring telemetry support. Visualization suites require GPU cluster provisioning that scales with rendering load.
Product Type:
After-sales service intensity varies sharply across product categories, with maintenance and irrigation software requiring continuous sensor calibration support while design tools front-load training costs.
- Design Software:Core terrain modeling and planting specification tools built on CAD-compatible geometry engines. Demand concentrates among landscape architects in Germany and Australia where municipal green infrastructure procurement mandates digital compliance documentation. EU Green Deal biodiversity tracking requirements pull authorities toward integrated platforms that collapse design iteration cycles.
- Visualization Software:Photorealistic rendering engines leveraging distributed GPU clusters for real-time terrain simulation. Commercial landscaping fleets in drought-prone US states adopt these tools for client presentation workflows, though GPU pricing volatility squeezes vendor margins on subscription tiers.
- Maintenance Software:Recurring subscription models attach to commercial landscaping fleets through IoT sensor integration for soil moisture and canopy health monitoring. Margin profiles exceed design tools due to persistent telemetry support requirements.
- Irrigation Software:Hydraulic modeling tools satisfying EPA water efficiency standards across California, Arizona, and Texas. Replacement demand accelerates as legacy systems fail to meet federal compliance thresholds.
- Project Management Software:Coordination platforms linking field crews with design offices through GNSS-integrated workflows. Adoption lags among smaller practices lacking IT infrastructure.
By volume, Design Software leads. By growth pace, Maintenance Software is ahead.
Deployment:
Cost tier stratification separates enterprise-grade cloud-native implementations from budget-constrained on-premise installations among smaller design practices.
- Cloud-Based:Distributed GPU cluster architectures enabling photorealistic rendering without local workstation investment. Municipal authorities in Victoria and New South Wales abandon on-premise servers under state-level green infrastructure programs, creating first-mover advantages for cloud-native vendors.
- On-Premise:Perpetual licensing models retaining computation on local workstations. Legacy AutoCAD workflow entrenchment slows migration among established German landscape architecture practices with decades-old DWG-based processes.
- Hybrid:Split architectures retaining sensitive design files locally while pushing rendering workloads to cloud clusters. Appeals to mid-size practices balancing security concerns with computational demands.
- SaaS:Subscription licensing with automatic feature updates and API maintenance. Seasonal leasing patterns emerge in Germany where practices rent terrain modeling capabilities rather than maintaining perpetual seats.
- Web-Based:Browser-accessible lightweight tools for field crews and client review. Limited parametric modeling depth constrains adoption among technically sophisticated users.
By revenue concentration, Cloud-Based deployments dominate. By expansion trajectory, SaaS models are climbing the fastest.
Application:
Application segmentation tracks customer maturity, with environmental restoration demanding deep ecological science integration while residential gardening serves price-sensitive amateurs.
- Urban Planning:Large-scale green infrastructure design tools encoding WHO urban health guidelines for green space allocation. EU Green Deal restoration targets mandate digital compliance tracking across German municipal authorities.
- Sports Complex Design:Specialized turf management and drainage modeling for stadium and golf course applications. Precision GNSS hardware integration tightens field-to-office data loops for commercial landscaping fleets.
- Residential Gardening:Consumer-grade tools with simplified plant databases and automated maintenance schedules. Price sensitivity limits vendor margins despite large addressable user bases.
- Commercial Landscaping:Fleet management and job costing modules for multi-crew operations. REACH chemical compliance for treated lumber specifications forces hardscape layout modules to embed automated material substitution alerts in France and Germany.
- Environmental Restoration:Ecological validation tools simulating long-term habitat performance. Computational landscape architect talent scarcity concentrates deployment in Western Europe and select US coastal metros.
By installed base, Commercial Landscaping leads. By technical sophistication requirements, Environmental Restoration sets the standard.
End User:
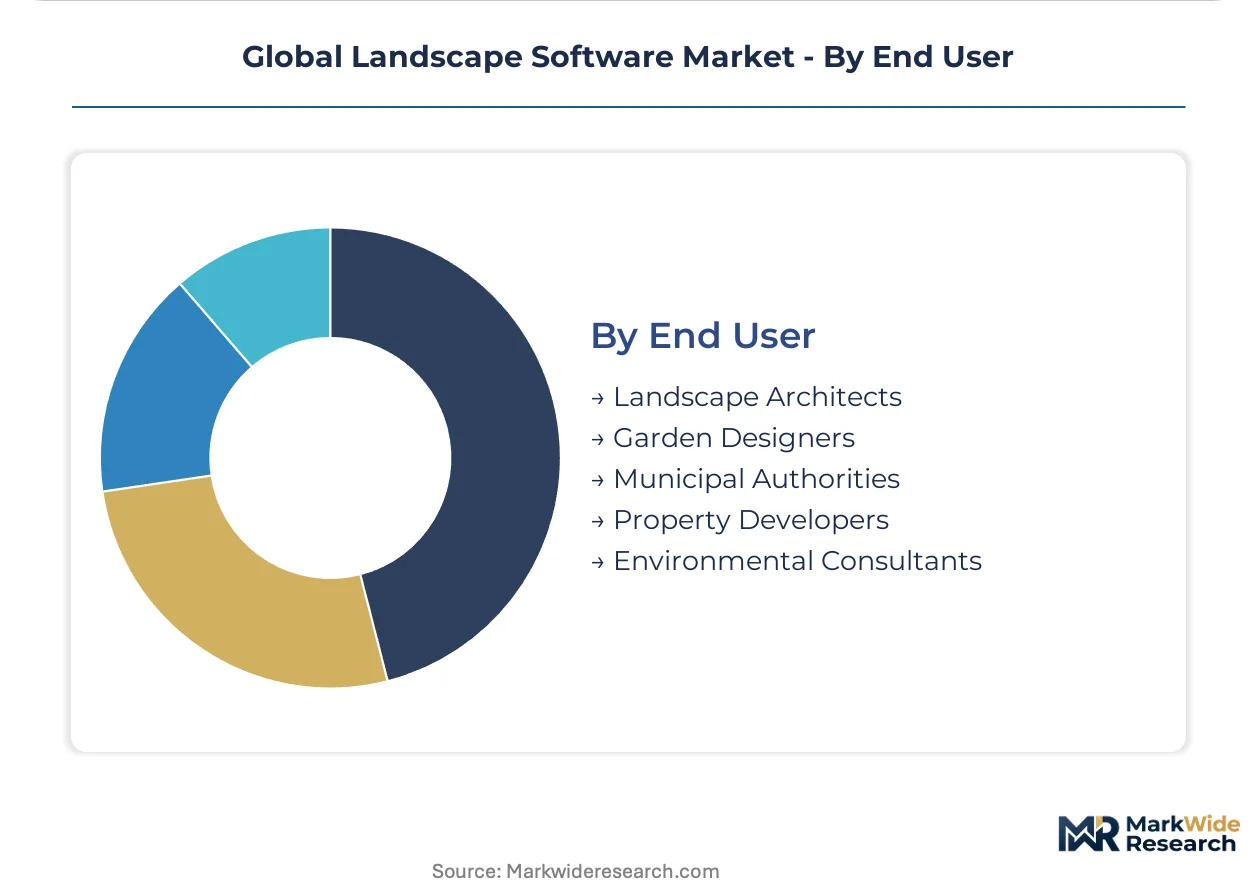
Customer type segmentation reveals procurement authority concentration, with municipal authorities driving standardization while garden designers fragment across individual preferences.
- Landscape Architects:Technically sophisticated users demanding deep parametric modeling capabilities. Vectorworks sustains appeal among this segment through computational design proficiency.
- Garden Designers:Smaller-scale practitioners prioritizing visualization speed over ecological simulation. Subscription unbundling in Australia enables competitive displacement at contract renewal points.
- Municipal Authorities:Standardized procurement driving cloud migration across Germany and Australia. EU Green Deal biodiversity mandates accelerate software adoption for environmental compliance tracking.
- Property Developers:BIM interoperability requirements force costly custom API development for landscape platforms seeking construction workflow integration.
- Environmental Consultants:Specialized users requiring hydrological modeling satisfying EPA stormwater regulations. ISO 19650 compliance gaps create friction with generalized construction software suites.
By procurement volume, Municipal Authorities lead. By platform loyalty intensity, Landscape Architects are deepest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Municipal procurement authorities and commercial landscaping fleets concentrate demand across five national markets, with regulatory compliance mandates and green infrastructure investment cycles shaping software adoption velocity.
United States
EPA water efficiency standards drive irrigation software replacement across California, Arizona, and Texas. Federal stormwater regulations shape hydrological modeling requirements that landscape platforms must satisfy. Commercial landscaping fleets in the Pacific Southwest deploy precision GNSS hardware for field-to-office data synchronization.
Germany
EU Green Deal biodiversity restoration mandates accelerate municipal procurement of cloud-based design tools for urban green infrastructure. REACH chemical compliance for treated lumber specifications forces hardscape modules to embed automated material substitution alerts. Landscape architecture practices in Berlin and Munich increasingly lease terrain modeling capabilities seasonally rather than maintaining perpetual licenses.
Australia
State-level green infrastructure programs in Victoria and New South Wales abandon on-premise servers, creating first-mover advantages for cloud-native vendors. Subscription unbundling fragments the traditional design-to-maintenance software stack, enabling competitive displacement at contract renewal points. Municipal planning departments in Sydney and Melbourne deploy drone-captured neural radiance fields for existing conditions modeling.
United Kingdom
ISO 19650 compliance gaps force costly custom API development for landscape platforms seeking construction workflow integration. BIM interoperability requirements from property developers pressure specialized vendors toward generalized construction software ecosystems. London-based landscape architects demand deep parametric modeling capabilities for technically sophisticated ecological restoration projects.
Japan
METI urban health guidelines indirectly influence green space planning standards that software tools encode. Precision GNSS hardware convergence tightens survey-grade positioning integration with terrain modeling workflows. Commercial landscaping operations in the Tokyo-Osaka corridor adopt maintenance software with IoT sensor integration for soil moisture and canopy health monitoring.
Global Landscape Software Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a market structure that fragments between construction-technology conglomerates and dedicated landscape architecture platforms. Autodesk leverages its construction technology ecosystem to extend design workflows into adjacent civil engineering markets. Trimble anchors its position through precision GNSS hardware integration that tightens field-to-office data loops. Vectorworks competes by sustaining deep parametric modeling capabilities that appeal to technically sophisticated landscape architects. Strategic moves concentrate on cloud-native architecture migration and API development for BIM ecosystem interoperability.
Among North American software developers, Autodesk and Trimble occupy positions as construction-technology conglomerates with landscape software modules embedded within broader civil engineering ecosystems. Vectorworks exemplifies the specialized vertical approach, representing the dedicated landscape architecture platform archetype with computational design proficiency. Land F/X sits within the irrigation-specialist tier, anchoring hydraulic modeling capabilities for drought-prone municipal markets. These three patterns—conglomerate-embedded, specialized vertical, and application-specific—structure competitive positioning across procurement segments.
| Leading Market Players |
|---|
| Autodesk |
| Land F/X |
| RealGreen Systems |
| Include Software |
| Vectorworks |
| DynaSCAPE Software |
| Trimble |
| ProLandscape |
| Westrom Software |
| Others |
Supply & Pricing Matrix
GPU cluster provisioning concentrates in hyperscaler facilities across the United States, Ireland, and Singapore, anchoring margin pools in rendering-intensive subscription tiers where photorealistic terrain visualization commands premium positioning. This upstream compute concentration forces landscape software vendors to absorb infrastructure cost volatility or pass through to municipal buyers with limited procurement flexibility.
Pricing Analysis
Cost-plus contracts with GPU cluster indexation dominate enterprise SaaS tiers, particularly for photorealistic rendering modules serving Australian municipal authorities. Three-tier pricing structure across premium, standard, and economy levels separates cloud-native concurrent seats from hybrid deployments and legacy perpetual licenses. Pricing pressure stems from hyperscaler compute pricing volatility squeezing vendor margins on visualization features. Municipal authorities exhibit lowest price sensitivity due to EU Green Deal compliance mandates, while residential gardening applications face acute cost consciousness limiting monetization depth.
Supply Chain Analysis
Export-control regimes restricting advanced GPU and GNSS chipset flows constrain supply chain configuration for precision hardware-integrated software bundles. Manufacturing concentration centers on Taiwan for GPU silicon, South Korea for memory components, and Germany for survey-grade positioning equipment. Raw material dependencies span rare earth elements for permanent magnets in GNSS receivers, high-purity silicon for chip fabrication, and lithium-ion cells for field sensor power systems. Single-source vulnerability in advanced GPU allocation creates procurement risk for rendering-intensive platforms. Distribution runs through direct enterprise sales teams targeting municipal procurement authorities and commercial landscaping fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Landscape Software Market sits in early-cycle expansion as cloud-native architecture penetration remains below saturation across municipal procurement segments, with EU Green Deal biodiversity mandates accelerating replacement demand for legacy on-premise systems.
For Market Incumbents: Insulate recurring revenue streams by deepening API development for ISO 19650 BIM interoperability, neutralizing displacement risk from generalized construction software suites. Prioritize backward integration into precision GNSS hardware to tighten field-to-office data loops and raise switching costs for commercial landscaping fleets. Cloud-native challengers and parametric modeling skill scarcity represent primary threat vectors requiring defensive capability investment.
For New Entrants and Emerging Players: Build out seasonal leasing models for terrain modeling capabilities targeting German landscape architecture practices seeking alternatives to perpetual license maintenance. White-space concentration sits in maintenance software IoT sensor integration for soil moisture and canopy health monitoring, where recurring telemetry support generates above-average margins. Go-to-market execution should anchor on drone-captured NeRF site documentation workflows displacing traditional survey vendor relationships.
For Investors and Strategic Acquirers: Capital is best deployed toward specialized vertical platforms with deep parametric modeling capabilities and established landscape architect user loyalty, as these assets command durable positioning against conglomerate-embedded competitors. Long-term viability over the next decade hinges on digital twin convergence readiness and REACH chemical compliance module development. The signal to watch is municipal procurement standardization accelerating cloud migration velocity in Victoria and New South Wales.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Architecture Migration | Distributed GPU clusters enable photorealistic rendering without local workstation investment for municipal authorities. |
| Precision GNSS Hardware Integration | Survey-grade positioning tightens field-to-office data loops for commercial landscaping fleet synchronization. |
| API Development for BIM Interoperability | ISO 19650 compliance gaps force custom integration investments to access construction workflow ecosystems. |
| IoT Sensor Platform Convergence | Real-time soil moisture monitoring collapses maintenance software into design platforms for recurring revenue. |
| REACH Compliance Module Expansion | Automated treated lumber substitution alerts address operational disruption risk for European hardscape contractors. |
Research Methodology
Operator-level perspectives from municipal IT procurement officers, landscape architecture practice principals, commercial landscaping fleet managers, and precision GNSS hardware engineers anchored the qualitative base. Primary interview findings combined with secondary validation from SEC filings of construction technology conglomerates, hyperscaler capex disclosures, EU Green Deal implementation reports, and EPA stormwater regulation guidance documents. Bottom-up segmentation modeling and top-down market sizing triangulated volume and value estimates across deployment modes, product categories, and end-user archetypes.
Scenario-bracketing framed demand projections across the analysis window, with analytical outputs reflecting probabilistic weighting of regulatory acceleration, cloud procurement standardization, and parametric modeling talent pipeline constraints. Segmentation dimensions modeled encompassed deployment architecture, organization size tier, vertical application, integration complexity with BIM ecosystems, and regional adoption pattern. CAGRs derived from fitted growth curves incorporating replacement cycle dynamics for legacy AutoCAD workflows and net-new adoption curves for maintenance software IoT convergence.
The forecast holds incumbent behavior within observed patterns; aggressive moves by hyperscalers into vertical SaaS or construction-technology conglomerates into specialized landscape modules would shift outcomes. Forecasts reflect assumptions of continued EU Green Deal implementation trajectory, stable hyperscaler GPU pricing regimes, and gradual BIM interoperability standardization. Material shifts in municipal procurement centralization, export control expansion for positioning technologies, or breakthrough generative design automation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
EDA Tools Market
Software & Services
Global Board Management Software Market
Software & Services
Europe Digital Signage Software Market
Software & Services
Global Healthcare Contract Management Software Market
Software & Services
Augmented Reality Software Development Kit Market
Software & Services
Global Online Expense Management Software Market
Software & Services
Self-Storage Software Market
Software & Services
United States Human Resource (HR) Technology Market
Software & Services
Construction Simulation Software Market
Software & Services
Global Retail Execution Software Market
Software & Services
Talent Acquisition Software Market
Software & Services
Enterprise Resource Planning (ERP) Software Market
Software & Services
Europe Feedback Management Software Market
Software & Services
Automotive Dealership Software Market
Software & Services
Global Demand Planning Software Market
Software & Services
Employee Wellness Software Market