
 Home Design Software Market | 2026-2036
Home Design Software Market Size, Share, and Industry Trends Forecast 2026-2036
Home Design Software Market Foresight
The EU Green Deal is repositioning building energy standards across member states, forcing architects and contractors to adopt simulation-capable design tools. Chief Architect leverages parametric modeling to sustain its foothold among professional remodelers. Autodesk Revit dominates BIM-compliant workflows for commercial-to-residential crossovers. SketchUp anchors the prosumer segment with intuitive 3D geometry tools that lower training barriers.
Home design software comprises digital platforms that generate spatial models, material specifications, and construction documentation from user inputs, typically rendering outputs at 1:1 scale fidelity with photorealistic texture mapping. These tools serve residential planning, renovation bidding, and permit submission by translating conceptual layouts into build-ready instructions. Cloud-based deployment leads technology adoption by removing hardware constraints and enabling real-time client collaboration. 3D Modeling captures the largest product type share as homeowners and contractors demand immersive visualization before committing capital. Virtual Reality remains the fastest-expanding technology segment, with headset compatibility turning remote walkthroughs into standard pre-construction milestones.
REACH compliance in Europe and California's Title 24 energy codes in the United States both mandate material transparency and thermal performance documentation that design software now automates. The EPA's ENERGY STAR certification pathways and the EU's CE marking for construction products create dual compliance layers that platform developers must embed natively. Stakeholders should monitor which vendors integrate regulatory databases directly into specification workflows, as this capability will separate compliant-first platforms from retrofit laggards.
Market Dynamics
Cloud-based deployment is compressing hardware barriers and democratizing access to professional-grade visualization tools, forcing incumbent vendors to rebundle collaboration features or surrender market position to agile SaaS entrants.
Growth Catalysts
- EU Green Deal energy standards:Member states now mandate thermal performance simulation for renovation permits, compelling architects to adopt compliant design platforms.
- Residential renovation spending:Homeowners committing capital to property upgrades require photorealistic previews before contractor engagement, accelerating software subscriptions.
- Mobile-first accessibility:Smartphone and tablet compatibility removes training friction for DIY users, expanding addressable demand beyond professional segments.
Market Restraints
- High-performance GPU dependency:Real-time ray tracing and VR rendering require discrete graphics hardware that prices out entry-level users in emerging markets.
- Data sovereignty fragmentation:Divergent cloud storage regulations across European member states complicate cross-border project collaboration for multinational firms.
- Interoperability gaps:Proprietary file formats between BIM and CAD ecosystems force manual translation workflows that erode productivity gains.
Strategic Opportunities
- Underpenetrated contractor digitization:Small-scale remodeling businesses in Spain and Italy still rely on paper-based bidding, presenting SaaS conversion potential.
- AI-assisted generative design:Machine learning algorithms that auto-populate code-compliant layouts from rough sketches are converging with parametric modeling engines.
- Utility rebate integration:US state-level efficiency incentive programs create channel partnerships where software vendors embed real-time rebate calculations into specification workflows.
Industry Challenges
- Building code versioning complexity:Municipal amendments to national standards require continuous database updates that strain smaller development teams.
- Legacy ERP integration:Established contractors running on-premise accounting systems face middleware costs when connecting cloud design tools to invoicing workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Home Design Software Market |
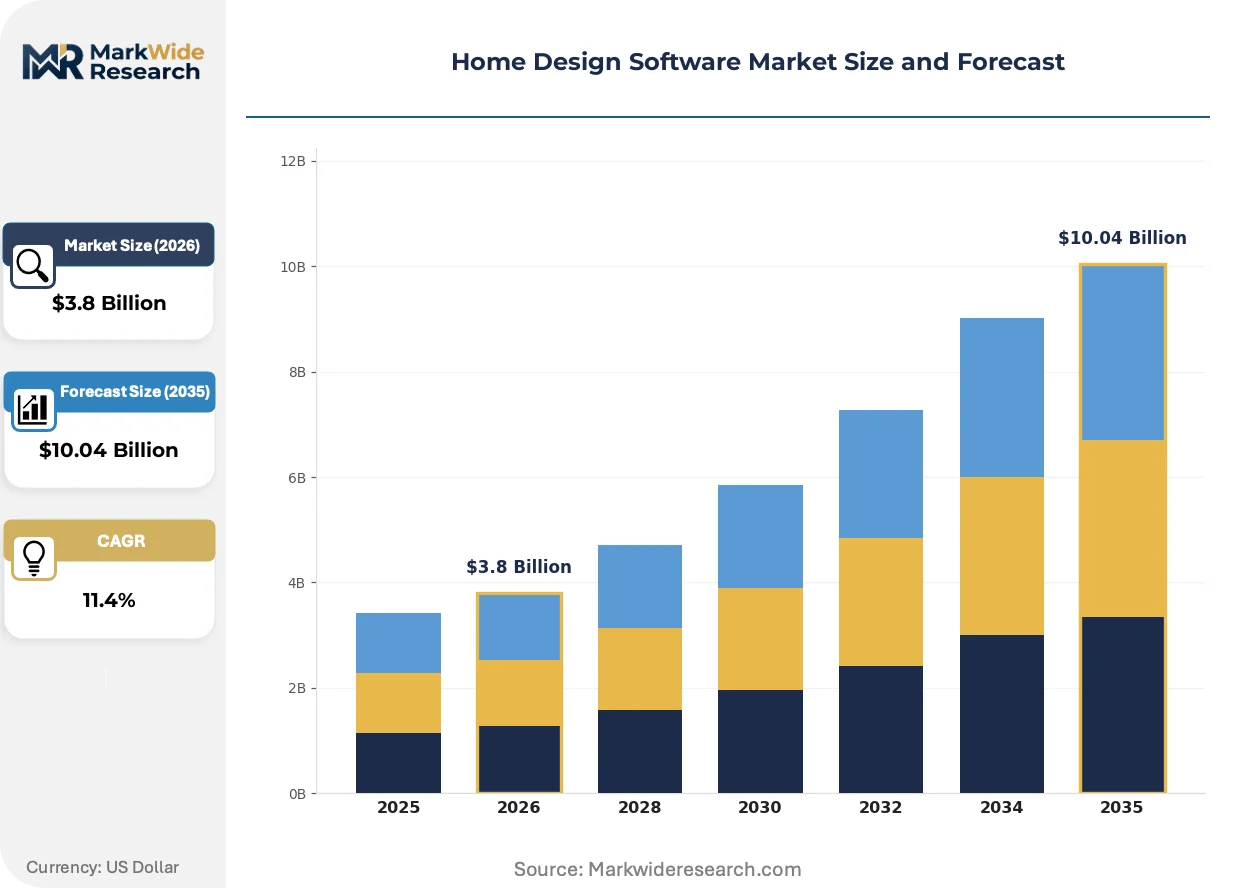
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 3D Modeling, Space Planning, Virtual Reality, Landscape Design Application: Interior Design, Architectural Design, Renovation, Landscaping End User: Homeowners, Interior Designers, Architects, Contractors Technology: Cloud-based, Desktop Application, Mobile Application, Augmented Reality |
| Companies Covered | Chief Architect, Floorplanner, Homestyler, RoomSketcher, Autodesk Revit, Planner 5D, Foyr Neo, Coohom, SketchUp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Home Design Software Market Shifts & Advancements
Immersive visualization technologies are collapsing the distance between conceptual design and physical construction, converting software from documentation tools into pre-sales engines that lock in client commitment before material procurement.
Generative AI is expanding into spatial layout optimization, interpreting natural language prompts to produce code-compliant floor plans with structural load calculations embedded. Custom home builders in Texas and Florida are adopting these tools at twice the rate of commercial architects, compressing the schematic design phase from weeks to hours and reallocating professional time toward value-engineering consultations.
California's Title 24 energy codes now mandate automated thermal bridging analysis for all residential permits submitted after compliance deadlines, forcing software vendors to license ASHRAE calculation engines or build proprietary simulation modules. The regulatory pressure is most acute among mid-size firms serving the Bay Area and Los Angeles metro corridors, where permit rejection rates for manual submissions have spiked.
Subscription fatigue among professional users is fragmenting purchasing authority, with individual designers expensing personal tool licenses rather than waiting for centralized IT procurement cycles. This behavioral shift concentrates in North American AEC consultancies under fifty employees, where shadow IT prevalence now exceeds formal vendor management and creates compliance exposure for intellectual property protection.
Home Design Software Market Segmentation
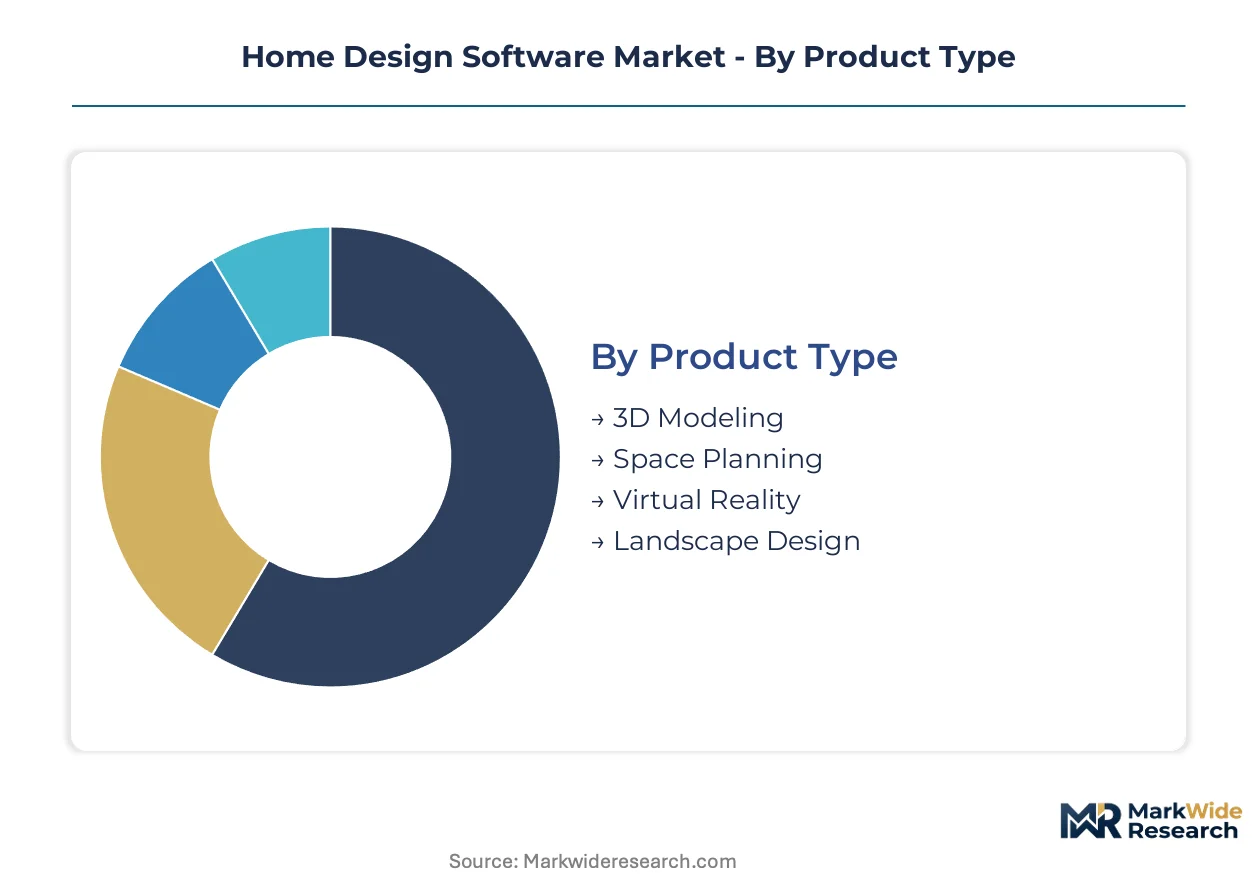
Segmentation in home design software reveals how purchasing authority fragments across technical sophistication levels and project complexity tiers. Buyers select platforms based on rendering fidelity requirements, collaboration intensity, and regulatory compliance burdens rather than price alone.
Product Type:
Purchasing decisions here hinge on visualization depth required before capital commitment.
- 3D Modeling:Generates photorealistic spatial representations with material texture mapping and lighting simulation at 1:1 scale fidelity. Residential contractors in the United States demand these capabilities for renovation bidding where client approval precedes procurement. Cloud-based delivery removes GPU hardware barriers for smaller firms.
- Virtual Reality:Enables immersive walkthroughs via headset compatibility, converting pre-sales presentations into commitment-locking experiences. Custom home builders in Texas and Florida adopt VR tools at accelerated rates, compressing schematic approval cycles from weeks to days. This segment climbs the fastest as hardware costs decline and client expectations shift.
- Space Planning:Focuses on 2D layout optimization and furniture placement algorithms for rapid conceptual iteration.
- Landscape Design:Integrates terrain modeling, vegetation libraries, and irrigation planning for outdoor residential projects.
3D Modeling leads on scale; Virtual Reality leads on momentum.
Application:
Application selection tracks project phase entry points and documentation requirements for permit submission.
- Renovation:Combines as-built scanning integration with code-compliance checking for existing structure modifications. Homeowners in the United States drive subscriptions through DIY platforms that automate material takeoffs and contractor bid packages. EU Green Deal thermal performance mandates now require simulation-capable tools for permit approval in member states.
- Architectural Design:Supports full construction documentation with structural load calculations and specification generation. BIM-compliant workflows dominate commercial-to-residential crossovers where Autodesk Revit maintains entrenched position.
- Interior Design:Emphasizes material libraries and fixture specification for finish selection workflows.
- Landscaping:Addresses outdoor hardscaping, drainage, and planting design with seasonal visualization.
Renovation applications expand most quickly; Architectural Design commands premium pricing tiers.
End User:
End user segmentation reflects training investment capacity and collaboration frequency with external stakeholders.
- Contractors:Require estimation integration, permit-ready documentation, and client presentation tools that compress sales cycles. Small-scale remodeling businesses in Spain and Italy remain underpenetrated, presenting SaaS conversion opportunity from paper-based bidding. Shadow IT prevalence among North American firms under fifty employees now exceeds formal procurement.
- Homeowners:Prioritize intuitive interfaces and mobile accessibility that remove training friction for DIY renovation planning. Subscription fatigue concentrates purchasing authority with individual designers expensing personal licenses.
- Interior Designers:Demand extensive material libraries and manufacturer specification linking for procurement coordination.
- Architects:Mandate BIM interoperability and regulatory database integration for compliance-first specification workflows.
Contractors represent the largest addressable expansion; Homeowners gain share fastest through mobile-first platform adoption.
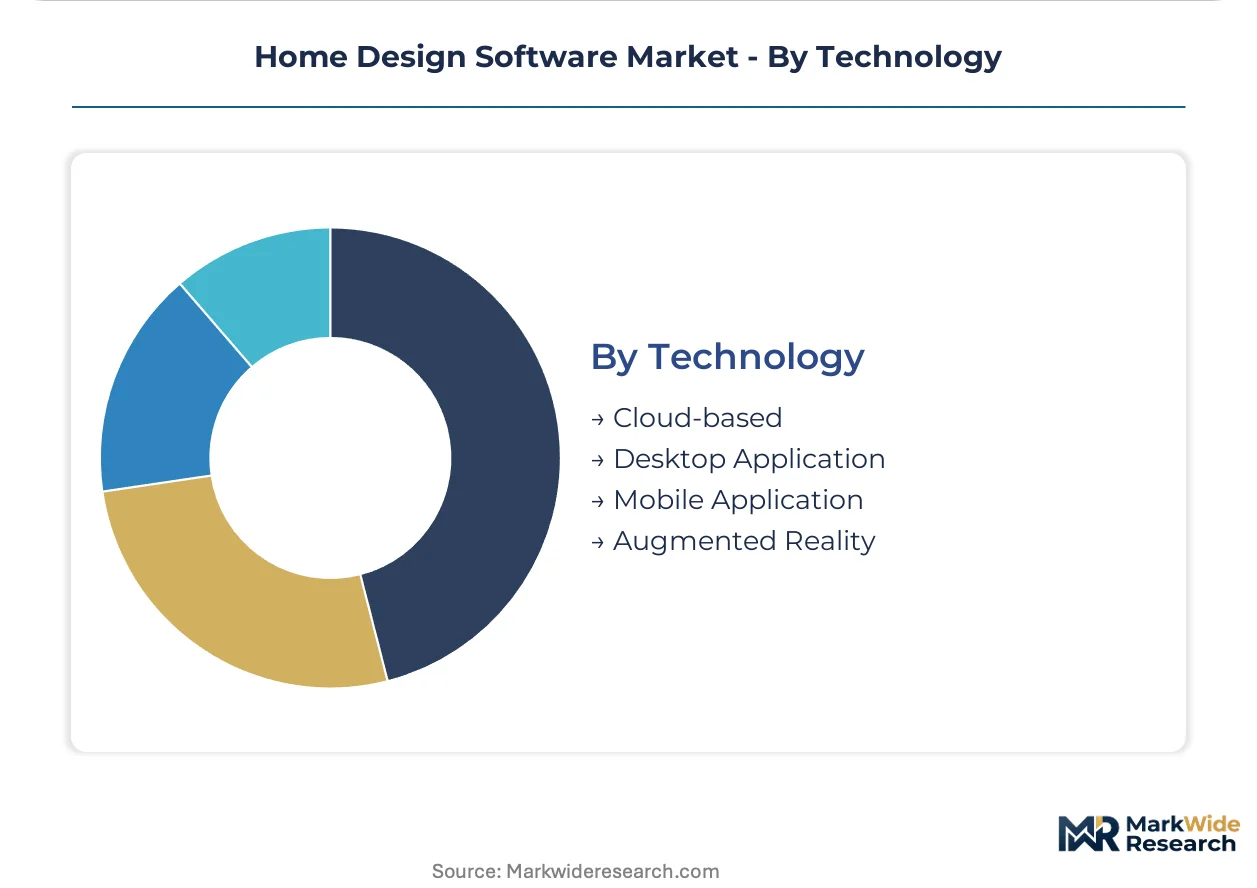
Technology:
Technology deployment mode determines hardware investment requirements and real-time collaboration capabilities.
- Cloud-based:Removes local GPU dependencies and enables simultaneous client collaboration through browser-based rendering. Data sovereignty fragmentation across European member states complicates cross-border project workflows for multinational firms. California's Title 24 energy code automation now requires thermal bridging analysis modules accessible via cloud APIs.
- Mobile Application:Delivers sketch-to-layout conversion and on-site measurement tools through smartphone and tablet interfaces. Field contractors leverage these for immediate client feedback capture during property walkthroughs.
- Desktop Application:Retains preference for complex parametric modeling requiring dedicated workstation performance.
- Augmented Reality:Overlays digital furniture and finish visualization onto physical spaces through camera-enabled devices.
Cloud-based deployment leads on scale; Mobile Application shows steepest expansion trajectory as smartphone penetration saturates professional segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The home design software industry traces its commercial origins to Silicon Valley and Boston-area CAD pioneers of the 1980s, where desktop visualization tools first migrated from aerospace engineering into residential construction workflows. This North American foundation established the technical architectures and subscription business models now diffusing worldwide.
United States
DIY renovation culture and contractor digitization drive premium subscription uptake across Texas and Florida custom home markets. The EPA's ENERGY STAR certification pathways and California's Title 24 energy codes mandate thermal performance documentation that software platforms now automate. Bay Area and Los Angeles metro corridors concentrate compliance-driven adoption among mid-size architectural firms.
Germany
Professional remodelers and energy-efficient renovation specialists demand simulation-capable platforms aligned with federal building codes. The EU Green Deal's thermal performance mandates flow through German implementation, compelling software integration of ASHRAE calculation engines. Bavaria and Baden-Württemberg host dense clusters of Mittelstand construction firms converting from paper-based bidding.
United Kingdom
Residential architects and interior design studios prioritize BIM-compliant workflows for commercial-to-residential crossover projects. The country's building safety regulator enforces stricter documentation standards post-Grenfell, pushing smaller practices toward cloud-based specification tools. Greater London concentrates demand for real-time client collaboration features.
India
Rapid urbanization and rising middle-class homeownership expand addressable demand for mobile-first design tools. The country's central housing authority promotes digitized building permits through Smart Cities Mission infrastructure. Bangalore and Hyderabad technology corridors incubate SaaS startups targeting contractor digitization gaps.
Australia
Custom home builders and renovation contractors adopt immersive visualization for pre-sales commitment locking. The national construction code regulator mandates energy efficiency ratings that design software automates through NatHERS integration. Sydney and Melbourne metropolitan markets lead headset-compatible VR walkthrough adoption.
Home Design Software Market Competitive Landscape
Premium-margin players sit above commodity-margin players across rendering fidelity and regulatory compliance depth, with BIM-integrated suites commanding annual subscriptions while basic floor-plan tools compete on freemium conversion. The vendor base organizes into three tiers: enterprise-grade platforms with native code databases, prosumer tools emphasizing intuitive geometry manipulation, and mobile-first entrants stripping functionality for smartphone accessibility. Consolidation pressure concentrates among mid-market SaaS providers lacking thermal simulation modules. Dominant competitive moves include strategic partnerships with utility rebate programs and vertical integration into material specification databases.
Within the enterprise-platform tier, Autodesk Revit and Chief Architect occupy positions anchored to professional remodeling and architectural design workflows respectively. SketchUp exemplifies the prosumer archetype where lowered training barriers expand adoption beyond credentialed practitioners. Among mobile-first specialists, Planner 5D and RoomSketcher represent the accessibility-driven segment converting smartphone users into paying subscribers through freemium tier progression.
| Leading Market Players |
|---|
| Chief Architect |
| Floorplanner |
| Homestyler |
| RoomSketcher |
| Autodesk Revit |
| Planner 5D |
| Foyr Neo |
| Coohom |
| SketchUp |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up SaaS specialists dominate the vendor landscape, compressing R&D cycles to sustain subscription pricing power while cloud infrastructure costs anchor margin structures. This ownership pattern intensifies pricing discipline through recurring revenue optimization and selective feature bundling that segments buyers by technical sophistication.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates enterprise BIM suites from prosumer visualization tools and mobile-first freemium platforms. Price differentiation hinges on rendering fidelity and regulatory database depth, with California Title 24 compliance modules commanding substantial premiums. Cost compression in the mid-market tier intensifies as SaaS entrants undercut legacy desktop licenses. DIY homeowners exhibit highest price sensitivity, while architectural firms under fifty employees demonstrate inelastic demand for compliance-integrated workflows.
Supply Chain Analysis
Reverse-logistics flows for VR headset hardware and GPU workstation refurbishment create secondary equipment channels that extend technology accessibility to price-sensitive segments. Software development concentrates in the United States, Germany, and India, with cloud infrastructure drawing from hyperscaler networks across these jurisdictions. The supply chain rests on semiconductor availability for rendering acceleration and ASHRAE calculation engine licensing for thermal simulation modules. Single-source vulnerability concentrates in proprietary BIM file format dependencies. Distribution runs through direct SaaS subscriptions, channel partnerships with utility rebate programs, and embedded marketplace integrations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in home design software stems from cloud infrastructure cost curves flattening while premium-tier compliance modules capture regulatory-driven demand. The shift toward automated thermal simulation and AI-assisted layout generation concentrates value capture among vendors with native code database integration.
For Market Incumbents: Cement defensible positioning through backward integration into material specification databases and exclusive ASHRAE engine licensing that locks out mid-tier competitors. Threats from generative AI entrants with natural language floor plan generation demand accelerated R&D in spatial layout automation. Channel control through utility rebate program partnerships represents the critical lever for contractor segment retention. For New Entrants and Emerging Players: Begin with underpenetrated small-scale remodeling contractors in Spain and Italy, where paper-based bidding persists and SaaS conversion offers lowest customer acquisition costs. Mobile-first accessibility for field measurement and on-site client collaboration provides the most penetrable entry angle against incumbent desktop dependencies. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-market SaaS providers lacking thermal simulation modules, where regulatory compliance gaps create distressed acquisition opportunities. Long-term viability favors platforms with embedded ENERGY STAR and Title 24 automation that withstand building code versioning complexity. Monitor permit rejection rates for manual submissions in California metro corridors as inflection indicator for compliance-first platform demand.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Native embedding of EPA ENERGY STAR pathways differentiates compliant-first suites from retrofit laggards. |
| Strategic Partnership | Utility rebate program alliances convert software vendors into efficiency incentive distribution channels. |
| Acquisition of Specialist Firm | ASHRAE calculation engine specialists command scarcity premiums as Title 24 mandates thermal bridging analysis. |
| Product Launch | Generative AI layout tools compress schematic design from weeks to hours for Texas and Florida custom builders. |
| Geographic Expansion | Smart Cities Mission alignment positions SaaS entrants for India's digitized building permit infrastructure. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Primary interviews engaged chief technology officers at SaaS platforms, IT procurement officers at architectural consultancies, platform engineers at hyperscaler infrastructure providers, and channel partners in utility rebate programs. Secondary sources encompassed SEC filings, hyperscaler capex disclosures, and building permit databases from California and German federal agencies. Bottom-up segment sizing and top-down macroeconomic triangulation anchored value projections.
Granularity-level modeling deployed deployment mode, organization size, vertical specialization, and regional adoption pattern as core segmentation dimensions. CAGRs were derived through trend-line extrapolation of subscription growth rates cross-referenced with renovation spending elasticity. Forecast inputs incorporated EU Green Deal implementation timelines and mobile penetration saturation curves across professional segments.
Several conditions sit outside the modeled scope, including abrupt regulatory reversals, hyperscaler pricing volatility, and hardware shortage disruptions affecting GPU-dependent rendering tiers. Practitioners should monitor municipal building code amendment velocity and shadow IT prevalence among North American small firms for early signals of platform consolidation pressure.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Freight Forwarding Software Market
Software & Services
DevOps Market
Software & Services
Global Diagram Software Market
Software & Services
Low Code Development Platform Market
Software & Services
Global Pension Administration Software Market
Software & Services
North America Digital Marketing Software Market
Software & Services
Global Food Traceability Software Market
Software & Services
Productivity Management Software Market
Software & Services
PCB CAD Software Market
Software & Services
Cursor Reviewer Market
Software & Services
Bank Reconciliation Software Market
Software & Services
Global Ad Server Software Market
Software & Services
Global Wedding Invitations Software Market
Software & Services
Global Address Verification Software Market
Software & Services
PLM and Engineering Software Market
Software & Services
Europe Drone Software Market