
 File Sharing Software Market | 2026-2036
File Sharing Software Market Size, Share, and Industry Trends Forecast 2026-2036
File Sharing Software Market Analysis
The IT security talent shortage is unwinding as enterprises scramble to staff zero-trust architecture teams. Microsoft SharePoint leverages its Office 365 integration to dominate enterprise deployments. Dropbox Business anchors its position through consumer-to-business channel migration. Egnyte specializes in hybrid-cloud governance for regulated industries.
File sharing software denotes systems that enable digital content distribution across networks through protocols supporting concurrent access, version control, and permission-based retrieval with throughput parameters typically exceeding 100 Mbps for enterprise-grade solutions. Cloud-Based deployment leads structural growth as organizations abandon capital-intensive on-premises infrastructure, while Collaboration Tools within the Service Type dimension capture expanding margin pools through real-time co-editing and workflow integration. Encryption capabilities under Security Features represent the fastest-growing specification tier as breach liability reshapes procurement criteria.
The SEC enforces cybersecurity disclosure rules that mandate incident reporting for publicly traded software users, while GDPR and HIPAA impose data residency and access audit requirements that shape product architecture. ISO 27001 certification has become a baseline market access credential for vendors serving multinational accounts. Stakeholders must monitor regulatory divergence between EU AI Act data governance provisions and US sector-specific frameworks to anticipate compliance-driven purchasing cycles.
Market Dynamics
Zero-trust architecture mandates from the SEC and GDPR are forcing enterprise file sharing vendors to rebuild access control frameworks from session-based to continuous verification models.
Growth Catalysts
- HIPAA Enforcement:Healthcare providers in the United States face audit expansion for patient data exchange, driving procurement of compliant platforms with granular access logging.
- Cloud Migration Mandates:The SEC's cybersecurity disclosure rules compel publicly traded enterprises to abandon on-premises infrastructure for auditable cloud-native alternatives.
- Real-Time Collaboration:Distributed engineering teams require synchronous co-editing capabilities that legacy FTP systems cannot deliver, accelerating platform replacement cycles.
Market Restraints
- Data Residency Requirements:GDPR's cross-border transfer restrictions fragment vendor architectures, forcing redundant infrastructure deployment across European member states.
- Encryption Export Controls:Dual-use technology classifications in multiple jurisdictions delay product release cycles and complicate multinational rollout timelines.
- Legacy System Entrenchment:Manufacturing and financial services retain decades-old file transfer protocols due to integration dependencies with specialized hardware.
Strategic Opportunities
- AI-Generated Content Governance:The EU AI Act creates demand for provenance-tracking features that document training data lineage and model output distribution.
- Edge Computing Integration:Hybrid architectures combining cloud repositories with local caching nodes address latency-sensitive workflows in autonomous vehicle development.
- Vertical-Specific Compliance Bundles:Pre-configured templates for FDA 21 CFR Part 11 in pharmaceutical R&D reduce implementation friction and accelerate sales cycles.
Industry Challenges
- Zero-Trust Talent Scarcity:Enterprise security teams lack engineers certified in continuous verification architecture, extending deployment timelines by 6-12 months.
- Interoperability Fragmentation:Proprietary API ecosystems from dominant vendors create vendor lock-in that complicates multi-platform enterprise environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | File Sharing Software Market |
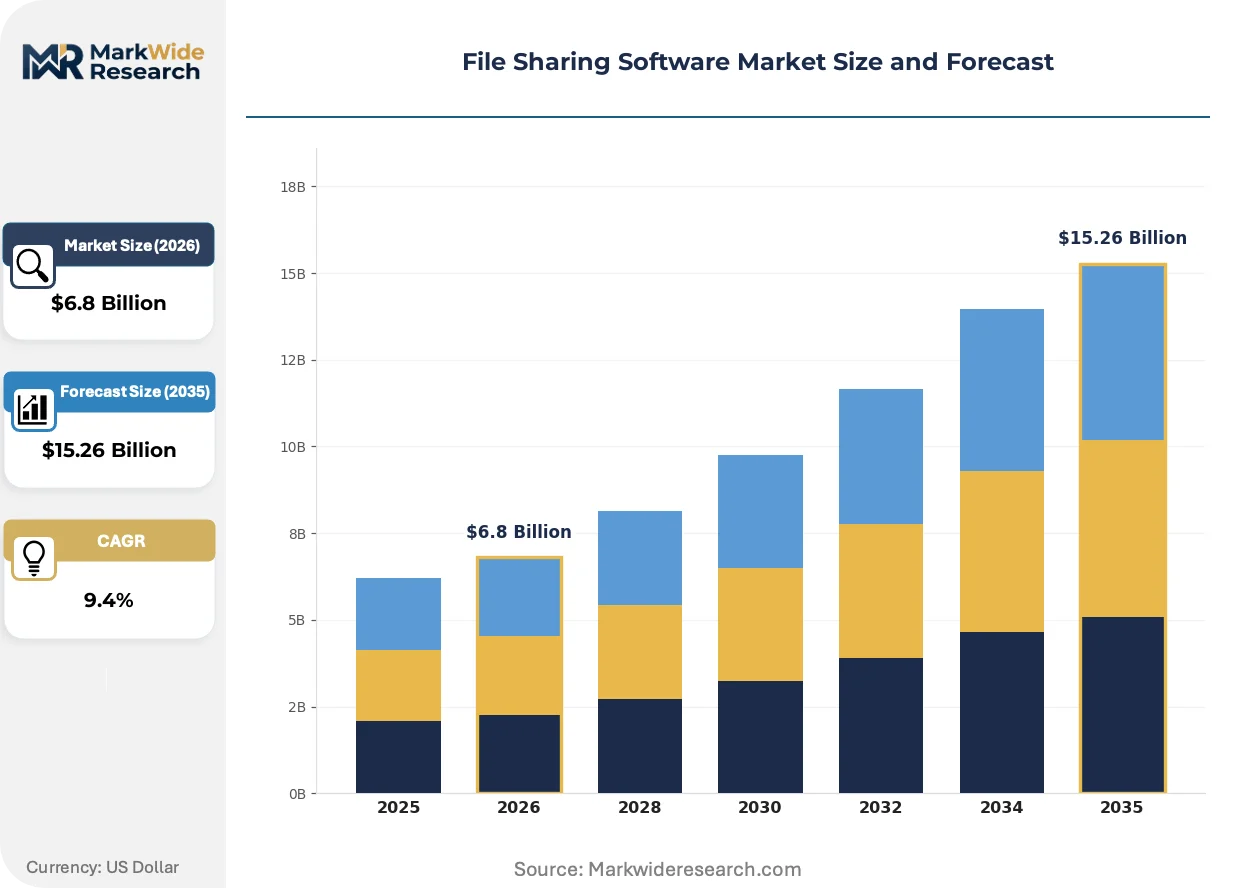
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $15.26 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Private Cloud Service Type: File Sync, File Transfer, File Storage, Collaboration Tools End User: Small Businesses, Enterprises, Educational Institutions, Individual Users Security Features: Encryption, Access Controls, Two-Factor Authentication, Data Loss Prevention |
| Companies Covered | Box, Citrix ShareFile, Microsoft SharePoint, Amazon WorkDocs, Egnyte, Google Drive for Workspace, OneDrive for Business, Zoho Docs, Dropbox Business, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
File Sharing Software Market Emerging Trajectories
File sharing architecture is converging with identity infrastructure, transforming standalone storage into embedded components of broader security and workflow stacks.
Confidential computing enclaves are miniaturizing data processing boundaries, enabling encryption-in-use for sensitive analytics without exposing cleartext to cloud operators. Pharmaceutical companies conducting multi-party clinical trials adopt these architectures to satisfy FDA data integrity requirements while enabling cross-institutional collaboration. The technology is miniaturizing the trust perimeter from network boundaries to individual computation instances, collapsing traditional DMZ architectures.
The EU AI Act's data governance provisions impose documentation burdens on AI training dataset distribution, requiring file sharing platforms to embed automated metadata capture and audit trails. Vendors serving European enterprise accounts must rebuild ingestion pipelines to tag provenance at the point of upload. Healthcare AI developers in Germany and France face the strictest compliance timelines, with platform selection criteria now weighting governance automation above transfer speed.
Consumption-based licensing is displacing per-seat subscriptions in enterprise procurement, with IT departments preferring metered billing tied to actual storage and bandwidth utilization. Channel partners report that CFO-driven vendor consolidation favors platforms offering granular cost visibility. This pattern is most pronounced in United States technology sector accounts, where finance teams mandate showback mechanisms for departmental cloud spending.
File Sharing Software Market Segmentation
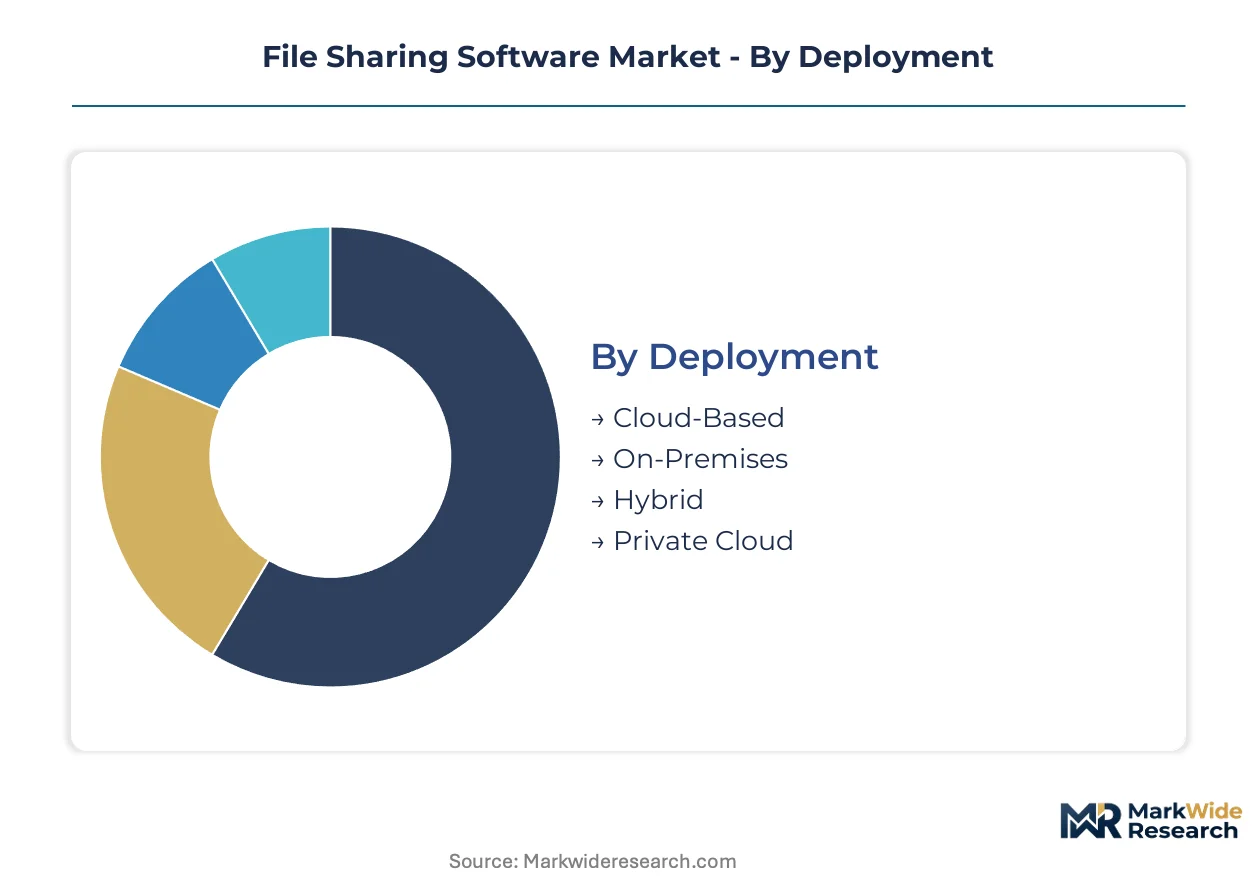
Deployment architecture determines channel economics and customer acquisition costs in file sharing software. Security specifications increasingly gate market access in regulated verticals. Service type differentiation separates commodity storage from premium workflow solutions.
Deployment:
Cloud-Based solutions flow through direct vendor channels and hyperscaler marketplaces, while On-Premises deployments rely on systems integrators and value-added resellers with deep legacy integration expertise.
- Cloud-Based:Multi-tenant architectures with automatic scaling and API-first integration patterns. Healthcare providers in the United States select these platforms to satisfy HIPAA audit requirements without capital expenditure. By volume, Cloud-Based leads. By growth pace, Hybrid is ahead.
- On-Premises:Single-tenant installations on customer-managed hardware with full data sovereignty. Financial services in Germany retain these configurations to satisfy BaFin operational resilience mandates for critical trading infrastructure.
- Hybrid:Orchestrated workloads spanning private data centers and public cloud nodes with policy-driven data placement. Manufacturing firms in Japan deploy these architectures to balance latency-sensitive shop floor operations with centralized analytics.
- Private Cloud:Dedicated cloud infrastructure with tenant-isolated compute and storage resources. Defense contractors in the United States procure these deployments to meet CMMC 2.0 controlled unclassified information handling requirements.
Channel partners report Hybrid deployments command the longest sales cycles but generate recurring professional services revenue.
Service Type:
Collaboration Tools capture the highest gross margins through real-time co-editing and workflow automation, while File Storage competes primarily on unit economics.
- File Sync:Continuous background replication across endpoints with conflict resolution and versioning. Distributed creative agencies in France prioritize these capabilities for seamless asset handoffs between remote contributors.
- File Transfer:High-throughput bulk movement with checkpoint restart and integrity verification. Media production houses in Japan rely on UDP-accelerated protocols to move uncompressed 8K footage between Tokyo and Osaka facilities.
- File Storage:Object and block storage with tiered durability classes and lifecycle policies. Enterprise archives in Germany exploit cold storage tiers to reduce GDPR-mandated retention costs.
- Collaboration Tools:Synchronous document editing with comment threading, task assignment, and approval workflows. Pharmaceutical R&D teams in the United States embed these features to accelerate FDA submission package assembly.
By revenue contribution, Collaboration Tools dominates. By expansion trajectory, File Sync is climbing the fastest.
End User:
Enterprises consolidate procurement through centralized IT governance, while Small Businesses activate through self-service product-led growth channels.
- Small Businesses:Teams under 100 seats with limited IT staff and preference for out-of-box configuration. Professional services firms in Germany adopt these solutions to satisfy GDPR documentation obligations without dedicated compliance personnel.
- Enterprises:Organizations with 1000+ seats, SSO integration requirements, and custom SLA negotiations. Multinational banks in the United States mandate these platforms to satisfy SEC cybersecurity disclosure rule audit trails.
- Educational Institutions:Campus-wide licensing with FERPA compliance and learning management system connectors. Research universities in Japan deploy these systems for cross-institutional data sharing under METI-funded consortium agreements.
- Individual Users:Consumer-grade freemium accounts with basic storage and sharing capabilities. Freelance creators in France form the core upgrade pipeline to paid tiers through storage quota exhaustion.
By seat count, Enterprises commands the largest installed base. By activation velocity, Individual Users is gaining share fastest.
Security Features:
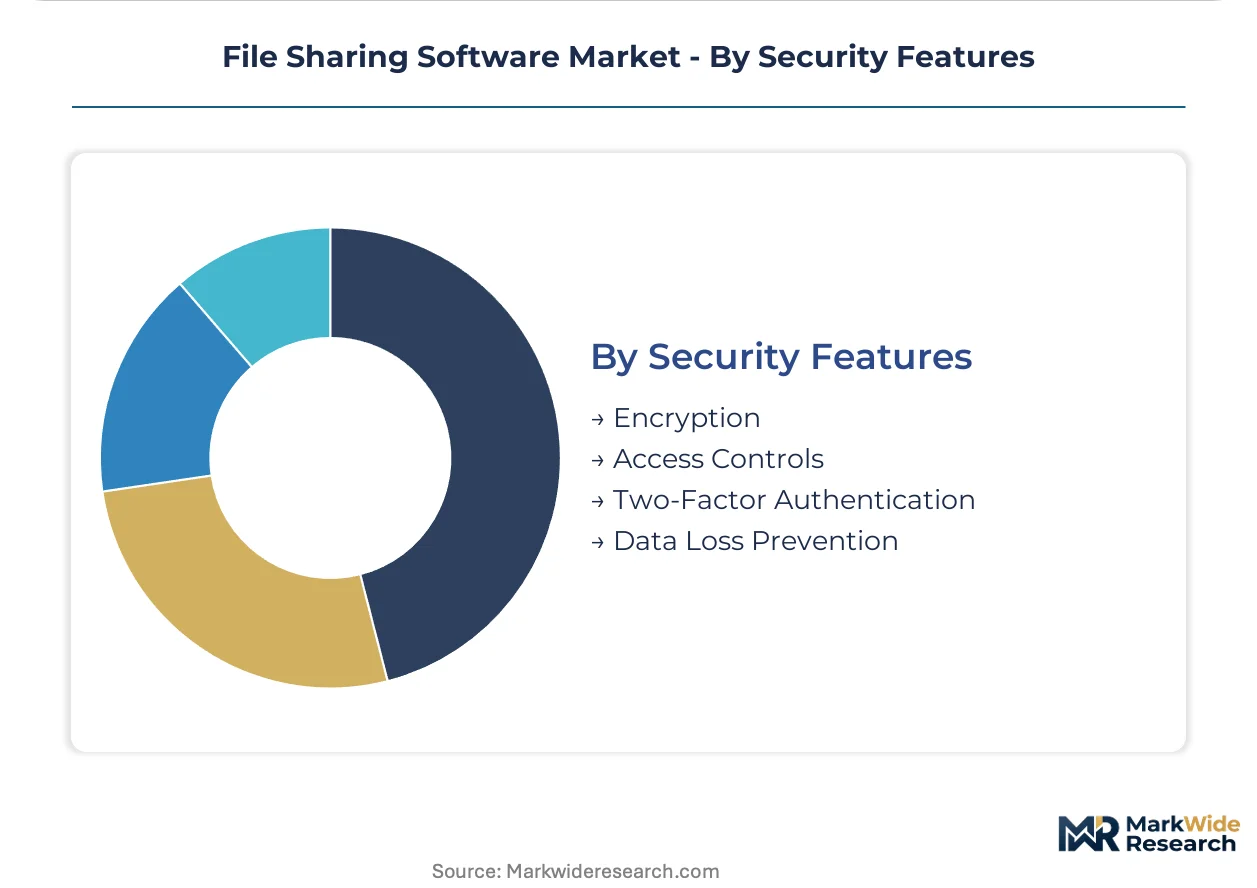
Encryption capabilities differentiate premium tiers from standard offerings, while Access Controls determine enterprise qualification status.
- Encryption:Data-at-rest and in-transit protection with AES-256, TLS 1.3, and emerging post-quantum algorithms. Healthcare systems in the United States require these specifications to satisfy HIPAA technical safeguard implementation specifications.
- Access Controls:Role-based and attribute-based permission models with just-in-time provisioning. Government contractors in Germany implement these frameworks to enforce Bundesdatenschutzgesetz need-to-know principles.
- Two-Factor Authentication:TOTP, FIDO2, and hardware token verification for credential hardening. Financial technology startups in Japan deploy these mechanisms to satisfy FSA guidelines for electronic payment service providers.
- Data Loss Prevention:Content inspection, egress monitoring, and automated policy enforcement. Pharmaceutical companies in the United States activate these modules to prevent FDA 21 CFR Part 11 regulated record exfiltration.
By procurement frequency, Encryption leads. By implementation urgency, Data Loss Prevention shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Healthcare providers in the United States deploy HIPAA-compliant cloud platforms at scale, while German manufacturers retain on-premises sovereignty for critical infrastructure. Japanese enterprises favor hybrid architectures balancing latency-sensitive operations with centralized governance.
United States
SEC cybersecurity disclosure rules compel publicly traded enterprises to abandon legacy FTP systems for auditable cloud-native alternatives. HIPAA enforcement expansion drives procurement of platforms with granular access logging across hospital networks. Boston's biomedical research corridor concentrates demand for FDA 21 CFR Part 11 compliant collaboration tools.
Germany
BaFin operational resilience mandates preserve on-premises installations for financial trading infrastructure despite cloud migration pressure. GDPR cross-border transfer restrictions fragment vendor architectures, forcing redundant European data center deployment. Munich's automotive engineering clusters adopt hybrid configurations to protect proprietary design data while enabling supplier collaboration.
Japan
METI-funded research consortiums accelerate cross-institutional data sharing adoption among technical universities and corporate R&D centers. FSA guidelines for electronic payment providers mandate hardware token verification for credential hardening. Nagoya's manufacturing belt deploys edge-integrated file sharing to synchronize shop floor robotics with cloud analytics.
France
CNIL enforcement of GDPR documentation obligations pushes professional services firms toward out-of-box compliance configurations. ANSM requirements for clinical trial data integrity shape pharmaceutical platform selection criteria. Parisian creative agencies prioritize file sync capabilities for seamless asset handoffs between remote production teams.
United Kingdom
Financial services regulators emphasize audit trail completeness for cross-border transaction documentation. Research universities deploy campus-wide licensing with FERPA-equivalent student data protections. London's fintech cluster consumes metered billing platforms offering granular cost visibility for departmental cloud spending.
File Sharing Software Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with hyperscaler-backed platforms commanding enterprise procurement through existing productivity suite relationships. The middle tier comprises vertical specialists targeting regulated industries with pre-configured compliance bundles. Competitive dynamics center on M&A activity consolidating adjacent workflow capabilities and strategic partnerships embedding file sharing into broader security stacks.
Within the integrated platform tier, Microsoft SharePoint and Google Drive for Workspace exemplify productivity-suite bundling strategies, while Dropbox Business represents consumer-to-business channel migration archetypes. Box occupies a position emphasizing enterprise-grade security certifications for regulated verticals. Egnyte anchors the hybrid-cloud governance specialization serving multinational accounts with complex data residency requirements.
| Leading Market Players |
|---|
| Box |
| Citrix ShareFile |
| Microsoft SharePoint |
| Amazon WorkDocs |
| Egnyte |
| Google Drive for Workspace |
| OneDrive for Business |
| Zoho Docs |
| Dropbox Business |
| Others |
Supply Flow & Price Mechanics
Hyperscale data center utilization rates in Northern Virginia and Frankfurt determine unit economics for cloud storage tiers, compressing marginal costs for multi-tenant architectures while erecting price floors for smaller regional operators lacking comparable scale.
Pricing Analysis
Long-term enterprise offtake agreements dominate procurement for multinational accounts, with annual or multi-year subscriptions locking in per-seat rates against metered consumption alternatives. Three-tier pricing structure across premium, standard, and economy levels separates HIPAA-compliant healthcare bundles from basic file sync tiers, with ISO 27001 certification commanding material premiums. Pricing pressure stems from hyperscaler bundling of storage with productivity suites, forcing standalone vendors toward specialized vertical offerings. Small businesses exhibit highest price sensitivity, while defense contractors and pharmaceutical firms prioritize compliance specifications over unit cost.
Supply Chain Analysis
Submarine cable chokepoints across the Atlantic and Pacific underwrite latency premiums for cross-border data transit, with Singapore-Japan and US-Europe routes commanding infrastructure investment priority. Cloud infrastructure concentrates in the United States, Ireland, and Singapore, with compute and storage hardware sourcing from Taiwan, South Korea, and China. Supply chain risk centers on single-source vulnerability for advanced encryption processors subject to dual-use export classifications. Distribution runs through hyperscaler marketplaces, direct vendor sales teams, and systems integrators with vertical specialization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Managed security services and compliance automation layers expand faster than raw storage capacity, transforming file sharing from commodity infrastructure into governance-embedded platforms with recurring professional services attach rates.
For Market Incumbents: Secure zero-trust architecture certification pipelines before SEC disclosure rules harden procurement barriers against uncertified alternatives. Deepen hybrid-cloud orchestration capabilities to defend against hyperscaler bundling, while acquiring vertical-specific compliance boutiques to pre-package FDA and GDPR templates. Threat substitution from AI-native collaboration platforms demands workflow integration investments that embed file sharing deeper into customer operations. For New Entrants and Emerging Players: Edge-integrated file caching for autonomous vehicle and robotics development represents the most penetrable white-space where latency requirements outstrip incumbent cloud-centric architectures. Target mid-market manufacturing firms in Japan's industrial corridors with shop floor-to-cloud synchronization offerings. Go-to-market through OT-system integrators already embedded in plant automation projects bypasses saturated IT procurement channels. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among hybrid-cloud specialists serving multinational accounts with complex data residency requirements, offering visibility into multi-year expansion trajectories. Acquisition candidates should demonstrate pre-built compliance templates for at least two regulated verticals with active customer references. Watch for inflection when EU AI Act enforcement timelines accelerate provenance-tracking feature procurement among European enterprise accounts.| Strategic Initiative | Industry Significance |
|---|---|
| Zero-Trust Architecture Certification | SEC disclosure rules mandate continuous verification frameworks for publicly traded enterprise users. |
| Vertical Compliance Bundle Development | FDA 21 CFR Part 11 templates accelerate pharmaceutical R&D procurement cycles in Boston's biomedical corridor. |
| Edge Computing Integration | Hybrid architectures address latency-sensitive workflows in Nagoya's autonomous vehicle development clusters. |
| Consumption-Based Licensing Transition | Metered billing aligns vendor economics with CFO-driven cloud cost visibility mandates in US technology sector accounts. |
| AI Provenance Tracking Capability | EU AI Act documentation burdens require automated metadata capture at ingestion points for European enterprise compliance. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of SEC cybersecurity disclosure filings, hyperscaler capex disclosures, and regulatory enforcement databases to validate market sizing assumptions. Interviews with CISOs, IT procurement officers, platform engineers, and channel partners across healthcare, financial services, and manufacturing verticals inform deployment preference patterns. Bottom-up triangulation of vendor-reported seat counts and top-down validation against enterprise IT spending surveys ensure cross-verified demand estimates.
Segmentation dimensions modeled span deployment architecture, organization size, vertical industry, integration complexity, and regional regulatory framework across the projection horizon. CAGRs derive from logistic adoption curve fitting against historical cloud migration velocity benchmarks, with inputs including HIPAA audit expansion timelines and GDPR cross-border transfer restriction enforcement patterns. Scenario modeling incorporates hyperscaler bundling pressure and zero-trust talent scarcity constraints on deployment velocity.
Forecasts assume regulatory continuity in SEC cybersecurity disclosure and EU AI Act data governance regimes; material policy shifts would require re-modeling adoption trajectories for affected verticals. Specific risk factors include encryption export control expansion, legacy system entrenchment in manufacturing, and interoperability fragmentation from proprietary API ecosystems. Practitioners should keep alternative scenarios live as zero-trust certification pipeline capacity and hyperscaler vertical specialization depth evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Interior Design Software Market
Software & Services
Email Checker Tools Market
Software & Services
Africa HR Payroll Software Market
Software & Services
Photobooth Software Market
Software & Services
Lease Accounting Software Market
Software & Services
Mainframe Software Market
Software & Services
Mobile Backend As a Service (Mbaas) Market
Software & Services
Product Optimization Software Market
Software & Services
ID Photo Software Market
Software & Services
Global Servicenow Store Apps Market
Software & Services
Software Testing Tools Market
Software & Services
Automotive Design Software Market
Software & Services
Home Fitness App Market
Software & Services
Global Customer Journey Mapping Software Market
Software & Services
CGI Software Market
Software & Services
Global Wedding Invitations Software Market