
 Conductive Fibers Market | 2026-2036
Conductive Fibers Market Size, Share, and Industry Trends Forecast 2026-2036
Conductive Fibers Market Analysis
Market Context
Electrospinning expertise and polymer chemistry talent is collapsing across Western manufacturing bases, creating acute bottlenecks for producers scaling next-generation conductive fiber output. Toray Industries leverages its integrated carbon fiber-conductive polymer platform to dominate high-performance segments in Japan and export markets. NV Bekaert SA anchors global metal fiber supply through its stainless steel and copper filament operations serving antistatic and filtration end uses. Seiren Co. Ltd. differentiates via proprietary plating and coating technologies that enable fine-denier conductive yarns for precision electronics applications.
Technical Definition and Segment Structure
Conductive fibers are engineered textile structures—natural, synthetic, metal, or composite—that incorporate electrically conductive elements through intrinsic material properties, surface metallization, or conductive filler loading, typically achieving resistivity below 10^6 ohm-cm for functional current or signal transmission. Synthetic fibers and metal fibers currently occupy the largest volume positions, while composite fibers integrating carbon nanotubes or graphene represent the fastest-expanding margin pool as performance requirements tighten in aerospace and medical device shielding. Smart textiles and wearable technology applications are outpacing antistatic fabrics in growth velocity, though e-textiles for industrial safety retain stable replacement demand across automotive and chemical processing sectors.
Regulatory Environment
REACH and RoHS frameworks in Europe restrict hazardous substances in conductive coatings and metal fiber production, compelling reformulation of copper-nickel plating chemistries and solvent-based processing aids. FDA device regulations and FCC electromagnetic interference standards in the United States shape biocompatibility and shielding performance thresholds for healthcare and telecommunications applications respectively. Stakeholders must monitor evolving EU Green Deal textile sustainability mandates and China's GB standards for electromagnetic compatibility as these frameworks increasingly dictate material certification requirements and cross-border market access conditions.
Market Dynamics
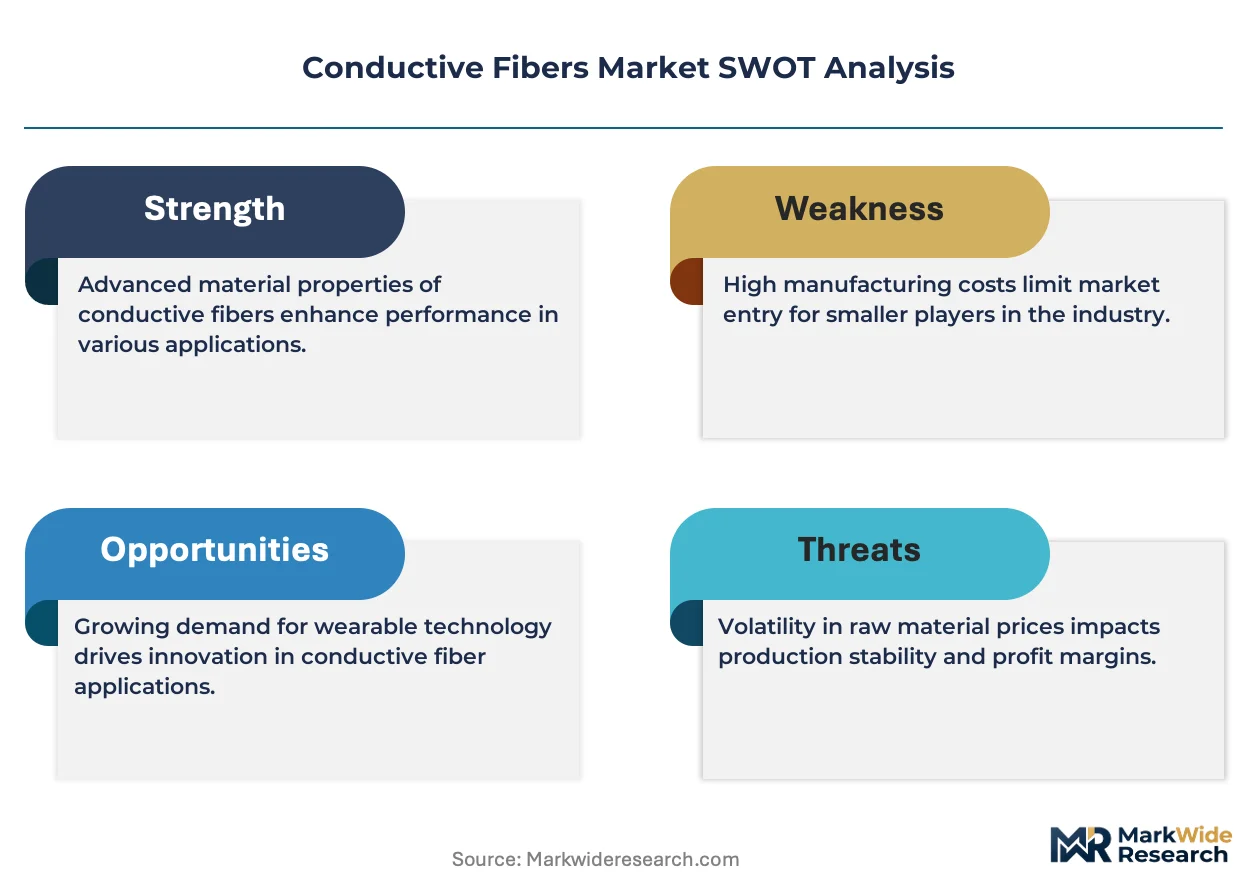
Electromagnetic compatibility mandates across Europe and Asia are compressing certification timelines while electrospinning talent scarcity in Western manufacturing bases constrains capacity expansion for next-generation conductive fiber production.
Growth Catalysts
- EU Green Deal textile sustainability mandates:REACH and RoHS frameworks compel manufacturers to reformulate plating chemistries, accelerating certified conductive material substitution in automotive and medical device supply chains.
- Healthcare wearable integration:Smart textiles for patient monitoring in Japan and South Korea are pulling fine-denier conductive yarns into FDA and PMDA-regulated device ecosystems.
- Carbon nanotube loading:Composite fiber platforms achieving resistivity below 10^6 ohm-cm are penetrating aerospace shielding applications previously served by metal fiber alternatives.
Market Restraints
- Copper and nickel price volatility:Surface metallization processes remain exposed to London Metal Exchange fluctuations, compressing margin pools for stainless steel and copper filament producers.
- Western electrospinning talent collapse:Polymer chemistry expertise concentration in China and Japan creates supply-side bottlenecks for producers scaling carbon-based conductive fiber output.
- Biocompatibility certification friction:FDA device regulations and FCC electromagnetic interference standards impose 18-24 month approval timelines that delay healthcare textile commercialization.
Strategic Opportunities
- India's PLI scheme for technical textiles:Production-linked incentives for functional fiber manufacturing are attracting plating and coating technology transfers from Japanese and South Korean suppliers.
- Antistatic industrial safety fabrics:Underpenetrated chemical processing and mining sectors in Brazil and Saudi Arabia present replacement demand for certified conductive workwear.
- AI-enabled predictive maintenance:Convergence of conductive fiber sensors with edge computing platforms is opening predictive equipment monitoring contracts in German and US automotive assembly plants.
Industry Challenges
- Electrospinning equipment capex intensity:Multi-million dollar cleanroom investments for carbon nanotube alignment systems strain mid-cap producers attempting composite fiber scale-up.
- Cross-border GB standard harmonization:China's electromagnetic compatibility certification requirements diverge from IEC baselines, forcing dual testing protocols for export-oriented suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Conductive Fibers Market |
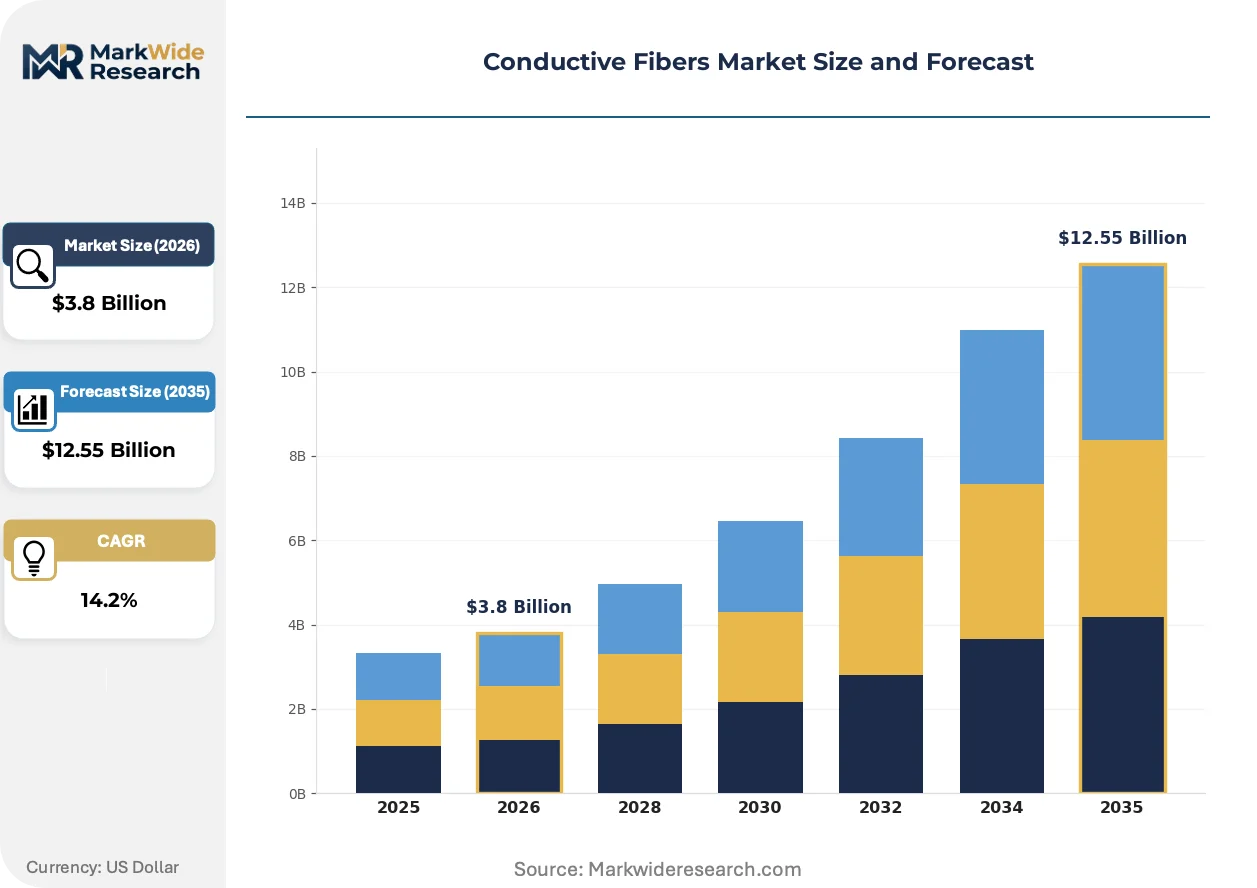
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Fibers, Synthetic Fibers, Composite Fibers, Metal Fibers End User: Textiles, Electrical Components, Aerospace, Healthcare Application: Smart Textiles, Wearable Technology, E-Textiles, Antistatic Fabrics Technology: Conductive Coating, Fiber Blending, Printing Technology, Nano-coatings |
| Companies Covered | Kuraray Co Ltd, Laird Performance Materials, Toray Industries, Eeonyx Corporation, Hitek Electronic Materials Ltd., NV Bekaert SA, Seiren Co. Ltd., Statex Produktions & Vertriebs GmbH, Covestro AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Conductive Fibers Market Emerging Trajectories
Graphene-loaded polymer matrices and solvent-free coating processes are actively restructuring competitive positioning in high-performance conductive fiber segments, while regulatory pressure on hazardous substances accelerates chemistry substitutions.
Carbon nanotube composite fibers are supplanting traditional metal-plated synthetics in aerospace electromagnetic shielding applications. Boeing and Airbus tier-1 suppliers in Germany and Japan have adopted these platforms for next-generation avionics harnesses. The shift is compressing demand for copper-nickel filament in satellite and defense contracts where weight reduction commands premium pricing.
REACH authorization requirements for nickel compounds are forcing reformulation of conductive plating baths across European textile finishing operations. ECHA's 2023 restriction proposals on hexavalent chromium chemistries have triggered capital redeployment toward electroless nickel-phosphorus alternatives. Italian and Portuguese technical textile clusters are consolidating wet-processing capacity to amortize compliance investments.
Direct mill-to-OEM contracting is fragmenting traditional distributor channels for antistatic fabrics. Automotive seating manufacturers in Michigan and Bavaria now specify conductive fiber grades directly with Toray and Seiren, bypassing regional textile merchants. The disintermediation compresses lead times but concentrates technical service burdens on fiber producers.
Conductive Fibers Market Segmentation
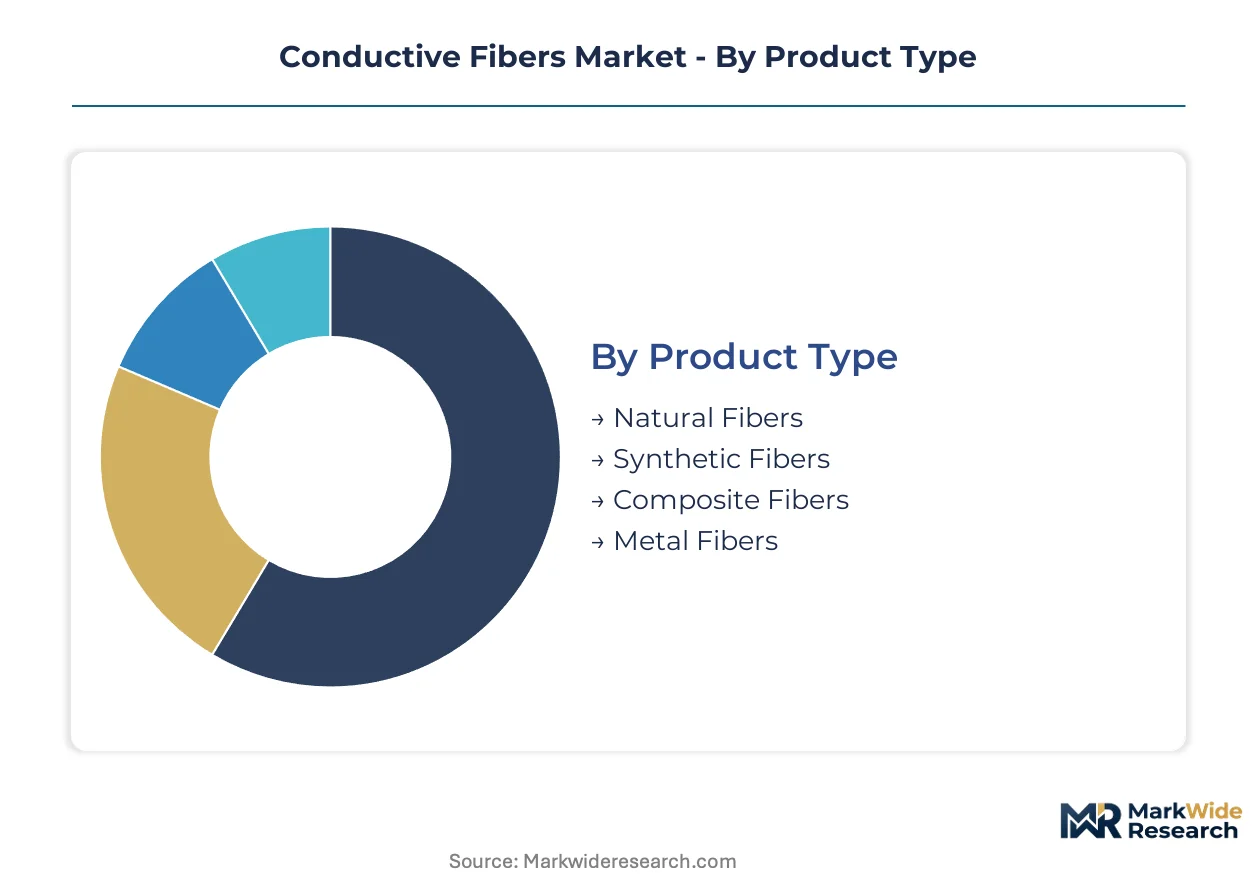
Conductive fiber producers face divergent substitution threats across material platforms, with carbon-based composites displacing metal filaments in weight-sensitive applications while synthetic substrates retain cost advantages in high-volume textile processing. Segmentation clarity determines which technology investments align with end-use certification requirements and regional manufacturing capabilities.
Product Type:
Metal fibers confront the most acute substitution pressure as composite platforms achieve equivalent electromagnetic shielding performance at reduced mass.
- Synthetic Fibers:Polyester and polyamide substrates loaded with carbon black or metallic fillers dominate antistatic workwear and industrial filtration media. Chinese textile clusters in Zhejiang and Jiangsu province consume the largest volumes for automotive seating and chemical processing protective garments, driven by GB standard compliance mandates for electrostatic discharge protection.
- Composite Fibers:Carbon nanotube and graphene-loaded polymer matrices achieve resistivity below 10^6 ohm-cm for aerospace and medical device shielding. Japanese producers leverage electrospinning expertise to supply Boeing and Airbus tier-1 suppliers in Germany and Japan, where weight reduction commands premium positioning in satellite harness contracts.
- Metal Fibers:Stainless steel and copper filaments from NV Bekaert SA operations anchor antistatic and filtration applications requiring mechanical durability.
- Natural Fibers:Cotton and wool substrates with conductive coatings serve niche sustainable textile segments in European fashion applications.
Synthetic fibers retain volume leadership; composite fibers hold the steepest expansion curve.
End User:
Cost tier stratification separates commodity textile applications from certified medical and aerospace segments requiring extensive qualification protocols.
- Textiles:Smart fabrics and antistatic industrial workwear represent the largest addressable base, with automotive seating manufacturers in Michigan and Bavaria specifying conductive grades directly with fiber producers to compress lead times.
- Healthcare:FDA and PMDA-regulated patient monitoring garments in Japan and the United States require biocompatibility certification that imposes 18-24 month approval timelines, filtering out mid-cap suppliers lacking regulatory infrastructure.
- Electrical Components:Flexible circuit substrates and connector textiles for consumer electronics concentrate demand in South Korean and Chinese assembly operations.
- Aerospace:Electromagnetic interference shielding for avionics harnesses represents the highest margin pool, with German and Japanese suppliers qualifying carbon nanotube composites for next-generation platforms.
Textile applications command the largest shipment volumes; healthcare segments generate the highest unit economics.
Application:
Technology maturity varies sharply across use cases, with established antistatic fabrics facing margin compression while emerging e-textile formats require novel manufacturing partnerships.
- Smart Textiles:Sensor-integrated fabrics for fitness and medical monitoring pull fine-denier conductive yarns into wearable ecosystems. South Korean electronics manufacturers collaborate with Seiren Co. plating technologies to achieve signal transmission precision in garment-integrated biometric systems.
- Antistatic Fabrics:Industrial safety textiles for chemical processing and mining operations in Brazil and Saudi Arabia present replacement demand for certified conductive workwear meeting IEC baseline standards.
- Wearable Technology:Consumer electronics integration concentrates in Chinese and Japanese device assembly supply chains.
- E-Textiles:Fashion-forward conductive garments remain commercially constrained by wash durability and comfort trade-offs.
Antistatic fabrics maintain the broadest installed base; smart textiles are climbing the fastest.
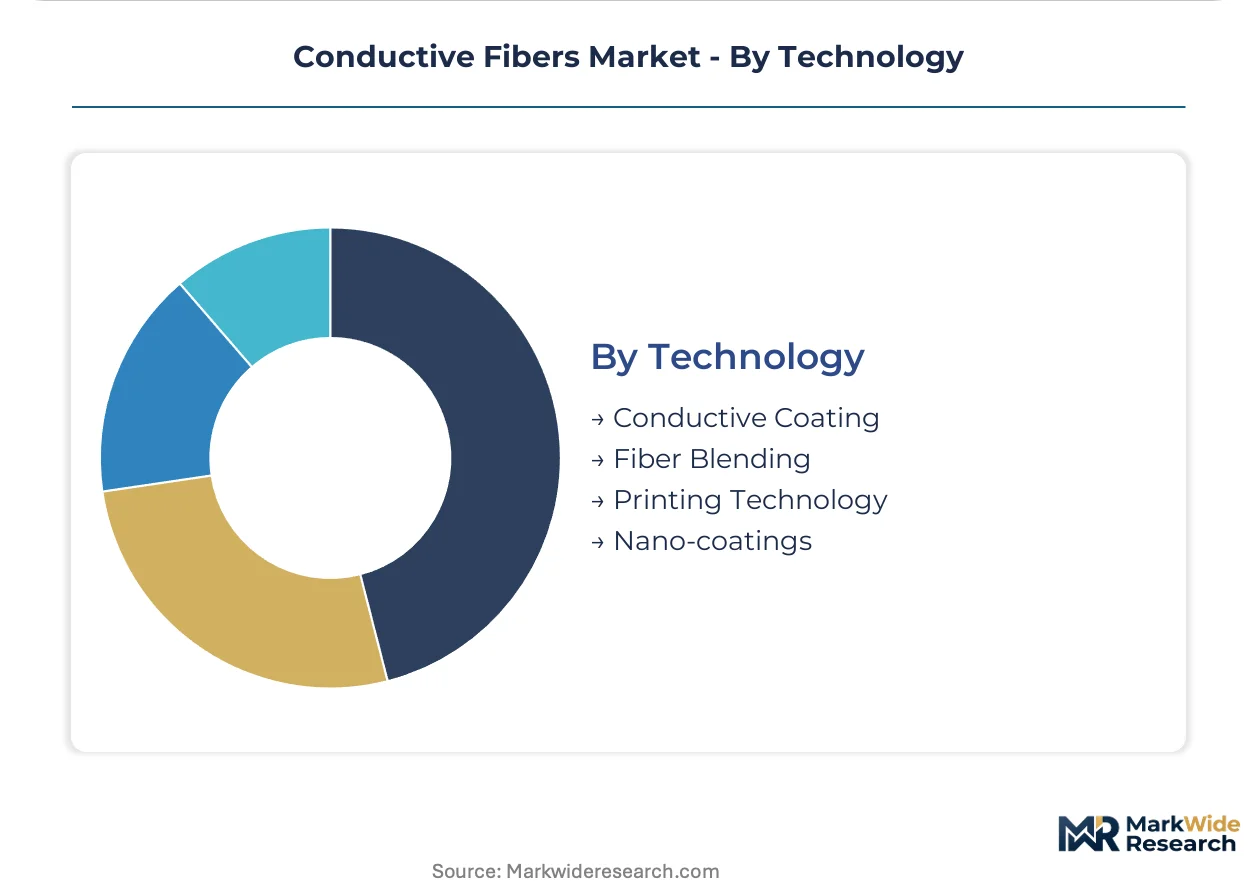
Technology:
Supply concentration in plating and coating equipment creates barriers for producers attempting process transitions.
- Conductive Coating:Electroless nickel-phosphorus and copper plating baths dominate fine-denier yarn production. REACH authorization requirements for nickel compounds and ECHA restrictions on hexavalent chromium chemistries are forcing Italian and Portuguese technical textile clusters to consolidate wet-processing capacity.
- Nano-coatings:Atomic layer deposition and spray-based graphene applications enable thin-film conductivity without compromising textile hand. German automotive suppliers pilot these processes for predictive maintenance sensor integration in assembly plant equipment monitoring contracts.
- Fiber Blending:Melt compounding of conductive fillers into polymer matrices serves high-volume synthetic fiber production.
- Printing Technology:Screen and inkjet deposition of conductive traces enables patterned functionality in e-textile prototypes.
Conductive coating retains process dominance; nano-coatings are gaining share fastest in premium segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MIIT and GB standards for electromagnetic compatibility anchor the dominant geography, with regulatory pressure cascading through Japanese METI directives and South Korean MFDS frameworks across the Asia-Pacific manufacturing belt.
China
Electronics assembly clusters in Shenzhen and Dongguan pull conductive fibers into flexible circuit substrates for consumer devices. MIIT's GB/T standards for electromagnetic compatibility compel domestic suppliers to certify plating chemistries for automotive and telecommunications applications. Zhejiang and Jiangsu province textile operations consume the largest synthetic fiber volumes for antistatic automotive seating.
Japan
PMDA-regulated patient monitoring garments drive fine-denier conductive yarn demand in Osaka and Tokyo medical device corridors. METI's JIS standards for electrostatic discharge protection shape material specifications for industrial safety textiles. Toray Industries leverages Nagoya-area carbon fiber integration to supply Boeing and Airbus tier-1 suppliers with aerospace-grade composites.
South Korea
Seoul Capital Area electronics manufacturers integrate conductive sensors into wearable biometric systems for fitness and medical monitoring. MFDS biocompatibility requirements filter mid-cap suppliers from healthcare textile commercialization. Busan-Ulsan chemical processing hubs anchor plating technology partnerships with Japanese coating specialists.
Germany
Bavarian automotive seating manufacturers specify conductive grades directly with Asian fiber producers to compress lead times. ECHA's REACH authorization requirements for nickel compounds force reformulation of plating baths across technical textile finishing operations. Stuttgart and Munich aerospace clusters qualify carbon nanotube composites for next-generation avionics harness shielding.
United States
FDA device regulations and FCC electromagnetic interference standards impose 18-24 month approval timelines for healthcare textile commercialization. Michigan automotive assembly plants pilot AI-enabled predictive maintenance contracts using conductive fiber sensor networks. Boston and San Francisco medical device corridors concentrate demand for biocompatible patient monitoring fabrics.
Conductive Fibers Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with the upper tier commanding carbon fiber-polymer platforms and electrospinning expertise while mid-cap players concentrate on plating and coating process refinement. The structure rewards backward integration into polymer chemistry and captive supply of conductive fillers. Three archetypes dominate: diversified materials conglomerates with textile-electronics crossovers, pure-play conductive fiber specialists with proprietary metallization technologies, and metal fiber producers anchored in stainless steel and copper filament operations. Competitive moves center on capacity consolidation in European wet-processing clusters and technology licensing partnerships targeting India's PLI scheme for technical textiles.
Among diversified Japanese producers, Toray Industries and Kuraray Co Ltd exemplify the integrated-materials archetype through their control of upstream polymer and carbon fiber assets. NV Bekaert SA represents the metal fiber specialist tier with its European-rooted stainless steel and copper filament operations. Seiren Co. Ltd. occupies a position within the precision-coating specialist segment, leveraging proprietary plating technologies for fine-denier yarn applications.
| Leading Market Players |
|---|
| Kuraray Co Ltd |
| Laird Performance Materials |
| Toray Industries |
| Eeonyx Corporation |
| Hitek Electronic Materials Ltd. |
| NV Bekaert SA |
| Seiren Co. Ltd. |
| Statex Produktions & Vertriebs GmbH |
| Covestro AG |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts between Japanese carbon fiber producers and German aerospace tier-1 suppliers lock in multi-year price visibility while securing allocation priority for conductive composite grades. These arrangements concentrate pricing power among electrospinning-capable manufacturers in Japan and China, compressing margin flexibility for Western plating specialists exposed to London Metal Exchange volatility.
Pricing Analysis
Price spreads between Japanese aerospace-grade composites and Chinese synthetic fiber commodities span a factor of ten or more, reflecting certification tier divergence. Three-tier pricing structure across aerospace-certified, automotive-industrial, and basic antistatic levels separates Toray's satellite harness contracts from Zhejiang province automotive seating volumes. Pricing pressure stems from copper-nickel plating chemistry reformulation costs under REACH nickel authorization requirements. Automotive OEM procurement teams in Bavaria and Michigan exhibit the highest price sensitivity, while PMDA-regulated medical device developers absorb premium positioning for biocompatible fine-denier yarns.
Supply Chain Analysis
Inventory buffers for carbon nanotube feedstock stretch to six months or more given single-source dependence on Chinese chemical vapor deposition capacity. Supply concentrates in Japan, China, and South Korea for electrospinning equipment and conductive polymer compounding, with German automotive buyers drawing from Asian fiber producers through direct mill-to-OEM channels. Raw material dependencies center on acrylonitrile precursor for carbon fiber, copper cathode for metallization baths, and graphene nanoplatelets for composite loading. Tariff exposure on Chinese-origin carbon materials threatens cost structures for European textile finishers. Distribution runs through consolidated technical textile clusters in Italy and Portugal that amortize REACH compliance investments across pooled wet-processing capacity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward automotive and aerospace OEMs as direct contracting fragments traditional distributor channels, with German and Japanese manufacturers consolidating specification authority over conductive fiber grades.
For Market Incumbents: Fortify backward integration into polymer chemistry and captive carbon nanotube supply to defend against composite fiber substitution threatening metal filament positions. Anchor capacity expansion in Nagoya-area carbon fiber platforms where Toray leverages integrated assets. Prioritize FDA and PMDA certification infrastructure investments to filter mid-cap competitors from healthcare textile commercialization. For New Entrants and Emerging Players: Lead with nano-coating technology partnerships targeting India's PLI scheme for technical textiles, where production-linked incentives attract plating and coating transfers from Japanese specialists. Brazil and Saudi Arabia chemical processing sectors present the most penetrable white-space for certified antistatic workwear. Pursue AI-enabled predictive maintenance sensor integration as the go-to-market angle with German automotive assembly plants. For Investors and Strategic Acquirers: Electrospinning-capable mid-tier Japanese producers with aerospace qualification represent the priority acquisition archetype for technology-hungry Western materials conglomerates. Long-term viability hinges on carbon-based composite platforms displacing metal filaments across the analysis window. Watch for ECHA restriction finalization on hexavalent chromium chemistries as the signal for consolidation timing in European wet-processing clusters.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carbon Nanotube Supply | Toray's Nagoya platform demonstrates how captive filler production secures aerospace contract margins against commodity volatility. |
| REACH-Compliant Plating Chemistry Reformulation | Italian and Portuguese cluster consolidation amortizes compliance costs while filtering out sub-scale European finishers. |
| Direct Mill-to-OEM Contracting | Bavarian automotive seating manufacturers bypass distributors to compress lead times with Seiren and Toray specification teams. |
| India PLI Scheme Technology Transfer | Japanese coating specialists leverage production-linked incentives to establish Busan-Ulsan chemical corridor partnerships. |
| AI-Enabled Predictive Maintenance Sensor Networks | Michigan automotive plants pilot conductive fiber integration with edge computing platforms for equipment monitoring contracts. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across primary fieldwork, including textile finishing plant managers in Italy and Portugal, procurement leads at German automotive seating manufacturers, plating technology specialists at Japanese coating operations, and biomedical engineers developing PMDA-regulated patient monitoring garments. Secondary validation drew from ECHA restriction proposal documentation, MIIT GB standard filings, FDA 510(k) device submissions, and customs trade data for carbon fiber and conductive polymer flows. Bottom-up volume modeling triangulated against top-down market sizing from electrospinning equipment capacity disclosures.
Across the analysis window, the forecasting framework modeled segmentation dimensions including material platform (synthetic, composite, metal, natural), end-use certification tier (aerospace, healthcare, automotive, industrial), and technology process (conductive coating, nano-coating, fiber blending, printing). CAGRs were derived from elasticity-adjusted demand projections tied to GB standard compliance mandates and EU Green Deal textile sustainability timelines. Industry-specific inputs included carbon nanotube loading rates for aerospace shielding specifications and electrospinning cleanroom capex intensity curves.
The analysis sits within stated boundaries; outcomes outside sustained REACH enforcement, continued MIIT GB standard expansion, or stable copper-nickel price corridors would require recalibration. Forecasts reflect documented assumptions regarding electrospinning talent migration patterns and plating chemistry substitution timelines. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Synthetic Fibers
Glass Fiber Yarn Market
Synthetic Fibers
Rayon Fibers Market
Synthetic Fibers
US Textile Market
Synthetic Fibers
North America High Performance Fibers Market
Synthetic Fibers
Nylon Tire Cord Fabrics Market
Synthetic Fibers
Synthetic Fiber Market
Synthetic Fibers
Extruded PLA Fiber Market
Synthetic Fibers
Polybenzoxazole Fibers Market
Synthetic Fibers
High End Synthetic Suede Market
Synthetic Fibers
Regenerated Fibers Market
Synthetic Fibers
Polyester Straps Market
Synthetic Fibers
Kevlar Fiber Market
Synthetic Fibers
High-Strength Polyester Thread Market
Synthetic Fibers
Polyester Strap for Manual Grade Market
Synthetic Fibers
Global Acrylic Fibers Market
Synthetic Fibers
Neoprene Fabric Market