
 Para-Virtualization Market | 2026-2036
Para-Virtualization Market Size, Share, and Industry Trends Forecast 2026-2036
Para-Virtualization Market Analysis
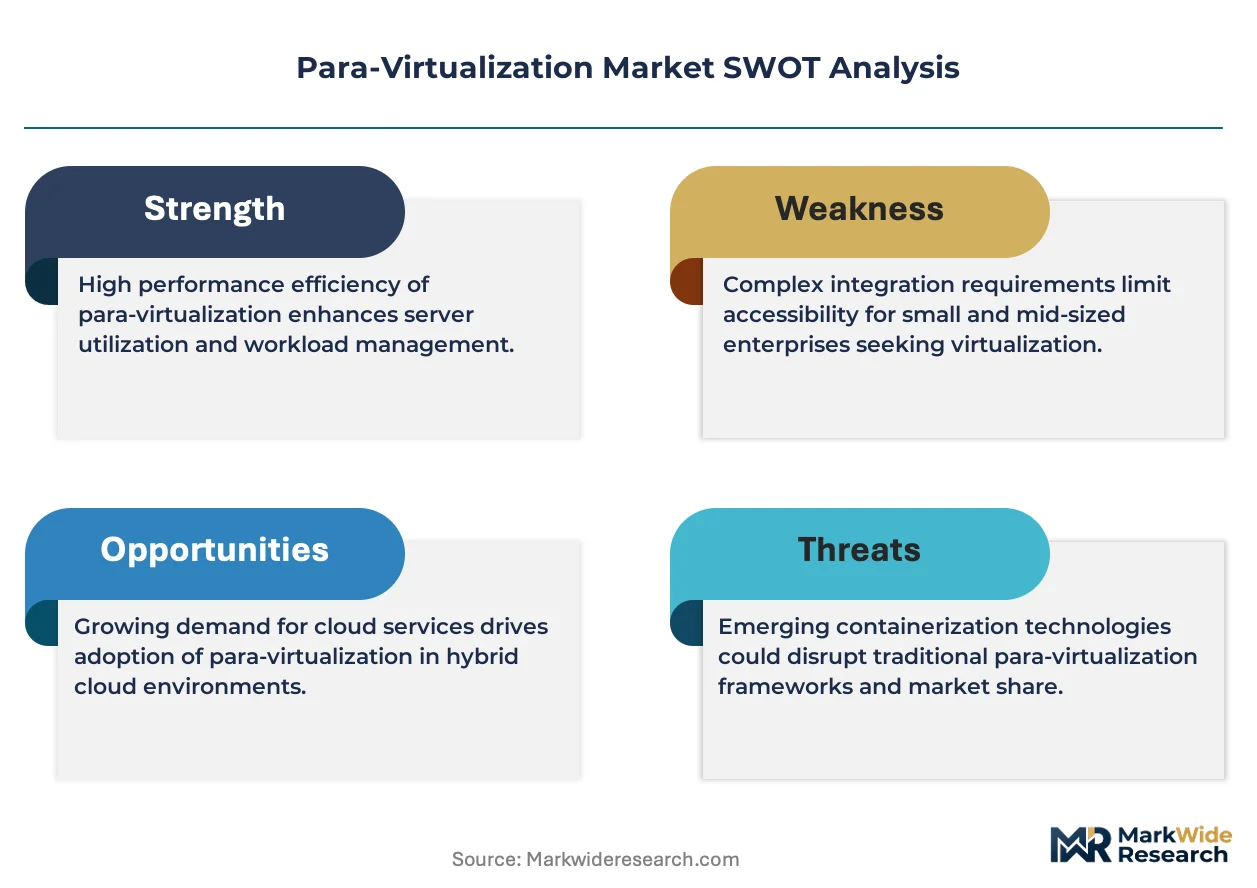
Software-defined networking overlays is recalibrating what enterprises purchase in the para-virtualization stack. VMware leverages its hypervisor heritage to anchor premium data center contracts across North American financial services. Red Hat sustains open-source momentum by competing on hybrid cloud portability for Linux-native workloads. Amazon.com Inc. dominates cloud-native para-virtualization through its Nitro system architecture, which offloads virtualization functions to dedicated hardware.
Para-virtualization is a virtualization technique where the guest operating system is modified to communicate directly with the hypervisor through optimized APIs, eliminating the overhead of full hardware emulation while requiring kernel-level paravirt_ops patches for x86 and ARM architectures. Its primary purpose is to maximize host resource efficiency for I/O-intensive workloads in consolidated server environments. Cloud-based deployments are capturing the fastest expansion as enterprises migrate legacy VMware estates to elastic infrastructure. Large enterprises retain the deepest margin pools due to complex multi-hypervisor environments requiring specialized consulting services. Data center management applications lead volume, though infrastructure virtualization is accelerating fastest at the edge.
FCC guidelines on critical infrastructure cybersecurity and the EU Cybersecurity Act's Common Criteria certification are reshaping procurement standards for virtualized platforms in regulated sectors. ISO 27001 and IEC 62351 frameworks further constrain vendor selection for energy and healthcare deployments. NIST SP 800-53 controls in the United States and Germany's BSI IT-Grundschutz requirements are converging on mandatory hypervisor hardening. Stakeholders must weigh sovereign cloud mandates against the operational complexity of maintaining paravirtualized kernels across heterogeneous compliance regimes.
Market Dynamics
Software-defined networking overlays are recalibrating enterprise purchasing patterns across the para-virtualization stack, forcing vendors to bundle hypervisor capabilities with programmable infrastructure orchestration rather than selling isolated licenses.
Growth Catalysts
- EU Cybersecurity Act certification mandates:Common Criteria requirements for virtualized infrastructure are accelerating replacement cycles in regulated European sectors, particularly energy and healthcare deployments.
- Industrial automation cloud migrations:German automotive manufacturers are consolidating factory-floor virtualization estates to support connected vehicle development pipelines and predictive maintenance workloads.
- Nitro-style hardware offloading:Dedicated silicon for virtualization functions is eliminating CPU overhead penalties that previously constrained I/O-intensive workload consolidation ratios.
Market Restraints
- Kernel modification dependencies:Paravirt_ops patching requirements for x86 and ARM architectures create version-fragility that lengthens enterprise qualification timelines and raises support costs.
- Specialized hypervisor engineering talent scarcity:Deep expertise in KVM and Xen internals concentrates within cloud-native vendors, constraining enterprise self-managed deployment options.
- Proprietary management tool ecosystems:VMware's vSphere control plane dominance creates switching friction that locks mid-market buyers into premium pricing tiers despite open-source alternatives.
Strategic Opportunities
- Edge infrastructure virtualization:Manufacturing sites and telecommunications central offices are deploying lightweight para-virtualized stacks for sub-10ms latency workloads that public cloud cannot satisfy.
- BSI IT-Grundschutz compliance services:German federal contracting requirements are creating a captive market for hypervisor hardening consultancies serving Mittelstand industrial clients.
- Hybrid cloud portability tooling:Workload migration between on-premises KVM estates and AWS Nitro-based instances is absorbing vendor investment in abstraction layer standardization.
Industry Challenges
- Multi-hypervisor certification complexity:Maintaining Common Criteria and ISO 27001 attestations across heterogeneous paravirtualized environments consumes 40-60% of enterprise security engineering capacity.
- Legacy VMware estate technical debt:Custom vSphere extensions and third-party integrations require surgical extraction before cloud-native para-virtualization migration, extending project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Para-Virtualization Market |
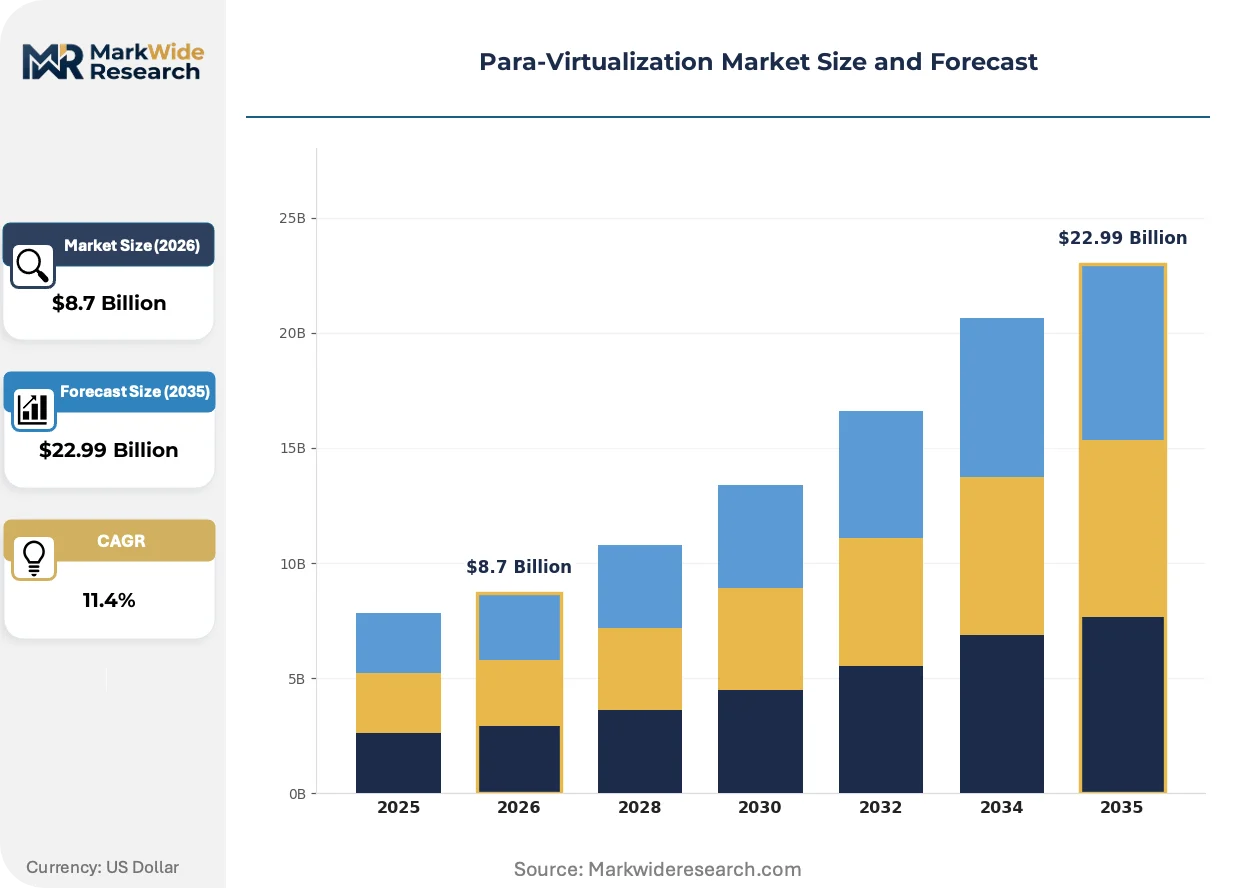
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Managed Services End User: SMEs, Large Enterprises, Government Institutions, Educational Organizations Service Type: Support Services, Consulting Services, Training Services, Maintenance Services Application: Data Center Management, Infrastructure Virtualization, Application Hosting, Load Balancing |
| Companies Covered | VMware, Oracle, Red Hat, Citrix, Microsoft, Google LLC, Amazon.com Inc., Huawei Technologies, Proxmox Server Solutions GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Para-Virtualization Market Emerging Trajectories
Kernel-bypass networking and hardware-rooted trust architectures are compressing the functional boundary between hypervisor and host silicon, reshaping how vendors differentiate at the infrastructure layer.
SmartNIC-based virtualization offloading is absorbing CPU cycles previously consumed by software-emulated device drivers. Financial services firms in North America are deploying these adapters at scale for high-frequency trading and risk calculation workloads. This silicon migration is compressing the addressable market for pure-software hypervisor licenses while expanding attach rates for integrated hardware-software bundles.
The EU Cybersecurity Act's Common Criteria certification pathways are mandating formal verification for hypervisor code bases used in critical national infrastructure. Energy utilities across Germany, France, and the Netherlands are now requiring EAL4+ attestations for any virtualization layer touching SCADA systems. Vendors without pre-certified offerings are losing procurement eligibility regardless of technical performance.
Cloud repatriation patterns among large European manufacturers are shortening hypervisor evaluation cycles from 18-24 months to 6-9 months. Sourcing teams are prioritizing portability certifications and API compatibility over feature-depth comparisons. This compression is most visible in German automotive supply chains, where just-in-time production requirements demand rapid infrastructure elasticity without cloud dependency.
Para-Virtualization Market Segmentation
Para-virtualization procurement patterns diverge sharply across deployment models and end-user scale, with kernel modification requirements and compliance mandates reshaping how buyers bundle services. Understanding these fault lines clarifies where vendor investment concentrates and which segments absorb premium pricing.
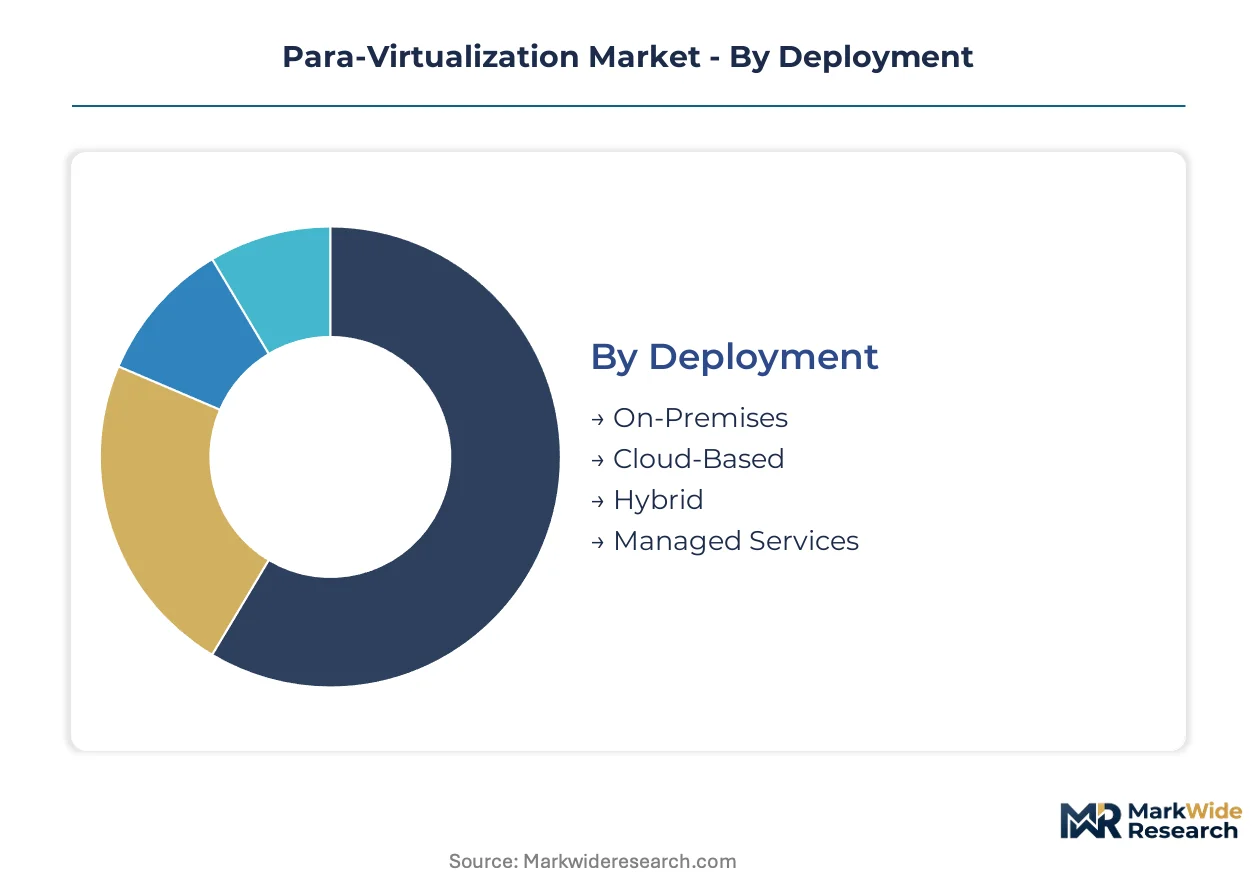
Deployment:
Supply concentration in cloud-native hypervisor engineering tilts commercial leverage toward providers with dedicated silicon programs.
- On-Premises:Traditional datacenter installations requiring kernel-level paravirt_ops modifications for x86 and ARM hosts. German automotive manufacturers and energy utilities in the Netherlands favor this model for air-gapped SCADA compliance under EU Cybersecurity Act mandates.
- Cloud-Based:Elastic consumption of para-virtualized instances through hardware-offloaded architectures. Financial services firms in the United States deploy Nitro-style virtualization for high-frequency trading workloads demanding sub-microsecond latency.
- Hybrid:Split workloads spanning owned infrastructure and public cloud with unified orchestration layers. Portability certifications dominate procurement criteria as enterprises hedge sovereign cloud requirements.
- Managed Services:Third-party operation of para-virtualized estates including kernel patching and hardening. Mittelstand industrial clients in Germany source these to satisfy BSI IT-Grundschutz without internal hypervisor expertise.
On-Premises absorbs the bulk of installed capacity; Cloud-Based is expanding most quickly.
End User:
Customer scale determines whether procurement optimizes for unit economics or compliance depth.
- SMEs:Mid-market buyers constrained by VMware vSphere switching friction and premium pricing tiers. These organizations increasingly evaluate open-source KVM alternatives bundled with managed service overlays.
- Large Enterprises:Complex multi-hypervisor environments requiring specialized consulting for legacy estate extraction. These buyers retain deepest margin pools through multi-year infrastructure transformation contracts.
- Government Institutions:Public sector deployments mandating Common Criteria EAL4+ certification for critical infrastructure. Procurement eligibility hinges on pre-certified hypervisor code bases regardless of technical performance benchmarks.
- Educational Organizations:Research computing clusters utilizing para-virtualization for HPC workload isolation. Budget constraints favor community-supported Xen or KVM distributions over commercial licenses.
Large Enterprises command the greatest service attach rates; Government Institutions impose the steepest certification barriers.
Service Type:
Margin capture shifts from license revenue toward recurring service streams as kernel fragility extends qualification timelines.
- Support Services:Tiered response commitments for paravirt_ops patching conflicts and version compatibility issues. German federal contractors require 24/7 escalation paths for production hypervisor incidents.
- Consulting Services:Migration architecture for VMware-to-KVM transitions and hybrid cloud portability design. These engagements absorb 40-60% of enterprise security engineering capacity during multi-hypervisor certification.
- Training Services:Certification programs for KVM and Xen internals addressing specialized hypervisor engineering scarcity. Cloud-native vendors concentrate this expertise internally, constraining external training supply.
- Maintenance Services:Sustained kernel hardening and vulnerability management for regulated deployments. Energy utilities across France and the Netherlands contract these separately from initial installation.
Consulting Services generates the highest per-engagement value; Maintenance Services delivers the most predictable recurring revenue.
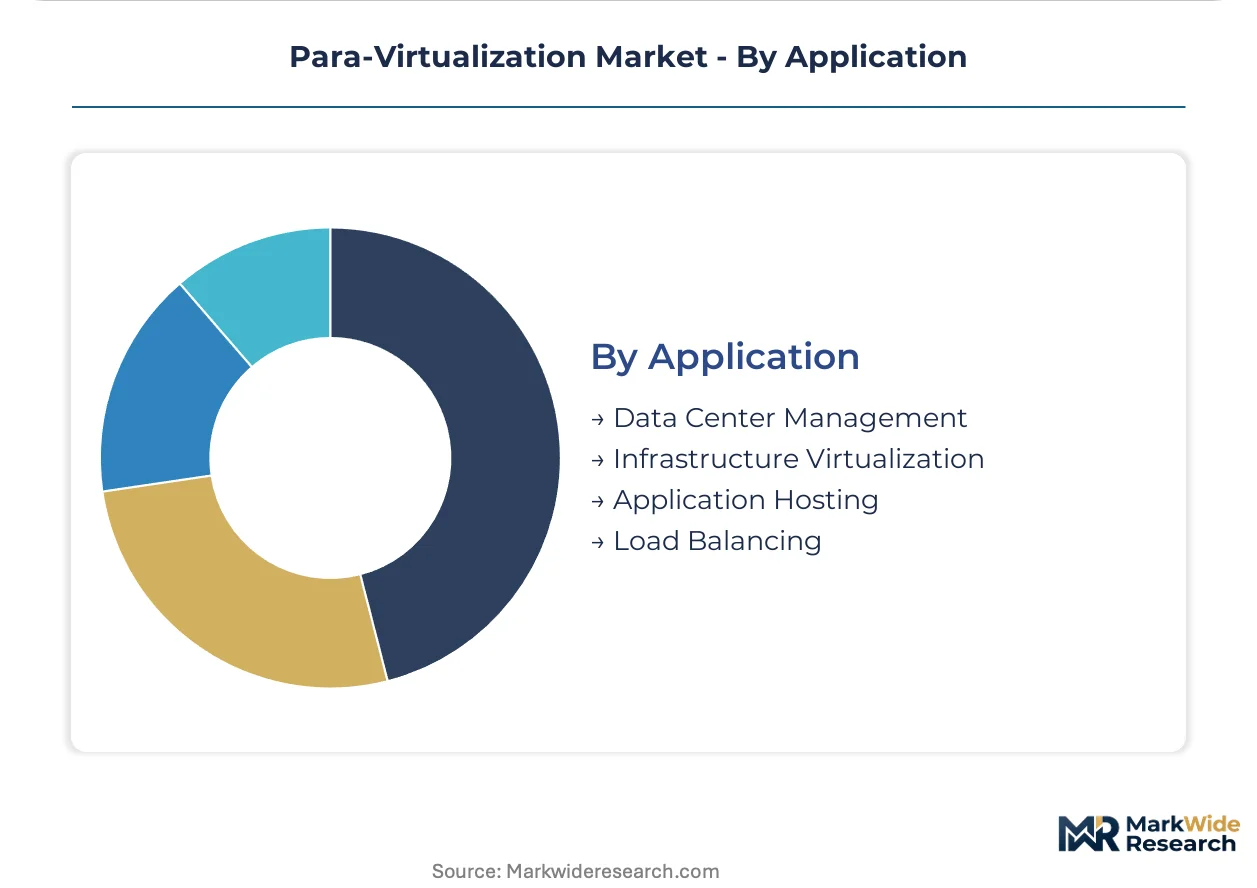
Application:
Workload characteristics dictate whether para-virtualization delivers measurable efficiency gains over full virtualization alternatives.
- Data Center Management:Consolidation of heterogeneous server estates through unified hypervisor control planes. This application leads segment volume through legacy infrastructure replacement cycles.
- Infrastructure Virtualization:Edge deployment of lightweight para-virtualized stacks for manufacturing sites and telecommunications central offices. Sub-10ms latency requirements here exclude public cloud dependency.
- Application Hosting:Container-adjacent isolation for multi-tenant SaaS platforms requiring stronger security boundaries than namespace separation. I/O-intensive database workloads show measurable throughput advantages.
- Load Balancing:Traffic distribution across paravirtualized instances with direct hypervisor API communication. SmartNIC offloading eliminates CPU overhead penalties previously constraining consolidation ratios.
Data Center Management retains the largest installed base; Infrastructure Virtualization is climbing the fastest as edge deployments multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors European para-virtualization demand through its dense concentration of automotive engineering headquarters migrating factory-floor systems to cloud-native infrastructure.
United States
Financial services firms in New York and Chicago deploy Nitro-style hardware offloading for high-frequency trading workloads demanding sub-microsecond latency. FCC guidelines on critical infrastructure cybersecurity reshape procurement standards for virtualized platforms across energy and healthcare sectors. Silicon Valley cloud providers concentrate engineering talent for KVM and Xen internals development.
Germany
Industrial automation cloud migrations by automotive manufacturers in Bavaria and Baden-Württemberg consolidate factory-floor virtualization estates for connected vehicle pipelines. BSI IT-Grundschutz requirements mandate hypervisor hardening for federal contractors serving Mittelstand industrial clients. Berlin hosts compliance consultancies specializing in Common Criteria certification for energy utilities.
France
Energy utilities in the Île-de-France region require EAL4+ attestations for virtualization layers touching SCADA systems under EU Cybersecurity Act mandates. EDF and Engie procurement teams prioritize pre-certified hypervisor code bases regardless of technical performance benchmarks. Lyon clusters host SmartNIC integration specialists serving financial risk calculation workloads.
Netherlands
Amsterdam data center operators expand para-virtualized edge deployments for sub-10ms latency manufacturing workloads that public cloud cannot satisfy. Rotterdam port logistics firms adopt lightweight para-virtualized stacks for predictive maintenance systems. The Hague hosts regulatory compliance firms navigating NIS2 Directive certification pathways for critical infrastructure.
China
MIIT standards for virtualization security drive domestic hypervisor certification programs for state-owned enterprise data center consolidation. Shenzhen cloud providers develop hardware-rooted trust architectures for financial services deployments. Beijing research institutes advance kernel-bypass networking for high-performance computing clusters.
Para-Virtualization Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the para-virtualization stack, with silicon-integrated virtualization functions displacing pure-software licensing models. The vendor base stratifies into three tiers: cloud-native hyperscalers with dedicated hardware programs, enterprise software incumbents with hypervisor heritage, and open-source distributors competing on hybrid portability. Consolidation pressure intensifies as kernel modification dependencies lengthen enterprise qualification timelines. Dominant competitive moves include strategic partnerships for SmartNIC integration and geographic expansion of compliance-certified service delivery.
Within the cloud-native tier, Amazon.com Inc. exemplifies hardware-offloaded architecture dominance, while VMware anchors premium data center contracts through vSphere control plane integration. Red Hat occupies a position bridging open-source momentum with enterprise support structures for Linux-native workloads.
| Leading Market Players |
|---|
| VMware |
| Oracle |
| Red Hat |
| Citrix |
| Microsoft |
| Google LLC |
| Amazon.com Inc. |
| Huawei Technologies |
| Proxmox Server Solutions GmbH |
| Others |
Supply Flow & Price Mechanics
Kernel-level hypervisor engineering talent concentration in Germany's Stuttgart-Berlin corridor feeds directly into pricing-tier spreads, with labor-cost differentials between certified security consultants and commodity virtualization administrators widening premium service margins against economy license tiers.
Pricing Analysis
Throughput-guaranteed uptime pricing anchors enterprise contracts, with financial services firms in New York and Chicago paying premium tiers for sub-microsecond latency assurances on Nitro-style hardware-offloaded instances. Certification grade separates EAL4+ Common Criteria offerings from uncertified open-source alternatives, while volume scale discounts concentrate in multi-year government procurement bundles. Pricing pressure stems from SmartNIC integration costs compressing pure-software license values, with mid-market SMEs showing greatest price sensitivity as VMware vSphere switching friction locks them into premium tiers despite KVM alternatives.
Supply Chain Analysis
Common Criteria certification gating restricts qualified vendor pools, with hypervisor code base formal verification capabilities concentrating in the United States, Germany, and China. Silicon foundry capacity for SmartNIC production draws from Taiwan and South Korea, while kernel development expertise rests on specialized engineering clusters in Silicon Valley and Shenzhen. Single-source vulnerability runs through TSMC's advanced node allocation for virtualization offload chips. Distribution runs through direct enterprise sales for large accounts and certified managed service providers for Mittelstand industrial clients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The para-virtualization market sits in a hardware-offloading transition phase, with Nitro-style silicon virtualization displacing legacy software-emulated device drivers and reshaping competitive economics across the stack.
For Market Incumbents: Anticipate margin compression in pure-software hypervisor licenses as SmartNIC bundles capture pricing power. Defend position by deepening vertical integration into silicon partnerships with Taiwan-based adapter manufacturers, and accelerate EAL4+ certification investment for EU Cybersecurity Act compliance before procurement eligibility windows narrow. For New Entrants and Emerging Players: Begin with edge infrastructure virtualization white space in German manufacturing sites and Netherlands port logistics, where sub-10ms latency requirements exclude hyperscale cloud dependency. Target managed service overlays for BSI IT-Grundschutz compliance as the most penetrable segment, with kernel hardening subscription models as the primary go-to-market angle. For Investors and Strategic Acquirers: The window for entry favors compliance-certified consultancies with captive hypervisor engineering talent. Long-term viability hinges on hybrid cloud portability tooling acquisition, with KVM-to-Nitro migration specialists representing the optimal target archetype. Watch cloud repatriation announcement velocity among European automotive manufacturers as the signal for infrastructure transformation investment inflection.| Strategic Initiative | Industry Significance |
|---|---|
| SmartNIC Integration Partnership | Hardware offloading eliminates CPU overhead penalties for I/O-intensive financial services workloads. |
| Common Criteria EAL4+ Certification | Pre-certified code bases unlock EU energy utility procurement under Cybersecurity Act mandates. |
| Hybrid Cloud Portability Tooling | Abstraction layer standardization absorbs vendor investment for KVM-to-Nitro workload migration. |
| Edge Infrastructure Virtualization | Lightweight para-virtualized stacks serve manufacturing sub-10ms latency requirements public cloud cannot satisfy. |
| Managed Compliance Services | Kernel hardening subscriptions address Mittelstand BSI IT-Grundschutz requirements without internal expertise. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, with primary interviews conducted among data center infrastructure directors, hypervisor platform engineers, cloud procurement officers, and managed service provider executives. FCC guidelines, EU Cybersecurity Act implementation documents, and BSI IT-Grundschutz technical specifications supplemented hyperscaler capex disclosures and enterprise software SEC filings. Bottom-up installation base estimates triangulated against top-down addressable market sizing.
Shipment volume and value outputs reconcile across the analysis window through segmented modeling of deployment mode, end-user scale, service type, and application workload characteristics. CAGRs derive from elasticity-adjusted adoption curves incorporating kernel modification dependency resolution timelines and certification qualification cycle lengths. SmartNIC attach rate assumptions and sovereign cloud mandate penetration feed industry-specific forecast inputs.
Underlying measurement precision varies by segment; cloud-based deployments carry tighter precision than on-premises legacy estate transformations due to disclosed hyperscaler utilization metrics. Forecasts reflect documented assumptions regarding hardware offloading adoption velocity and EU regulatory enforcement consistency. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
Asia-Pacific Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
India Virtual Production Market
Virtual Reality (VR) and Augmented Reality (AR)
3D Telepresence Market
Virtual Reality (VR) and Augmented Reality (AR)
AR in Education Market
Virtual Reality (VR) and Augmented Reality (AR)
Wireless AR Glass Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Production Market
Virtual Reality (VR) and Augmented Reality (AR)
Global VR for Medical Market
Virtual Reality (VR) and Augmented Reality (AR)
Europe Virtual Reality (VR) Health Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Prototype Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Augmented and Virtual Reality (AR VR) Market
Virtual Reality (VR) and Augmented Reality (AR)
North America Augmented Reality (AR) and Mixed Reality (MR) Market
Virtual Reality (VR) and Augmented Reality (AR)
US Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
US Augmented and Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
AR and VR Solutions Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality Training Market
Virtual Reality (VR) and Augmented Reality (AR)
UK Virtual Tour Market