
 Virtual Production Market | 2026-2036
Virtual Production Market Size, Share, and Industry Trends Forecast 2026-2036
Virtual Production Market Intelligence
The expansion of virtual production from its core in film production into video game development is realigning the market's center of gravity. Epic Games Inc. leverages its Unreal Engine to dominate the real-time rendering engine segment, influencing both film and gaming pipelines. NVIDIA Corporation sustains its position by providing the essential GPU hardware for complex, high-fidelity rendering tasks. Meanwhile, Autodesk Inc. specializes in a broad suite of software tools for the pre-visualization and asset creation stages of production.
Virtual production is a methodology that merges live-action footage with computer-generated imagery directly on set, in real time. It utilizes technologies like large-format LED walls displaying real-time rendered environments, allowing filmmakers to see the final shot during principal photography. Real-time rendering engines from providers like Epic Games represent the software core of the ecosystem. While film production remains the largest application, video game development and advertising segments represent the fastest-growing areas of adoption.
Data handling for cloud-based workflows falls under regulations like the EU's GDPR, impacting how studios manage assets across borders. Advertising content created with these tools must adhere to standards set by bodies like the US Federal Trade Commission (FTC) and China's SAMR. Stakeholders must decide whether to build in-house capabilities or rely on specialized post-production companies for these services.
Market Dynamics
The convergence of real-time rendering engines from the video game industry with traditional filmmaking workflows is the central force defining the market. This technological fusion allows for unprecedented creative flexibility on set, collapsing pre-production, production, and post-production timelines into a unified process.
Growth Catalysts
- AI-Driven Animation:The integration of artificial intelligence into animation software automates character rigging, motion capture cleanup, and environment generation, significantly reducing labor costs and production time for visual effects studios.
- Live Events Adoption:Demand from the concert and corporate events sector for immersive, interactive backdrops on large-scale LED walls is creating a new, high-volume application area beyond film and television production.
- National Content Initiatives:Government incentives in countries like South Korea and Canada provide tax credits and funding for studios that develop and utilize advanced digital content creation technologies, fostering innovation hubs.
Market Restraints
- High Capital Outlay:The initial investment required for constructing a virtual production stage, including high-resolution LED walls, camera tracking systems, and powerful rendering hardware, presents a significant financial barrier for smaller studios.
- Data Pipeline Latency:Achieving zero-latency, photorealistic rendering on set remains a technical challenge, with large, complex scenes straining data transfer rates and processing power, potentially causing on-set delays.
- Cross-Border Data Governance:The use of cloud-based asset management and collaborative workflows is complicated by data sovereignty and privacy regulations, such as the EU's GDPR, which governs the transfer of personal and proprietary data.
Strategic Opportunities
- Enterprise Sector Expansion:Architectural visualization, automotive design, and aerospace engineering represent significant growth opportunities, using virtual production for collaborative design reviews and realistic simulations before physical prototyping.
- Standardization Initiatives:The development of open-source standards for 3D asset formats and scene descriptions, such as Universal Scene Description (USD), creates opportunities for greater interoperability between different software tools.
- Advertising Market Penetration:The fast-paced advertising industry in markets like Brazil and India offers a substantial opportunity for creating high-quality, visually compelling commercials with rapid turnaround times.
Industry Challenges
- Specialized Talent Scarcity:A critical shortage exists for professionals who possess a hybrid skillset combining film production knowledge with expertise in real-time game engines like Unreal Engine, creating a bottleneck for studio expansion.
- Legacy System Integration:Integrating new real-time pipelines with established, decades-old post-production workflows and asset management systems within large studios is complex and often requires custom-built software bridges.
- Intellectual Property Licensing:Navigating the complex licensing agreements for game engine software, digital assets, and proprietary plug-ins creates administrative overhead and legal risks for production companies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Virtual Production Market |
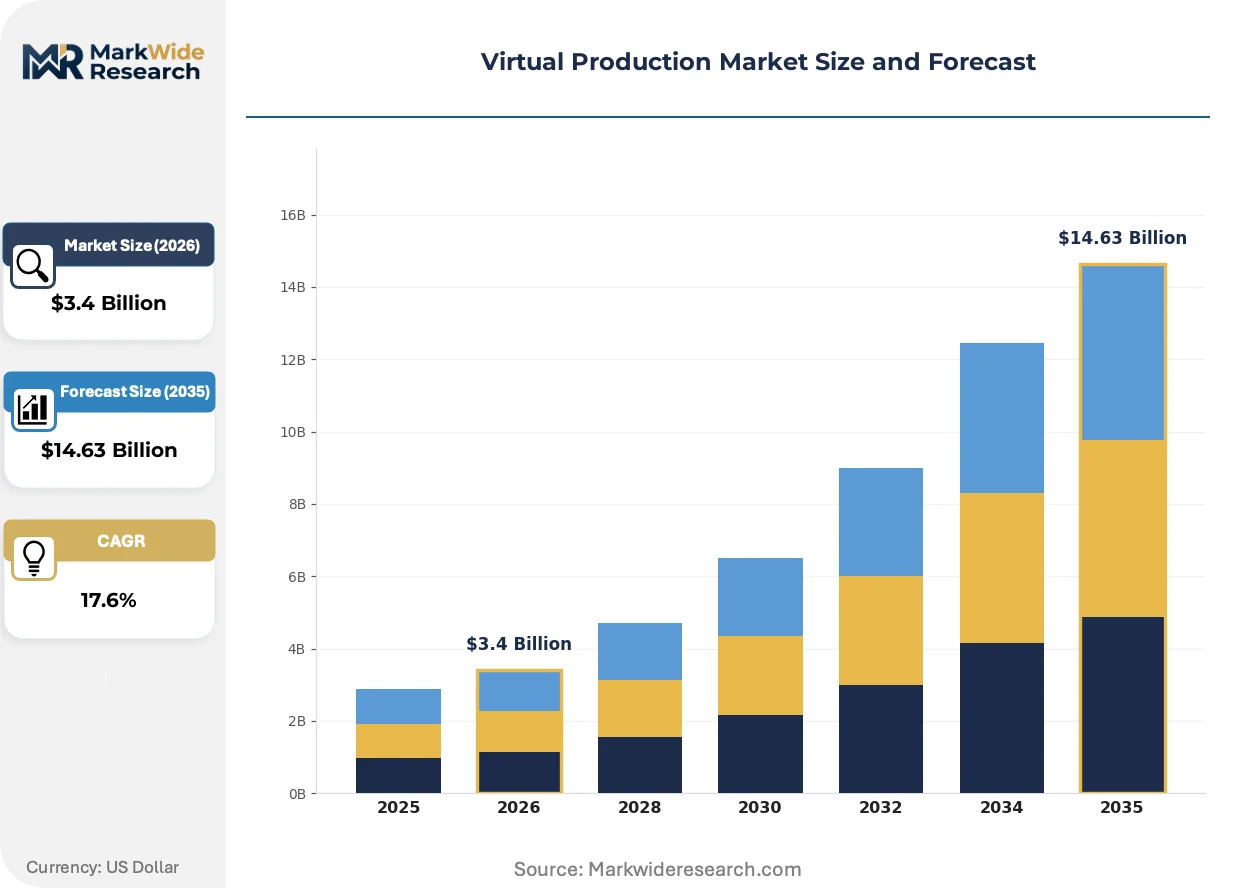
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $14.63 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Camera Tracking Systems, LED Walls, Real-time Rendering Engines, Motion Capture Systems, Virtual Cameras Technology: Augmented Reality, Photorealistic Rendering, LED Display Technology, Cloud Computing, AI-driven Animation Application: Film Production, Advertising, Video Game Development, Live Events, Architectural Visualization End User: Film Studios, Post-production Companies, Game Developers, Event Management Firms, Design Consultancies |
| Companies Covered | Autodesk Inc., Mo-Sys Engineering Ltd., Epic Games Inc., Sony Group Corporation, Disguise Technologies Limited, NVIDIA Corporation, HTC Corporation, Technicolor Creative Studios SA, Adobe Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Virtual Production Market Strategic Shifts & Innovations
The industrialization of virtual production is moving the methodology from bespoke, high-end projects toward more accessible, scalable workflows. This shift is driven by software abstraction, hardware commoditization, and the codification of best practices, enabling wider adoption across different budget levels.
Generative AI for asset creation is a key technological evolution, automating the production of 3D models, textures, and environments from simple text prompts. Film studios and game developers are rapidly adopting these tools to accelerate pre-production and conceptualization phases. This technology is absorbing significant portions of the manual labor previously required for digital artistry and asset library creation.
China's State Administration for Market Regulation (SAMR) is enforcing stricter rules on digital advertising, including claims made via photorealistic computer-generated imagery. This compels brands using virtual production for commercials to ensure that digital assets do not misrepresent product functionality or appearance. The advertising segment is most affected, now implementing rigorous validation processes to align visual depictions with product realities.
A notable behavioral change involves large media companies building permanent, in-house virtual production stages instead of renting third-party facilities on a project basis. This strategy displaces the traditional outsourcing model where specialized post-production houses handled these services. This trend is most prominent in production hubs like Los Angeles and London, as studios seek greater control over pipelines and intellectual property.
Virtual Production Market Segmentation
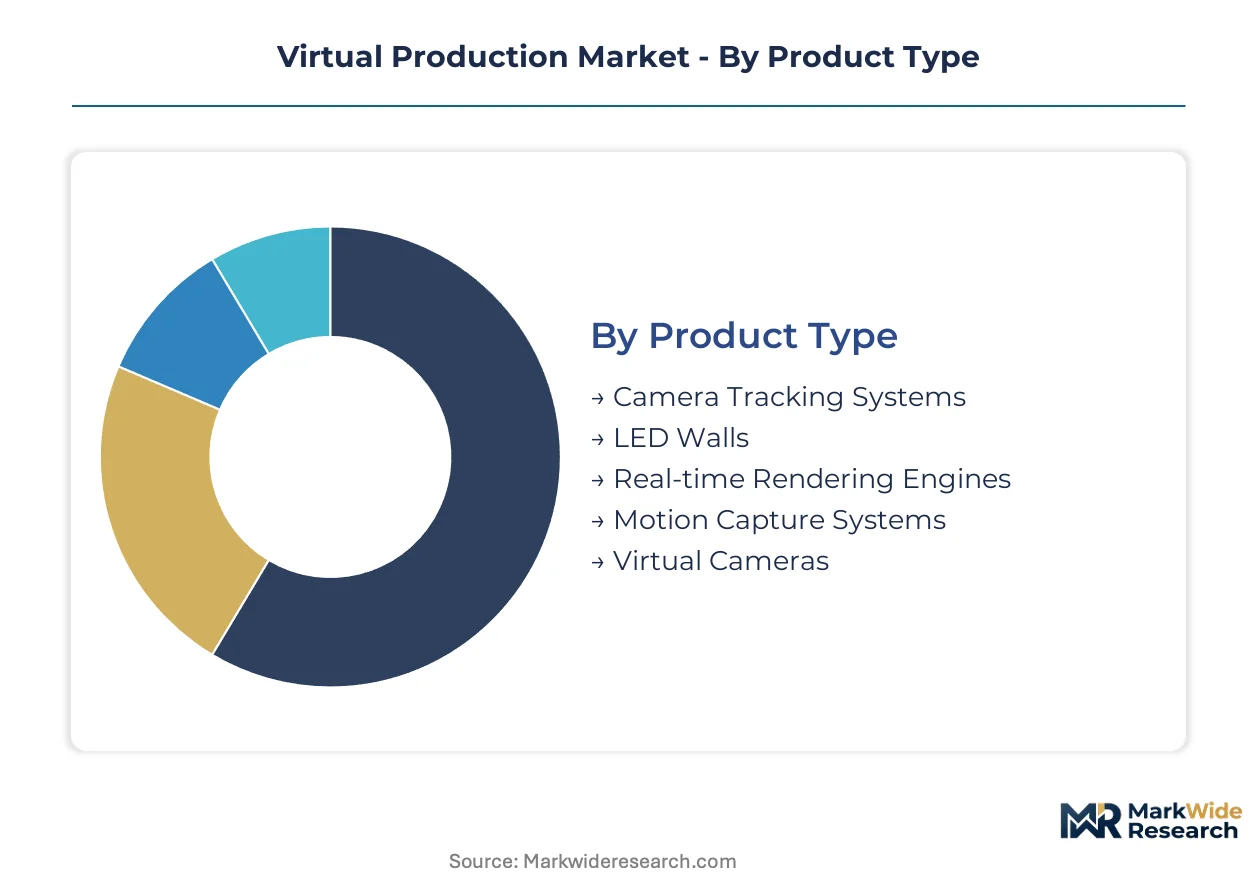
Segmentation provides a granular view of the Virtual Production Market, highlighting how different components and applications contribute to its overall valuation. Understanding these distinctions helps stakeholders identify areas of concentrated investment and emerging demand. This analysis categorizes the market by the core tools, underlying technologies, diverse applications, and primary end-users driving adoption.
Product Type:
The product type segmentation reveals a clear distinction between high-volume foundational components and specialized, premium-tier solutions that enhance creative control.
- LED Walls:These large-format displays project real-time rendered environments, forming the immersive backdrop for virtual production. Demand concentrates in film production and live events, where visual fidelity directly impacts audience engagement and creative output.
- Real-time Rendering Engines:Software platforms like Unreal Engine process complex 3D graphics to generate virtual environments instantaneously. Film studios and game developers leverage these engines to accelerate pre-visualization and achieve photorealistic visuals on set.
- Camera Tracking Systems:These systems precisely monitor camera movement, integrating physical camera data with virtual environments for seamless compositing.
- Motion Capture Systems:Equipment captures physical movements of actors or objects, translating them into digital animation for character performance.
- Virtual Cameras:Digital camera tools simulate traditional camera operation within virtual spaces, empowering directors to scout and frame shots in real-time.
Mature deployment sits with Real-time Rendering Engines. Newer deployment is concentrated in LED Walls.
Technology:
Technology segmentation illustrates how specific innovations underpin diverse applications across the virtual production workflow, from visual fidelity to operational efficiency.
- AI-driven Animation:This technology automates complex animation tasks, including character rigging, motion capture cleanup, and environment generation. It significantly reduces labor costs and production time for visual effects studios, accelerating content creation.
- Photorealistic Rendering:Advanced algorithms and computational power create imagery indistinguishable from real-world photography, crucial for high-fidelity film and advertising content. Demand for this technology is particularly strong in markets requiring stringent visual authenticity, such as China's advertising sector, regulated by SAMR.
- Augmented Reality:This technology overlays computer-generated images onto a live view of the real world, enhancing interactive experiences for live events.
- LED Display Technology:High-resolution LED panels form dynamic backdrops, enabling real-time environment display and immersive on-set visual effects.
- Cloud Computing:Cloud platforms facilitate remote collaboration and scalable processing power for virtual production workflows, impacting cross-border data governance, such as the EU's GDPR.
AI-driven Animation is expanding most quickly, transforming traditional production pipelines.
Application:
The application segment delineates distinct end-user needs, showcasing where virtual production methodologies are gaining traction across various creative and industrial sectors.
- Film Production:This segment involves using virtual production techniques for feature films and television series, integrating CGI with live-action footage on set. It remains the largest application area, driven by a desire for creative flexibility and streamlined post-production workflows.
- Video Game Development:Virtual production tools are increasingly utilized in game development for real-time asset creation, environment design, and cinematic sequences. This segment is one of the fastest-growing areas, leveraging real-time rendering engines for interactive content.
- Advertising:Brands use virtual production for creating visually compelling commercials with rapid turnaround times, particularly in markets like Brazil and India.
- Live Events:This application involves creating immersive concert and broadcast experiences using large-scale LED walls and real-time content.
- Architectural Visualization:Virtual production aids in collaborative design reviews and realistic simulations for building projects before physical construction.
Film Production maintains its market dominance, while Video Game Development shows the steepest expansion trajectory.
End User:
End-user segmentation highlights the primary stakeholders adopting virtual production, reflecting shifts in in-house capabilities versus reliance on specialized service providers.
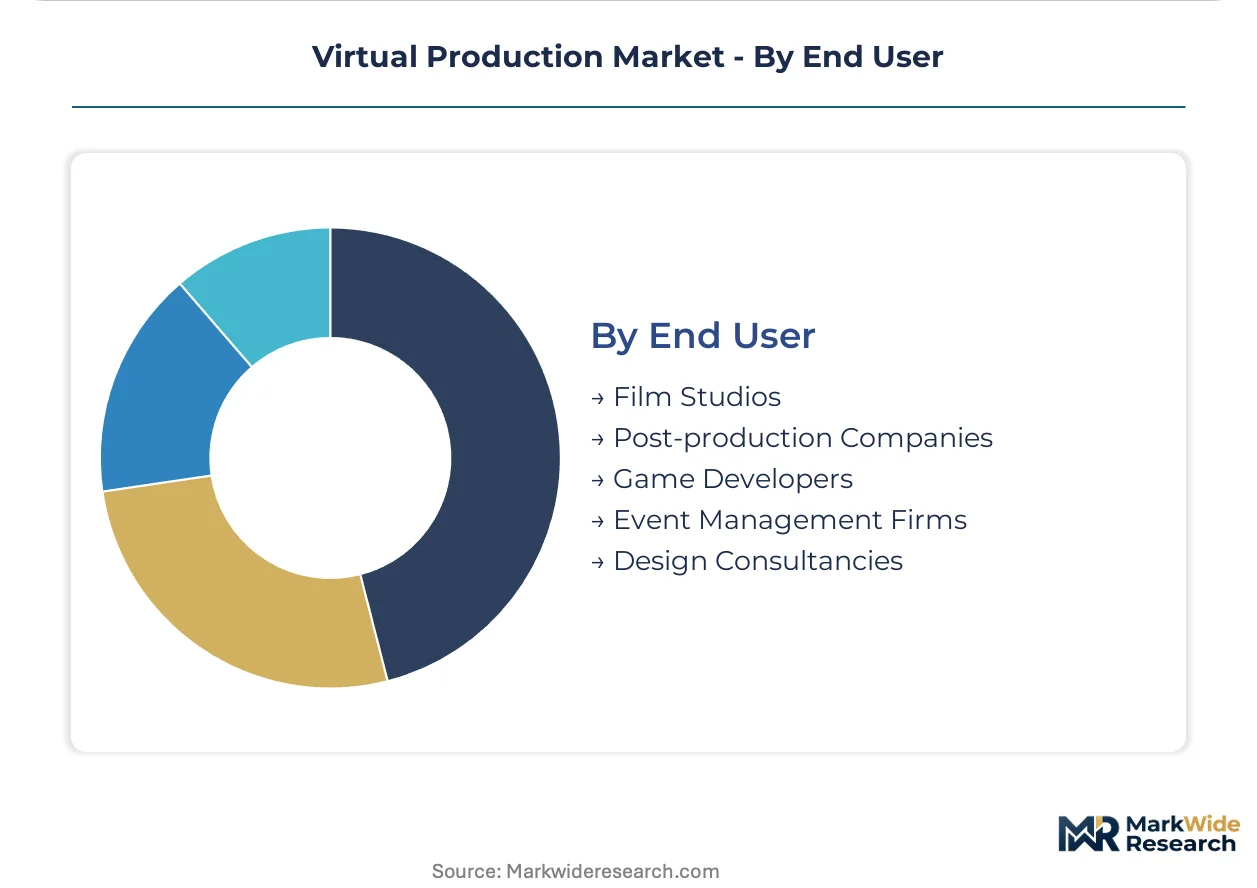
- Film Studios:These entities are increasingly investing in permanent in-house virtual production stages, moving away from traditional outsourcing models. This strategy provides greater control over production pipelines and intellectual property, particularly in hubs like Los Angeles and London.
- Game Developers:Companies specializing in video game creation are significant end-users, leveraging real-time rendering engines for asset creation and interactive experiences. They drive demand for advanced virtual production tools to enhance visual fidelity and accelerate development cycles.
- Post-production Companies:These firms traditionally handled visual effects, but some are adapting to offer virtual production services to studios.
- Event Management Firms:Companies organize concerts and corporate events, utilizing virtual production for immersive, large-scale visual backdrops.
- Design Consultancies:These firms apply virtual production for architectural visualization and automotive design, enabling realistic simulations and collaborative reviews.
Film Studios are consolidating capabilities, while Game Developers are rapidly integrating new workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government incentives in Canada, particularly tax credits for digital content creation, drive investment in virtual production infrastructure and talent development. This fosters innovation hubs across the country. The market also sees strong growth in other regions.
South Korea
South Korea exhibits strong demand for virtual production, driven by its vibrant digital content industry and K-pop concert scene. The Ministry of Culture, Sports and Tourism actively supports studios developing advanced digital content. Seoul's Gangnam district hosts numerous innovative production studios leveraging virtual production for immersive experiences.
United States
The United States market is fueled by major film studios and a rapidly expanding advertising sector utilizing virtual production for high-quality visuals. Regulations from the US Federal Trade Commission (FTC) influence advertising content created with advanced tools. Los Angeles, California, remains a primary production hub, with studios building permanent in-house virtual production stages.
United Kingdom
United Kingdom demand stems from its robust film and television production industry, alongside growing applications in live broadcast events. Data handling for cloud-based workflows must comply with the EU's GDPR, impacting cross-border asset management. London serves as a significant European hub, attracting investment in virtual production facilities and specialized talent.
China
China's virtual production market sees accelerated adoption, particularly within its fast-paced advertising sector and for domestic film productions. The State Administration for Market Regulation (SAMR) enforces strict rules on digital advertising content, ensuring visual authenticity. Shanghai's burgeoning digital media parks are becoming centers for virtual production innovation and technology deployment.
Canada
Canadian studios benefit from extensive visual effects expertise and government incentives, including tax credits for digital content development. These initiatives shape the broader creative industry landscape. Vancouver and Montreal are key clusters, known for their advanced visual effects companies and growing virtual production stages.
Virtual Production Market Key Industry Players
Top-tier vendors anchor the real-time rendering engine segment, while specialized hardware providers and software tool developers form distinct competitive tiers. The market structure is tiered, with a few dominant technology providers and a broader base of specialized service companies. Strategic archetypes include real-time engine developers, GPU manufacturers, and pre-visualization software specialists. Companies pursue strategic partnerships to integrate diverse technologies and expand their solution portfolios. Capacity expansion in virtual production stage construction also represents a significant competitive move.
Among the core technology providers, Epic Games Inc. anchors the real-time rendering engine segment with its Unreal Engine platform, influencing both film and gaming pipelines. NVIDIA Corporation represents a key hardware enabler, supplying the essential GPU infrastructure for complex, high-fidelity rendering tasks. Autodesk Inc. exemplifies a software specialist, offering a broad suite of tools for pre-visualization and asset creation stages of production. These entities collectively shape the foundational layers of the virtual production ecosystem. Their offerings influence both film and video game development pipelines, driving advancements in visual fidelity and production efficiency across various creative industries.
| Leading Market Players |
|---|
| Autodesk Inc. |
| Mo-Sys Engineering Ltd. |
| Epic Games Inc. |
| Sony Group Corporation |
| Disguise Technologies Limited |
| NVIDIA Corporation |
| HTC Corporation |
| Technicolor Creative Studios SA |
| Adobe Inc. |
| Others |
Cost & Logistics Intelligence
Specialized talent pools in hubs like Los Angeles and London command premium rates for virtual production services, influencing pricing tiers across the market. Labor-cost differentials for these hybrid skillsets impact project-based pricing, especially for high-fidelity content.
Pricing Analysis
Premium pricing for virtual production projects often reflects short lead times and highly customized integration requirements. The dominant pricing model combines project-based service fees with software licensing and hardware procurement costs. Customization level and after-sales support significantly drive price differentiation for complex setups. Pricing pressure stems from the high capital outlay required for smaller studios, making them highly price-sensitive, while large film studios exhibit lower sensitivity for in-house stage development.
Supply Chain Analysis
Qualification and certification for high-performance hardware and software components gate the virtual production supply chain. Key technology supply centers in the United States provide essential GPUs and real-time rendering engines, while South Korea is a significant source for advanced LED display technology. The supply chain faces single-source vulnerability for specialized hardware and intellectual property licensing complexities. Distribution occurs primarily through direct vendor channels and specialized system integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Virtual Production Market is undergoing a consolidation play, as the high capital outlay for advanced virtual production stages forces smaller, undercapitalized studios to exit or merge. This pressure drives larger entities to acquire specialized capabilities and infrastructure.
For Market Incumbents:Anchor core technology leadership by investing further in permanent in-house virtual production stages, particularly in hubs like Los Angeles. Form strategic partnerships with real-time rendering engine developers and GPU manufacturers to mitigate single-source dependencies. This strategy counters the threat of specialized talent scarcity and complex legacy system integration challenges. Deepen vertical integration into asset creation and post-production workflows.
For New Entrants and Emerging Players:China's SAMR regulations on digital advertising open a window for specialized firms offering validated, compliant visual content. Target the advertising segment in fast-growing markets like Brazil and India, which demand rapid turnaround times. Focus on providing cost-effective, high-quality solutions for mid-tier advertising agencies. Penetrate the enterprise sector with tailored virtual production services for architectural visualization and automotive design.
For Investors and Strategic Acquirers:Re-rating potential sits with technology providers focused on generative AI for asset creation, given the catalyst of accelerating content demand and efficiency gains. The long-term viability of virtual production is assured by its ability to deliver immersive experiences and streamline production workflows. Target specialized post-production companies that have successfully integrated real-time pipelines. A key signal to watch is the widespread adoption of open-source standardization initiatives like Universal Scene Description (USD).
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Generative AI R&D | Automates 3D asset creation, significantly reducing labor costs for film studios and game developers. |
| Establish In-House VP Stages | Major film studios gain greater control over intellectual property and production pipelines in Los Angeles and London. |
| Form Software-Hardware Partnerships | Real-time rendering engine developers and GPU manufacturers integrate offerings for seamless on-set workflows. |
| Develop Open-Source Standards (USD) | Promotes interoperability between diverse software tools, benefiting asset management across production houses. |
| Expand into Enterprise Applications | Architectural visualization firms and automotive designers leverage virtual production for collaborative design reviews. |
Research Approach
Document review covered industry reports, company financial filings, and government digital content initiatives, complemented by interviews with visual effects supervisors and studio executives. Primary data collection involved discussions with real-time engine developers and LED display manufacturers. This approach ensured a robust understanding of market dynamics through bottom-up and top-down triangulation.
The quantitative model produced volume and value projections across the analysis window, integrating various market dynamics. Segmentation dimensions modeled included product type, underlying technology, application, end-user, and geographic region. Compound Annual Growth Rates were derived from historical trends and projected technology adoption rates. Production budgets and investment in virtual production infrastructure served as key forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for generative AI integration would alter the outlook. Forecasts reflect assumptions regarding production budgets and infrastructure investment. A model refresh is warranted upon material change in rapid AI advancements or content regulation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
China Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Middle East and Africa Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Smart Augmented Reality Glasses for B2B Market
Virtual Reality (VR) and Augmented Reality (AR)
VR Ski Machines Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality Content Creation Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality Box Glasses Market
Virtual Reality (VR) and Augmented Reality (AR)
VR Collaboration Platform Market
Virtual Reality (VR) and Augmented Reality (AR)
Holographic AR Display Market
Virtual Reality (VR) and Augmented Reality (AR)
Asia-Pacific Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
North America Augmented Reality (AR) and Mixed Reality (MR) Market
Virtual Reality (VR) and Augmented Reality (AR)
South Korea Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
US Virtual Tour Market
Virtual Reality (VR) and Augmented Reality (AR)
Europe Augmented Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
VR Box Glasses Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality for Consumer Market
Virtual Reality (VR) and Augmented Reality (AR)
Europe Augmented Reality (AR) and Mixed Reality (MR) Market