
 North America Augmented Reality (AR) and Mixed Reality (MR) Market | 2026-2036
North America Augmented Reality (AR) and Mixed Reality (MR) Market Size, Share, and Industry Trends Forecast 2026-2036
North America Augmented Reality (AR) and Mixed Reality (MR) Market Analytics
Canada's Ontario corridor is fragmenting as a production hub for optical waveguide components and spatial computing hardware. Meta Platforms leverages its Reality Labs infrastructure to sustain deep R&D pipelines in passthrough mixed reality. Apple anchors premium headset manufacturing through tightly controlled supply relationships with Asian foundries. Microsoft competes in enterprise MR by dominating industrial simulation deployments across automotive and aerospace clients.
Augmented Reality and Mixed Reality denote systems that overlay or embed digital information into the physical world through optical see-through displays, video passthrough cameras, and spatial mapping sensors operating at sub-millimeter tracking precision. These technologies serve commercial and industrial purposes by enabling hands-free data visualization, remote collaboration, and immersive training without full sensory isolation. MR Platforms currently capture the highest margin pools as integrated software-hardware ecosystems, while AR Glasses represent the fastest-growing product type as weight reduction and field-of-view expansion advance. Among end users, Healthcare Providers drive the most specialized demand through FDA-cleared surgical navigation and diagnostic imaging overlays.
The US FDA oversees software-as-medical-device classifications for AR diagnostic tools, while the FCC manages spectrum allocation for wireless headset tethering and the FAA evaluates AR displays for aviation maintenance applications. Canadian regulators under Health Canada align with FDA breakthrough device pathways to streamline cross-border immersive health technology approvals. Stakeholders must monitor how evolving eye-tracking data privacy rules under state-level biometric laws reshape hardware design requirements and enterprise deployment contracts.
Market Dynamics
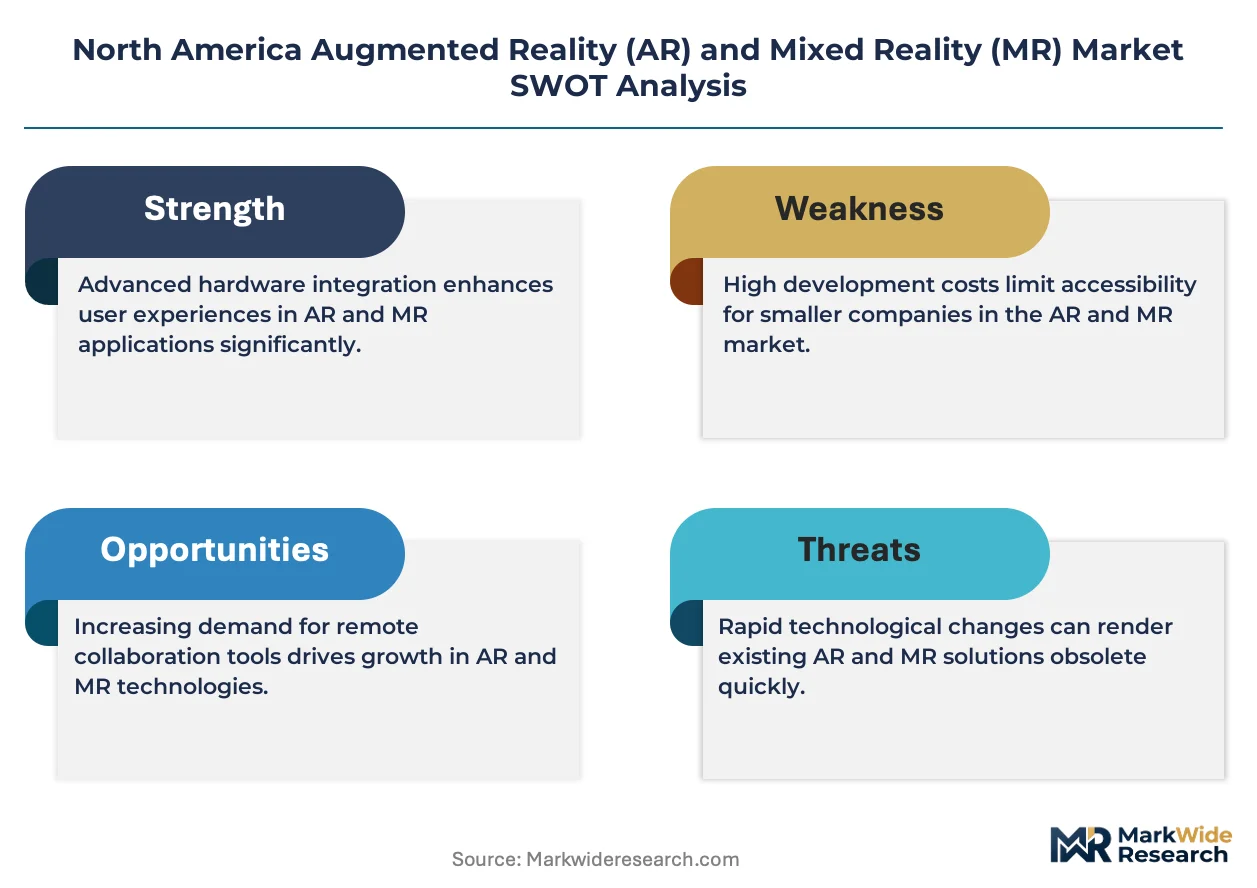
The North America AR and MR market is compressing around optical waveguide supply concentration and FDA software-as-medical-device reclassifications, forcing hardware makers to redesign sensor architectures while healthcare providers accelerate clinical validation timelines.
Growth Catalysts
- FDA Breakthrough Device Pathway:The FDA's streamlined premarket review for AR surgical navigation tools is cutting clinical trial durations for mixed reality diagnostic overlays.
- Spatial Computing Hardware Clusters:Seattle's mixed reality engineering concentration and California's Silicon Valley optical design firms are pooling specialized talent for next-generation passthrough systems.
- Aviation Maintenance Mandates:The FAA's evaluation protocols for AR-assisted inspection workflows are embedding immersive displays into commercial airline MRO operations.
Market Restraints
- Asian Foundry Dependency:Premium headset manufacturing relies on tightly controlled Asian foundry relationships, creating single-source vulnerability for micro-OLED and waveguide substrates.
- State Biometric Privacy Laws:Illinois BIPA and Texas biometric statutes are imposing eye-tracking data retention limits that complicate enterprise deployment contracts.
- Power Density Constraints:Battery chemistry limitations cap continuous operation times for untethered AR glasses below industrial shift lengths.
Strategic Opportunities
- Canadian Cross-Border Alignment:Health Canada's synchronization with FDA breakthrough pathways is streamlining immersive health technology approvals for Ontario-based developers.
- Enterprise Simulation Convergence:Automotive and aerospace clients are integrating MR industrial simulation with digital twin platforms for real-time design validation.
- Remote Diagnostics White Space:Hospital networks are expanding AR-guided surgical planning across rural facilities where specialist access is limited.
Industry Challenges
- Optical Engineering Talent Scarcity:Waveguide design and spatial mapping algorithm development require specialized photonics expertise concentrated in fewer than five North American academic programs.
- Legacy System Integration Friction:Enterprise MR deployments face API incompatibility with decades-old manufacturing execution systems in automotive and aerospace facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Augmented Reality (AR) and Mixed Reality (MR) Market |
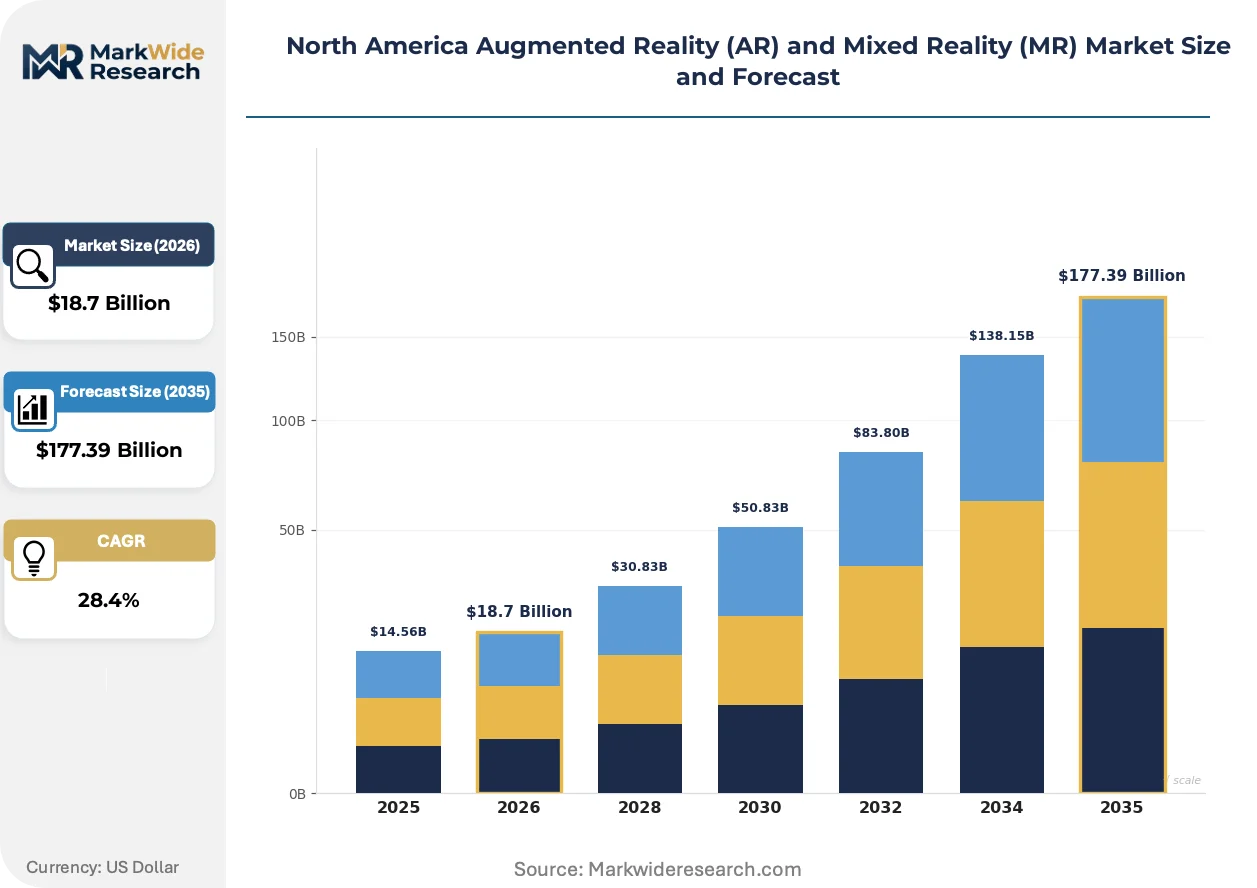
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $177.39 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AR Glasses, VR Headsets, Mobile AR Apps, MR Platforms End User: Healthcare Providers, Retail Chains, Education Institutions, Gaming Companies Technology: Marker-Based, Markerless, Projection-Based, Superimposition Application: Medical Training, Retail Visualization, Remote Assistance, Industrial Simulation |
| Companies Covered | Meta Platforms, Apple, Microsoft, Google, Magic Leap, PTC, Vuzix, EON Reality, Ultraleap, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Augmented Reality (AR) and Mixed Reality (MR) Market Evolving Landscape
Optical architectures and regulatory frameworks are simultaneously evolving, compressing product development cycles while expanding addressable use cases across healthcare and industrial verticals.
Waveguide display technology is migrating from bulky prism-based optics to surface-relief grating architectures that halve headset weight. Healthcare providers and industrial field technicians are adopting these lighter systems for multi-hour continuous use. The shift is compressing competitive differentiation around optical efficiency rather than raw compute power.
The FDA's digital health software guidance is formalizing clinical validation requirements for AR diagnostic overlays. Medical device manufacturers must now submit eye-tracking accuracy data and spatial mapping precision metrics as part of 510(k) premarket notifications. Surgical navigation vendors are responding by embedding sub-millimeter tracking sensors directly into sterilizable instrument handles.
Enterprise buyers are consolidating vendor relationships around integrated software-hardware ecosystems rather than point solutions. Automotive and aerospace procurement teams now require MR platforms to include pre-certified industrial simulation modules and multi-year remote support contracts. This preference shift is most visible in Seattle and Detroit manufacturing clusters where production engineers specify single-vendor immersive training deployments.
North America Augmented Reality (AR) and Mixed Reality (MR) Market Segmentation
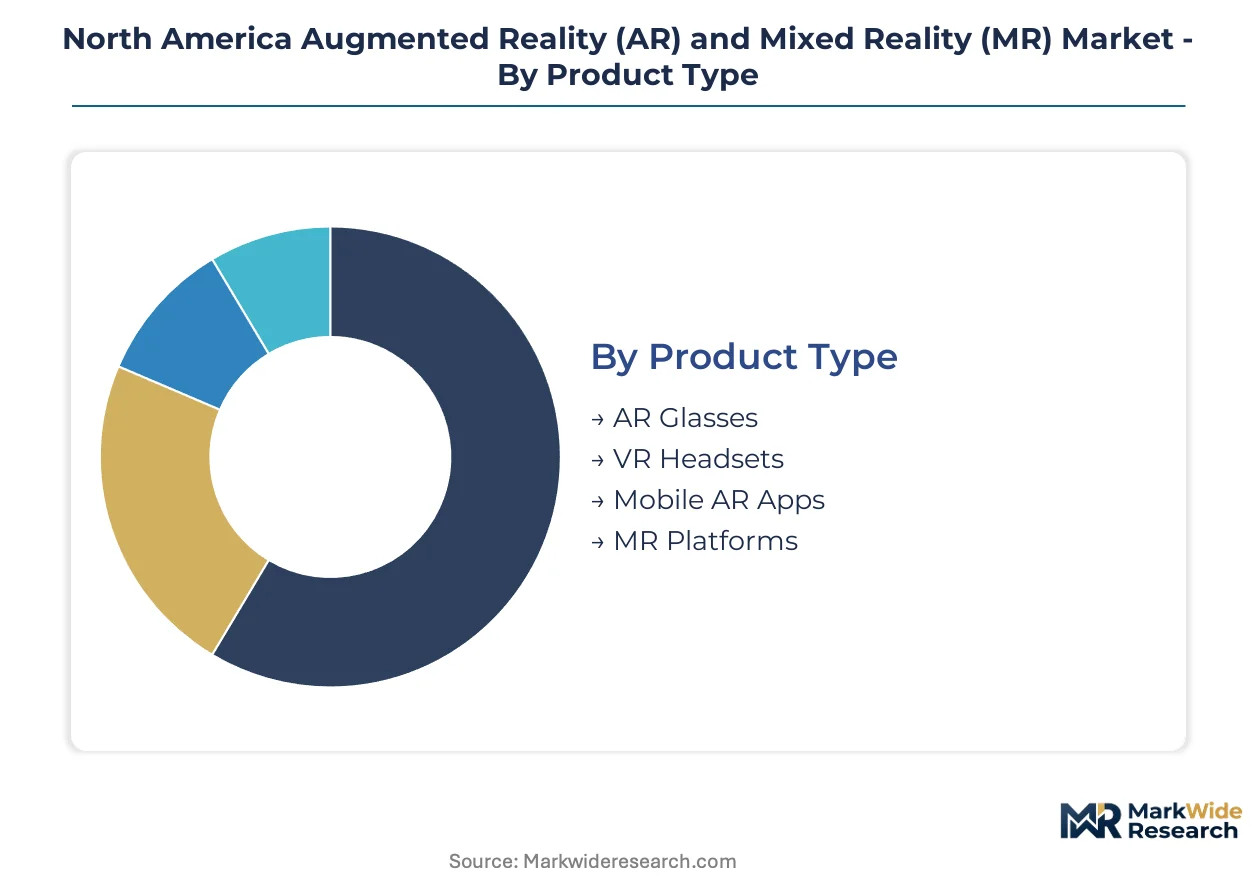
Segmentation in the North America AR and MR market reveals distinct service intensity profiles across hardware ecosystems. After-sales support requirements vary dramatically between disposable mobile applications and capital-intensive surgical navigation platforms requiring continuous calibration.
Product Type:
After-sales service intensity escalates with hardware complexity and clinical certification burdens.
- AR Glasses:Lightweight optical see-through devices deploy surface-relief grating waveguides for sub-millimeter spatial mapping. California's Silicon Valley engineering clusters and Seattle's mixed reality hardware developers drive refinement cycles for multi-hour industrial use cases. Battery chemistry constraints limit continuous operation below standard shift lengths, forcing rapid swap architectures.
- MR Platforms:Integrated software-hardware ecosystems demand multi-year remote support contracts and pre-certified industrial simulation modules. Automotive procurement teams in Detroit specify single-vendor immersive training deployments with embedded digital twin convergence. FDA software-as-medical-device reclassifications compress clinical validation timelines for diagnostic overlay components.
- VR Headsets:Full sensory isolation systems serve gaming and training applications with lower regulatory overhead than clinical MR systems.
- Mobile AR Apps:Smartphone-based overlays leverage existing device infrastructure with minimal specialized hardware support requirements.
By volume, Mobile AR Apps leads. By growth pace, MR Platforms is ahead.
End User:
Cost tier stratification separates capital-intensive clinical deployments from volume-driven consumer applications.
- Healthcare Providers:FDA-cleared surgical navigation and diagnostic imaging overlays demand sterilizable instrument handles with embedded sub-millimeter tracking sensors. Hospital networks across rural Ontario and the US Midwest expand AR-guided surgical planning where specialist access is limited. Eye-tracking accuracy data and spatial mapping precision metrics now accompany 510(k) premarket submissions.
- Industrial Simulation:Automotive and aerospace clients integrate MR platforms with legacy manufacturing execution systems, facing API friction with decades-old infrastructure. Seattle and Detroit production engineers consolidate vendor relationships around single-source immersive training deployments.
- Retail Chains:Visualization applications prioritize rapid deployment and consumer engagement over precision tracking specifications.
- Education Institutions:Budget-constrained procurement favors mobile AR solutions over capital-intensive headset ecosystems.
- Gaming Companies:Entertainment-focused development cycles emphasize content velocity over clinical-grade hardware certification.
Healthcare Providers command premium pricing tiers. Education Institutions expand most quickly as federal training grants accelerate adoption.
Technology:
Volume concentration favors markerless architectures as spatial mapping sensors achieve standalone operation without visual fiducials.
- Markerless:Computer vision and depth-sensing arrays enable arbitrary surface detection without pre-placed reference points. Seattle's mixed reality engineering concentration and California optical design firms pool specialized talent for next-generation passthrough algorithms. State biometric privacy laws in Illinois and Texas impose eye-tracking data retention limits complicating enterprise deployment contracts.
- Superimposition:Real-time object replacement and occlusion handling support industrial maintenance and medical visualization where precise spatial registration is critical. FAA evaluation protocols for AR-assisted inspection workflows embed these displays into commercial airline MRO operations across US maintenance hubs.
- Marker-Based:Visual fiducial dependency limits scalability but reduces computational requirements for cost-sensitive applications.
- Projection-Based:Spatial light modulation enables shared collaborative experiences without individual head-mounted hardware.
Markerless systems dominate unit shipments. Superimposition gains share fastest as precision requirements harden in clinical and aviation applications.
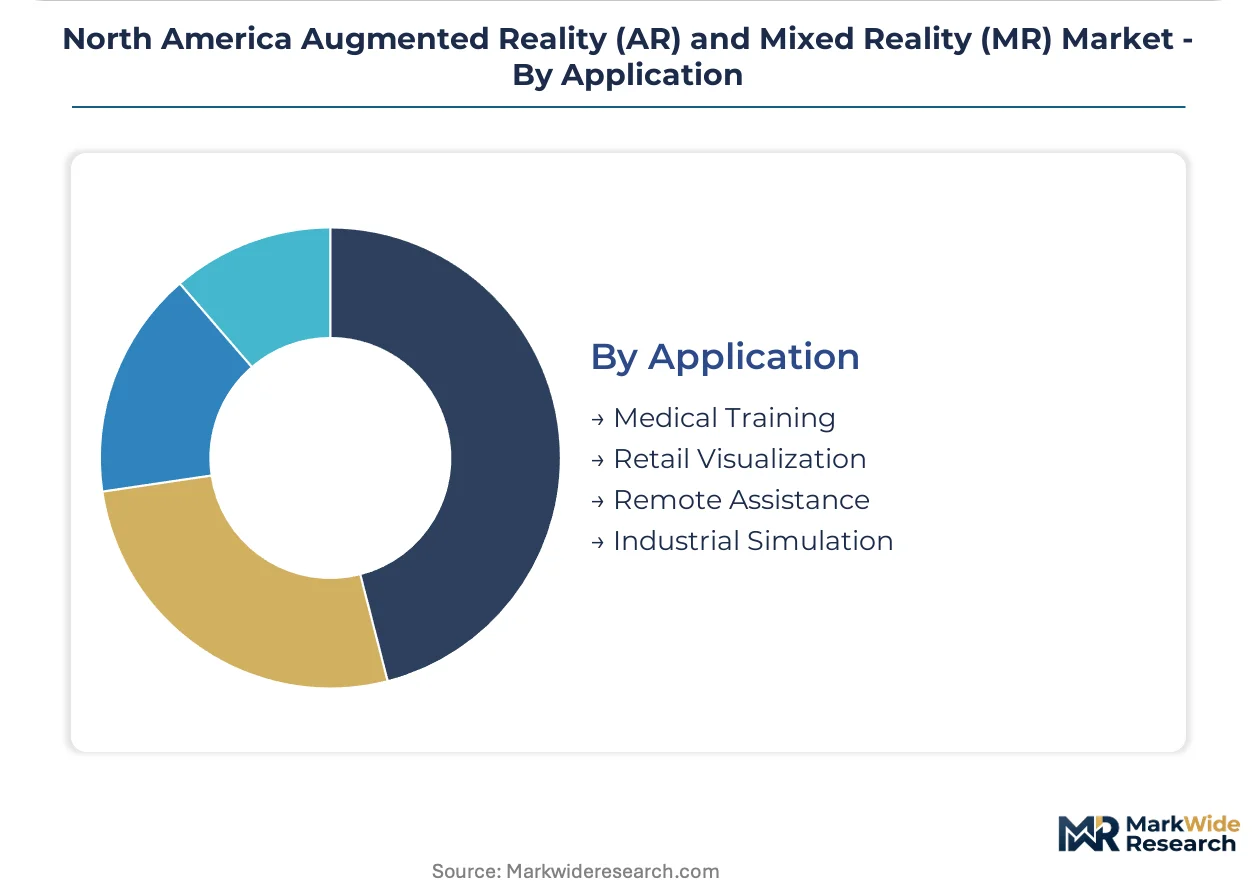
Application:
Margin structure varies with regulatory certification depth and integration complexity.
- Medical Training:Haptic feedback integration and physiological simulation require specialized curriculum development alongside hardware deployment. Canadian Health Canada alignment with FDA breakthrough pathways streamlines immersive health technology approvals for Ontario-based developers. Surgical navigation vendors embed tracking sensors into sterilizable instrument handles to satisfy premarket notification requirements.
- Industrial Simulation:Digital twin convergence with real-time design validation commands multi-year platform commitments from automotive and aerospace procurement teams. API incompatibility with legacy manufacturing execution systems creates implementation friction requiring custom middleware development.
- Remote Assistance:Field technician support applications prioritize network latency optimization over spatial precision.
- Retail Visualization:Consumer-facing deployment cycles emphasize rapid content refresh rates over hardware durability specifications.
Industrial Simulation captures highest margin pools. Remote Assistance climbs the fastest as distributed workforce models persist.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The cross-border fiber optic corridors linking Seattle's mixed reality engineering clusters to Vancouver's photonics research facilities underwrite North America's concentration in spatial computing hardware development.
United States
Healthcare providers across the Midwest and Southeast are expanding AR-guided surgical planning networks to address specialist shortages in rural markets. The FDA's breakthrough device pathway accelerates premarket review for mixed reality diagnostic overlays, compressing clinical trial timelines for immersive medical devices. California's Silicon Valley optical design firms and Seattle's engineering concentration pool specialized talent for next-generation passthrough systems.
Canada
Ontario-based developers are leveraging Health Canada's synchronization with FDA pathways to streamline immersive health technology approvals for cross-border deployment. The country's national pharmaceutical regulator aligns breakthrough device classifications with US standards, reducing regulatory friction for surgical navigation vendors. Toronto-Waterloo corridor photonics programs supply waveguide engineering talent to spatial computing hardware manufacturers.
Mexico
Aviation maintenance operations in Baja California and Querétaro are adopting AR-assisted inspection workflows as FAA evaluation protocols extend to North American MRO networks. The federal telecommunications regulator manages spectrum allocation for wireless headset tethering in industrial zones near the US border. Guadalajara's electronics manufacturing cluster is integrating optical component assembly into existing consumer hardware supply chains.
North America Augmented Reality (AR) and Mixed Reality (MR) Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream controlling waveguide substrates and spatial mapping sensors. The vendor base organizes around three structural tiers: integrated software-hardware ecosystems, optical component fabricators, and enterprise application developers. Consolidation pressure concentrates among platform providers seeking captive supply of micro-OLED and waveguide architectures. Dominant competitive moves include strategic partnerships for optical engineering talent access and geographic expansion into Canadian regulatory-aligned development corridors.
Among US-based platform integrators, Meta Platforms, Apple, and Microsoft exemplify the three competitive archetypes shaping market structure. Meta Platforms occupies a position as the passthrough mixed reality specialist with deep R&D infrastructure. Apple represents the premium-tier hardware anchor with tightly controlled Asian foundry relationships. Microsoft sits within the enterprise MR segment dominating industrial simulation deployments. These three entities collectively illustrate how vertical integration depth, supply chain control, and end-market specialization define competitive positioning.
| Leading Market Players |
|---|
| Meta Platforms |
| Apple |
| Microsoft |
| Magic Leap |
| PTC |
| Vuzix |
| EON Reality |
| Ultraleap |
| Others |
Value Network & Pricing Analysis
Undercapacity in micro-OLED foundry capacity across Taiwan and South Korea is compressing supplier pricing power for North American headset manufacturers while forcing buyers into multi-year offtake commitments. This utilization squeeze elevates component costs for optical waveguides and spatial mapping sensors, reshaping how platform integrators structure procurement contracts.
Pricing Analysis
Volume-discount tiering structures separate enterprise MR deployments from consumer AR glasses across premium, standard, and economy levels. FDA certification grade and after-sales service bundling drive price differentiation between clinical-grade surgical navigation systems and industrial field technician headsets. Pricing pressure stems from Asian foundry concentration as single-source vulnerability elevates input costs. Healthcare providers exhibit lowest price sensitivity due to reimbursement pathways, while education institutions demand aggressive economy-tier procurement.
Supply Chain Analysis
Contract-manufacturing concentration rests with Taiwanese and South Korean foundries for micro-OLED substrates, Chinese suppliers for waveguide optical components, and Mexican assembly facilities near the US border. Raw material dependencies center on rare-earth elements for laser diodes, photoresist chemicals for grating fabrication, and lithium-ion cell chemistry for power density. Single-source vulnerability in waveguide substrate supply creates structural risk. Distribution runs through direct enterprise sales teams for healthcare and industrial segments, consumer electronics retail for AR glasses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of optical engineering talent with photonics expertise constrains how quickly vendors can scale next-generation passthrough systems, making human capital retention the decisive competitive variable.
For Market Incumbents: Insulate proprietary waveguide architectures through captive supply agreements with Asian foundries and accelerated hiring from Toronto-Waterloo corridor photonics programs. FDA software-as-medical-device reclassifications threaten clinical validation timelines; vertical integration into sterilizable instrument handle manufacturing defends certification moats. For New Entrants and Emerging Players: Pursue remote diagnostics white space in rural Ontario and US Midwest hospital networks where specialist shortages create urgent demand. Canadian Health Canada alignment with FDA pathways offers the most penetrable regulatory entry point. Go-to-market positioning should emphasize cross-border deployment simplicity for Ontario-based developers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among enterprise MR platform providers with multi-year remote support contracts and pre-certified industrial simulation modules. Five-to-ten year viability favors vendors with backward integration into optical component supply. Monitor FAA evaluation protocol expansions for AR-assisted aviation maintenance as inflection signal for industrial simulation demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Optical Engineering Talent Acquisition | Waveguide design expertise from Toronto-Waterloo photonics programs accelerates product cycles for passthrough MR systems. |
| FDA Breakthrough Device Pathway Submission | Streamlined premarket review compresses clinical validation timelines for surgical navigation vendors. |
| Cross-Border Canadian Development Expansion | Health Canada synchronization with FDA standards reduces regulatory friction for immersive health technology approvals. |
| Enterprise Simulation Module Pre-Certification | Automotive procurement teams in Detroit require embedded digital twin convergence for single-vendor selection. |
| Aviation Maintenance Partnership | FAA evaluation protocols for AR-assisted inspection workflows embed displays into commercial airline MRO operations. |
Research Methodology
Operator-level perspectives from surgical navigation engineers, hospital procurement committees, automotive platform integration leads, and mixed reality hardware program managers anchored the qualitative base. Primary interviews combined with secondary validation from FDA 510(k) premarket notification databases, FCC spectrum allocation filings, Health Canada device approval records, and SEC R&D expenditure disclosures. Bottom-up unit economics and top-down market sizing triangulated segment-level estimates.
Scenario-bracketing framed low-base-high projections across the analysis window. Segmentation dimensions modeled include product type complexity, end-user regulatory tier, technology architecture, and application certification depth. CAGRs derived from weighted average of historical trajectory and forward-looking adoption curves. Industry-specific forecast inputs incorporated FAA protocol expansion timelines and Health Canada-FDA pathway synchronization velocity.
Macroeconomic conditions sit as an overlay; deviation in federal training grant allocations and semiconductor capital expenditure cycles would shift the trajectory. Forecasts reflect assumptions on optical component yield improvements and battery chemistry advancement rates. Quarterly review of FDA breakthrough device approval velocity and waveguide foundry utilization indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
Holographic AR Display Market
Virtual Reality (VR) and Augmented Reality (AR)
VR HMD Shipment Market
Virtual Reality (VR) and Augmented Reality (AR)
Canada Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Smart Augmented Reality Glasses for B2B Market
Virtual Reality (VR) and Augmented Reality (AR)
US Virtual Tour Market
Virtual Reality (VR) and Augmented Reality (AR)
AR/VR Chip Market
Virtual Reality (VR) and Augmented Reality (AR)
UK Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Para-Virtualization Market
Virtual Reality (VR) and Augmented Reality (AR)
Asia-Pacific Augmented Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual and Augmented Reality in Tourism Market
Virtual Reality (VR) and Augmented Reality (AR)
AR and VR in Training Market
Virtual Reality (VR) and Augmented Reality (AR)
Augmented Reality and Virtual Reality in Manufacturing Market
Virtual Reality (VR) and Augmented Reality (AR)
3D Somatosensory Virtual Fitting Market
Virtual Reality (VR) and Augmented Reality (AR)
Wireless AR Glass Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Immersive Technology Market
Virtual Reality (VR) and Augmented Reality (AR)
Italy Metaverse Market