
 US Augmented and Virtual Reality Market | 2026-2036
US Augmented and Virtual Reality Market Size, Share, and Industry Trends Forecast 2026-2036
US Augmented and Virtual Reality Market Insights
California's SB 1018 clean energy procurement mandate is hardening requirements for sustainable electronics manufacturing across West Coast technology corridors. Magic Leap sustains concentrated R&D operations in Florida, leveraging photonics expertise for enterprise spatial computing. Medivis specializes in surgical navigation overlays, anchoring its development to FDA-cleared clinical workflows. Snap Inc competes through consumer AR glasses distribution, controlling social media channel integration for mass-market reach.
Augmented and Virtual Reality encompasses computer-generated sensory environments delivered through head-mounted displays, spatial sensors, and haptic controllers operating at sub-20ms motion-to-photon latency to prevent simulator sickness. The technology serves industrial training, surgical visualization, and immersive commerce by overlaying or replacing physical perception with rendered digital content. Headsets command the dominant hardware margin pool, though software licensing for enterprise deployment shows faster expansion. Healthcare end users drive premium pricing for FDA-validated surgical planning applications, while gaming remains the volume base for consumer VR adoption. Mixed Reality systems integrating passthrough cameras are displacing sealed VR architectures in enterprise settings due to safer physical environment awareness.
The FDA regulates medical AR devices under digital health software premarket pathways, while the FCC governs wireless spectrum allocation for untethered headset transmission protocols. OSHA workplace safety standards influence industrial VR training system design, particularly regarding exposure duration limits and ergonomic load factors. Stakeholders must monitor evolving interoperability standards between proprietary platforms and open spatial computing frameworks to anticipate platform lock-in risks and partnership requirements.
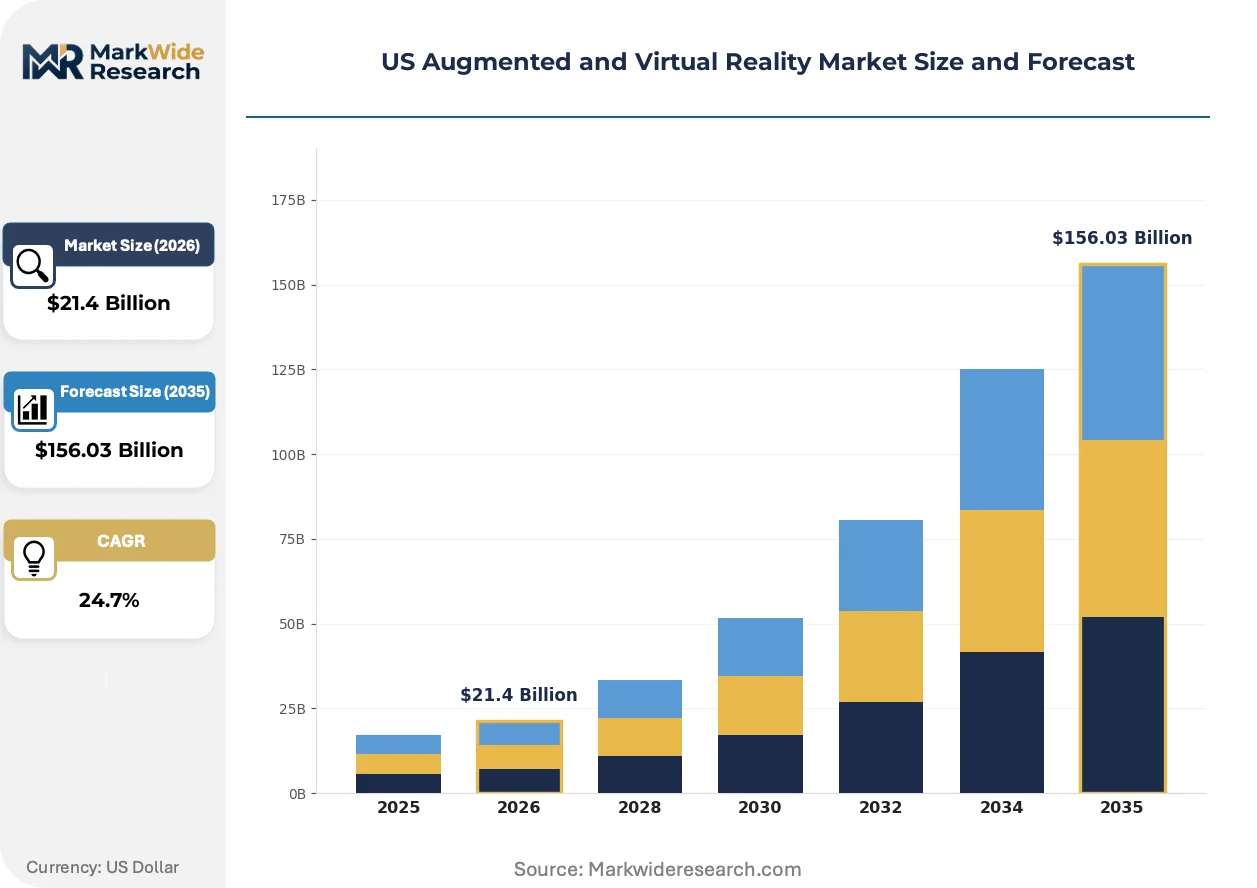
Market Dynamics
Defense procurement cycles and FDA clinical validation pathways are tightening the competitive filter across US AR/VR deployment, forcing vendors to choose between subsidized military contracts or premium healthcare margins.
Growth Catalysts
- OSHA Workplace Safety Standards:Industrial training mandates are expanding VR simulation requirements for hazardous environment preparation, creating captive demand from utilities and manufacturing operators.
- Passthrough Camera Architectures:Mixed Reality systems with real-world environmental awareness are accelerating enterprise adoption by eliminating collision risks in shared physical workspaces.
- California SB 1018:Clean energy procurement mandates are pressuring West Coast electronics manufacturers to certify sustainable supply chains for headset component sourcing.
Market Restraints
- Display Panel Concentration:Micro-OLED supply chains cluster in East Asian fabrication facilities, creating single-source vulnerability for premium headset optics.
- FDA 510(k) Pathway Friction:Digital health software premarket submissions for surgical AR applications face extended review timelines compared to traditional medical devices.
- Motion-to-Photon Latency Thresholds:Sub-20 millisecond rendering requirements demand specialized GPU architectures that inflate bill-of-materials costs for standalone headsets.
Strategic Opportunities
- Texas Medical Center Cluster:Houston's surgical innovation corridor presents concentrated pilot-to-deployment pathways for FDA-cleared AR navigation systems.
- 5G mmWave Spectrum Allocation:FCC untethered transmission protocols are enabling cloud-rendered enterprise VR without local compute hardware.
- Spatial Computing + Generative AI Convergence:Real-time environment reconstruction combined with procedural content generation is opening immersive training scenarios previously requiring physical set construction.
Industry Challenges
- Photonics Engineering Talent Scarcity:Waveguide design and laser MEMS fabrication expertise concentrates in legacy telecom and defense contractors, constraining headset OEM hiring pipelines.
- Legacy Simulation Platform Integration:Defense training systems built on decade-old software architectures require costly middleware development to ingest modern AR/VR content formats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Augmented and Virtual Reality Market |
| Market Size in 2026 | $21.4 Billion |
| Market Size in 2035 | $156.03 Billion |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Headsets, Software, Sensors, Controllers End User: Gaming, Healthcare, Education, Retail Technology: AR, VR, Mixed Reality, Haptic Feedback Application: Training, Simulation, Marketing, Entertainment |
| Companies Covered | Marxent, Medivis, Magic Leap, Wildnet Edge, VITURE Inc, Snap Inc, Avegant, Illumix, Mojo Vision, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Augmented and Virtual Reality Market Trends and Innovations
Computational photography and edge AI inference are compressing the hardware-software boundary in US spatial computing deployment, enabling lighter form factors without sacrificing environmental sensing fidelity.
Foveated rendering with dynamic resolution scaling is automating visual quality optimization by tracking pupil position in real-time and concentrating GPU resources on the active retinal area. Surgical visualization vendors at Cleveland Clinic and Mayo Clinic campuses are piloting these systems for extended procedure durations. The technology is automating the trade-off between battery endurance and image clarity that previously forced hardware bulk.
FDA digital health software guidance updates are tightening clinical validation documentation for AR surgical planning tools, requiring prospective studies rather than retrospective equivalence claims. Device manufacturers must now submit patient outcome data from controlled deployment environments. The policy shift most impacts neurosurgical navigation overlays where millimeter registration accuracy carries liability exposure.
Subscription-based enterprise licensing is displacing perpetual software ownership across industrial training deployments, with monthly per-seat fees replacing upfront capital expenditure approval cycles. Channel partners in Seattle's aerospace corridor are restructuring compensation around recurring revenue retention rather than initial hardware margin. The shift is most visible among defense contractors managing multi-year workforce certification programs across dispersed facility networks.
US Augmented and Virtual Reality Market Segmentation
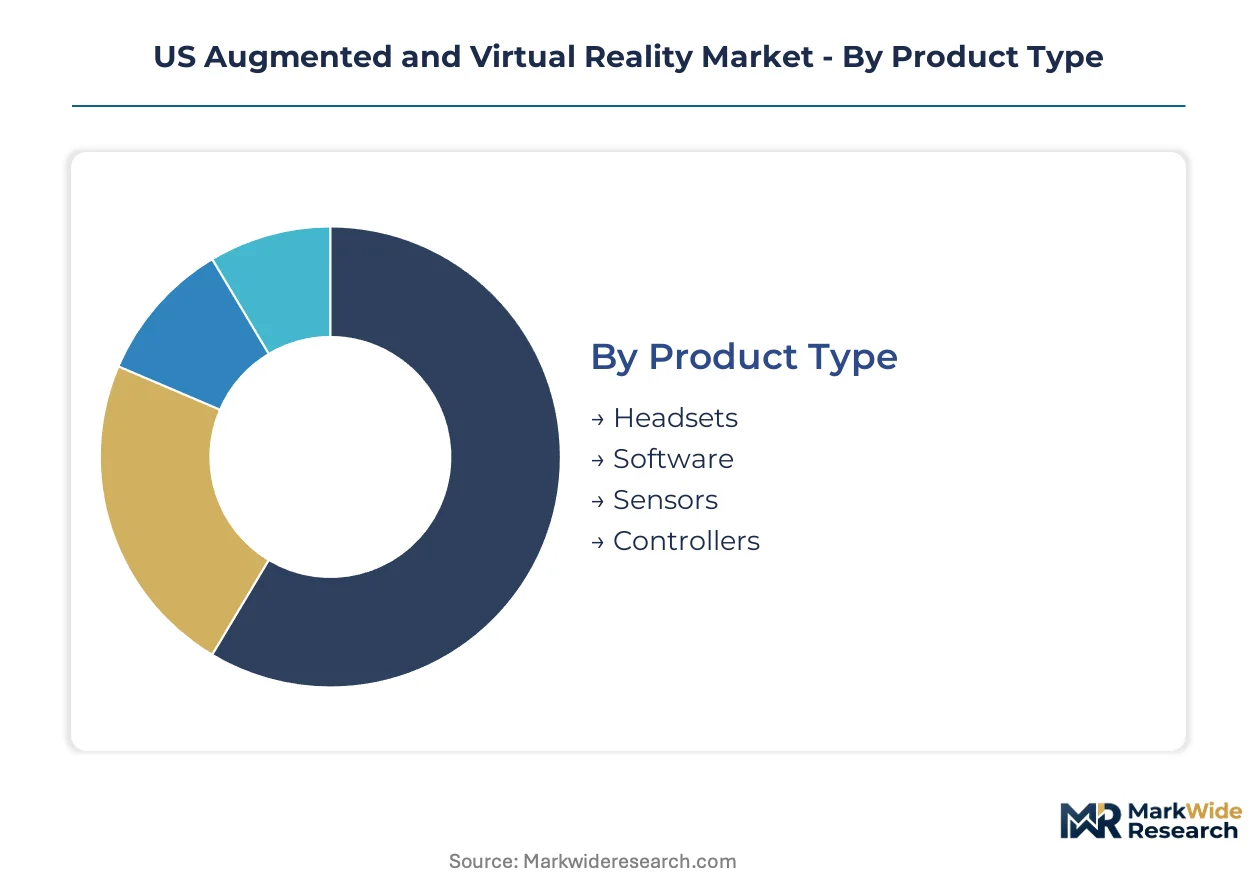
Segmentation in the US AR/VR market reveals how procurement priorities diverge between volume-driven consumer channels and margin-protected enterprise verticals. Understanding these splits exposes where hardware commoditization pressures software differentiation.
Product Type:
Customization intensity varies sharply across this category, from bespoke surgical visualization systems to mass-produced consumer peripherals.
- Headsets:Head-mounted displays integrate micro-OLED panels, waveguide optics, and spatial tracking cameras at sub-20ms latency thresholds. Defense training contracts in Texas and Virginia concentrate demand for ruggedized enterprise variants, though FDA clinical validation timelines constrain medical-grade releases.
- Software:Spatial computing platforms, rendering engines, and enterprise deployment tools command recurring licensing revenue. Seattle aerospace clusters and California logistics operators drive subscription adoption for industrial training modules.
- Sensors:Inertial measurement units, LiDAR arrays, and hand-tracking cameras enable environmental awareness.
- Controllers:Haptic input devices with force feedback and finger tracking complete interaction loops.
Most installed capacity flows through Headsets. Expansion is steepest in Software.
End User:
Customer sophistication tiers separate price-sensitive entertainment buyers from compliance-driven institutional purchasers.
- Gaming:Consumer entertainment applications prioritize visual fidelity and wireless convenience over enterprise durability. Volume concentrates in California's content development corridors where social platform integration drives hardware ecosystem choices.
- Healthcare:Surgical navigation, patient education, and clinical training applications require FDA 510(k) clearance and prospective outcome studies. Houston's Texas Medical Center anchors pilot-to-deployment pathways for AR visualization systems.
- Education:K-12 and university deployments emphasize cost scalability and content library breadth.
- Retail:Virtual try-on and immersive commerce implementations focus on conversion metrics and return rates.
Procurement volume concentrates in Gaming. Margin expansion is climbing the fastest in Healthcare.
Technology:
Architectural maturity separates proven display formats from emerging sensory integration approaches.
- AR:Optical see-through displays overlay digital content onto physical environments using waveguide or birdbath optics. Enterprise maintenance and logistics operations in Seattle manufacturing clusters drive adoption for hands-free workflow guidance.
- VR:Sealed immersive environments replace visual perception entirely through high-resolution panels and lens systems. Gaming remains the volume anchor, though OSHA-compliant industrial training is gaining share.
- Mixed Reality:Passthrough camera architectures blend physical and digital perception with spatial awareness.
- Haptic Feedback:Force-resistance and texture-simulation peripherals extend immersion beyond visual channels.
Deployment scale currently favors VR. Technology transition is accelerating most quickly in Mixed Reality.
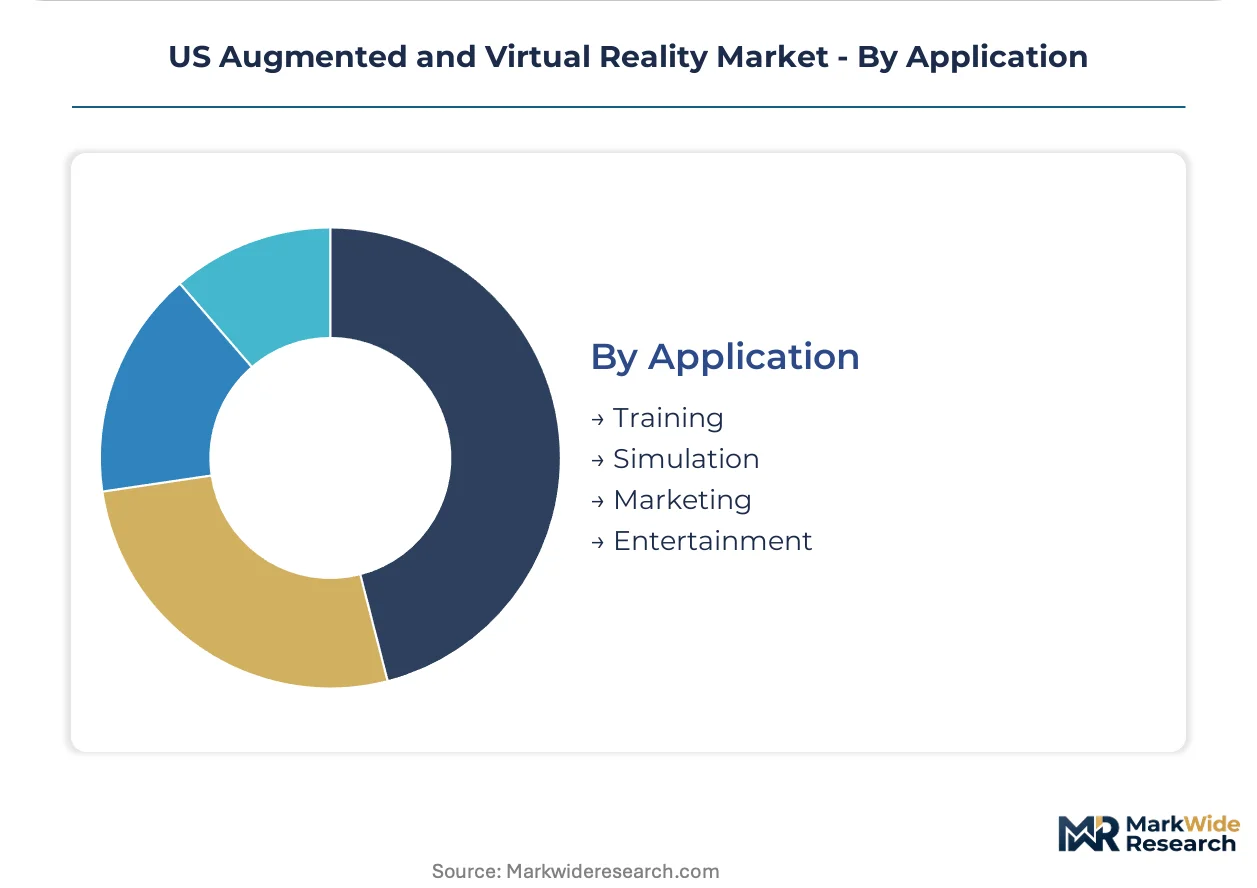
Application:
Use case specificity ranges from standardized entertainment consumption to highly tailored procedural simulations.
- Training:Workforce skill acquisition and hazardous environment preparation leverage repeatable, measurable simulation scenarios. OSHA workplace safety mandates are expanding captive demand from utilities and manufacturing operators across the Midwest.
- Simulation:Defense procurement cycles and medical procedure rehearsal require high-fidelity physics modeling and anatomical accuracy. Pentagon training budgets and Cleveland Clinic surgical innovation programs anchor premium pricing tiers.
- Marketing:Brand engagement and product visualization applications prioritize viral shareability and conversion attribution.
- Entertainment:Passive and interactive content consumption targets mass-market reach and session duration metrics.
Contract value concentrates in Simulation. Adoption velocity is expanding most quickly in Training.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Photonics engineering talent concentrates in Florida and California, anchoring spatial computing R&D corridors that feed defense and enterprise verticals nationwide.
California
Silicon Valley clusters dominate consumer AR hardware and software platform development, with social media integration driving ecosystem choices. SB 1018 clean energy procurement mandates pressure sustainable electronics manufacturing certification across West Coast supply chains. San Francisco Bay Area operators specialize in subscription-based enterprise licensing for industrial training modules.
Texas
Houston's Texas Medical Center anchors pilot-to-deployment pathways for FDA-cleared surgical navigation systems, with neurosurgical accuracy requirements driving premium pricing. Department of Defense training budgets in Dallas-Fort Worth sustain demand for ruggedized simulation headsets. Austin's emerging tech corridor attracts spatial computing startups seeking lower operational costs than coastal metros.
Florida
Magic Leap sustains concentrated photonics R&D operations in the state, leveraging legacy telecom and defense contractor talent pools for waveguide design expertise. The region lacks comparable clean energy procurement pressure, reducing compliance overhead for hardware prototyping. Orlando's simulation training heritage connects to defense procurement cycles for mixed reality maintenance applications.
Washington State
Seattle's aerospace corridor drives OSHA-compliant industrial VR training adoption, with channel partners restructuring compensation around recurring revenue retention. Pacific Northwest cloud infrastructure proximity enables 5G mmWave cloud-rendered enterprise deployments without local compute hardware. Boeing supplier networks generate captive demand for passthrough camera architectures in manufacturing environments.
Ohio
Cleveland Clinic anchors surgical innovation programs requiring millimeter registration accuracy for AR navigation overlays, with FDA digital health software guidance tightening prospective study requirements. Midwest utilities and manufacturing operators expand VR simulation adoption under OSHA workplace safety mandates for hazardous environment preparation. Cincinnati's logistics hubs pilot hands-free AR workflow guidance for warehouse operations.
US Augmented and Virtual Reality Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the US AR/VR landscape, with headset OEMs bearing micro-OLED panel costs while software vendors capture recurring licensing margins. The vendor base separates into three tiers: defense contractors managing multi-year certification programs, FDA-cleared medical device specialists, and consumer electronics platforms chasing social channel integration. Consolidation pressure concentrates in enterprise software, where subscription retention metrics determine valuation. Dominant competitive moves include strategic partnerships for photonics engineering access and geographic expansion into Texas Medical Center corridors for clinical validation.
Within the medical device archetype, Medivis exemplifies FDA-cleared surgical navigation specialization, while Magic Leap occupies a position in enterprise spatial computing R&D. Snap Inc represents consumer AR glasses distribution through social media channel integration. These three companies illustrate how competitive positioning diverges between premium healthcare margins, subsidized military contracts, and mass-market volume strategies.
| Leading Market Players |
|---|
| Marxent |
| Medivis |
| Magic Leap |
| Wildnet Edge |
| VITURE Inc |
| Snap Inc |
| Avegant |
| Illumix |
| Mojo Vision |
| Others |
Pricing and Supply Chain Analysis
OSHA workplace safety mandates for industrial VR training are forcing procurement departments toward subscription-based licensing models that bundle hardware refresh cycles with software maintenance, compressing upfront capital expenditure into recurring operational budgets and reshaping how vendors structure component sourcing commitments.
Pricing Analysis
Bundled subscription services versus unbundled perpetual licensing splits the US AR/VR market into two distinct commercial architectures. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared surgical navigation systems from OSHA-compliant industrial training modules and mass-market consumer peripherals. Price differentiation stems from certification grade and after-sales service intensity. Cost compression in consumer VR hardware is intensifying because micro-OLED panel suppliers concentrate in East Asian fabrication facilities. Gaming end users exhibit highest price sensitivity; healthcare institutions demonstrate lowest sensitivity due to liability exposure from uncertified devices.
Supply Chain Analysis
California SB 1018 clean energy procurement mandates are reshaping sourcing requirements for West Coast electronics manufacturers, pressuring headset OEMs to certify sustainable supply chains for battery and display components. Micro-OLED panels, waveguide optics, and spatial tracking cameras draw from Taiwan, South Korea, and Japan. Single-source vulnerability concentrates in East Asian micro-OLED fabrication facilities where capacity allocation favors smartphone display contracts. Distribution runs through defense procurement channels, hospital GPO networks, and consumer electronics retail chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US AR/VR market represents a late-cycle quality story where FDA clinical validation requirements and OSHA safety mandates are filtering marginal vendors, concentrating procurement authority with buyers who prioritize certified reliability over lowest-unit-cost sourcing.
For Market Incumbents: Anticipate margin compression from cloud-rendered enterprise VR architectures that eliminate local compute hardware requirements. Lock in photonics engineering talent through acquisitions of legacy telecom and defense contractor specialists in Florida and California. Secure multi-year workforce certification contracts with Pentagon training budgets to establish recurring revenue visibility. For New Entrants and Emerging Players: The gap between premium FDA-cleared surgical systems and economy-tier consumer peripherals offers white-space entry for mid-market industrial training solutions. Target OSHA-compliant utilities and manufacturing operators across the Midwest where incumbent coverage remains thin. Pursue pilot-to-deployment pathways through Houston's Texas Medical Center corridor for clinical validation credibility. For Investors and Strategic Acquirers: Asymmetric upside sits with enterprise software vendors capturing subscription licensing margins rather than hardware OEMs bearing micro-OLED panel cost volatility. Five-to-ten-year viability favors FDA-cleared medical device specialists with prospective outcome study documentation. Monitor FDA 510(k) review timeline acceleration as inflection indicator for clinical AR deployment velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Seattle aerospace corridor channel partners are restructuring compensation around recurring revenue retention metrics. |
| Regulatory Approval Pathway | FDA digital health software guidance updates require prospective studies for AR surgical planning tools. |
| Strategic Partnership | Photonics engineering access partnerships with Florida defense contractors constrain headset OEM hiring pipelines. |
| Acquisition of Specialist Firm | Waveguide design expertise concentrates in legacy telecom and defense contractors. |
| Geographic Expansion | Texas Medical Center corridors offer concentrated pilot-to-deployment pathways for clinical validation. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with defense procurement officers, FDA regulatory affairs leads, hospital biomedical engineers, and industrial training directors with secondary validation against SEC filings, FDA 510(k) submission databases, and hyperscaler capex disclosures. Bottom-up and top-down triangulation cross-checked headset shipment estimates against enterprise software licensing revenue pools.
Comparable historical reference periods anchored the forecast window across the analysis window, with segmentation modeling across product type, end user vertical, technology architecture, and application use case. CAGRs derived from growth rate convergence analysis incorporating defense budget cycle timing, FDA review pipeline velocity, and 5G mmWave spectrum deployment trajectories.
Caveats apply where FDA digital health software guidance revisions or OSHA workplace safety standard updates could materially shift the outlook, and forecasts reflect assumptions about micro-OLED supply chain capacity allocation and photonics engineering labor availability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
Social VR Market
Virtual Reality (VR) and Augmented Reality (AR)
VR Box Market
Virtual Reality (VR) and Augmented Reality (AR)
Wireless AR Glass Market
Virtual Reality (VR) and Augmented Reality (AR)
VR Head Show Market
Virtual Reality (VR) and Augmented Reality (AR)
Global AR and VR Smart Glasses Market
Virtual Reality (VR) and Augmented Reality (AR)
Holographic AR Display Market
Virtual Reality (VR) and Augmented Reality (AR)
Automotive Augmented Reality (AR) HUD System Market
Virtual Reality (VR) and Augmented Reality (AR)
Florida Augmented and Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Augmented Reality and Virtual Reality (AR/VR) in Aviation Market
Virtual Reality (VR) and Augmented Reality (AR)
Asia-Pacific Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
UK Virtual Tour Market
Virtual Reality (VR) and Augmented Reality (AR)
US Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
VR Amusement Equipment Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Dressing Room Market
Virtual Reality (VR) and Augmented Reality (AR)
AR in Healthcare Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Augmented Reality (AR) and Mixed Reality (MR) Market