
 3D Telepresence Market | 2026-2036
3D Telepresence Market Size, Share, and Industry Trends Forecast 2026-2036
3D Telepresence Market Analysis
Multi-source component procurement is recalibrating how vendors manage optical sensor arrays and real-time rendering chipsets. Cisco Systems Inc. anchors its position through proprietary codec ecosystems and enterprise channel density. Sony Corporation leverages broadcast-grade camera expertise to differentiate in high-fidelity capture subsystems. Microsoft Corporation competes via cloud-native delivery platforms that integrate with existing productivity stacks.
3D telepresence denotes immersive communication systems that capture, transmit, and reconstruct three-dimensional human likeness in real time using stereoscopic depth sensors, photogrammetric arrays, and volumetric display surfaces. The technology serves commercial and industrial users requiring spatial presence fidelity beyond conventional video conferencing. Hardware segments currently dominate installed value due to specialized capture equipment and display volumes, though software layers are capturing disproportionate margin expansion as AI-driven compression reduces bandwidth requirements. Holography technology leads in premium enterprise deployments while 3D video maintains broader accessibility across mid-market corporate users.
The FCC governs spectrum allocation for wireless 3D transmission in the United States while the EU AI Act imposes algorithmic transparency requirements on facial reconstruction systems deployed in Europe. GDPR mandates explicit consent frameworks for biometric depth data capture, directly constraining product design for European installations. ISO standards for immersive display ergonomics shape hardware certification pathways across jurisdictions. Stakeholders must weigh regulatory compliance costs against latency-sensitive performance benchmarks when selecting deployment architectures for cross-border implementations.
Market Dynamics
Real-time volumetric compression is compressing bandwidth requirements below fiber threshold limits, enabling 3D telepresence deployment over standard enterprise networks previously incapable of supporting holographic data streams.
Growth Catalysts
- EU AI Act compliance mandates:European healthcare systems are accelerating procurement of algorithmically transparent facial reconstruction systems to meet biometric processing standards ahead of enforcement deadlines.
- Surgical training digitization:Academic medical centers in the United States are replacing cadaver-based instruction with immersive remote collaboration platforms that reduce physical facility constraints.
- Photogrammetric sensor cost curves:Consumer electronics manufacturing scale is driving depth camera module prices downward, expanding addressable mid-market corporate budgets.
Market Restraints
- Specialized display volume concentration:Manufacturing of holographic projection substrates concentrates among East Asian component suppliers, creating single-source vulnerability for European system integrators.
- GDPR biometric consent friction:Explicit opt-in requirements for depth data capture are extending European sales cycles and complicating multi-tenant deployment architectures.
- Conventional video substitution:Mature 4K videoconferencing platforms satisfy presence requirements for price-sensitive enterprise segments without holographic fidelity.
Strategic Opportunities
- Remote industrial inspection:German automotive manufacturers are piloting 3D telepresence for real-time quality verification across dispersed assembly plants, creating pull for ruggedized capture hardware.
- Japan METI digital infrastructure subsidies:National funding for Society 5.0 initiatives is offsetting deployment costs for smart city holographic communication nodes.
- Neural radiance field convergence:Integration of NeRF rendering with existing telepresence codecs is enabling photorealistic reconstruction from sparse sensor arrays.
Industry Challenges
- Volumetric data engineering scarcity:Pipeline optimization for real-time point cloud transmission requires specialized compression expertise concentrated among broadcast technology veterans.
- ISO 9241-307 ergonomic certification:Display luminance and motion-to-photon latency testing timelines are delaying product launches for premium enterprise segments.
- Legacy AV infrastructure retrofit complexity:Existing conference room investments in conventional displays and control systems require costly overlay architectures for 3D capability addition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D Telepresence Market |
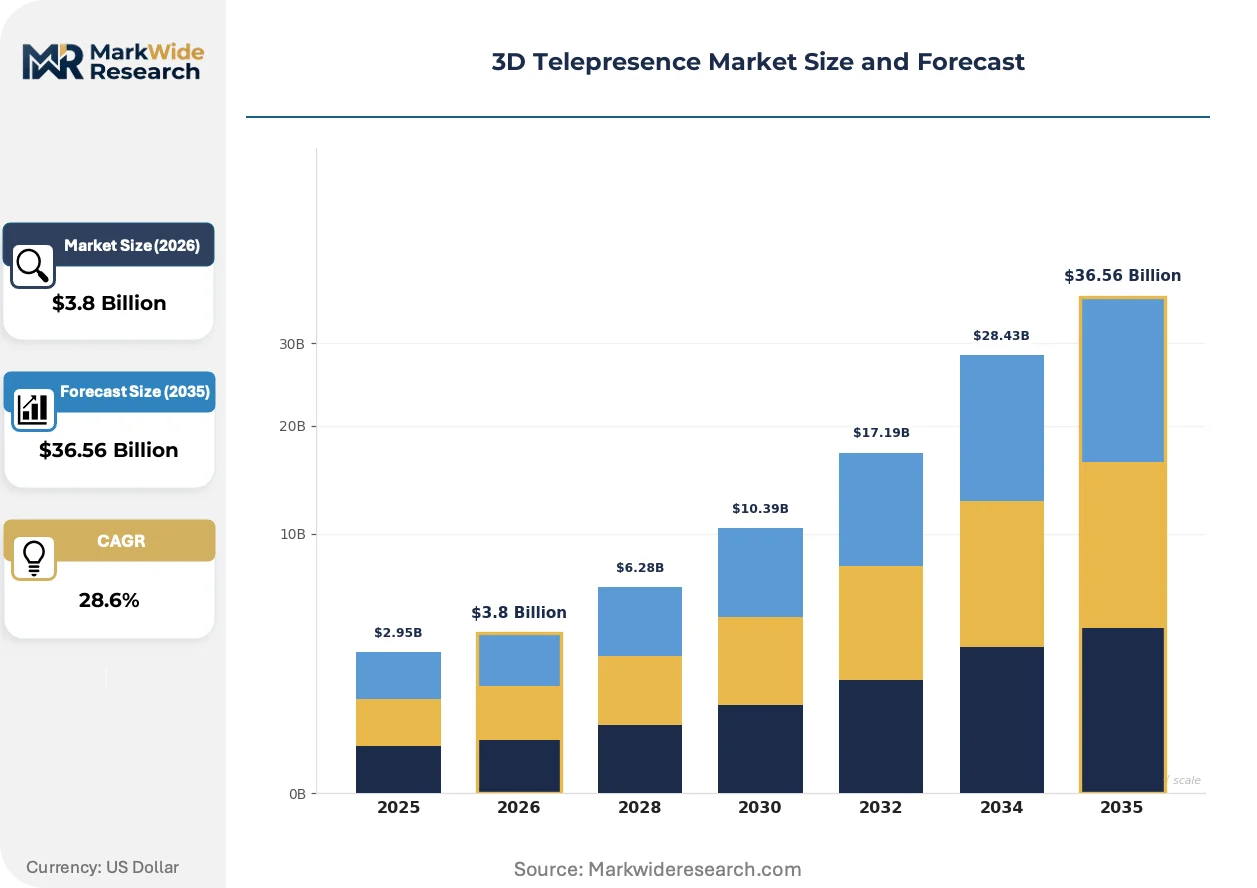
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $36.56 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hardware, Software, Service, Infrastructure Technology: Virtual Reality, Augmented Reality, Holography, 3D Video End User: Corporate, Education, Healthcare, Entertainment Deployment: Cloud-Based, On-Premises, Hybrid, Edge Computing |
| Companies Covered | Digital Video Enterprises Inc., Sony Corporation, Cisco Systems Inc., Musion 3D, TelePresence Tech, Microsoft Corporation, ZTE Corporation, Panasonic Corporation, Polycom Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Telepresence Market Emerging Trajectories
Edge-based inference is redistributing computational load away from centralized cloud render farms, altering how vendors architect latency-sensitive holographic delivery systems.
Neural compression codecs are decentralizing rendering workloads to local GPU clusters while maintaining photorealistic output quality. Automotive design studios in Stuttgart and Detroit are adopting these distributed architectures for real-time collaborative clay modeling reviews. The shift is compressing infrastructure requirements for mid-market buyers previously excluded by cloud render subscription economics.
The EU AI Act's algorithmic transparency requirements are mandating explainability documentation for facial reconstruction neural networks deployed in European healthcare settings. System vendors must now maintain model cards and bias audit trails as standard product deliverables. German hospital procurement committees are prioritizing compliant platforms, creating certification-driven vendor selection.
Enterprise buyers are consolidating vendor relationships around integrated hardware-software-service bundles rather than component procurement. Japanese manufacturing conglomerates are demanding single-source accountability for capture, transmission, and display subsystems. This pattern concentrates contract value with full-stack providers while marginalizing point-solution specialists in Tokyo and Osaka enterprise accounts.
3D Telepresence Market Segmentation
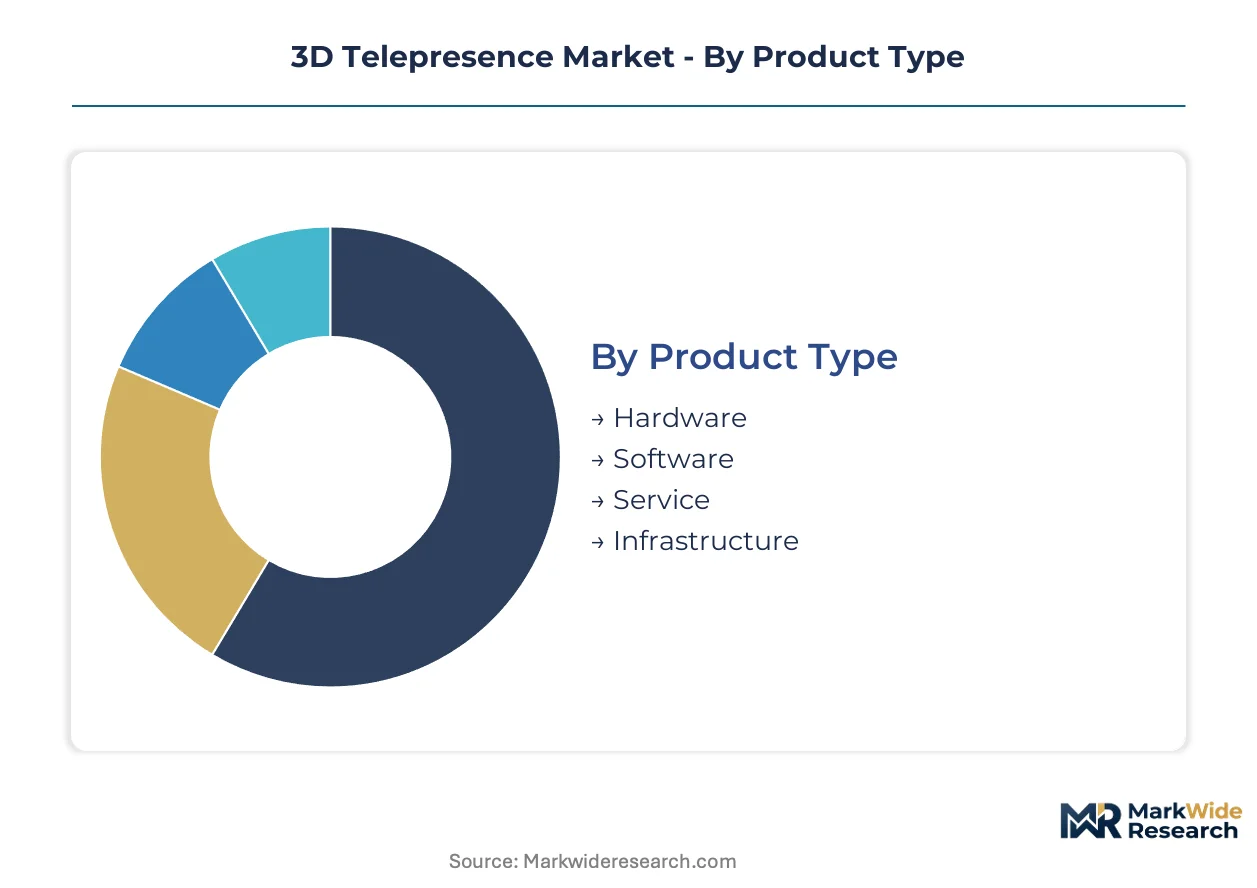
Segmentation in 3D telepresence reveals how value concentrates across capture hardware, rendering software, and service layers. Vendors must align portfolio depth with where enterprise budgets are flowing.
Product Type:
Supply concentration in optical sensor arrays and holographic projection substrates determines margin distribution across the value chain.
- Hardware:Specialized depth cameras, volumetric capture rigs, and holographic display volumes constitute the installed value base. German automotive manufacturers and Japanese smart city deployments currently absorb the majority of premium hardware shipments.
- Software:Real-time compression codecs, facial reconstruction algorithms, and spatial audio engines capture expanding margin share as AI-driven bandwidth reduction improves. European healthcare procurement committees now mandate algorithmic transparency documentation as standard deliverables.
- Service:Integration consulting, managed deployment, and ongoing technical support address legacy AV retrofit complexity.
- Infrastructure:Fiber-optic transmission upgrades and edge compute node provisioning enable latency-sensitive holographic delivery.
Today's leader: Hardware. Tomorrow's challenger: Software.
Technology:
Cost tier stratification separates accessible mid-market solutions from premium enterprise deployments requiring photorealistic fidelity.
- Holography:Volumetric light field reconstruction delivers the highest spatial presence fidelity through specialized projection substrates. Academic medical centers in the United States and corporate headquarters in Tokyo currently dominate demand for these premium installations.
- 3D Video:Stereoscopic depth transmission over standard enterprise networks addresses broader corporate budgets through reduced infrastructure requirements. Mid-market adoption in Germany and Japan is climbing fastest as photogrammetric sensor costs decline.
- Virtual Reality:Headset-mediated immersive environments serve training and simulation use cases with full environmental control.
- Augmented Reality:Spatial computing overlays blend holographic presence with physical workspace contexts for collaborative design reviews.
Current volume concentrates in 3D Video. Steepest expansion trajectory belongs to Holography.
End User:
Application-specific performance requirements reshape how vendors configure capture density and display specifications.
- Healthcare:Surgical training digitization and remote specialist consultation demand sub-50ms motion-to-photon latency with biometric depth data compliance. United States academic medical centers are replacing cadaver-based instruction with immersive platforms.
- Corporate:Distributed engineering collaboration and executive telepresence drive the largest absolute spending volume across Fortune 500 headquarters.
- Education:Remote laboratory access and immersive classroom experiences create pull for mid-fidelity 3D video systems.
- Entertainment:Live performance holography and interactive media experiences test the boundaries of real-time rendering scale.
Dominant spender: Corporate. Fastest qualification timelines: Healthcare.
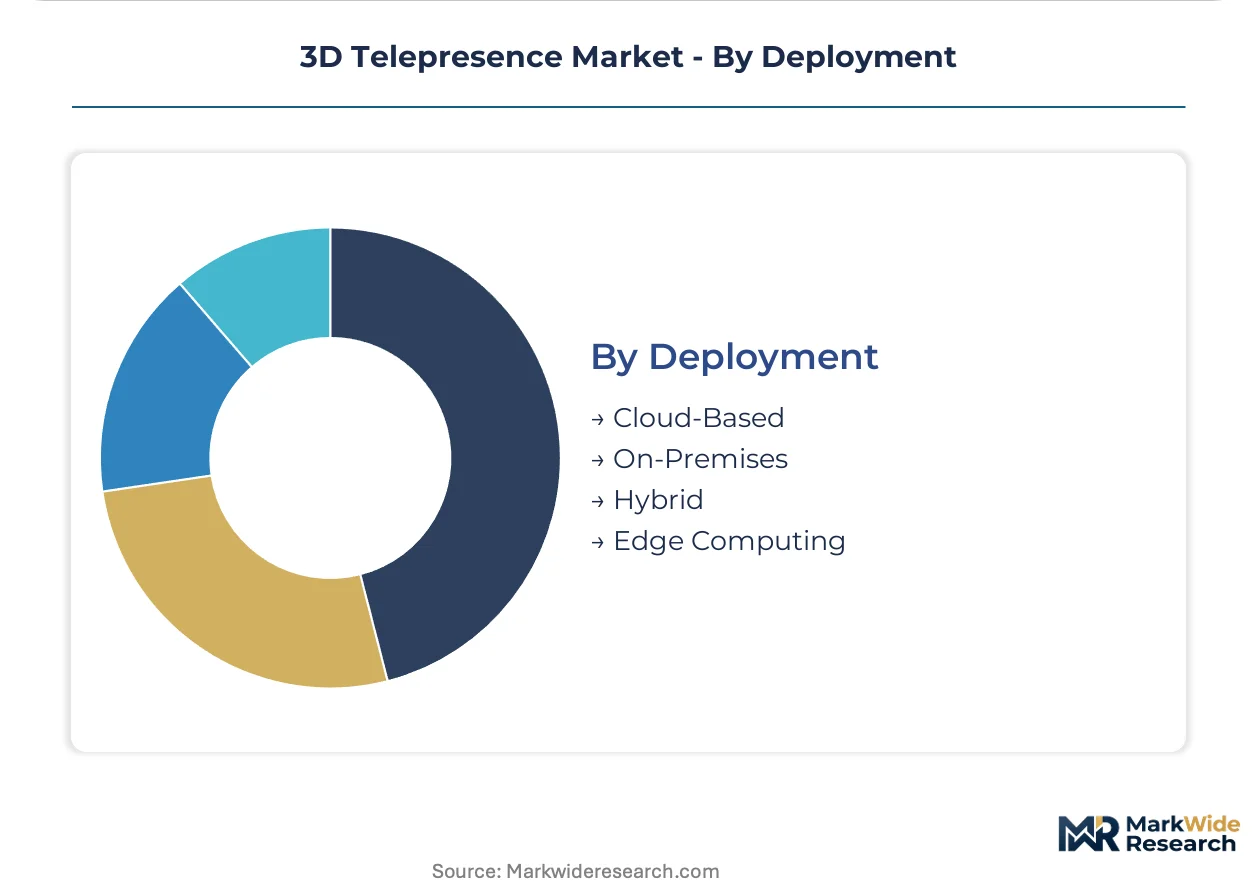
Deployment:
Customer IT maturity and data sovereignty requirements fragment architecture preferences across enterprise segments.
- Cloud-Based:Centralized render farms and managed transmission services reduce capital requirements for mid-market buyers. GDPR biometric consent frameworks complicate multi-tenant European deployments.
- Edge Computing:Local GPU clusters with neural compression codecs redistribute computational load for latency-sensitive automotive design studios in Stuttgart and Detroit.
- On-Premises:Captive infrastructure addresses classified government and defense applications with strict air-gap requirements.
- Hybrid:Split architectures process sensitive capture data locally while leveraging cloud scale for non-critical rendering workloads.
Current default: Cloud-Based. Emerging preference: Edge Computing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tokyo's corporate headquarters cluster drives premium holographic installation demand. Enterprise IT spending concentrates in three national markets where fiber infrastructure and regulatory frameworks align with real-time volumetric transmission requirements.
United States
Academic medical centers in Boston and Baltimore are replacing cadaver-based surgical instruction with immersive remote collaboration platforms. FCC spectrum allocation governs wireless 3D transmission while HIPAA frameworks shape biometric depth data handling protocols. Detroit automotive design studios deploy edge-compute holographic systems for real-time clay modeling reviews across dispersed engineering teams.
Germany
Stuttgart automotive manufacturers pilot ruggedized 3D telepresence for cross-plant quality verification during assembly operations. EU AI Act algorithmic transparency mandates constrain facial reconstruction neural networks deployed in European healthcare settings. Bavarian hospital procurement committees prioritize compliant platforms with model cards and bias audit documentation as standard deliverables.
Japan
METI digital infrastructure subsidies under Society 5.0 initiatives offset deployment costs for smart city holographic communication nodes. Osaka manufacturing conglomerates demand single-source accountability across capture, transmission, and display subsystems. Tokyo corporate headquarters absorb the majority of premium holographic display volume shipments in the Asia-Pacific region.
United Kingdom
London financial services firms evaluate immersive telepresence for executive client engagement requiring spatial presence fidelity. GDPR explicit consent frameworks extend sales cycles for multi-tenant biometric depth data deployments. Cambridge technology clusters host compression codec development for real-time point cloud transmission optimization.
South Korea
Seoul-based electronics conglomerates integrate depth camera modules into enterprise collaboration hardware leveraging consumer manufacturing scale. National broadband infrastructure supports sub-50ms latency requirements for holographic delivery. Busan industrial zones test augmented reality overlays blending holographic presence with physical workspace contexts for shipbuilding design reviews.
3D Telepresence Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized capture hardware and edge-render software niches. The vendor base stratifies across full-stack integrators, component specialists, and cloud-native delivery platforms. Three archetypes dominate: broadcast-heritage capture equipment manufacturers, enterprise IT incumbents with codec ecosystems, and telecommunications equipment providers with transmission infrastructure. Consolidation pressure favors integrated hardware-software-service bundles over point-solution procurement.
Within the full-stack integration tier, Cisco Systems Inc. and Microsoft Corporation exemplify divergent architectural approaches. Sony Corporation represents broadcast-grade capture heritage applied to high-fidelity depth sensor arrays. ZTE Corporation and Panasonic Corporation occupy positions among Asian telecommunications and electronics conglomerates with integrated display manufacturing capabilities. These entities anchor competitive dynamics around proprietary codec ecosystems versus open cloud-native delivery platforms.
| Leading Market Players |
|---|
| Digital Video Enterprises Inc. |
| Sony Corporation |
| Cisco Systems Inc. |
| Musion 3D |
| TelePresence Tech |
| Microsoft Corporation |
| ZTE Corporation |
| Panasonic Corporation |
| Polycom Inc. |
| Others |
Supply Flow & Price Mechanics
Holographic fidelity tiering separates premium enterprise deployments from accessible mid-market 3D video systems, with that divergence manifesting in both component-level pricing power and geographic sourcing strategies. Algorithmic transparency certification under the EU AI Act adds a compliance-cost ladder that reshapes supplier selection for European healthcare buyers.
Pricing Analysis
Photogrammetric sensor cost declines pass through to mid-market 3D video tiers while holographic projection substrates retain pricing power due to East Asian manufacturing concentration. Three-tier pricing structure across premium holographic, standard 3D video, and economy headset-mediated VR separates healthcare procurement committees from corporate training budgets. Cost compression in depth camera modules intensifies as consumer electronics manufacturing scale expands addressable corporate segments. Education buyers exhibit highest price sensitivity; academic medical centers demonstrate lowest sensitivity due to surgical training digitization mandates.
Supply Chain Analysis
Specialized volumetric compression engineers concentrate in Stuttgart broadcast technology clusters and Tokyo post-production hubs, constraining pipeline optimization talent availability. Holographic display substrate manufacturing draws from South Korean and Japanese component suppliers, while depth camera module assembly rests on Chinese and Taiwanese electronics manufacturing. Single-source vulnerability in projection substrate supply creates procurement risk for European system integrators. Distribution runs through enterprise IT channel partners with AV integration capabilities and direct OEM relationships for Fortune 500 headquarters deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Quality specifications are hardening as German hospital procurement committees mandate algorithmic transparency documentation ahead of EU AI Act enforcement, favoring vendors with certified facial reconstruction platforms over commodity alternatives.
For Market Incumbents: Deploy proprietary codec ecosystem leverage to lock in enterprise channel density before cloud-native alternatives achieve parity. Defensive consolidation moves should prioritize edge-compute rendering partnerships with Stuttgart automotive design studios and captive supply of holographic projection substrates to offset East Asian supplier concentration. The threat of neural radiance field convergence from sparse sensor arrays demands accelerated R&D in compression efficiency.
For New Entrants and Emerging Players: Begin with mid-market 3D video corporate training segments in Japan where METI subsidies offset deployment friction and incumbent bundling is weakest. White-space targets include ruggedized capture hardware for German automotive cross-plant quality verification and algorithmic transparency compliance tooling for EU healthcare procurement. A channel partnership with established AV integrators offers the most penetrable go-to-market angle against full-stack incumbents.
For Investors and Strategic Acquirers: Consolidation pressure builds where point-solution specialists lack single-source accountability across capture-transmission-display subsystems demanded by Osaka manufacturing conglomerates. Long-term viability favors full-stack providers with certified healthcare platforms and edge-render software capabilities. Acquisition target archetype: broadcast-heritage compression codec developers with volumetric data engineering expertise. The signal to watch is Japanese smart city holographic node deployment velocity as a proxy for infrastructure subsidy effectiveness.
| Strategic Initiative | Industry Significance |
|---|---|
| Algorithmic Transparency Certification | EU AI Act compliance documentation opens German hospital procurement channels previously closed to non-compliant vendors. |
| Edge-Compute Rendering Partnership | Local GPU cluster deployment captures Stuttgart automotive design studio demand for sub-50ms latency clay modeling reviews. |
| Holographic Substrate Supply Agreement | Captive supply of East Asian projection components mitigates single-source vulnerability for European system integrators. |
| Neural Compression Codec Development | NeRF integration with existing telepresence codecs enables photorealistic reconstruction from sparse sensor arrays at reduced bandwidth. |
| Smart City Infrastructure Pilot | METI-funded Society 5.0 holographic communication nodes in Tokyo establish reference deployments for Asia-Pacific enterprise expansion. |
Methodological Framework
Coverage spans the United States, Germany, Japan, the United Kingdom, and South Korea, with primary inputs from each market informing demand calibration. The analysis combines executive interviews with enterprise IT procurement officers, hospital biomedical engineering directors, automotive design studio technical leads, and broadcast technology compression specialists with secondary validation against FCC spectrum allocation filings, EU AI Act implementation guidance, METI subsidy program disclosures, and ISO 9241-307 ergonomic certification records. Bottom-up segment sizing triangulates against top-down macroeconomic anchors.
Rate-of-change decomposition separates volume expansion from value-per-unit trajectories across hardware, software, service, and infrastructure segments. The analytical framework models deployment architecture preferences, technology cost tier stratification, end-use application requirements, and regional regulatory cluster variations throughout the forecast period. CAGRs derive from installed base growth curves, replacement cycle assumptions, and penetration rate ceilings by enterprise size tier. Industry-specific inputs include photogrammetric sensor cost curves and fiber infrastructure deployment timelines.
Several conditions sit outside the modeled scope, including unforeseen bandwidth infrastructure disruptions, algorithmic transparency standard revisions, and holographic display substrate supply shocks. Forecasts reflect assumptions about enterprise IT budget allocation continuity and regulatory enforcement timelines. Material deviation in EU AI Act implementation velocity or METI subsidy program extension warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
AR & VR in Aviation Market
Virtual Reality (VR) and Augmented Reality (AR)
Middle East Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Augmented Learning Market
Virtual Reality (VR) and Augmented Reality (AR)
US Virtual Tour Market
Virtual Reality (VR) and Augmented Reality (AR)
Extended Reality (XR) Market
Virtual Reality (VR) and Augmented Reality (AR)
VR Box Glasses Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality All-In-One Headset Market
Virtual Reality (VR) and Augmented Reality (AR)
North America Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Asia-Pacific Augmented Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality (VR) Simulator Market
Virtual Reality (VR) and Augmented Reality (AR)
US Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Augmented Reality (AR) Market
Virtual Reality (VR) and Augmented Reality (AR)
Social VR Market
Virtual Reality (VR) and Augmented Reality (AR)
VR Firefighter Simulator Market
Virtual Reality (VR) and Augmented Reality (AR)
Automotive Augmented Reality (AR) HUD System Market
Virtual Reality (VR) and Augmented Reality (AR)
South Korea Metaverse Market