
 Wireless AR Glass Market | 2026-2036
Wireless AR Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Wireless AR Glass Market Insights
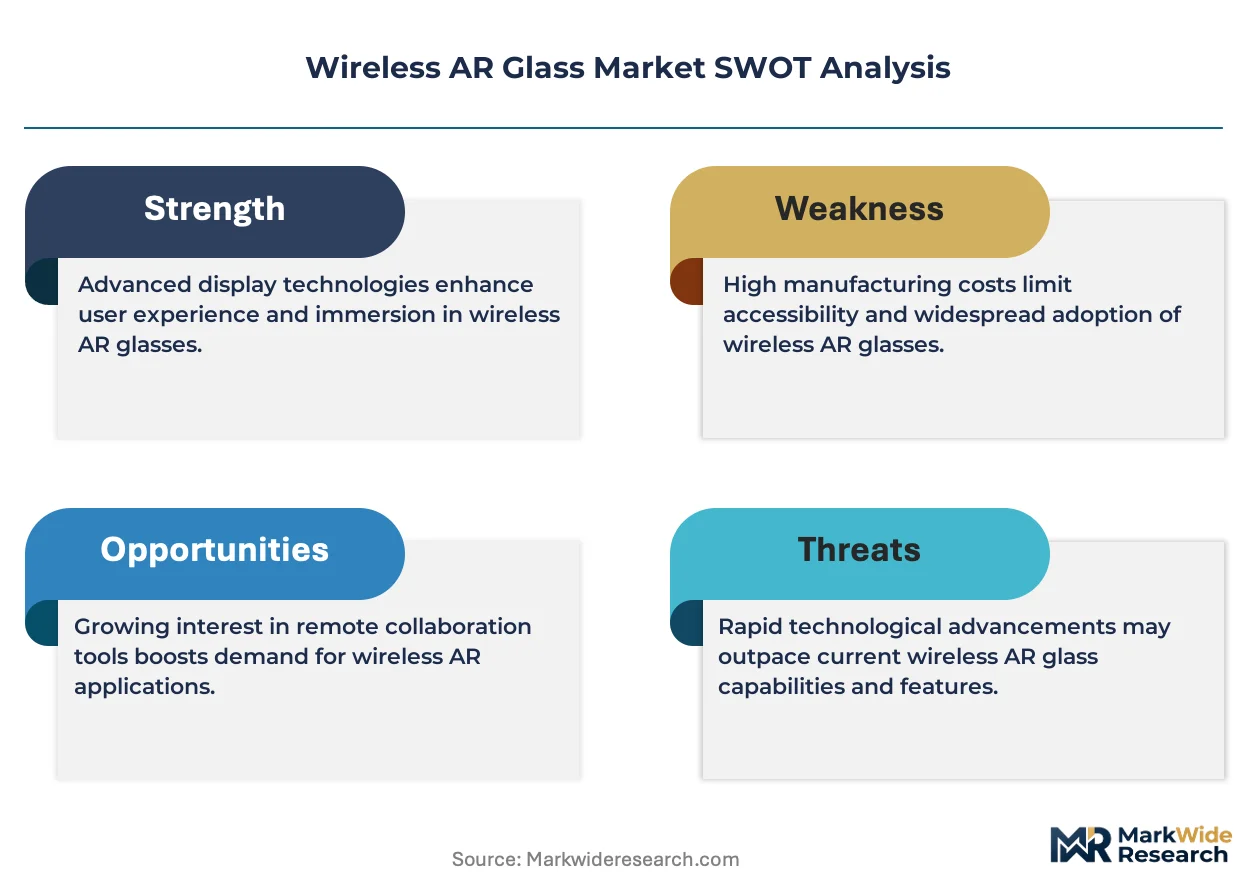
Capital-intensity divergence between custom silicon foundry access and off-the-shelf component sourcing is redrawing competitive boundaries in wireless AR glass manufacturing. XREAL, Inc. leverages vertical integration into micro-OLED supply partnerships to control bill-of-materials escalation. Magic Leap, Inc. sustains R&D intensity through photonics foundry relationships that anchor its waveguide technology leadership. Microsoft dominates enterprise channel control, positioning its industrial SKU portfolio across Fortune 500 deployment frameworks.
Wireless AR glasses are untethered optical see-through displays that overlay digital information onto the physical environment using waveguide or projection optics, typically weighing under 80 grams and operating via Wi-Fi or proprietary low-latency protocols for real-time spatial computing. Their primary commercial purpose spans hands-free workflow guidance, immersive training simulation, and contextual data visualization in field operations. Augmented Reality Glasses currently occupy the largest addressable volume pool, while Mixed Reality Headsets command premium pricing through passthrough camera fidelity and spatial anchoring precision. Waveguide Technology leads optical architecture adoption for slim form factors, though Projection Technology sustains growth in price-sensitive enterprise bulk deployments where field-of-view breadth outweighs aesthetic minimalism.
FCC equipment authorization requirements govern radio-frequency emissions for wireless AR glasses sold in the United States, while the EU AI Act imposes risk-classification obligations on devices deploying biometric inference or real-time environmental analysis. EMA medical device coordination with national competent authorities in Germany and France shapes clinical trial pathways for surgical navigation applications. Stakeholders must monitor evolving eye-safety exposure limits from IEC laser classification standards and anticipate how CSRD supply-chain disclosure mandates will force component traceability through Asian micro-display sourcing networks.
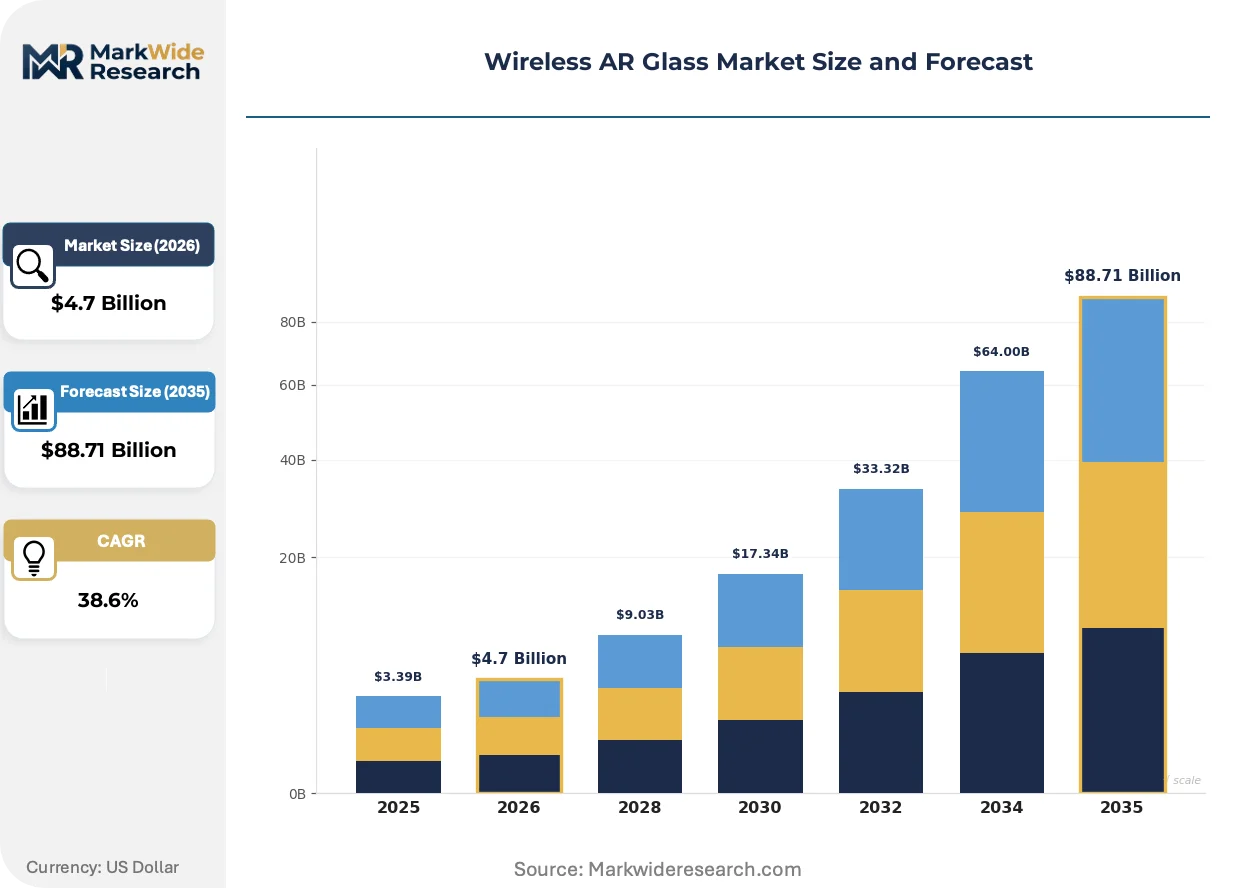
Market Dynamics
Waveguide foundry concentration in East Asian electronics clusters is compressing optical component lead times while EU AI Act compliance costs are diverting R&D budgets toward biometric inference documentation. This dual pressure is restructuring competitive boundaries between vertically integrated device makers and modular assemblers.
Growth Catalysts
- Industrial workflow digitization:Enterprise manufacturing in Germany, France, and Japan is accelerating hands-free guidance deployment for assembly line quality assurance and maintenance protocols.
- FDA digital health pathway expansion:The agency's evolving guidance for immersive medical displays is enabling surgical navigation trials that validate clinical efficacy for reimbursement.
- Micro-display fab co-location:Shenzhen and Seoul electronics clusters concentrate waveguide foundries adjacent to final assembly, reducing logistics friction for high-mix production runs.
Market Restraints
- Custom silicon foundry access costs:Captive supply of micro-OLED backplanes requires multi-year capacity commitments that lock working capital for emerging entrants.
- Single-source waveguide dependency:Photonics foundry relationships in Taiwan and South Korea concentrate critical optical component supply among three dominant suppliers.
- IEC laser classification compliance:Evolving eye-safety exposure limits force iterative hardware redesigns that extend certification timelines by 8-14 months.
Strategic Opportunities
- CSRD supply-chain disclosure mandates:The EU directive forces component traceability through Asian micro-display sourcing networks, creating first-mover advantage for audit-ready manufacturers.
- Wi-Fi 7 low-latency protocol adoption:The wireless standard's timing precision enables untethered spatial computing for motion-intensive field operations previously requiring tethered headsets.
- Indian electronics manufacturing incentives:PLI scheme subsidies for component localization attract waveguide assembly investments that serve Middle Eastern and African distribution channels.
Industry Challenges
- Photonics systems engineering talent scarcity:Waveguide design and optical simulation expertise concentrates among legacy telescope and semiconductor lithography specialists with limited mobility.
- EMA-FDA parallel trial coordination:Divergent clinical evidence requirements for surgical navigation applications force redundant study designs that inflate regulatory submission costs.
- Legacy ERP integration complexity:Enterprise buyers require API compatibility with incumbent manufacturing execution systems that lack native spatial computing data structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wireless AR Glass Market |
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $88.71 Billion |
| CAGR (2026 – 2036) | 38.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Augmented Reality Glasses, Mixed Reality Headsets, Smart Eyewear, Interactive Glasses Technology: Waveguide Technology, Projection Technology, Optical See-Through, Video See-Through End User: Gaming Industry, Healthcare Sector, Industrial Sector, Education Sector Distribution Channel: Online Retail, Offline Retail, Direct Sales, B2B Sales |
| Companies Covered | XREAL, Inc., Magic Leap, Inc., Microsoft, Seiko Epson Corporation, Rokid, RealWear, Inc., Vuzix, RayNeo, Meta, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wireless AR Glass Market Trends and Innovations
Optical architecture decisions are locking in competitive positioning for the next hardware refresh cycle, with waveguide slimness trading against field-of-view breadth in ways that segment addressable use cases. These technical commitments cascade through supply chain partnerships and certification roadmaps.
Surface-relief grating waveguides are displacing holographic optical elements in enterprise-grade devices by delivering superior luminance efficiency at sub-2-millimeter thickness. Automotive inspection teams at German OEMs are piloting these optics for engine bay overlay guidance, compressing the acceptable form factor threshold from 80 grams toward 50 grams. This displacement is forcing projection-based competitors toward niche price-sensitive bulk deployments where aesthetic minimalism carries less buyer weight.
The EU AI Act's risk-classification framework for biometric inference is mandating conformity assessment procedures that extend product launch timelines for devices deploying real-time environmental analysis. Medical device manufacturers seeking surgical navigation approval must now document algorithmic decision transparency alongside traditional hardware safety testing. French and German notified bodies are developing specialized audit capacities that concentrate compliance expertise within specific national competent authorities.
Enterprise procurement teams are consolidating vendor relationships around industrial SKU portfolios that bundle hardware, fleet management software, and tiered support into multi-year framework agreements. Fortune 500 manufacturing divisions in Japan are displacing pilot-project purchasing with standardized deployment templates that specify interoperability with existing digital twin infrastructure. This consolidation favors suppliers with established channel control and documented integration protocols over point-solution specialists.
Wireless AR Glass Market Segmentation
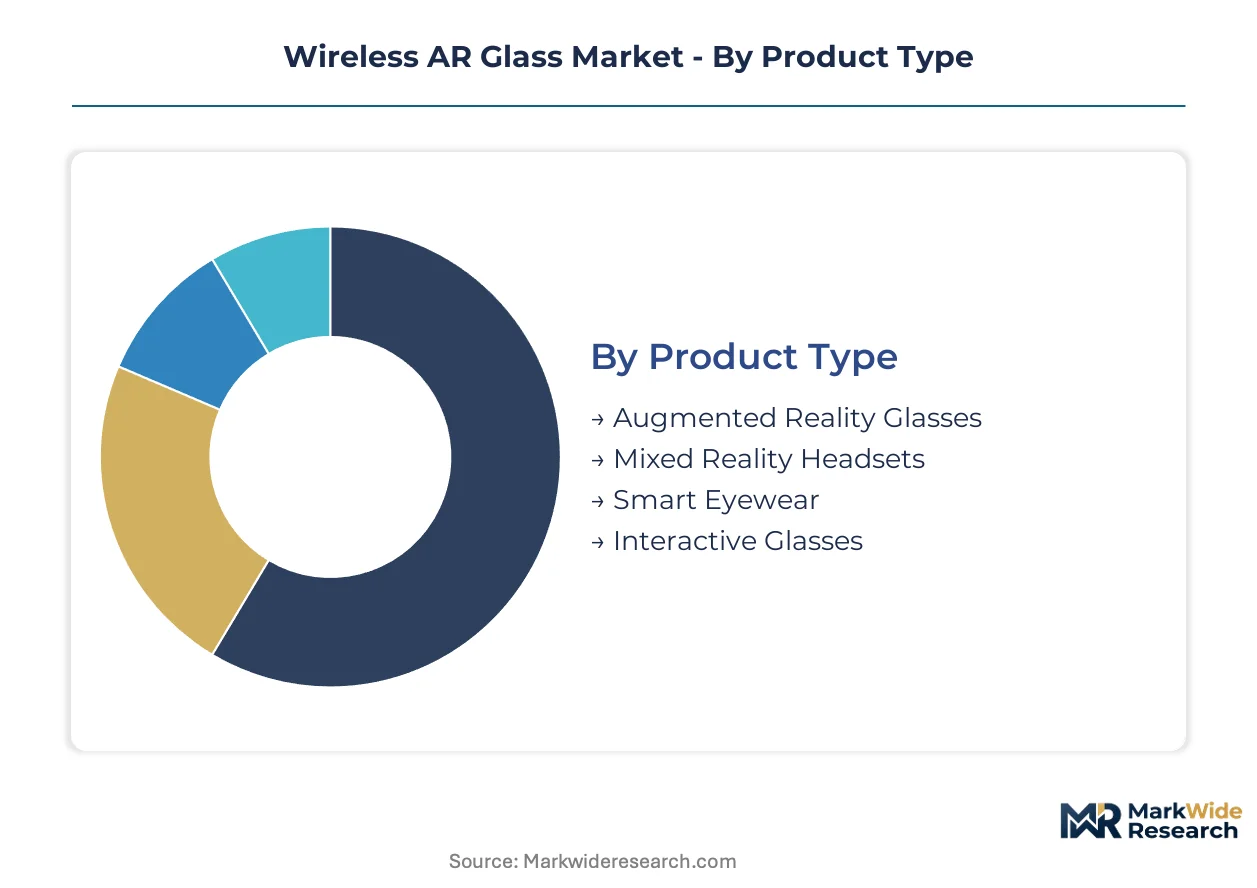
Optical architecture and regulatory classification create distinct commercial zones within wireless AR glass manufacturing. Each segment carries unique certification burdens and supply chain requirements that reshape vendor positioning.
Product Type:
FDA digital health pathways and EU AI Act risk classifications segment this category by clinical validation requirements and biometric inference documentation obligations.
- Augmented Reality Glasses:Optical see-through displays overlay digital information onto physical environments using waveguide or projection optics, typically weighing under 80 grams. German automotive OEMs and French industrial equipment manufacturers are deploying these for hands-free assembly guidance, driving procurement through multi-year framework agreements that bundle hardware with fleet management software.
- Mixed Reality Headsets:Passthrough camera systems enable spatial anchoring with higher fidelity environmental mapping, commanding premium pricing through superior depth sensing and hand tracking precision. Japanese enterprise manufacturing divisions are consolidating vendor relationships around industrial SKU portfolios that specify interoperability with existing digital twin infrastructure.
- Smart Eyewear:Notification-centric devices with limited optical overlay capabilities serve consumer notification and basic navigation use cases.
- Interactive Glasses:Gesture and voice-controlled interfaces target education sector deployments with simplified interaction paradigms for classroom environments.
Augmented Reality Glasses handles the majority of throughput; Mixed Reality Headsets is expanding most quickly on share.
Technology:
East Asian electronics clusters concentrate manufacturing investment based on thickness-to-luminance tradeoffs and foundry access economics.
- Waveguide Technology:Surface-relief grating architectures deliver superior luminance efficiency at sub-2-millimeter thickness, displacing holographic optical elements in enterprise-grade devices. Shenzhen and Seoul waveguide foundries co-locate with micro-display fabs, compressing optical component lead times for high-mix production runs serving industrial sector demand.
- Projection Technology:Birdbath and curved mirror systems sustain growth in price-sensitive enterprise bulk deployments where field-of-view breadth outweighs aesthetic minimalism. Automotive inspection teams tolerate larger form factors in exchange for overlay coverage across wide engine bay workspaces.
- Optical See-Through:Direct optical path preservation maintains environmental awareness for safety-critical healthcare sector applications.
- Video See-Through:Camera-mediated reality reconstruction enables complete digital environment replacement for gaming industry immersive experiences.
Waveguide Technology dominates volume shipments; Projection Technology retains strongest position in cost-optimized procurement tenders.
End User:
EMA medical device coordination and OSHA-equivalent industrial safety frameworks create divergent compliance pathways across vertical applications.
- Industrial Sector:Manufacturing workflow digitization accelerates hands-free guidance deployment for assembly line quality assurance and maintenance protocols. German and Japanese factory automation investments are displacing pilot-project purchasing with standardized deployment templates.
- Healthcare Sector:Surgical navigation applications require EMA-FDA parallel trial coordination with divergent clinical evidence requirements that inflate regulatory submission costs. French and German notified bodies are developing specialized audit capacities for algorithmic decision transparency documentation.
- Gaming Industry:Consumer entertainment applications prioritize low-latency wireless protocols and immersive content libraries over enterprise-grade durability specifications.
- Education Sector:Institutional procurement cycles favor ruggedized designs with simplified fleet management for classroom-scale deployments.
Industrial Sector generates the highest absolute unit demand; Healthcare Sector commands the steepest pricing premium per device.
Distribution Channel:
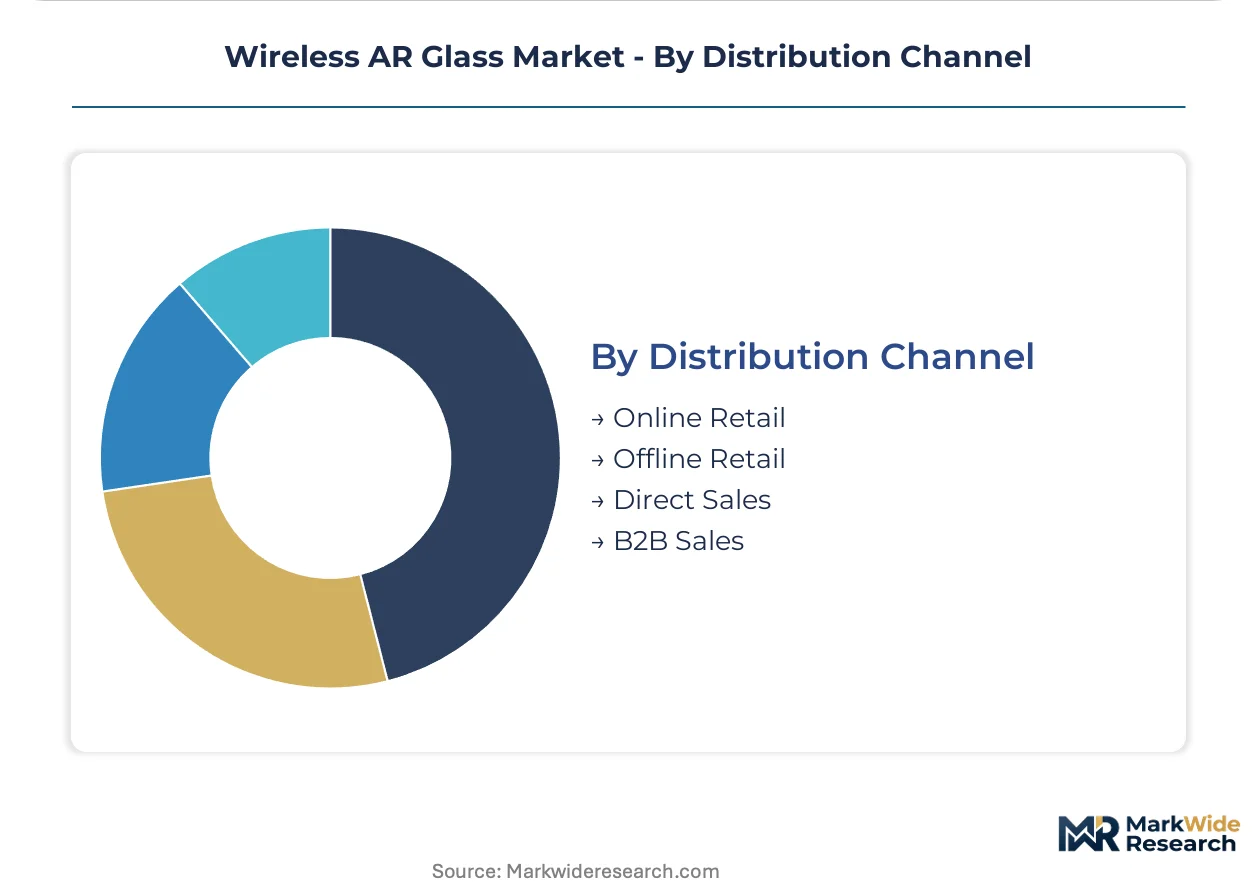
Enterprise procurement consolidation around multi-year framework agreements is restructuring channel economics away from transactional hardware sales.
- B2B Sales:Direct vendor relationships with Fortune 500 manufacturing divisions bundle hardware, software licensing, and tiered support into integrated service contracts. Japanese industrial buyers require documented API compatibility with incumbent manufacturing execution systems.
- Direct Sales:Manufacturer-owned channels capture margin from early-adopter healthcare institutions and specialized industrial integrators seeking custom configuration support.
- Online Retail:E-commerce platforms serve gaming industry consumers and education sector small-scale purchasers with standardized SKU fulfillment.
- Offline Retail:Physical storefronts provide demonstration and fitting services for smart eyewear consumer segments.
B2B Sales captures the dominant revenue share; Direct Sales is climbing the fastest as vendors bypass distributor margins.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. Japanese industrial buyers prioritize optical precision and integration reliability over unit cost, while Indian procurement teams under PLI scheme incentives optimize for localization thresholds and duty advantages.
United States
Fortune 500 manufacturing divisions drive enterprise demand through multi-year framework agreements bundling hardware with fleet management software. FDA digital health pathway expansion enables surgical navigation trials requiring clinical efficacy documentation for reimbursement. Seattle and San Francisco Bay Area clusters concentrate photonics engineering talent and enterprise software integration expertise.
Germany
Automotive OEMs and industrial equipment manufacturers deploy hands-free assembly guidance for engine bay overlay and quality assurance protocols. EU AI Act risk-classification obligations mandate conformity assessment procedures for biometric inference capabilities. Bavaria and Baden-Württemberg manufacturing belts anchor waveguide pilot deployments with documented API compatibility requirements.
Japan
Factory automation investments displace pilot-project purchasing with standardized deployment templates specifying digital twin interoperability. METI industrial policy supports precision optics manufacturing through targeted R&D consortia. Tokyo-Osaka corridor electronics clusters co-locate waveguide foundries with micro-display assembly operations.
South Korea
Electronics manufacturing conglomerates accelerate procurement of industrial-grade devices for semiconductor fabrication facility maintenance. MFDS medical device coordination shapes clinical trial pathways for surgical navigation applications. Seoul metropolitan area concentrates surface-relief grating waveguide production adjacent to micro-OLED backplane fabrication.
India
PLI scheme subsidies for component localization attract waveguide assembly investments serving Middle Eastern and African distribution channels. BIS standards compliance creates entry barriers for non-localized supply chains. Maharashtra and Karnataka electronics manufacturing zones concentrate final assembly operations for price-sensitive enterprise bulk deployments.
Wireless AR Glass Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive micro-display supply and photonics foundry relationships determining competitive boundaries. The upper tier commands enterprise channel control through bundled hardware-software-service portfolios, while modular assemblers compete on configuration flexibility. Three archetypes dominate: vertically integrated device makers with upstream component partnerships, optical technology specialists leveraging waveguide IP, and enterprise platform vendors with established Fortune 500 relationships. Strategic moves concentrate on foundry capacity commitments and multi-year framework agreement capture.
Within the integrated device maker tier, XREAL, Inc. and Magic Leap, Inc. represent contrasting supply chain philosophies. Microsoft anchors the enterprise platform archetype through industrial SKU portfolio breadth. These three occupy positions that exemplify the vertical integration versus specialization tradeoff reshaping vendor economics.
| Leading Market Players |
|---|
| XREAL, Inc. |
| Magic Leap, Inc. |
| Microsoft |
| Seiko Epson Corporation |
| Rokid |
| RealWear, Inc. |
| Vuzix |
| RayNeo |
| Meta |
| Others |
Pricing and Supply Chain Analysis
Eight-to-twelve week waveguide foundry lead times concentrate pricing power among three dominant photonics suppliers in Taiwan and South Korea, while enterprise buyers in Germany and Japan absorb premium positioning through multi-year framework agreements that bundle hardware with fleet management software and tiered support services.
Pricing Analysis
After-sales service revenue from extended maintenance contracts and fleet management software subscriptions drives lifetime value beyond initial hardware margins. Three-tier pricing structure across premium, standard, and economy levels segments by optical precision grade and FDA digital health certification tier. Cost compression in projection-based systems is intensifying because automotive inspection teams in Germany prioritize field-of-view breadth over aesthetic minimalism. Indian procurement teams under PLI scheme incentives exhibit highest price sensitivity, while Japanese factory automation buyers prioritize integration reliability.
Supply Chain Analysis
Taiwan and South Korea anchor micro-OLED backplane fabrication and surface-relief grating waveguide production, while Shenzhen and Seoul electronics clusters concentrate final assembly operations. Critical inputs draw from rare-earth phosphors for display illumination, precision glass substrates for waveguide lamination, and custom ASICs for low-latency wireless protocols. Single-source photonics foundry dependency creates vulnerability to capacity allocation shifts during semiconductor fabrication facility maintenance cycles. Distribution runs through direct B2B vendor relationships with Fortune 500 manufacturing divisions and specialized industrial integrators seeking custom configuration support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now governs vendor viability as enterprise procurement teams consolidate around industrial SKU portfolios that specify interoperability with existing digital twin infrastructure, rewarding suppliers with documented API compatibility and established channel control.
For Market Incumbents: Compound enterprise channel control through captive photonics foundry relationships that lock surface-relief grating waveguide capacity, while accelerating FDA digital health pathway investments to defend against modular assemblers seeking surgical navigation certification. Microsoft and Magic Leap, Inc. exemplify this consolidation logic through multi-year framework agreement capture. For New Entrants and Emerging Players: Anchor in Indian electronics manufacturing zones under PLI scheme subsidies for waveguide assembly localization, targeting price-sensitive Middle Eastern and African distribution channels underserved by premium-tier incumbents. Pursue automotive inspection deployments in German OEM engine bay overlay guidance as the most penetrable industrial segment. For Investors and Strategic Acquirers: Long-term, this sits as a component-captive platform play because waveguide foundry access and micro-display fab partnerships determine competitive boundaries more than device-level innovation. Target acquisition candidates with established photonics foundry relationships and EMA-FDA parallel trial coordination capabilities. Watch Wi-Fi 7 low-latency protocol adoption rates as the inflection signal for untethered spatial computing viability.| Strategic Initiative | Industry Significance |
|---|---|
| Photonics Foundry Capacity Commitment | Locks surface-relief grating waveguide supply for enterprise-grade device manufacturing. |
| FDA Digital Health Pathway Investment | Enables surgical navigation reimbursement through clinical efficacy documentation. |
| EU AI Act Conformity Assessment | Mandates algorithmic decision transparency for biometric inference capabilities. |
| Digital Twin Infrastructure Integration | Secures Fortune 500 framework agreements through documented API compatibility. |
| PLI Scheme Localization Buildout | Captures Indian manufacturing subsidies for Middle Eastern and African channel access. |
Research Methodology
Desk research of SEC filings from photonics and display technology suppliers, EMA medical device coordination guidelines, and IEC laser classification standards preceded structured interviews with waveguide design engineers, enterprise manufacturing procurement directors, and surgical navigation clinical trial coordinators. Secondary validation drew from FDA digital health guidance documents, EU AI Act risk classification frameworks, and customs data from Shenzhen and Seoul electronics clusters. Bottom-up demand modeling across industrial, healthcare, and gaming verticals triangulated with top-down market sizing from component supply chain interviews.
Variance decomposition across optical architecture segments, regulatory certification tiers, and geographic procurement clusters shaped the analytical framework over the projection horizon. Modeled dimensions span waveguide versus projection technology, FDA digital health pathway versus industrial safety compliance, and B2B framework agreement versus direct sales channel economics. CAGRs were derived from segment-level demand elasticity analysis and foundry capacity expansion schedules, with inputs from Wi-Fi 7 protocol adoption curves and CSRD supply-chain disclosure mandate implementation timelines.
Underlying assumptions cover sustained EU AI Act compliance cost absorption, FDA pathway expansion for immersive medical displays, and photonics systems engineering talent scarcity, with deviation risk concentrated in single-source waveguide supplier consolidation and IEC laser classification standard revisions. Recalibration cycles align with material shifts in EMA-FDA parallel trial coordination requirements and Wi-Fi 7 low-latency protocol enterprise adoption rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
Extended Reality Display Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Augmented and Virtual Reality (AR VR) Market
Virtual Reality (VR) and Augmented Reality (AR)
Consumer Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality Content Creation Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Immersive Technology Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality (VR) Simulator Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Mirror Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Tour Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Dressing Room Market
Virtual Reality (VR) and Augmented Reality (AR)
5G and Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Production Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality (VR) Market
Virtual Reality (VR) and Augmented Reality (AR)
AR in Education Market
Virtual Reality (VR) and Augmented Reality (AR)
US Virtual Tour Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality in Retail Market
Virtual Reality (VR) and Augmented Reality (AR)
China Metaverse Market