
 Calcium Lactate Market | 2026-2036
Calcium Lactate Market Size, Share, and Industry Trends Forecast 2026-2036
Calcium Lactate Market Outlook
The calcium lactate market is repositioning around a widening gap between pharmaceutical-grade purity specifications and commodity food-grade volumes. Jungbunzlauer Suisse AG leverages its Swiss fermentation expertise to dominate high-purity pharmaceutical supply chains. Roquette Frères sustains broad food industry coverage through integrated carbohydrate feedstock control. Henan Jindan Lactic Acid Technology Co., Ltd. anchors Asia-Pacific cost structures with captive lactic acid fermentation capacity.
Calcium lactate is a calcium salt of lactic acid produced through neutralization of lactic acid with calcium carbonate or hydroxide, typically yielding a white crystalline powder with solubility of approximately 9 grams per 100 milliliters at room temperature, functioning primarily as a calcium fortifier, acidity regulator, and preservative across food, pharmaceutical, and feed applications. The food industry segment leads absolute volume due to widespread bakery and dairy preservation demand, while the dietary supplements segment captures expanding margin pools as consumers self-direct calcium intake. Powder form dominates industrial procurement for bulk fortification, though tablet and capsule formats concentrate value in pharmaceutical and direct-to-consumer channels.
US FDA food additive regulations and USP monograph standards shape pharmaceutical-grade calcium lactate purity requirements and market access conditions. EFSA evaluations under EU food additive frameworks determine acceptable daily intake levels and influence reformulation decisions across European food manufacturers. China's SAMR fortification standards and GB quality specifications govern domestic production and import compliance. Stakeholders must monitor evolving pharmaceutical excipient qualification requirements and regional clean-label regulatory trajectories to align capacity investments with shifting premium-commodity tier dynamics.
Market Dynamics
Pharmaceutical-grade purity mandates are bifurcating calcium lactate supply chains into premium-certified and commodity-grade tiers, forcing manufacturers to duplicate production lines or forfeit high-margin medical applications.
Growth Catalysts
- CDSCO tablet-grade mandates:Indian pharmaceutical formulators must source calcium lactate meeting revised excipient monographs, redirecting procurement toward qualified fermentation suppliers.
- EFSA clean-label redirection:European food additive evaluations are accelerating displacement of synthetic preservatives in bakery and dairy matrices.
- SAMR fortification channels:China's dietary supplement distribution expansion under national nutrition improvement programs is amplifying volume uptake through domestic e-commerce platforms.
Market Restraints
- Lactic acid feedstock volatility:Corn and sugar beet price swings directly compress fermentation economics for calcium lactate producers without captive carbohydrate supply.
- Swiss-Chinese supply concentration:High-purity pharmaceutical output clusters among fermentation specialists in Basel and Zhengzhou, creating single-source vulnerability for tablet manufacturers.
- Calcium carbonate quality variance:Food-grade limestone sourcing inconsistencies force redundant purification steps that erode batch economics.
Strategic Opportunities
- Brazilian pharmaceutical excipient qualification:ANVISA's expanding GMP certification framework for imported excipients creates first-mover positioning for fermentation-grade suppliers.
- Direct-to-consumer gummy formats:Chewable calcium delivery systems are capturing self-directed supplement buyers previously served by tablet channels.
- EU Green Deal bio-based mandates:Fermentation-derived calcium lactate qualifies for preferred procurement status under emerging sustainable chemistry taxonomies.
Industry Challenges
- Pharmaceutical excipient qualification timelines:USP-NF monograph compliance and DMF filing cycles extend 18-24 months, freezing capacity allocation decisions.
- Cross-contamination protocols:Dual food-pharma production facilities require segregated HVAC and cleaning validation systems that inflate capital intensity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Calcium Lactate Market |
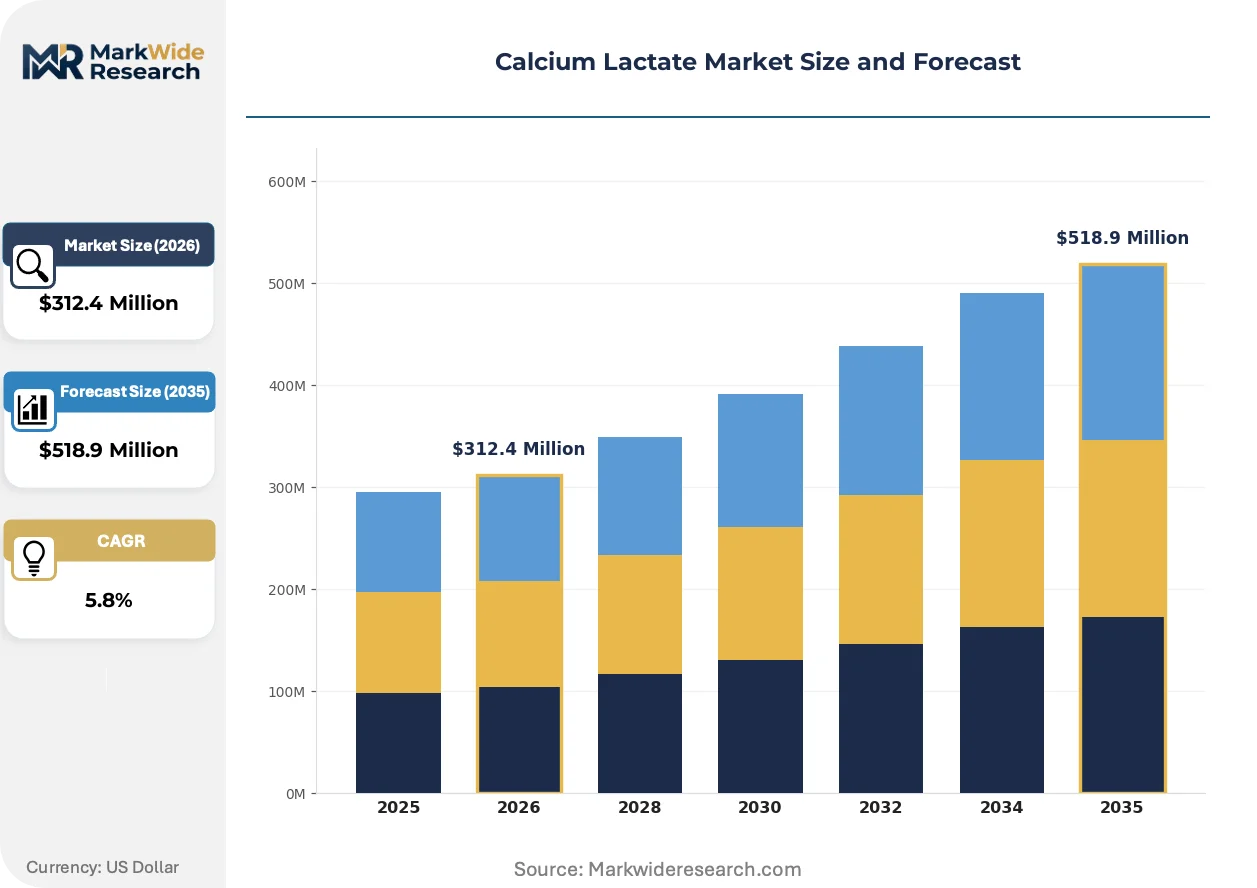
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $518.9 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | End User: Food Industry, Pharmaceutical Sector, Dietary Supplements, Animal Feed Application: Food Preservative, Calcium Supplement, Fortification, Flavor Enhancer Form: Powder, Granules, Tablets, Capsules Distribution Channel: Online Retail, Direct Sales, Wholesalers, Specialty Stores |
| Companies Covered | Jungbunzlauer Suisse AG, Roquette Frères, Cargill, Incorporated, GALACTIC, Merck KGaA, Corbion NV, Archer-Daniels-Midland Company, Henan Jindan Lactic Acid Technology Co., Ltd., Jost Chemical Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Calcium Lactate Market Strategic Shifts
Fermentation process intensification and regulatory chemistry are compressing traditional batch manufacturing timelines while redirecting demand toward certified supply chains. Clean-label preservation and pharmaceutical excipient qualification are converging on calcium lactate as a dual-use platform chemical.
Continuous fermentation with cell retention is absorbing calcium lactate production from fed-batch reactors, yielding higher volumetric productivity and tighter purity distributions. European pharmaceutical manufacturers are adopting these systems to meet USP residual solvent specifications. The technology is absorbing mid-scale batch capacity and concentrating supply among integrated fermentation-chemical processors.
REACH Annex XVII restrictions on synthetic acidity regulators are compelling European food manufacturers to reformulate toward fermentation-derived alternatives. EFSA's 2023 re-evaluation of calcium lactate acceptable daily intake confirmed expanded use levels in infant nutrition. Dairy preservative applications in Germany and France are responding fastest, with bakery matrix adoption trailing by approximately one reformulation cycle.
Buyer consolidation among contract dietary supplement manufacturers is compressing supplier qualification cycles and unbundling technical service from material pricing. Large North American nutraceutical brands are consolidating calcium lactate procurement through three-year framework agreements with fermentation specialists. This pattern is most pronounced in Utah and California, where supplement manufacturing clusters have achieved sufficient scale to dictate certificate-of-analysis specifications.
Calcium Lactate Market Segmentation
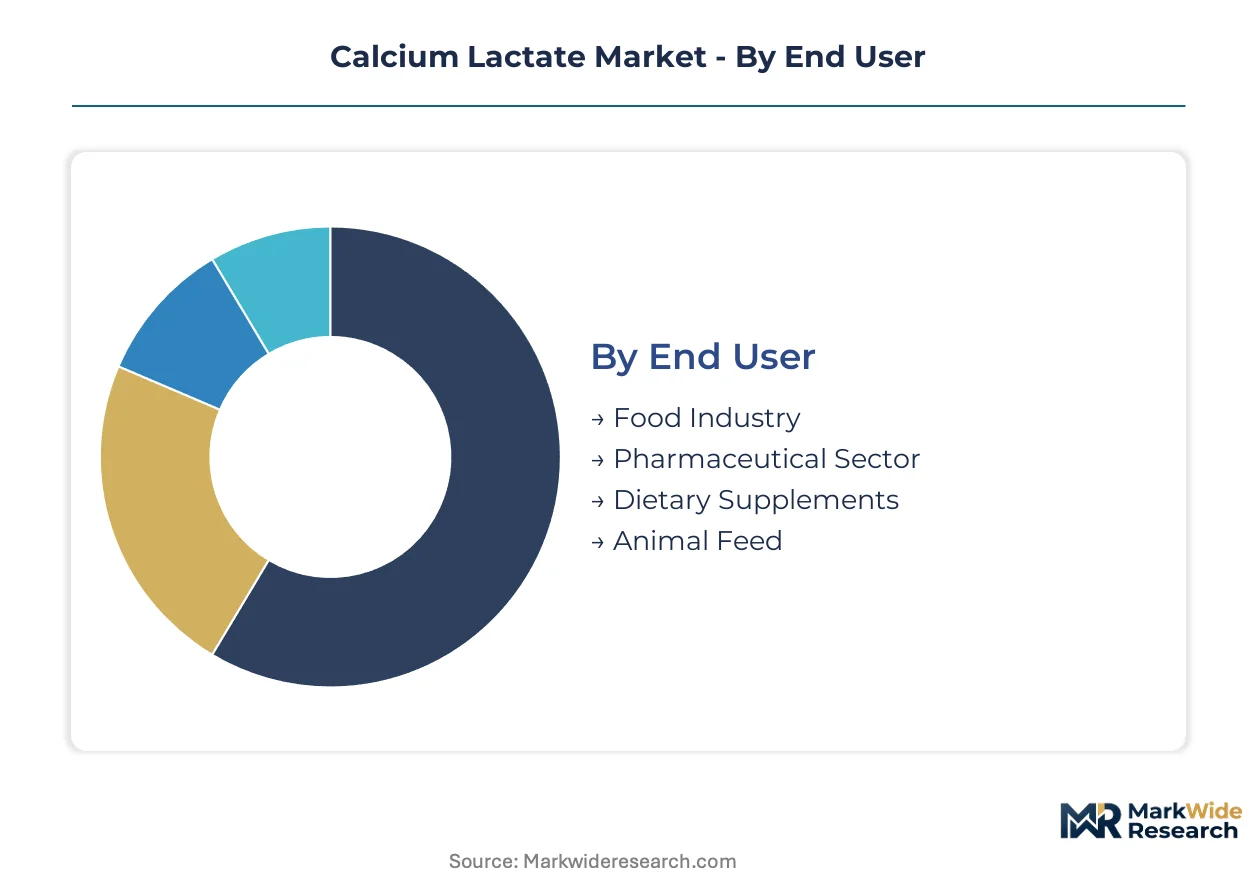
Calcium lactate segmentation reveals how purity grades, delivery formats, and channel structures fragment procurement economics. Pharmaceutical-grade specifications command premium multiples over commodity food-grade volumes, while direct-to-consumer formats reshape margin capture across supply tiers.
End User:
Volume concentrates in mass-market food preservation, while premium pools concentrate in pharmaceutical and nutraceutical channels where certification requirements filter supplier bases.
- Food Industry:Bakery and dairy preservation absorb the largest absolute tonnage, with EFSA clean-label mandates accelerating displacement of synthetic acidity regulators across German and French manufacturing clusters.
- Pharmaceutical Sector:Tablet and capsule excipient specifications under USP-NF monographs require dedicated fermentation lines with validated residual solvent controls, concentrating supply among Swiss and Chinese qualified manufacturers.
- Dietary Supplements:Direct-to-consumer calcium fortification is expanding most quickly through Utah and California contract manufacturing clusters, with gummy formats capturing self-directed buyers.
- Animal Feed:Livestock calcium supplementation operates at commodity margins with minimal regulatory differentiation, sourcing primarily from integrated fermentation-chemical processors with captive lactic acid supply.
Today's leader: Food Industry. Tomorrow's challenger: Pharmaceutical Sector.
Application:
Functional differentiation separates preservation demand from nutritional positioning, with fortification applications commanding formulation technical service premiums.
- Food Preservative:Acidity regulation and shelf-life extension in bakery matrices drives baseline volume, with REACH Annex XVII restrictions on synthetic alternatives redirecting European procurement toward fermentation-derived grades.
- Calcium Supplement:Direct consumption formats—tablets, capsules, and emerging gummies—concentrate value through USP-grade purity requirements and DMF-backed supplier qualification.
- Fortification:Beverage and infant nutrition integration requires solubility-optimized particle engineering, with China's SAMR standards governing acceptable daily intake thresholds for domestic distribution.
- Flavor Enhancer:Processed cheese and dairy applications leverage calcium lactate's mild taste profile, though this segment trails preservation and supplementation in absolute revenue contribution.
Preservation anchors current procurement volume. Fortification climbs the fastest as beverage and infant nutrition channels expand.
Form:
Industrial procurement favors bulk powder for cost efficiency, while consumer-facing formats extract value through unit-dose convenience and compliance positioning.
- Powder:Bulk fortification and industrial food processing absorb the largest tonnage, with spray-dried crystalline grades dominating bakery and dairy manufacturing input streams.
- Tablets:Direct-to-consumer calcium delivery concentrates margin in pharmaceutical and nutraceutical channels, with CDSCO tablet-grade mandates in India filtering supplier qualification requirements.
- Capsules:Hard-shell gelatin and vegetarian alternatives serve swallowing-convenience segments, though unit economics trail tablets at equivalent purity grades.
- Granules:Intermediate processing formats bridge bulk powder and finished dose manufacturing, with limited direct commercial presence outside integrated supply chains.
Powder commands absolute volume. Tablets gain share fastest as self-directed supplementation shifts from bulk to unit-dose formats.
Distribution Channel:
Channel structure bifurcates between industrial procurement through direct sales and fragmented retail access for finished consumer products.
- Direct Sales:Pharmaceutical and large food manufacturers negotiate multi-year framework agreements with fermentation specialists, unbundling certificate-of-analysis specifications from base material pricing.
- Wholesalers:Regional chemical distributors serve mid-scale food processors and compound feed operations with standardized food-grade inventory positions.
- Online Retail:Amazon and domestic e-commerce platforms in China are amplifying dietary supplement volume uptake through direct-to-consumer fulfillment, compressing traditional pharmacy channel margins.
- Specialty Stores:Health food and professional pharmacy outlets serve premium supplement positioning, though collective volume trails mass-market online and direct channels.
Direct Sales anchors industrial procurement. Online Retail expands most quickly as supplement brands bypass wholesale intermediaries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China absorbs more calcium lactate volume than any other single country, while Switzerland concentrates the highest-purity pharmaceutical output. Regulatory divergence between these poles is fragmenting procurement strategies across three continents.
China
SAMR fortification standards and expanding dietary supplement e-commerce channels are amplifying domestic volume uptake. GB quality specifications govern both production compliance and import screening at major ports. Zhengzhou's fermentation corridor anchors cost-competitive supply for tablet and capsule manufacturers serving the national nutrition improvement program.
Switzerland
Swissmedic pharmaceutical excipient mandates and USP-NF monograph alignment position Basel-area fermentation specialists at the premium tier. EU Green Deal bio-based chemistry taxonomies confer preferred procurement status on fermentation-derived grades. The country's pharmaceutical corridor supplies qualified material to German and French tablet manufacturers under validated DMF protocols.
India
CDSCO tablet-grade excipient revisions are redirecting pharmaceutical procurement toward qualified fermentation suppliers with validated residual solvent controls. FSSAI food additive frameworks run parallel to pharmaceutical mandates, creating dual-track compliance requirements. Hyderabad and Mumbai pharmaceutical clusters are expanding calcium lactate qualification programs for export-oriented generic tablet production.
Germany
REACH Annex XVII restrictions on synthetic acidity regulators are accelerating bakery and dairy reformulation toward fermentation-derived calcium lactate. EFSA's 2023 acceptable daily intake re-evaluation confirmed expanded use levels in infant nutrition. The Rhine-Ruhr industrial corridor hosts reformulation activity across dairy preservative applications, with Bavarian supplement manufacturers driving gummy format adoption.
United States
FDA food additive regulations and USP monograph standards bifurcate demand between commodity food-grade and certified pharmaceutical-grade procurement. Utah and California dietary supplement manufacturing clusters are consolidating procurement through multi-year framework agreements with fermentation specialists. Direct-to-consumer gummy formats are capturing self-directed calcium buyers previously served by tablet channels.
Calcium Lactate Market Competitive Environment
Top-tier vendors anchor pharmaceutical-grade certification, while commodity-grade food processors compete on fermentation scale and feedstock integration. Market structure splits between Swiss and Chinese purity specialists, European carbohydrate-integrated processors, and North American distribution-heavy conglomerates. Three archetypes dominate: fermentation-purity specialists, agribusiness-integrated suppliers, and pharmaceutical-excipient qualifiers. Competitive moves concentrate on backward integration into lactic acid supply and DMF-backed qualification timelines.
Among fermentation-purity specialists, Jungbunzlauer Suisse AG exemplifies the Swiss pharmaceutical-grade archetype, while Henan Jindan Lactic Acid Technology Co., Ltd. occupies a parallel position in Chinese cost structures. Roquette Frères represents the European agribusiness-integrated model with carbohydrate feedstock control. These three anchors illustrate how geography and feedstock strategy stratify competitive positioning across certification tiers.
| Leading Market Players |
|---|
| Jungbunzlauer Suisse AG |
| Roquette Frères |
| Cargill, Incorporated |
| GALACTIC |
| Merck KGaA |
| Corbion NV |
| Archer-Daniels-Midland Company |
| Henan Jindan Lactic Acid Technology Co., Ltd. |
| Jost Chemical Co. |
| Others |
Value Chain & Pricing Dynamics
Corn futures volatility cascades through calcium lactate value chains, compressing fermentation margins for non-integrated processors while amplifying pricing power for Zhengzhou and Basel-area manufacturers with captive carbohydrate supply. Pharmaceutical-grade certification premiums widen against commodity food-grade benchmarks as CDSCO and USP-NF qualification costs concentrate supply among qualified fermentation specialists.
Pricing Analysis
Capacity additions in Henan Province are reshaping price floors for standard-grade material, forcing European processors toward premium pharmaceutical positioning. Three-tier pricing structure across pharmaceutical-certified, food-grade, and feed-grade levels stratifies procurement economics, with USP-NF monograph compliance and DMF-backed qualification commanding substantial premiums over FSSAI-aligned food additive tiers. Cost compression in commodity food-grade segments is intensifying because Indian and Brazilian pharmaceutical formulators are redirecting volume toward qualified suppliers. Contract dietary supplement manufacturers in Utah and California exhibit lowest price sensitivity, while mid-scale bakery processors in Germany and France face acute margin pressure from synthetic preservative displacement mandates.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Shanghai coordinate hub-and-spoke patterns for pharmaceutical-grade inventory, with Basel and Zhengzhou fermentation corridors anchoring primary production nodes. Supply concentrates in Switzerland, China, and India for high-purity pharmaceutical output, while commodity food-grade volumes source more broadly from European carbohydrate-integrated processors. Lactic acid feedstock, calcium carbonate quality, and fermentation yield consistency constitute critical input dependencies. Single-source vulnerability runs through Swiss-Chinese pharmaceutical-grade corridors, where USP-NF qualification timelines create 18-24 month switching costs. Distribution runs through direct sales frameworks for pharmaceutical and large food manufacturers, with regional chemical distributors serving mid-scale processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Calcium lactate procurement economics favor margin expansion through fermentation scale efficiency and pharmaceutical-grade certification premiums. Continuous processing technology and backward integration into lactic acid supply are compressing unit costs for qualified manufacturers.
For Market Incumbents: Cement pharmaceutical excipient qualification advantages by accelerating DMF filings under USP-NF monographs before CDSCO mandate deadlines tighten supplier pools. Deepen captive lactic acid fermentation capacity to insulate margin structures from corn price volatility. Defensive positioning against emerging Chinese pharmaceutical-grade competitors requires validated residual solvent controls and segregated food-pharma production protocols. For New Entrants and Emerging Players: Begin with Brazilian pharmaceutical excipient qualification under ANVISA's expanding GMP framework, where first-mover positioning remains available for fermentation-grade suppliers. Direct-to-consumer gummy format manufacturing in North American contract supplement clusters offers the most penetrable entry vector. Go-to-market execution should leverage three-year framework agreement structures that unbundle technical service from material pricing. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale fermentation specialists possessing pharmaceutical-grade certification infrastructure but suboptimal capacity utilization. Five-to-ten year viability favors processors with demonstrated USP-NF compliance and backward integration into carbohydrate feedstock. Monitor CDSCO tablet-grade mandate enforcement timelines as inflection indicators for supplier consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lactic Acid Supply | Corn price volatility protection secures margin stability for fermentation-dependent processors. |
| Pharmaceutical Excipient DMF Filing | USP-NF qualification opens CDSCO-mandated procurement channels for Indian tablet manufacturers. |
| Continuous Fermentation Technology Deployment | Cell retention systems meet residual solvent specifications for European pharmaceutical buyers. |
| Direct-to-Consumer Gummy Format Expansion | Chewable delivery captures self-directed supplement buyers from traditional tablet channels. |
| EU Green Deal Bio-Based Certification | Fermentation-derived status qualifies for preferred procurement under sustainable chemistry taxonomies. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with fermentation plant managers, pharmaceutical procurement leads, dietary supplement contract manufacturers, and EFSA regulatory affairs specialists with secondary validation from FDA food additive filings, USP-NF monograph databases, CDSCO excipient guidelines, and customs trade flow records. Bottom-up capacity assessments and top-down demand segmentation were triangulated against SAMR fortification program disclosures and EFSA additive re-evaluation documentation.
Historical reference periods anchored volume and value projections across the modeling period, with analytical frameworks segmenting by purity grade tier, end-use industry application, delivery format, and regional regulatory cluster. CAGRs were derived from fitted growth curves calibrated to disclosed capacity expansions and procurement framework agreement patterns. Forecast inputs incorporated lactic acid feedstock price trajectories, pharmaceutical excipient qualification timelines, and clean-label regulatory displacement rates across European food manufacturing.
Several conditions sit outside the modeled scope, including unannounced regulatory revisions to infant nutrition additive thresholds, breakthrough synthetic preservative technologies, and geopolitical disruptions to Swiss-Chinese pharmaceutical-grade trade corridors. Forecasts reflect documented assumptions around CDSCO enforcement timing and EFSA clean-label mandate adoption curves. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Global Sodium Chlorate Market
Bulk Chemicals
Putty Powder Market
Bulk Chemicals
Global Hexane Market
Bulk Chemicals
Europe Acetic Acid Market
Bulk Chemicals
Adipic Acid Market
Bulk Chemicals
Global Lithium Carbonate Market
Bulk Chemicals
Global Chlorinated Paraffin Wax Market
Bulk Chemicals
India Chlorine Market
Bulk Chemicals
North America Calcium Chloride Market
Bulk Chemicals
Hydrogen Bromide Market
Bulk Chemicals
Global Vinyl Chloride Monomer Market
Bulk Chemicals
4-Diisopropylbenzene Market
Bulk Chemicals
Acetochlor Market
Bulk Chemicals
Chloroacetophenone Market
Bulk Chemicals
North America Methyl Acrylate Market
Bulk Chemicals
North America Starch Derivatives Market