
 Global Pitch Coke Market | 2026-2036
Global Pitch Coke Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pitch Coke Market Foresight
High-carbon low-ash specification tiers is redrawing procurement priorities across the pitch coke supply base. Mitsubishi Chemical leverages captive refinery integration to sustain premium needle coke output for graphite electrode buyers. Baosteel Chemical anchors Chinese domestic supply through backward integration into coking operations. Rain Carbon Inc. competes across both coal tar and petroleum pitch streams with specialized calcination technology.
Pitch coke denotes the solid carbonaceous residue derived from thermal processing of coal tar pitch or petroleum pitch, typically exhibiting fixed carbon content above 95 percent and serving as a critical binder and filler in carbon anodes for primary aluminum smelting. Manufacturing employs delayed coking or rotary kiln calcination at temperatures exceeding 1,200 degrees Celsius to drive out volatiles and establish crystalline structure. Aluminum anode applications dominate volume absorption given the electrolytic reduction process demands consistent reactivity and low trace metal contamination. Graphite electrodes represent the fastest-expanding application segment as electric arc furnace steelmaking intensifies in India and the Middle East. Needle coke commands the steepest quality premium within product type splits due to its essential role in ultra-high-power electrode fabrication for ladle metallurgy.
EPA emissions standards in the United States restrict volatile organic compound releases from coking operations, compelling facility upgrades and alternative thermal treatment investments. REACH registration requirements in Europe mandate comprehensive substance characterization for coal tar pitch derivatives, elevating compliance costs for importers and domestic blenders alike. China's MEE enforces increasingly stringent air quality thresholds around coking clusters in Shanxi and Shandong provinces, accelerating capacity consolidation among smaller producers. Stakeholders must monitor regulatory divergence between jurisdictions while calibrating product certification strategies for cross-border aluminum and steel supply chains.
Market Dynamics
China's dual carbon goals and tightening emissions standards are forcing refiners to upgrade coking processes, redrawing competitive positioning across the pitch coke supply base while aluminum smelters expand procurement of high-sulfur grades for anode production.
Growth Catalysts
- Aluminum smelter expansion:Gulf aluminum capacity growth in the United Arab Emirates is concentrating demand for high-carbon low-ash pitch coke in anode applications.
- Electric arc furnace steelmaking:Intensifying EAF adoption in India and the Middle East is pulling needle coke volumes for ultra-high-power graphite electrodes.
- REACH registration:European substance characterization mandates for coal tar pitch derivatives are consolidating compliant supplier bases and favoring established blenders.
Market Restraints
- Feedstock volatility:Coal tar pitch supply fluctuations from steelmaking output variations create input cost instability for coking operations.
- Shanxi-Shandong concentration:China's coking cluster dependency exposes buyers to localized MEE air quality enforcement disruptions.
- Calcined petroleum coke substitution:Lower-sulfur CPC alternatives compete for standard-grade anode applications in cost-sensitive procurement.
Strategic Opportunities
- India aluminum capacity:Greenfield smelter projects in Odisha and Gujarat offer underpenetrated demand pockets for long-term offtake agreements.
- Delayed coking technology:Advanced thermal processing convergence with digital process control enables higher-yield needle coke production.
- EU Green Deal carbon border adjustments:Embedded carbon accounting for aluminum imports creates premium positioning for low-emission pitch coke certification.
Industry Challenges
- Calcination expertise shortage:Specialized rotary kiln operation and temperature control skills are scarce across emerging producer markets.
- EPA VOC compliance capex:United States coking facility upgrades for volatile organic compound containment demand significant capital deployment.
- Multi-jurisdiction certification lag:Divergent REACH, MEE, and EPA substance timelines delay cross-border product qualification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pitch Coke Market |
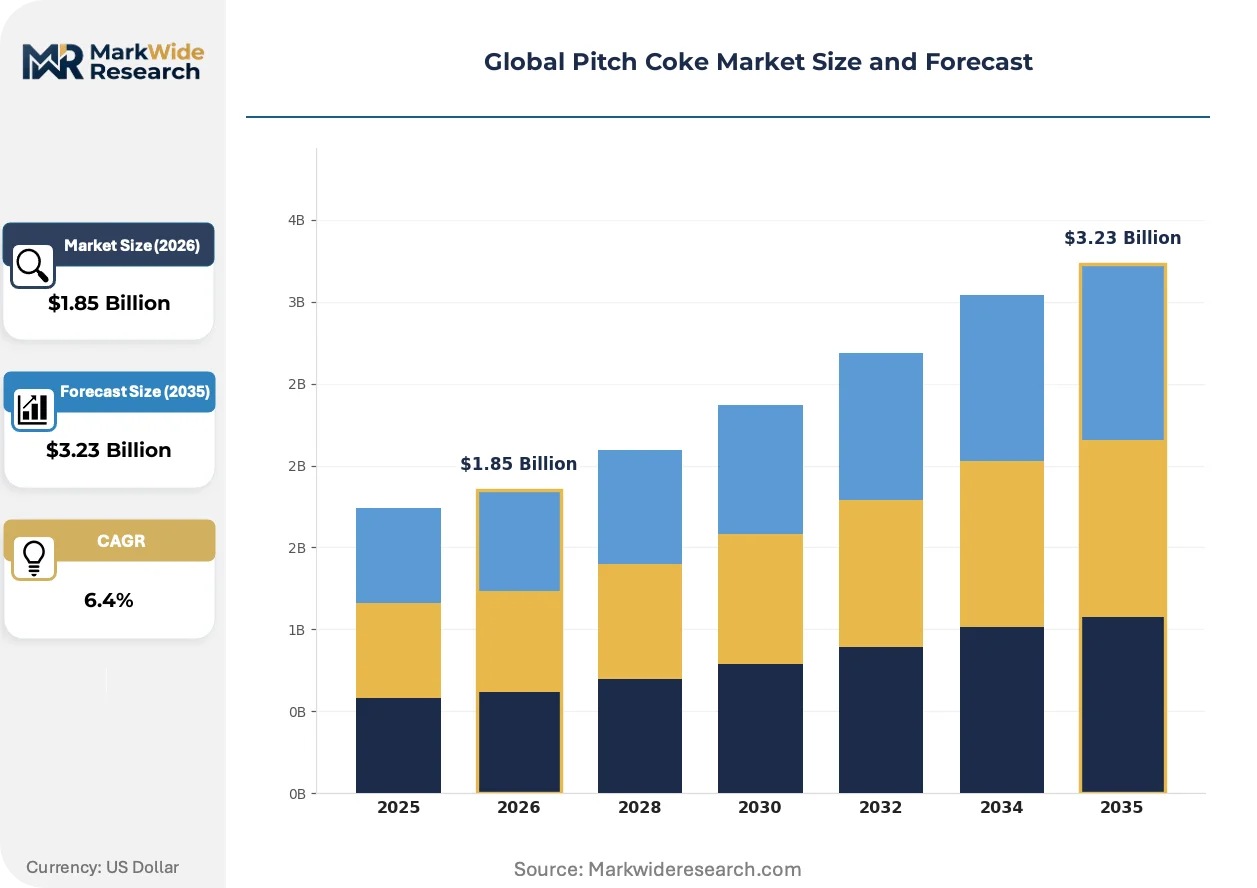
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coal Tar Pitch, Petroleum Pitch, Impregnation Coal Tar, Needle Coke Application: Aluminum Anode, Graphite Electrodes, Carbon Products Fabrication, Refractory Industry End User Industry: Metal Extraction Plants, Carbon Manufacturing Units, Chemical Processing Plants, Foundries Packaging Type: 25 kg Bags, 50 kg Bags, Bulk Loose, Jumbo Bags |
| Companies Covered | Sojitz JECT Corporation, Shamokin Carbons, Rain Carbon Inc., Tianjin Yunhai Carbon Element Products Co., Ltd., Bilbaina de Alquitranes, S.A, SUMMIT CRM Limited, Mitsubishi Chemical, Baosteel Chemical, ASBURY CARBONS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pitch Coke Market Shifts & Advancements
Digital process control and emissions capture technologies are actively reshaping pitch coke manufacturing economics, while procurement patterns favor suppliers with integrated refinery-calciner operations and verified low-carbon production pathways.
Needle coke production from petroleum pitch feedstocks is decomposing traditional coal tar dominance in ultra-high-power electrode applications. Japanese and South Korean graphite electrode manufacturers are accelerating adoption of synthetic pitch-derived needle coke for ladle metallurgy. This technology is decomposing historical supply relationships and compressing quality premiums for legacy coal tar grades.
REACH registration requirements for coal tar pitch derivatives are elevating compliance costs and consolidating European importer bases. ECHA substance characterization mandates now cover polycyclic aromatic hydrocarbon profiles and thermal processing byproducts. Specialty carbon producers are responding by shifting procurement toward pre-registered petroleum pitch streams with clearer regulatory pathways.
Long-term offtake contracting is displacing spot market purchasing among major aluminum smelters seeking supply security. Smelters in India and the Middle East are locking in multi-year volumes directly with calciners possessing captive refinery integration. This pattern is most visible in the United Arab Emirates and Saudi Arabia, where Gulf aluminum capacity expansion outpaces regional pitch coke supply development.
Global Pitch Coke Market Segmentation
Pitch coke market segmentation reveals distinct procurement patterns across feedstock origins and end-use specifications. Aluminum smelters and graphite electrode manufacturers drive divergent demand profiles that reshape supplier priorities across each category.
Product Type:
Domestic supply chains dominate coal tar pitch derivatives in China and India, while petroleum pitch grades concentrate in export-oriented production from integrated refiners in Japan and South Korea.
- Coal Tar Pitch:Derived from high-temperature coking of metallurgical coal, this feedstock yields pitch coke with fixed carbon content exceeding 99 percent and low sulfur profiles preferred by European aluminum smelters. Demand concentrates in Shanxi province coking clusters serving domestic Chinese anode producers, though REACH registration requirements are redirecting European procurement toward pre-registered supply streams.
- Petroleum Pitch:Refinery fluid catalytic cracking residues supply this synthetic alternative with controlled aromaticity and reduced polycyclic hydrocarbon content. Needle coke production for ultra-high-power electrodes in India and the Middle East pulls volumes from Japanese and South Korean manufacturers with delayed coking technology mastery.
- Impregnation Coal Tar:Specialized binder formulations for carbon product densification.
- Needle Coke:Premium-grade material commanding quality premiums for ladle metallurgy applications.
Coal Tar Pitch commands the established base. The steepest expansion runs through Petroleum Pitch.
Application:
Volume absorption splits between bulk anode consumption and specialized electrode fabrication, with margin concentration inversely distributed.
- Aluminum Anode:Electrolytic reduction cells in primary smelting consume the largest tonnage, requiring consistent reactivity and low trace metal contamination. Greenfield projects in Odisha and Gujarat, India, and expansions in the United Arab Emirates and Saudi Arabia are locking in long-term offtake agreements directly with calciners possessing captive refinery integration.
- Graphite Electrodes:Electric arc furnace steelmaking intensification drives this segment, with ultra-high-power grades for ladle metallurgy requiring needle coke with specific crystalline structure. Indian and Middle Eastern EAF adoption is accelerating demand for synthetic pitch-derived alternatives that decompose historical coal tar supply relationships.
- Carbon Products Fabrication:Structural components and specialty shapes for industrial applications.
- Refractory Industry:High-temperature lining materials for steel and glass furnaces.
Aluminum Anode anchors volume absorption. Graphite Electrodes gains share fastest on steel decarbonization trends.
End User Industry:
Customer concentration varies from integrated multinationals with captive supply to fragmented foundry operations dependent on distributor networks.
- Metal Extraction Plants:Primary aluminum smelters and copper refineries operating electrolytic processes. Gulf aluminum capacity expansion in the United Arab Emirates and Saudi Arabia outpaces regional pitch coke supply development, forcing direct procurement relationships with Asian calciners.
- Carbon Manufacturing Units:Electrode fabricators and specialty carbon producers with blending and forming capabilities. ECHA substance characterization mandates are consolidating European importer bases toward established blenders with REACH-compliant coal tar pitch derivative registrations.
- Chemical Processing Plants:Carbon black and activated carbon production facilities.
- Foundries:Small-scale metal casting operations with dispersed procurement patterns.
Metal Extraction Plants concentrate demand volume. Carbon Manufacturing Units show the most rapid procurement sophistication gains.
Packaging Type:
Logistics economics and handling infrastructure determine format adoption across ocean freight versus regional distribution.
- 25 kg Bags:Manual handling applications in smaller foundries and remote smelter sites.
- 50 kg Bags:Standard unitization for regional distributor networks and mid-scale carbon manufacturers.
- Bulk Loose:Dedicated vessel shipments for integrated aluminum smelters with pneumatic unloading systems. Long-term offtake contracts from Indian and Middle Eastern smelters increasingly specify bulk delivery to minimize handling costs and contamination risk.
- Jumbo Bags:Intermediate bulk containers for flexible deployment across multiple production lines.
Bulk Loose dominates intercontinental trade. Jumbo Bags expands most quickly for operational flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Coking capacity clusters in Shanxi and Shandong provinces, with calcination expertise concentrating in Japan and South Korea. Procurement patterns diverge sharply between aluminum smelter demand in the Gulf and electrode fabrication requirements in India.
China
Shanxi province hosts the densest coking cluster, supplying domestic anode producers with high-carbon low-ash grades. MEE air quality thresholds are forcing smaller refiners to consolidate or upgrade thermal processing systems. Shandong province calciners are investing in emissions capture technology to maintain operating permits under tightening provincial standards.
India
Greenfield aluminum smelters in Odisha and Gujarat are locking in multi-year offtake agreements with Asian calciners. BIS quality certifications for anode-grade pitch coke are becoming mandatory for import clearance. The Dahej and Mundra industrial corridors are attracting dedicated bulk handling infrastructure for carbon material imports.
United States
Domestic electrode fabricators source needle coke through long-term contracts with Japanese and South Korean suppliers. EPA VOC containment rules are driving capital deployment at remaining coking facilities. The Gulf Coast petrochemical corridor maintains limited calcination capacity focused on specialty carbon grades.
Japan
Delayed coking technology mastery sustains premium needle coke output for ultra-high-power electrode applications. METI industrial policy supports carbon material R&D through designated technology clusters. Osaka-based manufacturers are expanding synthetic pitch-derived needle coke production to serve Indian and Middle Eastern EAF steelmakers.
United Arab Emirates
Gulf aluminum capacity expansion in Abu Dhabi and Dubai outpaces regional pitch coke supply development. MOHAP environmental permitting for new calcination facilities is tightening in response to air quality commitments. Smelters are establishing direct procurement relationships with Chinese and Indian calciners possessing captive refinery integration.
Global Pitch Coke Market Competitive Landscape
Concentration sits with integrated refinery-calciner operators and established coal tar processors. The supply base stratifies across three tiers: multinational chemical conglomerates with captive coking assets, regional specialists with calcination technology mastery, and commodity traders with blending capabilities. Competitive dynamics center on backward integration into coking operations and long-term offtake contracting with aluminum smelters.
Within the integrated chemical conglomerate tier, Mitsubishi Chemical and Baosteel Chemical exemplify refinery-calciner convergence strategies. Rain Carbon Inc. occupies a position spanning both coal tar and petroleum pitch streams. These three anchors demonstrate how captive feedstock access and specialized thermal processing capabilities define sustainable positioning in quality-tiered procurement environments.
| Leading Market Players |
|---|
| Sojitz JECT Corporation |
| Shamokin Carbons |
| Rain Carbon Inc. |
| Tianjin Yunhai Carbon Element Products Co., Ltd. |
| Bilbaina de Alquitranes, S.A |
| SUMMIT CRM Limited |
| Mitsubishi Chemical |
| Baosteel Chemical |
| ASBURY CARBONS |
| Others |
Supply & Pricing Matrix
Calcined petroleum coke substitution into standard-grade anode applications is simultaneously redrawing procurement geography toward Gulf aluminum smelters and compressing margin structures for coal tar pitch refiners in Shanxi province. This input displacement forces coking operators to defend needle coke premiums through MEE-compliant emissions upgrades while spot volatility in metallurgical coal output destabilizes contract pricing power.
Pricing Analysis
REACH registration dictates the pricing tier structure across European coal tar pitch derivative imports, separating pre-registered supply streams from compliance-lagged alternatives. Three-tier pricing structure across premium needle coke, standard anode-grade, and economy CPC-substitute levels reflects quality grade and certification tier differentiation. Cost compression in standard anode-grade is intensifying because Indian greenfield smelters are consolidating procurement through multi-year offtake agreements. Spot market buyers in fragmented foundry operations exhibit highest price sensitivity; integrated aluminum smelters with pneumatic unloading systems show least.
Supply Chain Analysis
Container availability constraints on Asia-Middle East trade lanes are elevating inbound logistics costs for UAE and Saudi Arabian smelters sourcing from Chinese calciners. Geographic supply concentration centers on China, Japan, and South Korea. Raw material dependencies draw from metallurgical coal coking output, refinery fluid catalytic cracking residues, and petroleum pitch streams. Single-source vulnerability sits with Shanxi province coking cluster dependency for coal tar pitch derivatives. Distribution runs through dedicated bulk vessel charters for integrated smelters and regional distributor networks for carbon manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where long-term offtake contracting interoperability between aluminum smelters and calciners is displacing spot procurement liquidity and consolidating relationship-based supply access.
For Market Incumbents: Consolidate backward integration into coking operations to secure captive feedstock access against petroleum pitch substitution threats. Prioritize MEE emissions compliance investment in Shanxi and Shandong facilities to defend operating permits. Lock multi-year volume commitments with UAE and Indian greenfield smelters before delayed coking technology mastery diffuses to emerging competitors. For New Entrants and Emerging Players: Lead with synthetic pitch-derived needle coke production targeting Indian and Middle Eastern EAF steelmakers where coal tar supply relationships remain underdeveloped. Odisha and Gujarat aluminum capacity expansion offers the most penetrable demand pocket for long-term offtake positioning. Pursue direct procurement relationships with smelters possessing pneumatic unloading infrastructure to bypass established distributor networks. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed calcination specialists possessing delayed coking technology but lacking refinery integration. Five-to-ten year viability hinges on carbon border adjustment mechanism exposure and low-emission certification positioning. Watch for EU Green Deal embedded carbon accounting implementation as inflection indicator for premium pitch coke demand bifurcation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coking Operations | Captive metallurgical coal supply secures feedstock cost stability against steelmaking output fluctuations. |
| Delayed Coking Technology Deployment | Higher-yield needle coke production from Japanese and South Korean manufacturers serves Indian EAF expansion. |
| Long-term Supply Agreement | Multi-year offtake contracts with UAE smelters displace spot market purchasing and consolidate supplier relationships. |
| Emissions Capture Technology Investment | MEE-compliant calcination systems preserve operating permits in Shanxi and Shandong provinces. |
| Green Manufacturing Transition | Low-emission pitch coke certification positions suppliers for EU carbon border adjustment mechanism premiums. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with aluminum smelter procurement directors, carbon anode plant managers, coking refinery technical leads, and graphite electrode manufacturer R&D heads. Secondary validation drew from customs trade data, SEC filings of listed carbon material producers, EPA emissions compliance records, and ECHA REACH registration databases. Bottom-up volume modeling triangulated against top-down industry association estimates.
Across the analysis window, forecasts employed segmented growth projection across feedstock origin, product grade tier, end-use application, and regional production hub dimensions. CAGRs were derived from historical volume trajectories adjusted for capacity expansion announcements and regulatory enforcement timelines. Forecast inputs incorporated aluminum smelter greenfield commissioning schedules and EAF steelmaking adoption curves in India and the Middle East.
The analysis sits within stated boundaries; outcomes outside sustained Gulf aluminum capacity expansion, stable metallurgical coal coking output, and consistent REACH-MEE-EPA regulatory enforcement convergence would require recalibration. Forecasts reflect documented assumptions regarding needle coke quality premium persistence and calcined petroleum coke substitution elasticity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Titanium Dioxide Market
Bulk Chemicals
Natural Thickener Market
Bulk Chemicals
Diisopropylbenzene Market
Bulk Chemicals
Sodium Hydrogen Sulphite Market
Bulk Chemicals
North America Carbon Black Market
Bulk Chemicals
FT Wax Market
Bulk Chemicals
Sodium Nitrate Market
Bulk Chemicals
Potassium Fluoborate Market
Bulk Chemicals
Phosphate Rock Market
Bulk Chemicals
Magnesium Acetate Market
Bulk Chemicals
Furandicarboxylic Acid Market
Bulk Chemicals
North America Calcium Carbonate Market
Bulk Chemicals
Chlor Alkali Market
Bulk Chemicals
United States Soda Ash Market
Bulk Chemicals
Aluminum Sulfate Market
Bulk Chemicals
Green Petroleum Coke and Calcined Petroleum Coke Market