
 Sodium Metasilicate Pentahydrate Market | 2026-2036
Sodium Metasilicate Pentahydrate Market Size, Share, and Industry Trends Forecast 2026-2036
Sodium Metasilicate Pentahydrate Market Analysis
Capital-intensity divergence between integrated silicate producers and regional blenders is reorganizing competitive tiers in sodium metasilicate pentahydrate supply. PQ Corporation leverages captive alkali-silicate feedstock to sustain margin structures that smaller competitors cannot replicate. Qingdao Hai Wan Chemical anchors Asia-Pacific supply through integrated soda ash and silica sourcing, while Silmaco competes on specialty-grade purity for European detergent formulators.
Sodium metasilicate pentahydrate, Na₂SiO₃·5H₂O, is a crystalline alkaline silicate produced via controlled crystallization from sodium silicate solutions, typically assaying 28-30% SiO₂ and 28-30% Na₂O with a molar ratio near 1.0. The compound functions primarily as a builder, emulsifier, and corrosion inhibitor in alkaline cleaning formulations. Powder and granular grades dominate volume flows into industrial and institutional end users where automated dosing systems favor free-flowing particulates over liquid alternatives. Detergent applications occupy the largest value pool, though coating and adhesives segments are gaining formulation share as silicate chemistry displaces solvent-based systems.
EPA regulations under the Toxic Substances Control Act govern silicate manufacturing emissions in the United States, while REACH registration requirements in Europe mandate full toxicological dossiers for pentahydrate imports above one tonne annually. China's MEE enforces wastewater discharge limits on silicate crystallization facilities, raising compliance costs for producers serving domestic and export markets. Buyers must monitor regulatory divergence between jurisdictions to avoid supply chain disruption from non-compliant material.
Market Dynamics
Phosphate-free detergent mandates across institutional and industrial cleaning sectors are restructuring sodium metasilicate pentahydrate demand patterns, as formulators substitute silicate builders for banned phosphates in automated dishwashing and hard-surface cleaners.
Growth Catalysts
- EU Green Deal chemical safety frameworks:REACH registration requirements and the Chemicals Strategy for Sustainability are accelerating phosphate replacement timelines in European institutional cleaning, expanding silicate builder volumes in commercial laundries and food service operations.
- Industrial cleaning automation:Automated dosing systems in healthcare and hospitality facilities favor free-flowing granular silicates over liquid alternatives, locking in powder-grade specifications for equipment compatibility.
- Coating chemistry displacement:Water-based silicate binders are displacing solvent-based systems in corrosion-resistant primers and refractory coatings, opening technical-grade demand channels outside traditional detergent applications.
Market Restraints
- Soda ash feedstock volatility:Energy-intensive Solvay process production and natural gas price swings transmit directly to sodium silicate crystallization economics, compressing margin stability for non-integrated producers.
- Supply concentration in Shandong Province:Crystallization capacity clusters along China's eastern seaboard create geographic risk concentration for buyers dependent on seaborne material flows to European and North American formulators.
- Solid caustic soda handling limitations:Pentahydrate's hygroscopicity and alkaline dust generation restrict automated handling options in small-scale blending operations, capping penetration into artisanal detergent manufacturing.
Strategic Opportunities
- India BIS standardization gap:Absence of mandatory ISI certification for silicate builders in institutional cleaning creates first-mover positioning for quality-assured imports as domestic formulators upgrade from ungraded material.
- MEA wastewater discharge incentives:Saudi Arabia's treated industrial effluent reuse mandates and UAE green building codes are accelerating silicate-based corrosion inhibitor adoption in cooling water treatment circuits.
- Spray-dried agglomeration convergence:Combination of fluidized bed processing with controlled hydration is enabling dust-free granular grades that bridge powder flowability and liquid dissolution speed in single-dose detergent pods.
Industry Challenges
- Crystallization process control expertise:Narrow temperature and concentration windows for pentahydrate nucleation require skilled operators absent in emerging market production expansions, elevating defect rates and off-spec volumes.
- REACH dossier maintenance burdens:ECHA's substance evaluation cycles and updated toxicological endpoint requirements demand continuous registration investment that smaller importers struggle to sustain against integrated manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sodium Metasilicate Pentahydrate Market |
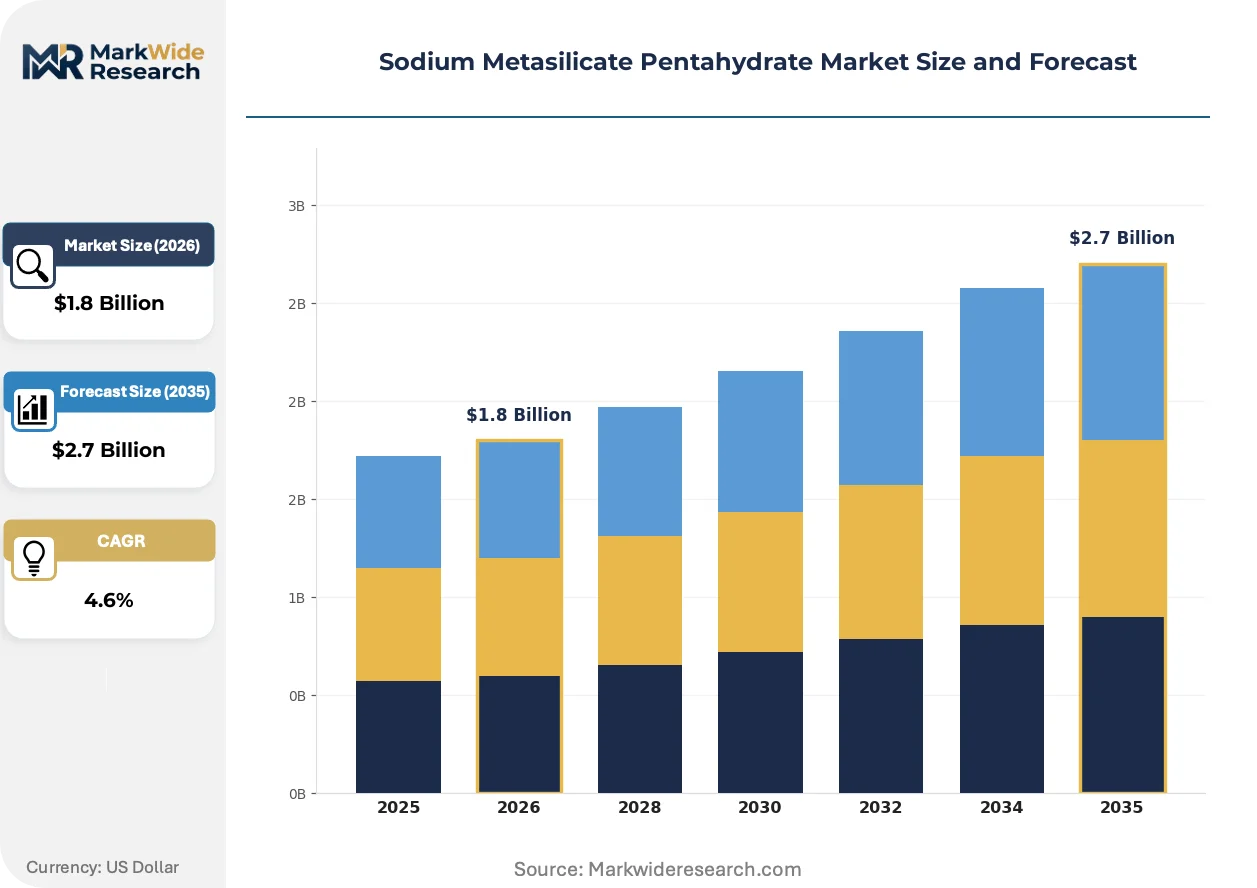
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granular, Powder, Liquid, Flakes Application: Detergents, Cleaning Agents, Coating, Adhesives End User: Household, Industrial, Commercial, Institutional Packaging Type: Bags, Drums, Totes, Pails |
| Companies Covered | American Elements, Henny Enterprises, Jay Dinesh Chemicals, Mistral Industrial Chemicals, Nippon Chemical Industrial Co. Ltd., Qingdao Hai Wan Chemical (Group) Co. Ltd., PQ Corporation, Silmaco, Occidental Chemical Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sodium Metasilicate Pentahydrate Market Emerging Trajectories
Silicate chemistry is migrating beyond detergent builders into functional coating and adhesive applications, while regulatory pressure on phosphate alternatives intensifies formulation R&D investment across institutional cleaning supply chains.
Controlled-hydration spray-dried agglomerates are fragmenting traditional powder-grade specifications in automated dishwashing. European contract cleaners and North American healthcare laundries are adopting these engineered particles at accelerating rates. The technology is fragmenting procurement patterns by enabling single-dose pod formats that bypass conventional bulk silicate handling infrastructure.
REACH's 2023-2027 substance evaluation roadmap is tightening silicate classification requirements for respiratory and dermal exposure endpoints. Industrial formulators must now submit extended safety data sheets and exposure scenarios for downstream uses. Detergent compounders serving European institutional markets are responding by consolidating supplier bases toward dossier-complete manufacturers with established only-representative structures.
Direct mill-to-blender procurement contracts are displacing distributor intermediaries in North American industrial cleaning supply chains. Large facility management groups and national janitorial service providers are negotiating volume commitments with crystallization producers for silicate builders. This disintermediation is most visible in California and Texas, where consolidated healthcare systems and energy sector maintenance operations favor transparent chain-of-custody documentation for chemical inventory compliance.
Sodium Metasilicate Pentahydrate Market Segmentation
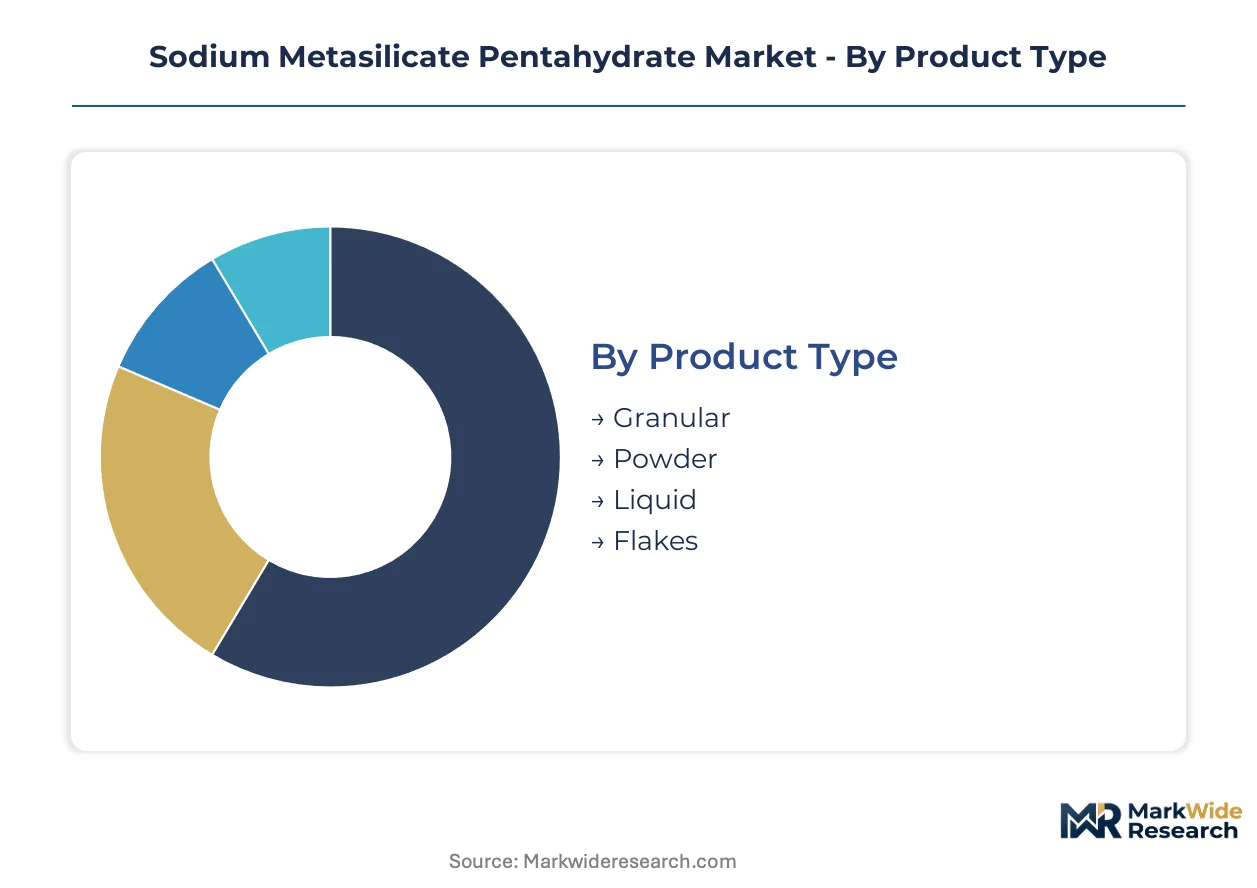
Sodium metasilicate pentahydrate procurement patterns diver sharply across physical forms and end-use specifications. Channel economics favor bulk granular flows into automated industrial systems, while specialty packaging unlocks premium pricing in institutional segments.
Product Type:
Granular and powder grades flow predominantly through distributor networks serving institutional cleaning contractors, while liquid and flake formats reach formulators via direct mill relationships.
- Granular:Free-flowing crystalline particles with controlled particle size distribution optimize automated dosing equipment in healthcare and hospitality laundries. Demand concentrates in California and Texas healthcare systems where consolidated procurement mandates equipment-compatible formats. REACH-compliant granular grades command sourcing premiums from European detergent compounders.
- Powder:Fine particulate silicate with higher surface area accelerates dissolution in hard-surface cleaners and manual dishwashing compounds. Industrial blenders in Shandong Province and the US Gulf Coast favor powder for flexible formulation adjustments. Dust generation during handling restricts penetration into small-scale artisanal operations.
- Liquid:Pre-dissolved sodium silicate solution eliminates hydration variables for coating formulators displacing solvent-based binders.
- Flakes:Thin crystalline plates dissolve rapidly in hot-process detergent manufacturing, serving regional blenders in India and Brazil.
Granular dominates installed base. Powder is where expansion concentrates.
Application:
Margin structures stratify sharply across these four use cases, with coating and adhesives commanding technical-grade premiums over commodity detergent builders.
- Detergents:Primary builder function in phosphate-free laundry and dishwashing formulations, leveraging alkaline pH and sequestration chemistry. Institutional laundries in Germany and France drive volume as EU Green Deal timelines accelerate phosphate replacement. Automated dosing compatibility locks in granular specifications for commercial operators.
- Cleaning Agents:Hard-surface degreasers and metal cleaners exploit silicate emulsification and corrosion inhibition. Food service operations in Saudi Arabia and UAE adopt silicate-based cleaners under treated effluent reuse mandates. Powder grades prevail in manual application settings.
- Coating:Water-based silicate binders for corrosion-resistant primers and refractory linings, displacing solvent systems under EPA VOC regulations.
- Adhesives:Inorganic silicate bonding in high-temperature construction applications, serving cement and ceramic sectors.
Detergents anchor volume throughput. Coating is climbing the fastest.
End User:
Procurement scale and specification rigor vary dramatically across these four customer types, with institutional buyers driving standardization while industrial users prioritize supply security.
- Industrial:Large-scale manufacturing maintenance operations demand bulk granular deliveries with chain-of-custody documentation. Energy sector facilities in Texas and Alberta specify pentahydrate for equipment cleaning and corrosion protection. Direct mill contracts displace distributor intermediaries for volume accounts.
- Institutional:Healthcare systems, educational facilities, and government buildings mandate phosphate-free formulations under sustainability procurement policies. Consolidated facility management groups in California negotiate transparent pricing with crystallization producers. REACH dossier completeness filters supplier pools.
- Commercial:Food service, hospitality, and retail cleaning services balance cost against equipment compatibility.
- Household:Consumer detergent brands specify spray-dried agglomerates for single-dose pod formats.
Industrial commands the largest contract values. Institutional is gaining share fastest.
Packaging Type:
Logistics economics and handling automation dictate packaging selection, with bulk formats dominating high-volume flows and smaller containers serving fragmented demand.
- Bags:Multi-wall paper or woven polypropylene sacks in 25-50 kg sizes serve regional blenders and small industrial accounts. Bagged powder moves through distributor networks in India and Southeast Asia where ungraded material still prevails. Handling labor intensity limits adoption in automated facilities.
- Drums:Steel or fiber drums contain 200-250 kg of granular or powder product for mid-scale formulators. Drum specifications dominate European imports where REACH documentation accompanies each container. Reconditioned drum programs reduce packaging costs for circular-economy-focused buyers.
- Totes:Intermediate bulk containers in 1000-1250 kg capacities optimize freight economics for liquid silicate and large powder accounts.
- Pails:20-25 kg plastic pails serve specialty coating formulators and adhesive compounders requiring precise batch control.
Bags dominate transaction count. Totes is where freight optimization concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and France demonstrate the lowest price elasticity, absorbing REACH compliance premiums for certified granular grades, while Indian blenders remain highly sensitive to landed cost fluctuations from Shandong crystallization facilities.
China
Shandong Province crystallization clusters supply the majority of global powder and granular volumes, with Qingdao and Weifang facilities serving European detergent compounders under MEE wastewater discharge protocols. The country's dual carbon goals are elevating energy costs for Solvay-process soda ash feedstock, compressing margins for non-integrated silicate producers. PQ Corporation and Qingdao Hai Wan Chemical anchor production capacity along the eastern seaboard, consolidating export flows through Qingdao port.
Germany
REACH dossier completeness filters supplier pools for institutional cleaning compounders in North Rhine-Westphalia and Bavaria, where healthcare laundries specify granular grades for automated dosing compatibility. The EU Green Deal's Chemicals Strategy for Sustainability accelerates phosphate replacement timelines, expanding silicate builder volumes in commercial operations. ECHA substance evaluation cycles demand continuous registration investment that favors integrated manufacturers with established only-representative structures.
United States
EPA Toxic Substances Control Act emissions governance shapes silicate manufacturing economics in Texas and Louisiana, where energy sector maintenance operations specify pentahydrate for equipment cleaning and corrosion protection. Direct mill-to-blender procurement contracts displace distributor intermediaries for large facility management groups in California and Texas. Consolidated healthcare systems mandate transparent chain-of-custody documentation for chemical inventory compliance.
India
Absence of mandatory BIS certification for silicate builders creates first-mover positioning for quality-assured imports as domestic formulators in Maharashtra and Gujarat upgrade from ungraded material. Regional blenders favor bagged powder for flexible formulation adjustments in manual dishwashing compounds. Handling labor intensity limits adoption of automated dosing systems outside institutional facilities in Delhi-NCR and Bangalore.
Saudi Arabia
Treated industrial effluent reuse mandates under the country's wastewater discharge framework accelerate silicate-based corrosion inhibitor adoption in cooling water treatment circuits serving Riyadh and Eastern Province petrochemical complexes. SFDA chemical safety requirements govern imported silicate specifications for food service cleaning applications. UAE green building codes in Dubai and Abu Dhabi extend similar demand patterns for institutional hospitality operations.
Sodium Metasilicate Pentahydrate Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive alkali-silicate feedstock sustaining margin structures that smaller competitors cannot replicate. The market organizes around three strategic archetypes: integrated silicate producers with backward control over soda ash and silica sourcing, regional blenders competing on formulation flexibility, and specialty-grade purists serving European detergent formulators. Dominant competitive moves include capacity consolidation through strategic partnerships and geographic expansion into understandardized import markets.
Within the integrated producer tier, PQ Corporation exemplifies captive feedstock economics, while Qingdao Hai Wan Chemical occupies a position anchored in Shandong Province crystallization capacity. Silmaco represents the specialty-grade archetype, serving European institutional formulators with dossier-complete material. These three entities collectively illustrate how feedstock control, geographic concentration, and regulatory compliance stratify competitive positioning across the value chain.
| Leading Market Players |
|---|
| American Elements |
| Henny Enterprises |
| Jay Dinesh Chemicals |
| Mistral Industrial Chemicals |
| Nippon Chemical Industrial Co. Ltd. |
| Qingdao Hai Wan Chemical (Group) Co. Ltd. |
| PQ Corporation |
| Silmaco |
| Occidental Chemical Corporation |
| Others |
Supply Flow & Price Mechanics
Phosphate-free detergent mandates replacing banned phosphates with silicate builders are simultaneously redrawing supply geography toward Shandong Province crystallization clusters and compressing pricing power for non-integrated producers lacking captive soda ash feedstock. This substitution dynamic concentrates volume leverage among PQ Corporation and Qingdao Hai Wan Chemical while fragmenting margin structures for regional blenders dependent on spot soda ash purchases.
Pricing Analysis
After-sales service contracts for automated dosing system maintenance drive lifetime value capture for REACH-compliant granular grades serving European institutional laundries. Three-tier pricing structure across premium REACH-certified, standard industrial-grade, and economy unbranded material segments the market by documentation completeness and purity specifications. Cost compression in economy powder grades is intensifying because Solvay-process energy costs transmit directly to non-integrated crystallization economics. Industrial buyers in Texas energy sector maintenance operations demonstrate lowest price sensitivity, while Indian regional blenders in Maharashtra and Gujarat absorb highest elasticity to landed cost fluctuations.
Supply Chain Analysis
Container availability constraints on the Qingdao-to-Rotterdam trade lane elevate inbound logistics costs for European detergent compounders sourcing granular grades from Shandong Province facilities. Supply concentrates in China, Germany, and the United States, with crystallization capacity clustering along China's eastern seaboard and captive alkali-silicate production anchoring North American and European supply security. Raw material dependencies draw from soda ash via Solvay process, silica sand, and energy inputs, with single-source vulnerability concentrated in Shandong crystallization capacity serving global export flows. Distribution runs through direct mill-to-blender contracts displacing distributor intermediaries for large healthcare and energy sector accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sodium metasilicate pentahydrate demand sits in early-cycle expansion as EU Green Deal phosphate replacement timelines accelerate silicate builder adoption across institutional cleaning supply chains.
For Market Incumbents: Shield margin structures by deepening backward integration into soda ash feedstock or securing long-term energy supply agreements for Solvay-process economics. Consolidate supplier relationships with REACH dossier-complete manufacturers to defend against ECHA substance evaluation cycle disruptions that threaten registration continuity for smaller competitors. For New Entrants and Emerging Players: Anchor in India's quality-assured import gap created by absent BIS certification standards for institutional cleaning silicate builders. Target Maharashtra and Gujarat regional blenders upgrading from ungraded material with drum-packaged REACH-compliant granular grades, leveraging documentation transparency as the primary go-to-market wedge against established unbranded suppliers. For Investors and Strategic Acquirers: The market sits at a capacity-constrained phase that favors integrated producers with captive alkali-silicate feedstock and established only-representative structures for European REACH compliance. Long-term viability over the next decade rests on crystallization process control expertise and geographic diversification away from Shandong concentration risk. Watch for MEE wastewater discharge enforcement tightening as the signal indicating margin compression inflection for non-compliant Chinese export capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Soda Ash | PQ Corporation's captive alkali-silicate feedstock sustains margin structures smaller competitors cannot replicate. |
| REACH Dossier Investment | ECHA substance evaluation cycles demand continuous registration investment favoring integrated manufacturers with established only-representative structures. |
| Spray-Dried Agglomeration Capacity | Fluidized bed processing with controlled hydration enables dust-free granular grades for single-dose detergent pod formats. |
| Direct Mill-to-Blender Contracts | Consolidated California and Texas healthcare systems mandate transparent chain-of-custody documentation for chemical inventory compliance. |
| India Quality-Assured Import Positioning | Absence of mandatory BIS certification creates first-mover advantage for REACH-compliant drum shipments to Maharashtra blenders. |
Methodological Framework
Two parallel data streams informed the analysis: primary field engagement with crystallization plant managers, procurement leads at detergent compounders, distribution channel partners, and technical R&D directors; and secondary validation through customs/trade data, ACC and Cefic industry reports, SEC 10-K filings, and ECHA registration dossiers. Bottom-up capacity and consumption modeling triangulated against top-down trade flow analysis ensured convergence across estimation approaches.
Across the projection horizon, the analytical framework modeled segmentation across physical form tier, end-use industry, packaging format, and regional production hub. CAGRs were derived from elasticity-adjusted demand projections incorporating phosphate replacement timeline acceleration, Solvay-process energy cost trajectories, and institutional procurement automation penetration rates.
Decision-makers should treat outputs as directional under assumptions of sustained EU Green Deal enforcement and stable Shandong export capacity; material deviation in MEE wastewater discharge stringency or REACH classification tightening would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Formate Brine Market
Bulk Chemicals
Global Ammonium Chloride Market
Bulk Chemicals
Ethylene Glycol Market
Bulk Chemicals
Dicyclopentadiene (DCPD) Market
Bulk Chemicals
Dimethyl Terephthalate (DMT) Market
Bulk Chemicals
Precipitated Barium Sulphate Market
Bulk Chemicals
Ammonium Nitrate Market
Bulk Chemicals
Global Sodium Lactate Market
Bulk Chemicals
Carbonate Market
Bulk Chemicals
Lithium Benzoate Market
Bulk Chemicals
Sodium Dicyanamide Market
Bulk Chemicals
Magnesium Chloride Market
Bulk Chemicals
Banlangen Granules Market
Bulk Chemicals
3-Mercapto-2-Pentanone Market
Bulk Chemicals
Acetyl Tributyl Citrate Market
Bulk Chemicals
Heavy Alkyl Benzenes Market