
 Pyrimidine Market | 2026-2036
Pyrimidine Market Size, Share, and Industry Trends Forecast 2026-2036
Pyrimidine Market Analytics
Chinese specialty chemical producers is hardening pyrimidine supply security through backward integration into nitrile and urea feedstocks. BASF SE leverages its Ludwigshafen integrated site to sustain cost-advantaged pyrimidine derivative output for European pharmaceutical customers. Merck & Co. Inc. anchors its pyrimidine nucleoside position through high-specification cGMP manufacturing protocols. Alkyl Amines Chemicals Ltd competes on aliphatic amine linkages that feed into pyrimidine ring construction for agrochemical intermediates.
Pyrimidine denotes a six-membered heterocyclic aromatic compound containing two nitrogen atoms at positions 1 and 3, typically synthesized via Biginelli or Pinner-type condensation reactions using amidines and active methylene compounds, and serves as the structural scaffold for cytosine, thymine, and uracil in nucleic acids plus synthetic drugs and crop protection agents. Halogenated pyrimidines occupy the margin-rich tier where fluorinated substituents command pharmaceutical licensing premiums for kinase inhibitor programs. Pyrimidine nucleosides represent the fastest-expanding category as mRNA vaccine platform companies secure long-term supply agreements for modified uridine building blocks. Chemical intermediates remain the mature volume anchor, with pricing disciplined by commoditized Asian supply.
EPA regulates pyrimidine biocide formulations under FIFRA antimicrobial registration requirements, while ECHA enforces REACH substance authorization for halogenated pyrimidine intermediates crossing into European pharmaceutical supply chains. China's MEE implements dual carbon goals that tighten energy intensity benchmarks for pyrimidine nitrile precursor plants. Stakeholders must monitor how FDA drug master file expectations for pyrimidine-derived active pharmaceutical ingredients evolve against tightening ICH Q3D elemental impurity standards.
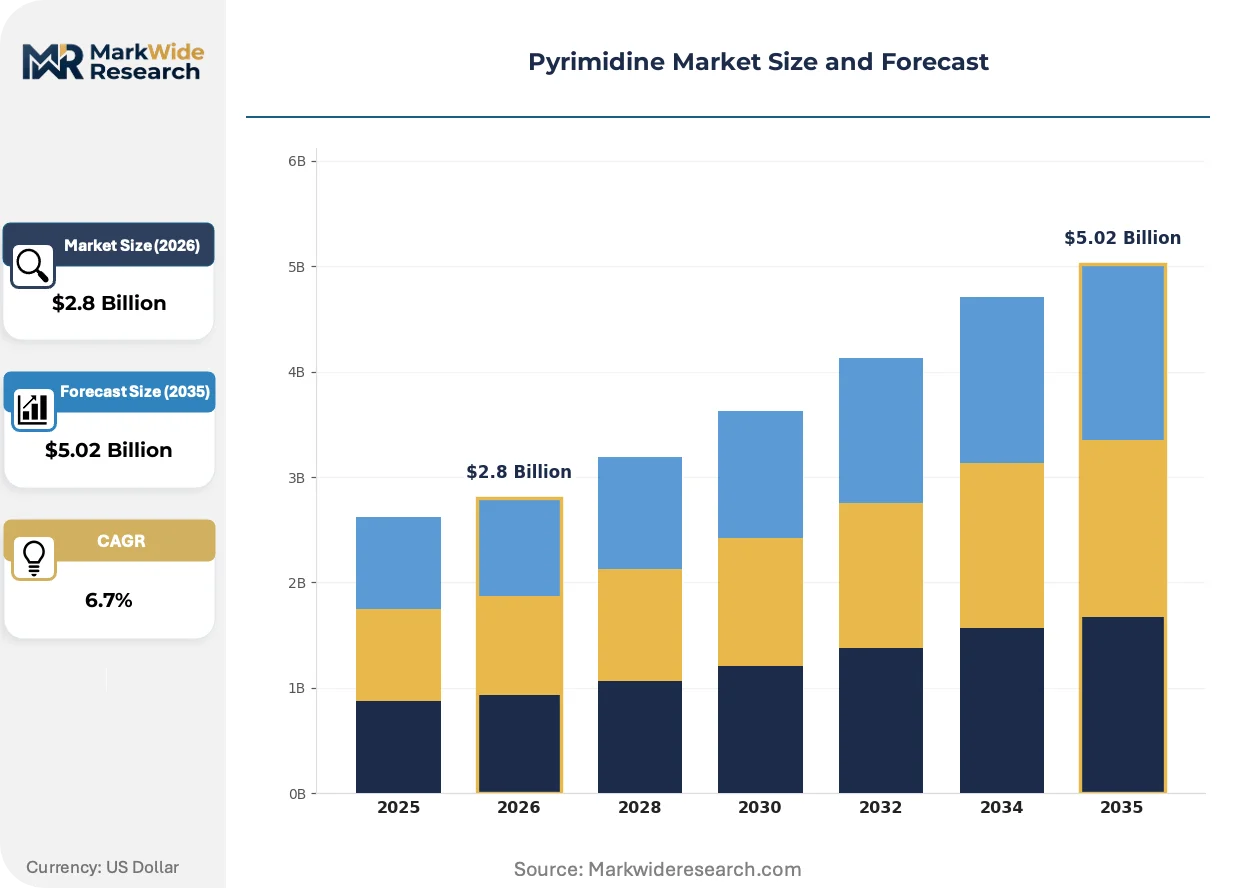
Market Dynamics
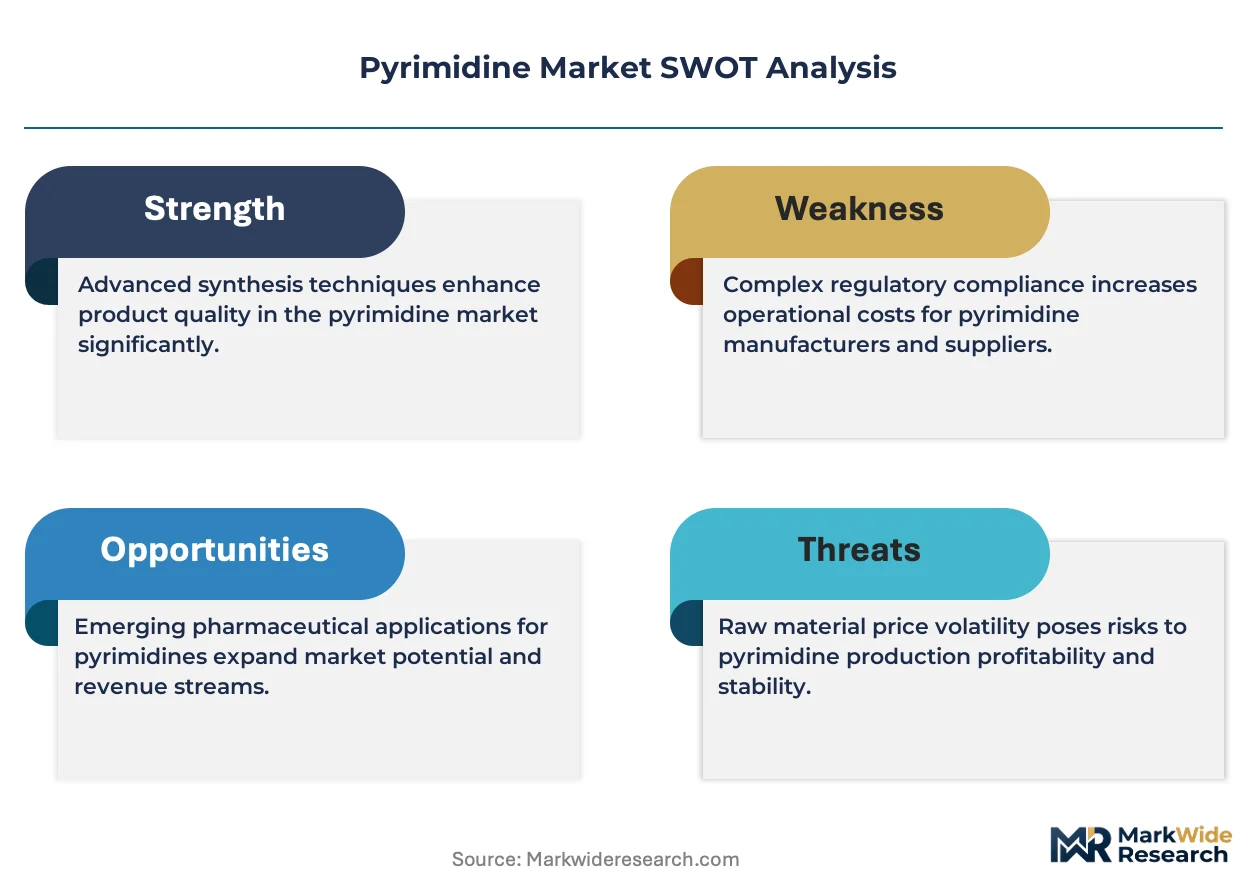
Pharmaceutical-grade pyrimidine procurement is consolidating around cGMP-certified producers as FDA and EMA tighten elemental impurity thresholds under ICH Q3D, forcing API manufacturers to requalify supply chains and absorb higher purity premiums.
Growth Catalysts
- Modified nucleoside demand:mRNA vaccine platforms require fluorinated uridine building blocks for therapeutic candidates, pulling pyrimidine nucleoside volumes into long-term supply agreements.
- REACH substance authorization:ECHA's tightening controls on halogenated intermediates are accelerating pharmaceutical-grade certification investments among European specialty chemical producers.
- China's dual carbon policy:MEE energy intensity benchmarks for nitrile precursors are pushing domestic API manufacturers toward captive pyrimidine production to secure feedstock access.
Market Restraints
- Acetonitrile feedstock volatility:Pyrimidine synthesis relies on amidine precursors derived from acetonitrile, whose pricing swings with acrylic fiber and pharmaceutical solvent demand cycles.
- Jiangsu-Zhejiang supply concentration:Over half of global pyrimidine intermediate capacity sits within a 200-kilometer radius, exposing buyers to regional environmental shutdowns and logistics bottlenecks.
- Fluorination complexity:Selective halogenation requires anhydrous hydrogen fluoride handling capabilities that many mid-scale producers lack, capping margin-rich fluorinated pyrimidine output.
Strategic Opportunities
- India's PLI scheme for APIs:Production-linked incentives for bulk drug manufacturing are attracting pyrimidine intermediate investments to reduce import dependence from China.
- Continuous flow synthesis:Microreactor technology for Biginelli condensations promises yield improvements and waste reduction for contract manufacturers serving agrochemical clients.
- Biocide formulation registration:EPA FIFRA antimicrobial pathways for pyrimidine-derived fungicides open specialty chemical margins outside pharmaceutical commoditization.
Industry Challenges
- Analytical method transfer:Migrating from HPLC to UPLC-MS for pyrimidine impurity profiling requires revalidation timelines that delay customer qualification by 12-18 months.
- Process safety management:Pinner-type condensations using hydrogen cyanide derivatives demand specialized engineering controls that strain capital budgets at scale-up.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pyrimidine Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Base Pyrimidines, Halogenated Pyrimidines, Pyrimidine Nucleosides, Pyrimidine Derivatives Application: Pharmaceuticals, Agriculture, Biocides, Chemical Intermediates End User: Research Laboratories, Pharmaceutical Companies, Agrochemical Firms, Contract Manufacturing Organizations Distribution Channel: Online Platforms, Direct Sales, Distributor Networks, Retail Outlets |
| Companies Covered | Hubei Nanjing Chemical Industry Group Co, Merck & Co. Inc., BASF SE, Alkyl Amines Chemicals Ltd, AbbVie Inc., Eli Lilly and Company, AstraZeneca, LGC Limited, Novartis AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pyrimidine Market Evolving Landscape
Process intensification and regulatory convergence are compressing the traditional batch-to-market timeline for pyrimidine derivatives, with technology adopters capturing margin premiums in both pharmaceutical and agrochemical channels.
Continuous manufacturing is unifying pyrimidine synthesis steps previously executed in discrete vessels. Pharmaceutical contract manufacturers in Switzerland and Singapore are piloting integrated Biginelli-Pinner sequences that cut solvent volumes by two-thirds. This unifying architecture is compressing capital requirements for mid-scale entrants while tightening purity consistency beyond batch reproducibility limits.
REACH authorization deadlines for halogenated pyrimidine intermediates are forcing supply chain reconfiguration. ECHA's 2026 sunset date for non-authorised uses is redirecting European pharmaceutical procurement toward pre-registered suppliers with complete dossiers. Fluorinated pyrimidine categories face the steepest compliance cliffs, with kinase inhibitor programs accelerating supplier audits to secure continuity.
Long-term offtake agreements are displacing spot purchasing for nucleoside-grade pyrimidines. mRNA platform companies in Massachusetts and Bavaria are locking in five-year supply contracts with built-in price escalation caps, stripping traditional distributors from high-value transactions. This contractual shift is most visible in modified uridine categories where vaccine developers prioritize supply security over quarterly price optimization.
Pyrimidine Market Segmentation
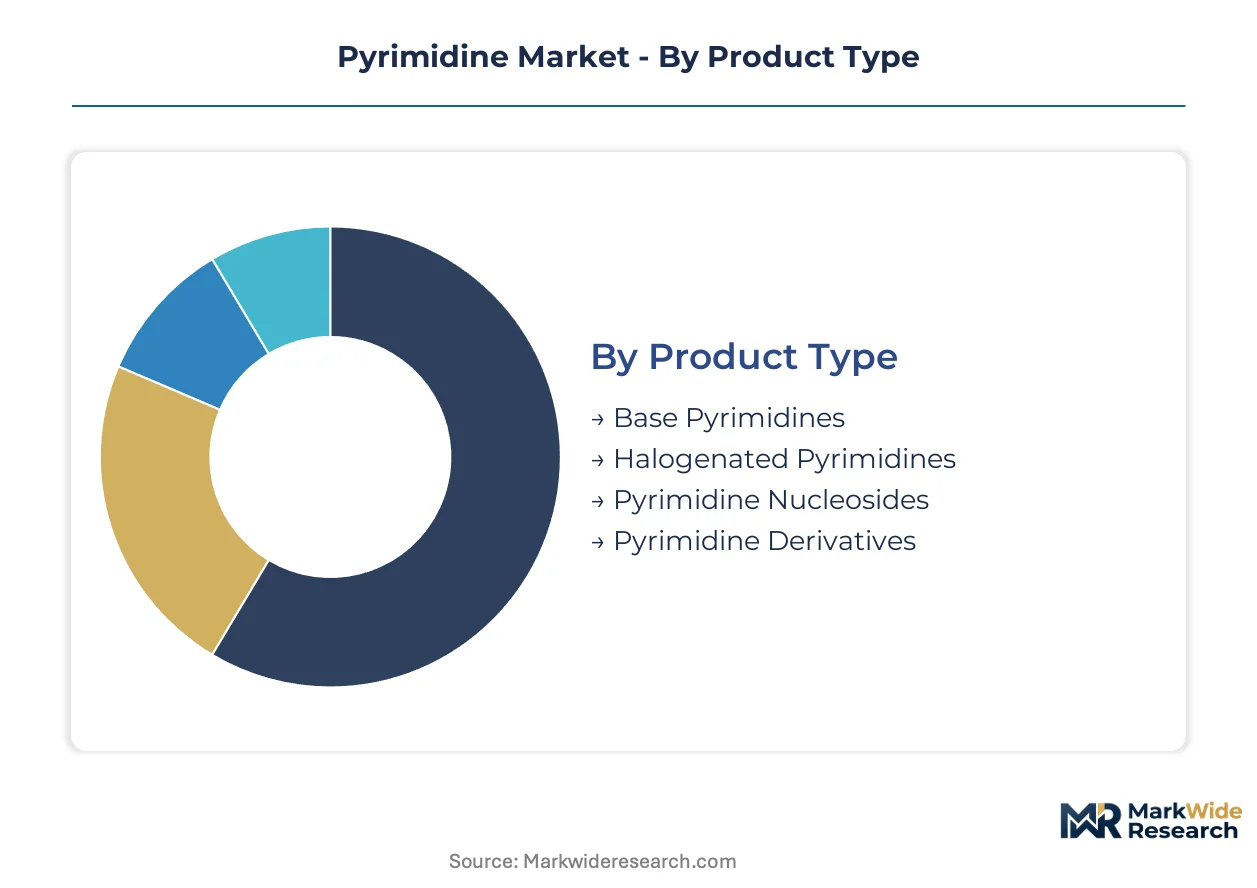
Pyrimidine procurement decisions split across technical specifications, regulatory compliance burdens, and supply security requirements. Buyers in pharmaceutical and agrochemical channels weight purity grades, certification status, and geographic sourcing concentration differently. Understanding these segment boundaries clarifies where margin pools concentrate versus where commoditization pressures dominate.
Product Type:
Pharmaceutical buyers prioritize substitution patterns on the pyrimidine ring that enable specific kinase binding or nucleoside incorporation.
- Base Pyrimidines:Unsubstituted six-membered heterocyclic cores serve as feedstock for downstream functionalization. Demand concentrates in Chinese API manufacturing clusters where amidine condensation capacity underwrites cost-competitive supply for generic drug producers facing FDA and EMA impurity scrutiny.
- Halogenated Pyrimidines:Fluorinated and chlorinated ring systems carry pharmaceutical licensing premiums due to selective halogenation complexity. Massachusetts and Bavaria-based mRNA platform developers secure long-term offtake agreements for fluorinated intermediates, stripping spot market liquidity from this tier.
- Pyrimidine Nucleosides:Modified uridine and cytidine building blocks for nucleic acid therapeutics.
- Pyrimidine Derivatives:Functionalized scaffolds spanning agrochemical and specialty chemical applications.
Base pyrimidines lead on scale; nucleosides lead on momentum.
Application:
Regulatory intensity varies sharply across end-use channels, with pharmaceutical applications absorbing the steepest compliance costs.
- Pharmaceuticals:Antiviral and oncology drug synthesis drives specification-grade procurement. cGMP-certified producers in Switzerland and Singapore capture premiums as FDA and EMA tighten ICH Q3D elemental impurity thresholds, forcing API manufacturers to requalify supply chains.
- Agriculture:Crop protection agents utilize pyrimidine scaffolds for fungicide and herbicide actives. Indian agrochemical formulators source aliphatic amine-linked intermediates from domestic producers leveraging PLI scheme incentives to reduce Chinese import dependence.
- Biocides:Antimicrobial formulations regulated under EPA FIFRA registration requirements.
- Chemical Intermediates:Commoditized building blocks for diverse synthetic chemistry.
Pharmaceuticals command the highest purity premiums; agriculture offers volume scale with thinner margins.
End User:
Procurement sophistication tracks R&D intensity and regulatory exposure, with large pharmaceutical companies driving standard-setting.
- Research Laboratories:Small-volume, high-SKU procurement for discovery chemistry. Academic and biotech researchers in Boston and Basel clusters source through online platforms, prioritizing rapid fulfillment over long-term contracting.
- Pharmaceutical Companies:Integrated drug developers with captive process chemistry capabilities. Merck and Roche anchor nucleoside demand through high-specification cGMP manufacturing protocols, internalizing critical pyrimidine production where supply security warrants capital investment.
- Agrochemical Firms:Syngenta and Bayer crop science divisions.
- Contract Manufacturing Organizations:CDMOs serving multiple pharmaceutical clients with flexible batch scale.
Pharmaceutical companies lead on contract value; research laboratories lead on transaction velocity.
Distribution Channel:
Channel selection reflects order size, technical support requirements, and the buyer's need for supply chain transparency.
- Direct Sales:Long-term supply agreements for nucleoside-grade pyrimidines. mRNA vaccine developers in Massachusetts bypass distributors entirely, locking in five-year contracts with built-in price escalation caps to secure modified uridine continuity.
- Distributor Networks:Regional specialty chemical distributors serve mid-scale pharmaceutical and agrochemical accounts. European distributors face ECHA REACH authorization pressures, filtering their supplier base toward pre-registered producers with complete substance dossiers.
- Online Platforms:E-commerce procurement for research-grade materials.
- Retail Outlets:Limited presence for small-volume laboratory supply.
Direct sales capture the highest-value transactions; distributor networks retain broadest geographic coverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting pyrimidine production toward jurisdictions where compliance costs align with end-market pricing power, compressing margins for non-integrated European producers while rewarding Chinese and Indian manufacturers with captive feedstock control.
China
Jiangsu and Zhejiang provinces concentrate over half of global pyrimidine intermediate capacity within a 200-kilometer radius, exposing buyers to regional environmental shutdowns. MEE dual carbon goals tighten energy intensity benchmarks for nitrile precursor plants, pushing domestic API manufacturers toward captive pyrimidine production. Yangtze River Delta chemical parks are hardening supply security through backward integration into urea and amidine feedstocks.
United States
Massachusetts-based mRNA platform developers lock in five-year supply contracts for modified uridine building blocks, stripping spot market liquidity from nucleoside-grade tiers. EPA FIFRA antimicrobial registration requirements govern pyrimidine biocide formulations, while FDA drug master file expectations tighten against ICH Q3D elemental impurity standards. Greater Boston biotech clusters source through direct sales channels, bypassing distributors entirely for supply security.
Germany
BASF SE leverages its Ludwigshafen integrated site to sustain cost-advantaged pyrimidine derivative output for European pharmaceutical customers. ECHA REACH substance authorization deadlines for halogenated intermediates redirect procurement toward pre-registered suppliers with complete dossiers. Bavaria-based mRNA vaccine developers accelerate supplier audits to secure fluorinated pyrimidine continuity ahead of 2026 sunset dates.
India
PLI scheme production-linked incentives for bulk drug manufacturing attract pyrimidine intermediate investments to reduce import dependence from China. CDSCO regulatory alignment with ICH standards forces API manufacturers to requalify supply chains for pharmaceutical-grade certification. Gujarat and Maharashtra chemical corridors compete on aliphatic amine linkages feeding into pyrimidine ring construction for agrochemical intermediates.
Switzerland
Swissmedic-certified contract manufacturers pilot integrated Biginelli-Pinner continuous sequences that cut solvent volumes by two-thirds. Pharmaceutical CDMOs in Basel clusters capture cGMP premiums as FDA and EMA tighten elemental impurity thresholds, forcing API manufacturers to absorb higher purity costs. Swiss producers anchor nucleoside demand through high-specification manufacturing protocols, internalizing critical pyrimidine production where supply security warrants capital investment.
Pyrimidine Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue fluorinated specialty positions where selective halogenation complexity sustains licensing premiums. The vendor base stratifies across three tiers: integrated petrochemical giants with captive amidine feedstock, mid-scale API manufacturers with cGMP certification investments, and regional distributors serving commoditized agrochemical channels. Strategic archetypes include backward-integrated Chinese producers, European regulatory-compliance specialists, and Indian PLI-scheme beneficiaries. Dominant competitive moves center on long-term offtake contracting with mRNA platform companies and continuous flow technology licensing for yield improvements.
Among diversified chemical conglomerates, BASF SE and Merck & Co. Inc. exemplify the integrated-tier archetype, while Alkyl Amines Chemicals Ltd occupies a position within the specialty amine-feedstock segment. These entities represent contrasting strategic postures: European regulatory pre-registration versus Asian cost-position optimization.
| Leading Market Players |
|---|
| Hubei Nanjing Chemical Industry Group Co |
| Merck & Co. Inc. |
| BASF SE |
| Alkyl Amines Chemicals Ltd |
| AbbVie Inc. |
| Eli Lilly and Company |
| AstraZeneca |
| LGC Limited |
| Novartis AG |
| Others |
Value Network & Pricing Analysis
Pharmaceutical-grade certification tiers separate cGMP-validated producers from commodity amidine suppliers, creating parallel pricing architectures where nucleoside-grade premiums absorb REACH compliance costs while base pyrimidine volumes compete on Jiangsu-Zhejiang feedstock proximity. This bifurcation concentrates margin capture among Swiss and Singaporean contract manufacturers with integrated Biginelli-Pinner capabilities, while Chinese API clusters defend volume positions through captive nitrile production under MEE dual carbon benchmarks.
Pricing Analysis
Distributor margins compress as Massachusetts mRNA developers execute direct long-term offtake agreements for modified uridine, stripping intermediaries from nucleoside-grade transactions. Contract-based long-term supply structures dominate pharmaceutical channels, with price differentiation anchored in ICH Q3D certification status and cGMP audit history. Cost compression in halogenated tiers intensifies because ECHA authorization deadlines accelerate supplier pre-qualification spending. Generic API manufacturers exhibit highest price sensitivity; kinase inhibitor program sponsors accept premium escalation for fluorinated intermediate security.
Supply Chain Analysis
Dual-sourcing mandates from European pharmaceutical procurement teams now require pre-registered REACH dossiers from at least two qualified producers, reshaping supplier qualification timelines. Geographic supply concentration centers on China, India, and Switzerland, with Jiangsu province hosting over half of global amidine condensation capacity. Raw material dependencies draw from acetonitrile, urea, and anhydrous hydrogen fluoride feedstocks. Single-source vulnerability persists in fluorinated intermediate categories where selective halogenation capabilities remain scarce. Distribution runs through direct sales for nucleoside grades and regional specialty distributors for agrochemical intermediates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pyrimidine procurement has shifted toward late-cycle quality specifications as FDA and EMA tighten elemental impurity thresholds, rewarding producers with validated cGMP protocols and pre-registered REACH dossiers.
For Market Incumbents: Acquire continuous flow synthesis assets to defend nucleoside-grade margins against batch-process competitors. Consolidate REACH authorization positions ahead of 2026 sunset deadlines through targeted cGMP capacity additions in Basel and Singapore clusters. Backward integration into amidine feedstocks mitigates acetonitrile volatility exposure from acrylic fiber demand cycles. For New Entrants and Emerging Players: Enter via India's PLI scheme for bulk drug manufacturing, where production-linked incentives reduce capital barriers for pyrimidine intermediate investments. Target agrochemical channels in Gujarat and Maharashtra as the most penetrable segment, leveraging aliphatic amine linkages for fungicide actives. Pursue EPA FIFRA biocide registration as a go-to-market angle outside pharmaceutical commoditization. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-scale producers lack hydrogen fluoride handling capabilities for fluorinated pyrimidine output. Five-to-ten year viability favors Swissmedic-certified CDMOs with integrated continuous manufacturing and locked mRNA platform offtake agreements. Watch ECHA authorization compliance rates as the inflection signal for supplier tier migration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Amidine Feedstocks | Yangtze River Delta producers secure nitrile supply against MEE energy intensity benchmarks. |
| Continuous Flow Technology Licensing | Swiss CDMOs cut solvent volumes by two-thirds in Biginelli-Pinner sequences for pharmaceutical clients. |
| Long-term Supply Agreement | Massachusetts mRNA developers lock five-year contracts with built-in price escalation caps for modified uridine. |
| REACH Substance Authorization | Bavaria-based vaccine sponsors accelerate supplier audits to secure fluorinated pyrimidine continuity. |
| cGMP Certification Investment | Singapore contract manufacturers capture premiums as FDA tightens ICH Q3D elemental impurity thresholds. |
Research Methodology
Bottom-up pharmaceutical and agrochemical demand modeling reconciled against top-down nitrile precursor capacity tracking forms the analytical core of this study. Primary interviews with API manufacturing executives, regulatory affairs leads at European pharmaceutical companies, procurement managers at Massachusetts biotech clusters, and plant managers in Jiangsu chemical parks were combined with secondary validation from ECHA REACH dossiers, FDA drug master file disclosures, CDSCO regulatory circulars, and customs trade data for pyrimidine intermediate flows. Triangulation across these sources anchors volume estimates against actual procurement patterns.
Input-output matrices map amidine feedstock availability through condensation capacity to downstream nucleoside and halogenated derivative output across the projection horizon. Segmentation dimensions modeled include product grade tier, end-use application, certification status, and regional production hub. CAGRs were derived from supply-demand balance projections incorporating MEE dual carbon policy impacts and mRNA platform pipeline expansion. Forecast inputs include acetonitrile pricing volatility indices and ECHA authorization timeline assumptions.
Inputs from ECHA pre-registration databases and FDA cGMP inspection records were available through the study window; gaps in real-time Chinese environmental shutdown notifications introduce uncertainty bands around Jiangsu-Zhejiang capacity estimates. Forecasts reflect documented assumptions regarding mRNA therapeutic development continuity and REACH compliance cost pass-through. Deviation in ECHA enforcement intensity or MEE carbon benchmark implementation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Bronopol Market
Chemicals
HATU Market
Chemicals
Indonesia Nitric Acid Market
Chemicals
Calcium Hydride Market
Chemicals
Global Acetic Anhydride Market
Chemicals
US Methanol Market
Chemicals
P-Ethylphenol Market
Chemicals
Middle East and Africa Construction Chemicals Market
Chemicals
South America Surface Treatment Chemicals Market
Chemicals
Caustic Soda Market
Chemicals
North America Ethylene Dichloride (EDC) Market
Chemicals
Photographic Film Processing Chemicals Market
Chemicals
Allyl Chloride Market
Chemicals
Glyoxal Market
Chemicals
Guanidine Carbonate Market
Chemicals
Electroplating Chemicals Market