

(S)-(+)-2-Amino-1-Propanol Market Size, Share, and Industry Trends Forecast 2026-2036
(S)-(+)-2-Amino-1-Propanol Market Insights
Asset-light toll manufacturing and contract synthesis partnerships is rewriting competitive entry dynamics for specialty amino alcohol producers. BASF SE leverages backward integration into propylene oxide feedstocks to control cost volatility across its chiral amine portfolio. Evonik Industries anchors its position through dedicated pharmaceutical-grade production lines that meet FDA and EMA purity requirements. Clariant competes by offering customized enantiomeric enrichment services for agrochemical clients seeking specific optical purity thresholds.
(S)-(+)-2-Amino-1-Propanol is a chiral amino alcohol with the molecular formula C3H9NO, possessing a specific optical rotation that distinguishes it from its racemic and enantiomeric counterparts, and it serves primarily as a building block for asymmetric synthesis in pharmaceutical manufacturing and as a functional additive in personal care formulations. The compound is produced through catalytic hydrogenation of amino acid precursors or via resolution of racemic mixtures using chiral auxiliaries. Pharmaceutical intermediates command the largest value share due to stringent purity premiums and multi-step qualification requirements, while surfactant applications in personal care products represent the fastest-growing segment as brands reformulate around milder amphoteric systems. Solvent-grade volumes remain mature with thin margins, whereas corrosion inhibitor formulations for water treatment concentrate margin pools through performance-based specifications.
EPA registration requirements for antimicrobial additives and REACH substance evaluation protocols in Europe shape product specifications and market access timelines for (S)-(+)-2-Amino-1-Propanol suppliers serving regulated end-uses. FDA cGMP standards for pharmaceutical intermediates and China's NMPA drug master file obligations create compliance moats that favor established producers with dedicated quality systems. India's CDSCO active pharmaceutical ingredient registration pathway and BIS chemical purity standards further fragment regulatory requirements across major demand centers. Stakeholders must monitor evolving pharmaceutical impurity profiling guidelines and biobased feedstock certification schemes that could redefine cost structures and qualification pathways for chiral amino alcohol supply chains.
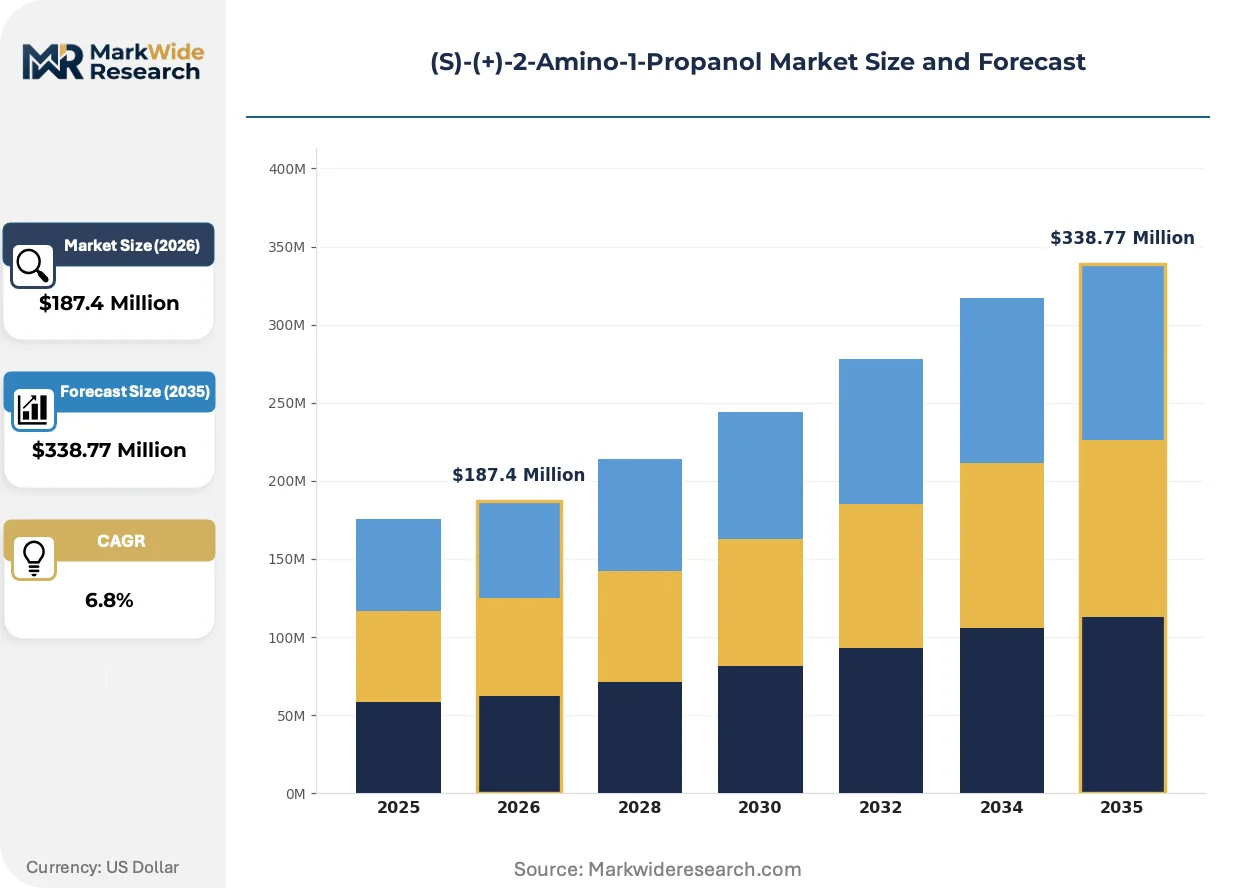
Market Dynamics
Pharmaceutical impurity profiling guidelines are tightening qualification timelines for chiral amino alcohol suppliers, forcing dedicated quality system investments that favor established producers with captive hydrogenation capacity and backward-integrated feedstock positions.
Growth Catalysts
- REACH substance evaluation protocols:European ECHA registration requirements for antimicrobial additives create compliance moats that filter out marginal suppliers and consolidate qualified vendor lists for personal care formulators.
- Amphoteric surfactant reformulation:Personal care brands are replacing traditional quaternary ammonium compounds with milder amino alcohol systems in rinse-off applications, expanding specification volumes for high-purity grades.
- India CDSCO API registration pathway:Domestic pharmaceutical manufacturing expansion under India's production-linked incentive scheme is generating localized demand for chiral intermediates with documented supply chain traceability.
Market Restraints
- Propylene oxide feedstock volatility:Crude oil price swings directly transmit to amino alcohol production economics, compressing margins for non-integrated manufacturers lacking captive alkylene oxide supply.
- China NMPA drug master file obligations:Foreign suppliers face extended documentation timelines and on-site inspection requirements that delay market entry for pharmaceutical-grade qualifications.
- Racemic mixture resolution limitations:Classical diastereomeric salt resolution methods generate substantial organic solvent waste streams, attracting environmental compliance costs under China's MEE discharge standards.
Strategic Opportunities
- Brazil ANVISA pharmaceutical registration:Latin American generic drug manufacturing expansion offers first-mover advantages for suppliers establishing local technical service presence ahead of qualification deadlines.
- Biobased feedstock certification:EU Green Deal sustainable chemistry mandates are creating premium pricing tiers for amino alcohols derived from fermentation-based propionic acid rather than petrochemical routes.
- Continuous flow hydrogenation:Convergence of fixed-bed catalytic reactors with real-time optical rotation monitoring enables on-demand enantiomeric enrichment, reducing inventory carrying costs for contract manufacturers.
Industry Challenges
- Chiral chromatography analyst shortage:Specialized HPLC method development expertise for enantiomeric purity verification commands salary premiums that inflate quality control department budgets.
- FDA cGMP facility certification timelines:Pharmaceutical intermediate suppliers face 18-24 month validation periods for dedicated production lines, delaying revenue recognition from qualified customer audits.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
(S)-(+)-2-Amino-1-Propanol Market Trends and Innovations
Biocatalytic transamination routes and continuous processing architectures are displacing batch hydrogenation as the dominant production paradigm, while regulatory data integrity requirements reshape documentation standards across pharmaceutical supply chains.
Asymmetric transfer hydrogenation using Noyori-type ruthenium catalysts is migrating from laboratory-scale synthesis to commercial production for (S)-(+)-2-Amino-1-Propanol manufacturing. Pharmaceutical contract manufacturers in Switzerland and Germany are adopting these systems to reduce noble metal loading and improve enantioselectivity beyond traditional Raney nickel approaches. The technology is compressing capital intensity for new market entrants by enabling smaller reactor footprints and shorter batch cycle times.
EU MDR medical device regulation and REACH authorization restrictions on CMR substances are forcing reformulation of corrosion inhibitors in water treatment applications where amino alcohols serve as neutralizing agents. Industrial chemical distributors must now maintain substance volume tracking and exposure scenario documentation that was previously exempt. Pharmaceutical intermediate suppliers with existing regulatory affairs infrastructure are cross-leveraging these capabilities into adjacent industrial segments.
Specification-driven spot purchasing is displacing annual framework agreements for solvent-grade amino alcohol volumes as water treatment compounders adopt just-in-time inventory models. Regional distributors in the US Gulf Coast and Rotterdam are consolidating warehousing positions to serve fragmented municipal utility accounts. The shift is most visible in North American cooling tower chemical markets where seasonal demand spikes reward flexible supply arrangements over committed offtake contracts.
(S)-(+)-2-Amino-1-Propanol Market Segmentation
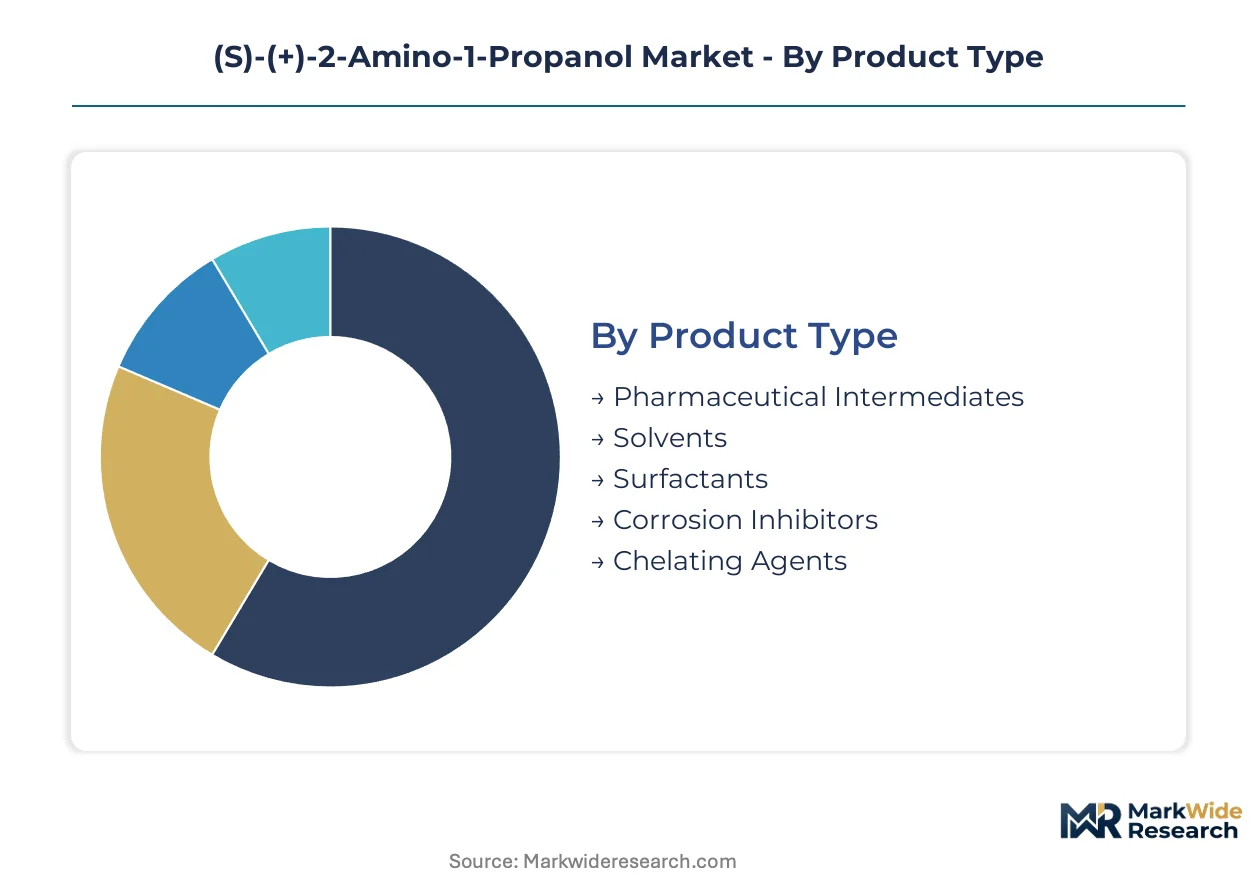
Chiral amino alcohol supply chains fragment across specification tiers that pharmaceutical, personal care, and industrial formulators cannot interchange. Segmentation discipline separates margin pools tied to FDA cGMP compliance from commodity volumes serving water treatment and coatings markets.
Product Type:
Use-case spectrum spans life-science purity premiums through industrial performance specifications.
- Pharmaceutical Intermediates:Enantiomeric purity exceeding 99.5% supports asymmetric synthesis of beta-blockers and antiviral APIs. CDSCO registration requirements in India and NMPA drug master file obligations in China concentrate demand among qualified suppliers with dedicated hydrogenation lines and chiral HPLC verification capabilities.
- Solvents:Technical-grade material serves as polar aprotic reaction media for peptide coupling and organometallic chemistry. Specifications emphasize moisture content and residual amine levels rather than optical rotation, compressing margins through substitutability with racemic amino alcohols.
- Surfactants:Amphoteric systems for mild rinse-off personal care formulations.
- Corrosion Inhibitors:Neutralizing agents for water treatment and metalworking fluids.
- Chelating Agents:Complexing functionality for industrial cleaning and electroplating baths.
Established volume favors pharmaceutical intermediates; emerging adoption favors surfactants.
Form:
Physical state determines logistics economics and formulation integration pathways across end-use segments.
- Liquid:Bulk tanker and drum distribution dominates pharmaceutical and coatings manufacturing where metered addition and homogeneous blending are required. REACH substance evaluation protocols for liquid-phase antimicrobial additives in Europe favor concentrated aqueous solutions over solid forms for personal care compounders seeking simplified formulation workflows.
- Powder:Free-flowing material enables precise dosing in agrochemical granulation and dry blend personal care products. Dust exposure controls and cGMP containment requirements inflate packaging costs for pharmaceutical-grade specifications.
- Granular:Reduced dust generation supports agricultural formulation and water treatment tablet production.
- Emulsion:Pre-dispersed systems for coatings and textile processing applications.
Distribution infrastructure favors liquid; specialty formulation integration favors powder.
Application:
Downstream demand concentrates where chiral functionality or amphoteric behavior commands specification premiums.
- Personal Care Products:Amphoteric surfactant reformulation replaces traditional quaternary ammonium compounds in shampoos and body washes. ECHA registration requirements for antimicrobial additives create compliance moats that filter marginal suppliers and consolidate qualified vendor lists for European formulators.
- Agrochemicals:Chiral building blocks for enantioenriched pesticide active ingredients.
- Water Treatment:Corrosion inhibition and pH buffering in cooling tower and boiler systems.
- Coatings:Crosslinking catalysts and pH adjustment for industrial and decorative paints.
- Textile Processing:Softening agents and dye leveling auxiliaries.
Regulatory complexity favors personal care; volume scale favors water treatment.
End User:
Customer capability and compliance infrastructure segment procurement behavior and contract structures.
- Chemical Manufacturers:Multi-step synthesis houses and contract development organizations purchasing pharmaceutical intermediates under multi-year qualification agreements. FDA cGMP facility certification timelines of 18-24 months for dedicated production lines lock in supplier relationships and create switching costs that established producers exploit.
- Cosmetics Producers:Brand owners and contract manufacturers reformulating around milder amino alcohol surfactant systems.
- Agriculture Firms:Pesticide formulators seeking enantiopure chiral auxiliaries for stereoselective synthesis.
- Coating Companies:Industrial and architectural paint manufacturers using amino alcohols as neutralizing agents and coalescing aids.
Qualification intensity favors chemical manufacturers; specification flexibility favors coating companies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical contract manufacturers in Switzerland and agrochemical formulators in India concentrate procurement of high-purity chiral amino alcohols, while personal care compounders in Germany and water treatment specialists in the United States drive specification-grade volume.
China
Domestic API manufacturing expansion under the NMPA drug master file system concentrates demand for pharmaceutical-grade (S)-(+)-2-Amino-1-Propanol in Jiangsu and Zhejiang provinces. MEE discharge standards for organic solvent waste from classical resolution processes are forcing producers toward catalytic hydrogenation routes. Shanghai-based contract manufacturers are installing dedicated chiral HPLC verification lines to serve export-qualified pharmaceutical intermediates.
Germany
REACH substance evaluation protocols for antimicrobial additives in personal care formulations are consolidating qualified vendor lists around established amino alcohol suppliers. ECHA registration requirements create compliance moats that filter marginal entrants from the European market. BASF SE in Ludwigshafen leverages backward integration into propylene oxide feedstocks to control cost volatility across its chiral amine portfolio.
India
CDSCO API registration pathways and production-linked incentive schemes for domestic pharmaceutical manufacturing are generating localized demand for chiral intermediates with documented supply chain traceability. Hyderabad and Ahmedabad clusters house contract development organizations qualifying multi-source amino alcohol suppliers for beta-blocker synthesis. BIS chemical purity standards further fragment procurement requirements against imported specifications.
United States
EPA registration requirements for antimicrobial additives in cooling tower water treatment concentrate specification volumes for corrosion inhibitor-grade amino alcohols. FDA cGMP standards for pharmaceutical intermediates lock in 18-24 month qualification timelines that favor established producers with dedicated quality systems. Gulf Coast chemical distributors are consolidating warehousing positions to serve fragmented municipal utility accounts through specification-driven spot purchasing.
Switzerland
Pharmaceutical contract manufacturers in Basel and Geneva are adopting asymmetric transfer hydrogenation using Noyori-type ruthenium catalysts for commercial-scale chiral amino alcohol production. Swissmedic oversight of active pharmaceutical ingredient quality systems creates qualification premiums for dedicated pharmaceutical-grade production lines. Domestic producers are compressing capital intensity through smaller reactor footprints and real-time optical rotation monitoring.
(S)-(+)-2-Amino-1-Propanol Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three distinct tiers. Integrated petrochemical conglomerates with captive alkylene oxide supply dominate bulk solvent-grade volumes, while dedicated pharmaceutical-grade specialists command purity premiums through FDA and EMA-qualified production lines. Custom synthesis houses and toll manufacturers occupy a fragmented middle tier serving agrochemical and personal care formulators with flexible batch sizes. Capacity expansion in Asia-Pacific manufacturing clusters and strategic partnerships for biobased feedstock certification represent the dominant competitive moves reshaping supply relationships.
Among German-headquartered diversified chemical conglomerates, BASF SE and Evonik Industries exemplify contrasting strategic archetypes. BASF SE represents the backward-integrated petrochemical model with control over propylene oxide feedstock economics, while Evonik Industries anchors the pharmaceutical-grade specialist position through dedicated production lines meeting regulatory purity requirements. Clariant occupies a position within the custom synthesis tier, offering enantiomeric enrichment services that serve agrochemical clients seeking specific optical purity thresholds without captive hydrogenation investment.
| Leading Market Players |
|---|
| BASF SE |
| Dow |
| Huntsman Corporation |
| Evonik Industries |
| Solvay |
| Mitsubishi Chemical Corporation |
| Arkema |
| Eastman Chemical Company |
| Clariant |
| Others |
Pricing and Supply Chain Analysis
Propylene oxide feedstock volatility functions as the primary risk vector determining both pricing tier spreads and supply chain configuration across the (S)-(+)-2-Amino-1-Propanol market. Crude oil price swings transmit directly to production economics, compressing margins for non-integrated manufacturers while rewarding backward-integrated producers with captive alkylene oxide supply and pricing power in pharmaceutical-grade segments.
Pricing Analysis
Cost-plus contracts with propylene oxide indexation dominate commercial arrangements for technical-grade volumes serving water treatment and coatings markets. Pharmaceutical intermediates command premium-mid-economy pricing differentiation based on enantiomeric purity thresholds and FDA cGMP certification status rather than feedstock pass-through alone. Pricing pressure stems from racemic mixture substitutability in solvent applications where optical rotation specifications are relaxed. Water treatment compounders exhibit highest price sensitivity due to specification-driven spot purchasing and seasonal demand spikes, while pharmaceutical contract manufacturers demonstrate lowest sensitivity given 18-24 month qualification lock-ins.
Supply Chain Analysis
Upstream propylene oxide availability anchors supply chain geography across China, Germany, and the United States where integrated petrochemical complexes concentrate capacity. Catalytic hydrogenation catalysts and chiral auxiliaries for resolution processes constitute critical input dependencies alongside the primary feedstock. Single-source vulnerability runs through Jiangsu and Zhejiang province clusters where NMPA-registered API manufacturers concentrate demand and MEE discharge standards constrain classical resolution capacity. Distribution runs through regional chemical distributors in the US Gulf Coast and Rotterdam serving fragmented municipal utility accounts through just-in-time warehousing positions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The (S)-(+)-2-Amino-1-Propanol market functions as a defensive-moat story where regulatory entrenchment creates structural advantages. FDA cGMP qualification timelines and NMPA drug master file obligations generate switching costs that protect incumbent positions across pharmaceutical supply chains.
For Market Incumbents: Insulate market position through captive hydrogenation capacity expansion in Zhejiang province and dedicated chiral HPLC verification lines serving export-qualified pharmaceutical intermediates. Biocatalytic transamination R&D investment counters emerging continuous flow hydrogenation entrants from Swiss contract manufacturers. CDSCO registration pathway navigation in Hyderabad and Ahmedabad clusters reinforces India market access against Chinese supply alternatives. For New Entrants and Emerging Players: Establish a beachhead in surfactant-grade amino alcohols for European personal care reformulation where REACH substance evaluation protocols filter marginal competitors and consolidate qualified vendor lists. Brazil ANVISA pharmaceutical registration offers white-space opportunity ahead of Latin American generic drug manufacturing expansion. Local technical service presence in São Paulo accelerates qualification timelines relative to distant Asian suppliers. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors pharmaceutical-grade specialists with existing FDA and EMA-qualified production lines. Long-term viability rests on regulatory affairs infrastructure cross-leveragable across pharmaceutical, personal care, and medical device segments under EU MDR and REACH authorization restrictions. Acquisition target archetype: mid-cap custom synthesis houses with chiral chromatography analyst teams and documented supply chain traceability systems. Signal to watch: biobased feedstock certification scheme adoption rates among European formulators seeking Green Deal compliance premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Propylene Oxide | BASF SE's Ludwigshafen complex demonstrates feedstock cost control across chiral amine portfolios. |
| Continuous Flow Hydrogenation Adoption | Swiss contract manufacturers compress capital intensity through Noyori-type ruthenium catalyst systems. |
| Biobased Feedstock Certification | EU Green Deal mandates create premium pricing tiers for fermentation-based propionic acid routes. |
| CDSCO Registration Pathway Investment | Hyderabad clusters generate localized demand under India's production-linked incentive scheme. |
| Chiral HPLC Verification Line Installation | Shanghai-based producers serve export-qualified pharmaceutical intermediates with dedicated quality systems. |
Research Methodology
Initial hypotheses were tested against primary input from pharmaceutical process chemists, personal care formulation scientists, agrochemical procurement managers, and water treatment chemical distributors and refined through secondary validation. Primary interviews explored hydrogenation route economics, enantiomeric purity verification workflows, and regulatory qualification timelines across FDA, EMA, NMPA, and CDSCO jurisdictions. Secondary sources included customs and trade flow databases, SEC 10-K filings from diversified chemical conglomerates, ECHA registration dossiers, and BIS chemical purity standards documentation. Bottom-up volume estimates from end-use consumption patterns were triangulated against top-down capacity assessments from regional manufacturing clusters.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, modeling consumption by pharmaceutical intermediate grade, surfactant specification, solvent technical grade, corrosion inhibitor formulation, and chelating agent application alongside regional production hub concentration. CAGRs were derived from segment-level volume trajectories weighted by purity premium differentials and qualification intensity barriers. Industry-specific forecast inputs incorporated REACH substance evaluation protocol timelines, NMPA drug master file approval velocities, and CDSCO API registration pathway completion rates.
Sensitivities concentrate around propylene oxide price volatility, MEE discharge standard enforcement intensity, and biobased feedstock certification scheme adoption rates. Forecasts reflect assumptions regarding sustained pharmaceutical manufacturing expansion in India and China, continued amphoteric surfactant reformulation in European personal care, and stable corrosion inhibitor specification volumes in North American water treatment. Cross-checking against ECHA registration volume data and NMPA drug master file submission statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.