
 Clear Envelopes and Mailing Supplies Market | 2026-2036
Clear Envelopes and Mailing Supplies Market Size, Share, and Industry Trends Forecast 2026-2036
Clear Envelopes and Mailing Supplies Market Outlook
ISO 9001 quality management certification is unwinding competitive access for smaller converters unable to sustain audit cycles. International Plastics leverages captive extrusion capacity across multiple North American facilities. PAC Worldwide sustains defense and aerospace qualification pathways that competitors struggle to replicate. JBM Packaging anchors its position through specialized short-run customization capabilities.
Clear envelopes and mailing supplies comprise transparent or semi-transparent protective enclosures manufactured from polyethylene, polypropylene, or cellulose-based films, designed for document visibility during transit and automated sorting compatibility. Polypropylene variants dominate commercial volumes due to superior tear resistance and moisture barrier performance versus standard polyethylene grades. Document folders command premium positioning within the product type taxonomy, while bio-based materials represent the fastest-expanding material category as brand owners face Scope 3 emissions accounting pressures. Custom sizes capture disproportionate margin pools compared to standardized A4 and DL formats, reflecting setup charges and die investment recovery.
FDA food-contact regulations govern mailers used in specialty food subscription channels, while EPA guidelines on recycled content thresholds shape procurement specifications for federal and municipal contracts. The EU Packaging and Packaging Waste Regulation imposes extended producer responsibility fees that alter cost structures for exporters serving European corporate accounts. Stakeholders must monitor evolving state-level plastic bag bans in the United States, as preemption battles between municipal ordinances and state legislation create compliance fragmentation that favors multi-jurisdiction operators with dedicated regulatory staff.
Market Dynamics
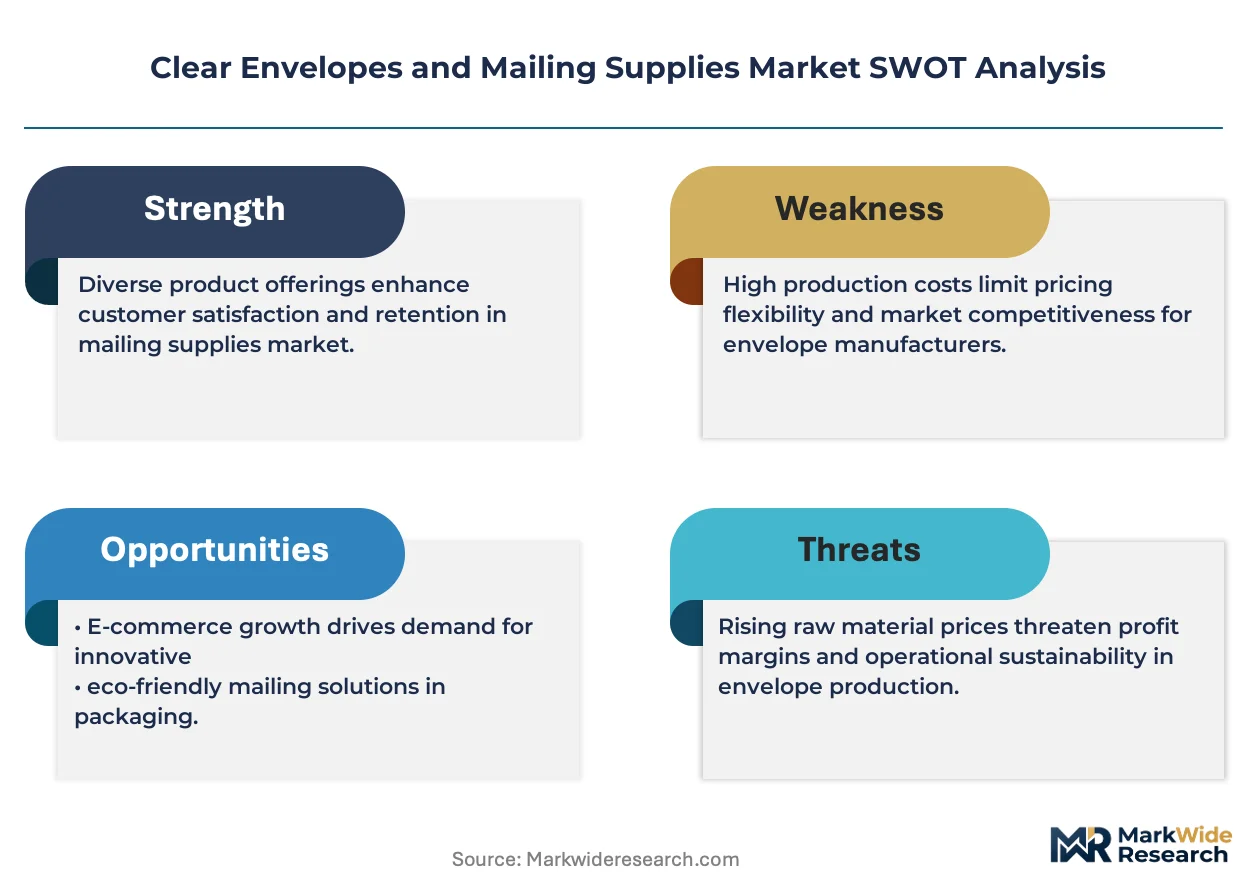
The EU Packaging and Packaging Waste Regulation is compressing margin structures for converters serving European corporate accounts, forcing material substitution investments and extended producer responsibility compliance systems that smaller competitors cannot absorb.
Growth Catalysts
- E-commerce fulfillment expansion:Tamper-evident mailing supplies are capturing volume from traditional opaque packaging as direct-to-consumer brands prioritize unboxing visibility and automated sortation compatibility.
- REACH material compliance:The EU's chemical registration framework is accelerating bio-based film adoption by penalizing petroleum-derived alternatives through carbon accounting mechanisms.
- Industrial mail-order networks:Germany's dense procurement infrastructure sustains concentrated demand for document folders and custom-size clear envelopes with short lead-time requirements.
Market Restraints
- Polypropylene feedstock volatility:Propylene monomer price swings transmit directly to film extrusion costs, compressing converter margins during supply shocks.
- ISO 9001 audit burden:Quality management certification cycles consume 15-20% of annual administrative resources for mid-tier converters.
- Cellulose film substitution:Transparent paper-based alternatives are capturing premium positioning in gift and subscription channels where tactile differentiation commands price premiums.
Strategic Opportunities
- Scope 3 emissions accounting:Brand owner pressure is creating first-mover advantage for converters with certified bio-based material supply chains and cradle-to-gate carbon transparency.
- Specialty food subscription channels:FDA food-contact compliant clear mailers represent underpenetrated white space as meal-kit and artisan food delivery segments expand.
- Short-run customization:Digital die-cutting and web-to-print workflows are enabling margin capture from SKU-proliferating e-commerce brands requiring batch sizes below 5,000 units.
Industry Challenges
- Regulatory fragmentation:Preemption battles between US state plastic bag bans and municipal ordinances require dedicated compliance staff to navigate overlapping jurisdictions.
- Extrusion equipment capex:Multi-layer barrier film lines demand capital commitments that strain balance sheets for sub-$50 million revenue converters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clear Envelopes and Mailing Supplies Market |
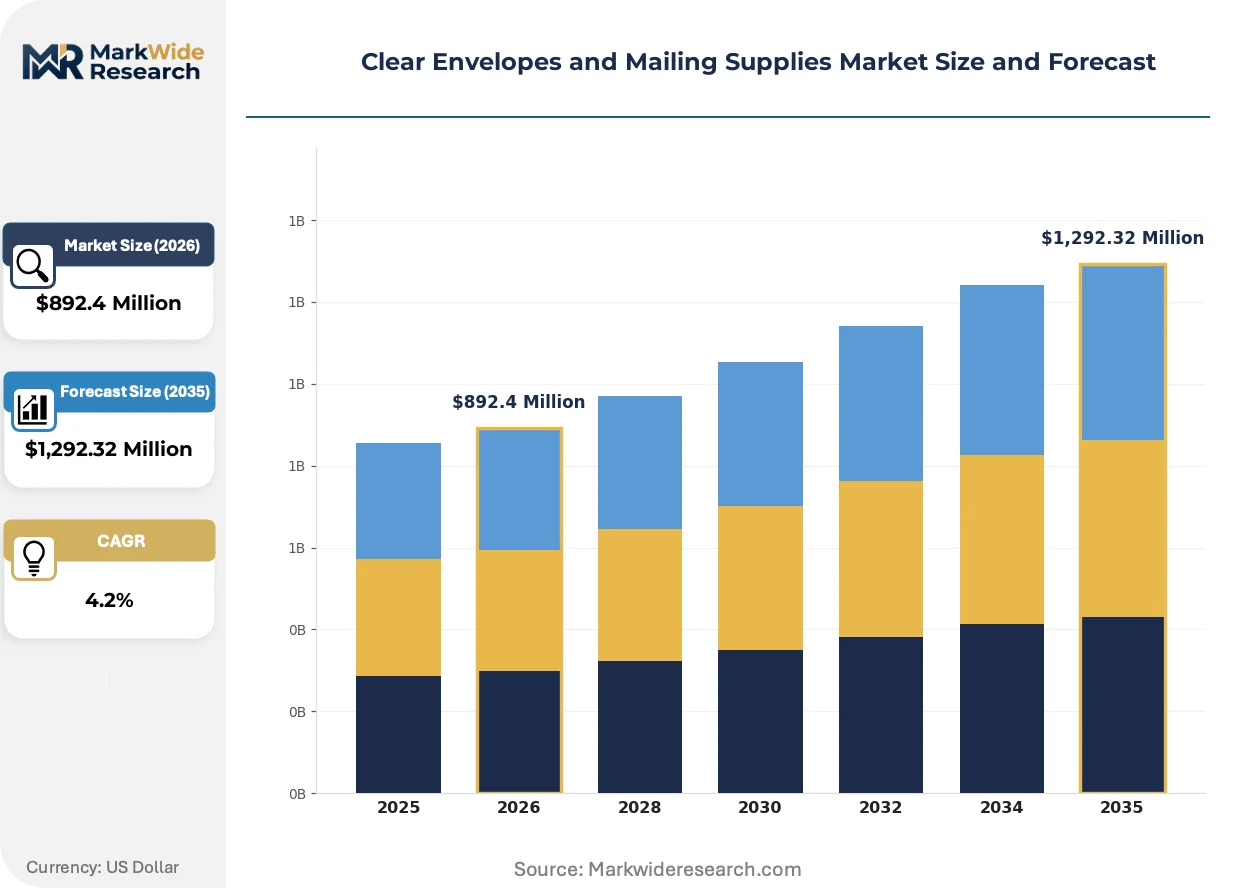
| Market Size in 2026 | $892.4 Million |
| Market Size in 2035 | $1,292.32 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clear Envelopes, Document Folders, Mailing Bags, Padded Envelopes Material: Plastic, Paper, Bio-based Materials, Polypropylene Size: A4, A5, DL, Custom Sizes End User: Retail, Corporations, Educational Institutions, Non-profits |
| Companies Covered | International Plastics, PAC Worldwide, JBM Packaging, APEX Packaging, Skyline Box and Packaging, Infekta Packaging International, Western States Envelopes & Label, NELMAR Security Packaging Systems, POLYPAK PACKAGING, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clear Envelopes and Mailing Supplies Market Strategic Shifts
Material science advances and regulatory chemistry restrictions are simultaneously enabling and forcing substitution patterns across the clear envelope value chain. Converters must now synchronize R&D roadmaps with compliance timelines that outpace traditional product development cycles.
Multi-layer coextruded polypropylene films with embedded tamper-evident tear tapes are supplanting standard single-ply polyethylene grades in high-value document and pharmaceutical distribution channels. Financial services and legal sector procurement teams are mandating these structures for client correspondence. The technology is compressing addressable volume for commodity converters lacking coextrusion capability.
REACH Annex XVII restrictions on persistent organic pollutants are tightening specifications for plastic additives used in mailing films. The regulation is forcing reformulation of slip agents and anti-static compounds across European supply chains. Converters serving German industrial mail-order accounts are accelerating migration to bio-based additive packages to preempt compliance deadlines.
Direct procurement from converters via B2B platforms is displacing traditional distributor relationships among mid-size e-commerce fulfillment operators. These buyers are consolidating specifications across multiple SKUs to capture volume discounts previously available only to enterprise accounts. The pattern is most visible in US West Coast technology and apparel subscription segments where procurement teams prioritize supply chain transparency over distributor service bundling.
Clear Envelopes and Mailing Supplies Market Segmentation
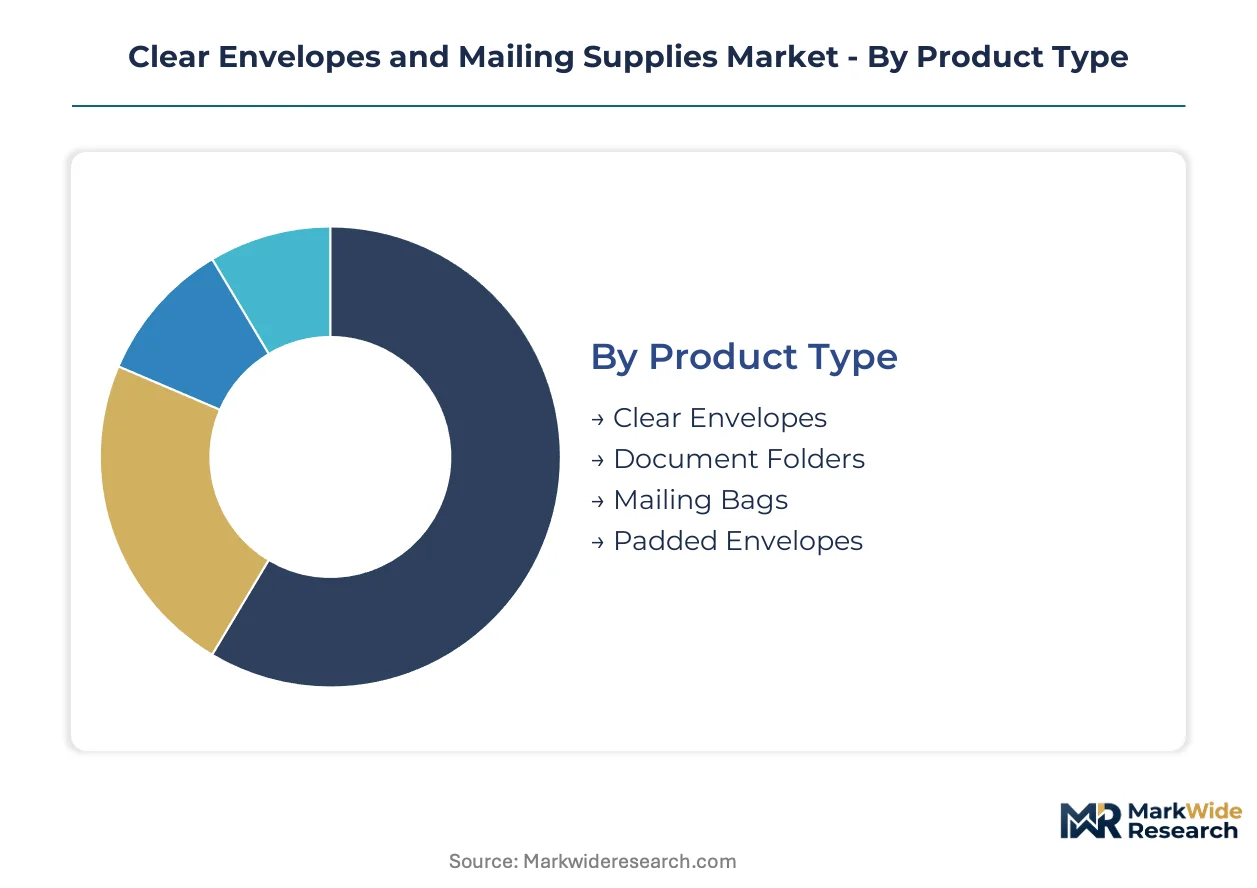
Segmentation in clear envelopes and mailing supplies reveals how regulatory pressure and end-use specialization fragment procurement patterns. Buyers sort across material compliance tiers, dimensional requirements, and visibility needs that vary sharply between industrial mail-order networks and subscription commerce channels.
Product Type:
REACH Annex XVII restrictions on persistent organic pollutants differentiate which structures qualify for European corporate accounts versus domestic US fulfillment operations.
- Clear Envelopes:Polyethylene and polypropylene films with transparent windows for automated sortation compatibility. German industrial mail-order distributors specify these for invoice and statement distribution where barcode visibility reduces handling errors.
- Document Folders:Rigid or semi-rigid transparent sleeves with reinforced edges for legal and financial document protection. Premium positioning reflects FDA food-contact compliance requirements when used in specialty food subscription inserts.
- Mailing Bags:Lightweight polyethylene pouches for soft goods and apparel fulfillment. E-commerce brands in California and New York prioritize these for weight-based shipping cost optimization.
- Padded Envelopes:Bubble-lined or foam-padded transparent structures for fragile item protection. Electronics and pharmaceutical distributors specify multi-layer coextruded variants with tamper-evident tear tapes.
Clear Envelopes handle the majority of throughput; Document Folders are expanding most quickly on share as compliance requirements tighten for client correspondence.
Material:
Cost tier stratification separates commodity converters from certified bio-based suppliers serving Scope 3-conscious brand owners.
- Plastic:Standard polyethylene grades for high-volume, low-specification applications. Price volatility in propylene monomer transmits directly to converter margins during supply shocks.
- Paper:Cellulose-based transparent alternatives capturing premium positioning in gift and subscription channels. Tactile differentiation commands price premiums over synthetic films in direct-to-consumer unboxing experiences.
- Bio-based Materials:Certified compostable films derived from corn starch or sugarcane feedstocks. The fastest-expanding category as EU Packaging and Packaging Waste Regulation extended producer responsibility fees penalize petroleum-derived alternatives.
- Polypropylene:Superior tear resistance and moisture barrier performance versus polyethylene. Dominates commercial volumes in German procurement networks with short lead-time requirements for custom specifications.
Polypropylene captures the largest volume position; Bio-based Materials are climbing the fastest as carbon accounting mechanisms mature.
Size:
Application-specific dimensional requirements determine whether converters amortize die investments across standardized runs or capture margin from setup charges.
- A4:Standard letter-size transparent enclosures for document and invoice distribution. European corporate procurement teams consolidate specifications around this format to capture volume discounts.
- DL:Compact envelope format for machine-inserted direct mail campaigns. Financial services sector procurement specifies DL for statement and notice distribution at reduced postage weights.
- A5:Mid-size format for marketing collateral and smaller document sets. Educational institutions in Germany specify A5 for transcript and certificate mailing.
- Custom Sizes:Non-standard dimensions requiring dedicated die investment and setup charges. SKU-proliferating e-commerce brands require batch sizes below 5,000 units, enabling margin capture from digital die-cutting workflows.
A4 handles the majority of throughput; Custom Sizes are gaining share fastest as direct-to-consumer brands prioritize dimensional optimization for product-specific unboxing.
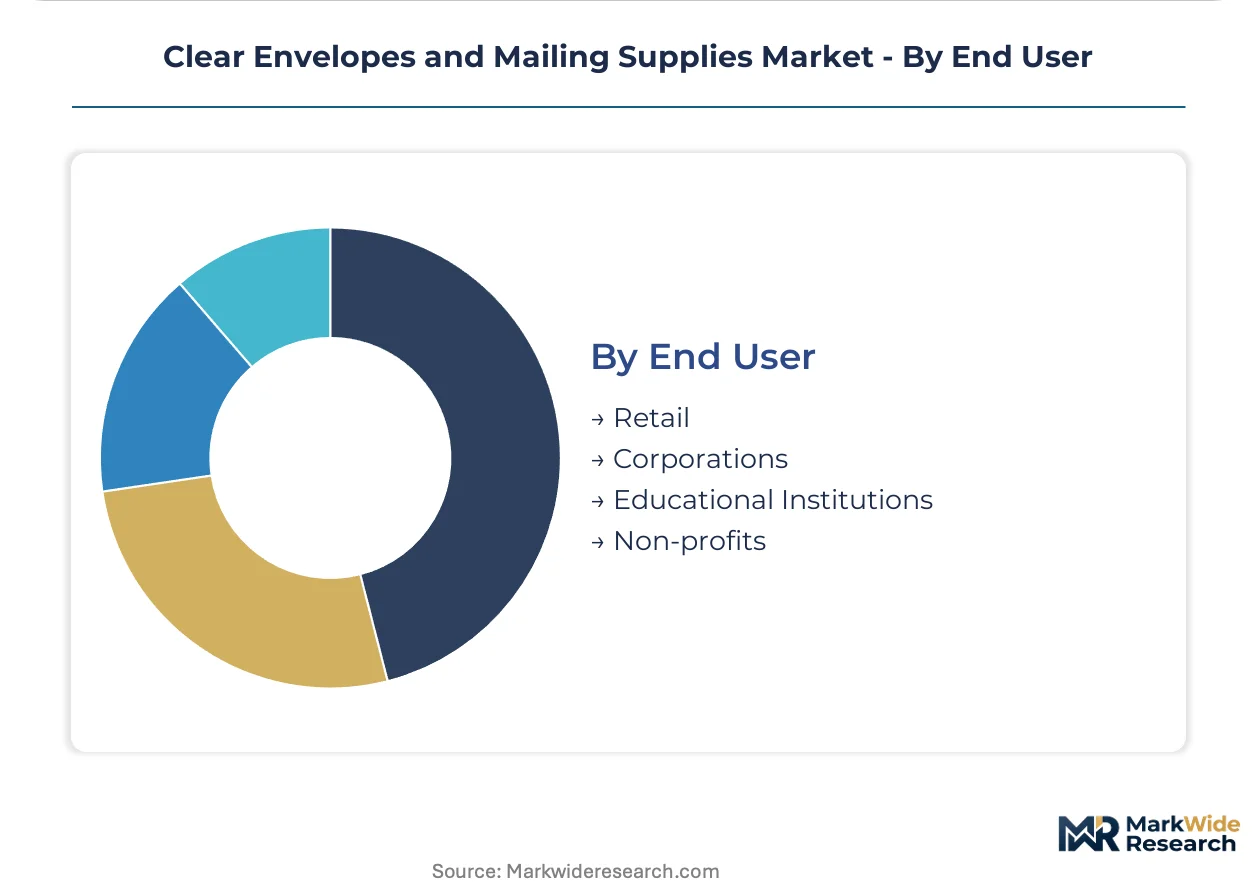
End User:
Customer type determines whether procurement prioritizes regulatory documentation, cost minimization, or brand experience differentiation.
- Corporations:Industrial mail-order networks and financial services procurement teams mandating tamper-evident structures for client correspondence. ISO 9001 certification requirements filter supplier pools.
- Retail:Brick-and-mortar and omnichannel retailers specifying clear envelopes for gift card and loyalty program distribution. Seasonal volume spikes strain converter capacity planning.
- Educational Institutions:Universities and certification bodies requiring document folders for transcript and diploma protection. German academic procurement networks sustain concentrated demand for archival-grade materials.
- Non-profits:Donor acknowledgment and fundraising campaign distribution with tight budget constraints. These buyers consolidate specifications across multiple SKUs to capture volume discounts previously available only to enterprise accounts.
Corporations handle the majority of throughput; Retail is expanding most quickly on share as subscription commerce channels proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial mail-order networks and e-commerce fulfillment operators concentrate procurement volumes in specific national markets where regulatory frameworks and logistics infrastructure align. Buyer archetypes sort across German industrial distributors, US subscription commerce platforms, and Asian manufacturing export corridors.
Germany
Dense industrial mail-order distribution networks sustain concentrated demand for custom-size clear envelopes with short lead-time requirements. The EU Packaging and Packaging Waste Regulation imposes extended producer responsibility fees that alter cost structures for converters serving corporate accounts. The Rhine-Ruhr metropolitan region anchors procurement volumes for document folders and tamper-evident mailing supplies.
United States
E-commerce fulfillment operators on the West Coast prioritize weight-based shipping cost optimization through lightweight polyethylene mailing bags. FDA food-contact regulations govern clear mailers used in specialty food subscription channels. California and New York procurement teams drive specification consolidation for automated sortation compatibility.
China
Export-oriented manufacturing clusters generate demand for protective transparent enclosures in cross-border e-commerce fulfillment. The country's dual carbon goals accelerate scrutiny of petroleum-derived film supply chains serving European brand owners. The Yangtze River Delta concentrates converter capacity for polypropylene film extrusion.
United Kingdom
Financial services procurement teams mandate tamper-evident structures for client correspondence and statement distribution. REACH material compliance requirements filter supplier pools for converters serving EU-UK trade corridors. London-based industrial distributors consolidate specifications around DL format envelopes for machine-inserted direct mail.
India
Educational institutions and certification bodies drive demand for document folders in transcript and diploma protection. The BIS quality certification framework shapes procurement specifications for archival-grade materials. Maharashtra and Gujarat host emerging converter capacity serving domestic e-commerce fulfillment growth.
Clear Envelopes and Mailing Supplies Market Competitive Environment
Player mix skews toward mid-tier converters with specialized extrusion or customization capabilities rather than integrated multinational packaging conglomerates. The vendor base separates into three strategic tiers: captive extrusion specialists serving high-volume industrial accounts, short-run customization shops capturing SKU-proliferating e-commerce brands, and defense-aerospace qualified suppliers with compliance pathway moats. Competitive moves center on material substitution investments for bio-based film certification and digital die-cutting workflow deployment for batch sizes below 5,000 units.
Within the captive extrusion tier, International Plastics and POLYPAK PACKAGING represent scale-driven positioning through multi-facility North American footprints. PAC Worldwide occupies a defense-aerospace qualification niche that competitors struggle to replicate. JBM Packaging anchors the short-run customization vector through specialized capabilities for e-commerce brands requiring dimensional optimization.
| Leading Market Players |
|---|
| International Plastics |
| PAC Worldwide |
| JBM Packaging |
| APEX Packaging |
| Skyline Box and Packaging |
| Infekta Packaging International |
| Western States Envelopes & Label |
| NELMAR Security Packaging Systems |
| POLYPAK PACKAGING |
| Others |
Value Chain & Pricing Dynamics
Bio-based polypropylene substitution for petroleum-derived polyethylene is simultaneously shifting converter sourcing toward German and Chinese extrusion hubs and compressing margin structures as extended producer responsibility fees alter landed cost economics for EU-bound shipments.
Pricing Analysis
Cost-plus contracts indexed to propylene monomer spot pricing dominate procurement between German industrial mail-order distributors and captive extrusion specialists. Price differentiation rests on ISO 9001 certification tier and customization level, with certified bio-based material supply chains commanding premiums over commodity grades. Pricing pressure stems from REACH Annex XVII compliance investments that smaller converters cannot amortize across volume. Mid-tier e-commerce fulfillment operators exhibit highest price sensitivity, while defense-aerospace qualified suppliers face inelastic demand from financial services procurement teams.
Supply Chain Analysis
Just-in-time inventory strategies prevail among West Coast e-commerce fulfillment operators, while German industrial distributors maintain strategic stockpiles of custom-size clear envelopes to meet short lead-time requirements. Extrusion capacity concentrates in China, Germany, and the United States, with polypropylene resin supply anchored in Gulf Coast petrochemical corridors and Yangtze River Delta manufacturing clusters. Raw material dependencies include propylene monomer, corn starch feedstocks for bio-based films, and specialized slip agents for automated sortation compatibility. Single-source vulnerability runs through concentrated polypropylene resin supply. Distribution feeds from converter direct sales via B2B platforms displacing traditional distributor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Direct procurement platforms are transforming this market toward ecosystem economics where interoperability between converter ERP systems and buyer inventory management platforms determines supplier stickiness.
For Market Incumbents: Compound certification moats by accelerating FDA food-contact pathway investments ahead of specialty food subscription channel expansion. Deepen backward integration into bio-based resin supply through offtake agreements with corn starch processors to defend against cellulose film substitution threats. Extend digital die-cutting workflows to capture SKU-proliferating e-commerce brands requiring batch sizes below 5,000 units. For New Entrants and Emerging Players: Differentiate on cradle-to-gate carbon transparency by building certified bio-based material supply chains ahead of Scope 3 accounting mandates. Target underpenetrated specialty food subscription channels where FDA compliance requirements filter incumbent supplier pools. Pursue white-label converter partnerships with West Coast technology subscription brands prioritizing supply chain visibility over distributor service bundling. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors mid-tier converters with captive extrusion capability and regulatory compliance infrastructure. Long-term viability hinges on material substitution investments outpacing regulatory timelines. Acquisition targets should demonstrate multi-jurisdiction regulatory staff and bio-based certification pathways. Watch for propylene monomer price volatility spikes as inflection indicators that compress commodity converter margins and accelerate consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-based Resin Supply | Corn starch offtake agreements secure feedstock for EU Packaging and Packaging Waste Regulation compliance. |
| Digital Die-cutting Workflow Deployment | Web-to-print capabilities capture margin from SKU-proliferating e-commerce brands requiring sub-5,000 unit batches. |
| FDA Food-contact Certification Investment | Specialty food subscription channel penetration requires compliance pathways that filter commodity competitors. |
| Multi-jurisdiction Regulatory Staff Expansion | Preemption battles between US state plastic bag bans favor operators with dedicated compliance infrastructure. |
| Direct B2B Platform Procurement Integration | ERP interoperability with buyer inventory systems displaces traditional distributor relationships among mid-size operators. |
Study Parameters
A standing panel of converter operations directors, industrial mail-order procurement leads, e-commerce fulfillment supply chain managers, and regulatory compliance officers provided ongoing calibration throughout the study. Primary fieldwork combined structured interviews with extrusion specialists and secondary validation through customs trade data, EPA recycled content threshold filings, and EU Packaging and Packaging Waste Regulation implementation guidance. Bottom-up volume modeling across material grades and top-down market sizing triangulated through propylene monomer consumption patterns anchored the analysis.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including product type, material compliance tier, dimensional format, and end-user procurement archetype. CAGRs derived from regression analysis of historical price-volume relationships and forward-looking regulatory compliance cost trajectories. Industry-specific inputs included REACH Annex XVII additive reformulation timelines and FDA food-contact petition approval patterns.
Material uncertainties — propylene monomer supply shocks, REACH restriction scope expansions, and state-level plastic bag ban preemption rulings — sit outside the modeled envelope. Forecasts reflect assumptions regarding regulatory implementation pacing and bio-based material cost parity achievement. Revision becomes warranted when EU extended producer responsibility fee structures cross thresholds that alter exporter cost competitiveness.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Foam Cups Market
Paper & Paperboard Packaging
Paper Waste Strippers Market
Paper & Paperboard Packaging
Schrenz Paper Market
Paper & Paperboard Packaging
Mailer Box Market
Paper & Paperboard Packaging
Medical Packaging Paper Market
Paper & Paperboard Packaging
Wall Mounted Paper Napkin Dispensers Market
Paper & Paperboard Packaging
Global Cooking and Baking Papers Market
Paper & Paperboard Packaging
GCC Paper Bags Market
Paper & Paperboard Packaging
Secondary Paper and Paperboard Luxury Packaging Market
Paper & Paperboard Packaging
Impregnated Paper Market
Paper & Paperboard Packaging
Paper and Paperboard Trays Market
Paper & Paperboard Packaging
Composite Paper Cans Market
Paper & Paperboard Packaging
Polycoated Paper Packaging Market
Paper & Paperboard Packaging
Sublimation Paper Market
Paper & Paperboard Packaging
Corrugated Boxes Market
Paper & Paperboard Packaging
Postal Tubes Market