
 Middle East and Africa Liver Cancer Diagnostics Market | 2026-2036
Middle East and Africa Liver Cancer Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Liver Cancer Diagnostics Market Foresight
CE-IVDR compliance tier is rotating toward the top of procurement criteria across Gulf health systems. Siemens Healthineers leverages its imaging installed base to sustain service contract renewals in Saudi Arabia's largest hospital networks. F. Hoffmann-La Roche Ltd anchors its position through centralized laboratory partnerships in the UAE. Thermo Fisher Scientific Inc. competes on molecular workflow integration for high-throughput screening programs.
Liver cancer diagnostics encompasses imaging modalities, serological biomarker assays, nucleic acid amplification techniques, and tissue sampling procedures designed to detect hepatocellular carcinoma at stages amenable to curative intervention. CT protocols with triphasic contrast enhancement remain the reference standard for lesion characterization, while MRI with hepatobiliary-specific contrast agents improves sensitivity for sub-centimeter nodules in cirrhotic livers. Imaging modalities command the largest revenue share due to capital equipment lock-in and radiologist dependency, though biomarker segments show the fastest expansion as liquid biopsy platforms mature and price points fall toward public-sector affordability. End-user concentration tilts heavily toward hospitals, where multidisciplinary tumor boards coordinate diagnostic and therapeutic decisions under single governance structures.
South Africa's Health Products Regulatory Authority, Saudi Food and Drug Authority, and Egypt's Drug Authority each enforce distinct registration pathways for in vitro diagnostics, creating fragmented market access conditions that favor multinationals with dedicated regulatory affairs teams. CE marking under the EU In Vitro Diagnostic Regulation serves as a de facto quality passport for Gulf procurement tenders, while national preference policies in North Africa protect local distributors. Stakeholders must monitor harmonization initiatives between the African Medicines Agency and Gulf Cooperation Council standardization bodies to anticipate future convergence or continued divergence in approval requirements.
Market Dynamics
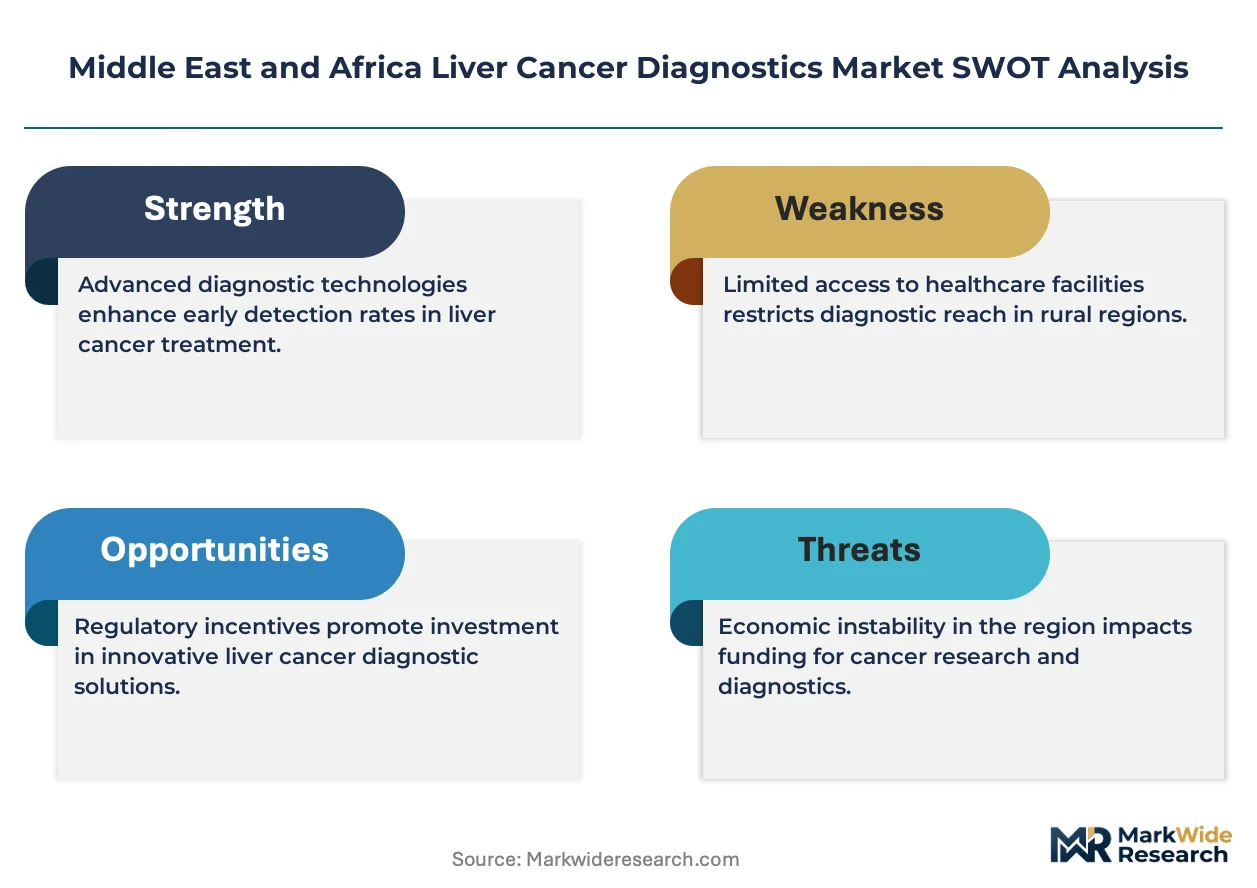
The Middle East and Africa Liver Cancer Diagnostics Market pivots on the tension between Egypt's government-led hepatitis C elimination infrastructure and the fragmented regulatory landscapes governing in vitro diagnostic entry across Gulf and sub-Saharan jurisdictions.
Growth Catalysts
- Egypt's Hepatitis C Surveillance Architecture:Mass screening programs have generated sustained demand for longitudinal liver monitoring among seropositive cohorts, creating predictable diagnostic volumes for hospital-based oncology departments.
- CE-IVDR Procurement Mandates:Gulf health systems now embed EU In Vitro Diagnostic Regulation compliance tiers into tender evaluations, elevating quality thresholds and filtering lower-grade competitors from public hospital supply chains.
- Liquid Biopsy Platform Maturation:Circulating tumor DNA assays are approaching cost structures compatible with public-sector reimbursement in South Africa and Morocco, expanding biomarker accessibility beyond private oncology networks.
Market Restraints
- Capital Equipment Lock-In:CT and MRI installed bases in Saudi Arabia's hospital networks create switching costs that slow adoption of competing imaging modalities despite superior sensitivity profiles.
- Regulatory Pathway Fragmentation:Divergent registration requirements across South Africa's Health Products Regulatory Authority, Saudi Food and Drug Authority, and Egypt's Drug Authority force multinationals to maintain redundant compliance infrastructures.
- Radiologist Dependency:Triphasic contrast-enhanced CT interpretation requires specialized hepatobiliary expertise concentrated in urban tertiary centers, constraining diagnostic throughput in peripheral facilities.
Strategic Opportunities
- North African Biomarker Localization:Algeria and Tunisia present underpenetrated markets where centralized laboratory partnerships could replicate the UAE hub model for molecular workflow integration.
- Telepathology Networks:Digital slide-sharing platforms connecting rural Egyptian clinics to Cairo-based tumor boards address the geographic maldistribution of diagnostic expertise without capital relocation.
- Harmonization Prepositioning:Early alignment with African Medicines Agency technical guidelines positions suppliers for streamlined market access as regional regulatory convergence materializes.
Industry Challenges
- Multidisciplinary Coordination Complexity:Tumor board governance structures spanning radiology, pathology, and oncology departments create decision-cycle friction that delays diagnostic closure.
- IVDR Transition Timeline Compression:Legacy CE-marked assays face recertification deadlines under the 2022 regulation, straining notified body capacity and risking supply interruptions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Liver Cancer Diagnostics Market |
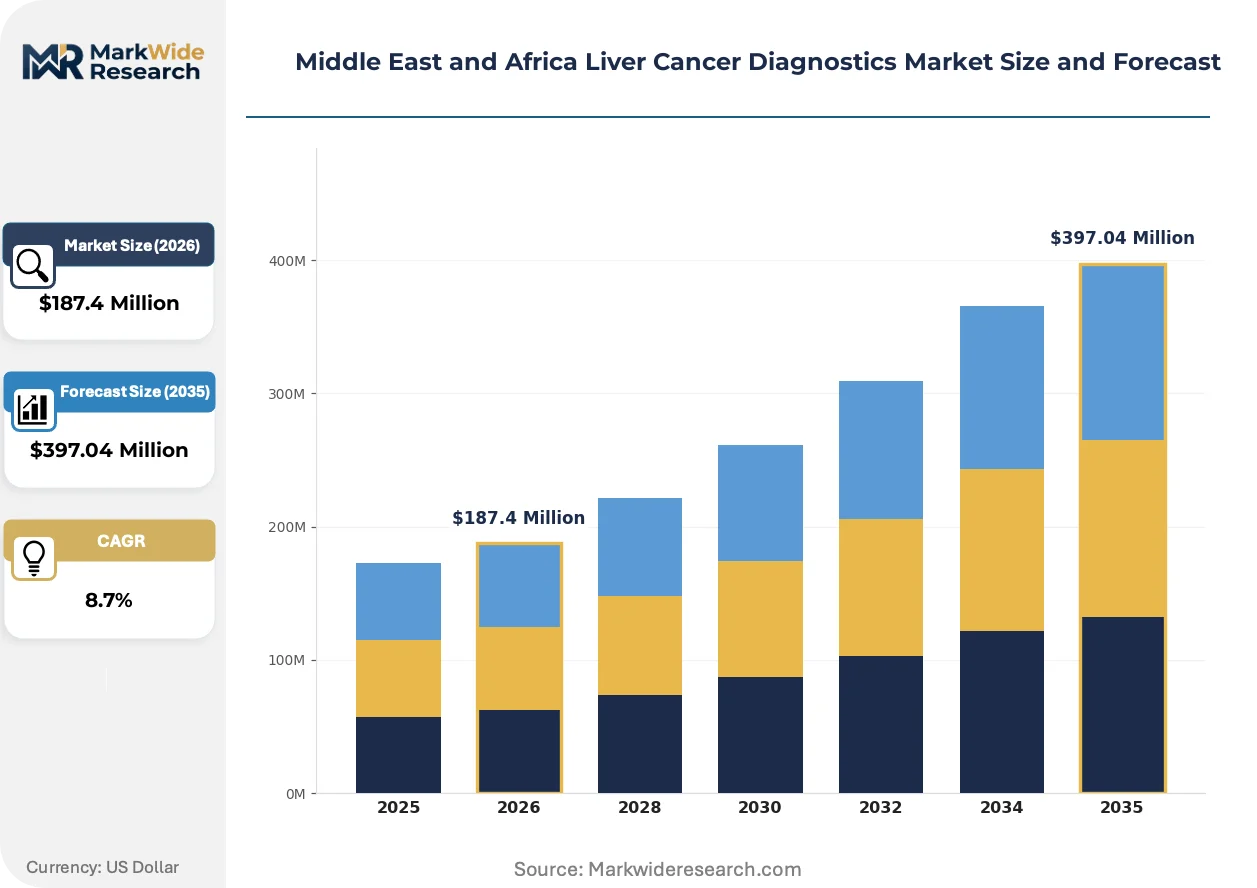
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Imaging, Biomarkers, PCR, Endoscopy Technology: CT Scan, MRI, Ultrasound, Laparoscopy End User: Hospitals, Diagnostic Centers, Research Labs, Clinics Distribution Channel: Direct Sales, Distributors, Online Sales, Retail |
| Companies Covered | Siemens Healthineers, F. Hoffmann-La Roche Ltd, Koninklijke Philips N.V., Thermo Fisher Scientific Inc., QIAGEN N.V., Illumina, Inc., Becton, Dickinson & Company, FUJIFILM Corporation, Sysmex Corporation, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Liver Cancer Diagnostics Market Shifts & Advancements
Diagnostic workflows across the Middle East and Africa are compressing toward non-invasive staging protocols, with biomarker panels and advanced imaging converging to reduce reliance on tissue sampling in cirrhotic patients.
MRI with hepatobiliary-specific contrast agents is supplanting multiphasic CT as the reference standard for sub-centimeter nodule characterization in Saudi Arabia's largest hospital networks. Hepatologists in Dubai's tertiary centers have accelerated adoption curves by twelve to eighteen months relative to public-sector facilities. The modality shift is compressing radiation exposure concerns while elevating radiologist training requirements as a procurement criterion.
South Africa's Health Products Regulatory Authority has tightened in vitro diagnostic registration requirements to accelerate quality upgrades across the national laboratory network. The policy industrial consequence is a filtering effect that favors suppliers with dedicated regulatory affairs teams capable of navigating extended dossier review cycles. Molecular assay manufacturers are responding by pre-submission engagement with the regulator's technical committees to anticipate evidentiary thresholds.
Service contract unbundling is reshaping how Saudi hospital networks acquire imaging maintenance and biomarker platform support. Procurement officers in Riyadh's Ministry of Health-affiliated facilities now separate equipment purchase from multi-year service agreements, enabling competitive tendering for technical support. The disintermediation is most visible in the Kingdom's largest oncology centers, where third-party engineering firms now compete against OEM service divisions for contrast injector and MRI coil maintenance contracts.
Middle East and Africa Liver Cancer Diagnostics Market Segmentation
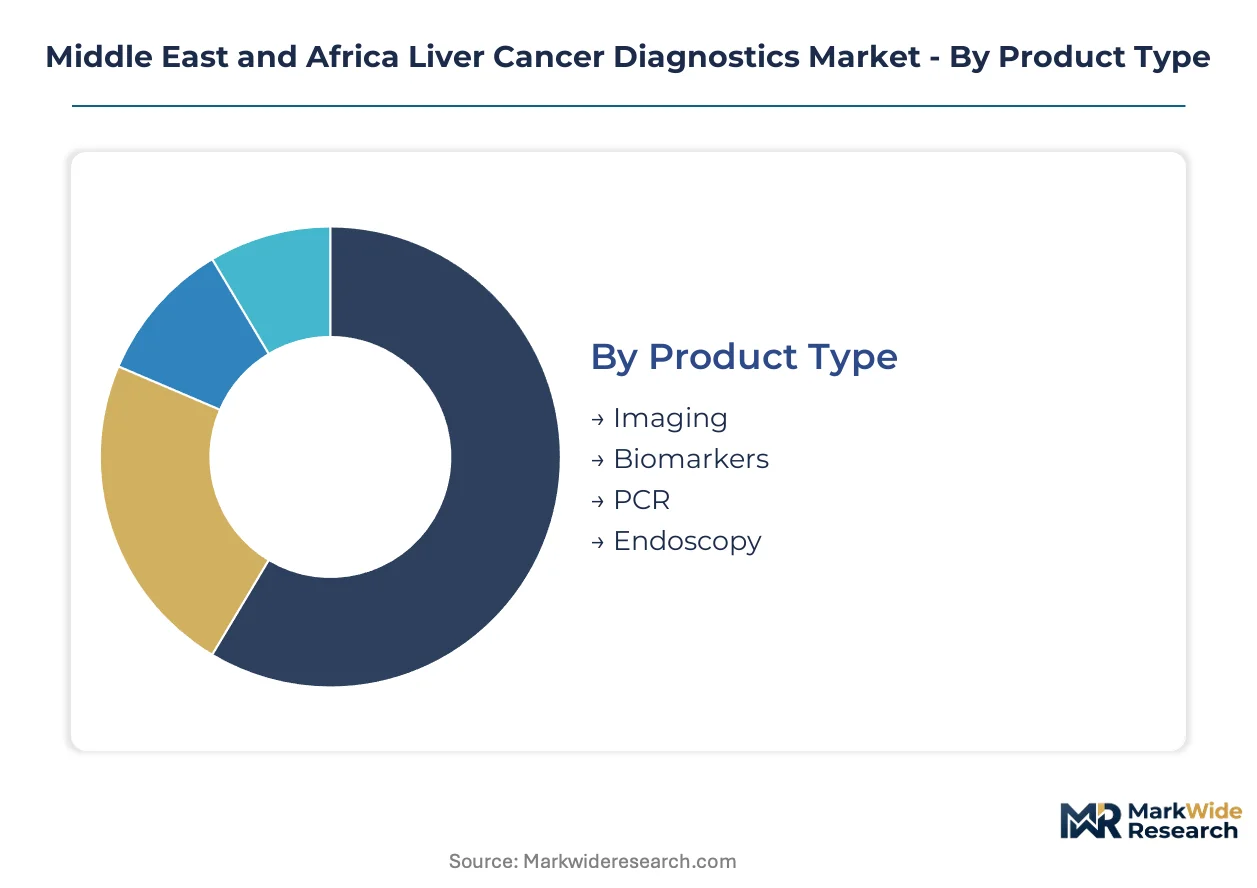
Diagnostic modality selection in Middle East and Africa liver cancer care follows divergent procurement logics across public hospital networks and private oncology chains. Segment boundaries blur as multimodal staging protocols integrate imaging, molecular testing, and tissue sampling into unified clinical pathways.
Product Type:
Margin pools concentrate in imaging equipment service contracts and high-throughput biomarker platforms, while commoditized endoscopy accessories compress profitability.
- Imaging:Triphasic CT and hepatobiliary MRI systems anchor diagnostic workflows through capital equipment lock-in and radiologist dependency. Saudi Arabia's Ministry of Health-affiliated hospitals sustain Siemens Healthineers service renewals despite superior sensitivity profiles from competing modalities.
- Biomarkers:Circulating tumor DNA assays and AFP-L3 isoform testing are approaching public-sector reimbursement thresholds in South Africa and Morocco. Egypt's hepatitis C elimination infrastructure generates predictable longitudinal monitoring volumes for serological panels.
- PCR:Nucleic acid amplification supports viral load quantification in hepatitis-related cirrhosis progression monitoring across Egyptian central laboratories.
- Endoscopy:Tissue sampling procedures retain role in indeterminate lesion characterization, though non-invasive staging protocols reduce procedural frequency in Dubai's tertiary hepatology centers.
Imaging holds installed capacity. Biomarkers is rotating up the share rankings.
Technology:
Technology adoption curves separate by patient volume tier, with high-throughput centers in Gulf states leading modality transitions by twelve to eighteen months.
- CT Scan:Multiphasic contrast-enhanced protocols remain reference standard for lesion characterization despite radiation exposure concerns. Procurement concentrates in Egypt's government hospital networks where equipment amortization cycles extend replacement timelines.
- MRI:Hepatobiliary-specific contrast agents improve sub-centimeter nodule detection in cirrhotic livers. Adoption accelerates in Saudi Arabia's largest hospital networks where hepatologist training investments justify modality premiums.
- Ultrasound:Surveillance screening for at-risk populations relies on portable systems in peripheral Egyptian clinics with limited CT access.
- Laparoscopy:Diagnostic staging retains niche role in surgical planning for resectable lesions across South Africa's academic medical centers.
CT Scan maintains procedural dominance. MRI is climbing the fastest among staging modalities.
End User:
Customer concentration tilts toward integrated delivery networks where multidisciplinary tumor boards consolidate purchasing authority.
- Hospitals:Tertiary oncology departments in Cairo, Riyadh, and Johannesburg coordinate diagnostic and therapeutic decisions under single governance structures. Procurement officers bundle imaging, pathology, and molecular testing contracts to extract volume discounts.
- Diagnostic Centers:Centralized laboratory partnerships in the UAE hub model integrate molecular workflow platforms for high-throughput screening programs.
- Research Labs:Academic medical centers in South Africa pilot liquid biopsy validation studies under Health Products Regulatory Authority oversight.
- Clinics:Peripheral Egyptian facilities connect to Cairo-based tumor boards through telepathology networks addressing geographic maldistribution of hepatobiliary expertise.
Hospitals command procurement volume. Diagnostic Centers are gaining share fastest as laboratory outsourcing expands.
Distribution Channel:
Channel structure reflects equipment-versus-consumable splits, with capital sales direct and reagent flows intermediated.
- Direct Sales:Imaging system manufacturers maintain field engineering teams for installation and training across Saudi Arabia's hospital networks.
- Distributors:Local partners navigate Egypt's Drug Authority registration pathways and North African national preference policies protecting domestic intermediaries.
- Online Sales:Reagent procurement platforms penetrate South African private laboratory networks with streamlined reorder workflows.
- Retail:Point-of-care testing consumables reach peripheral clinics through pharmaceutical wholesale channels in Morocco and Tunisia.
Direct Sales retains equipment dominance. Distributors are rotating up the share rankings as biomarker localization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Diagnostic infrastructure concentrates in Gulf Cooperation Council health systems and Egypt's hepatitis C elimination network, while sub-Saharan markets rely on academic medical centers for specialized hepatobiliary expertise. Procurement patterns diverge between CE-IVDR-aligned tenders in Saudi Arabia and UAE versus national preference policies protecting Egyptian and North African distributors. Service contract unbundling in Riyadh and Cairo is compressing OEM maintenance margins.
Saudi Arabia
Massive hospital network expansions under Vision 2030 sustain demand for hepatobiliary MRI systems and contrast-enhanced CT protocols. The Saudi Food and Drug Authority enforces CE-IVDR compliance tiers in public procurement, filtering lower-grade diagnostic suppliers from Ministry of Health tenders. Riyadh's King Faisal Specialist Hospital anchors regional reference laboratory standards for circulating tumor DNA validation.
United Arab Emirates
Medical tourism flows from South Asia and Africa concentrate diagnostic demand in Dubai's private oncology chains. MOHAP registration pathways prioritize centralized laboratory partnerships for molecular workflow integration. Abu Dhabi's Sheikh Khalifa Medical City hosts the Gulf's largest hepatobiliary tumor board, coordinating multimodal staging protocols across radiology and pathology departments.
Egypt
Government-led hepatitis C elimination campaigns have generated sustained longitudinal liver monitoring volumes among seropositive cohorts. Egypt's Drug Authority maintains distinct registration pathways for in vitro diagnostics, protecting local distributors through national preference policies. Cairo's National Liver Institute anchors the country's hepatocellular carcinoma surveillance architecture, connecting peripheral clinics via telepathology networks.
South Africa
Academic medical centers in Johannesburg and Cape Town pilot liquid biopsy validation studies under tightened Health Products Regulatory Authority oversight. The regulator's extended dossier review cycles favor multinationals with dedicated regulatory affairs teams. Groote Schuur Hospital's hepatology unit coordinates sub-Saharan training programs for hepatobiliary MRI interpretation.
Morocco
Centralized laboratory networks in Casablanca and Rabat are approaching public-sector reimbursement thresholds for AFP-L3 isoform testing. The country's national pharmaceutical regulator harmonizes technical guidelines with African Medicines Agency initiatives. OCP Group's employee health networks provide captive demand for occupational liver screening programs in phosphate mining regions.
Middle East and Africa Liver Cancer Diagnostics Market Competitive Landscape
Concentration sits with diversified imaging OEMs and molecular diagnostics specialists competing through installed base lock-in and centralized laboratory partnerships. Market structure tilts toward tiered procurement where CE-IVDR compliance filters lower-grade competitors from Gulf public hospital supply chains. Two strategic archetypes dominate: imaging system manufacturers leveraging service contract renewals, and assay developers integrating molecular workflows for high-throughput screening. Competitive moves center on unbundling service agreements from equipment sales and pre-submission regulator engagement to compress approval timelines.
Among diversified health technology conglomerates, Siemens Healthineers and Koninklijke Philips N.V. occupy positions sustained by imaging installed bases and radiologist training dependencies. F. Hoffmann-La Roche Ltd exemplifies the molecular diagnostics archetype through centralized laboratory anchoring. Thermo Fisher Scientific Inc. represents workflow integration specialists competing on platform consolidation for screening program scale. QIAGEN N.V. and Illumina, Inc. sit within the nucleic acid amplification tier, their positions contingent on viral load quantification demand from hepatitis-related cirrhosis monitoring.
| Leading Market Players |
|---|
| Siemens Healthineers |
| F. Hoffmann-La Roche Ltd |
| Koninklijke Philips N.V. |
| Thermo Fisher Scientific Inc. |
| QIAGEN N.V. |
| Illumina, Inc. |
| Becton, Dickinson & Company |
| FUJIFILM Corporation |
| Sysmex Corporation |
| Others |
Supply & Pricing Matrix
Liquid biopsy platform maturation is displacing multiphasic CT protocols in Egyptian and South African procurement cycles, simultaneously shifting supply geography toward molecular assay manufacturers in Western Europe and compressing pricing economics for imaging OEM service contracts.
Pricing Analysis
CE-IVDR compliance dictates the pricing tier structure across Gulf hospital procurement, separating premium-validated assays from standard-grade alternatives. Price differentiation rests on certification grade and volume scale, with centralized laboratory contracts commanding steepest discounts. Cost compression in imaging services is intensifying because Saudi procurement officers now unbundle maintenance agreements from equipment sales. Public-sector screening programs in Egypt show highest price sensitivity; private oncology chains in Dubai demonstrate lowest.
Supply Chain Analysis
Germany and the United States anchor high-sensitivity MRI system manufacturing, while China and South Korea feed contrast agent and coil component production. Raw material dependencies span gadolinium-based contrast media, superconducting magnet wire, and hepatobiliary-specific agent precursors. Single-source vulnerability concentrates in cryogen supply for superconducting systems. Distribution runs through OEM field engineering teams for capital equipment and pharmaceutical wholesale channels for consumables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in North African biomarker localization, where Algeria and Tunisia's underpenetrated centralized laboratory networks create niches for molecular workflow integrators following the UAE hub model.
For Market Incumbents: Consolidate imaging service contract portfolios in Saudi Arabia's Ministry of Health-affiliated networks before third-party engineering firms capture maintenance volumes. Deepen backward integration into hepatobiliary-specific contrast agent production to offset unbundling pressure. CE-IVDR recertification deadlines present the critical threat; preemptive notified body engagement secures supply continuity. For New Entrants and Emerging Players: Telepathology infrastructure gaps in rural Egyptian clinics present the most penetrable white-space target, connecting peripheral facilities to Cairo-based tumor boards without capital relocation. Morocco's centralized laboratory networks approach public-sector reimbursement thresholds for AFP-L3 testing. Partner with Algeria's national pharmaceutical regulator for pre-submission pathway alignment. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed molecular diagnostics specialists holding CE-IVDR transition readiness but limited North African distribution. Five-to-ten year viability favors workflow integration platforms over pure-play imaging OEMs. Monitor African Medicines Agency guideline harmonization as inflection indicator for streamlined market access scalability.| Strategic Initiative | Industry Significance |
|---|---|
| CE-IVDR Recertification Pathway | Notified body engagement prevents supply interruption in Gulf procurement pipelines. |
| Centralized Laboratory Partnership | UAE hub model replication captures high-throughput screening program scale in North Africa. |
| Telepathology Network Deployment | Digital slide-sharing platforms address Egypt's geographic expertise maldistribution without relocation. |
| Service Contract Unbundling Response | Competitive tendering for technical support defends maintenance margins in Saudi networks. |
| Biomarker Localization Investment | Algerian regulatory pre-submission positions for African Medicines Agency convergence. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hepatologists, hospital procurement officers, biomedical engineers, and centralized laboratory directors. Secondary validation drew from SFDA registration databases, Egypt's Drug Authority filings, Health Products Regulatory Authority submission records, and GPO contract repositories. Bottom-up procedure volume modeling and top-down equipment installed base estimates were triangulated against manufacturer service contract disclosures.
Across the projection horizon, analytical frameworks segmented by diagnostic modality, technology platform, end-user concentration, and distribution channel structure. CAGRs were derived from procedure volume trajectories and price elasticity assumptions specific to hepatitis C surveillance cohorts and medical tourism flows. Forecast inputs incorporated CE-IVDR transition timelines and African Medicines Agency harmonization progress.
Forecasts assume regulatory continuity in SFDA, Egypt's Drug Authority, and Health Products Regulatory Authority regimes; material policy shifts would require re-modeling. Recalibration cycles align with material shifts in reimbursement threshold announcements and regional regulatory convergence milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Companion Animal Diagnostic Services Market
Diagnostics
Point of Care (Poc) Molecular Diagnostics Market
Diagnostics
Diabetes Diagnostics Market
Diagnostics
Singleplex Immunoassay Market
Diagnostics
North America Non-Hodgkin Lymphoma Diagnostics Market
Diagnostics
Global Rheumatoid Arthritis Diagnostic Tests Market
Diagnostics
Global Veterinary POC Diagnostic Market
Diagnostics
Animal Auto-Immune Disease Diagnostics Market
Diagnostics
Alanine Aminotransferase Reagent Market
Diagnostics
Global Predictive Genetic Testing and Consumer/Wellness Genomics Market
Diagnostics
Latent Tuberculosis Infection Detection Market
Diagnostics
Global Companion Diagnostic Technologies Market
Diagnostics
Home Diagnostics Market
Diagnostics
Infectious Respiratory Disease Diagnostics Market
Diagnostics
Global Rabies Diagnostics Market
Diagnostics
Glaucoma Diagnostics Market