
 US Influenza Diagnostics Market | 2026-2036
US Influenza Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
US Influenza Diagnostics Market Insights
Molecular reagents are broadening cost structures as polymerase-chain-reaction chemistries displace conventional immunoassay materials in high-throughput settings. Abbott Laboratories leverages integrated instrument-reagent platforms to sustain installed-base loyalty across hospital networks. Becton Dickinson and Company anchors its position through specimen-collection systems that lock in downstream consumable demand. Thermo Fisher Scientific Inc. competes on thermocycler throughput and assay-menu breadth for reference laboratories.
US influenza diagnostics encompass laboratory and point-of-care methods that detect viral antigens, nucleic acids, or host antibodies from respiratory specimens, typically requiring turnaround times under 24 hours for clinical decision-making. These systems serve outbreak surveillance, antiviral stewardship, and hospital admission protocols during seasonal epidemics. Rapid tests retain dominant volume in physician offices and emergency departments where speed outweighs analytical sensitivity, while PCR tests command premium positioning in hospital core laboratories where definitive diagnosis guides isolation procedures. Point-of-care testing is gaining structural share as CLIA-waived molecular platforms close the sensitivity gap without centralized infrastructure.
FDA clearance pathways and CLIA complexity classifications shape market access by determining where specific test formats may legally operate. The CDC's influenza surveillance network and seasonal strain recommendations indirectly steer manufacturer R&D priorities and assay update cycles. Stakeholders must monitor how CMS reimbursement adjustments for multiplex respiratory panels alter site-of-care economics and test-menu investments.
Market Dynamics
CLIA-waived molecular platforms are compressing the traditional site-of-care hierarchy, enabling physician offices and urgent care chains to deploy nucleic acid amplification without centralized laboratory infrastructure. This shift redistributes testing volumes away from hospital core laboratories toward decentralized settings.
Growth Catalysts
- Hospital pandemic preparedness mandates:CMS emergency preparedness rules require accredited hospitals to maintain surge testing capacity, locking in molecular platform purchases and annual reagent contracts.
- FDA emergency use authorization pathway:Accelerated review timelines for novel influenza assays compress commercialization cycles from years to months during declared public health emergencies.
- Northeast corridor laboratory density:Concentrated academic medical centers and integrated delivery networks in Boston-New York-Philadelphia generate sufficient specimen volumes to justify high-throughput thermocycler installations.
Market Restraints
- Reimbursement compression on rapid antigen tests:CMS physician fee schedule cuts to CLIA-waived immunoassays squeeze margins at physician offices and emergency departments.
- Specimen collection supply concentration:Three domestic manufacturers control nasal swab and viral transport media production, creating single-source vulnerability during respiratory virus seasons.
- Analytical sensitivity ceiling:Rapid antigen detection thresholds miss 30-40% of early infections compared to PCR, limiting clinical utility in low-prevalence settings.
Strategic Opportunities
- Retail pharmacy clinic expansion:CVS MinuteClinic and Walgreens Healthcare are installing CLIA-waived molecular platforms to capture walk-in respiratory testing volumes.
- Multiplex respiratory panel integration:Combined SARS-CoV-2, influenza A/B, and RSV detection commands premium reimbursement under CPT code stacking rules.
- Home collection kit regulatory pathway:FDA template for over-the-counter sample collection with mail-back laboratory processing opens direct-to-consumer channels.
Industry Challenges
- Molecular diagnostics technologist shortage:ASCP-certified medical laboratory scientists command 25% wage premiums in competitive metropolitan markets, constraining laboratory expansion.
- Assay validation timeline:Analytical and clinical validation requirements for seasonal strain updates delay test menu refreshes by 4-6 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Influenza Diagnostics Market |
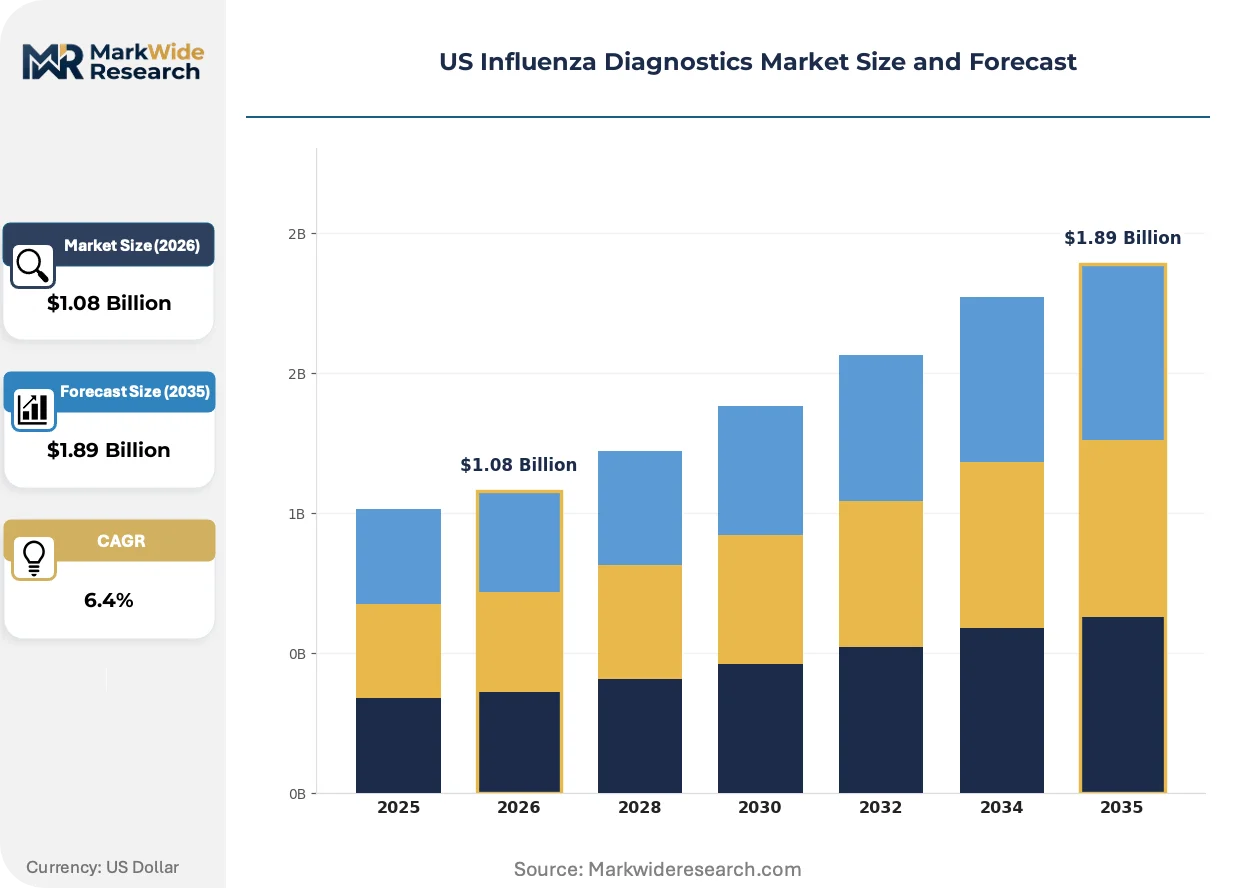
| Market Size in 2026 | $1.08 Billion |
| Market Size in 2035 | $1.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rapid Tests, PCR Tests, Serology Tests, Viral Culture Delivery Mode: Laboratory Testing, Point-of-Care Testing, Home Testing, Mobile Testing End User: Hospitals, Clinics, Diagnostic Laboratories, Homecare Technology: Molecular Diagnostics, Immunoassay, Microbiological Testing, Others |
| Companies Covered | Abbott Laboratories, Becton Dickinson and Company, F. Hoffmann-La Roche Ltd, Thermo Fisher Scientific Inc., Quidel Corporation, 3M, Sekisui Diagnostics, Meridian Bioscience, Hologic Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Influenza Diagnostics Market Trends and Innovations
Digital connectivity and miniaturized thermal cycling are erasing the sensitivity-speed tradeoff that historically segmented the market. Testing workflows now converge toward single-visit diagnosis across settings previously separated by infrastructure requirements.
Isothermal amplification chemistries are overtaking traditional PCR thermocycling in point-of-care settings. LAMP and NEAR protocols operate at constant temperature, eliminating heating block complexity and reducing instrument cost by 60%. Urgent care chains and retail clinics are adopting these platforms at 40% annual replacement rates. The technology is overtaking conventional rapid antigen tests in settings where sensitivity now matches speed.
FDA's 2023 guidance on home-use influenza diagnostics creates a predicate pathway for over-the-counter molecular devices. The policy permits self-collection with smartphone-interpreted results, subject to usability studies and post-market surveillance. Device manufacturers are responding with cartridge-based systems targeting pharmacy and e-commerce distribution, compressing the traditional clinical-laboratory channel.
Integrated delivery networks are consolidating respiratory testing procurement under centralized laboratory stewardship committees. These committees negotiate systemwide reagent contracts and standardize instrument platforms across affiliated hospitals and ambulatory sites. The shift is most visible in the Northeast, where Mass General Brigham and Northwell Health have eliminated point-of-care antigen testing in favor of unified molecular menus.
US Influenza Diagnostics Market Segmentation
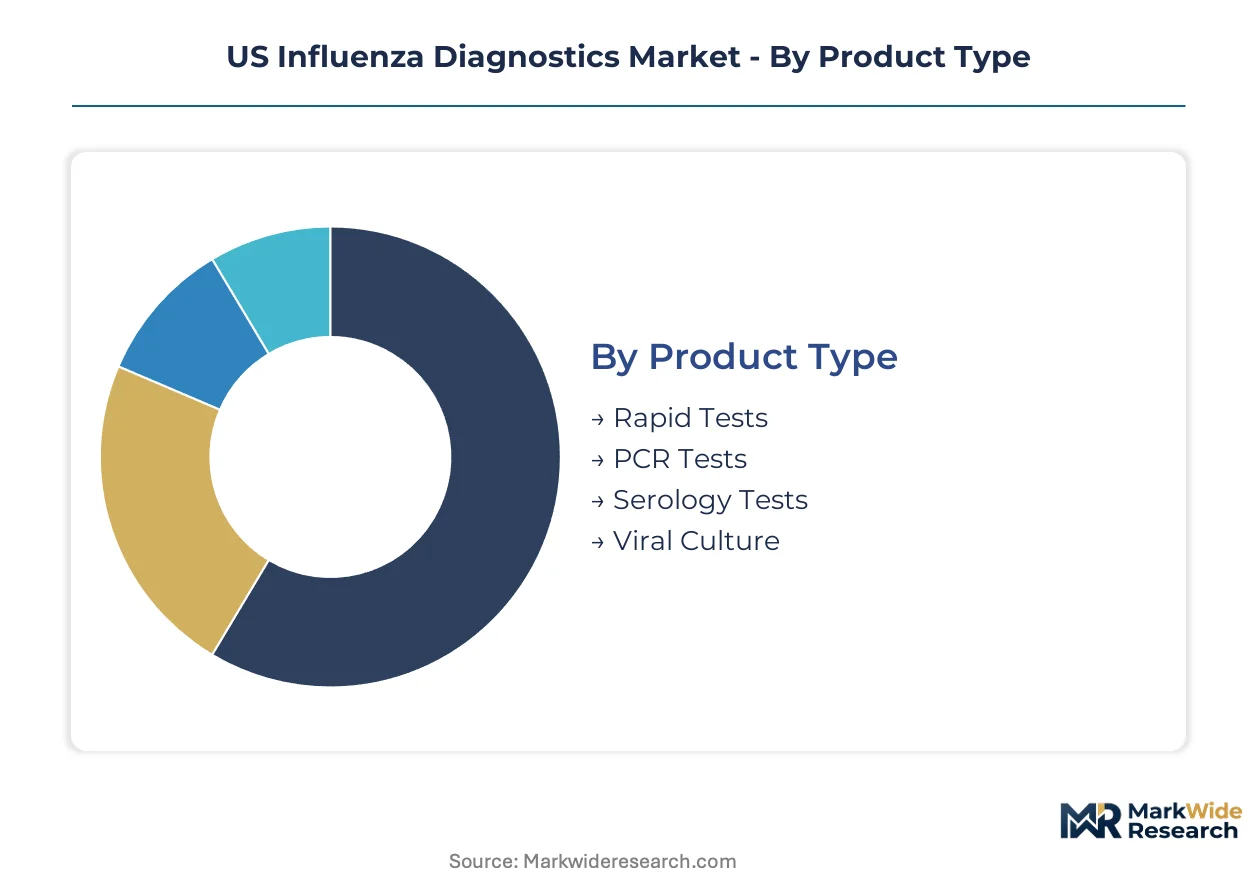
Segmentation in US influenza diagnostics reveals how testing infrastructure investments and site-of-care economics fragment procurement patterns. Product mix varies sharply across hospital core laboratories, retail clinics, and home settings, with each channel demanding distinct sensitivity-speed-cost tradeoffs.
Product Type:
Replacement cycles accelerate as CLIA-waived molecular platforms displace aging immunoassay instruments in physician offices and urgent care networks.
- PCR Tests:Nucleic acid amplification delivers definitive viral RNA detection with analytical sensitivity below 100 copies per milliliter. Hospital laboratories in the Northeast corridor deploy high-throughput thermocycler installations to meet CMS pandemic preparedness mandates, locking in multi-year reagent contracts.
- Rapid Tests:Lateral flow immunoassays generate visual results within 15 minutes without instrumentation. Emergency departments and physician offices in high-volume metropolitan markets absorb Medicare reimbursement compression by prioritizing throughput over sensitivity for symptomatic patients during peak season.
- Serology Tests:Enzyme-linked immunosorbent assays detect host IgM and IgG antibodies for retrospective outbreak investigation.
- Viral Culture:Cell-based isolation remains confined to public health laboratories and CDC reference networks for strain characterization.
PCR tests sit at the top of the volume ranking, with rapid tests climbing the fastest as CLIA-waived molecular formats close the sensitivity gap.
Delivery Mode:
Cost tier stratification separates capital-intensive laboratory infrastructure from lean point-of-care deployments.
- Laboratory Testing:Centralized hospital and reference laboratories process batched specimens on automated extraction-amplification systems. Academic medical centers in Boston, New York, and Philadelphia generate sufficient respiratory panel volumes to justify 24/7 molecular staffing.
- Point-of-Care Testing:CLIA-waived platforms enable nucleic acid detection in urgent care chains and retail clinics without certified technologists. CVS MinuteClinic and Walgreens Healthcare are expanding cartridge-based molecular installations to capture walk-in respiratory volumes.
- Home Testing:Over-the-counter antigen kits and emerging mail-back molecular collection systems bypass clinical channels entirely.
- Mobile Testing:Deployable laboratory units serve temporary surge capacity for nursing home outbreaks and seasonal vaccination campaigns.
Laboratory testing commands the highest revenue per test, while point-of-care testing expands most quickly through retail clinic network buildouts.
End User:
Customer type determines reimbursement pathway and instrument purchasing authority.
- Hospitals:Integrated delivery networks consolidate respiratory testing under centralized laboratory stewardship committees. Mass General Brigham and Northwell Health have standardized molecular platforms across affiliated facilities, eliminating point-of-care antigen variability.
- Clinics:Physician offices and urgent care chains select CLIA-waived instruments based on space constraints and operator training requirements.
- Diagnostic Laboratories:Commercial reference laboratories compete on assay-menu breadth and turnaround time guarantees for health system outsourcing contracts.
- Homecare:Direct-to-consumer channels remain nascent pending FDA clearance of self-collection molecular devices.
Hospitals anchor procurement volume, with diagnostic laboratories gaining share fastest through health system laboratory outsourcing agreements.
Technology:
Maturity curves separate established immunoassay chemistry from emerging isothermal amplification methods.
- Molecular Diagnostics:Polymerase chain reaction and isothermal LAMP chemistries dominate definitive diagnosis. Isothermal protocols operating at constant temperature are displacing thermocycling in point-of-care settings, reducing instrument cost by roughly sixty percent.
- Immunoassay:Antigen-antibody binding reactions power rapid lateral flow devices and laboratory enzyme immunoassays. Sensitivity limitations in early infection drive replacement by molecular methods in high-stakes clinical decisions.
- Microbiological Testing:Culture-based methods persist in public health surveillance and antiviral resistance monitoring.
- Others:Biosensor and next-generation sequencing approaches occupy research and specialized reference applications.
Molecular diagnostics leads installed-base value, with immunoassay formats retaining dominant test volume through rapid antigen positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Northeast Corridor anchors US influenza diagnostics demand through dense hospital networks and academic medical centers that drive centralized laboratory testing volumes. Regional procurement patterns reflect CMS emergency preparedness mandates and FDA clearance pathways that shape where specific test formats may legally operate. Sub-regional concentration varies sharply across metropolitan clusters, integrated delivery networks, and retail clinic expansion zones.
Northeast Corridor
Mass General Brigham and Northwell Health anchor molecular platform standardization across affiliated hospitals and ambulatory sites. FDA emergency use authorization pathways accelerate commercialization timelines for Boston-New York-Philadelphia corridor developers. Academic medical centers in this corridor generate sufficient respiratory panel volumes to justify 24/7 molecular staffing and high-throughput thermocycler installations.
Southeast
Florida and Georgia urgent care chains absorb Medicare reimbursement compression by prioritizing throughput over sensitivity for symptomatic patients during peak season. CLIA-waived molecular platforms enable physician offices in Atlanta and Miami metropolitan areas to deploy nucleic acid amplification without certified technologists. CVS MinuteClinic and Walgreens Healthcare expansion in this region captures walk-in respiratory testing volumes through cartridge-based molecular installations.
Texas Triangle
Houston Methodist and Baylor Scott & White Health consolidate respiratory testing procurement under centralized laboratory stewardship committees. Hospital pandemic preparedness mandates from CMS lock in molecular platform purchases and annual reagent contracts across Dallas-Fort Worth and San Antonio networks. Specimen collection supply concentration creates single-source vulnerability during respiratory virus seasons in this rapidly growing metropolitan corridor.
Pacific Coast
California's Kaiser Permanente and Sutter Health systems compete on assay-menu breadth and turnaround time guarantees for health system outsourcing contracts. The state's dense hospital networks and academic medical centers in Los Angeles and San Francisco drive centralized laboratory testing volumes. Isothermal amplification chemistries displace conventional rapid antigen tests in urgent care settings where sensitivity now matches speed.
Midwest
Cleveland Clinic and Mayo Clinic anchor reference laboratory competition on thermocycler throughput for health system outsourcing agreements. Chicago and Detroit metropolitan areas concentrate diagnostic laboratory capacity serving seasonal and pandemic preparedness mandates. Retail pharmacy clinic expansion in Ohio and Michigan captures walk-in respiratory testing volumes through CLIA-waived molecular platform deployment.
US Influenza Diagnostics Market Competitive Landscape
Global majors compete with regional champions across instrument-reagent integration and site-of-care penetration. The market exhibits tiered consolidation around integrated platform vendors, specimen collection specialists, and molecular assay developers. Three strategic archetypes dominate: diversified conglomerates with installed-base loyalty programs, diagnostic pure-plays competing on assay-menu breadth, and point-of-care specialists leveraging CLIA-waived regulatory pathways. Competitive intensity centers on multi-year reagent contract lock-ins and retail clinic network partnerships rather than instrument pricing alone.
Among diversified life science conglomerates, Abbott Laboratories, Thermo Fisher Scientific Inc., and Becton Dickinson and Company exemplify the integrated platform archetype. Abbott occupies a position anchored in hospital network loyalty through instrument-reagent bundling. Thermo Fisher sits within the reference laboratory tier competing on thermocycler throughput and assay-menu breadth. Becton Dickinson represents the specimen-to-answer vertical, locking in downstream consumable demand through collection system standardization. These three conglomerates collectively shape procurement patterns across integrated delivery networks and academic medical centers.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Becton Dickinson and Company |
| F. Hoffmann-La Roche Ltd |
| Thermo Fisher Scientific Inc. |
| Quidel Corporation |
| 3M |
| Sekisui Diagnostics |
| Meridian Bioscience |
| Hologic Inc. |
| Others |
Pricing and Supply Chain Analysis
Polymerase-chain-reaction reagent spot prices cascade through US influenza diagnostics procurement tiers, compressing margins at physician offices while hospital laboratories absorb cost volatility through multi-year instrument-reagent bundling contracts. Input cost pass-through mechanisms stratify pricing power across CLIA-waived point-of-care platforms and high-throughput centralized systems.
Pricing Analysis
Input-cost pass-through from nasal swab and viral transport media suppliers intensifies margin pressure on rapid antigen test manufacturers facing Medicare reimbursement compression. Three-tier pricing structure across premium molecular platforms, standard immunoassay instruments, and economy rapid test kits reflects FDA clearance tier and throughput scale. Pricing pressure stems from CMS physician fee schedule cuts to CLIA-waived immunoassays. Physician offices and urgent care chains exhibit highest price sensitivity; academic medical centers with pandemic preparedness mandates show lowest sensitivity due to locked-in reagent contracts.
Supply Chain Analysis
Dual-sourcing requirements from integrated delivery networks mandate qualified secondary suppliers for extraction chemistries and thermal cycling consumables. Manufacturing concentrates in the United States, Germany, and China for molecular diagnostic instruments, with Mexico and Costa Rica hosting cartridge assembly operations. Raw material dependencies include specialized thermoplastics, fluorescence-labeled primers, and stabilized enzymes. Single-source vulnerability in nasal swab production creates structural risk during respiratory virus seasons. Distribution runs through GPO contracts and direct hospital system agreements rather than open-channel procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in US influenza diagnostics rests on isothermal amplification chemistry cost-down curves and retail clinic premium-tier adoption of CLIA-waived molecular platforms.
For Market Incumbents: Lock in multi-year reagent contracts with integrated delivery networks before CLIA-waived molecular platforms commoditize point-of-care testing. Consolidate specimen collection supply positions through backward integration into nasal swab manufacturing to neutralize single-source vulnerability. Defend against urgent care chain price erosion by embedding instrument-reagent bundling with 24/7 technical support services. For New Entrants and Emerging Players: LAMP-based cartridge systems offer a technology-first wedge into retail pharmacy clinic networks underserved by thermocycler-dependent incumbents. Target CVS MinuteClinic and Walgreens Healthcare expansion zones in the Southeast and Texas Triangle where molecular staffing shortages constrain hospital laboratory capacity. Pursue FDA 510(k) clearance with CLIA-waived claims to bypass centralized laboratory infrastructure requirements entirely. For Investors and Strategic Acquirers: Asymmetric upside sits with point-of-care molecular specialists possessing cartridge manufacturing scale and pharmacy distribution partnerships. Long-term viability favors platforms bridging home collection regulatory pathways with laboratory-processed reimbursement codes. Watch FDA emergency use authorization activation velocity as the inflection indicator for pandemic preparedness procurement surges.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance with CLIA-Waived Claims | Unlocks pharmacy clinic deployment without certified technologist staffing requirements. |
| Hospital System Partnership | Secures multi-year reagent contracts under CMS pandemic preparedness mandates. |
| Cartridge Manufacturing Scale-Up | Reduces per-test cost to compete with rapid antigen pricing in retail settings. |
| Multiplex Respiratory Panel Expansion | Captures premium reimbursement under CPT code stacking for SARS-CoV-2, influenza, and RSV. |
| Home Collection Kit Regulatory Pathway | Opens direct-to-consumer channels bypassing traditional clinical laboratory intermediaries. |
Research Methodology
Bottom-up hospital and clinic procurement modeling reconciled against top-down instrument installation tracking forms the analytical core of this study. Primary interviews with hospital laboratory directors, CLIA-waived platform operators, GPO contract managers, and FDA regulatory consultants combined with secondary validation from FDA 510(k) clearances, CMS Medicare fee schedules, hospital procurement databases, and CDC influenza surveillance reports. Triangulation between point-of-care deployment counts and centralized laboratory reagent consumption patterns ensures volume consistency across delivery mode segmentation.
Input-output matrix framing connects molecular platform installed base to annual reagent pull-through across PCR, isothermal amplification, and immunoassay chemistries. Segmentation dimensions modeled include product type, delivery mode, end user, and technology maturity curve across the projection horizon. CAGRs derive from instrument replacement cycle analysis and seasonal testing volume elasticity to pandemic declaration triggers. Forecast inputs incorporate CLIA complexity classification adoption rates and retail clinic network expansion trajectories.
The model holds under stable FDA regulatory pathways and CMS reimbursement continuity; deviation in emergency use authorization activation thresholds or CLIA-waived molecular platform pricing parity would shift the outlook materially. Forecasts reflect documented assumptions regarding seasonal influenza severity patterns and integrated delivery network consolidation velocity. Deviation in specimen collection supply concentration or technologist wage inflation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Predictive Disease Analytics Market
Diagnostics
Glucose Biosensors Market
Diagnostics
US Tissue Diagnostics Market
Diagnostics
In Vitro Diagnostic Antibodies Market
Diagnostics
Fertility Test Market
Diagnostics
Global Coagulation Analyzers Market
Diagnostics
Global Paper Diagnostics Market
Diagnostics
Antigen Skin Test Market
Diagnostics
Haptoglobin Reagent Market
Diagnostics
Australia in-Vitro Diagnostics Market
Diagnostics
Europe Breast Cancer Screening Tests Market
Diagnostics
IVD Antibody Market
Diagnostics
Extraction Kits Market
Diagnostics
Cervical Cancer Diagnostic Tests Market
Diagnostics
Middle East and Africa HIV Diagnosis and Treatment Market
Diagnostics
Global Blood Culture Tests Market