
 India Floor Coatings Market | 2026-2036
India Floor Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
India Floor Coatings Market Outlook
Gujarat is fragmenting India's floor coatings supply base as new resin blending plants and distribution hubs multiply along the Vadodara-Ahmedabad corridor. Asian Paints leverages its decorative paint infrastructure to cross-sell industrial floor systems through existing dealer networks. Sika AG anchors the high-performance segment with specialized polyurethane and epoxy formulations for pharmaceutical cleanrooms and food processing plants. Akzo Nobel N.V. competes through technology leadership in water-based low-VOC systems suited to tightening environmental norms.
India floor coatings comprise polymer-based protective layers applied to concrete substrates, typically formulated with epoxy resins at 100-500 micron dry film thickness to resist abrasion, chemical attack, and moisture ingress. These systems serve primarily to extend substrate life in industrial facilities where heavy traffic, thermal cycling, or corrosive exposure would otherwise degrade bare concrete. Epoxy formulations dominate commercial and industrial installations due to superior adhesion and chemical resistance, while polyurethane coatings command premium positioning in settings requiring thermal shock tolerance and flexible crack bridging. Water-based technology is gaining fastest trajectory as BIS norms and green building certification push solvent reduction, though 100% solids systems retain margin concentration in high-wear manufacturing environments.
BIS mandates product certification for floor coatings used in public infrastructure and industrial safety zones, compelling reformulation cycles and testing investment from domestic and imported suppliers alike. The Central Pollution Control Board's VOC emission guidelines intersect with state-level construction codes in Maharashtra and Gujarat to create layered compliance obligations for applicators and manufacturers. Stakeholders must monitor evolving green building rating thresholds and state industrial policy incentives to align product portfolios with procurement criteria that will govern project awards across India's expanding manufacturing and logistics footprint.
Market Dynamics
BIS certification mandates for industrial flooring products are tightening material specifications and forcing reformulation cycles across domestic and imported supplier bases, compressing margins while raising qualification barriers.
Growth Catalysts
- PLI scheme incentives:Production-linked incentives for specialty chemicals manufacturing are attracting resin blending capacity expansion along the Vadodara-Ahmedabad corridor, strengthening local supply chains for epoxy and polyurethane raw materials.
- E-commerce fulfillment center construction:Warehousing and logistics facilities across Gujarat and Maharashtra are multiplying procurement volume for abrasion-resistant floor systems as last-mile infrastructure scales.
- Water-based technology maturation:Low-VOC formulations are crossing performance thresholds previously held by solvent-borne systems, enabling compliance with Central Pollution Control Board emission guidelines without sacrificing durability.
Market Restraints
- Petrochemical input volatility:Epoxy resin prices fluctuate with benzene and propylene feedstock costs, squeezing applicator margins on fixed-price contracts common in public infrastructure tenders.
- Import dependency for specialty hardeners:Aliphatic amine and polyaspartic ester supplies concentrate with European and Japanese producers, exposing project timelines to freight bottlenecks and currency swings.
- Curing temperature sensitivity:Ambient humidity and monsoon-season moisture ingress degrade epoxy adhesion on outdoor or semi-exposed concrete, limiting application windows and warranty coverage in coastal Maharashtra.
Strategic Opportunities
- Pharmaceutical cleanroom specification:USFDA-inspected facilities in Hyderabad and Bengaluru are specifying conductive polyurethane systems with coved skirting, creating premium installation contracts beyond standard industrial pricing.
- Food processing plant modernization:FSSAI hygiene audits are driving replacement cycles for failed tile-and-grout flooring in dairy and meat processing units across Punjab and Uttar Pradesh.
- Green building certification alignment:IGBC and GRIHA rating thresholds for low-emitting materials are creating procurement preference for water-based systems in IT park and hospital construction.
Industry Challenges
- Skilled applicator scarcity:Proper surface preparation and moisture-vapor transmission testing require certified technicians, yet training infrastructure lags project demand in tier-two manufacturing clusters.
- BIS testing timeline compression:Certification cycles for new formulations extend 8-14 months, delaying product launches behind competitor entries and locking R&D investment in queue.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Floor Coatings Market |
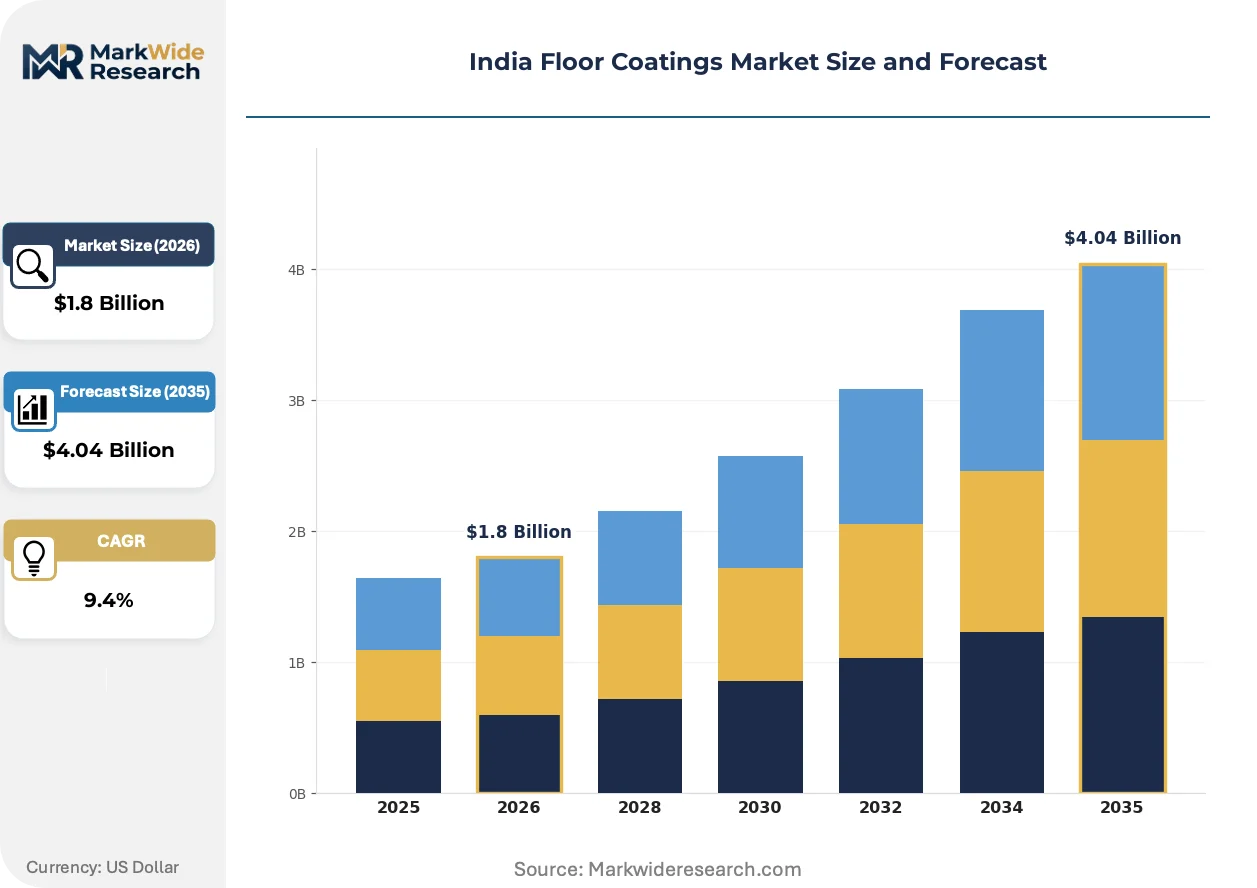
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Polyurethane, Acrylic, Vinyl End User: Residential, Commercial, Industrial, Institutional Application: Decorative, Protective, Anti-slip, Waterproofing Technology: Water-based, Solvent-based, 100% Solids, UV-cured |
| Companies Covered | Henkel AG & Co. KGaA, Nippon Paint Holdings Co., Ltd., Asian Paints, Sika AG, Jotun, Akzo Nobel N.V., Kansai Nerolac Paints Limited, The Sherwin-Williams Company, BASF SE, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Floor Coatings Market Strategic Shifts
Formulation chemistry and application methodology are converging to compress project timelines and environmental footprints simultaneously, with regulatory pressure and buyer sophistication accelerating technology turnover.
Polyaspartic aliphatic polyurea technology is collapsing the traditional 7-day epoxy cure window into same-day return-to-service installations. Pharmaceutical and automotive manufacturing facilities in Pune and Chennai are specifying these rapid-cure systems to minimize production downtime during floor refurbishment. The technology is collapsing the distinction between high-performance industrial flooring and decorative commercial finishes, as color-stable aliphatic chemistry penetrates showroom and retail applications previously served by slower-curing alternatives.
BIS certification requirements for floor coatings used in public infrastructure and industrial safety zones are mandating third-party testing for slip resistance, fire rating, and chemical resistance. The Central Pollution Control Board's VOC emission guidelines intersect with state-level construction codes in Maharashtra and Gujarat to create layered compliance obligations. Water-based epoxy and polyurethane suppliers are reformulating to meet both BIS product standards and green building procurement criteria simultaneously.
Buyer preference is consolidating around single-source accountability for substrate preparation through topcoat application, displacing fragmented subcontractor arrangements. Large warehousing developers in Ahmedabad and Mumbai are awarding turnkey flooring contracts to certified applicator networks with in-house shot-blasting and moisture mitigation capability. This bundling is most visible in western India, where manufacturing and logistics project scale justifies dedicated flooring contractor investment in capital equipment and technician training.
India Floor Coatings Market Segmentation
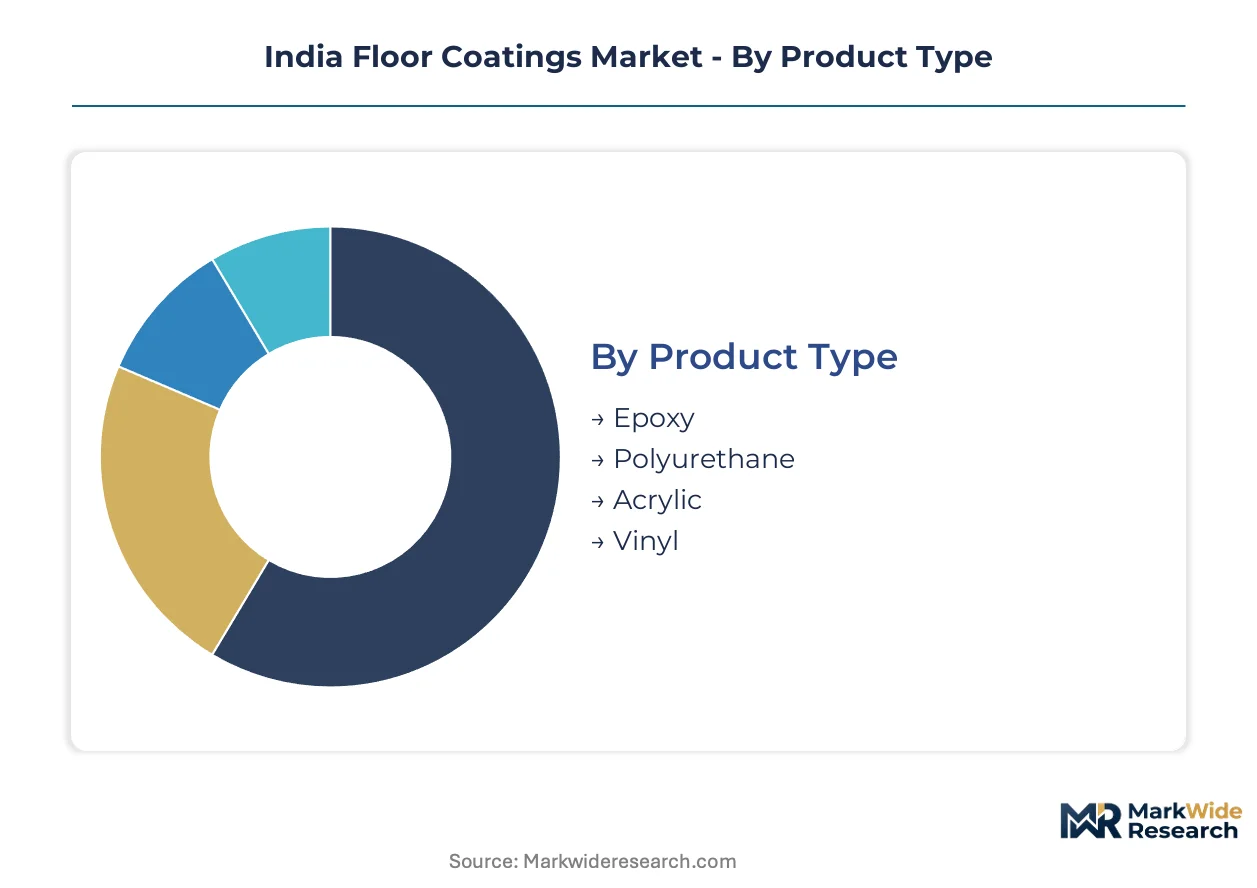
Floor coatings in India fragment across performance tiers and compliance requirements that reshape procurement decisions. Each segmentation axis carries distinct margin profiles, application constraints, and certification obligations that suppliers must navigate simultaneously.
Product Type:
Mature epoxy formulations dominate installed base volumes while emerging chemistries capture specification upgrades in premium segments.
- Epoxy:Two-part thermosetting systems formulated with bisphenol-A or bisphenol-F resins cure to 200-500 micron films with superior chemical resistance. Manufacturing facilities in Ahmedabad and Pune specify these for battery assembly floors and solvent storage areas where sulfuric acid exposure occurs. BIS certification mandates for industrial safety zones compel reformulation cycles that compress margins while locking out uncertified imports.
- Polyurethane:Aliphatic and aromatic isocyanate-cured elastomers deliver thermal shock tolerance and flexible crack bridging across -30°C to 80°C service ranges. Cold storage warehouses across Maharashtra specify polyurethane toppings over epoxy primers to withstand blast freezer cycling without delamination. Import dependency for specialty hardeners exposes project timelines to freight bottlenecks from European and Japanese suppliers.
- Acrylic:Water-dispersed or solvent-borne thermoplastic resins serve decorative commercial applications with lower abrasion requirements than industrial settings. Retail showrooms in Mumbai and Bengaluru specify these for cost-sensitive refurbishment cycles.
- Vinyl:Polyvinyl chloride or polyvinyl acetate emulsions provide seamless sheet or tile flooring systems for healthcare and education facilities. Hospital construction in Hyderabad drives procurement for infection-control surfaces with heat-welded seams.
Epoxy retains volume leadership; polyurethane holds the steepest expansion curve.
End User:
Cost tier stratification separates specification-grade industrial systems from commodity residential applications with minimal surface preparation standards.
- Residential:Decorative concrete sealers and thin-film epoxy coatings applied by homeowner DIY or small contractors. Apartment construction in tier-two cities generates volume for water-based acrylics with low odor profiles.
- Commercial:Medium-duty systems for retail, hospitality, and office environments balancing aesthetics with moderate traffic loads. Shopping mall developers in Delhi-NCR specify metallic epoxy finishes for atrium spaces.
- Industrial:Heavy-duty formulations resisting chemical attack, thermal cycling, and mechanical abrasion in manufacturing and logistics facilities. E-commerce fulfillment centers across Gujarat and Maharashtra multiply procurement for abrasion-resistant toppings as last-mile infrastructure scales.
- Institutional:Hygienic seamless flooring for healthcare, education, and government buildings with slip resistance and cleanability mandates. AIIMS-affiliated hospitals specify conductive polyurethane with coved skirting for operating theater compliance.
Industrial commands the highest per-square-meter pricing; institutional segments gain share fastest through healthcare infrastructure expansion.
Application:
Volume concentration sits with protective functions while decorative specification climbs through commercial premiumization.
- Decorative:Metallic pigments, quartz aggregates, and flake broadcast systems for visual impact in retail and hospitality settings. Hotel lobbies in Jaipur and Udaipur specify these for destination aesthetics.
- Protective:Chemical-resistant barriers extending concrete substrate life against abrasion, moisture ingress, and corrosive exposure. Fertilizer plants in Gujarat deploy epoxy novolac formulations for urea handling areas.
- Anti-slip:Broadcast aggregates or textured finishes meeting BIS slip resistance requirements for wet-process food plants and pharmaceutical cleanrooms. Dairy processing units in Punjab replace failed tile-and-grout systems following FSSAI hygiene audit failures.
- Waterproofing:Elastomeric membranes and cementitious coatings preventing moisture vapor transmission in basements, parking decks, and podium slabs. Mumbai coastal humidity drives specification for breathable systems that withstand monsoon-season hydrostatic pressure.
Protective applications anchor revenue concentration; decorative specification climbs fastest through retail format premiumization.
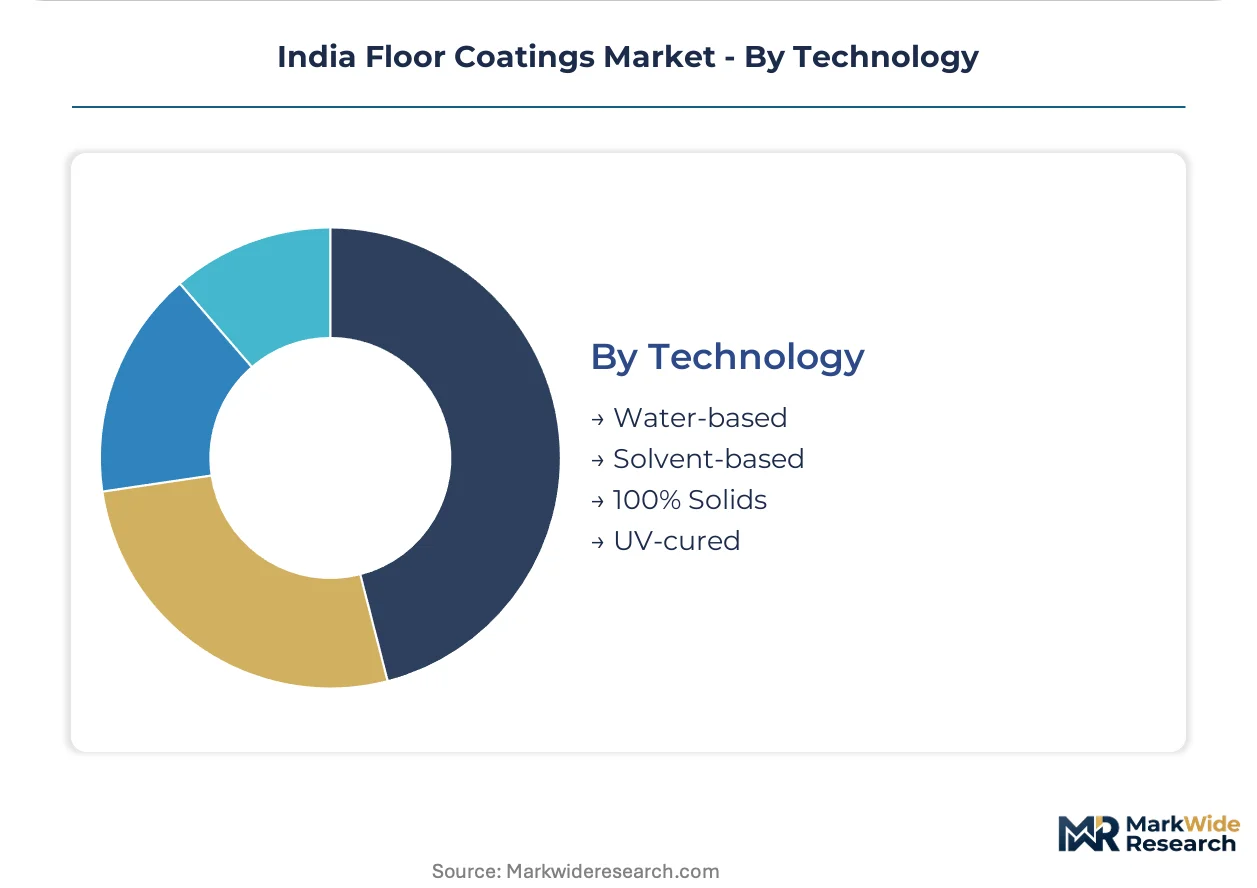
Technology:
Supply concentration for specialty hardeners shapes technology adoption curves more than formulation chemistry alone.
- Water-based:Low-VOC epoxy and polyurethane dispersions meeting Central Pollution Control Board emission guidelines and IGBC green building criteria. IT park construction in Bengaluru specifies these for LEED-equivalent certification compliance.
- Solvent-based:Traditional high-solids formulations with superior substrate wetting and rapid early-stage cure in low-temperature conditions. Road and bridge projects in Himalayan states specify these for cold-weather application windows.
- 100% Solids:Zero-VOC systems applied at high build thickness without solvent evaporation, delivering maximum chemical resistance and durability. Automotive paint shops in Chennai specify these for solvent-resistant containment areas.
- UV-cured:Photoinitiator-activated acrylates curing in seconds under ultraviolet exposure for rapid return-to-service in retail refurbishment. Limited adoption in India due to equipment capital requirements and substrate geometry constraints.
Water-based technology captures the fastest regulatory tailwinds; 100% solids retains margin concentration in high-wear manufacturing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Western India consumes floor coatings through manufacturing and logistics infrastructure, while southern states deploy premium systems for pharmaceutical and electronics cleanrooms. Northern markets favor institutional healthcare applications. Eastern India lags in specification-grade procurement.
Maharashtra
E-commerce fulfillment centers in Mumbai and Pune multiply procurement for abrasion-resistant toppings. BIS certification mandates for industrial safety zones compel reformulation cycles among applicators. The Mumbai-Ahmedabad industrial corridor concentrates project volume for multi-tenant warehousing developers.
Gujarat
Specialty chemicals manufacturing under PLI scheme incentives attracts resin blending capacity along the Vadodara-Ahmedabad corridor. Central Pollution Control Board VOC emission guidelines intersect with state construction codes to create layered compliance. Fertilizer plants in Bharuch and Vadodara deploy epoxy novolac formulations for urea handling areas.
Karnataka
USFDA-inspected pharmaceutical facilities in Bengaluru specify conductive polyurethane systems with coved skirting for cleanroom compliance. IGBC green building rating thresholds drive water-based system procurement in IT park construction. Electronics manufacturing clusters in the city generate demand for anti-static flooring.
Tamil Nadu
Automotive paint shops in Chennai specify 100% solids solvent-resistant containment systems. Polyaspartic rapid-cure technology penetrates manufacturing refurbishment to minimize production downtime. The Sriperumbudur-Oragadam auto belt concentrates high-performance coating contracts.
Telangana
Pharmaceutical formulation plants in Hyderabad drive specification-grade polyurethane procurement for USFDA compliance audits. FSSAI hygiene audit failures in neighboring food processing units create replacement demand. Genome Valley research facilities require specialized seamless flooring for laboratory environments.
India Floor Coatings Market Competitive Environment
Capability concentration sits with specialty chemical multinationals; scale advantage sits with domestic decorative paint conglomerates. The market structures around three tiers: global formulation leaders with certified industrial systems, national decorative paint networks cross-selling floor products, and regional applicator-contractors bundling installation services. Consolidation pressure favors players with captive resin supply and in-house BIS testing infrastructure. M&A activity targets certified applicator networks in western India; technology licensing agreements accelerate water-based formulation access.
Among global specialty chemical players, Sika AG and Akzo Nobel N.V. occupy positions anchoring high-performance specification segments. Asian Paints exemplifies the cross-selling archetype, leveraging decorative paint infrastructure for industrial floor system distribution. These three represent distinct competitive vectors: formulation technology leadership, regulatory certification depth, and distribution network density.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| Nippon Paint Holdings Co., Ltd. |
| Asian Paints |
| Sika AG |
| Jotun |
| Akzo Nobel N.V. |
| Kansai Nerolac Paints Limited |
| The Sherwin-Williams Company |
| BASF SE |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Gujarat's resin blending corridor is compressing margins for domestic epoxy formulators while forcing price discipline on imported specialty hardeners. BIS certification timelines and petrochemical feedstock volatility are reshaping how suppliers structure contracts and manage input exposure.
Pricing Analysis
Project-based contracts dominate industrial flooring procurement, with public infrastructure tenders locking applicators into fixed-price obligations despite benzene and propylene cost swings. Price differentiation separates BIS-certified systems from uncertified imports, while volume scale drives tiering between multi-tenant warehousing developers and small commercial refurbishments. Cost compression in solvent-borne formulations is intensifying as water-based alternatives close performance gaps. Small contractors in tier-two cities exhibit highest price sensitivity; pharmaceutical cleanroom specifiers show least.
Supply Chain Analysis
Export-control regimes on specialty amine hardeners from European and Japanese producers are constraining flows to Indian polyurethane formulators. Domestic supply draws from China for bisphenol-A resins, Germany for aliphatic isocyanates, and India for captive epoxy blending along the Vadodara-Ahmedabad corridor. Single-source vulnerability concentrates in polyaspartic ester imports. Distribution runs through Asian Paints' dealer networks for standard industrial grades and certified applicator-direct for high-performance specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits as a defensive-moat story. BIS certification entrenchment creates switching costs that lock qualified suppliers into multi-year specification cycles.
For Market Incumbents: Insulate margin position by deepening backward integration into resin blending capacity in Gujarat and accelerating BIS pre-certification for next-generation water-based formulations. Threat from unqualified imports is intensifying as compliance timelines compress. Channel control through certified applicator networks anchors pricing power. For New Entrants and Emerging Players: Eastern India's underpenetration in specification-grade industrial flooring offers white-space expansion as manufacturing investment shifts beyond western corridors. Food processing modernization in Uttar Pradesh and Punjab presents the most penetrable replacement cycle. Go-to-market through FSSAI hygiene audit-triggered refurbishment contracts bypasses entrenched specification relationships. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because certified applicator networks in western India command irreplaceable project execution capability and BIS testing infrastructure. Acquisition targets cluster around mid-cap specialists with captive surface preparation equipment and technician training programs. Watch for PLI scheme disbursement acceleration as inflection signal for resin supply capacity expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Blending | Captive epoxy supply secures margin control against benzene feedstock volatility from Reliance and IOC refineries. |
| BIS Pre-Certification Investment | Early testing lockup accelerates product launch timelines ahead of competitor queue positions. |
| Certified Applicator Network Acquisition | In-house shot-blasting and moisture mitigation capability enables turnkey contract bundling for warehousing developers. |
| Water-Based Formulation Pivot | Low-VOC systems align with Central Pollution Control Board guidelines and IGBC procurement criteria. |
| Pharmaceutical Cleanroom Specialization | Conductive polyurethane with coved skirting commands premium pricing in USFDA-inspected Bengaluru and Hyderabad facilities. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of customs trade data, BIS certification registries, Central Pollution Control Board emission filings, and state industrial policy documents. Primary interviews engaged plant managers at resin blending facilities, procurement leads at warehousing developers, certified flooring applicators, and technical directors at formulation companies. Bottom-up project pipeline tracking across Gujarat and Maharashtra triangulates against top-down chemical consumption estimates from petrochemical feedstock disclosures.
Forecast inputs span product type segmentation across epoxy, polyurethane, acrylic, and vinyl chemistries; end-use stratification from residential through institutional; and technology tiers from water-based through 100% solids systems. Modeled variables include e-commerce fulfillment center construction permits, PLI scheme disbursement trajectories, and BIS certification timeline compression. CAGRs derive from regression against historical project award data and forward pipeline visibility.
Macroeconomic conditions sit as an overlay; deviation in rupee-dollar exchange rates, crude oil price bands, or monsoon severity would shift the trajectory. Forecasts reflect assumptions on regulatory enforcement continuity and petrochemical capacity expansion timelines. Material shifts in BIS testing protocol changes or PLI scheme eligibility criteria would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paints & Coatings
Global Antifouling Paints and Coatings Market
Paints & Coatings
Middle East and Africa Floor Coatings Market
Paints & Coatings
Asia-Pacific Architectural Coatings Market
Paints & Coatings
Polyurethane Resins Paints and Coatings Market
Paints & Coatings
Insulating Paints and Coatings Market
Paints & Coatings
Aircraft Paint Market
Paints & Coatings
Fluorescent Paint Market
Paints & Coatings
Automotive Paints Market
Paints & Coatings
Cement Paints Market
Paints & Coatings
United Arab Emirates (UAE) Paints and Coatings Market
Paints & Coatings
India Automotive Paints and Coatings Market
Paints & Coatings
Low VOC Paints and Coatings Market
Paints & Coatings
Road Marking Paint Market
Paints & Coatings
North America Paints and Coatings Market
Paints & Coatings
Wall Putty Powder Market
Paints & Coatings
Core Plate Varnishes Market