
 Canvas Primer Market | 2026-2036
Canvas Primer Market Size, Share, and Industry Trends Forecast 2026-2036
Canvas Primer Market Outlook
Professional artist studios and academic ateliers is reorganizing procurement patterns across the canvas primer landscape, displacing casual hobbyist channels as the primary volume driver. Winsor & Newton leverages its heritage positioning and artist-grade certification to dominate premium distribution in Western Europe. PEBEO anchors its competitive stance through specialized gesso formulations that serve conservation-restoration workshops. CONDA Group extends manufacturing scale advantages across Asia-Pacific supply chains.
Canvas primer constitutes a preparatory coating system—typically comprising acrylic polymer emulsions, titanium dioxide pigment, and calcium carbonate extenders—engineered to seal woven textile substrates and establish tooth for subsequent paint adhesion. Acrylic primers occupy the largest share of the product type matrix due to faster drying cycles and universal media compatibility, while water-based variants represent the fastest-growing category as educational institutions phase out solvent-heavy studio practices. Surface coating applications command the deepest margin pools because conservation-grade specifications require multiple build layers and archival binders.
EPA VOC regulations in the United States and REACH frameworks administered by ECHA in Europe constrain solvent-based formulation chemistries, redirecting R&D investment toward low-emission acrylic and water-based systems. ISO 787 standards for pigment testing and ASTM D4236 labeling requirements further shape product certification pathways for international market access. Stakeholders must monitor evolving state-level chemical disclosure mandates and art school procurement policies to anticipate shifts in specification-driven demand.
Market Dynamics
Archival certification requirements from conservation laboratories are compressing formulation cycles and forcing manufacturers to validate substrate compatibility across multiple paint chemistries simultaneously.
Growth Catalysts
- EPA VOC Phase-III Standards:United States manufacturers are accelerating water-based acrylic reformulations to meet tightening emission thresholds for architectural coatings, expanding compliant product portfolios.
- Conservation-Restoration Workshops:Museum-grade surface preparation protocols are mandating calcium carbonate-extended primers with documented lightfastness, driving specification-grade volume in Western Europe.
- Art Education Infrastructure:China's expanding academy system is standardizing professional atelier curricula that require archival-quality gesso systems rather than student-grade alternatives.
Market Restraints
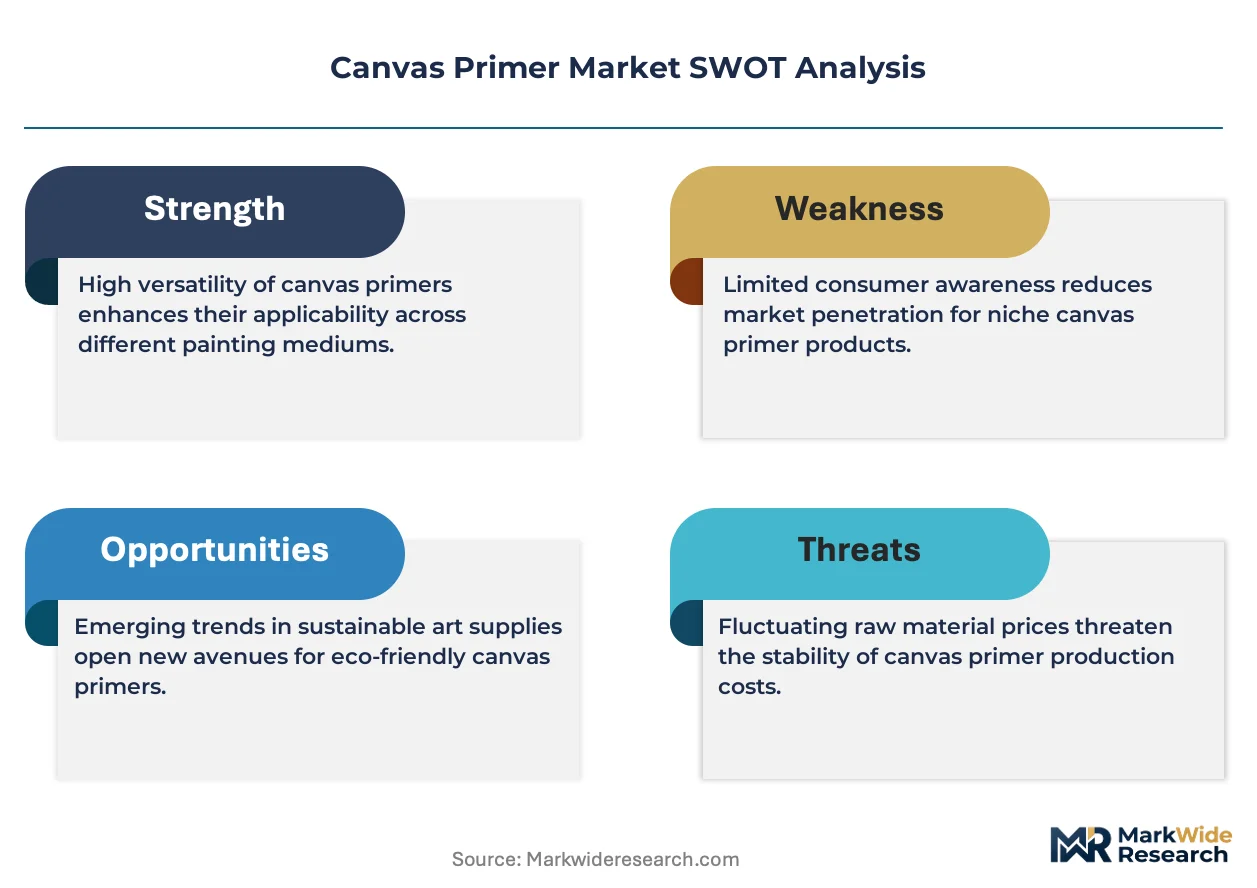
- Titanium Dioxide Feedstock Volatility:Pigment price swings constrain margin stability for mid-tier manufacturers dependent on chloride-process rutile imports.
- Solvent-Based Formulation Lock-In:REACH authorization timelines for traditional alkyd primers create regulatory friction that delays product portfolio transitions in EU member states.
- Substrate Substitution Threat:Aluminum composite panels and prepared wooden panels are capturing surface preparation budgets from traditional stretched canvas in commercial installation markets.
Strategic Opportunities
- India Art School Procurement:State-level vocational training expansions under Skill India directives are creating first-mover advantage for ISO-certified primer suppliers establishing institutional distribution.
- Digital Printing Convergence:Inkjet-receptive primer formulations are opening conservation photography and fine art reproduction applications previously served by uncoated substrates.
- E-Commerce Direct Channels:Professional artist collectives are consolidating purchasing through specialized supply platforms that bypass traditional distributor markups.
Industry Challenges
- Conservation Chemistry Expertise Gap:Formulation teams lack cross-training in polymer science and art historical materials, slowing archival validation protocols.
- ASTM D4236 Certification Timelines:Multi-jurisdictional labeling requirements extend product launch cycles by eight to fourteen months for international suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canvas Primer Market |
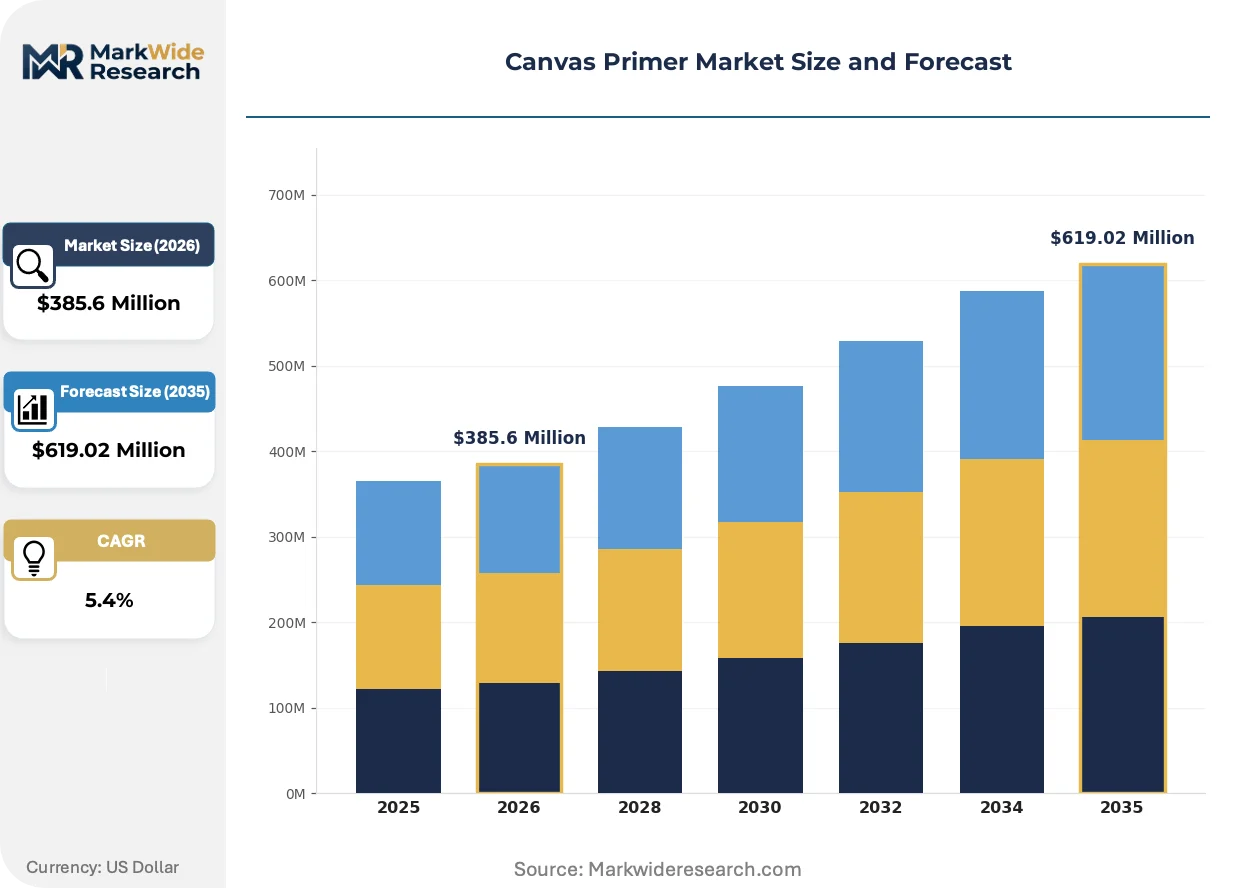
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $619.02 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic, Oil-Based, Water-Based, Solvent-Based End User: Artists, Educational Institutions, Hobbyists, Art Supplies Retailers Application: Canvas Preparation, Surface Coating, Texture Enhancement, Priming Size: Small (up to 250ml), Medium (250ml - 1L), Large (1L - 5L), Bulk (above 5L) |
| Companies Covered | Winsor & Newton, Fredrix, PEBEO, Canson, Daler-Rowney, Phoenix Arts Group, CONDA Group, Langer, Anhui Zhongsheng, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canvas Primer Market Strategic Shifts
Formulation chemistry is pivoting toward bio-based binder systems while digital color matching tools are compressing the specification process between manufacturers and atelier procurement officers.
Calcium carbonate-extended acrylic emulsions with engineered particle size distribution are supplanting traditional chalk-gesso formulations in museum conservation studios. Conservation-restoration workshops in Germany and Italy are adopting these systems within eighteen-month validation cycles. This transition is compressing demand for animal-protein based rabbit-skin glue primers and redirecting R&D toward synthetic archival binders.
REACH authorization requirements for titanium dioxide nanoparticles are forcing reformulation of high-opacity white primers across EU manufacturing facilities. The European Chemicals Agency's 2023 classification triggered substitution toward surface-treated pigment grades with enhanced dispersibility. Water-based acrylic systems with encapsulated titanium dioxide now dominate new product registrations in France and the Netherlands.
Professional artist studios are consolidating purchasing through cooperative buying groups that negotiate direct supply agreements with manufacturers. These collectives are displacing traditional fine art supply retailers in volume procurement for archival-grade materials. The shift is most pronounced in United States urban clusters where atelier density supports collective bargaining structures.
Canvas Primer Market Segmentation
Canvas primer manufacturers calibrate formulation portfolios and packaging formats against divergent technical requirements across conservation studios, educational ateliers, and retail channels. Segmentation discipline separates specification-grade archival systems from volume-oriented student products, with margin capture hinging on certification depth and substrate compatibility validation.
Product Type:
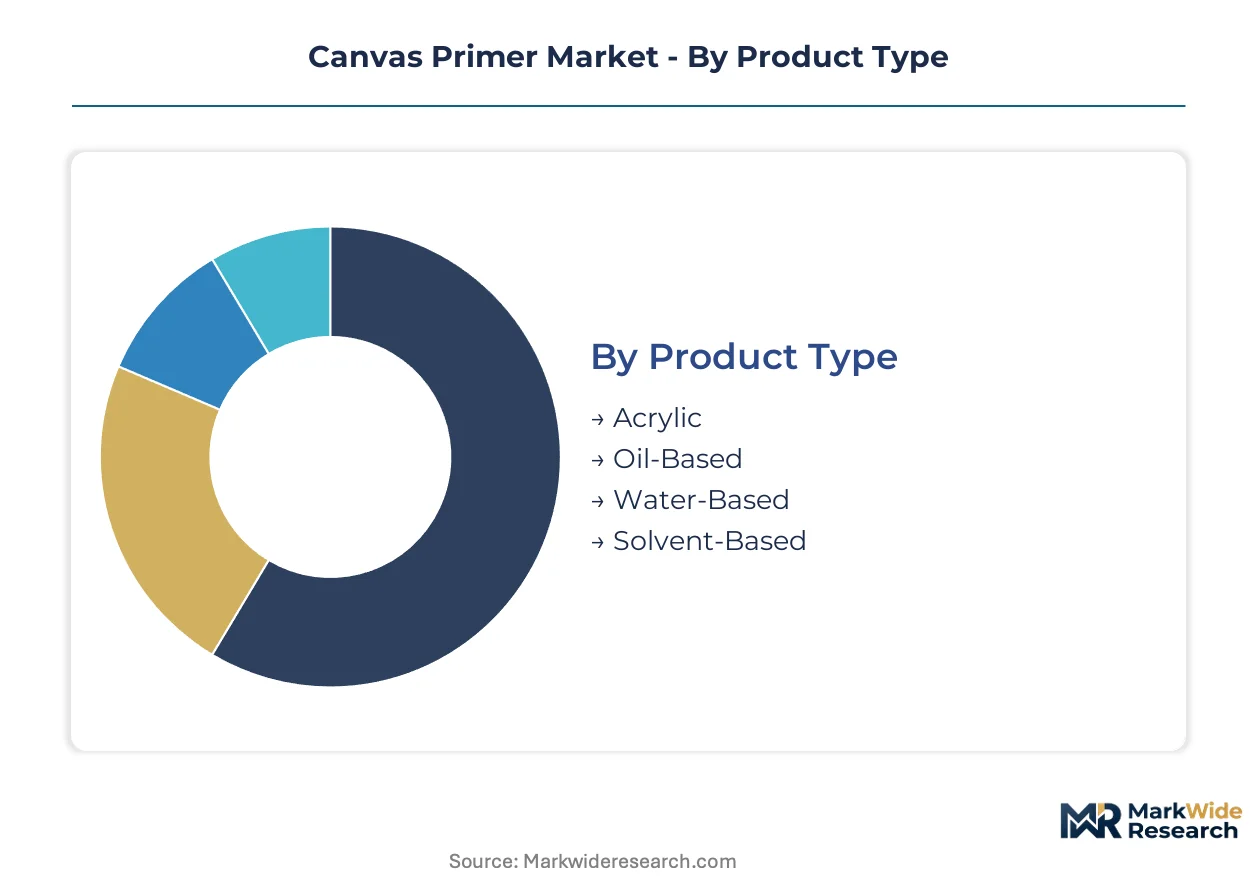
Margin pools concentrate in archival-grade acrylic systems where titanium dioxide loading and polymer binder quality drive price premiums, while water-based variants capture educational procurement volume through VOC compliance advantages.
- Acrylic:Polymer emulsion systems incorporating titanium dioxide pigment and calcium carbonate extenders deliver universal media compatibility with accelerated drying cycles. Professional ateliers in Germany and the United States specify these formulations for multi-layer build applications requiring documented substrate adhesion. Conservation-restoration workshops validate acrylic primers through eighteen-month archival testing protocols before procurement authorization.
- Water-Based:Low-emission formulations eliminate solvent content while maintaining tooth characteristics for subsequent paint layers. China's expanding academy system is standardizing water-based systems as baseline atelier equipment, displacing solvent-heavy alternatives through institutional procurement mandates. These formulations are climbing the fastest as educational infrastructure scales across Asia-Pacific markets.
- Oil-Based:Traditional alkyd binder systems retain niche demand among historical technique practitioners requiring extended working time and specific surface absorption rates.
- Solvent-Based:High-opacity formulations face regulatory compression under EPA VOC Phase-III standards and REACH authorization timelines, constraining portfolio transitions for EU manufacturers.
Acrylic holds installed capacity. Water-based is rotating up the share rankings.
End User:
Volume distribution tilts toward institutional procurement channels where specification-grade requirements and bulk purchasing terms reshape competitive positioning against fragmented hobbyist retail.
- Artists:Professional practitioners operating independent studios demand archival certification with documented lightfastness and substrate compatibility across oil, acrylic, and mixed media applications. Cooperative buying groups in United States urban clusters now negotiate direct supply agreements, displacing traditional retailer markups.
- Educational Institutions:Art academies and vocational training centers require VOC-compliant, water-based systems for studio safety protocols. India's Skill India directives are creating procurement windows for ISO-certified suppliers establishing institutional distribution networks.
- Hobbyists:Casual practitioners prioritize cost accessibility over archival specifications, driving private-label volume through mass-market art supply chains.
- Art Supplies Retailers:Specialty distributors curate tiered portfolios spanning student-grade to conservation-certified products, with shelf space allocation increasingly favoring professional-grade SKUs.
Educational institutions anchor volume procurement. Artists are consolidating purchasing power fastest.
Application:
Technical differentiation separates surface preparation functions by layer count, substrate type, and subsequent media compatibility requirements.
- Surface Coating:Multi-layer build systems for conservation-grade applications command the deepest margin pools through calcium carbonate-extended formulations with engineered particle size distribution. Museum workshops in Italy and Germany validate these systems for archival substrate preparation.
- Canvas Preparation:Base-layer sealing of woven textiles requires specific absorption control and tooth establishment for paint adhesion. Professional ateliers specify preparation-grade primers with documented polymer binder chemistry.
- Texture Enhancement:Impasto-capable formulations incorporate coarse extenders for three-dimensional surface effects.
- Priming:Universal sealing functions span student-grade through conservation-tier specifications.
Surface coating commands specification premiums. Canvas preparation rotates up through educational standardization.
Size:
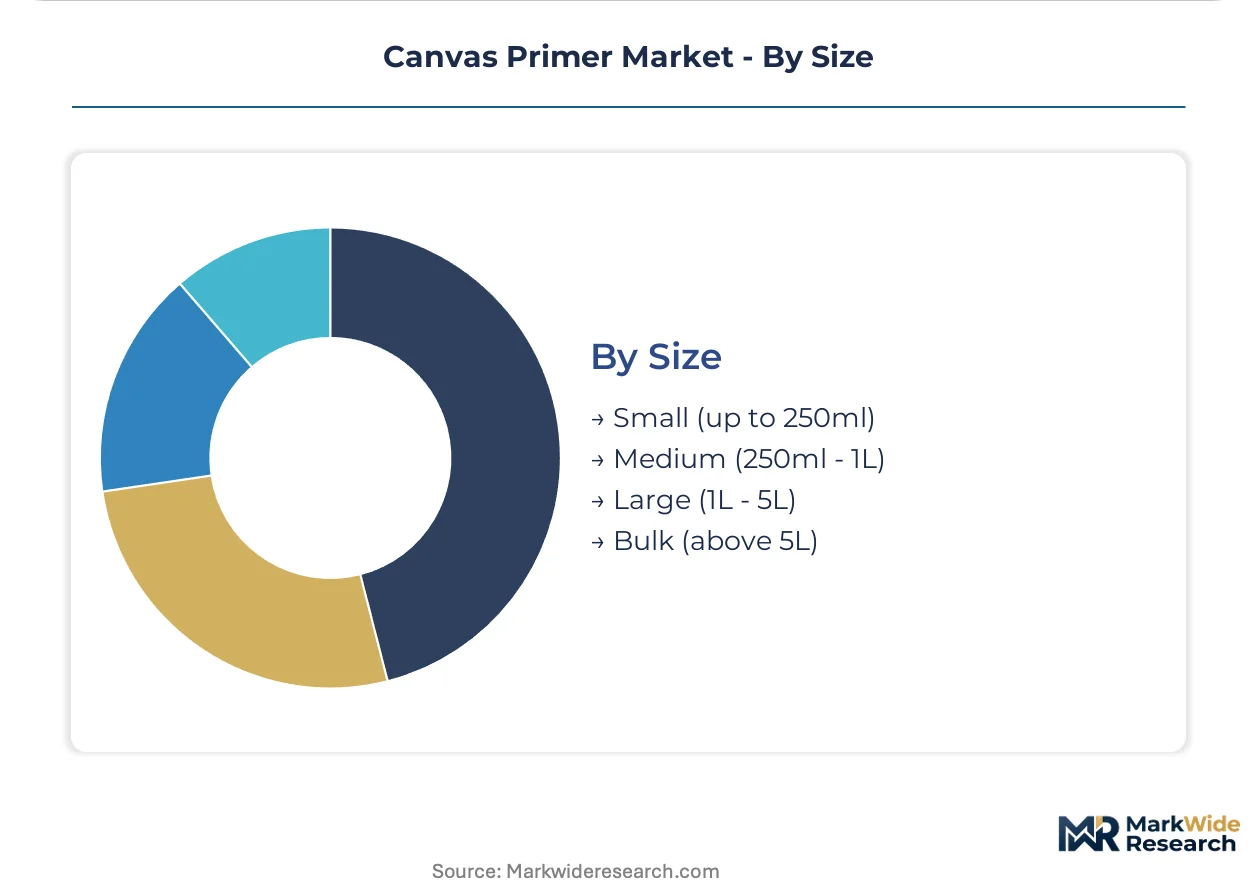
Packaging format segmentation aligns with usage intensity, storage constraints, and per-unit economics across studio, institutional, and retail contexts.
- Small (up to 250ml):Portable formats serve traveling artists and trial purchases, with premium pricing per milliliter reflecting convenience positioning.
- Medium (250ml - 1L):Standard studio quantities balance shelf stability with consumption rates for individual practitioners.
- Large (1L - 5L):Institutional procurement favors these formats for atelier supply rooms, with per-unit economics improving through volume concentration.
- Bulk (above 5L):Conservation-restoration workshops and academy systems specify bulk packaging for multi-year archival projects, with custom formulation contracts replacing off-shelf purchasing.
Large formats hold institutional volume. Bulk packaging is rotating up through conservation workshop procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's container throughput underwrites Germany's distribution dominance for conservation-grade art materials across Continental Europe.
United States
Professional artist cooperatives in Brooklyn and Los Angeles consolidate procurement through direct manufacturer agreements, bypassing traditional distributor networks. EPA VOC Phase-III standards accelerate water-based acrylic reformulations among domestic formulators. Chicago's conservation laboratory cluster validates archival primer systems for museum-grade applications.
Germany
Museum restoration workshops in Berlin and Munich mandate calcium carbonate-extended primers with documented lightfastness certification. ECHA REACH frameworks constrain titanium dioxide nanoparticle formulations, redirecting R&D toward surface-treated pigment grades. The Rhine-Ruhr manufacturing corridor hosts specialized gesso production for conservation studios.
China
State-funded academy expansions under vocational training directives standardize professional atelier curricula requiring archival-quality surface preparation. The country's national environmental regulator enforces emission controls on solvent-based coating facilities. Yangtze River Delta art supply manufacturing clusters scale water-based primer capacity for institutional procurement.
India
Skill India program expansions create procurement windows for ISO-certified suppliers establishing institutional distribution networks. The Bureau of Indian Standards mandates labeling compliance for imported art material formulations. Maharashtra's emerging art education infrastructure concentrates demand for student-grade primer volumes.
United Kingdom
London's conservation-restoration sector drives specification-grade demand through heritage collection maintenance protocols. The country's national chemical regulator administers REACH-aligned substance authorization timelines for imported primers. Oxford-Cambridge academic art programs standardize professional-grade gesso systems in studio curricula.
Canvas Primer Market Competitive Environment
Listed leaders compete with private specialists across formulation certification depth and institutional distribution reach. The vendor base organizes around heritage-brand incumbents, Asia-Pacific scale manufacturers, and conservation-focused niche formulators. Three archetypes dominate: archival-certification specialists leveraging museum validation protocols, volume-oriented producers capturing educational procurement, and integrated art-material conglomerates with cross-category shelf presence. Competitive moves concentrate on direct-to-studio e-commerce channel development and cooperative buying group penetration.
Within the heritage-brand tier, Winsor & Newton and Daler-Rowney occupy positions anchored by artist-grade certification and Western European distribution density. PEBEO exemplifies the conservation-specialist archetype through its focus on museum-workshop validation cycles. CONDA Group and Phoenix Arts Group represent Asia-Pacific scale manufacturers extending production capacity across regional supply chains. These named entities illustrate how competitive positioning separates archival-certification depth from volume-scale educational procurement.
| Leading Market Players |
|---|
| Winsor & Newton |
| Fredrix |
| PEBEO |
| Canson |
| Daler-Rowney |
| Phoenix Arts Group |
| CONDA Group |
| Langer |
| Anhui Zhongsheng |
| Others |
Value Chain & Pricing Dynamics
ASTM D4236 certification timelines gate both supply qualification and price differentiation simultaneously, compressing launch windows for international suppliers while enabling heritage brands to command archival-grade premiums through validated substrate compatibility protocols.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates conservation-certified systems from educational-grade and student-tier alternatives. Price differentiation centers on titanium dioxide loading and polymer binder quality, with archival certification adding substantial markup over base formulations. Cost compression in mid-tier segments is intensifying because pigment feedstock volatility constrains margin stability. Educational institutions exhibit highest price sensitivity through bulk procurement mandates, while conservation-restoration workshops prioritize specification compliance over unit cost.
Supply Chain Analysis
Container availability fluctuations on Asia-Europe trade lanes elevate inbound logistics costs for titanium dioxide and calcium carbonate raw materials sourced from Chinese processing facilities. Manufacturing concentrates in China, Germany, and the United States, with each hub serving distinct regional certification requirements. Formulation chemistry draws from acrylic polymer emulsions, rutile-grade pigments, and engineered carbonate extenders. Single-source vulnerability in chloride-process titanium dioxide creates supply chain risk. Distribution runs through specialized fine art supply retailers and direct-to-studio e-commerce platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical consultation and archival validation services represent a service-attach opportunity expanding faster than base primer volume, as conservation workshops demand documented substrate compatibility testing and multi-year certification support.
For Market Incumbents: Consolidate position through backward integration into titanium dioxide sourcing and captive production of surface-treated pigment grades, while deepening direct supply agreements with United States artist cooperatives to disintermediate distributor markups threatened by e-commerce channel expansion. For New Entrants and Emerging Players: Differentiate on water-based formulation specialization for India's Skill India procurement windows, targeting state-level vocational training expansions with ISO-certified institutional distribution networks rather than competing for saturated Western European conservation-studio accounts. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed art-material conglomerates seeking portfolio rationalization; acquisition targets include conservation-specialist formulators with validated museum-workshop relationships and eighteen-month archival testing protocols that create switching-cost moats.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pigment Sourcing | Captive titanium dioxide supply insulates margin compression from chloride-process rutile import volatility. |
| Direct-to-Studio E-Commerce Channel Development | Bypassing traditional distributor networks captures cooperative buying group volume in United States urban clusters. |
| Water-Based Formulation Portfolio Expansion | EPA VOC Phase-III compliance opens institutional procurement channels in educational markets. |
| Archival Certification Investment | Eighteen-month museum validation protocols create specification-grade switching costs in conservation-restoration workshops. |
| Institutional Distribution Partnership | Skill India directive alignment positions suppliers for state-level vocational training procurement windows. |
Study Parameters
Desk research of customs trade data, fine art supply industry associations, and regulatory filing databases preceded structured interviews with formulation chemists, conservation-restoration workshop directors, educational procurement officers, and fine art supply distributors. Primary fieldwork with museum-grade ateliers and academy systems validated secondary estimates of specification-grade demand concentration. Bottom-up volume modeling triangulated against top-down market sizing from import-export flows and manufacturer capacity disclosures.
Variance decomposition across product type, end-user segment, application function, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs derived from segment-level growth rate distributions weighted by titanium dioxide feedstock cost trajectories and institutional procurement cycle timing. Modeled inputs incorporated REACH authorization timelines for solvent-based formulations and EPA VOC phase-in schedules.
Material uncertainties — titanium dioxide nanoparticle reclassification, state-level chemical disclosure mandate expansion, and substrate substitution acceleration — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory stability and pigment supply chain configuration. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paints & Coatings
Global Decorative Coatings Market
Paints & Coatings
South Africa Paints and Coatings Market
Paints & Coatings
Egypt Paints and Coatings Market
Paints & Coatings
Middle-East and Africa Wood Coatings Market
Paints & Coatings
Polyurethane Resins Paints and Coatings Market
Paints & Coatings
Oman Paints and Coatings Market
Paints & Coatings
Asia-Pacific Paints and Coatings Market
Paints & Coatings
Wall Putty Powder Market
Paints & Coatings
Saudi Arabia Paints and Coatings Market
Paints & Coatings
Global Aerosol Paints Market
Paints & Coatings
Global Construction Paints and Coatings Market
Paints & Coatings
Europe Automotive Paints and Coatings Market
Paints & Coatings
India Floor Coatings Market
Paints & Coatings
Asia-Pacific Paint Spray Guns Market
Paints & Coatings
South America Paints and Coatings Market
Paints & Coatings
Global Antifouling Paints and Coatings Market