
 Prokaryotic Recombinant Protein Market | 2026-2036
Prokaryotic Recombinant Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Prokaryotic Recombinant Protein Market Analytics
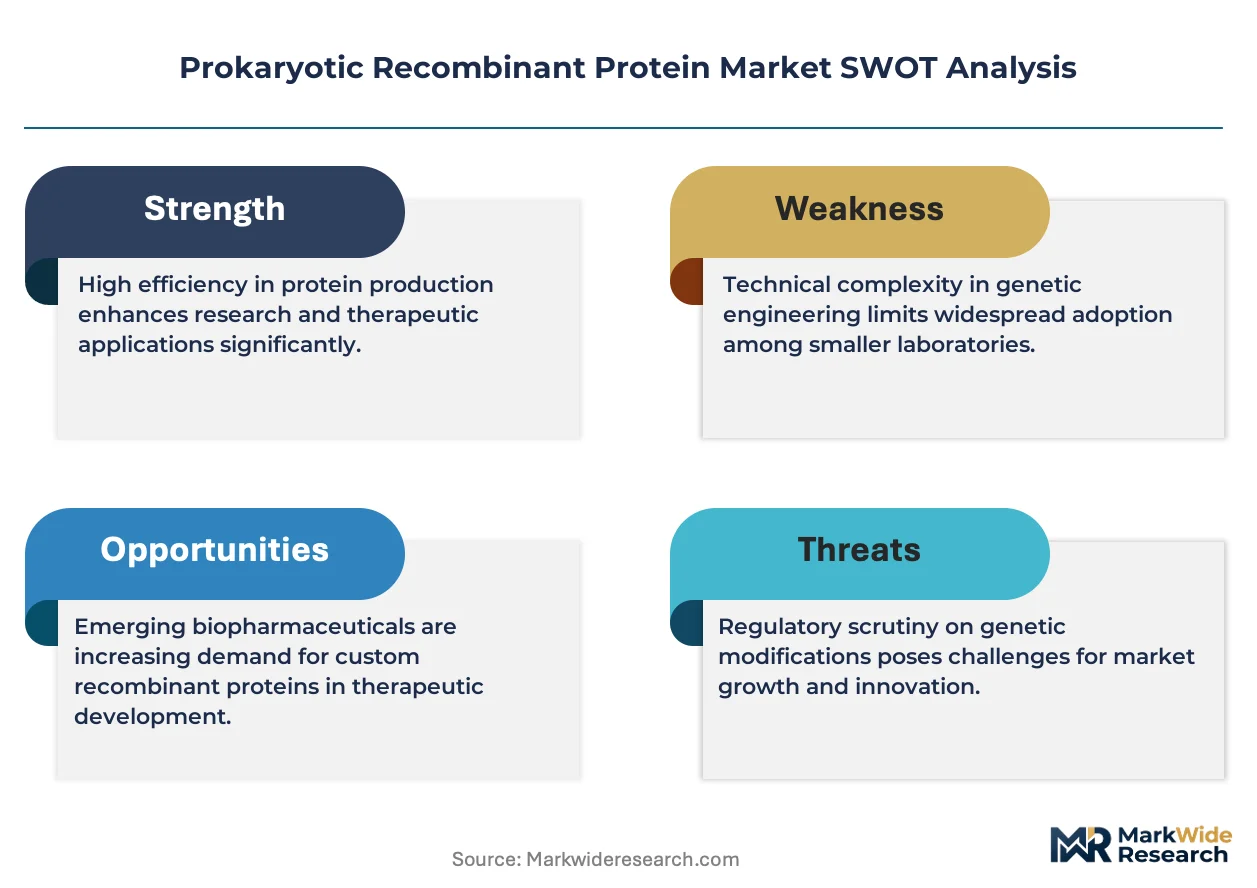
REACH compliance is shifting the cost-of-entry calculus for European suppliers of prokaryotic-derived research proteins. Thermo Fisher Scientific leverages its vertically integrated fermentation network to sustain margin advantages across multiple organism expression platforms. Merck KGaA anchors its position through deep expertise in E. coli strain engineering and downstream purification scale-up. GenScript Biotech Corporation differentiates through automated gene synthesis pipelines that compress lead times for custom protein orders.
Prokaryotic recombinant proteins are heterologous polypeptides produced in bacterial host systems, typically achieving yields of 1–10 grams per liter in high-density E. coli fermentation with intracellular or periplasmic accumulation. These proteins serve as critical inputs for therapeutic drug discovery, diagnostic assay development, and industrial biocatalysis where post-translational modification requirements remain minimal. Fermentation-based production dominates commercial supply due to decades of process optimization and established regulatory familiarity, while cell-free synthesis represents the fastest-expanding method for toxic or complex protein targets that destabilize living hosts. Among organism types, E. coli retains overwhelming market share for standard research-grade outputs, though Bacillus subtilis gains traction for secreted proteins requiring reduced endotoxin burdens.
The FDA and EMA jointly shape market access through divergent host cell protein impurity thresholds and validation documentation requirements that suppliers must navigate simultaneously. ISO 13485 certification and GMP alignment with ICH Q5D guidelines increasingly filter contract research participation, particularly for diagnostic reagent and vaccine applications. Stakeholders must monitor evolving pharmacopeial standards for endotoxin quantification as biosimilar and cell therapy pipelines expand their reliance on prokaryotic expression systems.
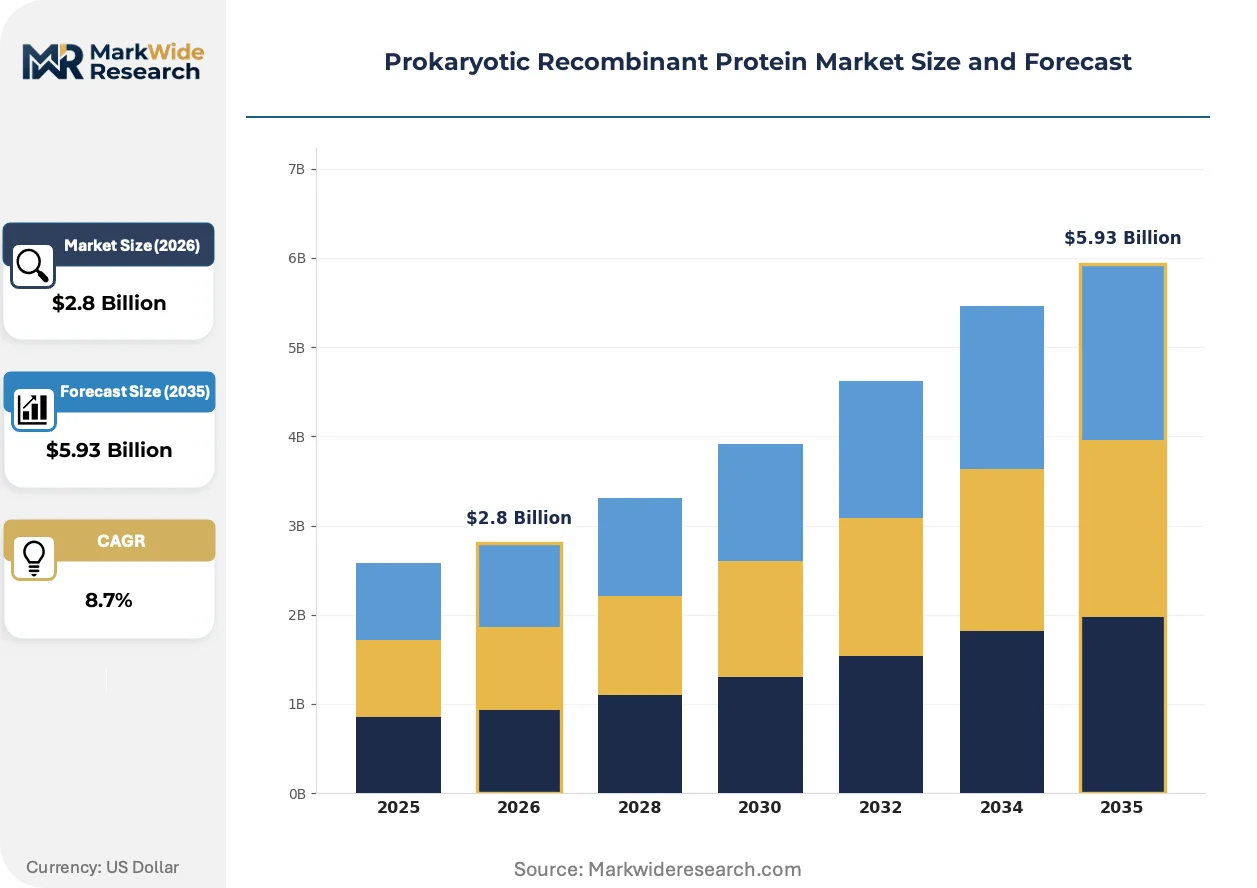
Market Dynamics
FDA's updated host cell protein impurity guidance is compressing supplier margins while accelerating consolidation among contract manufacturers serving monoclonal antibody pipelines. This regulatory pressure reshapes competitive positioning by privileging vertically integrated fermentation networks over fragmented specialty suppliers.
Growth Catalysts
- Cell-free synthesis:Toxic protein targets that destabilize living bacterial hosts now achieve viable yields through extract-based systems, expanding addressable protein classes for synthetic biology applications.
- EMA-FDA alignment pressure:Divergent validation documentation requirements are forcing dual-track compliance investments that filter out undercapitalized competitors, concentrating contract research participation among ISO 13485-certified suppliers.
- Bacillus subtilis secretion:Reduced endotoxin burdens in secreted protein outputs are displacing periplasmic E. coli accumulation for diagnostic reagent manufacturing.
Market Restraints
- Input cost volatility:Pharmaceutical-grade yeast extract and defined media components face price instability from agricultural supply fluctuations, squeezing fermentation economics at sub-10,000 liter scales.
- Supply concentration risk:High-purity recombinant protein supply concentrates among Boston and San Diego biotech clusters, creating geographic vulnerability to regional logistics disruptions.
- Technical limitation:Prokaryotic systems cannot execute mammalian glycosylation patterns, permanently excluding these platforms from therapeutic glycoprotein segments regardless of yield optimization.
Strategic Opportunities
- Indian CMO expansion:CDSCO's streamlined biosimilar approval pathways and PLI scheme incentives attract fermentation capacity investments for export-oriented recombinant protein production.
- Automated gene synthesis:Compression of custom protein lead times through integrated design-build-test platforms creates service differentiation beyond commodity catalog offerings.
- Cell therapy inputs:Biosimilar and regenerative medicine pipelines expand demand for GMP-aligned prokaryotic expression systems in cytokine and growth factor manufacturing.
Industry Challenges
- Downstream purification scale-up:Chromatography resin capacity constraints and skilled bioprocess engineering shortages delay tech transfer from pilot to commercial fermentation volumes.
- Endotoxin quantification standardization:Evolving pharmacopeial methods for lipopolysacride detection create validation backlogs that extend batch release timelines for diagnostic-grade outputs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Prokaryotic Recombinant Protein Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Production Method: Fermentation, Cell-Free Synthesis, Induction-Based, Batch Processing Applications: Therapeutic Proteins, Industrial Enzymes, Diagnostic Reagents, Vaccines Organism Type: Escherichia coli, Bacillus subtilis, Lactobacillus, Pseudomonas Purification Technique: Affinity Chromatography, Ion Exchange Chromatography, Precipitation, Filtration |
| Companies Covered | Thermo Fisher Scientific, Merck KGaA, GenScript Biotech Corporation, Bio-Techne, Bio-Rad Laboratories, Inc., Sino Biological, Inc., Abcam plc, Proteintech Group, Inc., Abnova Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Prokaryotic Recombinant Protein Market Evolving Landscape
Continuous processing architectures and synthetic biology toolkits are compressing development timelines while fragmenting the traditional value chain between discovery-scale and manufacturing-scale suppliers.
Cell-free protein synthesis is overtaking conventional fermentation for complex or toxic targets that compromise E. coli viability. Contract manufacturers serving antibody discovery workflows now adopt hybrid production strategies combining living hosts with extract-based systems. This dual-platform approach is overtaking single-organism dependencies in toxic protein categories.
REACH compliance is shifting the cost-of-entry calculus for European suppliers of research-grade proteins, with ECHA registration requirements for novel expression strains extending qualification timelines. German and French suppliers absorb disproportionate compliance burdens relative to US competitors, forcing specialization in high-margin custom synthesis over catalog commoditization.
Buyer concentration among biopharmaceutical contract manufacturers is consolidating procurement leverage, with large CDMOs demanding audited supplier networks and captive inventory buffers. Small research laboratories lose negotiating position as volume aggregates toward monoclonal antibody production facilities in Massachusetts and California. This purchasing power asymmetry is most visible in United States coastal biotech corridors where three contract manufacturers account for dominant recombinant protein absorption.
Prokaryotic Recombinant Protein Market Segmentation
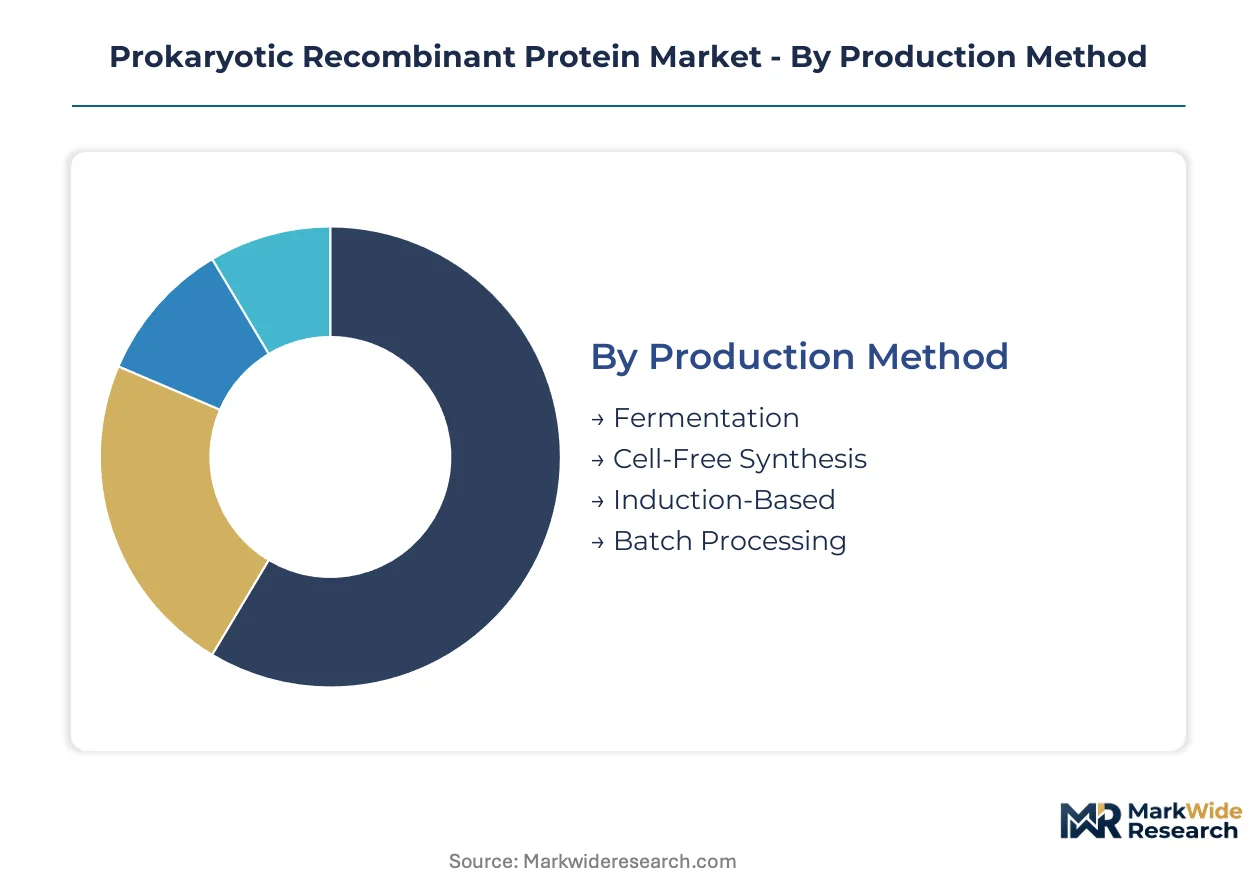
Prokaryotic recombinant protein supply fragments across four structural dimensions that determine technical capabilities, cost profiles, and regulatory pathways. Each segmentation axis shapes procurement decisions differently: production methods govern scale economics, applications dictate purity thresholds, organism types define post-translational limitations, and purification techniques control batch consistency.
Production Method:
Fermentation-based systems anchor high-volume supply while emerging extract-based methods carve niches in toxic protein categories.
- Fermentation:High-density bacterial cultivation in stainless steel bioreactors achieves titers of 1–10 grams per liter with decades of process optimization behind regulatory familiarity. Massachusetts and California CDMOs absorb dominant volumes for monoclonal antibody production workflows where E. coli platforms dominate.
- Cell-Free Synthesis:Lysate-based protein production from E. coli or wheat germ extracts bypasses cellular toxicity constraints that destabilize living hosts. Synthetic biology applications in Boston and San Diego biotech clusters drive uptake for complex targets requiring disulfide bond formation or non-canonical amino acid incorporation.
- Induction-Based:IPTG or temperature-shift protocols trigger recombinant expression in tightly controlled fermentation phases.
- Batch Processing:Traditional discontinuous cultivation retains cost advantages for catalog-grade research proteins at sub-100 liter scales.
Leading the category by volume: Fermentation. Expanding most quickly: Cell-Free Synthesis.
Applications:
End-use specifications create divergent purity and documentation requirements across therapeutic, industrial, and diagnostic segments.
- Therapeutic Proteins:GMP-aligned cytokines and growth factors for cell therapy pipelines require ISO 13485 certification and ICH Q5D-compliant host cell protein documentation. CDSCO's streamlined biosimilar pathways in India attract fermentation investments for export-oriented production.
- Industrial Enzymes:Bulk biocatalysts for detergents, textiles, and biofuels prioritize yield over endotoxin clearance, with Bacillus subtilis secretion systems displacing periplasmic E. coli for reduced downstream burden.
- Diagnostic Reagents:Antibody conjugates and assay components face evolving pharmacopeial standards for lipopolysaccharide quantification.
- Vaccines:Recombinant subunit antigens and carrier proteins demand validated impurity profiles for regulatory submission packages.
Steepest expansion trajectory: Therapeutic Proteins. Highest volume concentration: Industrial Enzymes.
Organism Type:
Strain selection trades expression efficiency against secretion capability, endotoxin burden, and genetic tool accessibility.
- Escherichia coli:K-12 and BL21-derived strains retain overwhelming market share through unmatched genetic tractability, high-copy plasmid systems, and established FDA master file precedents. Thermo Fisher Scientific and Merck KGaA leverage decades of strain engineering expertise for catalog and custom production.
- Bacillus subtilis:Gram-positive secretion machinery enables extracellular protein accumulation with intrinsically lower endotoxin loads, gaining traction in diagnostic reagent manufacturing where LAL test burdens constrain E. coli outputs.
- Lactobacillus:Generally recognized as safe status attracts oral delivery and food-grade enzyme applications.
- Pseudomonas:Specialized metabolic capabilities support non-standard amino acid incorporation and membrane protein targets.
Volume leader: Escherichia coli. Gaining share fastest: Bacillus subtilis.
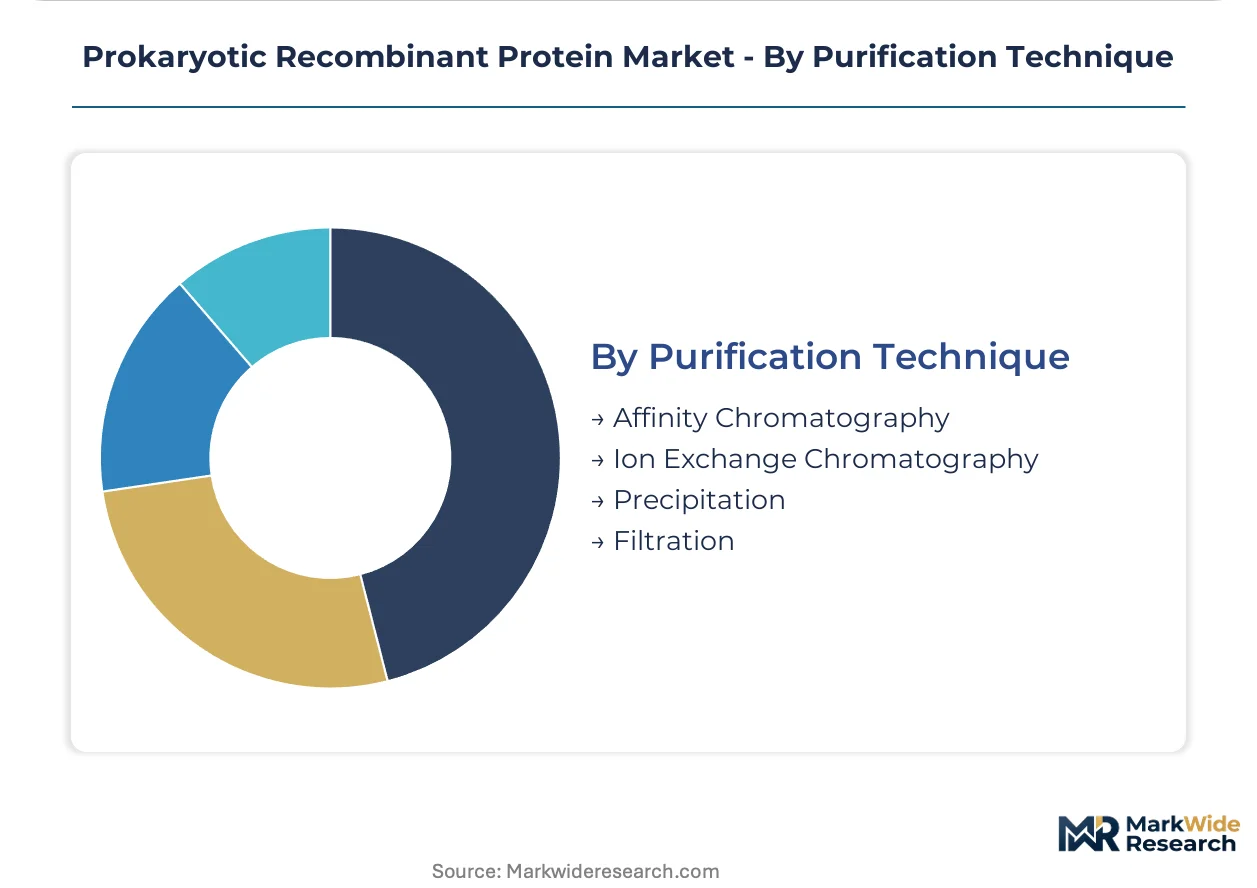
Purification Technique:
Downstream processing economics hinge on resin selectivity, scalability, and validation burden alignment with end-use requirements.
- Affinity Chromatography:Immobilized metal ion or protein A/G resins achieve single-step purity for His-tagged or Fc-fusion constructs, though capacity constraints and skilled bioprocess engineering shortages delay tech transfer to commercial volumes.
- Ion Exchange Chromatography:Charge-based separation scales efficiently for bulk industrial enzymes where tag-free recovery reduces cost structures.
- Precipitation:Ammonium sulfate or polyethylene glycol fractionation retains utility for early-stage research proteins.
- Filtration:Tangential flow and depth filtration configurations concentrate and clarify prior to chromatographic polishing.
Leading by installed capacity: Affinity Chromatography. Climbing the fastest: Ion Exchange Chromatography.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in India and biotechnology clusters in the United States concentrate fermentation capacity investments for recombinant protein manufacturing. Tax incentives and streamlined regulatory pathways in these jurisdictions reshape where suppliers locate production assets.
United States
FDA master file precedents for E. coli expression systems attract contract manufacturers serving monoclonal antibody discovery workflows. The IRA's domestic manufacturing incentives accelerate capacity investments in bioprocessing infrastructure. Massachusetts and California biotech corridors absorb dominant volumes of high-purity recombinant proteins for therapeutic development pipelines.
Germany
REACH compliance requirements for novel expression strains extend qualification timelines for research-grade protein suppliers. ECHA registration burdens force specialization toward high-margin custom synthesis over catalog commoditization. Bavaria and North Rhine-Westphalia host concentrated fermentation engineering expertise serving European pharmaceutical demand.
India
CDSCO's streamlined biosimilar approval pathways attract export-oriented recombinant protein production investments. The PLI scheme for active pharmaceutical ingredients extends to fermentation-based biologics inputs. Maharashtra and Gujarat contract manufacturing clusters expand capacity to serve North American and European therapeutic protein demand.
China
NMPA's evolving GMP alignment requirements for host cell protein documentation filter supplier participation in domestic therapeutic markets. Dual carbon goals pressure fermentation facilities to adopt energy-efficient bioreactor designs. Yangtze River Delta biotech parks concentrate automated gene synthesis and custom protein service providers.
Switzerland
Swissmedic's stringent impurity threshold standards privilege suppliers with validated downstream purification capabilities. The country's pharmaceutical manufacturing heritage sustains demand for high-grade recombinant proteins in diagnostic and vaccine applications. Basel and Zurich regions anchor contract research participation for ISO 13485-certified protein supply.
Prokaryotic Recombinant Protein Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across a market structure that privileges vertically integrated fermentation networks. The supplier base fragments between catalog commoditizers, custom synthesis service providers, and platform technology licensors. Three archetypes dominate: diversified life science conglomerates with captive fermentation assets, strain engineering specialists with deep E. coli expertise, and automated gene synthesis platforms compressing lead times. Consolidation pressures intensify as FDA host cell protein guidance raises compliance costs, while strategic partnerships between CDMOs and technology licensors accelerate capacity expansion.
Among diversified conglomerates, Thermo Fisher Scientific occupies a position representing scale-driven fermentation network advantages, while Merck KGaA exemplifies strain engineering depth anchored in E. coli platform development. GenScript Biotech Corporation sits within the automated synthesis tier, representing service differentiation through compressed custom protein lead times.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Merck KGaA |
| GenScript Biotech Corporation |
| Bio-Techne |
| Bio-Rad Laboratories, Inc. |
| Sino Biological, Inc. |
| Abcam plc |
| Proteintech Group, Inc. |
| Abnova Corporation |
| Others |
Value Network & Pricing Analysis
Certification-grade divergence between GMP-aligned therapeutic proteins and research-grade catalog outputs manifests in both pricing premiums and supply chain complexity. FDA master file documentation and ISO 13485 compliance add 40-60% cost layers that fragment supplier tiers, while Boston and San Diego biotech clusters concentrate procurement leverage among contract manufacturers demanding audited networks and captive inventory buffers.
Pricing Analysis
Expedited lead-time premiums command substantial markups for custom protein orders requiring sub-four-week turnaround, while spot inventory of catalog-grade His-tagged proteins trades at commodity discounts. Three-tier pricing structure across premium, standard, and economy levels reflects certification intensity: GMP cytokines for cell therapy pipelines price highest, ISO-compliant diagnostic reagents occupy mid-tier, and research-grade E. coli lysates compete on volume scale. Pricing pressure stems from REACH compliance extending European supplier qualification timelines and compressing margin structures. Academic laboratories exhibit highest price sensitivity, while monoclonal antibody CDMOs absorb premium tiers with limited negotiation leverage.
Supply Chain Analysis
Reverse-logistics flows for temperature-compromised protein shipments remain minimal given single-use bioprocessing dominance, though fermentation media returns and chromatography resin refurbishment programs are emerging in German and Swiss manufacturing hubs. Supply concentrates in the United States, India, and Germany, with Maharashtra and Gujarat contract manufacturing clusters expanding export-oriented capacity. Pharmaceutical-grade yeast extract and defined media components draw from agricultural supply chains vulnerable to price instability. Single-source vulnerability pervades affinity chromatography resin supply, with capacity constraints delaying tech transfer to commercial volumes. Distribution runs through direct supplier-CDMO relationships audited for FDA host cell protein documentation compliance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chromatography resin capacity scarcity props pricing power across GMP-aligned supplier tiers, constraining volume expansion for undercapitalized competitors. This supply bottleneck justifies selective capacity investments in downstream purification scale-up.
For Market Incumbents: To counter FDA host cell protein guidance raising compliance costs, Thermo Fisher Scientific-type diversified conglomerates should deepen backward integration into fermentation media production and captive chromatography resin manufacturing. Merck KGaA-type strain engineering specialists must defend position by securing ISO 13485 certification lock-in across diagnostic reagent customer bases. Capacity addition in Maharashtra and Gujarat contract manufacturing clusters represents the priority defensive lever against Indian CMO expansion threatening export-oriented revenue streams. For New Entrants and Emerging Players: Enter via automated gene synthesis platforms compressing custom protein lead times, targeting academic laboratories and early-stage biotech discovery workflows underserved by incumbent catalog commoditizers. Cell-free synthesis for toxic protein targets offers the most penetrable technology segment, with synthetic biology applications in Boston and San Diego biotech clusters presenting concentrated demand. Go-to-market execution should emphasize design-build-test integration rather than competing on fermentation scale economics. For Investors and Strategic Acquirers: Re-rating potential sits with Bacillus subtilis secretion technology specialists given EMA-FDA alignment pressure filtering Gram-negative endotoxin-burdened competitors from diagnostic reagent supply chains. Long-term viability over the next decade hinges on platform flexibility across living host and extract-based production modalities. Acquisition target archetype: mid-scale CMOs with validated downstream purification capabilities and existing ISO 13485 certification. Monitor CDSCO biosimilar approval velocity and PLI scheme disbursement rates as inflection indicators for Indian manufacturing competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Media | Captive supply of pharmaceutical-grade yeast extract insulates margin structures from agricultural commodity volatility. |
| Chromatography Resin Manufacturing Scale-Up | In-house resin production alleviates capacity constraints delaying tech transfer to commercial fermentation volumes. |
| Automated Gene Synthesis Platform Deployment | Integrated design-build-test pipelines compress custom protein lead times against catalog commoditizers. |
| ISO 13485 Certification Investment | Regulatory alignment with ICH Q5D guidelines filters contract research participation for diagnostic reagent supply. |
| Bacillus subtilis Strain Engineering Partnership | Gram-positive secretion systems reduce endotoxin burdens displacing periplasmic E. coli in diagnostic manufacturing. |
Research Methodology
Document review covered FDA master file databases, EMA scientific advice protocols, and CDSCO biosimilar approval records, complemented by interviews with fermentation process engineers, downstream purification specialists, regulatory affairs leads at contract manufacturers, and procurement managers at monoclonal antibody CDMOs. Secondary validation drew from SEC 10-K filings of diversified life science conglomerates, ISO certification registries, and REACH registration databases maintained by ECHA. Bottom-up protein demand modeling across therapeutic, diagnostic, and industrial enzyme applications was triangulated against top-down fermentation capacity estimates from bioprocessing equipment suppliers.
Cross-referencing historical capacity expansion patterns against expert panel input on regulatory timeline expectations shaped the analytical framework across the analysis window. Segmentation dimensions modeled included production method, application purity tier, organism type, and purification technique complexity, with regional regulatory cluster variations incorporated for United States, German, Indian, and Chinese supply bases. CAGRs were derived from elasticity-adjusted demand projections and capacity constraint modeling, with cell-free synthesis uptake curves and Bacillus subtilis secretion system adoption rates serving as industry-specific forecast inputs.
Revisions become necessary when FDA host cell protein impurity thresholds tighten beyond current guidance, EMA validation documentation requirements diverge further from FDA precedents, or chromatography resin supply disruptions extend batch release timelines. Forecasts reflect assumptions regarding CDSCO biosimilar pathway stability and PLI scheme continuity. Practitioners should monitor REACH registration burden evolution for novel expression strains and affinity resin manufacturing capacity announcements for early signals of supply constraint easing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
BRAF Kinase Inhibitors Market
Biopharmaceuticals
Isocitrate Dehydrogenase (IDH) Inhibitors Market
Biopharmaceuticals
Biologic Response Modifiers Market
Biopharmaceuticals
Canada Generic Drug Market
Biopharmaceuticals
Global Bruton Tyrosine Kinase (BTK) Inhibitors Market
Biopharmaceuticals
Antimycobacterial Drugs Market
Biopharmaceuticals
Macrolide Drugs Market
Biopharmaceuticals
Global Branded Generics Market
Biopharmaceuticals
Non-Receptor Tyrosine Kinase Inhibitors Market
Biopharmaceuticals
Radiopharmaceutical Theranostics Market
Biopharmaceuticals
Ocular Tuberculosis Therapeutics Market
Biopharmaceuticals
Global Resistant Pseudomonas Aeruginosa Infections Drugs Market
Biopharmaceuticals
HIV Drugs Market
Biopharmaceuticals
Insulin Syringes Market
Biopharmaceuticals
Pruritus Therapeutics Market
Biopharmaceuticals
Recombinant Hormone Market