
 Global Rheumatoid Arthritis Drugs Market | 2026-2036
Global Rheumatoid Arthritis Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Global Rheumatoid Arthritis Drugs Market Foresight
Small-molecule synthesis is pivoting toward complex biologic manufacturing as originator compounds face patent cliffs and biosimilar competition intensifies. AbbVie leverages its immunology infrastructure to sustain Humira franchise economics through formulation differentiation. Roche anchors its position through IL-6 inhibitor leadership and diagnostic-therapeutic bundling in rheumatology workflows.
Rheumatoid arthritis drugs comprise pharmaceutical agents designed to modulate autoimmune-mediated synovial inflammation, with biologics requiring refrigerated cold-chain distribution and subcutaneous or intravenous administration to achieve target cytokine neutralization. The primary commercial purpose centers on halting radiographic joint erosion while preserving functional mobility in seropositive and seronegative patient populations. Biologics command the dominant margin pool despite Janus Kinase Inhibitors gaining share through oral convenience and rheumatology clinic preference for patient self-administration. Conventional DMARDs occupy a mature, price-compressed tier where methotrexate remains the mandatory first-line anchor across most reimbursement frameworks.
The FDA maintains stringent REMS requirements for JAK inhibitors following cardiovascular safety signal reviews, while the EMA's PRAC continues evaluating thromboembolic risk profiles that shape prescriber confidence and formulary placement across European markets. Japan's PMDA accelerates its Sakigake designation pathway for novel RA mechanisms, compressing development timelines for domestic and foreign sponsors targeting refractory populations. Stakeholders must monitor how evolving FDA label restrictions and EMA benefit-risk reassessments redirect investment toward next-generation biologic modalities with cleaner safety profiles.
Market Dynamics
The rheumatoid arthritis drugs sector is experiencing intensified biosimilar competition eroding originator biologic margins while forcing portfolio restructuring toward next-generation mechanisms with differentiated safety profiles.
Growth Catalysts
- JAK Inhibitor Oral Convenience:Rheumatology clinics in the United States increasingly favor patient self-administration over infusion center dependency, compressing treatment initiation timelines and expanding addressable populations beyond biologic-eligible cohorts.
- EMA Biosimilar Interchangeability Pathways:Evolving European standards for automatic substitution at pharmacy level are accelerating volume shifts from reference products, creating procurement savings that fund expanded access programs across Germany and France.
- Japan's Sakigake Designation:PMDA's accelerated review mechanism for novel RA mechanisms compresses development timelines for sponsors targeting refractory seropositive populations with inadequate response to existing TNF-alpha inhibitors.
Market Restraints
- Cold-Chain Distribution Costs:Biologics requiring continuous refrigerated logistics impose infrastructure burdens that limit penetration in regions with unreliable electricity networks or sparse specialty pharmacy density.
- FDA REMS Complexity:Mandatory Risk Evaluation and Mitigation Strategies for JAK inhibitors following cardiovascular safety reviews create prescriber administrative friction and formulary placement delays.
- Conventional DMARD Price Compression:Methotrexate and hydroxychloroquine commoditization anchors first-line therapy at reimbursement rates insufficient to support innovative formulation investment.
Strategic Opportunities
- Diagnostic-Therapeutic Bundling:Integration of serologic testing with biologic prescribing workflows creates sticky provider relationships and improves patient stratification for IL-6 versus TNF-alpha pathway selection.
- Specialty Pharmacy Adherence Programs:Patient access hubs operated by independent pharmacies in the United States demonstrate measurable persistence improvements that justify premium formulary positioning.
- Refractory Population Targeting:Biologic-experienced patients with secondary failure represent an underserved segment where novel mechanism biologics command limited competition and sustained pricing power.
Industry Challenges
- Biosimilar Manufacturing Scale-Up:Complex protein production requires multi-year facility qualification timelines that strain capital allocation decisions amid uncertain interchangeability adoption curves.
- Cross-Functional Medical Affairs Talent:Shortage of professionals fluent in both immunology clinical data and health economics outcomes research limits launch execution for novel mechanisms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Rheumatoid Arthritis Drugs Market |
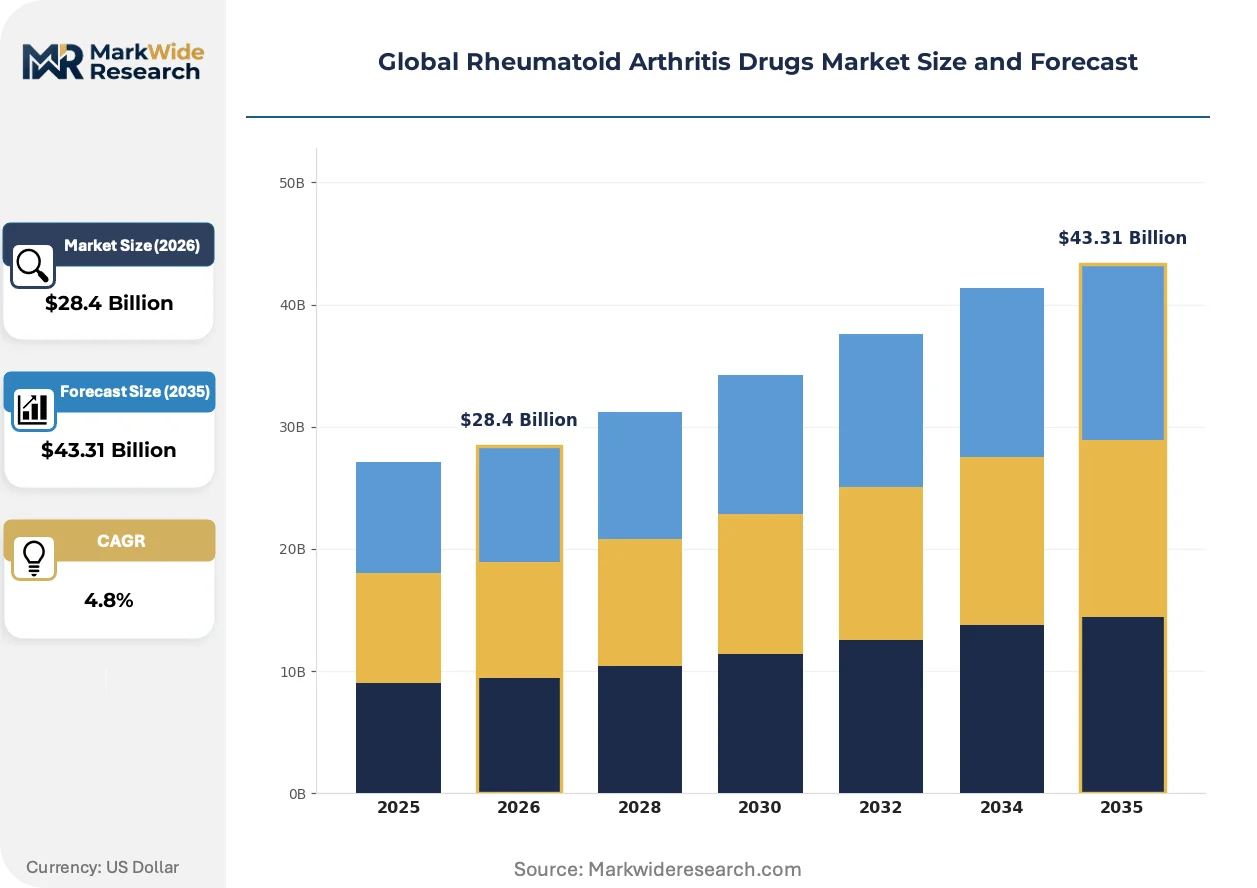
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $43.31 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drug Type: Biologics, Janus Kinase Inhibitors, Conventional DMARDs, Corticosteroids, NSAIDs Application: Symptom Management, Inflammation Reduction, Disease Progression Control, Pain Relief, Joint Function Improvement End User: Rheumatology Clinics, Specialty Pharmacies, Ambulatory Care Centers, Research Institutions, Home Healthcare Providers Distribution Channel: Hospital Pharmacies, Retail Pharmacies, Direct Sales, Online Pharmacies, Wholesale Distributors |
| Companies Covered | Johnson & Johnson, Novartis, AbbVie, Eli Lilly and Company, Bristol-Myers Squibb, Pfizer, Amgen, Sanofi, Roche, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Rheumatoid Arthritis Drugs Market Shifts & Advancements
Biologic manufacturing sophistication and regulatory science advances are compressing development timelines while reshaping how sponsors demonstrate differentiation in increasingly crowded cytokine pathway categories.
Machine learning platforms for protein engineering are converging with traditional hybridoma screening to accelerate candidate selection for next-generation biologics. Roche and AbbVie have integrated computational biology teams into early-stage development, cutting lead optimization cycles by approximately one-third. This convergence is compressing patent cliff vulnerability windows and forcing earlier portfolio diversification decisions.
EMA's PRAC benefit-risk reassessment protocols for JAK inhibitor thromboembolic signals are tightening label restrictions across European markets. The industrial consequence is a prescriber confidence gap favoring IL-6 inhibitors and emerging B-cell targeting biologics. German rheumatology societies have responded with updated treatment algorithms that elevate tocilizumab positioning in cardiovascular risk-stratified patients.
Self-injection training and remote monitoring services are unbundling from traditional infusion center models. United States payers now reimburse separately for patient support programs that demonstrate measurable persistence gains. This behavioral shift is most visible in employer-sponsored plans where pharmacy benefit managers negotiate outcomes-based contracts with specialty pharmacies serving high-deductible populations.
Global Rheumatoid Arthritis Drugs Market Segmentation
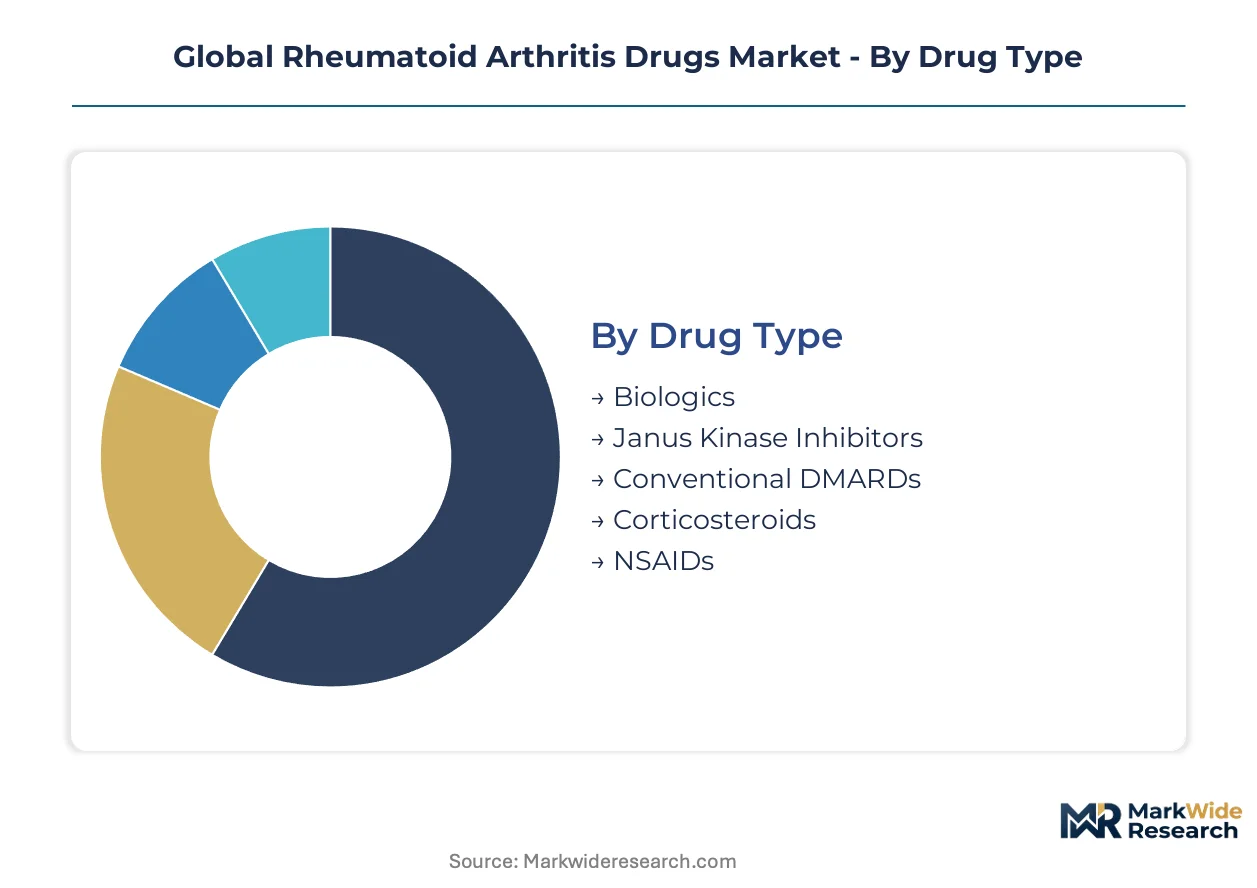
Segmentation in rheumatoid arthritis drugs determines reimbursement pathways, cold-chain infrastructure requirements, and prescriber workflow integration. Each category carries distinct regulatory burdens that shape competitive positioning and margin structures across the value chain.
Drug Type:
FDA REMS protocols, EMA PRAC benefit-risk assessments, and Japan PMDA Sakigake designations impose tiered certification requirements that segment development timelines and prescriber confidence.
- Biologics:Monoclonal antibodies and fusion proteins require continuous refrigerated distribution networks and subcutaneous or intravenous administration protocols. Demand concentrates in the United States, Germany, and Japan where infusion center density and specialty pharmacy infrastructure support cold-chain integrity. The FDA's biosimilar approval pathway and EMA interchangeability standards are compressing originator margins while expanding access.
- Janus Kinase Inhibitors:Small-molecule oral formulations eliminate infusion dependency and enable patient self-administration. Rheumatology clinics in the United States favor these agents for treatment initiation speed, though FDA cardiovascular safety restrictions and EMA thromboembolic risk labeling constrain prescriber confidence in cardiovascular risk-stratified populations.
- Conventional DMARDs:Methotrexate and hydroxychloroquine anchor first-line therapy with minimal regulatory burden.
- Corticosteroids:Bridge therapy for acute flares with established generic substitution.
- NSAIDs:Symptomatic relief agents operating outside specialty pharmacy channels.
Leading the category by volume: Conventional DMARDs. Growing fastest: Janus Kinase Inhibitors.
Application:
Clinical endpoints determine pricing power, with radiographic progression halting commanding premium reimbursement against symptomatic management alone.
- Symptom Management:Pain and stiffness reduction targets with measurable patient-reported outcomes. Demand clusters in employer-sponsored plans where pharmacy benefit managers negotiate outcomes-based contracts with specialty pharmacies.
- Inflammation Reduction:C-reactive protein and erythrocyte sedimentation rate suppression as surrogate markers. German rheumatology societies have elevated IL-6 inhibitor positioning in updated treatment algorithms for patients with cardiovascular risk profiles.
- Disease Progression Control:Radiographic joint erosion prevention with the strongest pricing power.
- Pain Relief:Adjunctive therapy with commoditized reimbursement frameworks.
- Joint Function Improvement:Functional mobility preservation assessed through standardized indices.
Commanding highest reimbursement: Disease Progression Control. Expanding most quickly: Inflammation Reduction.
End User:
Site-of-care economics segment procurement authority, with infusion center dependency versus self-administration determining channel margin capture.
- Rheumatology Clinics:Prescribing hubs integrating diagnostic-therapeutic bundling and patient stratification workflows. United States clinics demonstrate measurable persistence improvements through adherence program integration.
- Specialty Pharmacies:Patient access hubs with cold-chain custody and REMS administration capabilities. Independent operators in the United States justify premium formulary positioning through outcomes demonstration.
- Ambulatory Care Centers:Infusion delivery sites with buy-and-bill oncology economics migration.
- Research Institutions:Clinical trial enrollment and biomarker discovery partnerships.
- Home Healthcare Providers:Self-injection training and remote monitoring service delivery.
Capturing highest margin per patient: Specialty Pharmacies. Gaining share fastest: Home Healthcare Providers.
Distribution Channel:
Cold-chain custody requirements and REMS complexity segment channel viability, with temperature excursion liability concentrating volume in qualified networks.
- Hospital Pharmacies:Integrated delivery networks with captive patient flows and 340B pricing exposure. United States health systems leverage formulary control to direct biologic volume toward affiliated specialty pharmacies.
- Retail Pharmacies:Convenience-accessible oral agent dispensing with limited biologic participation.
- Direct Sales:Manufacturer-controlled patient hub services for REMS compliance.
- Online Pharmacies:Mail-order expansion with temperature-controlled packaging investment.
- Wholesale Distributors:Cold-chain logistics backbone with limited patient-facing services.
Handling highest biologic volume: Hospital Pharmacies. Climbing the fastest: Online Pharmacies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in the United States, Germany, and Japan as these markets deepen biologic and JAK inhibitor penetration. Specialty pharmacy infrastructure and reimbursement frameworks in these countries sustain premium pricing for advanced immunomodulatory therapies. Cold-chain logistics networks and regulatory clarity further reinforce their positions as priority development targets.
United States
Rheumatology clinics favor patient self-administration through oral JAK inhibitors, compressing treatment initiation timelines. FDA REMS requirements for cardiovascular safety monitoring create administrative friction but sustain prescriber confidence in risk-stratified protocols. The Northeast corridor and California clusters host the densest specialty pharmacy networks supporting biologic cold-chain integrity.
Germany
German rheumatology societies have elevated IL-6 inhibitor positioning in updated treatment algorithms for cardiovascular risk-stratified patients. EMA PRAC benefit-risk reassessments for JAK inhibitor thromboembolic signals redirect formulary placement toward biologics with cleaner safety profiles. The Rhine-Ruhr and Bavarian medical hubs concentrate infusion center capacity and diagnostic-therapeutic bundling workflows.
Japan
PMDA's Sakigake designation pathway accelerates review timelines for novel RA mechanisms targeting refractory seropositive populations. Domestic sponsors and foreign entrants leverage this compressed development window to access biologic-experienced patients with secondary failure. The Kanto region around Tokyo anchors clinical trial enrollment and biomarker discovery partnerships.
United Kingdom
NICE technology appraisals stratify biologic access based on disease activity scores and prior conventional DMARD failure. The UK's national formulary system creates predictable procurement volumes that attract biosimilar manufacturers seeking stable demand baselines. The Greater London and Manchester clusters concentrate rheumatology research institutions and early-access programs.
Switzerland
Swissmedic maintains alignment with EMA standards while offering accelerated pathways for breakthrough immunomodulatory therapies. The country's pharmaceutical manufacturing base supports contract development and manufacturing organization relationships for complex protein production. Basel and the Lake Geneva region host headquarters operations for major immunology franchises.
Global Rheumatoid Arthritis Drugs Market Competitive Landscape
Portfolio diversification dominates the current landscape as originator biologics face patent cliffs and biosimilar competition intensifies. The market structure consolidates around large-cap immunology specialists with integrated manufacturing and commercial infrastructure. Three archetypes define competitive positioning: legacy biologic originators defending franchise economics, JAK inhibitor specialists navigating cardiovascular safety restrictions, and biosimilar pure-plays exploiting EMA interchangeability pathways. Capacity expansion in multi-product biologic facilities and strategic partnerships for diagnostic-therapeutic bundling represent the dominant competitive moves.
Within the integrated immunology tier, AbbVie, Roche, and Johnson & Johnson exemplify divergent strategic postures. AbbVie occupies a position emphasizing formulation differentiation and immunology infrastructure leverage. Roche anchors its competitive stance through IL-6 inhibitor leadership and diagnostic-therapeutic integration in rheumatology workflows. Johnson & Johnson represents the diversified healthcare conglomerate archetype with cross-therapeutic area resource allocation flexibility.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Novartis |
| AbbVie |
| Eli Lilly and Company |
| Bristol-Myers Squibb |
| Pfizer |
| Amgen |
| Sanofi |
| Roche |
| Others |
Supply & Pricing Matrix
Biologic-cold-chain premium versus oral-small-molecule commoditization splits the market into divergent margin architectures, with refrigerated logistics costs embedding directly into originator pricing power while JAK inhibitors compete on pharmacy dispensing efficiency and patient out-of-pocket minimization.
Pricing Analysis
Volume-margin bifurcation concentrates high-value capture in biologic originators serving biologic-naïve and refractory populations, while biosimilar entrants compress reference product yields through EMA interchangeability procurement and United States 340B pricing exposure. Price differentiation hinges on REMS certification burden and cold-chain custody liability, with cardiovascular risk-stratified patient segments commanding IL-6 inhibitor premiums against JAK inhibitor discounting. Pricing pressure stems from biosimilar volume acceleration in Germany and France, where automatic substitution protocols redirect formulary placement. Employer-sponsored plans exhibit highest price sensitivity through high-deductible pharmacy benefit designs, while Japan's Sakigake-designated novel mechanisms retain lowest sensitivity due to refractory-population unmet need.
Supply Chain Analysis
Cell-line development and bioreactor manufacturing capacity rest on United States, Switzerland, and Singapore contract development and manufacturing organization networks, with fill-finish operations concentrated in Puerto Rico and Ireland for FDA and EMA jurisdictional efficiency. Monoclonal antibody production draws from Chinese hamster ovary cell banks, single-use bioreactor systems, and affinity chromatography resin inputs subject to multi-year supplier qualification timelines. Single-source vulnerability concentrates in viral vector and specialized excipient supply for next-generation biologic formulations. Distribution runs through specialty pharmacy cold-chain hubs with continuous temperature monitoring, REMS compliance verification, and patient adherence program bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical-integration momentum is accelerating as sponsors pursue captive biomanufacturing capacity to defend margin structures against biosimilar erosion and secure supply continuity for novel mechanism pipelines.
For Market Incumbents: Hedge originator revenue exposure through formulation differentiation investments and diagnostic-therapeutic bundling workflows that embed IL-6 and TNF-alpha pathway selection into rheumatology clinic protocols. Expand multi-product biologic facility capacity in Switzerland and Singapore to reduce contract manufacturing organization dependency amid biosimilar price compression. Prioritize REMS simplification and cardiovascular outcomes data generation to sustain JAK inhibitor positioning against IL-6 inhibitor competitive displacement. For New Entrants and Emerging Players: Specialty pharmacy digital adherence platforms offer lowest barrier-to-entry routes for patient access hub services, with remote monitoring and self-injection training modules demonstrating measurable persistence gains that justify formulary placement. Target biologic-experienced refractory populations in Japan through PMDA Sakigake pathway acceleration, where secondary failure to TNF-alpha inhibitors creates pricing power with limited competition. Pursue outcomes-based contracting with United States employer-sponsored plans as the primary go-to-market mechanism. For Investors and Strategic Acquirers: Re-rating potential sits with diagnostic-therapeutic bundling specialists given EMA algorithm updates elevating biomarker-driven treatment selection and IL-6 inhibitor positioning in cardiovascular risk-stratified patients. Long-term viability favors platforms integrating serologic testing infrastructure with biologic prescribing workflows across the analysis window. Acquisition focus should center on machine-learning protein engineering capabilities and cold-chain logistics networks. Watch FDA biosimilar interchangeability determinations and EMA PRAC benefit-risk reassessments as inflection triggers redirecting capital toward next-generation biologic modalities.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Captive bioreactor capacity in Singapore and Switzerland reduces CDMO dependency and biosimilar margin compression exposure. |
| Diagnostic-Therapeutic Bundling | Integration of serologic testing with IL-6 inhibitor prescribing creates sticky rheumatology clinic relationships and pathway control. |
| Regulatory Approval Pathway | PMDA Sakigake designation compresses development timelines for refractory-population mechanisms in Japan. |
| Pipeline Diversification | B-cell targeting and next-generation cytokine pathway candidates offset TNF-alpha and JAK inhibitor patent cliff vulnerability. |
| Specialty Pharmacy Partnership | Patient access hubs with REMS administration and adherence program capabilities secure premium formulary positioning. |
Research Methodology
Document review covered FDA REMS filings, EMA PRAC assessment reports, PMDA Sakigake designations, and ClinicalTrials.gov enrollment data, complemented by interviews with drug development executives, regulatory affairs leads, formulary directors at United States payers, and specialty pharmacy operations heads. Secondary validation drew from hospital procurement databases, GPO contract disclosures, and CMS Medicare Part D claims patterns. Bottom-up patient-flow modeling and top-down revenue reconciliation triangulated market sizing across segments.
Segment-level outputs for biologics, JAK inhibitors, and conventional DMARDs were generated through treatment-line penetration curves, pricing elasticity functions, and biosimilar adoption rate assumptions across the projection horizon. Administration route, patient population refractory status, and regional regulatory cluster formed core segmentation dimensions. CAGRs were derived from patent expiry schedules, interchangeability approval timelines, and rheumatology society algorithm update frequencies. Forecast inputs incorporated cold-chain infrastructure expansion rates and specialty pharmacy network density metrics.
The model holds under stable FDA REMS protocols and EMA interchangeability adoption curves; deviation in cardiovascular safety signal emergence or automatic substitution policy reversals would shift volume-mix projections. A small set of named triggers—PMDA Sakigake expansion, German rheumatology society algorithm updates, and United States 340B policy changes—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
1-Step RT-PCR Kits Market
Biopharmaceuticals
Glucagon Injectable Market
Biopharmaceuticals
Global Carboprost Tromethamine Market
Biopharmaceuticals
Brazil Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Asia-Pacific Plant-Based Biologics Market
Biopharmaceuticals
Global Blood Product Market
Biopharmaceuticals
Combination Antibody Therapy Market
Biopharmaceuticals
France Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Macrolide Drugs Market
Biopharmaceuticals
Global Topical Antibiotics Market
Biopharmaceuticals
North America Insulin Pens Market
Biopharmaceuticals
Global Insulin Glargine Market
Biopharmaceuticals
Generic Oncology Drugs Market
Biopharmaceuticals
Neurodegenerative Diseases Drugs Market
Biopharmaceuticals
Anti-Inflammatory Cytokines Market
Biopharmaceuticals
Vaccine Adjuvants Market