
 Global Biopharmaceuticals Market | 2026-2036
Global Biopharmaceuticals Market Size, Share, and Industry Trends Forecast 2026-2036
Global Biopharmaceuticals Market Analysis
Switzerland is narrowing the gap between research intensity and commercial manufacturing scale in European biopharmaceutical production. Roche Holding AG leverages its Basel-based R&D infrastructure to sustain leadership in monoclonal antibody development. Pfizer Inc. anchors large-scale recombinant protein manufacturing across multiple continents, while AbbVie Inc. differentiates through specialized immunology biologics that command premium positioning in hospital formularies.
Biopharmaceuticals comprise therapeutic products derived from living organisms or their components, including monoclonal antibodies produced via mammalian cell culture in bioreactors exceeding 10,000-liter capacity and gene therapies manufactured through viral vector platforms. These products treat diseases by modulating cellular processes rather than chemically synthesized small-molecule intervention. Monoclonal antibodies occupy the largest revenue pool due to established reimbursement in oncology and autoimmune indications, while gene therapies represent the fastest-expanding segment as manufacturing scalability improves and regulatory pathways mature for one-time curative treatments. Recombinant proteins maintain stable demand from hospital and clinic end users managing chronic conditions such as diabetes and hemophilia.
The FDA enforces current Good Manufacturing Practice standards through its Center for Biologics Evaluation and Research, directly influencing facility design and batch release timelines for US market access. EMA's Medical Device Regulation and the EU AI Act create layered compliance requirements for combination products and algorithm-driven manufacturing controls across European markets. China's NMPA accelerates domestic biologics approvals under its priority review channels, reshaping competitive dynamics for multinational sponsors. Stakeholders must monitor how divergent data integrity standards between FDA, EMA, and NMPA affect cross-regional clinical trial strategies and technology transfer agreements.
Market Dynamics
Manufacturing scalability constraints in viral vector production are compressing commercialization timelines for gene therapies while monoclonal antibody facilities race to expand single-use bioreactor capacity. This capacity bottleneck is forcing sponsors to choose between capital-intensive stainless steel investments and flexible disposable platforms.
Growth Catalysts
- FDA Accelerated Approval:The pathway compresses Phase II-to-launch intervals for breakthrough-designated biologics, enabling earlier revenue recognition for oncology monoclonal antibodies.
- China NMPA Priority Review:Domestic manufacturers gain faster market access for biosimilars, reshaping competitive dynamics for multinational sponsors in the world's second-largest biopharmaceuticals market.
- Continuous Bioprocessing:Perfusion cell culture technology reduces facility footprint requirements while increasing volumetric productivity for recombinant protein manufacturing.
Market Restraints
- Plasma Supply Concentration:Over 60% of global immunoglobulin feedstock originates from US collection centers, creating geographic vulnerability for European and Asian fractionators.
- EMA MDR Compliance Burden:Combination product manufacturers face layered documentation requirements for device-drug interfaces, extending approval timelines by 12-18 months.
- Gene Therapy Manufacturing Yield:Viral vector titers remain 2-3 orders of magnitude below monoclonal antibody productivity, constraining dose availability for one-time curative treatments.
Strategic Opportunities
- India CDMO Expansion:Contract development organizations in Hyderabad and Bengaluru are capturing biologics process development work as Western sponsors seek cost-optimized manufacturing alternatives.
- EU AI Act Manufacturing Controls:Algorithm-driven process analytical technology gains regulatory clarity, enabling real-time release testing that reduces batch cycle times.
- Subcutaneous Formulation Shift:Hospital formulary preference for self-administered biologics is opening formulation partnerships between monoclonal antibody developers and delivery device specialists.
Industry Challenges
- Cell Line Development Talent Scarcity:Mammalian cell engineering expertise concentrates among a limited pool of specialists, inflating compensation costs for early-stage biologics startups.
- Multi-Product Facility Validation:Campaign changeover protocols for shared bioreactor suites require extensive cleaning validation documentation, complicating capacity utilization strategies.
- Cross-Regional Data Integrity Standards:Divergent FDA, EMA, and NMPA expectations for electronic batch records create compliance friction for sponsors running parallel global trials.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Biopharmaceuticals Market |
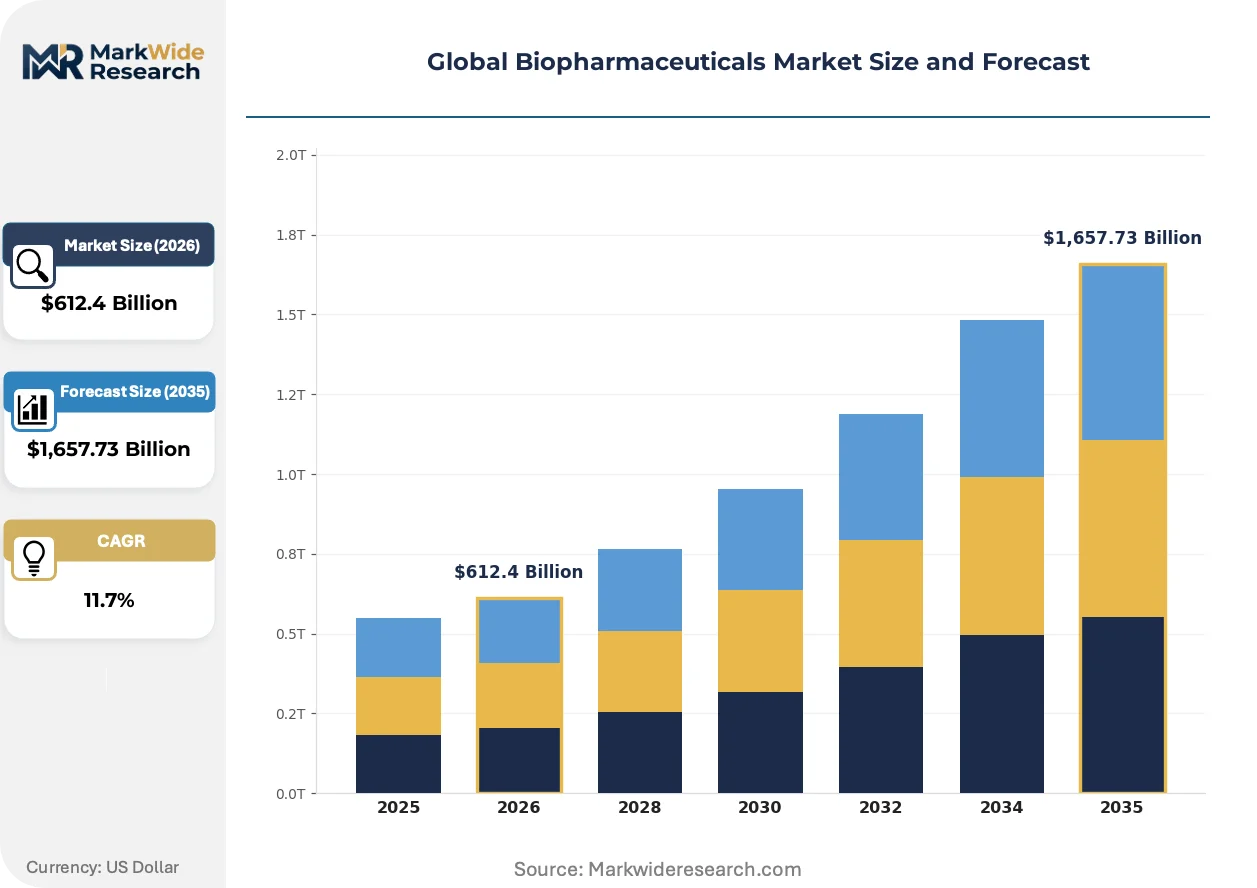
| Market Size in 2026 | $612.4 Billion |
| Market Size in 2035 | $1,657.73 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Vaccines, Recombinant Proteins, Gene Therapies End User: Hospitals, Research Laboratories, Clinics, Academic Institutions Delivery Mode: Injection, Oral, Intranasal, Transdermal Application: Oncology, Neurology, Cardiovascular, Infectious Diseases |
| Companies Covered | Johnson & Johnson, Roche Holding AG, Pfizer Inc., AbbVie Inc., Merck & Co., Novartis AG, AstraZeneca, Amgen Inc., Eli Lilly and Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Biopharmaceuticals Market Emerging Trajectories
Biopharmaceutical manufacturing is pivoting from batch processing toward integrated continuous bioprocessing platforms that compress residence times and reduce facility capital intensity. This shift is redrawing competitive advantage around process analytical technology capabilities rather than scale alone.
Single-use bioreactor technology is collapsing the economic threshold for multi-product facility deployment. Contract manufacturers in Switzerland and Germany are adopting 2,000-liter disposable systems for clinical-stage monoclonal antibodies, enabling rapid product changeovers without steam-in-place validation requirements. This flexibility is compressing the traditional 18-month facility repurposing cycle into 8-12 weeks.
EMA's Medical Device Regulation and the EU AI Act are creating convergent compliance frameworks for combination products incorporating algorithm-driven dosing. Manufacturers of insulin delivery systems and wearable biologics injectors must now satisfy dual regulatory pathways, with notified body capacity constraints extending certification timelines. German and French sponsors are responding by pre-submission engagement with both EMA and national competent authorities.
Hospital procurement committees are consolidating biologics purchasing through centralized tender mechanisms that unbundle originator premiums from clinical outcomes data. Oncology and immunology therapeutic categories face the steepest price compression as pharmacy benefit managers in the United States and hospital consortia in Germany demand real-world evidence packages. This behavioral shift is most visible in rheumatoid arthritis and psoriasis indications where multiple biosimilar alternatives have achieved interchangeability designation.
Global Biopharmaceuticals Market Segmentation
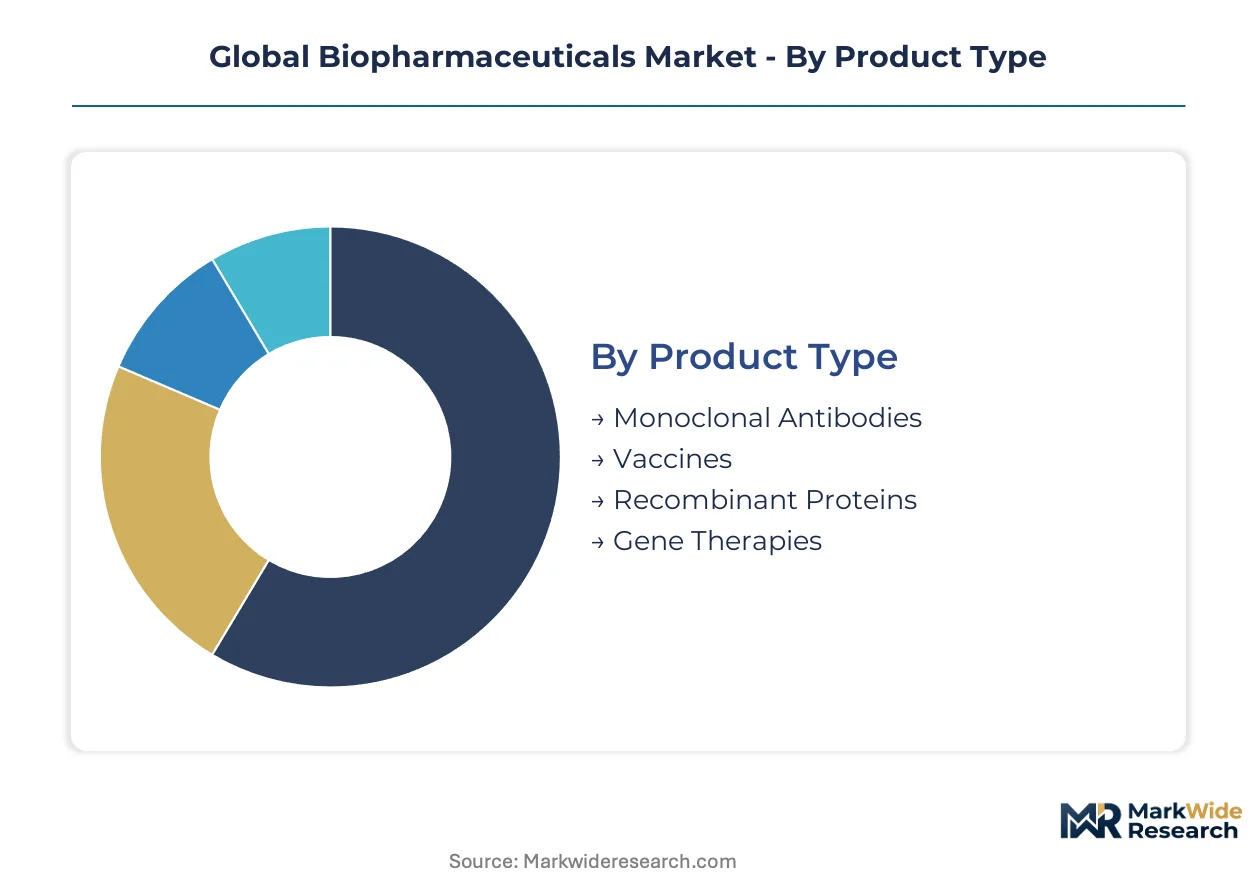
Biopharmaceutical market segmentation reveals distinct velocity profiles across product categories. Cycle times vary dramatically from rapid vaccine campaign launches to decade-long gene therapy development arcs, reshaping capital allocation and portfolio strategy for manufacturers.
Product Type:
Monoclonal antibodies turn inventory fastest through established manufacturing platforms, while gene therapies require extended development horizons that strain balance sheet capacity.
- Monoclonal Antibodies:Large glycoprotein molecules manufactured via Chinese hamster ovary cell culture in stainless steel or single-use bioreactors. Hospital procurement in the United States and Germany concentrates demand for oncology and autoimmune indications, with FDA accelerated approval pathways compressing commercialization timelines.
- Gene Therapies:One-time curative treatments delivered through adeno-associated viral vectors or lentiviral platforms. Manufacturing yield constraints in the United States and Switzerland limit dose availability, though Swissmedic priority review channels are shortening European access timelines for rare disease indications.
- Vaccines:Prophylactic and therapeutic formulations spanning mRNA, viral vector, and recombinant subunit technologies. China's NMPA domestic approval pathways concentrate demand for infectious disease programs.
- Recombinant Proteins:Engineered peptides and enzymes produced through microbial or mammalian expression systems. Chronic disease management in German hospital formularies sustains stable procurement volumes for insulin and coagulation factors.
Monoclonal antibodies dominate installed base. Gene therapies are where expansion concentrates.
End User:
Cost tiers separate high-volume hospital procurement from premium-priced research laboratory contracting, with reimbursement infrastructure determining addressable market depth.
- Hospitals:Centralized pharmacy and therapeutics committees manage biologics formularies through tender mechanisms. Oncology monoclonal antibodies in the United States command the largest procurement volumes, though German hospital consortia are compressing originator premiums through real-world evidence requirements.
- Research Laboratories:Contract research organizations and academic drug discovery units source early-stage biologics for preclinical validation. Basel-based R&D clusters in Switzerland concentrate demand for specialized reagent-grade materials.
- Clinics:Outpatient infusion centers and specialty care practices administer subcutaneous and intravenous biologics. Rheumatology and dermatology practices in the United States are expanding self-administered formulation adoption.
- Academic Institutions:University medical centers and teaching hospitals bridge clinical research and patient care. China's priority review channel access is reshaping competitive dynamics for domestic biologics sponsors.
Hospitals anchor volume procurement. Research laboratories capture premium pricing.
Delivery Mode:
Patient compliance and manufacturing complexity create divergent margin profiles across administration routes, with formulation technology determining competitive moats.
- Injection:Intravenous, subcutaneous, and intramuscular routes dominate biologics administration due to molecular size constraints. Prefilled syringes and autoinjector devices from German manufacturers are gaining hospital formulary preference in the United States.
- Oral:Limited to smaller peptide therapeutics and targeted delivery formulations. China's NMPA bioequivalence requirements create regulatory friction for biosimilar peptide entrants.
- Intranasal:Mucosal delivery platforms for vaccines and select peptide hormones. Seasonal influenza programs in the United States sustain manufacturing capacity utilization.
- Transdermal:Microneedle patches and iontophoresis systems for localized biologic delivery. Swiss device manufacturers are partnering with monoclonal antibody developers on wearable injector platforms.
Injection commands manufacturing scale. Transdermal formulations are climbing the fastest.
Application:
Therapeutic area maturity determines pricing power, with oncology defending premium positioning while cardiovascular faces biosimilar compression.
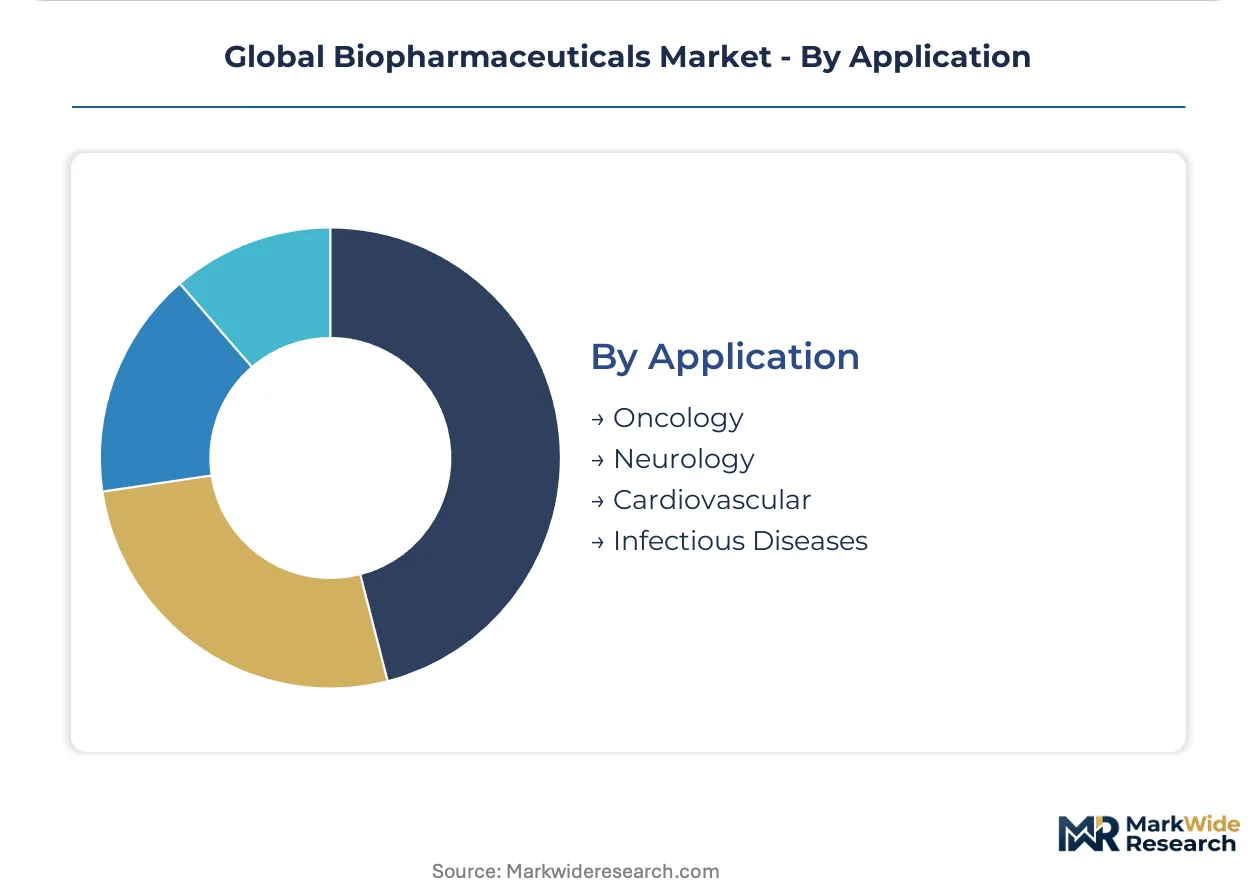
- Oncology:Immune checkpoint inhibitors and antibody-drug conjugates target solid and hematologic malignancies. FDA breakthrough therapy designations in the United States sustain accelerated approval velocity for novel mechanisms.
- Neurology:Disease-modifying therapies for Alzheimer's and multiple sclerosis require extended clinical validation. EMA adaptive licensing frameworks are shortening European access timelines for amyloid-targeting antibodies.
- Cardiovascular:PCSK9 inhibitors and anticoagulant biologics face reimbursement pressure from small-molecule alternatives. German hospital procurement committees are demanding outcome-based contracting.
- Infectious Diseases:Monoclonal antibody prophylaxis and therapeutic vaccines address resistant bacterial and viral pathogens. China's domestic manufacturing expansion is reshaping supply concentration for pandemic preparedness.
Oncology dominates revenue concentration. Neurology is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biopharmaceutical manufacturing capacity clusters in jurisdictions with mature regulatory science and concentrated venture capital access. The United States, Germany, Switzerland, China, and India host the dominant share of commercial-scale bioreactor installations and viral vector production facilities.
United States
FDA accelerated approval pathways and breakthrough therapy designations compress development timelines for oncology monoclonals. The IRA's Medicare price negotiation provisions reshape reimbursement expectations for mature biologics. The Greater Boston and San Francisco Bay Area clusters concentrate early-stage cell line development and gene therapy process innovation.
Germany
Hospital consortia and pharmacy benefit managers demand real-world evidence packages that compress originator premiums for immunology biologics. EMA adaptive licensing frameworks and MDR compliance requirements create layered documentation burdens for combination products. The Rhine-Main and Munich regions anchor large-scale recombinant protein manufacturing for European hospital formularies.
Switzerland
Swissmedic priority review channels shorten market access timelines for rare disease gene therapies. Basel-based R&D infrastructure sustains leadership in monoclonal antibody development through integrated discovery-to-manufacturing pipelines. The Lake Geneva corridor concentrates viral vector process development and specialized biologics finishing capacity.
China
NMPA priority review channels accelerate domestic biosimilar approvals and reshape competitive dynamics for multinational sponsors. Dual carbon goals and domestic manufacturing subsidies expand biologics capacity in Jiangsu and Zhejiang provinces. The Yangtze River Delta cluster concentrates mammalian cell culture manufacturing for regional hospital procurement.
India
CDSCO streamlined approval pathways for biosimilars attract Western sponsors seeking cost-optimized manufacturing alternatives. PLI scheme incentives and contract development organization expansion in Hyderabad and Bengaluru capture biologics process development work. The Genome Valley and Biotech Park clusters specialize in early-stage monoclonal antibody cell line engineering.
Global Biopharmaceuticals Market Vendor Landscape
Diversified pharmaceutical conglomerates and specialized biologics developers split the market across distinct capability vectors. Consolidation pressures intensify as manufacturing scale requirements and regulatory compliance costs favor organizations with balance sheet capacity for stainless steel facility investments or flexible single-use platform deployments. Three archetypes dominate: integrated pharma majors with legacy small-molecule infrastructure repurposed for biologics, pure-play biotech specialists with concentrated therapeutic area depth, and emerging-market contract manufacturers capturing process development outsourcing. Capacity expansion and strategic technology licensing represent the dominant competitive moves as sponsors race to secure viral vector manufacturing slots and perfusion cell culture expertise.
Within the integrated pharma tier, Roche Holding AG and Pfizer Inc. exemplify archetypes with established bioreactor networks across multiple continents. AbbVie Inc. occupies a position within the specialized immunology biologics segment. These entities represent the scale-driven and therapeutic-area-concentrated poles of competitive positioning, with their organizational footprints reflecting divergent strategic bets on manufacturing platform flexibility versus stainless steel economies of scale.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Roche Holding AG |
| Pfizer Inc. |
| AbbVie Inc. |
| Merck & Co. |
| Novartis AG |
| AstraZeneca |
| Amgen Inc. |
| Eli Lilly and Co. |
| Others |
Supply Flow & Price Mechanics
US plasma collection centers supply over sixty percent of global immunoglobulin feedstock, concentrating margin capture with fractionators operating multi-site purification networks while European and Asian manufacturers absorb geographic risk premiums. This upstream bottleneck cascades into hospital formulary negotiations where originator monoclonal antibodies defend position through real-world evidence bundling against biosimilar tender pressure.
Pricing Analysis
FDA accelerated approval pathways dictate the pricing tier structure for oncology biologics, separating breakthrough-designated therapies from standard-of-care alternatives through reimbursement velocity advantages. Three-tier pricing stratifies across premium originator monoclonals, interchangeable biosimilars, and emerging follow-on biologics with narrower indication claims. Cost compression in the standard tier intensifies as German hospital consortia mandate outcome-based contracting for immunology indications. Research laboratories exhibit least price sensitivity due to reagent-grade specification requirements, while outpatient clinics face steepest budget constraints from pharmacy benefit manager formulary exclusions.
Supply Chain Analysis
Export controls on gene therapy manufacturing equipment limit viral vector platform transfers from United States and Swiss facilities to emerging-market contract development organizations. Mammalian cell culture capacity clusters in China, Germany, and India, with stainless steel bioreactor installations concentrated in Basel and Boston corridor sites. Raw material dependencies center on Chinese-sourced cell culture media, German-engineered single-use bioreactor assemblies, and US-origin fetal bovine serum. Single-source vulnerability characterizes plasmid DNA supply for AAV vector production. Distribution runs through hospital centralized pharmacy committees in the United States and German hospital consortia procurement mechanisms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gene therapy manufacturing yield improvements represent a high-growth disruption, with regulatory clarity from FDA and EMA on real-time release testing compressing batch cycle timelines and reshaping capital allocation toward continuous bioprocessing platforms.
For Market Incumbents: Build manufacturing scale moats through perfusion cell culture technology deployment across Swiss and German facilities to outpace viral vector productivity constraints. Anchor capacity expansion in Yangtze River Delta sites to capture NMPA priority review channel access. Defend against CDMO cost arbitrage from Hyderabad and Bengaluru by integrating process analytical technology capabilities that enable real-time batch release. For New Entrants and Emerging Players: Establish a beachhead in subcutaneous formulation partnerships between monoclonal antibody developers and German autoinjector device manufacturers. Target the transdermal delivery segment where Swiss wearable injector collaborations remain underpenetrated relative to intravenous administration dominance. Pursue EU AI Act manufacturing controls compliance as a differentiated positioning lever for algorithm-driven process validation. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed contract development organizations in India possessing mammalian cell line engineering capabilities but lacking viral vector platform breadth. Five-to-ten year viability hinges on bioreactor network utilization rates and regulatory pathway diversification across FDA, EMA, and NMPA jurisdictions. Monitor Swissmedic priority review channel expansion for rare disease gene therapies as an inflection signal for European manufacturing capacity redeployment.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Bioprocessing Adoption | Perfusion cell culture technology reduces facility footprint requirements while increasing volumetric productivity for recombinant protein manufacturing. |
| Subcutaneous Formulation Partnerships | Hospital formulary preference for self-administered biologics opens collaboration opportunities between monoclonal antibody developers and German autoinjector specialists. |
| EU AI Act Manufacturing Compliance | Algorithm-driven process analytical technology gains regulatory clarity, enabling real-time release testing that reduces batch cycle times for European facilities. |
| India CDMO Capacity Expansion | Contract development organizations in Hyderabad and Bengaluru capture biologics process development work as Western sponsors seek cost-optimized manufacturing alternatives. |
| Viral Vector Manufacturing Scale-Up | Swiss and US facilities face yield constraints that limit dose availability for one-time curative gene therapies, creating capacity bottlenecks for sponsors. |
Methodological Framework
Initial hypotheses were tested against primary input from drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists and refined through secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital formulary databases. Bottom-up patient population modeling and top-down manufacturer capacity assessments were triangulated to anchor volume estimates.
Demand-supply balance dynamics across the analysis window were modeled through segmentation by product type, therapeutic indication, administration route, and regional regulatory cluster. CAGRs were derived from installed bioreactor capacity expansion trajectories, priority review channel velocity assumptions, and biosimilar interchangeability designation timelines. Forecast inputs incorporated viral vector manufacturing yield improvement curves and continuous bioprocessing adoption rates.
Sensitivities concentrate around regulatory pathway divergence between FDA, EMA, and NMPA data integrity standards, plasma supply geographic concentration risks, and gene therapy manufacturing scalability breakthroughs. Material shifts in accelerated approval pathway criteria or export control regime expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Germany Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
North America Contraceptives Market
Biopharmaceuticals
Mammalian Derived Proteins Market
Biopharmaceuticals
Olaparib API Market
Biopharmaceuticals
Global Bruton Tyrosine Kinase (BTK) Inhibitors Market
Biopharmaceuticals
Progesterone Market
Biopharmaceuticals
Global Carboprost Tromethamine Market
Biopharmaceuticals
Paediatric Oncology Therapeutics Market
Biopharmaceuticals
In Situ Gel Drug Delivery Market
Biopharmaceuticals
Sezary Syndrome Market
Biopharmaceuticals
Asia-Pacific Plant-Based Biologics Market
Biopharmaceuticals
Global Staphylococcal Infection Drugs Market
Biopharmaceuticals
Global Cytokine Market
Biopharmaceuticals
Insulin Delivery Pens Market
Biopharmaceuticals
Thailand Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Spectinomycin Market